China Telecommunication Satellite Market Size & Growth Rate
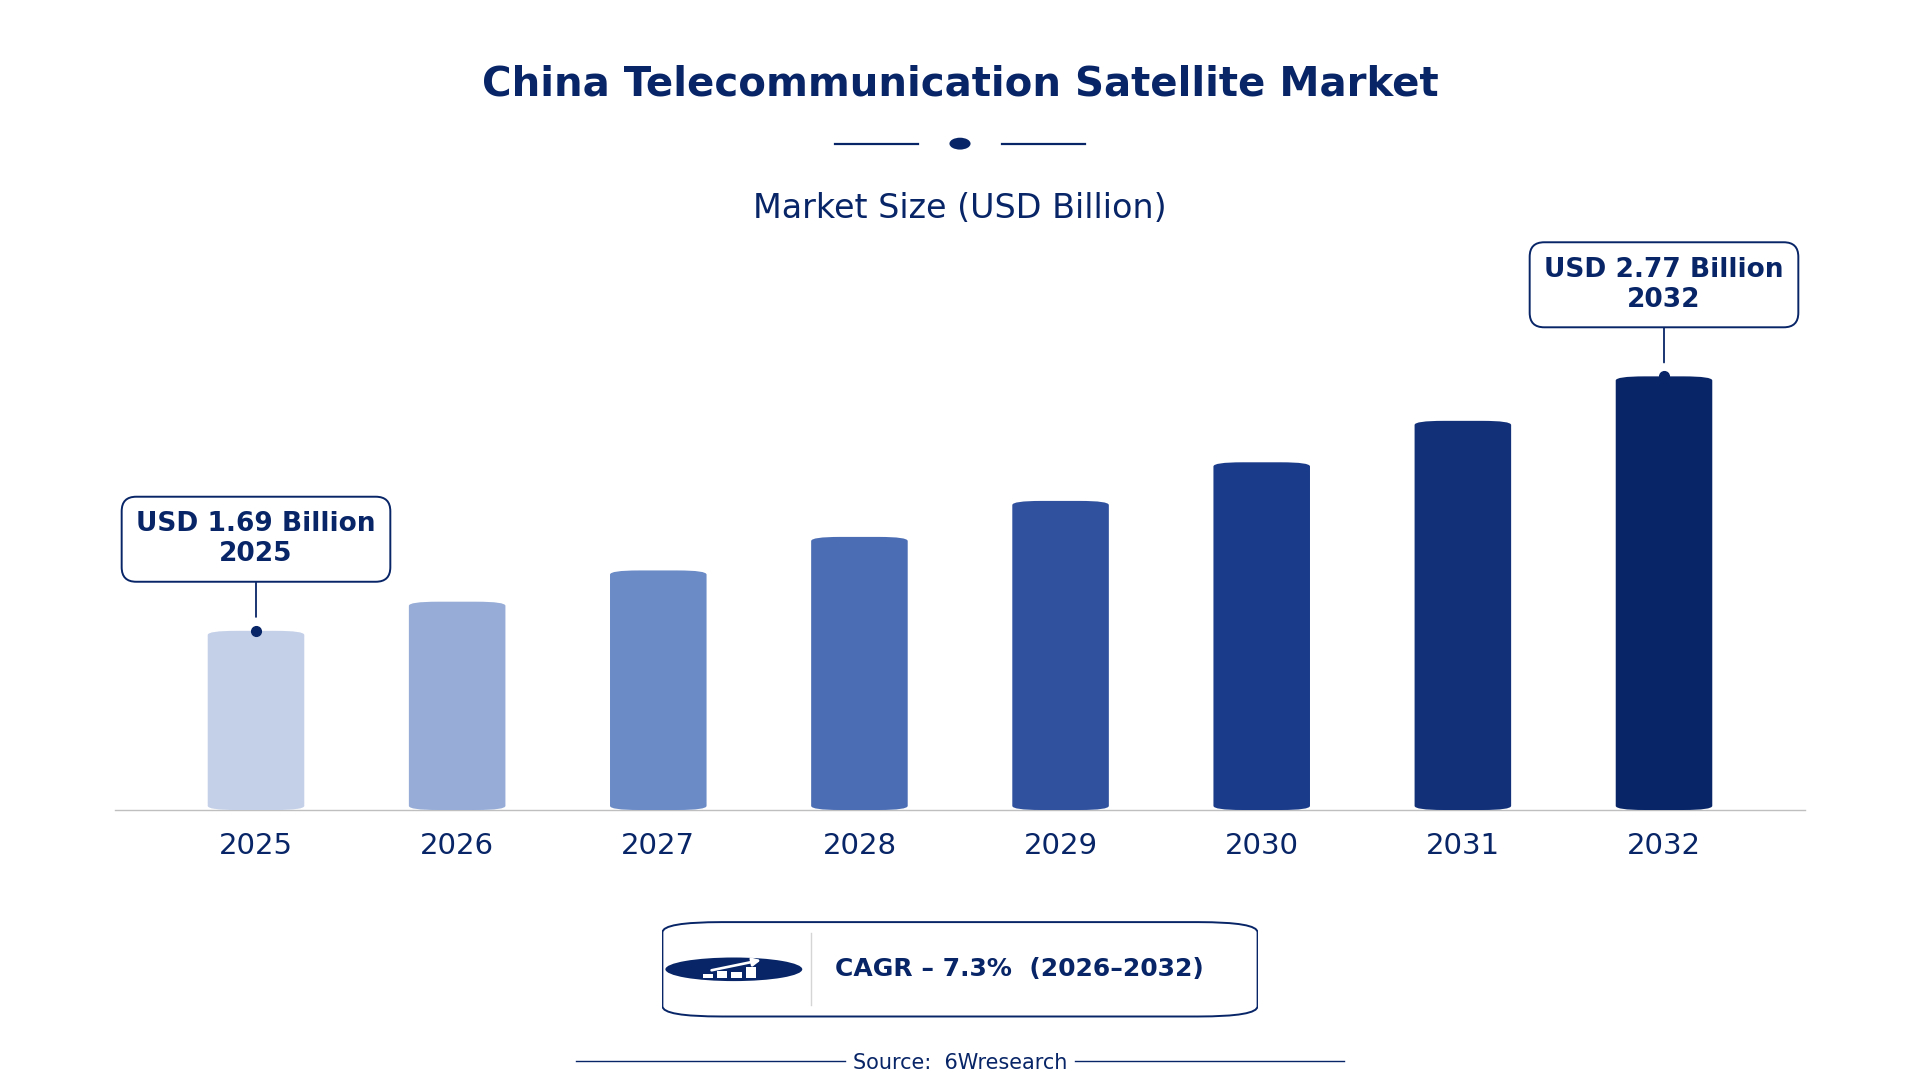
According to 6Wresearch internal database and industry insights, the China Telecommunication Satellite Market was valued at USD 1.69 billion in 2025 and is projected to reach USD 2.77 billion by 2032, growing at a CAGR of approximately 7.3% during 2026–2032.
China Telecommunication Satellite Market Highlights
| Report Metric | Details |
| Report Name | China Telecommunication Satellite Market |
| Market Size 2025 | USD 1.69 billion |
| Market Size 2032 | USD 2.77 billion |
| Absolute Growth 2025–2032 | USD 1.08 billion |
| CAGR 2026–2032 | 7.3% |
| Peak Annual Growth | 9.7% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Satellite Type, 2025 | Geostationary Satellites (41% share) |
| Leading Product Type, 2025 | Fixed Communication (53% share) |
| Leading Orbit Class, 2025 | GEO (36% share) |
| Leading Distribution Channel, 2025 | Satellite Builders (44% share) |
| Leading End User Industry, 2025 | National Carriers (37% share) |
| Fastest-Growing Satellite Type | LEO Satellites (8.3% CAGR) |
| Fastest-Growing Product Type | Internet Constellations (10.1% CAGR) |
| Fastest-Growing Orbit Class | LEO (9.5% CAGR) |
| Fastest-Growing Distribution Channel | Satellite Operators (9.5% CAGR) |
| Fastest-Growing End User Industry | Broadband Providers (9.2% CAGR) |
| Growing Sector | National Carriers |
| Key End Users | National Carriers, Broadband Providers, Government Services, Military & Airlines |
China Telecommunication Satellite Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
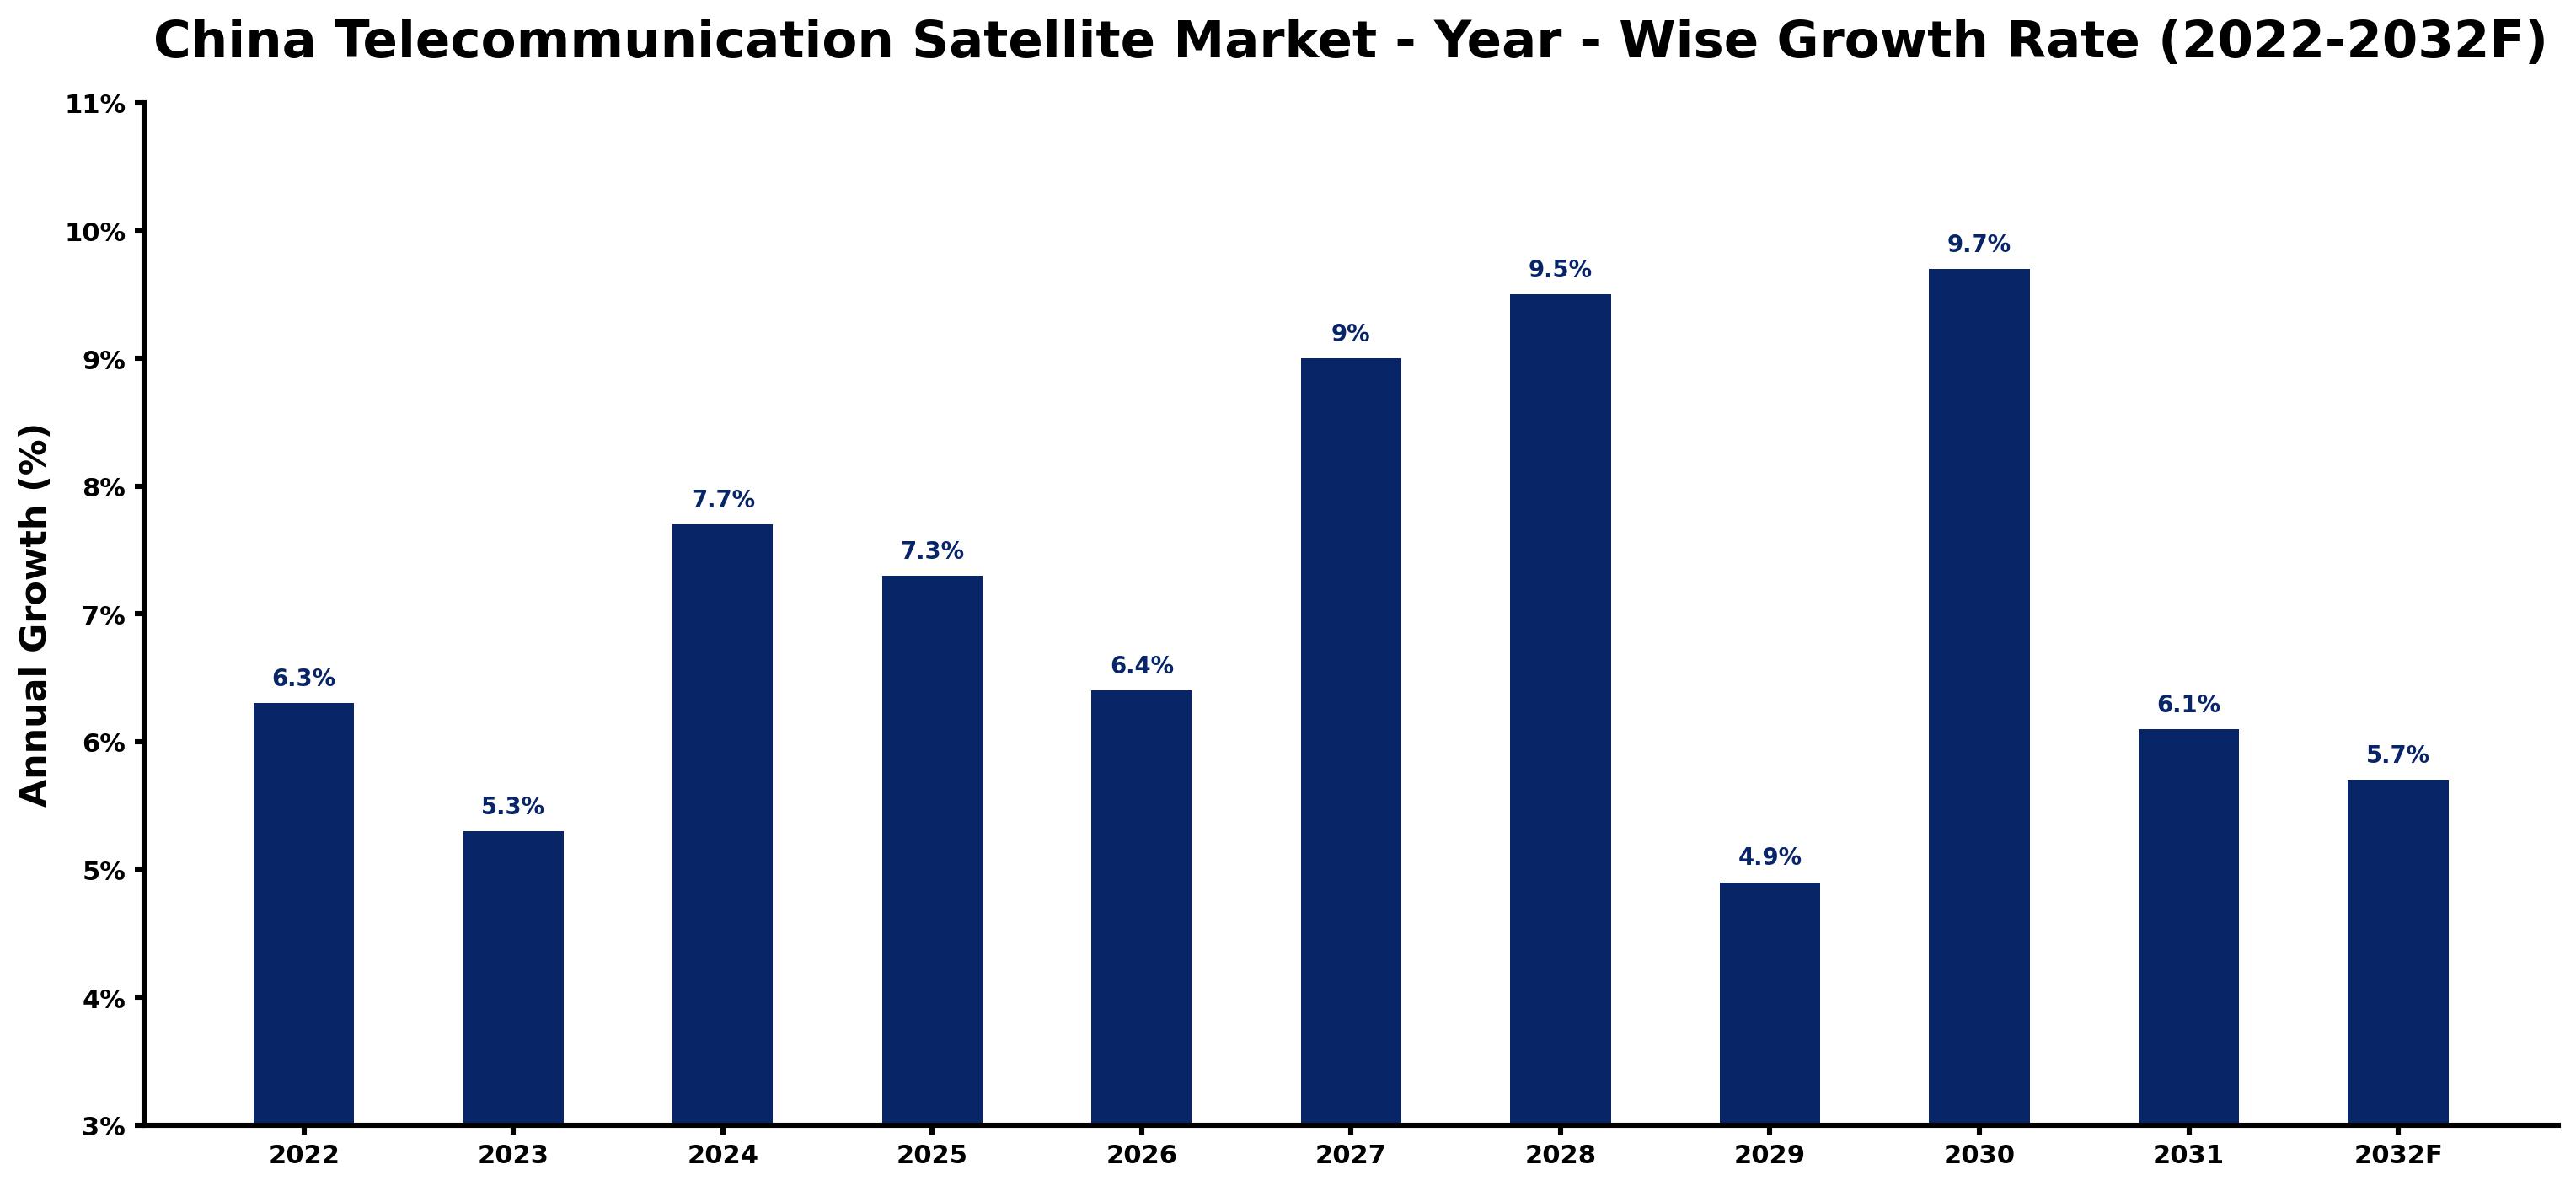
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.3 | Demand for telecommunication satellites increased due to improved broadband services and the 'Satellite Internet Development Plan'. |
| 2023 | 5.3 | Growth slowed as the market adjusted to operational challenges and an increase in satellite launches. |
| 2024 | 7.7 | The market expanded with new satellite projects and advancements in communication technology, driven by national carriers. |
| 2025 | 7.3 | Demand continued to rise, supported by the 'Satellite Internet Development Plan' and national infrastructure projects. |
| 2026 | 6.4 | Growth slowed as the market faced challenges in manufacturing and regulatory compliance, impacting timelines. |
| 2027 | 9.0 | An increase in private investment and government support boosted market performance, enhancing satellite capabilities. |
| 2028 | 9.5 | Demand accelerated with the expansion of broadband services and the launch of new satellite constellations, improving connectivity. |
| 2029 | 4.9 | Growth slowed as the market faced saturation in certain segments and competition intensified in satellite services. |
| 2030 | 9.7 | The market peaked due to substantial investments in satellite technology and infrastructure, enhancing service offerings. |
| 2031 | 6.1 | Growth slowed as the market stabilised after reaching peak demand levels in the previous year, impacting new projects. |
| 2032 | 5.7 | The market continues to grow, driven by ongoing advancements in satellite technology and increasing broadband penetration. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Telecommunication Satellite Market Synopsis
The Telecommunication Satellite Market in China encompasses advanced technology systems for communication purposes, including geostationary and low Earth orbit satellites. These systems provide essential services such as broadband internet and navigation. The market is growing due to increasing demand from national carriers and government services, with over 200 active satellites enhancing communication capabilities.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing broadband penetration drives demand for telecommunication satellites. | Driver | High | Fixed Communication |
| Expansion of satellite technology capabilities presents new opportunities for investment. | Opportunity | High | LEO Satellites |
| Regulatory challenges in satellite manufacturing may hinder market growth. | Restraint | Medium | Satellite Builders |
| High demand for broadband services creates a need for more satellites. | Driver | High | National Carriers |
| The need for advanced navigation systems limits growth in certain satellite segments. | Restraint | Medium | MEO Satellites |
| High costs associated with satellite launches can deter new entrants. | Challenge | High | Space Launch Partners |
| Competition among satellite operators may lead to price wars. | Challenge | Medium | Satellite Operators |
| Government initiatives support satellite technology development, creating opportunities. | Opportunity | High | Broadband Providers |
Evaluation of Drivers in China Telecommunication Satellite Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing broadband penetration in households increases demand for telecommunication satellites. | Fixed Communication | China's broadband penetration reached 70% by 2023, driving more satellite services. |
| Government support through funding boosts satellite manufacturing capabilities. | Satellite Builders | The National Development and Reform Commission approved $2 billion in 2022 for satellite technology. |
| The expansion of the BeiDou Navigation Satellite System increases demand for satellites. | Navigation Systems | The BeiDou system, operational since 2020, consists of over 30 satellites. |
| Increased investment in satellite technology encourages new market entrants. | LEO Satellites | China's space industry was valued at approximately $50 billion in 2022. |
| Rising global demand for internet services drives the need for satellite constellations. | Internet Constellations | China's LEO satellite constellation is expected to reach 12,000 satellites by 2030. |
The National Development and Reform Commission approved a budget of $2 billion in 2022, which improved satellite manufacturing capabilities. China's broadband penetration reached 70% of households by 2023, boosting demand for telecommunication satellites. The anticipated growth of China's LEO satellite constellation will also contribute to market expansion, as more households gain access to broadband services. Demand for satellite services is projected to rise as infrastructure improves.
Evaluation of Restraints in China Telecommunication Satellite Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High manufacturing costs limit the number of new satellite projects. | Satellite Builders | Manufacturers face challenges in meeting strict standards and regulations, impacting production timelines and increasing costs. |
| Regulatory compliance can delay satellite launches and operations. | Space Launch Partners | The updated 'National Space Administration Law' in 2021 introduced more stringent regulations, extending approval processes. |
| Limited availability of skilled workforce impacts satellite manufacturing efficiency. | Satellite Builders | The rapid development of the space industry has outpaced the training of qualified personnel, slowing production. |
| Competition in the satellite market can lead to price reductions, affecting profitability. | Satellite Operators | Increased number of operators has intensified rivalry, impacting pricing strategies and profit margins. |
| Technological challenges in satellite design can hinder innovation. | LEO Satellites | Complex engineering processes required for satellite manufacturing can slow down development and increase costs. |
China Telecommunication Satellite Market Challenges
China's telecommunication satellite market encounters regulatory hurdles that complicate project approvals, leading to delays in satellite launches and rising costs for producers. Updated regulations from the National Space Administration can extend approval processes by up to six months, financially straining manufacturers. Increasing production costs, driven by strict standards and complex engineering processes, can raise satellite system prices by 20%, negatively impacting suppliers' profit margins. A shortage of skilled engineers in satellite technology limits production capacity, causing delays that frustrate buyers seeking timely access to advanced communication solutions.
Trends in the China Telecommunication Satellite Market
The trends below show where the China Telecommunication Satellite Market is heading.
- Shift from Geostationary to LEO Satellites: China is increasingly prioritising LEO satellites for low-latency internet services. By 2023, the anticipated LEO satellite constellation is projected to reach 8,000 satellites, enhancing global coverage.
- Broadband Providers Prioritising Satellite Services: Broadband providers are broadening their service offerings through satellite technology. By 2023, China's broadband penetration reached 70%, driving demand for satellite internet services and improving connectivity.
- National Carriers Expanding Satellite Infrastructure: National carriers are making investments in satellite infrastructure to enhance communication capabilities. The 'Satellite Internet Development Plan' initiated in 2023 aims to improve satellite communication services across the country.
- Government Support for Satellite Technology Development: The Chinese government is actively backing advancements in satellite technology. The National Development and Reform Commission allocated $2 billion in 2022 for satellite manufacturing capabilities and infrastructure improvements.
Investment Opportunities in the China Telecommunication Satellite Market
Below are the investment opportunities with the strongest case in the China Telecommunication Satellite Market.
- Investment in Satellite Manufacturing: With a growing market, there is an opportunity to invest in satellite manufacturing. The National Development and Reform Commission's $2 billion budget in 2022 supports this sector's growth and innovation.
- Expansion of Ground Stations: The increasing number of satellite ground stations presents an opportunity for investment. By 2023, China exceeded 100 ground stations, significantly improving satellite operations and services.
- Partnerships for Satellite Technology Sharing: Establishing partnerships for satellite technology sharing is a viable entry route. With several nations collaborating on satellite technology, local partnerships can facilitate market entry and enhance capabilities.
- Development of Satellite Communication Services: The demand for satellite communication services is on the rise, with a projected market size of USD 2.77 billion by 2032. National carriers are key buyers, driving further investment and service expansion.
Government Initiatives in the China Telecommunication Satellite Market
The 'National Space Administration Law', updated in 2021, streamlined satellite regulations, making it easier for producers to navigate compliance. This law ensures that satellite operations align with international standards, improving the industry's credibility. Additionally, the 'Satellite Internet Development Plan', launched in 2021, aims to improve satellite communication infrastructure, benefiting both producers and buyers. The '14th Five-Year Plan' includes substantial investments in satellite technology and infrastructure, supporting the growth of the telecommunication satellite market in China.
In 2022, the National Development and Reform Commission approved a budget of $2 billion for satellite technology development. This funding supports satellite manufacturing capabilities and infrastructure improvements. The Ministry of Industry and Information Technology oversees the implementation of these initiatives, ensuring that satellite services meet national standards. Furthermore, the State Administration for Science, Technology and Industry for National Defense initiated the 'National Satellite Communication Strategy' in 2023, aimed at improving military communication systems and enhancing overall capabilities.
Future Insight of the China Telecommunication Satellite Market
By 2032, buyers and suppliers in China's telecommunication satellite market can expect transformative changes driven by the 'Satellite Internet Development Plan' and the '14th Five-Year Plan'. The aim to establish a complete satellite internet system by 2025 will enhance service availability nationwide. With China's LEO satellite constellation projected to reach 12,000 satellites by 2030, suppliers will experience a surge in demand for broadband services. Increased partnerships with international entities will further facilitate technology sharing and innovation, propelling market growth.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Satellite Type – Geostationary Satellites Dominated, LEO Satellites Expected to Grow Fastest
According to Sumit Sagar, AM at 6Wresearch, Geostationary Satellites accounted for a 41% market share by satellite type in 2025. Geostationary satellites dominate the market share due to their ability to provide stable communication links over fixed areas, which is essential for broadcasting services. Their reliability ensures connectivity for millions of users across urban and rural regions in China. LEO Satellites are set to record the highest CAGR in this split, 8.3% over 2026–2032. LEO satellites are experiencing rapid growth as they are crucial for delivering low-latency internet services and achieving global coverage. The rising demand for high-speed internet, particularly in underserved areas, is driving this segment's swift expansion. Suppliers should focus on enhancing LEO satellite capabilities to meet the increasing demand for broadband services.
By Product Type – Fixed Communication Dominated, Internet Constellations Expected to Grow Fastest
The largest product type category in 2025 was Fixed Communication, with a 53% share of total revenue. Fixed communication holds the largest market share as it is vital for providing stable communication services across various sectors. This segment is particularly important for national carriers that rely on fixed links for their operational requirements. Over 2026–2032, Internet Constellations are expected to post the fastest growth, at a CAGR of 10.1%. Internet constellations are witnessing rapid growth, driven by the urgent need to expand global internet access. With broadband penetration reaching 70% of households, this segment is set for substantial growth as more users seek reliable internet solutions. Buyers should consider investing in internet constellation technologies to ensure comprehensive coverage and connectivity.
By Orbit Class – GEO Dominated, LEO Expected to Grow Fastest
In 2025, GEO led the orbit class split with a 36% share. GEO satellites lead the market due to their critical role in long-distance communication and broadcasting. They provide extensive coverage that is especially advantageous for national carriers operating across vast geographic areas. The quickest growth will come from LEO, forecast to expand at a CAGR of 9.5% between 2026 and 2032. LEO satellites are growing at the fastest rate, increasingly essential for modern communication networks. The demand for low-latency services and enhanced global connectivity is propelling this rapid expansion. Suppliers must adapt to the rising demand for LEO satellites to maintain competitiveness in the market.
By Distribution Channel – Satellite Builders Dominated, Satellite Operators Expected to Grow Fastest
Satellite Builders held a 44% share of the China Telecommunication Satellite Market by distribution channel in 2025. Satellite builders hold the largest market share as they are directly involved in the manufacturing of satellites, which is fundamental for the industry's growth. Their expertise in satellite technology is crucial for meeting the rising demand for communication solutions. Satellite Operators are projected to grow fastest, at a CAGR of 9.5% during 2026–2032. Satellite operators are experiencing the fastest growth as they manage satellite networks and services that are increasingly vital for connectivity. The surge in satellite launches and operational networks is driving their rapid expansion. Buyers should collaborate with satellite operators to effectively leverage their expertise in managing satellite services.
By End User Industry – National Carriers Dominated, Broadband Providers Expected to Grow Fastest
National Carriers took a 37% share of end user industry in 2025, more than any other category. National carriers lead the market by utilising satellites for their national communication infrastructure, ensuring reliable connectivity for millions of users. Their extensive networks are crucial for maintaining communication across urban and rural areas alike. Broadband Providers are set to record the highest CAGR in this split, 9.2% over 2026–2032. Broadband providers are rapidly expanding, relying on satellites to deliver internet services to a broader audience. The increasing demand for high-speed internet access is significantly propelling this segment's growth. Suppliers should align their offerings with the needs of broadband providers to capture emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Telecommunication Satellite Market Outlook
- Market Size of China Telecommunication Satellite Market, 2025
- Forecast of China Telecommunication Satellite Market, 2032
- Historical Data and Forecast of China Telecommunication Satellite Revenues & Volume for the Period 2022 - 2032F
- China Telecommunication Satellite Market Trend Evolution
- China Telecommunication Satellite Market Drivers and Challenges
- China Telecommunication Satellite Price Trends
- China Telecommunication Satellite Porter's Five Forces
- China Telecommunication Satellite Industry Life Cycle
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Satellite Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Geostationary Satellites for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By LEO Satellites for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By MEO Satellites for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By SATCOM Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Fixed Communication for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Internet Constellations for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Navigation Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Terminals & Dishes for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Orbit Class for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By GEO for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By LEO for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By MEO for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Ground Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Satellite Builders for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Space Launch Partners for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Satellite Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Defense Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By National Carriers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Broadband Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Government Services for the Period 2022 - 2032F
- Historical Data and Forecast of China Telecommunication Satellite Market Revenues & Volume By Military & Airlines for the Period 2022 - 2032F
- China Telecommunication Satellite Import Export Trade Statistics
- Market Opportunity Assessment By Satellite Type
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Orbit Class
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Telecommunication Satellite Top Companies Market Share
- China Telecommunication Satellite Competitive Benchmarking By Technical and Operational Parameters
- China Telecommunication Satellite Company Profiles
- China Telecommunication Satellite Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Satellite Type
- Geostationary Satellites
- LEO Satellites
- MEO Satellites
- SATCOM Equipment
By Product Type
- Fixed Communication
- Internet Constellations
- Navigation Systems
- Terminals & Dishes
By Orbit Class
- GEO
- LEO
- MEO
- Ground Segment
By Distribution Channel
- Satellite Builders
- Space Launch Partners
- Satellite Operators
- Defense Integrators
By End User Industry
- National Carriers
- Broadband Providers
- Government Services
- Military & Airlines































