China Thermal Management Solutions Market Size & Growth Rate
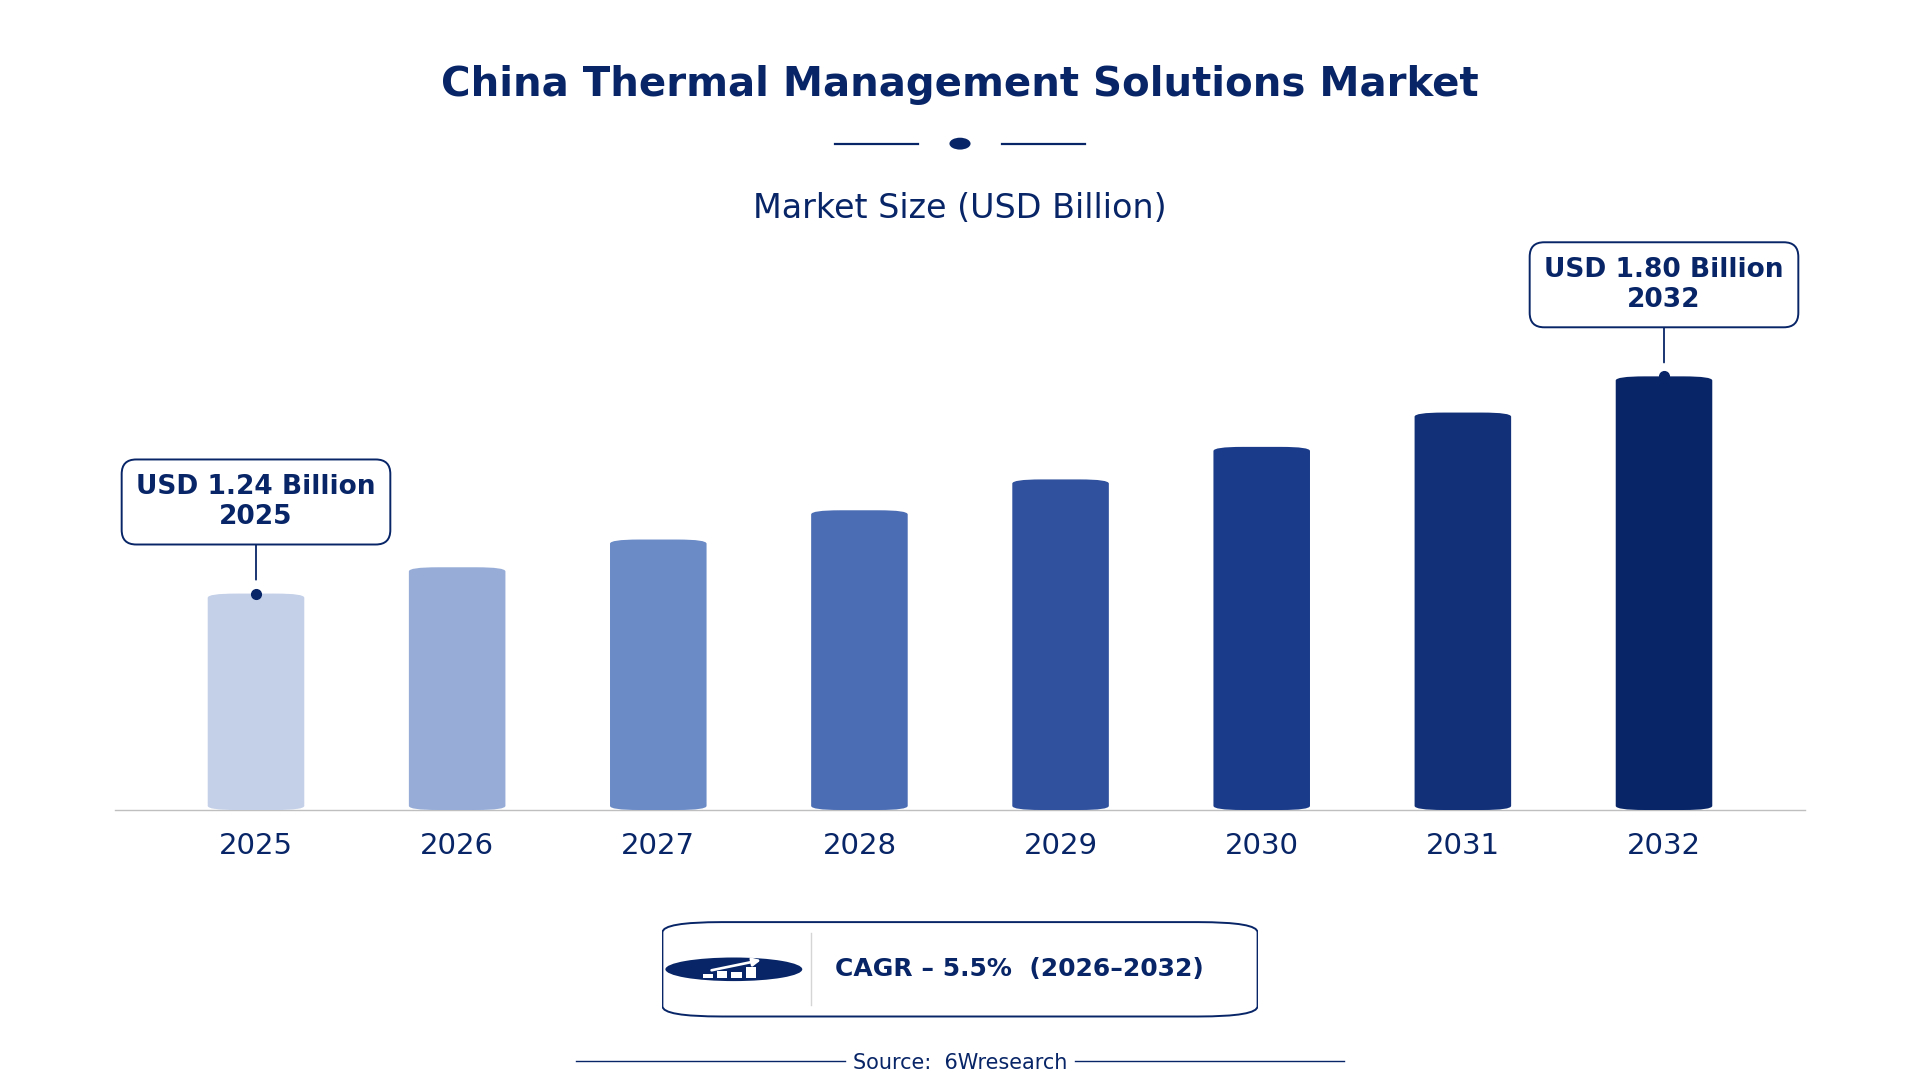
According to 6Wresearch internal database and industry insights, the China Thermal Management Solutions Market was valued at USD 1.24 billion in 2025 and is projected to reach USD 1.80 billion by 2032, growing at a CAGR of approximately 5.5% during 2026–2032.
China Thermal Management Solutions Market Highlights
| Report Metric | Details |
| Report Name | China Thermal Management Solutions Market |
| Market Size 2025 | USD 1.24 billion |
| Market Size 2032 | USD 1.80 billion |
| Absolute Growth 2025–2032 | USD 0.56 billion |
| CAGR 2026–2032 | 5.5% |
| Peak Annual Growth | 8.0% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Thermal Management Solutions, 2025 | Liquid Cooling Systems (52% share) |
| Leading Product Type, 2025 | Cold Plates (38% share) |
| Leading Technology, 2025 | Liquid Loop Cooling (39% share) |
| Leading Distribution Channel, 2025 | OEM Thermal Vendors (41% share) |
| Leading End User Industry, 2025 | HPC & Data Centers (52% share) |
| Fastest-Growing Thermal Management Solutions | Phase Change Materials (8.1% CAGR) |
| Fastest-Growing Product Type | PCM Sheets (7.4% CAGR) |
| Fastest-Growing Distribution Channel | System Integrators (7.2% CAGR) |
| Fastest-Growing End User Industry | Battery Systems (6.9% CAGR) |
| Growing Sector | Battery Systems |
| Key End Users | HPC & Data Centers, Laptop/Desktop OEMs, Consumer Electronics, Battery Systems |
China Thermal Management Solutions Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
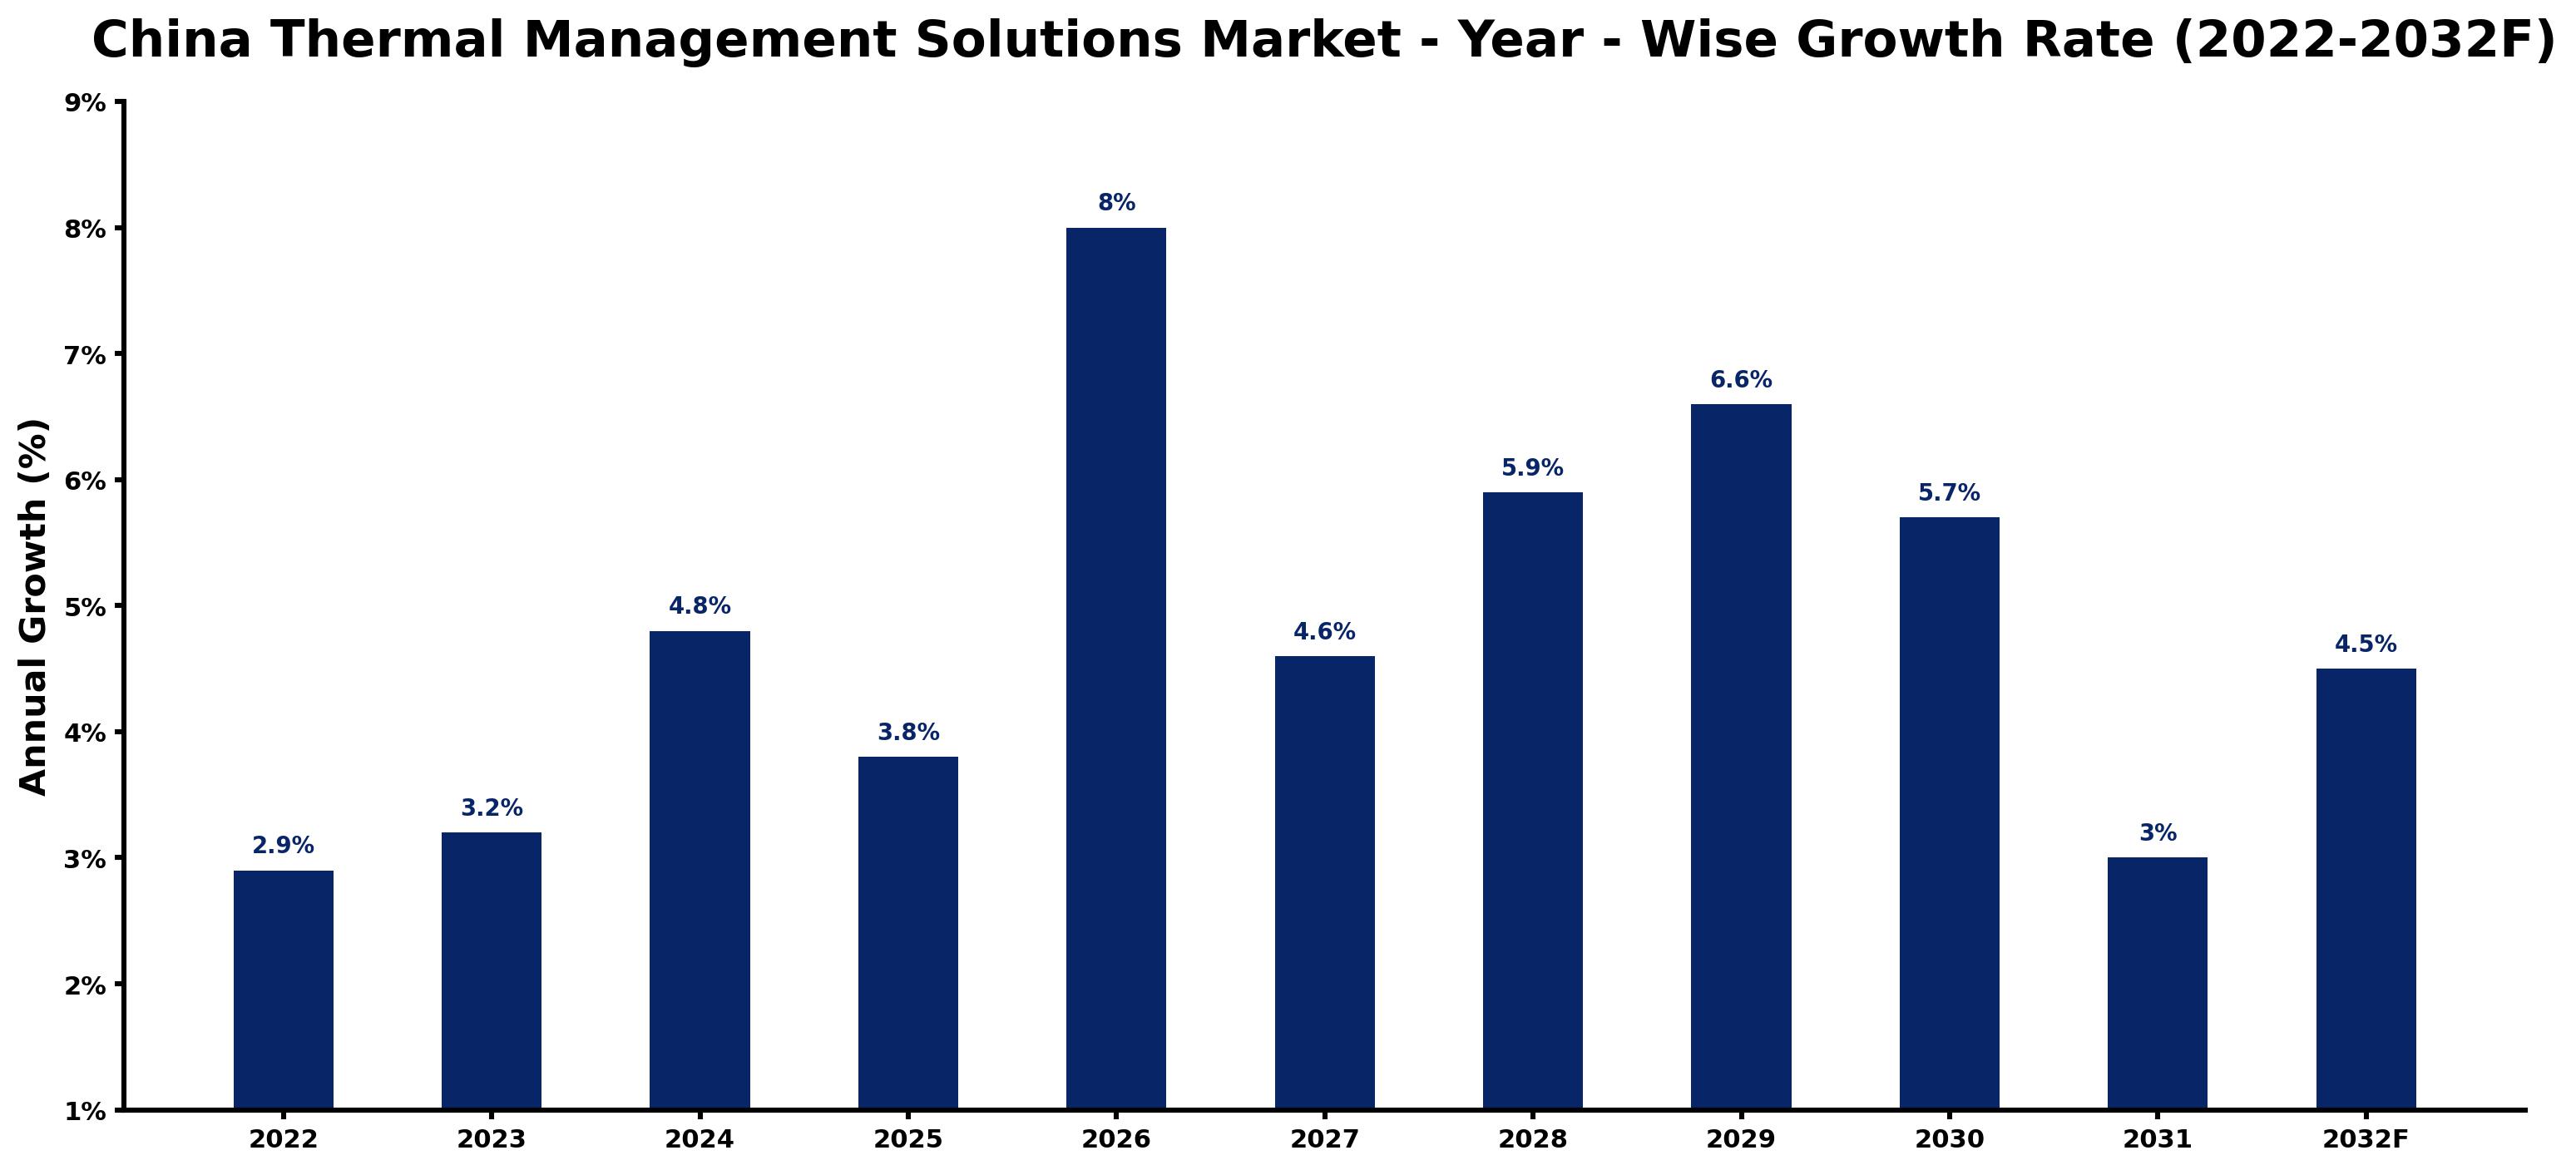
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.9 | The market experienced steady demand from electronics manufacturing in China. |
| 2023 | 3.2 | Growth was supported by increased investments in data center infrastructure. |
| 2024 | 4.8 | Demand surged as HPC applications expanded in various sectors. |
| 2025 | 3.8 | A slowdown occurred due to adjustments in production capacities following rapid growth. |
| 2026 | 8.0 | The market rebounded sharply, driven by rising adoption of liquid cooling systems in data centers. |
| 2027 | 4.6 | Growth slowed as the market stabilised after rapid expansion in previous years. |
| 2028 | 5.9 | Demand increased again, supported by the Green Data Center Program promoting efficient cooling technologies. |
| 2029 | 6.6 | The market continued to grow, driven by higher demand from battery systems in electric vehicles. |
| 2030 | 5.7 | Growth slowed as competition intensified among thermal management solution providers in the market. |
| 2031 | 3.0 | A further slowdown occurred as market maturity set in, affecting growth rates. |
| 2032 | 4.5 | The market is projected to see growth driven by new energy efficiency standards in manufacturing. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Thermal Management Solutions Market Synopsis
The China Thermal Management Solutions Market encompasses technologies and materials designed to control heat across various applications. These solutions are essential for cooling electronic devices, improving battery performance, and ensuring efficient thermal regulation in data centers. The market is expanding due to strong domestic demand from the electronics manufacturing sector, valued at over 3 trillion CNY, and the increasing adoption of advanced cooling technologies in data centers. With the average annual growth rate of HPC demand around 20%, there is a notable opportunity for suppliers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in data centers drive demand for effective cooling solutions. | Driver | High | Liquid Cooling Systems |
| Increasing adoption of Phase Change Materials in electric vehicle battery systems presents growth opportunities. | Opportunity | High | Phase Change Materials |
| The demand for heat pipe assemblies in laptops is driven by a market of over 300 million units annually. | Driver | High | Heat Pipe Assemblies |
| The Guangdong province is a major hub for thermal management solution production, creating opportunities for local suppliers. | Opportunity | Medium | Liquid Cooling Systems |
| Cost pressures from raw materials can affect production timelines for manufacturers. | Restraint | High | Thermal Interface Materials |
| The need for compliance with national standards can slow down product approvals. | Restraint | Medium | Liquid Cooling Systems |
| Competition among suppliers can lead to pricing pressures, impacting profitability. | Challenge | High | Liquid Cooling Systems |
| Technological advancements require continuous investment, which can strain smaller firms. | Challenge | Medium | Phase Change Materials |
Evaluation of Drivers in China Thermal Management Solutions Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising investments in data centers | Liquid Cooling Systems | This trend is driven by the increasing demand for efficient cooling solutions in high-performance computing environments, leading to a projected 30% rise in liquid cooling system adoption by 2026. |
| Growing demand for heat pipe assemblies | Heat Pipe Assemblies | With over 300 million laptops produced annually, manufacturers are increasingly adopting heat pipe assemblies to ensure effective cooling in electronic devices. |
| Expansion of electric vehicle production | Phase Change Materials | The rising use of Phase Change Materials in battery systems is driven by the increasing focus on energy efficiency in electric vehicles, supporting market growth. |
| Government support for energy-efficient technologies | Thermal Interface Materials | The establishment of national standards for thermal interface materials enhances product quality and safety, encouraging manufacturers to adopt these solutions. |
| Increased consumer electronics market size | Cold Plates | China's consumer electronics market, projected to reach 1.5 trillion CNY by 2025, drives demand for advanced cooling solutions like cold plates. |
The Thermal Management Solutions market in China is expanding as investments in data centers, rising demand for efficient cooling technologies, and the growth of electric vehicle production drive market activity. The average annual growth rate of HPC demand in China is approximately 20%, leading to increased adoption of effective thermal management solutions. With over 300 million laptops produced annually, manufacturers are increasingly turning to heat pipe assemblies for effective cooling.
Evaluation of Restraints in China Thermal Management Solutions Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stringent regulatory standards slow product approvals, delaying access for buyers in electronics manufacturing. | Liquid Cooling Systems | Compliance with new thermal interface material standards issued by the State Administration for Market Regulation in 2023 complicates the approval process. |
| A skills gap in the workforce hampers production capabilities for thermal management solutions. | Heat Pipe Assemblies | The rapid growth of the industry demands specialised expertise, leading to project delays and increased training costs. |
| Technological advancements are outpacing current production capabilities, increasing operational costs for suppliers. | Phase Change Materials | Suppliers must invest heavily in new equipment to keep up with evolving technology demands. |
| Fluctuating prices for raw materials impact budgets for buyers in consumer electronics. | Liquid Cooling Systems | Volatility in material costs can lead to increased end-user prices for thermal management solutions. |
| Limited awareness of advanced thermal management technologies reduces market penetration. | Thermal Interface Materials | Many manufacturers are hesitant to adopt new technologies without proven benefits. |
China Thermal Management Solutions Market Challenges
The China Thermal Management Solutions Market faces strict regulatory standards that can delay product approvals, creating significant challenges for buyers in electronics manufacturing who need timely access to cooling technologies. Suppliers are encountering a skills gap due to rapid industry growth, which can lead to project delays and increased training costs that may reach up to 15% of project budgets. Technological advancements are outpacing current production capabilities, compelling suppliers to invest heavily in new equipment, potentially raising operational costs by as much as 20%. Buyers also contend with fluctuating raw material prices, which can inflate costs for end-users in consumer electronics by approximately 10%.
Trends in the China Thermal Management Solutions Market
The trends below show where the China Thermal Management Solutions Market is heading.
- Shift Towards Liquid Cooling Systems in Data Centers: China is increasingly adopting liquid cooling systems in data centres to boost energy efficiency. The National Energy Administration's programme aims for a 30% rise in adoption by 2026, benefiting data centre operators.
- Growing Use of Phase Change Materials in Electric Vehicles: The use of Phase Change Materials is on the rise in electric vehicle battery systems, driven by the need for effective thermal regulation. This trend is expected to grow as electric vehicle production increases significantly.
- Adoption of Advanced Thermal Interface Materials: The introduction of new standards for thermal interface materials in 2023 is promoting improved product quality and safety. This initiative, led by the State Administration for Market Regulation, is set to enhance market competitiveness.
- Increase in High-Performance Computing Applications: The demand for high-performance computing applications is driving the need for advanced thermal management solutions. The average annual growth rate of HPC demand in China is around 20%, indicating substantial market potential.
Investment Opportunities in the China Thermal Management Solutions Market
Below are the investment opportunities with the strongest case in the China Thermal Management Solutions Market.
- Investment in Data Center Infrastructure: Data center operators in China are seeking advanced thermal management solutions to improve energy efficiency. With the market projected to reach 1.5 trillion CNY by 2025, suppliers can enter through partnerships with local vendors.
- Expansion in Electric Vehicle Market: The growing electric vehicle market creates opportunities for suppliers of thermal management solutions. With increased production, manufacturers can partner with automotive OEMs to provide effective cooling technologies.
- Development of Phase Change Materials: There is a rising demand for Phase Change Materials in various applications, particularly in battery systems. Suppliers can invest in R&D to innovate and meet this demand, especially in the Guangdong province.
- Emergence of Green Data Centers: The Green Data Center Program initiated in 2022 promotes energy-efficient technologies. Suppliers can engage with data center operators to provide tailored thermal management solutions.
Government Initiatives in the China Thermal Management Solutions Market
The 'Smart Manufacturing 2025' initiative launched by the Ministry of Industry and Information Technology in 2021 aims to improve thermal management solutions in manufacturing. This initiative focuses on enhancing energy efficiency and encourages the adoption of advanced technologies. By promoting standards and best practices, it supports manufacturers in meeting growing energy demands while ensuring product quality. The initiative also aims to stimulate innovation in thermal management technologies, benefiting both producers and consumers in the market.
In 2023, the National Development and Reform Commission allocated funding to support the Green Data Center Program, which promotes efficient cooling technologies. This programme aims to improve energy efficiency in data centres and is projected to boost the adoption of liquid cooling systems. The Ministry of Ecology and Environment is also involved, providing subsidies for companies that implement advanced thermal management technologies. These efforts are designed to reduce energy consumption and promote sustainable practices in the industry.
Future Insight of the China Thermal Management Solutions Market
The China Thermal Management Solutions Market is set for substantial change by 2032, with a strong focus on energy efficiency. The National Energy Administration's programme to enhance data centre efficiency is expected to drive liquid cooling system adoption by 30% by 2026, creating opportunities for both buyers and suppliers. The increasing use of Phase Change Materials in electric vehicle battery systems will further stimulate demand. The establishment of national standards for thermal interface materials will streamline production processes, promoting a more competitive market environment.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Thermal Management Solutions – Liquid Cooling Systems Dominated, Phase Change Materials Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, with a 52% revenue share in 2025, Liquid Cooling Systems was the largest thermal management solutions category. Liquid Cooling Systems hold the largest market share because they are essential for effective thermal management in high-performance computing and data centers. The anticipated 30% rise in adoption by 2026 underscores their critical role in maintaining operational efficiency in these environments. Phase Change Materials are set to record the highest CAGR in this split, 8.1% over 2026–2032. Phase Change Materials are rapidly growing as they find increasing applications in electric vehicle battery systems, which are projected to expand significantly. Government initiatives supporting advanced cooling technologies are expected to further propel this segment's growth. Suppliers should focus on enhancing their liquid cooling systems and phase change materials to meet the rising demand in China.
By Product Type – Cold Plates Dominated, PCM Sheets Expected to Grow Fastest
Cold Plates accounted for a 38% market share by product type in 2025. Cold Plates dominate the market share as they are widely used in liquid cooling systems, providing effective heat exchange that is crucial for performance. Their significant role in high-performance computing environments highlights their importance in the thermal management sector. Over 2026–2032, PCM Sheets are expected to post the fastest growth, at a CAGR of 7.4%. PCM Sheets are experiencing the fastest growth due to their specialised applications in thermal energy storage solutions, which are increasingly relevant in various industries. The rising emphasis on energy efficiency is expected to drive demand for these materials sharply. Suppliers must prioritise the innovation of PCM Sheet technologies to meet the growing demand for efficient thermal energy storage solutions.
By Technology – Liquid Loop Cooling Dominated and Is Expected to Record the Fastest Growth
In 2025, Liquid Loop Cooling led the technology split with a 39% share. Liquid Loop Cooling leads the market share as it is increasingly adopted in high-performance computing environments, where efficient thermal management is paramount. This technology's effectiveness in maintaining optimal operating conditions solidifies its dominant position. The same category is also set to grow fastest, at a CAGR of 7.2% during 2026–2032. Liquid Loop Cooling is also the fastest-growing technology, as its advantages in performance and efficiency continue to attract more users in the HPC sector. Its established lead in the market will likely widen as demand for advanced cooling solutions increases. Suppliers should prioritise advancements in Liquid Loop Cooling technologies to stay competitive in the growing HPC market.
By Distribution Channel – OEM Thermal Vendors Dominated, System Integrators Expected to Grow Fastest
The largest distribution channel category in 2025 was OEM Thermal Vendors, with a 41% share of total revenue. OEM Thermal Vendors lead the market share as they are key suppliers of thermal management solutions in the electronics sector. Their established relationships with manufacturers ensure a consistent demand for their products, reinforcing their market position. System Integrators are projected to grow fastest, at a CAGR of 7.2% during 2026–2032. System Integrators are witnessing the fastest growth as they play a crucial role in integrating thermal solutions into larger systems for end-users. This trend reflects the increasing complexity of thermal management requirements across various applications. Suppliers should consider partnerships with System Integrators to expand their reach and enhance product offerings in integrated thermal solutions.
By End User Industry – HPC & Data Centers Dominated, Battery Systems Expected to Grow Fastest
HPC & Data Centers took a 52% share of end user industry in 2025, more than any other category. HPC & Data Centers account for the largest market share due to the substantial demand for advanced cooling solutions in these sectors. The ongoing expansion of data centers in China continues to fuel this demand, highlighting the need for effective thermal management. Battery Systems are set to record the highest CAGR in this split, 6.9% over 2026–2032. Battery Systems are the fastest-growing segment as they become increasingly vital for thermal management in electric vehicles and energy storage solutions. The surge in electric vehicle adoption is a significant factor driving this growth. Suppliers should focus on developing tailored thermal management solutions for battery systems to capitalise on the expanding electric vehicle market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Thermal Management Solutions Market Outlook
- Market Size of China Thermal Management Solutions Market, 2025
- Forecast of China Thermal Management Solutions Market, 2032
- Historical Data and Forecast of China Thermal Management Solutions Revenues & Volume for the Period 2022 - 2032F
- China Thermal Management Solutions Market Trend Evolution
- China Thermal Management Solutions Market Drivers and Challenges
- China Thermal Management Solutions Price Trends
- China Thermal Management Solutions Porter's Five Forces
- China Thermal Management Solutions Industry Life Cycle
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Thermal Management Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Heat Pipe Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Liquid Cooling Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Phase Change Materials for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Thermal Interface Materials for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Vapor Chambers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Cold Plates for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By PCM Sheets for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By TIM Pastes for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Technology for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Vapor-Phase Cooling for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Liquid Loop Cooling for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Solid-Liquid Phase for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Metal/Graphite Pastes for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By OEM Thermal Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Laptop/Desktop OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By HPC & Data Centers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Battery Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Management Solutions Market Revenues & Volume By Consumer Electronics for the Period 2022 - 2032F
- China Thermal Management Solutions Import Export Trade Statistics
- Market Opportunity Assessment By Thermal Management Solutions
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Technology
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Thermal Management Solutions Top Companies Market Share
- China Thermal Management Solutions Competitive Benchmarking By Technical and Operational Parameters
- China Thermal Management Solutions Company Profiles
- China Thermal Management Solutions Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Thermal Management Solutions
- Heat Pipe Assemblies
- Liquid Cooling Systems
- Phase Change Materials
- Thermal Interface Materials
By Product Type
- Vapor Chambers
- Cold Plates
- PCM Sheets
- TIM Pastes
By Technology
- Vapor-Phase Cooling
- Liquid Loop Cooling
- Solid-Liquid Phase
- Metal/Graphite Pastes
By Distribution Channel
- OEM Thermal Vendors
- System Integrators
- Direct Sales
- Distributors
By End User Industry
- Laptop/Desktop OEMs
- HPC & Data Centers
- Battery Systems
- Consumer Electronics































