China Thermal Processing Market Size & Growth Rate
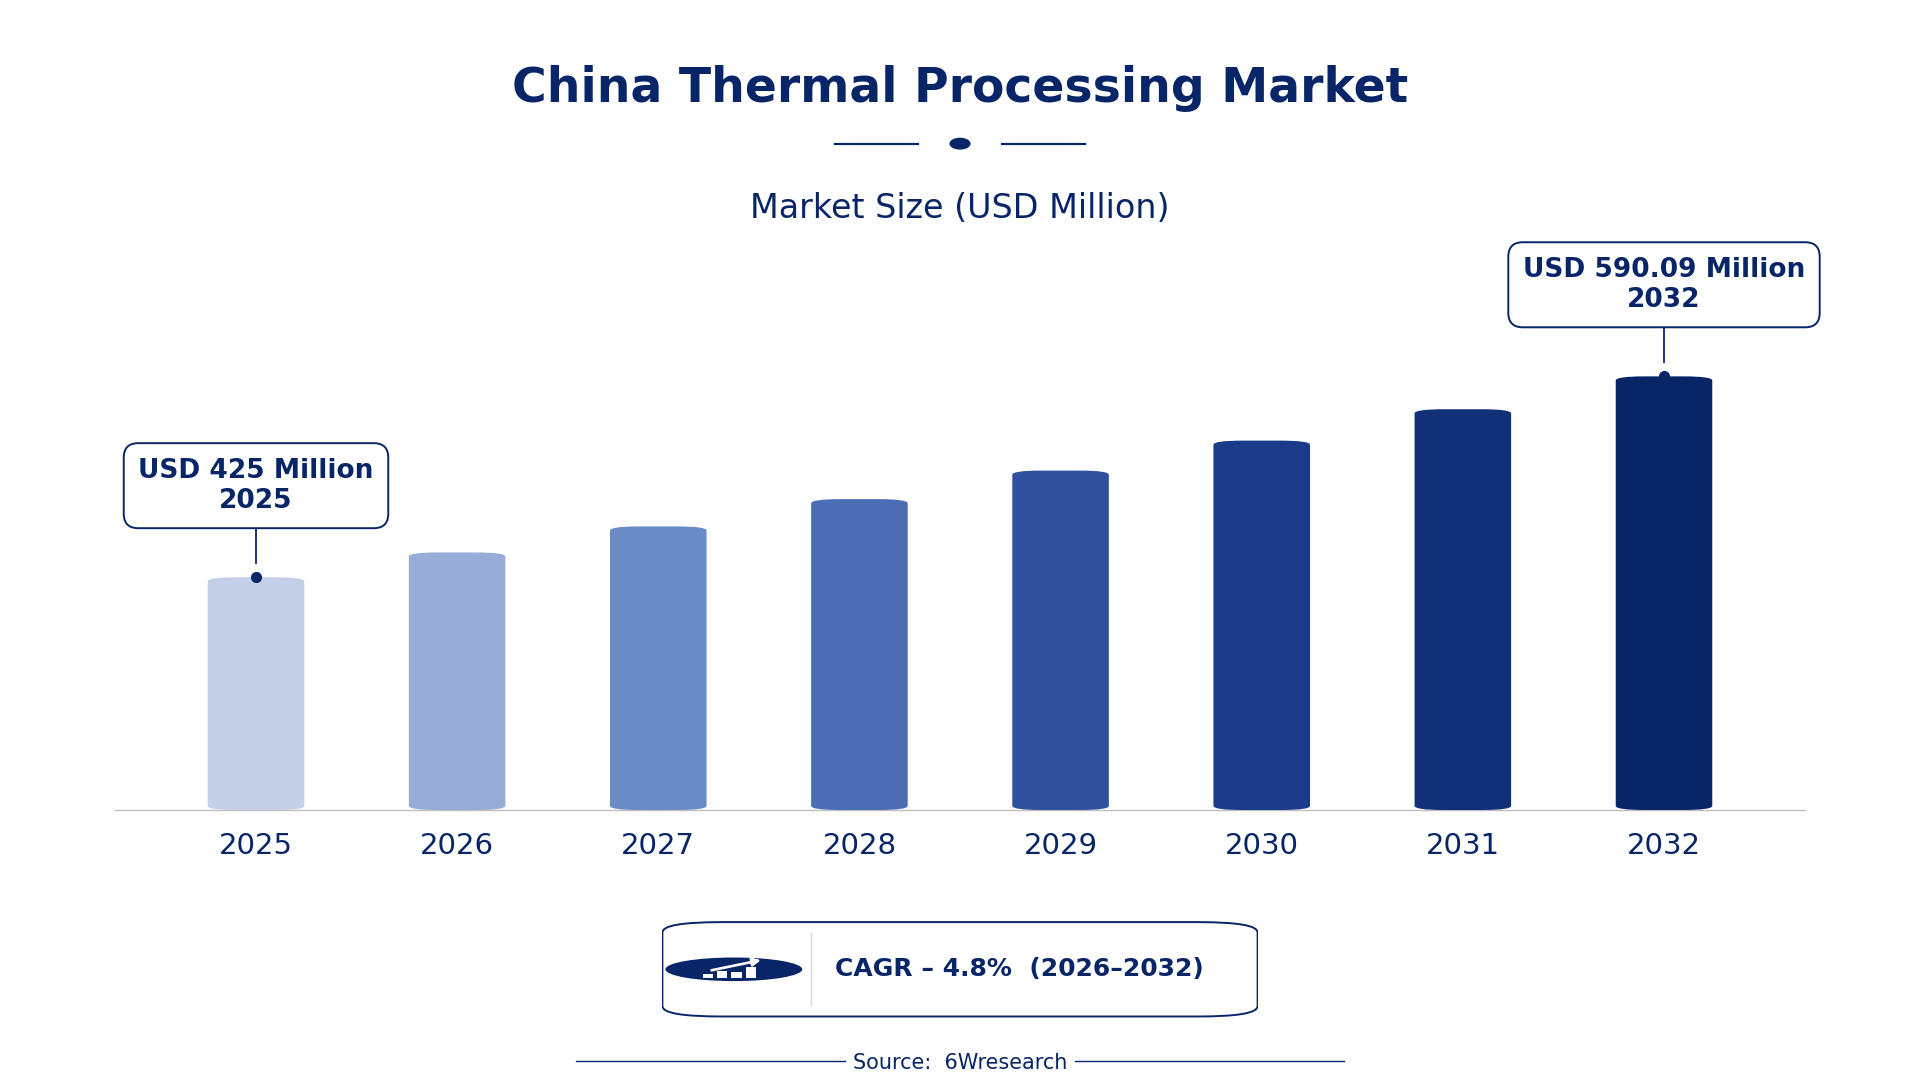
According to 6Wresearch internal database and industry insights, the China Thermal Processing Market was valued at USD 425.0 million in 2025 and is projected to reach USD 590.09 million by 2032, growing at a CAGR of approximately 4.8% during 2026–2032.
China Thermal Processing Market Highlights
| Report Metric | Details |
| Report Name | China Thermal Processing Market |
| Market Size 2025 | USD 425.0 million |
| Market Size 2032 | USD 590.09 million |
| Absolute Growth 2025–2032 | USD 165.09 million |
| CAGR 2026–2032 | 4.8% |
| Peak Annual Growth | 7.3% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Thermal Processing, 2025 | Heat Treatment Ovens (44% share) |
| Leading Product Type, 2025 | Batch/Furnaces (43% share) |
| Leading Processing Method, 2025 | Annealing/Quenching (52% share) |
| Leading Distribution Channel, 2025 | Equipment Vendors (47% share) |
| Leading End User Industry, 2025 | Automotive Components (47% share) |
| Fastest-Growing Thermal Processing | Food Thermal Processing (6.8% CAGR) |
| Fastest-Growing Product Type | Retort Systems (7.4% CAGR) |
| Fastest-Growing Processing Method | Sterilization (6.8% CAGR) |
| Fastest-Growing Distribution Channel | Food Equipment Suppliers (6.5% CAGR) |
| Fastest-Growing End User Industry | Food Manufacturing (6.7% CAGR) |
| Growing Sector | Food Manufacturing |
| Key End Users | Food Manufacturers, Electronics Manufacturers, Automotive Components, Metal Fabrication |
China Thermal Processing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
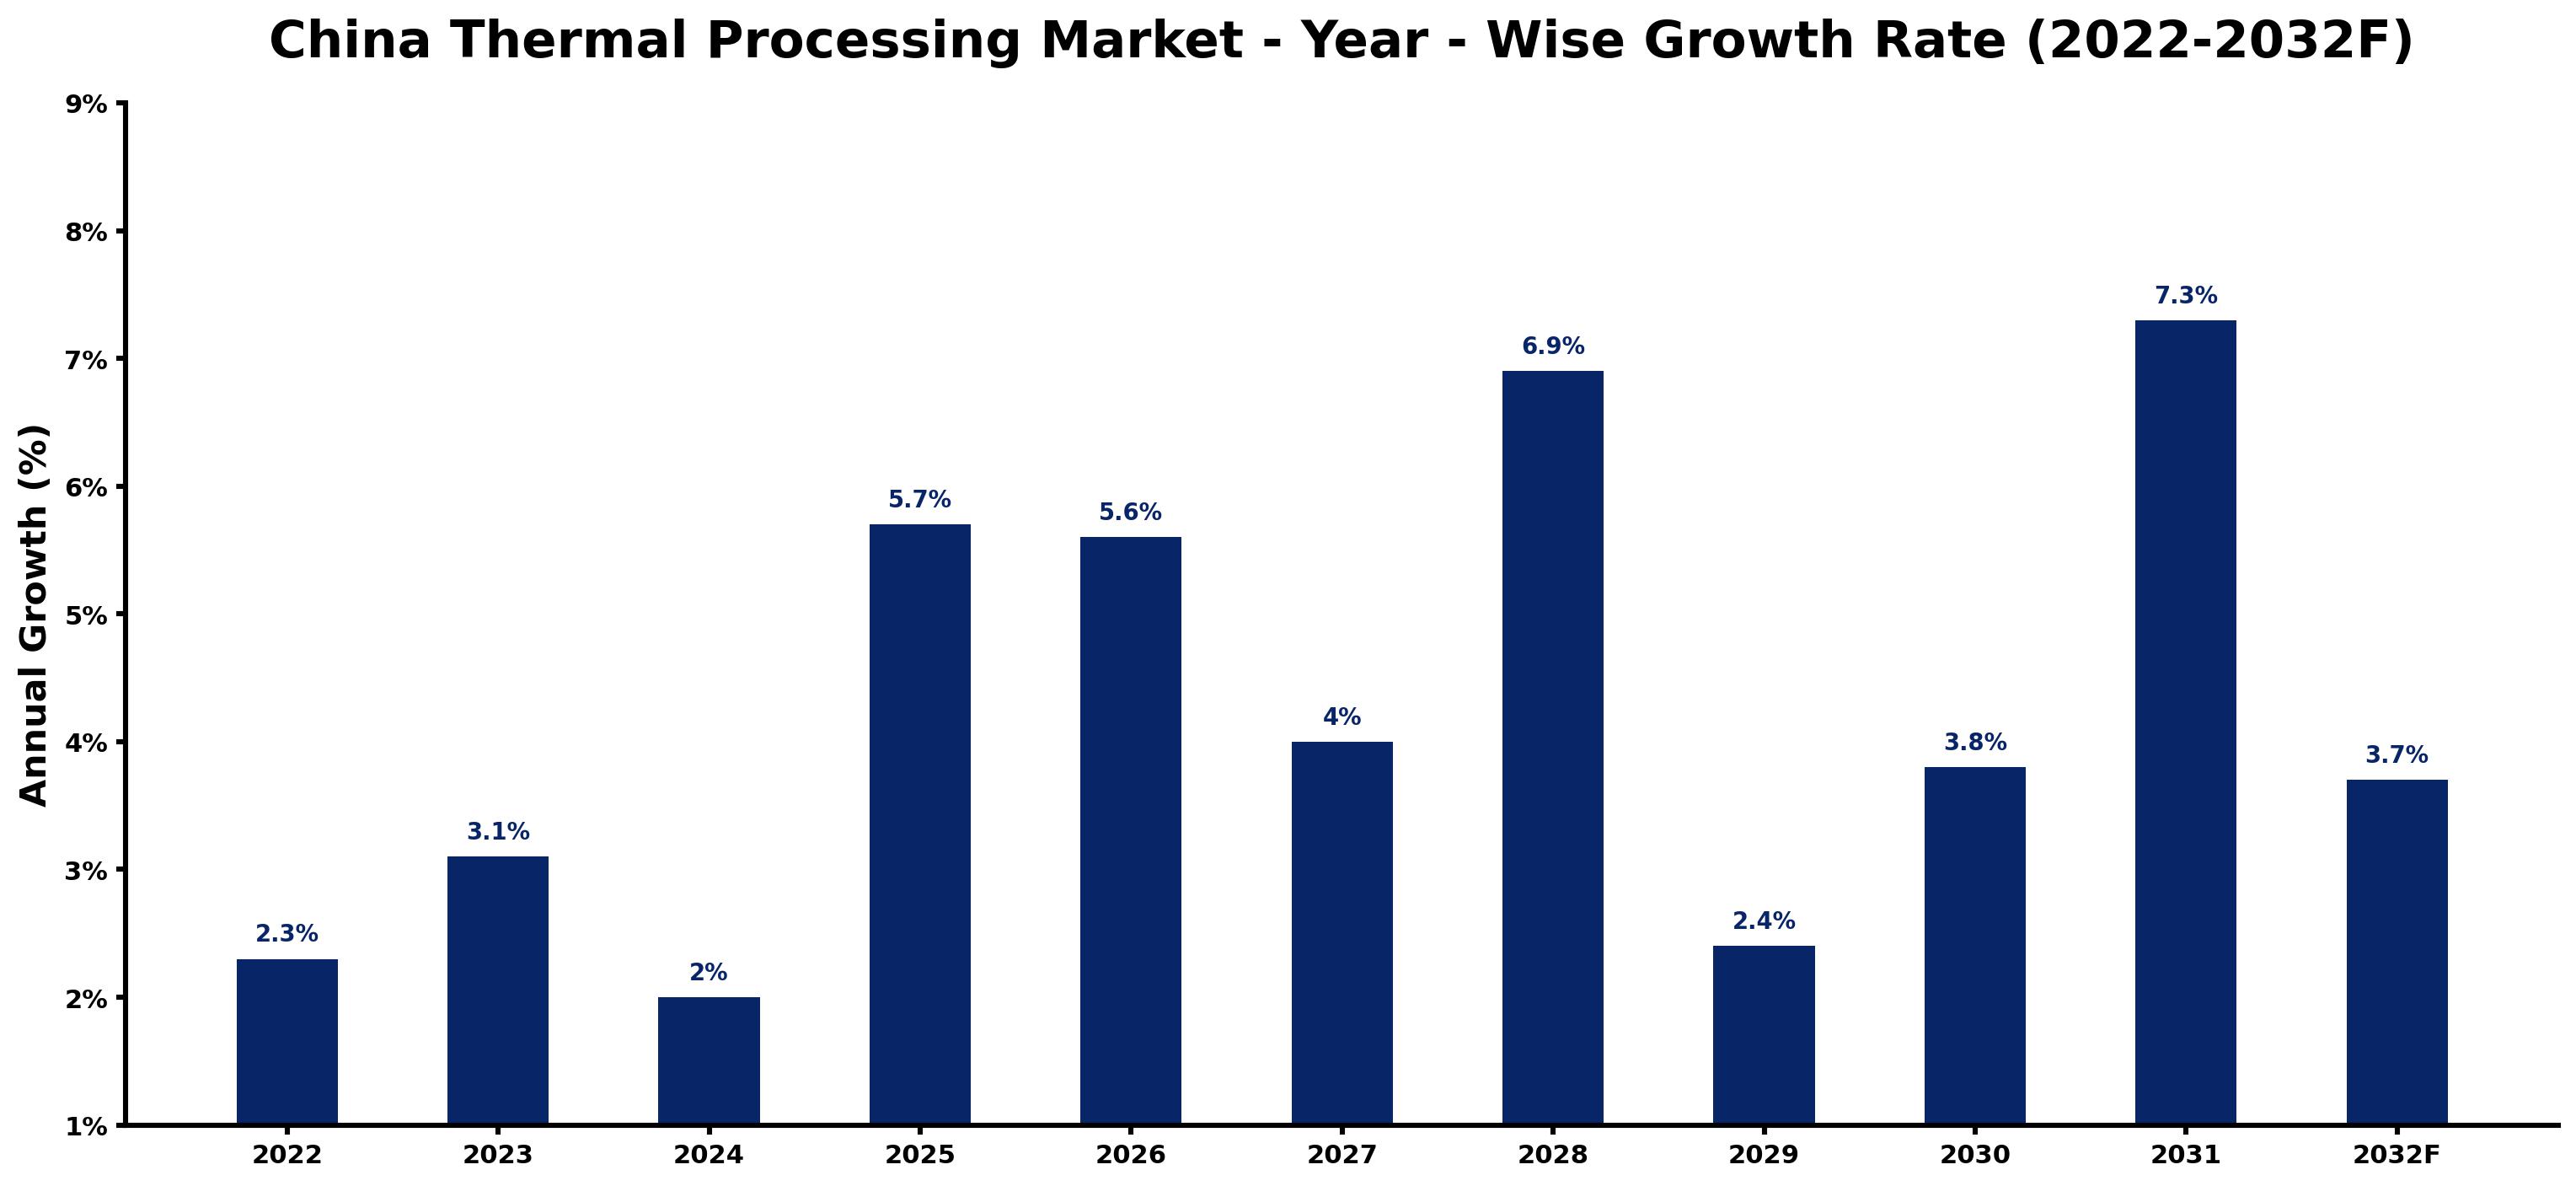
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.3 | The market experienced moderate growth, driven by steady demand from food manufacturing. |
| 2023 | 3.1 | Growth accelerated due to increased investments in thermal processing technology across various sectors. |
| 2024 | 2.0 | A slowdown occurred as investments stabilised, yet demand from electronics manufacturing remained strong. |
| 2025 | 5.7 | The market rebounded with significant growth, supported by the booming food processing industry. |
| 2026 | 5.6 | Growth slowed slightly as the market adjusted to previous peaks in demand. |
| 2027 | 4.0 | A further slowdown was noted as the automotive sector faced production challenges. |
| 2028 | 6.9 | The market rebounded with faster growth, driven by rising demand in food thermal processing. |
| 2029 | 2.4 | Growth slowed again as the electronics sector faced temporary production constraints. |
| 2030 | 3.8 | A recovery in growth occurred as investments in technology resumed across industries. |
| 2031 | 7.3 | The market peaked with the highest growth rate, driven by robust demand from multiple sectors. |
| 2032 | 3.7 | Growth slowed as the market stabilised, reflecting matured demand patterns. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Thermal Processing Market Synopsis
Thermal Processing in China involves applying heat to materials, transforming their properties for various industries. This technology finds its primary application in food processing, electronics, and metal fabrication, utilising methods such as ovens and retorts. The China Thermal Processing Market is expanding due to robust demand from the food manufacturing sector, valued at approximately 4 trillion CNY, alongside the electronics industry, which is projected to reach 8 trillion CNY by 2025. Continuous investments in upgrading thermal processing technology are further driving this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in thermal processing technology | Driver | High | Food Thermal Processing |
| Increasing demand for food safety and preservation | Driver | High | Food Thermal Processing |
| Growing need for energy-efficient processing solutions | Opportunity | High | Semiconductor Thermal |
| Expansion of the automotive components industry | Opportunity | Medium | Automotive Components |
| High operational costs for thermal processing facilities | Restraint | High | Heat Treatment Ovens |
| Regulatory compliance costs in food safety standards | Restraint | High | Food Thermal Processing |
| Thermal Processing Market in China faces challenges with technology upgrades | Challenge | High | Batch/Furnaces |
| Supply chain disruptions affecting thermal processing equipment availability | Challenge | Medium | Retort Systems |
Evaluation of Drivers in China Thermal Processing Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in upgrading thermal processing technology | Food Thermal Processing | In 2023, China invested 500 million CNY in upgrading thermal processing technology, boosting demand for modern equipment. |
| Growing food processing industry | Food Thermal Processing | China's food processing industry, valued at approximately 4 trillion CNY, drives demand for thermal processing solutions. |
| Rising production in the electronics sector | Semiconductor Thermal | The electronics manufacturing sector is expected to reach 8 trillion CNY by 2025, increasing demand for thermal processing. |
| Expansion of the automotive industry | Automotive Components | The automotive industry in China is projected to grow by 10% annually through 2025, enhancing demand for thermal processing. |
| Adoption of ISO 9001 standards | Heat Treatment Ovens | ISO 9001 is widely adopted, ensuring quality in thermal processing, leading to increased demand for compliant systems. |
Expansion of the Thermal Processing market in China is backed by rising investments in upgrading technology, with 500 million CNY allocated in 2023. The food processing industry, valued at approximately 4 trillion CNY, significantly boosts demand for thermal processing solutions. Additionally, the electronics sector, projected to reach 8 trillion CNY by 2025, drives further growth. The automotive components industry, expected to grow by 10% annually through 2025, also contributes to rising demand. Adoption of ISO 9001 standards ensures quality, enhancing the need for compliant thermal processing systems.
Evaluation of Restraints in China Thermal Processing Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High operational costs for thermal processing facilities | Batch/Furnaces | Operational costs remain high, impacting profitability for thermal processing facilities, particularly in the automotive sector. |
| Regulatory compliance costs in food safety standards | Food Thermal Processing | Compliance with National Standards of China (GB) incurs additional costs for food manufacturers, limiting profit margins. |
| Limited availability of skilled workforce | Heat Treatment Ovens | A shortage of skilled workers in thermal processing affects operational efficiency and increases training costs. |
| Supply chain disruptions affecting equipment availability | Retort Systems | Supply chain issues have delayed the delivery of essential thermal processing equipment, impacting production schedules. |
| Technological obsolescence risks | Semiconductor Thermal | Rapid advancements in technology pose risks of obsolescence for existing thermal processing equipment. |
China Thermal Processing Market Challenges
The China Thermal Processing Market encounters practical issues, starting with buyers facing challenges in meeting strict food safety standards. The National Standards of China (GB) result in compliance delays, raising operational costs for food producers. Many facilities still depend on outdated technology, which hampers efficiency and increases energy costs, compelling producers to invest heavily in upgrades; recent investments reached 500 million CNY in 2023, placing a burden on smaller players.
Trends in the China Thermal Processing Market
Several trends are reshaping the China Thermal Processing Market; the most important are set out below.
- Shift towards Energy-Efficient Thermal Processing: The Clean Production Promotion Law encourages efficient thermal processing methods, promoting energy savings. In 2023, over 1,000 thermal processing facilities in Guangdong are adopting these practices, reducing operational costs.
- Increased Adoption of Automation in Thermal Processing: Since 2022, automation has gained traction in thermal processing, particularly in food manufacturing. Approximately 20% of facilities have integrated automated systems, improving efficiency and product consistency.
- Growth in Food Thermal Processing Technologies: The food thermal processing sector has seen a 6.8% CAGR from 2026 to 2032, driven by the need for food safety. The National Development and Reform Commission supports this growth through funding initiatives.
- Expansion of Semiconductor Thermal Processing: The semiconductor thermal processing segment is expanding rapidly, with an expected 6.8% CAGR. Guangdong province, with over 5 million production units, is a key hub for this growth.
Investment Opportunities in the China Thermal Processing Market
Below are the investment opportunities with the strongest case in the China Thermal Processing Market.
- Investment in Energy-Efficient Technologies: With the government promoting clean technologies, there is an opportunity to invest in energy-efficient thermal processing solutions. The food manufacturing sector, serving approximately 1.4 billion people, is a prime target.
- Partnerships with Equipment Vendors: Now is the time to form partnerships with equipment vendors to supply advanced thermal processing machinery. The automotive components industry, employing over 4 million people, is seeking innovative solutions.
- Expansion of Food Thermal Processing Facilities: The food thermal processing sector is facing a capacity gap, with a projected growth of 6.8%. Investing in new facilities in Guangdong can address rising demand.
- Engaging with Government Initiatives: The 'Made in China 2025' initiative offers opportunities for companies to engage in advanced thermal processing projects. Aligning with this initiative can improve market entry prospects.
Government Initiatives in the China Thermal Processing Market
In 2023, the Chinese government launched the 'Made in China 2025' initiative, which promotes advanced thermal processing technologies and improves manufacturing capabilities. This initiative builds on previous laws, such as the Clean Production Promotion Law, which encourages efficient processing methods. Together, these measures aim to enhance the overall competitiveness of the thermal processing sector in China.
The Ministry of Industry and Information Technology oversees the implementation of thermal processing standards, ensuring compliance with safety regulations. The National Development and Reform Commission supports funding for projects that enhance energy efficiency in thermal processing. These agencies play a vital role in approving new technologies and ensuring that manufacturers meet established standards. In 2023, funding for energy-efficient projects reached 500 million CNY, benefiting numerous manufacturers.
Future Insight of the China Thermal Processing Market
The China Thermal Processing Market is set to evolve significantly by 2032, driven by several key factors. The 'Made in China 2025' initiative will enhance manufacturing capabilities, particularly in the electronics sector, projected to reach 8 trillion CNY by 2025. Investments in energy-efficient thermal processing technologies will rise, supported by the National Development and Reform Commission, promoting sustainable practices. Advances in clean technologies will transform operational methods, enabling producers to minimise waste and improve efficiency. These changes will ultimately provide buyers with higher quality and safer processed products.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Thermal Processing – Heat Treatment Ovens Dominated, Food Thermal Processing Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Heat Treatment Ovens took a 44% share of thermal processing in 2025, more than any other category. Heat treatment ovens hold the largest market share in China as they are crucial for metal hardening processes, particularly in the automotive components sector. This sector's substantial workforce of over 4 million people ensures a consistent demand for these ovens. Food Thermal Processing is set to record the highest CAGR in this split, 6.8% over 2026–2032. Food thermal processing is experiencing rapid growth due to its critical role in food safety and preservation, especially with China producing over 20 million tons of processed food in 2022. This segment's expansion will further enhance the dominance of heat treatment ovens in the market. Suppliers should focus on enhancing their offerings in food thermal processing to meet the rising demand.
By Product Type – Batch/Furnaces Dominated, Retort Systems Expected to Grow Fastest
With a 43% revenue share in 2025, Batch/Furnaces was the largest product type category. Batch/furnaces lead the market share as they are extensively used in metal processing applications across various industries, including automotive components. Their efficiency and adaptability make them a preferred choice among manufacturers. Over 2026–2032, Retort Systems are expected to post the fastest growth, at a CAGR of 7.4%. Retort systems are witnessing swift growth as they are essential for canning and food sterilization processes, which are increasingly important in food manufacturing. This trend indicates a shift towards advanced technologies in food processing. Buyers should consider investing in retort systems to maintain competitiveness in the evolving food processing sector.
By Processing Method – Annealing/Quenching Dominated, Sterilization Expected to Grow Fastest
In 2025, Annealing/Quenching led the processing method split with a 52% share. Annealing/quenching processes dominate the market due to their essential role in metal treatment, which is crucial for producing durable automotive components. This method is widely adopted across manufacturing operations, ensuring a significant market share. The quickest growth will come from Sterilization, forecast to expand at a CAGR of 6.8% between 2026 and 2032. Sterilization methods are growing rapidly as they are vital for food safety, particularly in a country where food processing is a major industry. This trend highlights the increasing importance of safety standards in food production. Suppliers must prioritise sterilization technologies to align with the heightened focus on food safety.
By Distribution Channel – Equipment Vendors Dominated, Food Equipment Suppliers Expected to Grow Fastest
Equipment Vendors held a 47% share of the China Thermal Processing Market by distribution channel in 2025. Equipment vendors hold the largest market share by supplying essential machinery for thermal processing across various industries, including automotive and food manufacturing. Their established networks and relationships with manufacturers reinforce their leading position. Food Equipment Suppliers are projected to grow fastest, at a CAGR of 6.5% during 2026–2032. Food equipment suppliers are rapidly expanding as they provide necessary processing equipment tailored for the food industry, which is significantly growing. This growth reflects the increasing demand for specialised equipment in food manufacturing. Suppliers should strengthen partnerships with food equipment suppliers to capitalise on the expanding food processing market.
By End User Industry – Automotive Components Dominated, Food Manufacturing Expected to Grow Fastest
The largest end user industry category in 2025 was Automotive Components, with a 47% share of total revenue. The automotive components sector leads the market as it extensively utilises thermal processing for parts manufacturing, supported by a workforce of over 4 million people. This reliance on thermal processing technologies ensures its dominant market share. Food Manufacturing is set to record the highest CAGR in this split, 6.7% over 2026–2032. Food manufacturing is the fastest-growing end user, leveraging thermal processing for food safety, particularly with the production of over 20 million tons of processed food in 2022. This growth highlights a broader trend towards prioritising food safety in production. Suppliers should focus on the food manufacturing sector to tap into its rapid growth and increasing demand for thermal processing.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Thermal Processing Market Outlook
- Market Size of China Thermal Processing Market, 2025
- Forecast of China Thermal Processing Market, 2032
- Historical Data and Forecast of China Thermal Processing Revenues & Volume for the Period 2022 - 2032F
- China Thermal Processing Market Trend Evolution
- China Thermal Processing Market Drivers and Challenges
- China Thermal Processing Price Trends
- China Thermal Processing Porter's Five Forces
- China Thermal Processing Industry Life Cycle
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Thermal Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Heat Treatment Ovens for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Food Thermal Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Semiconductor Thermal for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Coating Thermal Baths for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Batch/Furnaces for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Retort Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Bake/Anneal Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Curing Ovens for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Processing Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Annealing/Quenching for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Sterilization for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Wafer Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Powder Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Equipment Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Food Equipment Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Cleanroom Equipment for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Industrial Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Automotive Components for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Food Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Electronics Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermal Processing Market Revenues & Volume By Metal Fabrication for the Period 2022 - 2032F
- China Thermal Processing Import Export Trade Statistics
- Market Opportunity Assessment By Thermal Processing
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Processing Method
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Thermal Processing Top Companies Market Share
- China Thermal Processing Competitive Benchmarking By Technical and Operational Parameters
- China Thermal Processing Company Profiles
- China Thermal Processing Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Thermal Processing
- Heat Treatment Ovens
- Food Thermal Processing
- Semiconductor Thermal
- Coating Thermal Baths
By Product Type
- Batch/Furnaces
- Retort Systems
- Bake/Anneal Systems
- Curing Ovens
By Processing Method
- Annealing/Quenching
- Sterilization
- Wafer Processing
- Powder Coating
By Distribution Channel
- Equipment Vendors
- Food Equipment Suppliers
- Cleanroom Equipment
- Industrial Integrators
By End User Industry
- Automotive Components
- Food Manufacturing
- Electronics Manufacturing
- Metal Fabrication































