China Thermoformed Packaging Market Size & Growth Rate
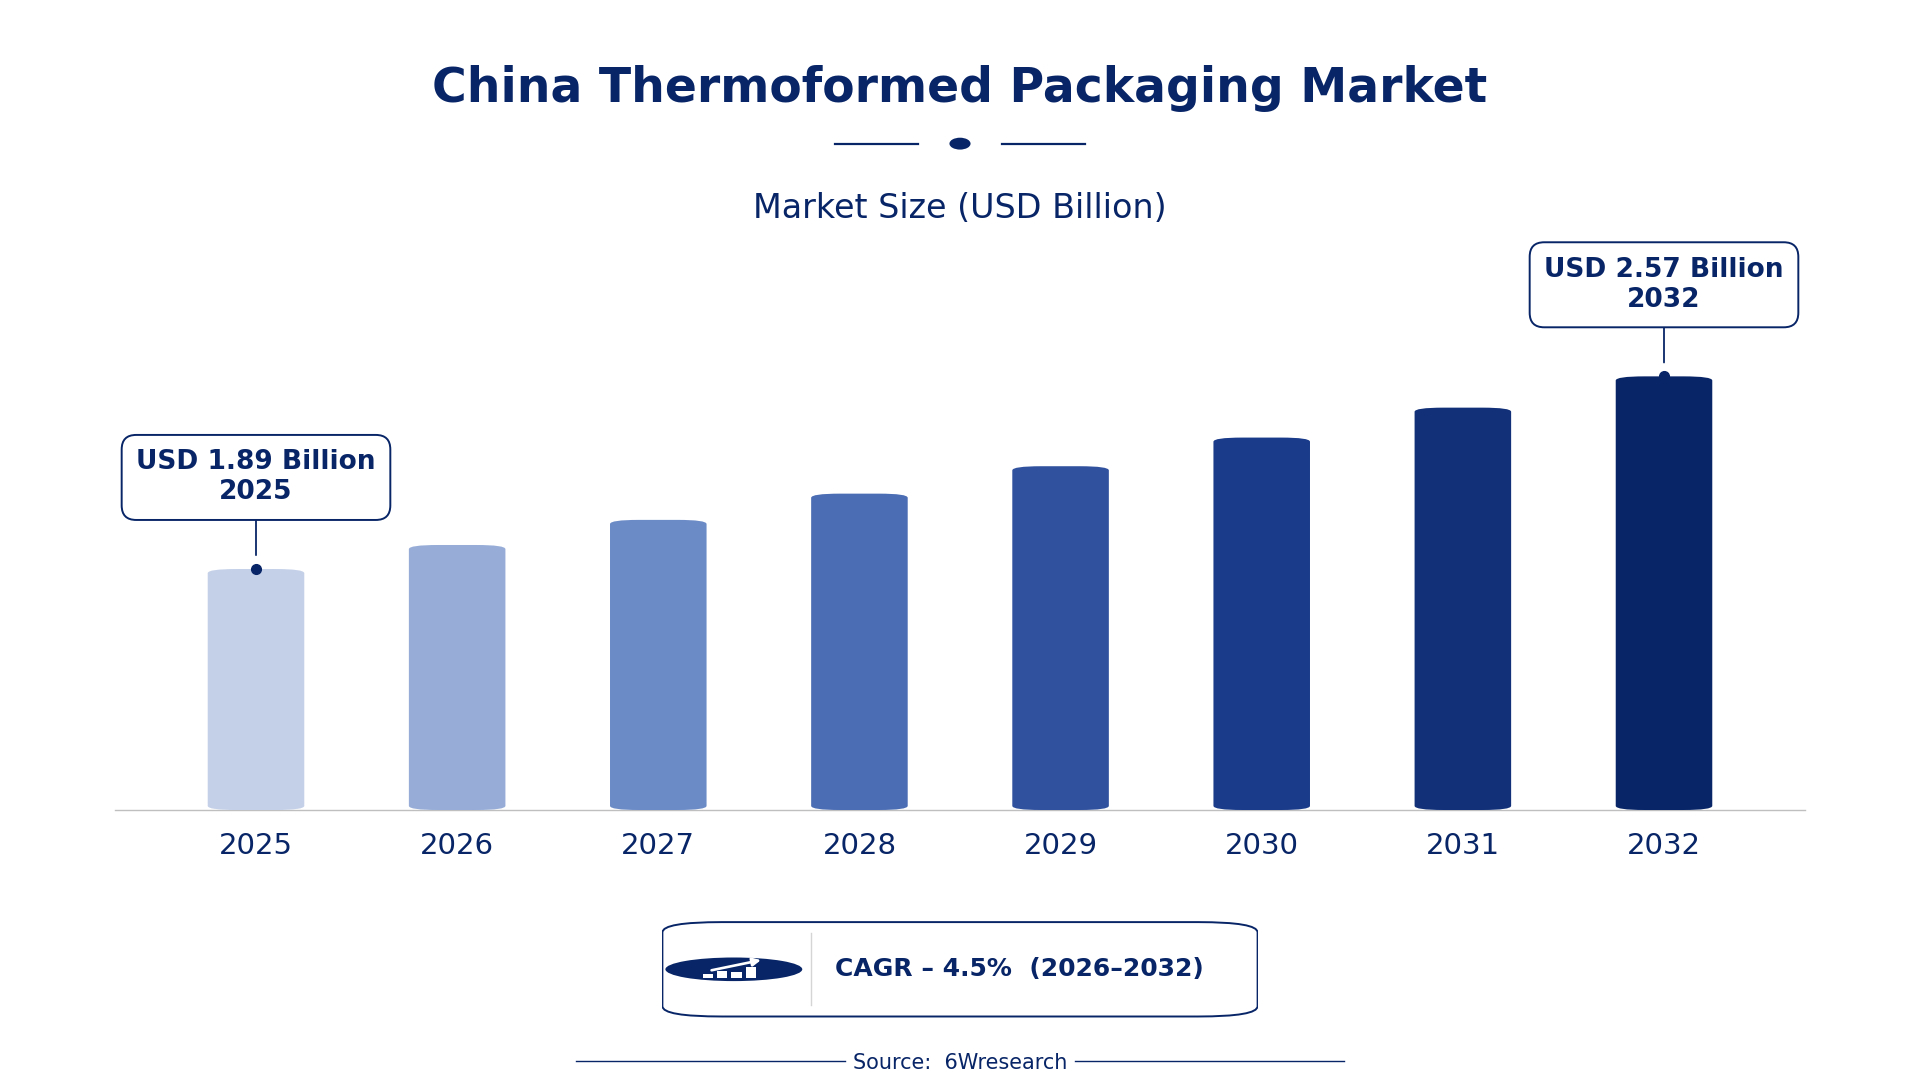
According to 6Wresearch internal database and industry insights, the China Thermoformed Packaging Market was valued at USD 1.89 billion in 2025 and is projected to reach USD 2.57 billion by 2032, growing at a CAGR of approximately 4.5% during 2026–2032.
China Thermoformed Packaging Market Highlights
| Report Metric | Details |
| Report Name | China Thermoformed Packaging Market |
| Market Size 2025 | USD 1.89 billion |
| Market Size 2032 | USD 2.57 billion |
| Absolute Growth 2025–2032 | USD 0.68 billion |
| CAGR 2026–2032 | 4.5% |
| Peak Annual Growth | 6.7% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Thermoformed Packaging, 2025 | Tray Packaging (47% share) |
| Leading Product Type, 2025 | Food Trays (47% share) |
| Leading Material Type, 2025 | PET/PS/PLA (38% share) |
| Leading Distribution Channel, 2025 | Food Packaging Suppliers (37% share) |
| Leading End User Industry, 2025 | Fresh Produce Industry (47% share) |
| Fastest-Growing Thermoformed Packaging | Clamshell Packaging (6.0% CAGR) |
| Fastest-Growing Product Type | Hinged Boxes (5.6% CAGR) |
| Fastest-Growing Material Type | RPET (6.5% CAGR) |
| Fastest-Growing Distribution Channel | Online Suppliers (7.1% CAGR) |
| Fastest-Growing End User Industry | Pharma Packaging (7.0% CAGR) |
| Growing Sector | Food Service Industry |
| Key End Users | Food Packaging Suppliers, Pharmaceutical Companies, Consumer Electronics Manufacturers |
China Thermoformed Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
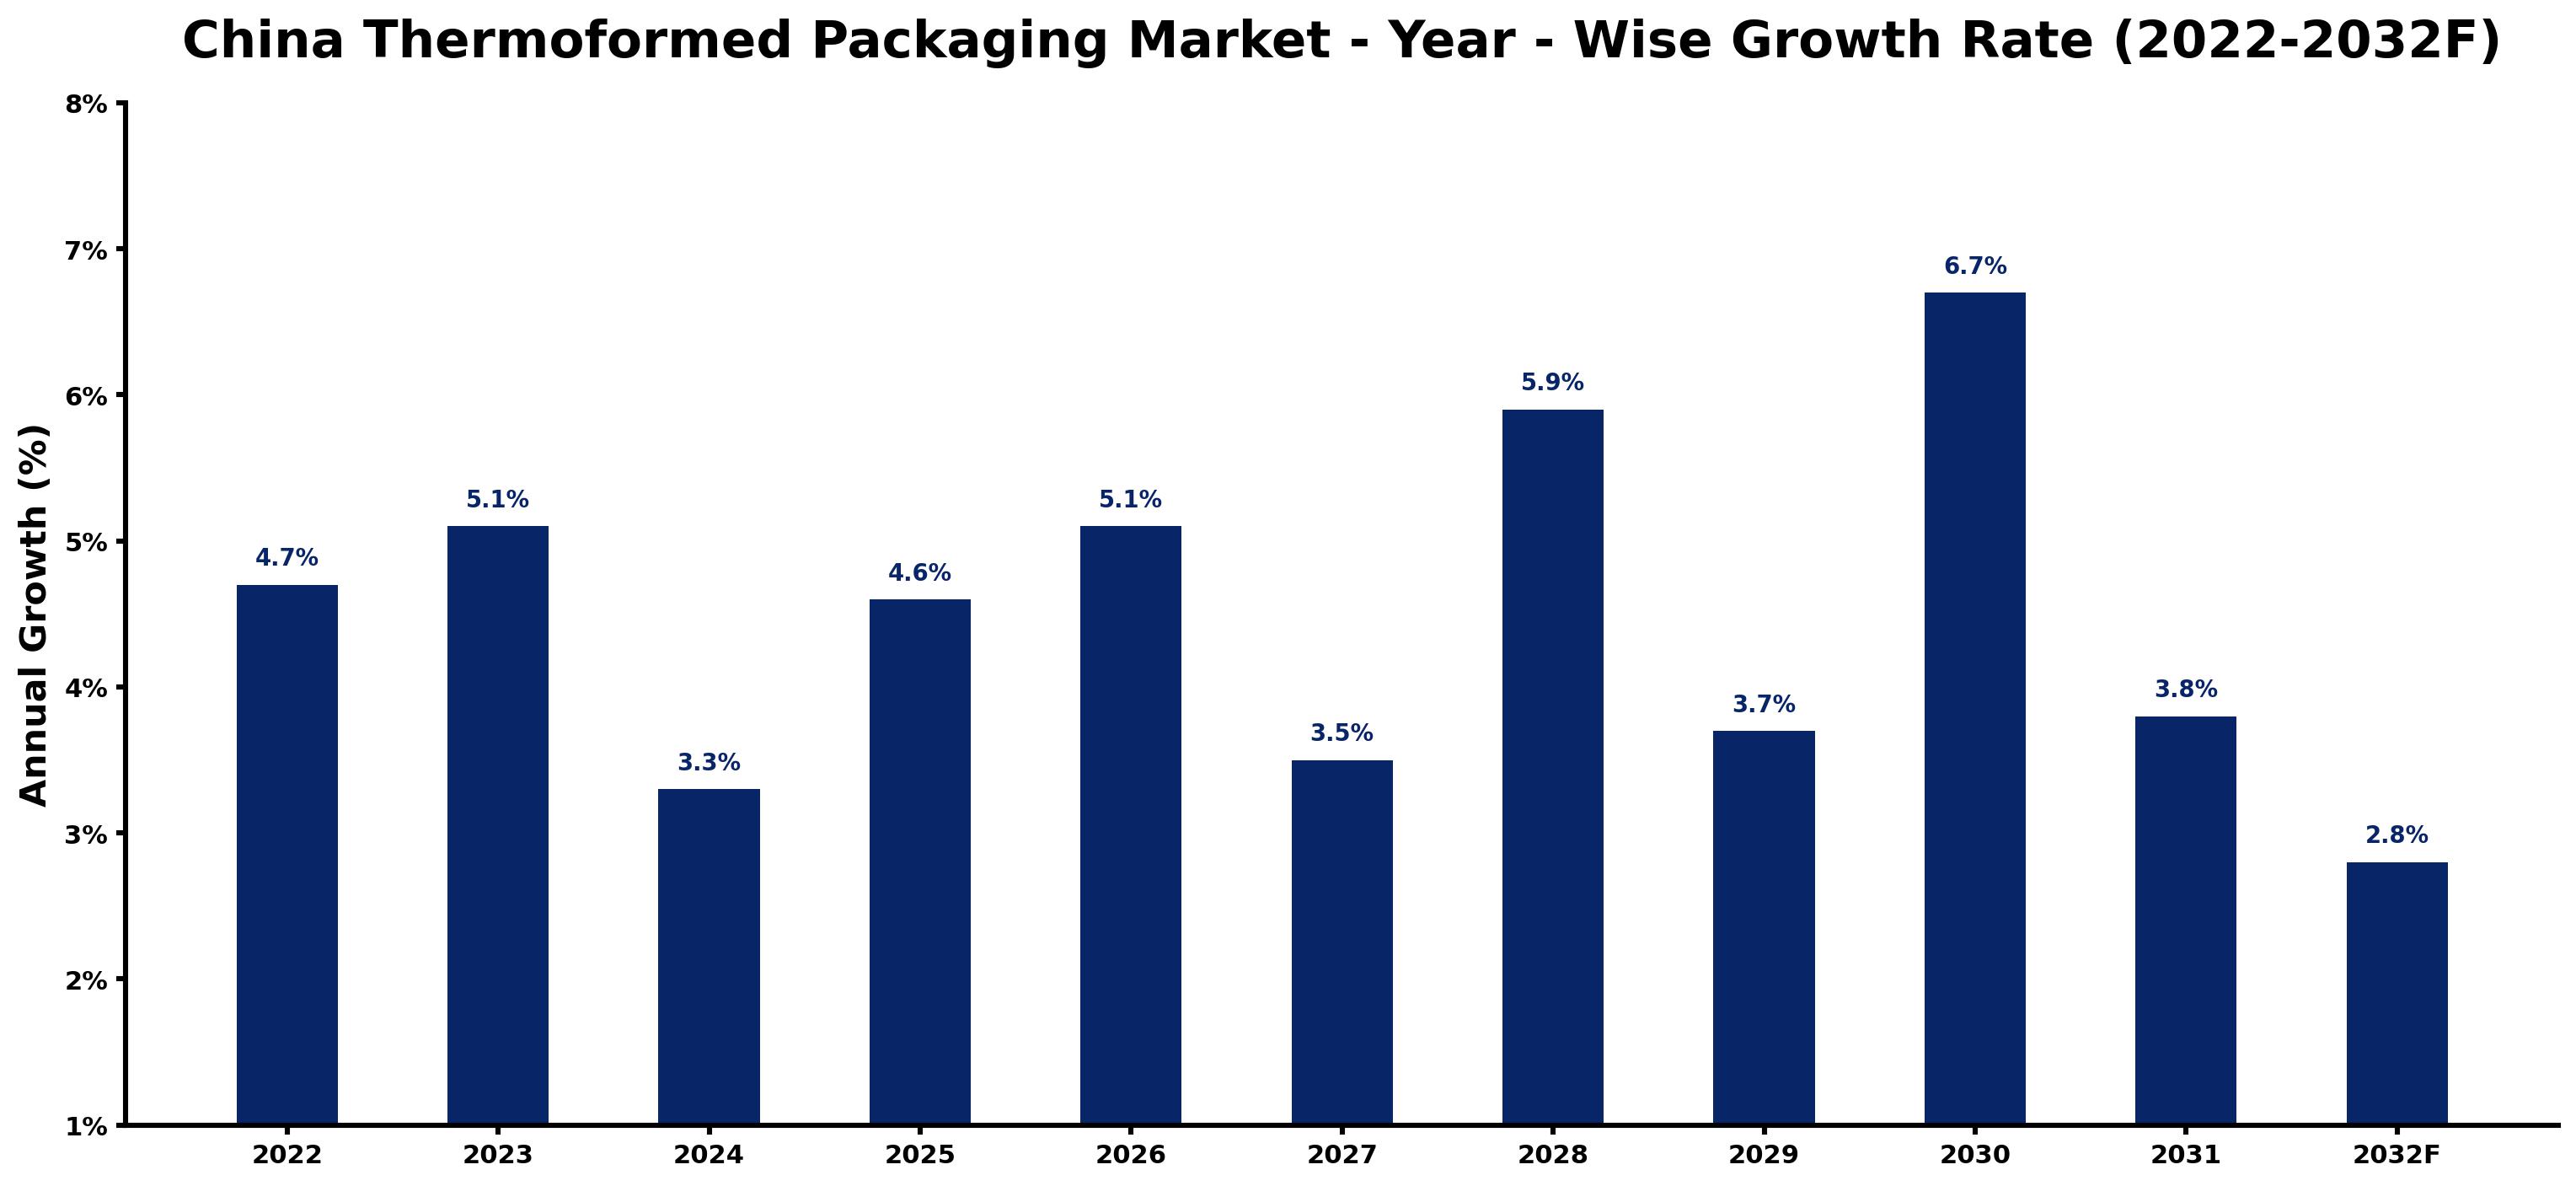
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.7 | The market experienced steady growth due to the implementation of the 'Green Packaging Initiative' promoting sustainable practices. |
| 2023 | 5.1 | Growth accelerated as consumer electronics sales surged, boosting packaging needs. |
| 2024 | 3.3 | A slowdown occurred as the market adjusted to changing consumer preferences in food packaging. |
| 2025 | 4.6 | Demand rose again, driven by the expanding food service industry projected to grow by 10%. |
| 2026 | 5.1 | Growth continued as food packaging producers adopted ISO 22000 standards for safety. |
| 2027 | 3.5 | A slowdown was noted as the market faced challenges in raw material sourcing and availability. |
| 2028 | 5.9 | Demand increased as the food service industry projected further growth, boosting food tray needs. |
| 2029 | 3.7 | The market slowed again, reflecting shifts in consumer purchasing behaviour towards sustainable options. |
| 2030 | 6.7 | A peak in growth was reached as the pharmaceutical sector expanded, increasing demand for blister packaging. |
| 2031 | 3.8 | Growth slowed as competition intensified among packaging suppliers, affecting pricing strategies. |
| 2032 | 2.8 | The market is expected to grow at a slower pace as sustainability standards become stricter. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Thermoformed Packaging Market Synopsis
Thermoformed Packaging in China encompasses plastic packaging formed by heating sheets into specific shapes, primarily for food and consumer products. This packaging type is essential across various sectors, including food service and consumer electronics. The China Thermoformed Packaging Market is expanding, driven by a growing population exceeding 1.4 billion and increasing demand from the food service industry, which is expected to grow by 10% annually. The implementation of the 'Green Packaging Initiative' promotes sustainable practices, further supporting market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand from the food service industry drives the need for food trays and clamshells. | Driver | High | Tray Packaging |
| The rise in consumer electronics sales boosts the demand for protective packaging solutions. | Driver | High | Blister Packaging |
| The push for sustainable packaging solutions creates opportunities for eco-friendly materials. | Opportunity | High | PET/PS/PLA |
| The growing pharmaceutical sector presents a significant opportunity for blister packaging. | Opportunity | High | Blister Packaging |
| Stricter regulations on plastic waste management may limit production capabilities. | Restraint | Medium | Tray Packaging |
| The fluctuating costs of raw materials can hinder profit margins for producers. | Restraint | Medium | Tray Packaging |
| Supply chain disruptions pose challenges for timely delivery of packaging materials. | Challenge | High | Tray Packaging |
| Intense competition among suppliers can lead to price wars, affecting profitability. | Challenge | Medium | Tray Packaging |
Evaluation of Drivers in China Thermoformed Packaging Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing food service industry | Tray Packaging | The food service industry is expected to grow by 10% annually, boosting demand for food trays. |
| Rising consumer electronics sales | Blister Packaging | Consumer electronics sales reached 1.5 trillion CNY in 2022, increasing the need for protective packaging. |
| Adoption of sustainable materials | PET/PS/PLA | The 'Green Packaging Initiative' promotes sustainable practices, driving demand for eco-friendly packaging solutions. |
| Expansion of the pharmaceutical sector | Blister Packaging | Healthcare spending rose significantly in 2023, increasing the demand for compliant packaging solutions. |
| Increasing focus on recycling | Tray Packaging | The 'Circular Economy Promotion Law' encourages the use of recyclable materials, enhancing sustainability in production. |
Market growth in China for Thermoformed Packaging rests on rising consumer electronics sales, the expanding food service industry, and the push for sustainable materials. Consumer electronics sales reached 1.5 trillion CNY in 2022, which increased the need for protective packaging solutions. The food service industry is expected to grow by 10% annually, driving demand for food trays and clamshells. Furthermore, healthcare spending rose significantly in 2023, leading to increased demand for blister packaging.
Evaluation of Restraints in China Thermoformed Packaging Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Stricter regulations on plastic waste management | Tray Packaging | The 'National Plastic Waste Management Strategy' may limit production capabilities for packaging producers. |
| Fluctuating raw material costs | Tray Packaging | Rising costs can hinder profit margins for producers, affecting their financial stability. |
| Supply chain disruptions | Tray Packaging | Disruptions can delay the delivery of packaging materials, impacting production schedules. |
| Intense competition among suppliers | Tray Packaging | Price wars among suppliers can erode profit margins and affect market stability. |
| Consumer preference shifts towards alternative packaging | Tray Packaging | Changing consumer preferences may lead to decreased demand for traditional thermoformed solutions. |
China Thermoformed Packaging Market Challenges
The China thermoformed packaging market faces practical challenges, with intense competition being a primary concern. Numerous local manufacturers drive down prices, squeezing profit margins for producers. Rising costs present another hurdle, as the 'National Plastic Pollution Control Action Plan' requires a 30% investment in sustainable practices, increasing operational expenses for suppliers. Regulatory pressures are mounting, with the adoption of ISO 22000 standards necessitating compliance from food packaging producers, which may delay product launches. Supply chain disruptions continue, as logistics issues in eastern provinces can prolong delivery times for buyers, affecting inventory management.
Trends in the China Thermoformed Packaging Market
Several trends are reshaping the China Thermoformed Packaging Market; the most important are set out below.
- Shift towards Sustainable Packaging Solutions: In 2023, the 'Green Packaging Initiative' launched, promoting eco-friendly materials in packaging. This initiative aligns with growing consumer demand for sustainability, with over 40% of the thermoformed packaging market focused on food packaging.
- Increase in Food Service Industry Demand: The food service industry in China is expected to grow by 10% annually, impacting the thermoformed packaging market. This growth translates to increased demand for food trays and clamshells, essential for food packaging.
- Rise in Pharmaceutical Packaging Needs: The pharmaceutical sector is experiencing growth, leading to increased demand for blister packaging. In 2023, healthcare spending rose significantly, driving the need for compliant packaging solutions to ensure product safety.
- Growing Consumer Electronics Sales: Consumer electronics sales reached 1.5 trillion CNY in 2022, boosting the need for protective packaging. This trend highlights the importance of blister packaging in safeguarding electronic items during transit.
Investment Opportunities in the China Thermoformed Packaging Market
Investors looking at the China Thermoformed Packaging Market should consider the following areas.
- Timing for Sustainable Solutions: With the implementation of the 'Green Packaging Initiative', there is an opportunity for suppliers of sustainable materials. The food packaging segment, accounting for over 40% of the market, is a prime target for investments.
- Pharmaceutical Sector Growth: The expanding pharmaceutical industry presents an opportunity for blister packaging suppliers. With healthcare spending increasing, suppliers can enter this market by focusing on compliance and safety standards.
- Food Service Industry Expansion: The food service industry is expected to grow by 10% annually, creating demand for food trays. Suppliers can capitalise on this by partnering with food packaging distributors to meet rising needs.
- Consumer Electronics Packaging Demand: The surge in consumer electronics sales highlights a gap in protective packaging solutions. Suppliers can invest in blister packaging tailored for electronic items to meet this growing demand.
Government Initiatives in the China Thermoformed Packaging Market
In 2023, the 'Food Safety Law' was updated by the National Health Commission to include stricter regulations on food packaging materials, improving safety standards for producers. This law adds to previous measures like the 'National Plastic Waste Management Strategy' launched in 2021, which aimed to promote recycling and reduce plastic waste in the packaging industry. The updated law requires producers to comply with new safety standards, enhancing consumer trust and market competitiveness.
The State Administration for Market Regulation oversees the implementation of the 'Green Packaging Initiative', which funds projects aimed at promoting sustainable packaging practices. This initiative supports food packaging suppliers in adopting eco-friendly materials, ensuring compliance with new regulations and improving market competitiveness. Additionally, the initiative has allocated 500 million CNY to support projects that enhance sustainability in packaging production. This funding allows producers to invest in new technologies and materials, positioning them better in the market.
Future Insight of the China Thermoformed Packaging Market
The China thermoformed packaging market will experience substantial changes by 2032, primarily due to the 'Green Packaging Initiative' launched in 2023, which encourages the use of sustainable materials. The food service industry is projected to grow by 10% annually, elevating demand for food trays and related solutions. The pharmaceutical sector will see increased packaging needs, spurred by rising healthcare spending. By 2032, the focus on recyclable materials from the 'Circular Economy Promotion Law' will reshape production processes, creating new opportunities for both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Thermoformed Packaging – Tray Packaging Dominated, Clamshell Packaging Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Tray Packaging took a 47% share of thermoformed packaging in 2025, more than any other category. Tray packaging holds the largest share in China's thermoformed packaging market, primarily due to its extensive use in food service and retail sectors for fresh produce. The demand from restaurants and supermarkets for effective presentation and storage of food items solidifies this segment's leading position. Clamshell Packaging is set to record the highest CAGR in this split, 6.0% over 2026–2032. Clamshell packaging is rapidly growing in popularity, particularly for food items and consumer goods, as it offers enhanced product visibility and convenience. The anticipated 10% annual growth in the food service industry is expected to further accelerate the expansion of this segment. Suppliers should focus on developing clamshell packaging solutions to align with the rising market demand.
By Product Type – Food Trays Dominated, Hinged Boxes Expected to Grow Fastest
In 2025, Food Trays led the product type split with a 47% share. Food trays capture a significant share of the product type segment, being indispensable for food packaging in restaurants and supermarkets. Their widespread use across various food service settings reinforces their status as the preferred choice among industry buyers. Over 2026–2032, Hinged Boxes are expected to post the fastest growth, at a CAGR of 5.6%. Hinged boxes are experiencing the fastest growth, driven by their specific applications for certain consumer products that appeal to niche markets. As consumer preferences shift towards versatile packaging solutions, hinged boxes are likely to gain more traction. Suppliers should consider expanding their product lines to include hinged boxes, addressing the evolving consumer needs.
By Material Type – PET/PS/PLA Dominated, RPET Expected to Grow Fastest
PET/PS/PLA held a 38% share of the China Thermoformed Packaging Market by material type in 2025. PET/PS/PLA materials lead the market as they are commonly used for sustainable packaging solutions, appealing to environmentally conscious consumers. The increasing adoption of these materials aligns with the industry's shift towards eco-friendly practices. The quickest growth will come from RPET, forecast to expand at a CAGR of 6.5% between 2026 and 2032. RPET is the fastest-growing material type, reflecting the rising demand for eco-friendly packaging options that utilise recycled materials. This growth is driven by regulatory initiatives promoting sustainability, such as the 'Circular Economy Promotion Law.' Suppliers should invest in RPET production capabilities to align with market trends towards sustainability.
By Distribution Channel – Food Packaging Suppliers Dominated, Online Suppliers Expected to Grow Fastest
Food Packaging Suppliers accounted for a 37% market share by distribution channel in 2025. Food packaging suppliers dominate the distribution channel segment, acting as primary providers for the food industry and ensuring consistent availability of packaging solutions. Their established relationships with food producers play a crucial role in maintaining their significant market share. Online Suppliers are projected to grow fastest, at a CAGR of 7.1% during 2026–2032. Online suppliers are quickly becoming a preferred distribution channel, catering to the growing demand for convenient purchasing options in the packaging sector. The shift towards e-commerce is reshaping how suppliers engage with customers, enhancing market reach. Suppliers should enhance their online presence to capitalise on the growing market share associated with online distribution.
By End User Industry – Fresh Produce Industry Dominated, Pharma Packaging Expected to Grow Fastest
The largest end user industry category in 2025 was Fresh Produce Industry, with a 47% share of total revenue. The fresh produce industry is the leading end user, heavily reliant on trays and clamshells for effective packaging solutions. This sector's strong demand for packaging is driven by the need for freshness and appealing presentation in retail environments, solidifying its market position. Pharma Packaging is set to record the highest CAGR in this split, 7.0% over 2026–2032. Pharma packaging is the fastest-growing end user industry, propelled by the critical need for product safety and compliance in healthcare. The increase in healthcare spending is further driving the demand for reliable packaging solutions in pharmaceuticals. Suppliers should focus on developing specialised packaging solutions tailored for the pharmaceutical sector to address growing regulatory requirements.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Thermoformed Packaging Market Outlook
- Market Size of China Thermoformed Packaging Market, 2025
- Forecast of China Thermoformed Packaging Market, 2032
- Historical Data and Forecast of China Thermoformed Packaging Revenues & Volume for the Period 2022 - 2032F
- China Thermoformed Packaging Market Trend Evolution
- China Thermoformed Packaging Market Drivers and Challenges
- China Thermoformed Packaging Price Trends
- China Thermoformed Packaging Porter's Five Forces
- China Thermoformed Packaging Industry Life Cycle
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Thermoformed Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Blister Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Tray Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Clamshell Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Blister Cards for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Clamshells for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Food Trays for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Hinged Boxes for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Consumer Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By PET/PS/PLA for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By PS, RPET for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By PET/PVC for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By PVC/PET Blister Film for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Packaging Converters for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Food Packaging Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Retail Packaging Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Online Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Consumer Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Fresh Produce Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Pharma Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Thermoformed Packaging Market Revenues & Volume By Retail Products for the Period 2022 - 2032F
- China Thermoformed Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Thermoformed Packaging
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Thermoformed Packaging Top Companies Market Share
- China Thermoformed Packaging Competitive Benchmarking By Technical and Operational Parameters
- China Thermoformed Packaging Company Profiles
- China Thermoformed Packaging Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Thermoformed Packaging
- Blister Packaging
- Tray Packaging
- Clamshell Packaging
- Blister Cards
By Product Type
- Clamshells
- Food Trays
- Hinged Boxes
- Consumer Packaging
By Material Type
- PET/PS/PLA
- PS
- RPET
- PET/PVC
- PVC/PET Blister Film
By Distribution Channel
- Packaging Converters
- Food Packaging Suppliers
- Retail Packaging Distributors
- Online Suppliers
By End User Industry
- Consumer Electronics
- Fresh Produce Industry
- Pharma Packaging
- Retail Products































