China third-party logistics for vehicles Market Size & Growth Rate
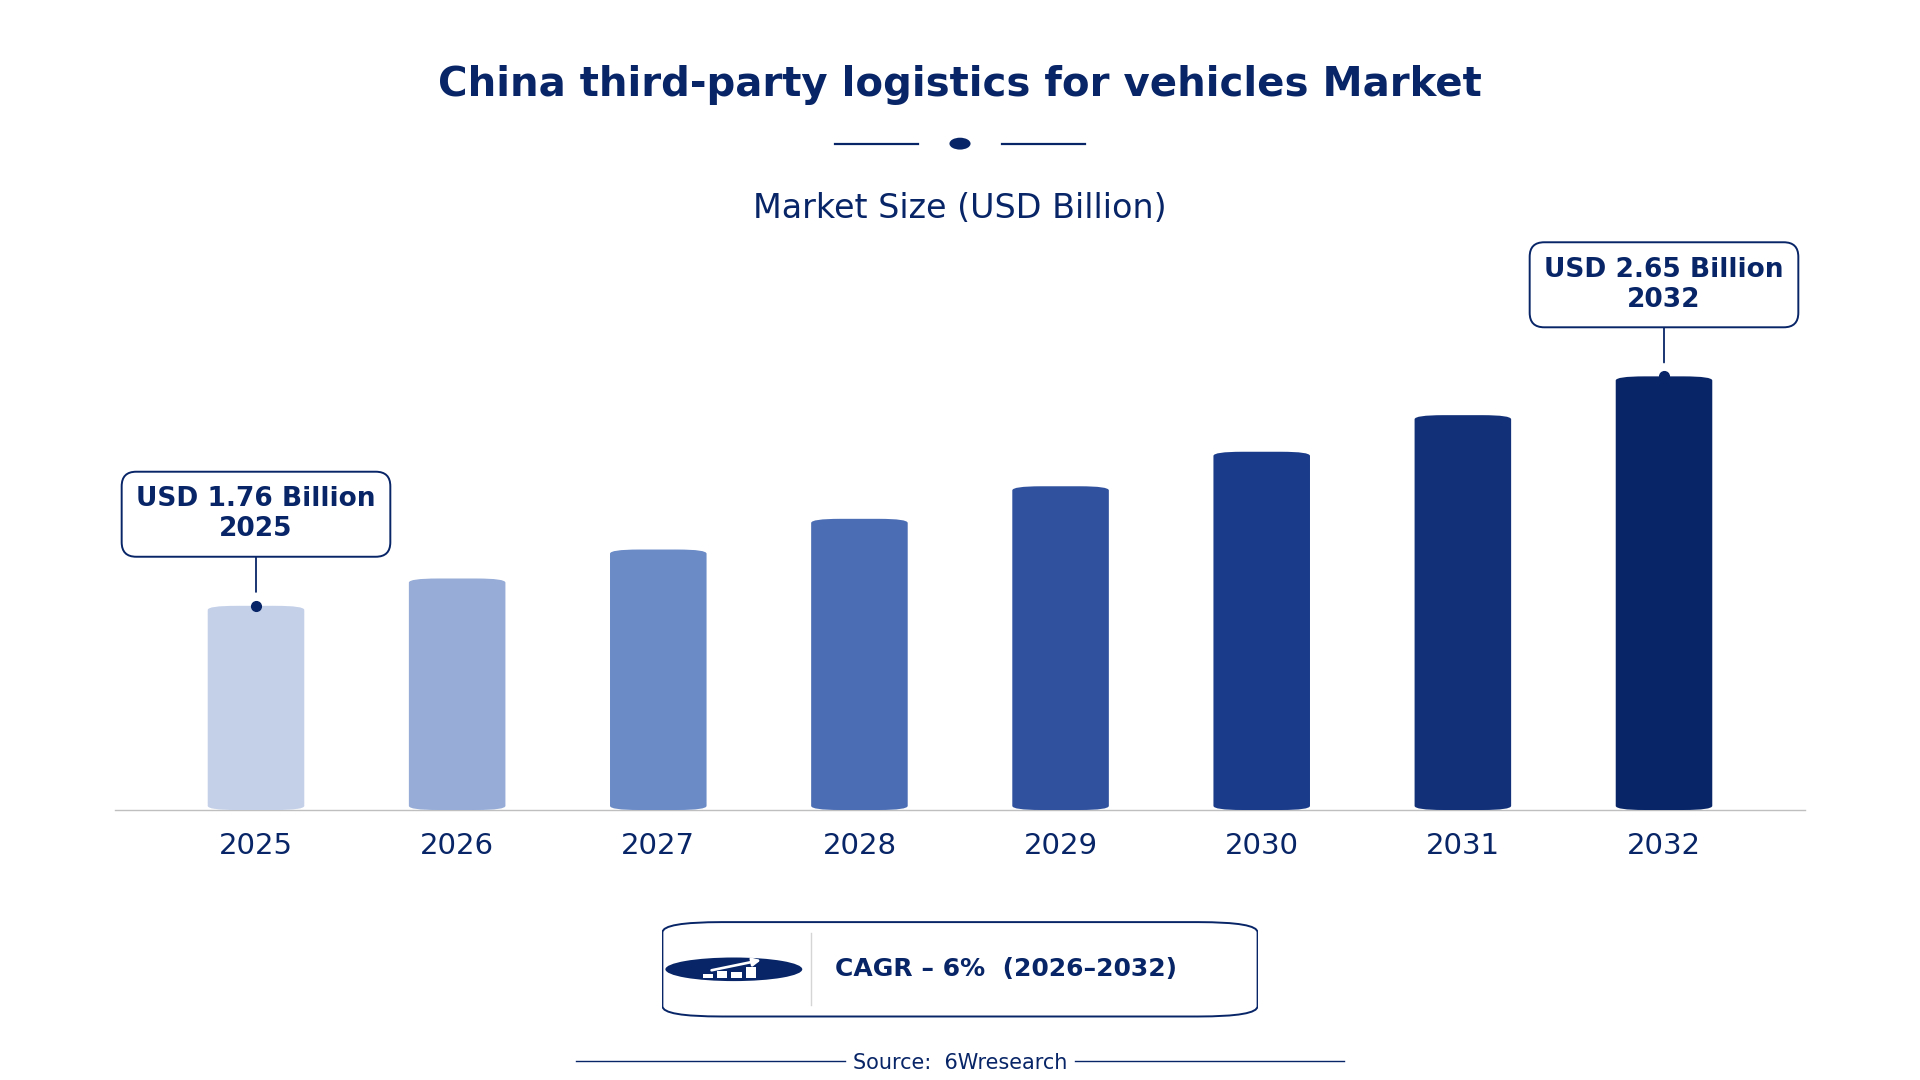
According to 6Wresearch internal database and industry insights, the China third-party logistics for vehicles Market was valued at USD 1.76 billion in 2025 and is projected to reach USD 2.65 billion by 2032, growing at a CAGR of approximately 6% during 2026–2032.
China third-party logistics for vehicles Market Highlights
| Report Metric | Details |
| Report Name | China third-party logistics for vehicles Market |
| Market Size 2025 | USD 1.76 billion |
| Market Size 2032 | USD 2.65 billion |
| Absolute Growth 2025–2032 | USD 0.89 billion |
| CAGR 2026–2032 | 6% |
| Peak Annual Growth | 7.3% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | Finished Vehicle Logistics (43% share) |
| Leading Transport Mode, 2025 | Road/Rail (52% share) |
| Leading Client Type, 2025 | OEMs (55% share) |
| Leading End User, 2025 | Auto Manufacturers (44% share) |
| Fastest-Growing Service Type | Inbound Logistics (8.5% CAGR) |
| Fastest-Growing Transport Mode | Express Delivery (8.2% CAGR) |
| Fastest-Growing Client Type | Aftermarket Suppliers (8.5% CAGR) |
| Fastest-Growing End User | Auto Distributors (7.8% CAGR) |
| Growing Sector | automotive |
| Key End Users | OEMs, dealerships, auto manufacturers, aftermarket suppliers |
China third-party logistics for vehicles Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
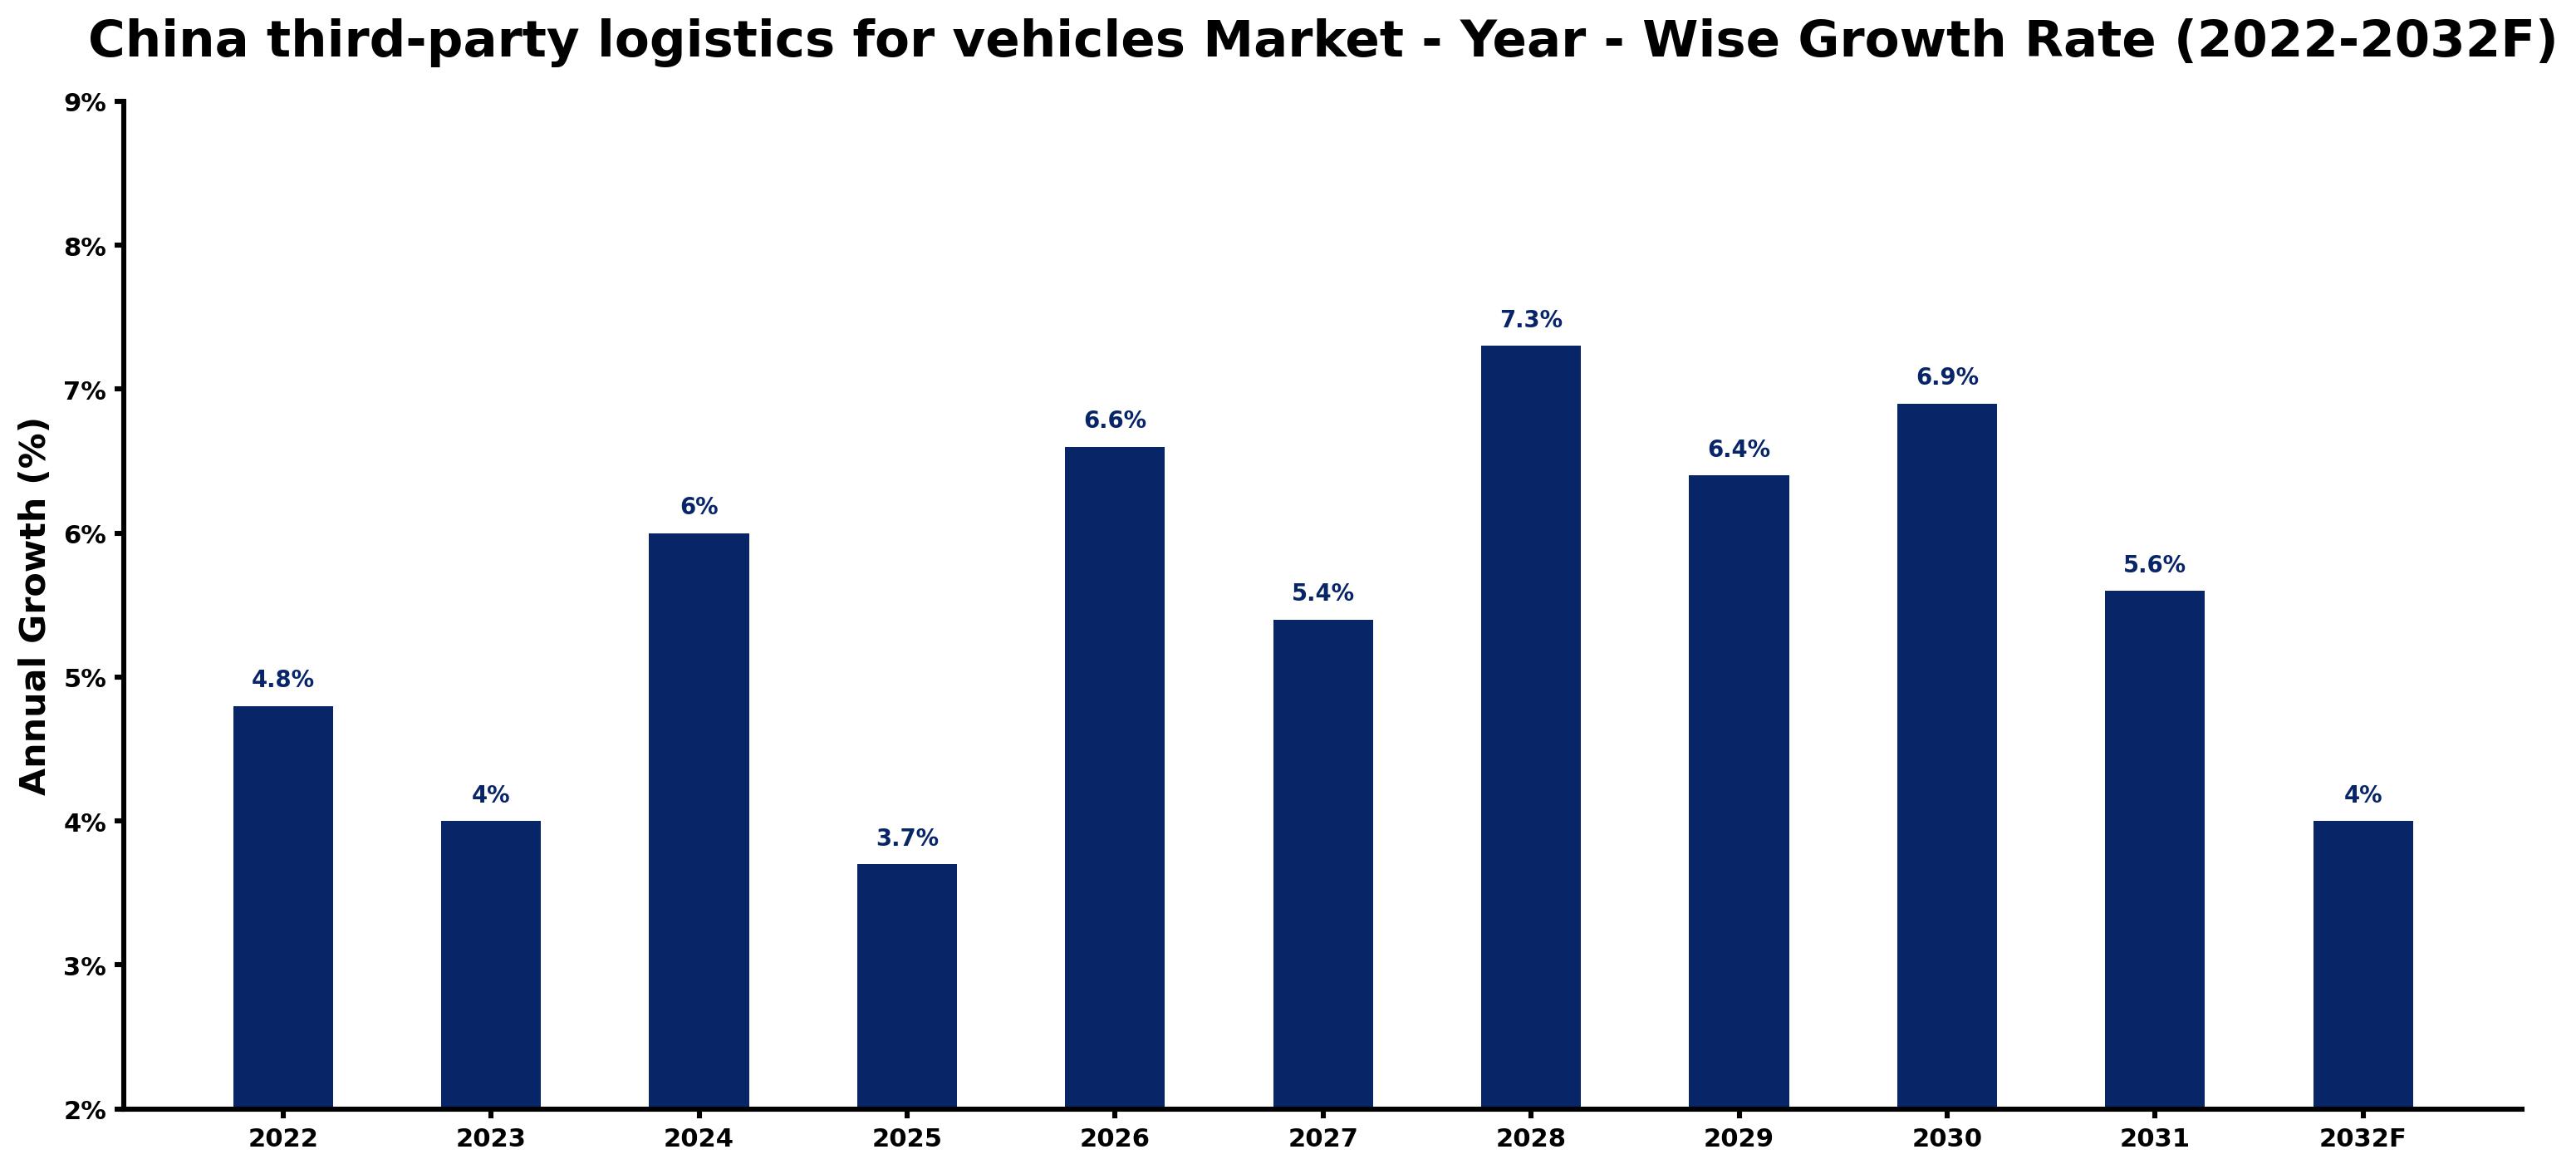
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.8 | The market experienced steady growth due to strong domestic demand for vehicles and the support from the automotive sector. |
| 2023 | 4.0 | Growth slowed as logistics infrastructure struggled to keep pace with increasing vehicle production demands. |
| 2024 | 6.0 | Increased production in the automotive sector boosted logistics requirements, particularly for finished vehicles. |
| 2025 | 3.7 | A slowdown occurred as the 'Automotive Industry Development Plan' was implemented to enhance logistics efficiency. |
| 2026 | 6.6 | Growth is expected to accelerate as logistics technology improves service quality and efficiency. |
| 2027 | 5.4 | A slight slowdown is projected as logistics providers adapt to evolving market needs and standards. |
| 2028 | 7.3 | The market is expected to peak with heightened demand driven by significant automotive production increases. |
| 2029 | 6.4 | Growth is projected to slow as logistics capacity aligns with market demands and operational efficiencies improve. |
| 2030 | 6.9 | Increased investment in logistics technology will support a rise in efficiency across the sector. |
| 2031 | 5.6 | A slowdown is anticipated as the market stabilises following rapid growth phases and operational improvements. |
| 2032 | 4.0 | Growth is expected to continue at a slower pace as the market matures and efficiencies are realised. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China third-party logistics for vehicles Market Synopsis
The China third-party logistics for vehicles Market encompasses the management of transportation and storage of vehicles and their components. This service is essential for the automotive industry, ensuring efficient delivery from manufacturers to dealerships. The market is growing due to rising vehicle production and an expanding automotive aftermarket. With over 25 million vehicles produced in 2022, demand for logistics services continues to increase, driven by both domestic sales and exports. The logistics sector supports over 1,000 auto manufacturers, facilitating the movement of finished vehicles and spare parts across the country.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising vehicle production fuels demand for logistics services. | Driver | High | Finished Vehicle Logistics |
| The automotive aftermarket is expanding, increasing logistics needs for parts distribution. | Driver | High | Spare Parts Logistics |
| Investment in logistics infrastructure is increasing, creating opportunities for service providers. | Opportunity | High | Inbound Logistics |
| The growth of e-commerce is driving demand for faster delivery services. | Opportunity | Medium | Express Delivery |
| Logistics inefficiencies can lead to delays in vehicle delivery. | Restraint | High | Finished Vehicle Logistics |
| High operational costs can limit the profitability of logistics providers. | Restraint | Medium | Spare Parts Logistics |
| The third-party logistics for vehicles market faces challenges from rising fuel prices. | Challenge | High | Inbound Logistics |
| Competition from in-house logistics operations can hinder third-party providers. | Challenge | Medium | Finished Vehicle Logistics |
Evaluation of Drivers in China third-party logistics for vehicles Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production creates higher demand for logistics services. | Finished Vehicle Logistics | In 2022, over 25 million vehicles were produced, necessitating efficient transportation to dealerships. |
| Growth in the automotive aftermarket drives parts distribution needs. | Spare Parts Logistics | The automotive aftermarket is projected to reach 1 trillion yuan by 2025, increasing logistics requirements. |
| Investment in logistics technology improves service efficiency. | Inbound Logistics | The 'Made in China 2025' initiative emphasises advancements in logistics technology, streamlining operations. |
| Expansion of logistics parks supports regional service capabilities. | Finished Vehicle Logistics | In 2023, approximately 200 logistics parks dedicated to automotive logistics were operational across China. |
| Rising e-commerce demand boosts express delivery services. | Express Delivery | The rise of online vehicle sales increases the need for faster logistics solutions. |
The third-party logistics for vehicles market in China is expanding due to heightened vehicle production, increasing automotive aftermarket demand, and growing investments in logistics technology. In 2022, over 25 million vehicles were produced, creating a need for efficient transportation to dealerships. The automotive aftermarket is anticipated to reach 1 trillion yuan by 2025, driving logistics requirements for parts distribution. The development of logistics parks, with around 200 dedicated facilities in 2023, improves regional service capabilities and optimises logistics operations.
Evaluation of Restraints in China third-party logistics for vehicles Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Logistics inefficiencies can lead to delays in vehicle delivery. | Finished Vehicle Logistics | In 2022, logistics efficiency ranked 26th globally, indicating room for improvement. |
| High operational costs can limit the profitability of logistics providers. | Spare Parts Logistics | The logistics sector employs over 10 million people, contributing to rising operational costs. |
| Fuel price fluctuations can impact logistics costs. | Inbound Logistics | Rising fuel prices directly affect transportation expenses for logistics providers, squeezing margins. |
| Limited integration between logistics and manufacturing sectors can hinder efficiency. | Finished Vehicle Logistics | Coordination issues between manufacturers and logistics providers can cause delays in deliveries. |
| Regulatory compliance costs can burden logistics providers. | Spare Parts Logistics | The Ministry of Industry and Information Technology regulates logistics standards, increasing operational costs. |
China third-party logistics for vehicles Market Challenges
The third-party logistics for vehicles market in China encounters a major technological hurdle, as outdated systems impede the timely movement of vehicles, delaying deliveries for manufacturers. Skills shortages in the logistics workforce lead to operational inefficiencies, increasing costs for suppliers who struggle to maintain quality service. Rising fuel prices have inflated transportation expenses, placing financial pressure on logistics providers and consequently raising prices for buyers. Supply chain disruptions, exacerbated by global events, result in inconsistent vehicle availability, frustrating dealerships and negatively impacting customer satisfaction.
Trends in the China third-party logistics for vehicles Market
Buyers and suppliers in the China third-party logistics for vehicles Market are adjusting to the following trends.
- Shift towards Eco-Friendly Logistics Practices: The launch of the 'Green Logistics Action Plan' in 2022 encourages sustainability in vehicle logistics. This initiative seeks to reduce carbon footprints and improve operational efficiency, aligning with global environmental standards.
- Growing Demand for Express Delivery Services: The surge in e-commerce has driven demand for express delivery services within the automotive sector. In 2023, this segment is expected to grow, reflecting changing consumer preferences.
- Expansion of Logistics Parks: The number of logistics parks dedicated to automotive logistics has risen, with around 200 operational in 2023. This growth strengthens regional service capabilities and supports the logistics sector's expansion.
- Increased Automation in Logistics Operations: The integration of automation technologies in logistics operations is gaining momentum. This shift, backed by the 'Made in China 2025' initiative, aims to improve efficiency and lower operational costs.
Investment Opportunities in the China third-party logistics for vehicles Market
Several openings in the China third-party logistics for vehicles Market merit attention from investors.
- Rising Demand for Inbound Logistics Services: With the automotive sector's growth, there is a strong opportunity for inbound logistics services. The logistics sector is projected to reach a value of 10 trillion yuan by 2025, creating investment opportunities for service providers.
- Investment in Logistics Technology: Now is the time to invest in logistics technology to improve efficiency. The 'Made in China 2025' initiative supports advancements in logistics, attracting investment from various stakeholders.
- Expansion of Automotive Aftermarket Services: The automotive aftermarket is projected to grow, presenting opportunities for logistics providers. With a projected value of 1 trillion yuan by 2025, suppliers can enter this market through partnerships.
- Development of New Logistics Parks: The current demand for logistics services creates opportunities for developing new logistics parks. Regions with high vehicle production, such as Guangdong, are ideal for investment, particularly through joint ventures.
Government Initiatives in the China third-party logistics for vehicles Market
The 'Automotive Industry Development Plan' introduced by the Ministry of Industry and Information Technology in 2021 aims to improve logistics efficiency and support innovation in the sector. This plan seeks to enhance coordination between manufacturers and logistics providers, ultimately benefiting buyers through reduced delivery times and improved service quality. The 'Green Logistics Action Plan' launched in 2022 promotes eco-friendly practices in vehicle logistics, encouraging companies to adopt sustainable operations, which can lead to cost savings and improved brand reputation. The updated 'National Standard for Vehicle Logistics' in 2021 further enhances service quality and operational efficiency for logistics providers.
In 2022, the National Development and Reform Commission allocated 500 million yuan to enhance logistics infrastructure for the automotive industry. This funding supports projects that improve transportation networks and logistics facilities, ultimately benefiting logistics providers and their clients. The Ministry of Transport oversees logistics standards and ensures compliance with regulations, which helps maintain service quality and operational efficiency in the sector. The 'Logistics Modernization Strategy' approved by the State Council in 2023 aims to improve logistics services for the automotive sector by 2025.
Future Insight of the China third-party logistics for vehicles Market
By 2032, buyers and suppliers in the third-party logistics for vehicles market in China can anticipate notable advancements driven by technology, including automated tracking systems that improve operational efficiency. The 'Automotive Industry Development Plan' will enhance collaboration among industry players, streamlining processes and ensuring timely deliveries. With the automotive aftermarket projected to grow to 1 trillion yuan by 2025, logistics companies will broaden their service offerings to meet evolving market needs. The 'Green Logistics Action Plan' will promote sustainable practices, aligning operations with international environmental standards.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Service Type – Finished Vehicle Logistics Dominated, Inbound Logistics Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Finished Vehicle Logistics took a 43% share of service type in 2025, more than any other category. Finished Vehicle Logistics commands the largest share due to its essential role in transporting completed vehicles to over 15,000 registered dealerships across China. This segment is crucial for maintaining the efficiency of the automotive supply chain, particularly with the production of over 25 million vehicles in 2022. Inbound Logistics is set to record the highest CAGR in this split, 8.5% over 2026–2032. Inbound Logistics is experiencing rapid growth as manufacturers increasingly require efficient sourcing of materials and components. The strong output of over 25 million vehicles in 2022 highlights the escalating demand for this logistics segment. Suppliers must focus on enhancing their inbound logistics capabilities to effectively support manufacturers' growing needs.
By Transport Mode – Road/Rail Dominated, Express Delivery Expected to Grow Fastest
Road/Rail accounted for a 52% market share by transport mode in 2025. Road/Rail dominates the market share as the primary modes for transporting vehicles across China's vast territory. With an average distance of approximately 1,000 kilometers for vehicle transportation, these modes are integral to logistics operations. The quickest growth will come from Express Delivery, forecast to expand at a CAGR of 8.2% between 2026 and 2032. Express Delivery is growing quickly, primarily for urgent deliveries of parts or documents, catering to the fast-paced demands of the automotive sector. The increasing focus on timely deliveries is propelling this segment's growth. Logistics providers must invest in express delivery capabilities to meet the rising expectations for speed and efficiency.
By Client Type – OEMs Dominated, Aftermarket Suppliers Expected to Grow Fastest
The largest client type category in 2025 was OEMs, with a 55% share of total revenue. OEMs represent the largest share as they are the primary clients needing logistics for their manufacturing processes, ensuring a steady flow of vehicles to the market. Their pivotal role in the automotive industry significantly drives the demand for reliable logistics services. Aftermarket Suppliers are projected to grow fastest, at a CAGR of 8.5% during 2026–2032. Aftermarket Suppliers are rapidly expanding as they increasingly rely on logistics for distributing parts to repair shops, driven by the automotive aftermarket projected to reach 1 trillion yuan by 2025. Logistics providers should tailor their services to meet the specific demands of aftermarket suppliers as their market share continues to grow.
By End User – Auto Manufacturers Dominated, Auto Distributors Expected to Grow Fastest
In 2025, Auto Manufacturers led the end user split with a 44% share. Auto Manufacturers hold the largest market share as they are the main users of logistics services for production and distribution, which is vital for the overall efficiency of the automotive sector. Their operations necessitate robust logistics solutions to effectively manage the flow of vehicles. Over 2026–2032, Auto Distributors are expected to post the fastest growth, at a CAGR of 7.8%. Auto Distributors are growing at the fastest rate as they require logistics for managing inventory and distribution, influenced by the increasing number of registered vehicles, which surpassed 300 million in 2023. Logistics firms should refine their services to better serve auto distributors, capitalising on the rising demand for efficient inventory management.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China third-party logistics for vehicles Market Outlook
- Market Size of China third-party logistics for vehicles Market, 2025
- Forecast of China third-party logistics for vehicles Market, 2032
- Historical Data and Forecast of China third-party logistics for vehicles Revenues & Volume for the Period 2022 - 2032F
- China third-party logistics for vehicles Market Trend Evolution
- China third-party logistics for vehicles Market Drivers and Challenges
- China third-party logistics for vehicles Price Trends
- China third-party logistics for vehicles Porter's Five Forces
- China third-party logistics for vehicles Industry Life Cycle
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Inbound Logistics for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Finished Vehicle Logistics for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Spare Parts Logistics for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Reverse Logistics for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Transport Mode for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Road/Rail for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Sea/Truck for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Express Delivery for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Pickup + Return for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Client Type for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Dealerships for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Aftermarket Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Used Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Auto Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Auto Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Parts Retailers for the Period 2022 - 2032F
- Historical Data and Forecast of China third-party logistics for vehicles Market Revenues & Volume By Vehicle Leasing Firms for the Period 2022 - 2032F
- China third-party logistics for vehicles Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Transport Mode
- Market Opportunity Assessment By Client Type
- Market Opportunity Assessment By End User
- China third-party logistics for vehicles Top Companies Market Share
- China third-party logistics for vehicles Competitive Benchmarking By Technical and Operational Parameters
- China third-party logistics for vehicles Company Profiles
- China third-party logistics for vehicles Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Service Type
- Inbound Logistics
- Finished Vehicle Logistics
- Spare Parts Logistics
- Reverse Logistics
By Transport Mode
- Road/Rail
- Sea/Truck
- Express Delivery
- Pickup + Return
By Client Type
- OEMs
- Dealerships
- Aftermarket Suppliers
- Used Vehicles
By End User
- Auto Manufacturers
- Auto Distributors
- Parts Retailers
- Vehicle Leasing Firms































