China Transmission Component Market Size & Growth Rate
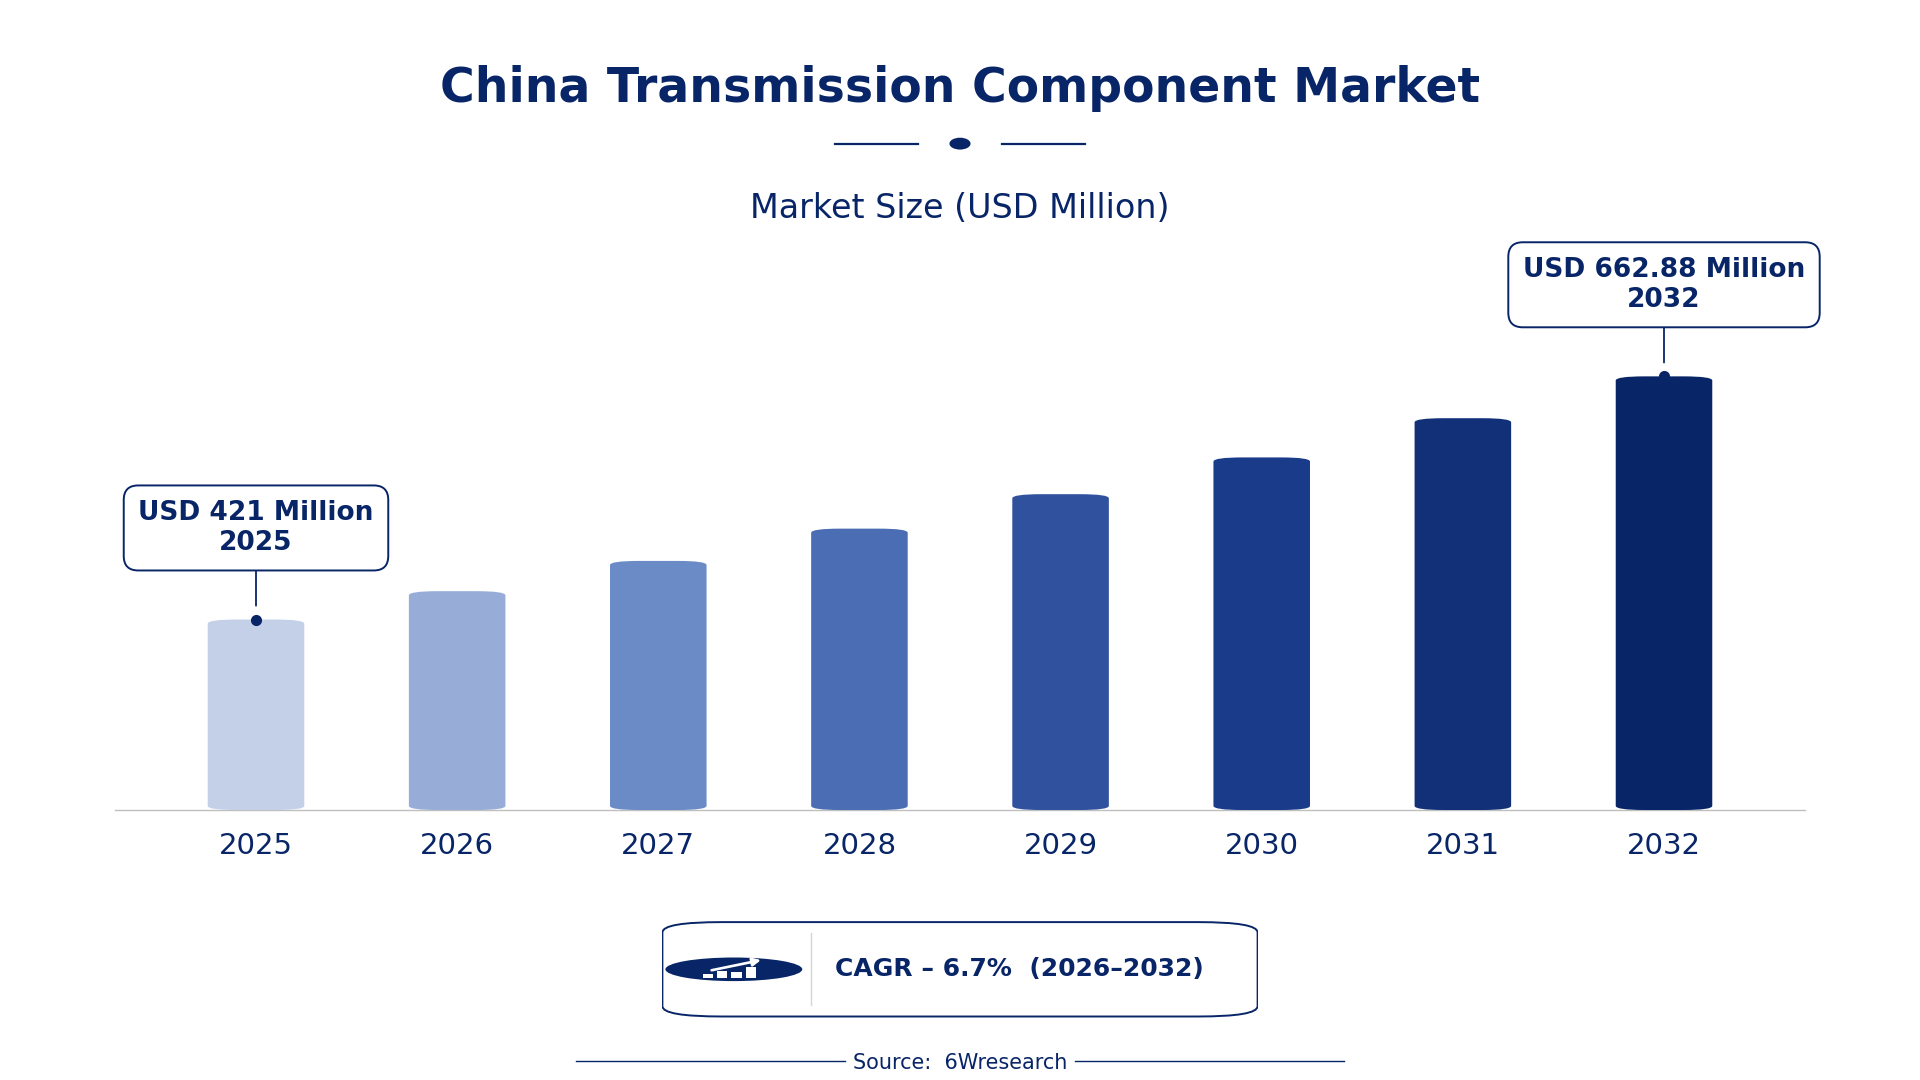
According to 6Wresearch internal database and industry insights, the China Transmission Component Market was valued at USD 421.0 million in 2025 and is projected to reach USD 662.88 million by 2032, growing at a CAGR of approximately 6.7% during 2026–2032.
China Transmission Component Market Highlights
| Report Metric | Details |
| Report Name | China Transmission Component Market |
| Market Size 2025 | USD 421.0 million |
| Market Size 2032 | USD 662.88 million |
| Absolute Growth 2025–2032 | USD 241.88 million |
| CAGR 2026–2032 | 6.7% |
| Peak Annual Growth | 8.4% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Gear Assemblies (36% share) |
| Leading Functionality, 2025 | Torque Transfer (51% share) |
| Leading Vehicle Segment, 2025 | Passenger Vehicles (53% share) |
| Leading End User, 2025 | Auto Manufacturers (36% share) |
| Fastest-Growing Component Type | Torque Converters (9.3% CAGR) |
| Fastest-Growing Functionality | Power Modulation (9.5% CAGR) |
| Fastest-Growing Vehicle Segment | SUVs & Vans (8.2% CAGR) |
| Fastest-Growing End User | Transmission Suppliers (7.7% CAGR) |
| Growing Sector | automotive |
| Key End Users | Auto Manufacturers, Transmission Suppliers, Gearbox Manufacturers, OEMs |
China Transmission Component Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
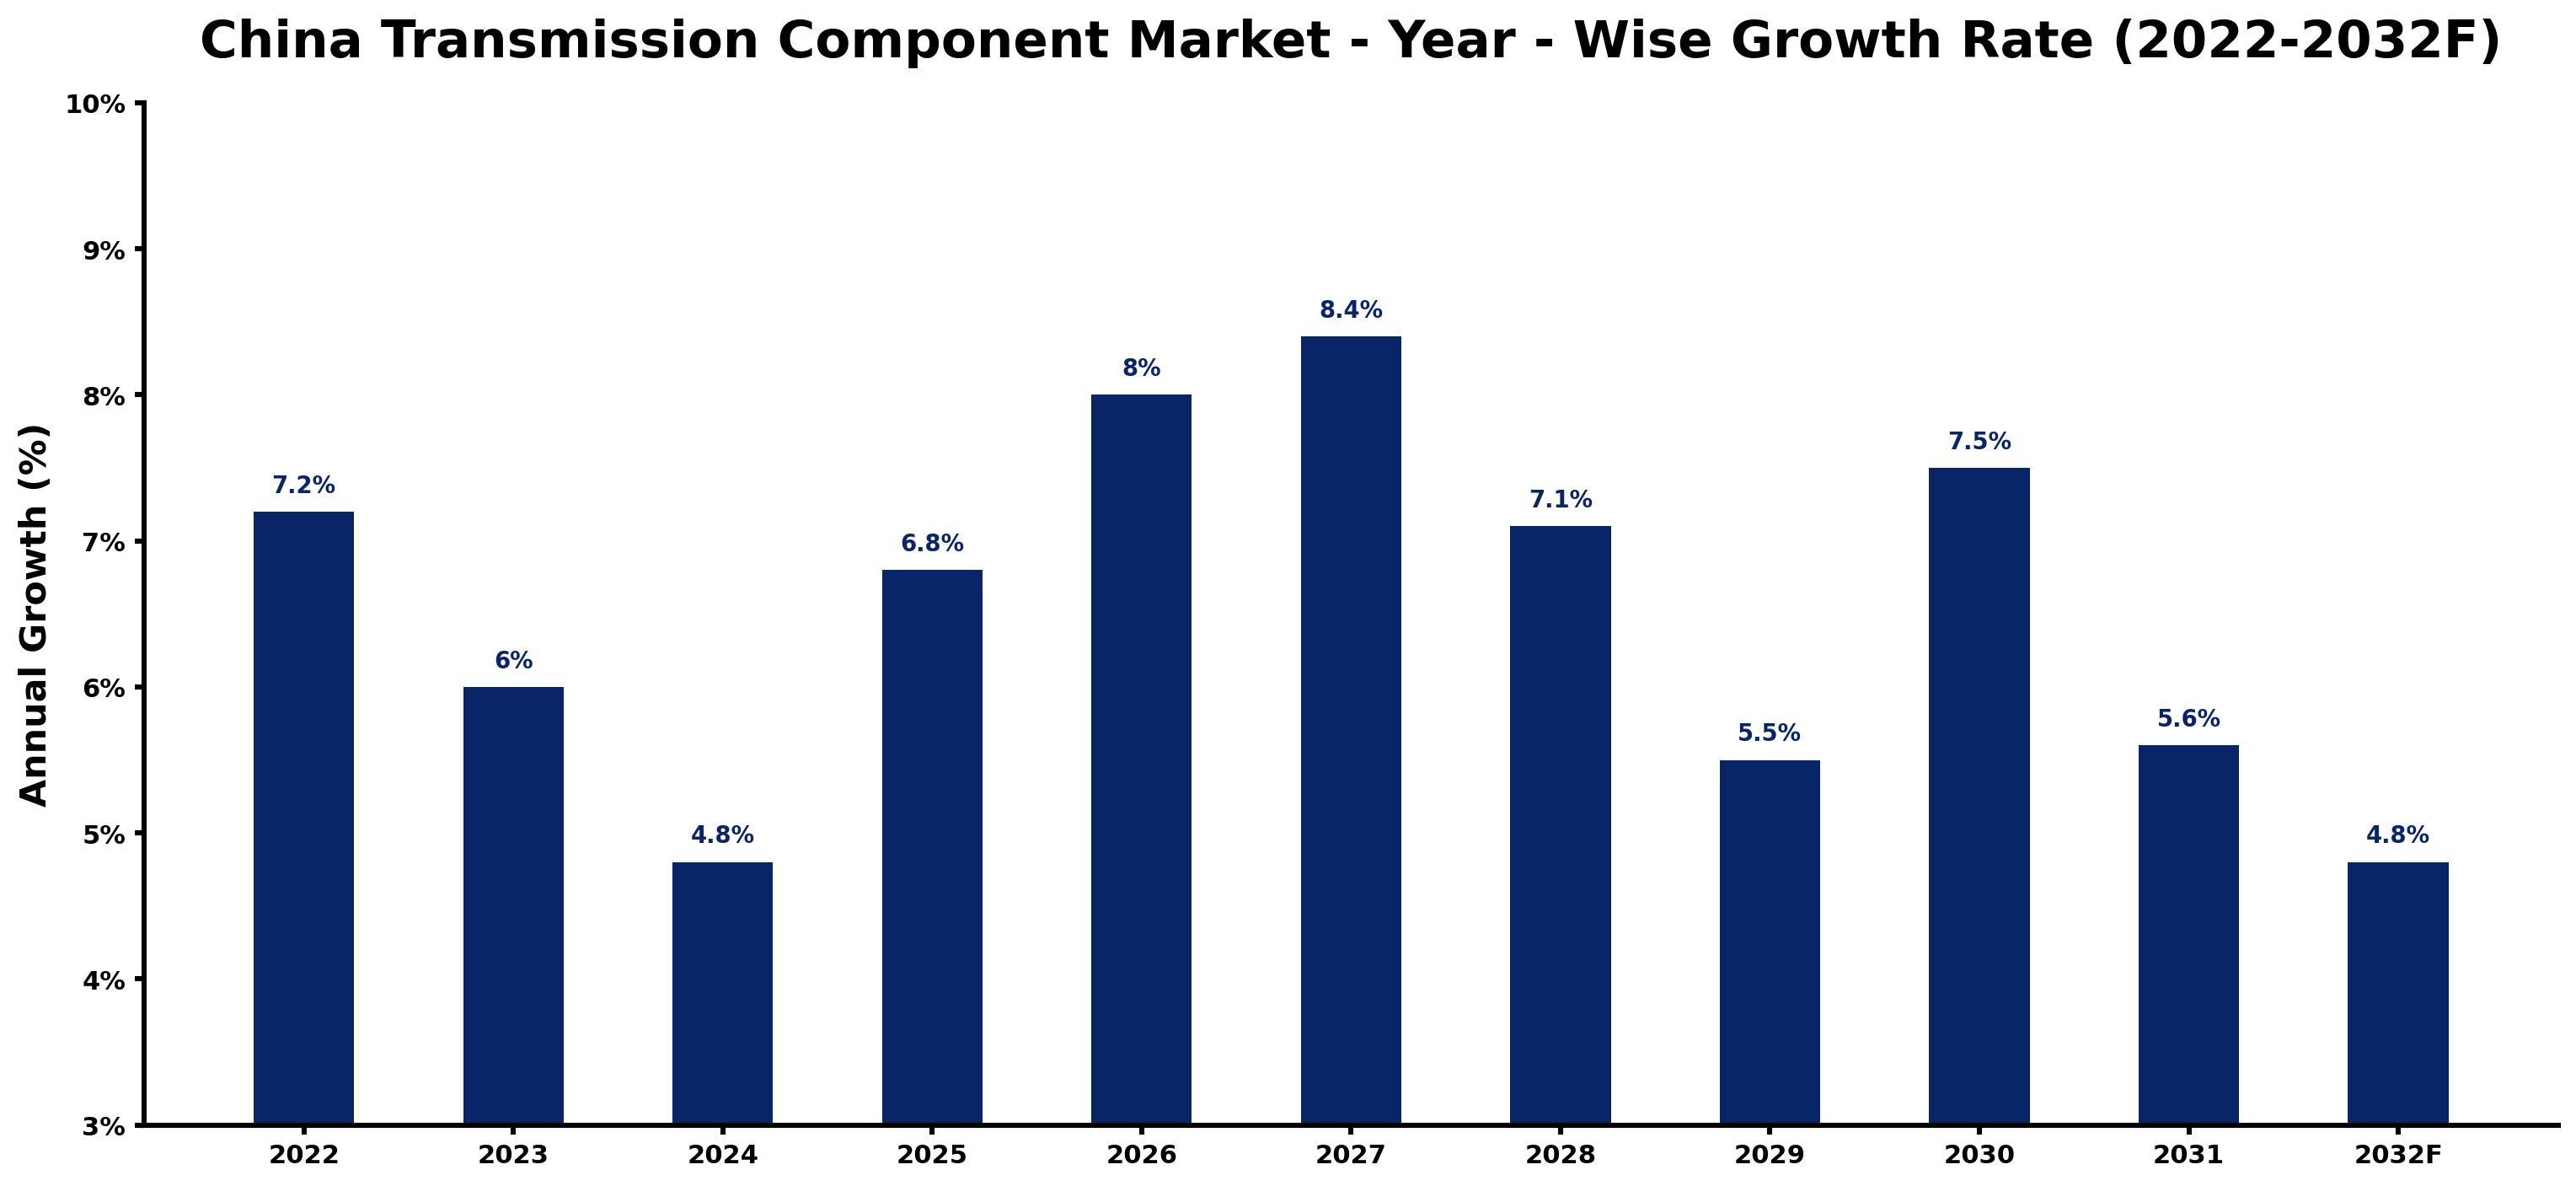
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.2 | The automotive sector remained strong, with vehicle production driving component demand. |
| 2023 | 6.0 | Demand growth slowed due to the 'New Energy Vehicle Industry Development Plan' focusing on electric vehicle technology. |
| 2024 | 4.8 | The market continued to experience a slowdown as manufacturers adapted to the updated emissions standards. |
| 2025 | 6.8 | Increased production capabilities led to a faster growth rate as demand rebounded. |
| 2026 | 8.0 | Investment in advanced transmission technologies is expected to spur growth, boosting component production. |
| 2027 | 8.4 | The peak growth rate is projected as the logistics sector expands rapidly. |
| 2028 | 7.1 | A slight slowdown is anticipated as the market adjusts to evolving consumer preferences. |
| 2029 | 5.5 | Continued adjustments in production strategies will lead to another slowdown in growth. |
| 2030 | 7.5 | Growth is expected to accelerate again as demand for SUVs and Vans surges in the market. |
| 2031 | 5.6 | A slowdown is projected as manufacturers face challenges in meeting new regulations. |
| 2032 | 4.8 | The market is expected to slow further as electric vehicle sales impact traditional component demand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Transmission Component Market Synopsis
The China Transmission Component Market encompasses mechanical parts essential for transferring power from engines to wheels. These components, including gear assemblies and clutches, are produced through precision engineering processes. The market is growing due to strong demand from auto manufacturers, driven by over 25 million passenger vehicles produced in 2022. The expansion of the logistics sector and the rise of electric vehicles also contribute to this growth. With the automotive aftermarket projected to reach 1 trillion yuan by 2025, opportunities for replacement components are increasing.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing production of passenger vehicles | Driver | High | Gear Assemblies |
| Increased focus on electric vehicle technology | Driver | High | Torque Converters |
| Rising demand for replacement components | Opportunity | High | Transmission Shafts |
| Expansion of the automotive aftermarket | Opportunity | High | Clutches |
| Challenges in meeting new emissions standards | Restraint | High | Torque Transfer |
| Supply chain disruptions affecting production | Restraint | Medium | Power Modulation |
| Technological advancements in electric vehicles | Challenge | High | Rotation Transmission |
| Increasing competition from international suppliers | Challenge | Medium | Speed Regulation |
Evaluation of Drivers in China Transmission Component Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased production of over 25 million passenger vehicles in 2022 | Gear Assemblies | This high production volume drives demand for essential components like gear assemblies. |
| Investment in advanced transmission technologies | Torque Converters | Manufacturers are focusing on improving automatic transmission systems, increasing demand for torque converters. |
| Growth of the logistics sector in urban areas | Transmission Shafts | As logistics expand, the need for reliable transmission shafts in commercial vehicles rises. |
| Surge in electric vehicle sales projected at 20% by 2025 | Clutches | Electric vehicles require advanced clutch designs, boosting demand for innovative components. |
| Expansion of the automotive aftermarket projected to reach 1 trillion yuan by 2025 | Torque Transfer | The growing aftermarket enhances demand for replacement torque transfer components. |
The Transmission Component market in China is expanding as increased production of over 25 million passenger vehicles in 2022 drives demand for essential components. Investment in advanced transmission technologies is expected to spur growth, leading to higher demand for torque converters. The logistics sector's growth in urban areas raises the need for reliable transmission shafts in commercial vehicles. Electric vehicle sales are projected to account for 20% of new car sales by 2025, increasing the demand for innovative clutches. The automotive aftermarket is anticipated to reach 1 trillion yuan by 2025, creating further opportunities for replacement torque transfer components.
Evaluation of Restraints in China Transmission Component Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in meeting new emissions standards | Torque Transfer | The updated emissions standards in 2023 require design changes, impacting production timelines for manufacturers. |
| Supply chain disruptions affecting production | Power Modulation | Global supply chain issues have delayed the availability of critical materials for power modulation components, hindering production schedules. |
| Rising costs of raw materials | Torque Converters | Increased material costs have pressured profit margins for manufacturers of torque converters, affecting pricing strategies. |
| Technological adaptation delays due to regulatory changes | Clutches | Manufacturers face challenges in quickly adapting to new regulations affecting clutch designs, leading to potential compliance issues. |
| Limited skilled workforce in advanced manufacturing | Gear Assemblies | A shortage of skilled workers in precision engineering is hindering production capacity for gear assemblies, impacting output. |
China Transmission Component Market Challenges
The China Transmission Component Market encounters several practical issues, starting with fierce competition among manufacturers. This competition stems from the high concentration of producers in Guangdong province, resulting in price reductions that squeeze profit margins. As a result, many suppliers find it challenging to sustain their operations. Rising raw material costs also weigh heavily on the market, inflating production expenses by up to 15% for manufacturers. Supply chain disruptions complicate operations, as delays in component delivery can extend lead times for buyers, adversely affecting vehicle production schedules. Regulatory changes from the National Development and Reform Commission may impose new compliance costs, compelling manufacturers to invest in updated processes that strain their budgets.
Trends in the China Transmission Component Market
The trends below show where the China Transmission Component Market is heading.
- Start of Electric Vehicle Integration in 2025: The shift towards electric vehicles began in 2025, impacting transmission component design. With electric vehicles projected to account for 20% of new sales, manufacturers are adapting their products to meet these new demands.
- Increase in Aftermarket Demand Since 2023: The automotive aftermarket has seen growth since 2023, with projections reaching 1 trillion yuan by 2025. This trend indicates a rising need for replacement transmission components among consumers.
- Shift Towards Advanced Torque Transfer Systems: Auto manufacturers are increasingly adopting advanced torque transfer systems to improve vehicle performance. This shift has been driven by the need for efficiency and compliance with new standards.
- Growth of the Logistics Sector Since 2022: The logistics sector has expanded rapidly since 2022, increasing demand for reliable transmission components in commercial vehicles. This growth is vital for meeting the needs of urban transportation.
Investment Opportunities in the China Transmission Component Market
Below are the investment opportunities with the strongest case in the China Transmission Component Market.
- Joint Ventures with Local Manufacturers: Establishing joint ventures with local manufacturers in Guangdong province can facilitate market entry. With over 25 million vehicles produced in 2022, there is a strong demand for transmission components.
- Investment in Electric Vehicle Components: Investing in components for electric vehicles is timely as they are expected to account for 20% of new sales by 2025. This offers opportunities for suppliers to innovate and capture market share.
- Expansion into the Automotive Aftermarket: The automotive aftermarket is projected to reach 1 trillion yuan by 2025, presenting a significant opportunity for suppliers of replacement components. Engaging with local distributors can facilitate market entry.
- Focus on Advanced Manufacturing Facilities: Now is the time to invest in advanced manufacturing facilities to meet the rising demand for high-quality transmission components. The logistics sector's growth supports this need.
Government Initiatives in the China Transmission Component Market
The '14th Five-Year Plan for the Development of the Automotive Industry' launched by the State Council in 2021 aims to improve innovation and competitiveness in the sector. This plan encourages manufacturers to invest in advanced technologies and enhance production capabilities. In 2020, the Ministry of Industry and Information Technology introduced the 'New Energy Vehicle Industry Development Plan', promoting electric vehicle technology and components. This initiative supports the transition to greener technologies and influences component design. In 2022, the National Development and Reform Commission approved a subsidy program for manufacturers investing in advanced transmission technologies, alleviating financial burdens and encouraging innovation in the sector.
The 'Green Freight Transport Development Plan' established by the Ministry of Transport in 2023 promotes efficient transmission systems in commercial vehicles. This initiative supports the logistics sector and enhances environmental standards. The National Development and Reform Commission oversees regulations affecting the transmission component industry, ensuring compliance with updated standards. Local manufacturers benefit from these measures as they can access funding for technology upgrades and improvements in production efficiency.
Future Insight of the China Transmission Component Market
The China Transmission Component Market will undergo significant changes by 2032, primarily driven by the rise of electric vehicles, projected to account for 25% of new car sales. This shift will necessitate a redesign of transmission components to accommodate electric drivetrains, prompting suppliers to integrate advanced manufacturing technologies. The 'Automotive Industry Development Plan' will support improvements in production capabilities, encouraging innovation in component design. By 2025, the automotive aftermarket is expected to reach 1.2 trillion yuan, creating new opportunities for buyers seeking replacement components and motivating suppliers to diversify their product offerings.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Component Type – Gear Assemblies Dominated, Torque Converters Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Gear Assemblies held a 36% share of the China Transmission Component Market by component type in 2025. Gear assemblies command the largest market share due to their essential role in vehicle operation, supported by the production of over 25 million passenger vehicles in 2022. Their reliability and widespread use among auto manufacturers, particularly in regions like Guangdong, solidify their leading position. Torque Converters are projected to grow fastest, at a CAGR of 9.3% during 2026–2032. Torque converters are experiencing rapid growth as they are critical for automatic transmissions, which are increasingly favoured by consumers. This shift towards automatic vehicles is expected to significantly boost demand in the coming years. Suppliers should focus on enhancing production capabilities for torque converters to meet the rising market demand.
By Functionality – Torque Transfer Dominated, Power Modulation Expected to Grow Fastest
Torque Transfer took a 51% share of functionality in 2025, more than any other category. Torque transfer holds the largest market share as it is fundamental for vehicle movement, ensuring efficient power delivery from the engine to the wheels. Given the high volume of passenger vehicles produced in China, this functionality's importance reinforces its market dominance. The quickest growth will come from Power Modulation, forecast to expand at a CAGR of 9.5% between 2026 and 2032. Power modulation is set to grow swiftly due to its integration in advanced systems designed to improve vehicle efficiency. As the industry adopts smarter technologies, the demand for power modulation components is anticipated to surge. Manufacturers should invest in power modulation technologies to align with the automotive industry's increasing focus on efficiency.
By Vehicle Segment – Passenger Vehicles Dominated, SUVs & Vans Expected to Grow Fastest
With a 53% revenue share in 2025, Passenger Vehicles was the largest vehicle segment category. Passenger vehicles account for the largest market share as they represent the primary segment for consumer use, with over 25 million units produced in 2022. This high production volume drives consistent demand for transmission components tailored to this segment. SUVs & Vans are set to record the highest CAGR in this split, 8.2% over 2026–2032. SUVs and vans are the fastest-growing vehicle segment, reflecting changing consumer preferences for family and utility vehicles. The increasing popularity of these vehicle types is expected to boost demand for specific transmission components designed for larger models. Suppliers must adapt their offerings to meet the rising demand for transmission components in the SUV and van segments.
By End User – Auto Manufacturers Dominated, Transmission Suppliers Expected to Grow Fastest
Auto Manufacturers accounted for a 36% market share by end user in 2025. Auto manufacturers capture the largest market share as they are the primary users of transmission components, directly influencing production volumes. Their significant role in the automotive sector, which employs over 5 million people, shapes the overall market environment. Over 2026–2032, Transmission Suppliers are expected to post the fastest growth, at a CAGR of 7.7%. Transmission suppliers are witnessing the fastest growth as they provide essential parts to manufacturers, responding to the rising vehicle production rates. The expansion of the automotive sector is leading to more partnerships with these suppliers. Suppliers should strengthen collaborations with auto manufacturers to secure a larger share of the growing market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Transmission Component Market Outlook
- Market Size of China Transmission Component Market, 2025
- Forecast of China Transmission Component Market, 2032
- Historical Data and Forecast of China Transmission Component Revenues & Volume for the Period 2022 - 2032F
- China Transmission Component Market Trend Evolution
- China Transmission Component Market Drivers and Challenges
- China Transmission Component Price Trends
- China Transmission Component Porter's Five Forces
- China Transmission Component Industry Life Cycle
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Gear Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Clutches for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Torque Converters for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Transmission Shafts for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Torque Transfer for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Power Modulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Speed Regulation for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Rotation Transmission for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Vehicle Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Passenger Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Commercial Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By SUVs & Vans for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Off-Road Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Auto Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Transmission Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By Gearbox Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Transmission Component Market Revenues & Volume By OEMs for the Period 2022 - 2032F
- China Transmission Component Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Vehicle Segment
- Market Opportunity Assessment By End User
- China Transmission Component Top Companies Market Share
- China Transmission Component Competitive Benchmarking By Technical and Operational Parameters
- China Transmission Component Company Profiles
- China Transmission Component Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Component Type
- Gear Assemblies
- Clutches
- Torque Converters
- Transmission Shafts
By Functionality
- Torque Transfer
- Power Modulation
- Speed Regulation
- Rotation Transmission
By Vehicle Segment
- Passenger Vehicles
- Commercial Vehicles
- SUVs & Vans
- Off-Road Vehicles
By End User
- Auto Manufacturers
- Transmission Suppliers
- Gearbox Manufacturers
- OEMs































