China Tube & Pipe Materials Market Size & Growth Rate
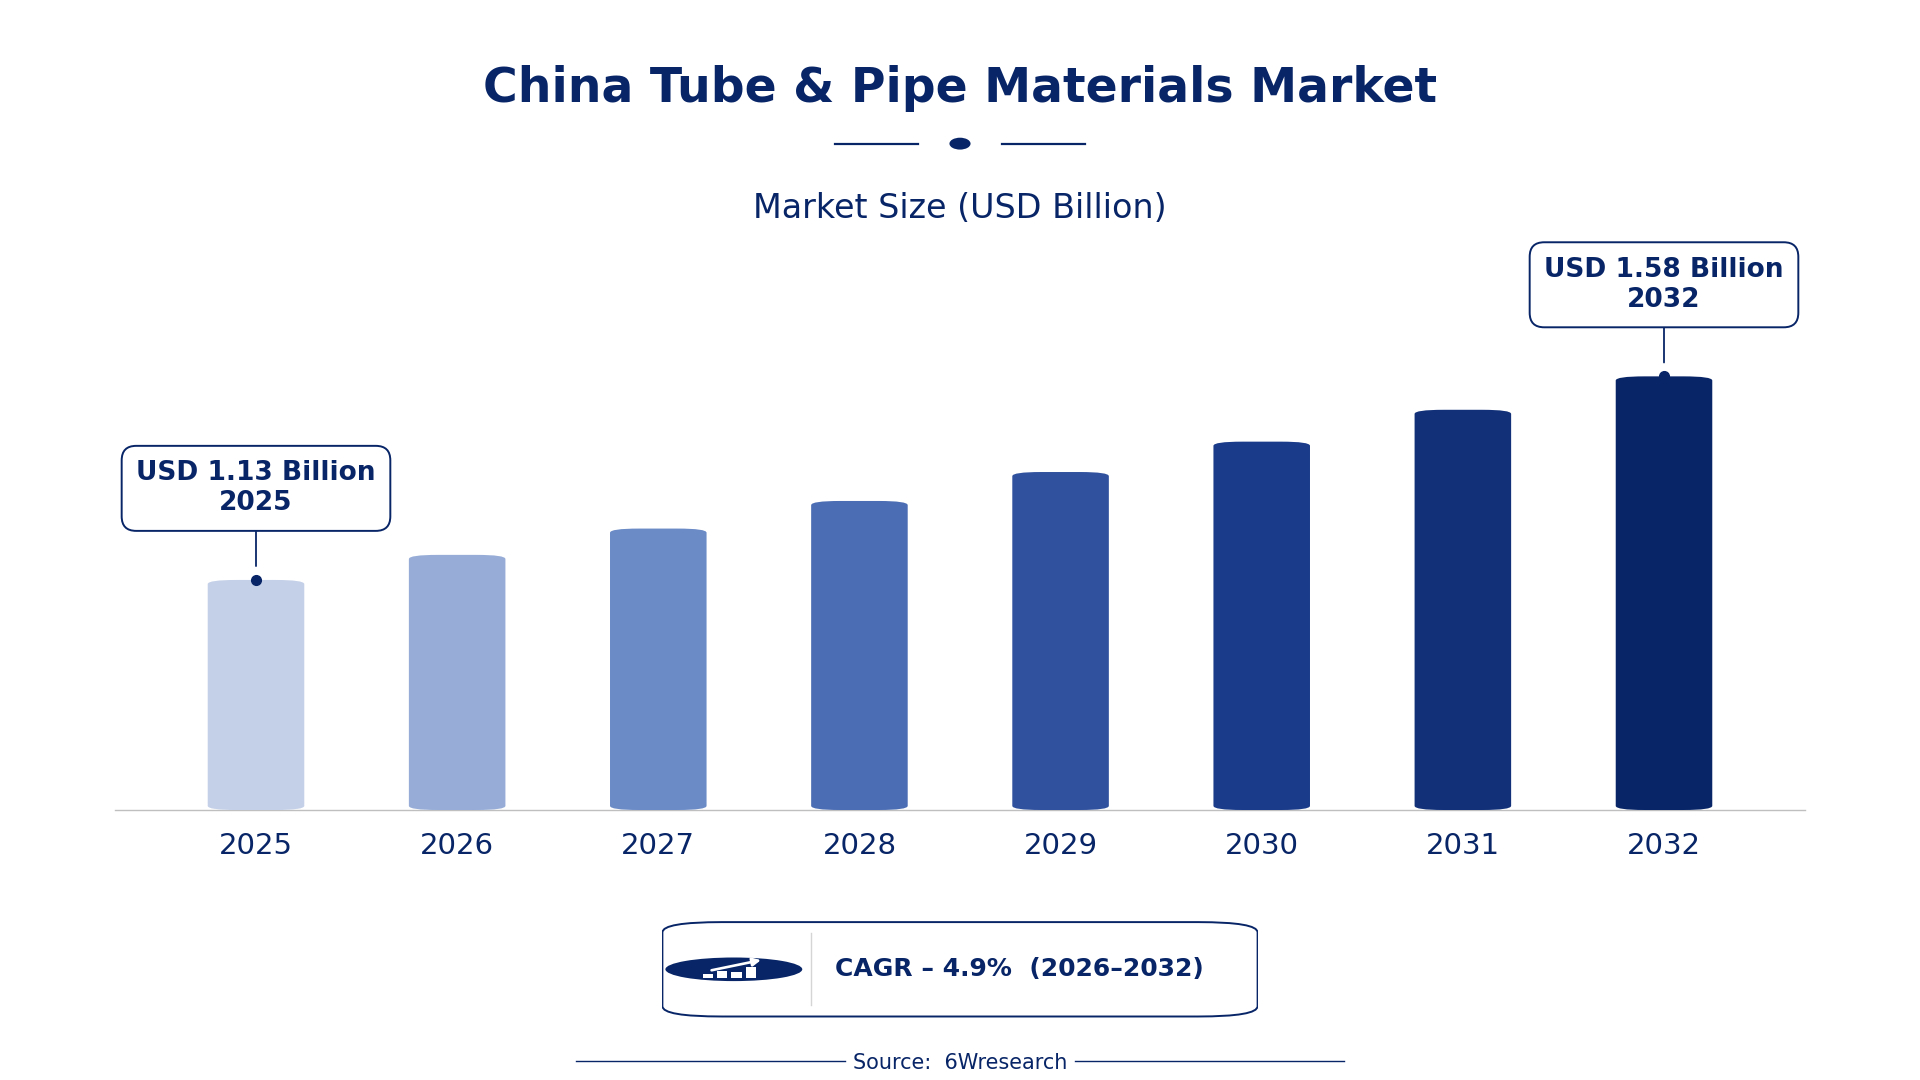
According to 6Wresearch internal database and industry insights, the China Tube & Pipe Materials Market was valued at USD 1.13 billion in 2025 and is projected to reach USD 1.58 billion by 2032, growing at a CAGR of approximately 4.9% during 2026–2032.
China Tube & Pipe Materials Market Highlights
| Report Metric | Details |
| Report Name | China Tube & Pipe Materials Market |
| Market Size 2025 | USD 1.13 billion |
| Market Size 2032 | USD 1.58 billion |
| Absolute Growth 2025–2032 | USD 0.45 billion |
| CAGR 2026–2032 | 4.9% |
| Peak Annual Growth | 6.7% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Carbon Steel (37% share) |
| Leading Form Type, 2025 | Seamless Pipe (43% share) |
| Leading Application Area, 2025 | Oil & Gas Pipelines (39% share) |
| Leading End User, 2025 | Construction Firms (32% share) |
| Fastest-Growing Material Type | Stainless Steel (6.0% CAGR) |
| Fastest-Growing Form Type | Welded Tubes (7.2% CAGR) |
| Fastest-Growing Application Area | Chemical Processing (6.4% CAGR) |
| Fastest-Growing End User | Industrial Manufacturers (7.3% CAGR) |
| Growing Sector | Oil & Gas |
| Key End Users | Construction Firms, Industrial Manufacturers, Refinery Contractors |
China Tube & Pipe Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
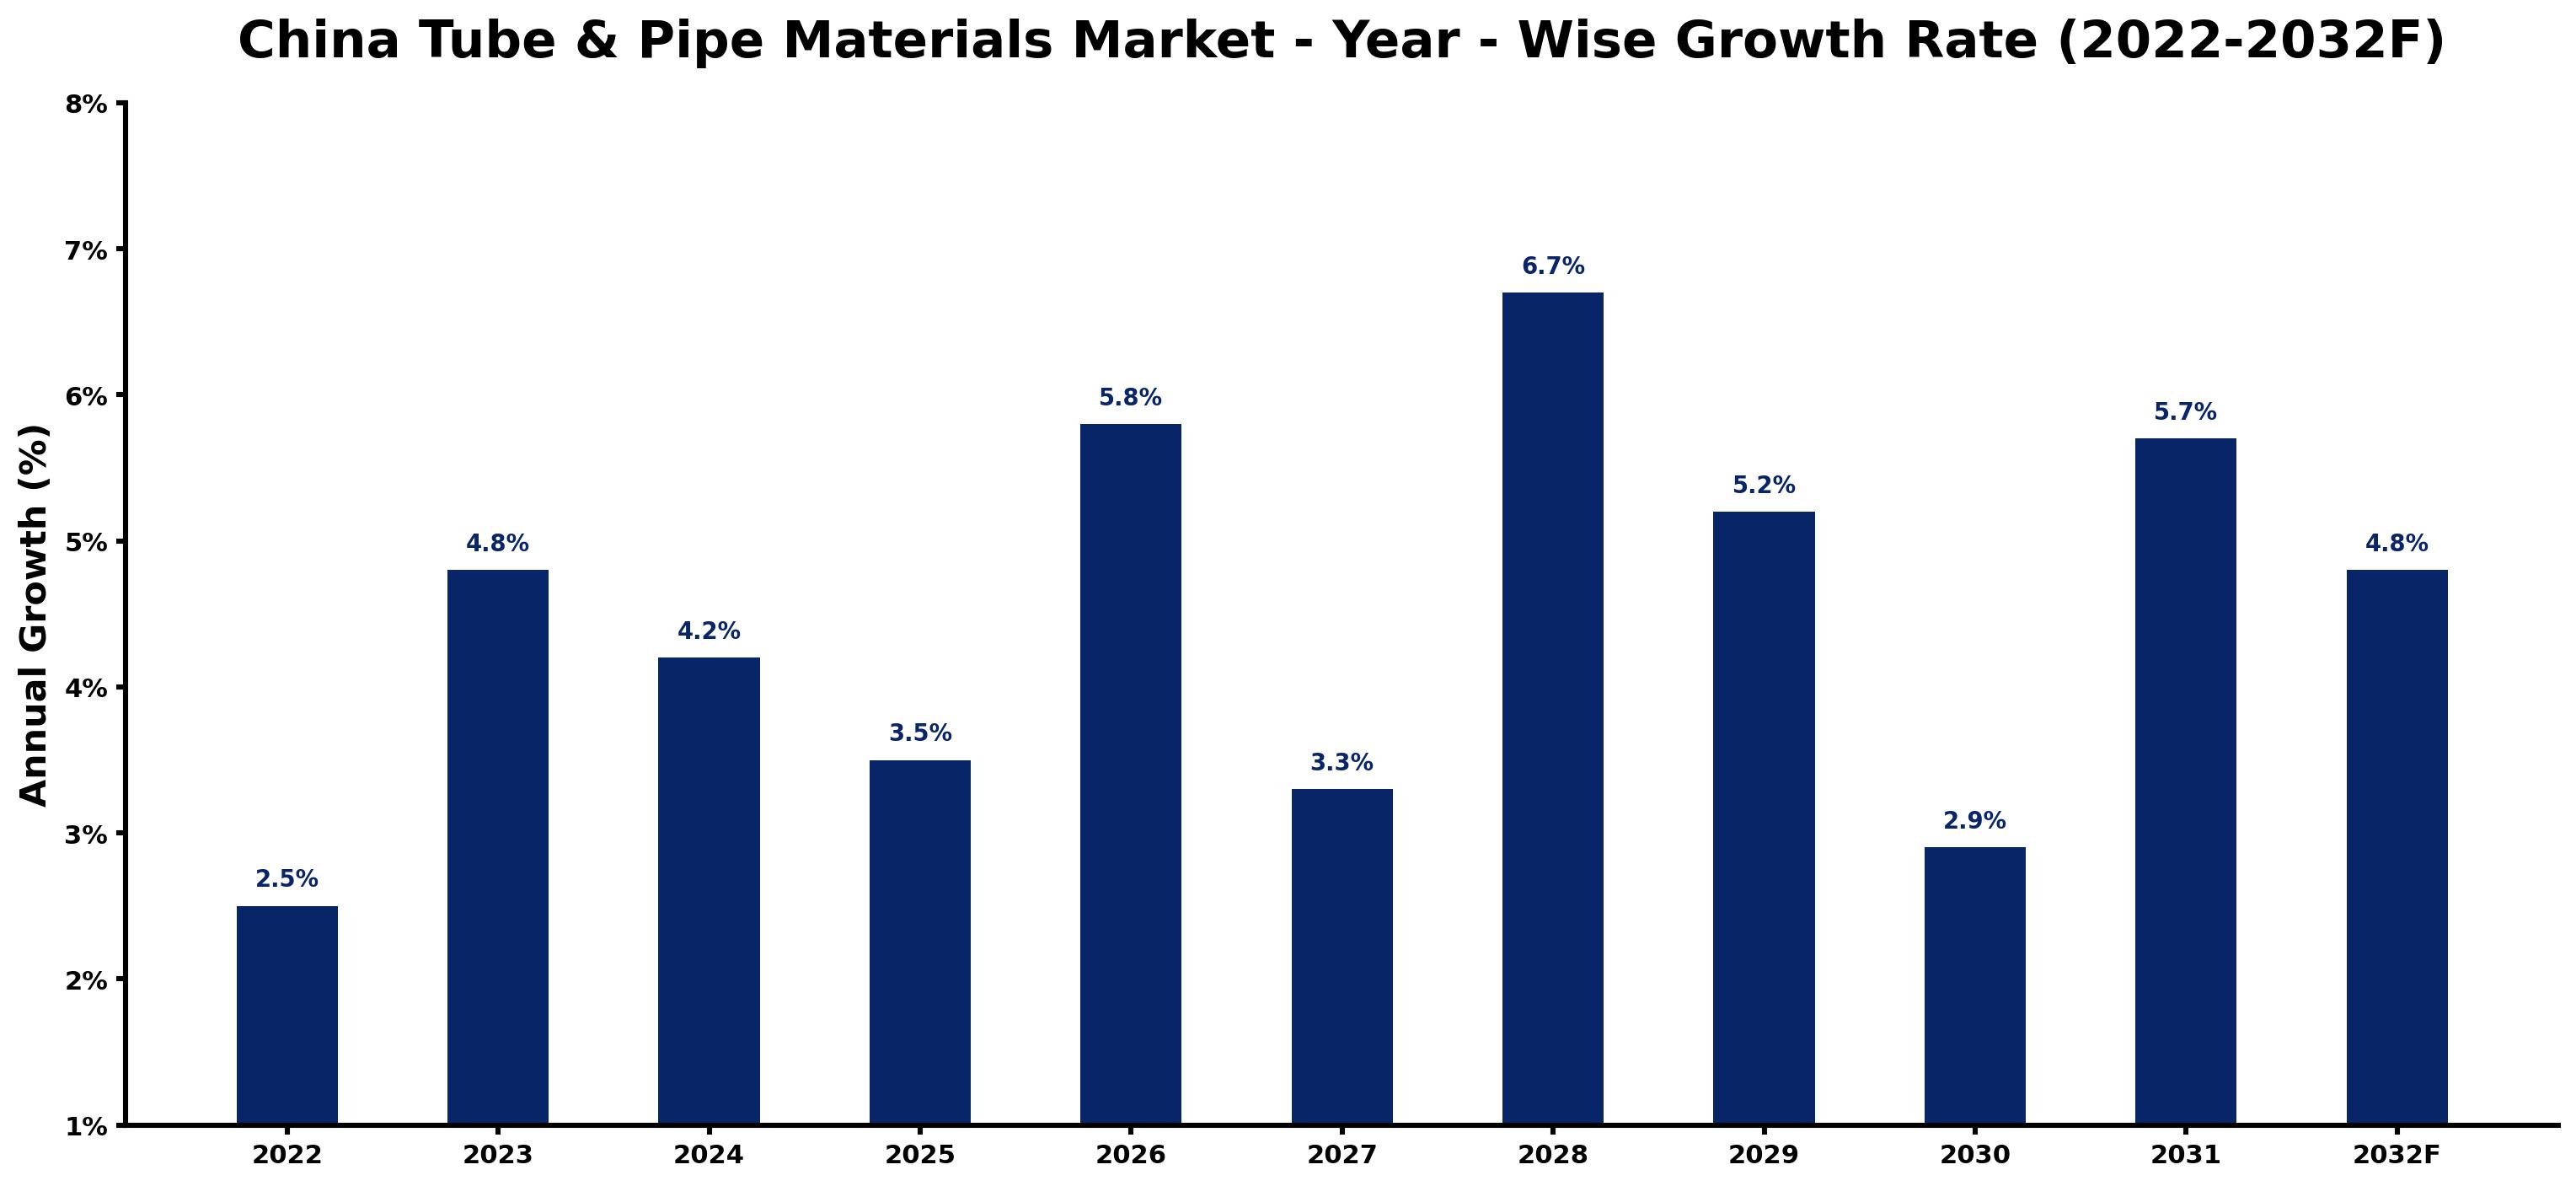
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.5 | The market experienced stable demand from construction firms and industrial manufacturers. |
| 2023 | 4.8 | Demand accelerated due to increased investments in pipeline infrastructure by the oil and gas sector. |
| 2024 | 4.2 | Growth slowed as the construction sector faced project delays and resource constraints. |
| 2025 | 3.5 | A further slowdown occurred as the market adjusted to changing material costs and supply chain issues. |
| 2026 | 5.8 | Demand is expected to rise again as the HVAC market expands with new installations. |
| 2027 | 3.3 | Investment in chemical processing facilities is projected to drive demand for tube materials. |
| 2028 | 6.7 | A surge in investment in chemical processing facilities is anticipated to drive demand. |
| 2029 | 5.2 | Growth is expected to slow as the market adjusts to new environmental regulations and standards. |
| 2030 | 2.9 | The market will continue to grow, albeit at a slower pace due to the 'Air Pollution Prevention and Control Action Plan'. |
| 2031 | 5.7 | A rebound in demand is projected as industrial manufacturers ramp up projects across the country. |
| 2032 | 4.8 | Growth is expected to slow as competition increases among suppliers and the 'Guideline for the Development of the Pipe Industry' takes effect. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Tube & Pipe Materials Market Synopsis
The Tube & Pipe Materials Market in China encompasses various metals used for constructing essential infrastructure. These materials, including carbon steel and stainless steel, are integral for pipelines, HVAC systems, and frameworks. The market is expanding due to rising investments from the oil and gas sector, which is projected to invest $200 billion in pipeline infrastructure by 2025. Additionally, the construction sector is expected to grow at a rate of 5% annually through 2025, further boosting demand. The HVAC market's growth also contributes significantly to the increasing need for these materials.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investments in pipeline infrastructure | Driver | High | Oil & Gas Pipelines |
| Expansion of the HVAC market | Driver | High | HVAC Systems |
| Growing demand for seamless pipes in high-pressure applications | Opportunity | High | Seamless Pipe |
| Rising investments in chemical processing facilities | Opportunity | High | Chemical Processing |
| Fluctuating raw material prices affecting production costs | Restraint | High | Carbon Steel |
| Environmental regulations leading to stricter manufacturing standards | Restraint | High | Stainless Steel |
| Supply chain disruptions impacting timely deliveries | Challenge | High | Welded Tubes |
| Competition from alternative materials in construction | Challenge | Medium | Structural Pipes |
Evaluation of Drivers in China Tube & Pipe Materials Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in pipeline infrastructure | Oil & Gas Pipelines | China's oil and gas industry is projected to invest $200 billion in pipeline infrastructure by 2025, driving demand for tube materials. |
| Expansion of the HVAC market | HVAC Systems | The HVAC market in China reached $80 billion in 2023, increasing the need for tube materials in system installations. |
| Growing demand for seamless pipes in high-pressure applications | Seamless Pipe | Seamless pipes are preferred in high-pressure applications, with a projected market share of 43% in 2025. |
| Rising investments in chemical processing facilities | Chemical Processing | China’s chemical processing industry is projected to reach $1 trillion by 2025, increasing demand for tube materials. |
| Increased construction activities | Construction Firms | Construction firms utilized over 40 million tons of various pipe materials in 2023, indicating strong demand. |
Growth across the Tube & Pipe Materials market in China is anchored in increased investments in pipeline infrastructure, expansion of the HVAC market, and rising construction activities. The oil and gas sector's projected investment of $200 billion by 2025 boosts demand for tube materials. The chemical processing industry's anticipated growth to $1 trillion by 2025 also indicates a strong need for these materials. Construction firms utilized over 40 million tons of various pipe materials in 2023, reflecting significant consumption. The HVAC market is expanding rapidly, further driving the requirement for durable tube solutions.
Evaluation of Restraints in China Tube & Pipe Materials Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices affecting production costs | Carbon Steel | The price volatility of raw materials like steel can lead to increased production costs, impacting profitability. |
| Environmental regulations leading to stricter manufacturing standards | Stainless Steel | Stricter emissions standards from the Air Pollution Prevention and Control Action Plan increase compliance costs for manufacturers. |
| Supply chain disruptions impacting timely deliveries | Welded Tubes | Ongoing supply chain issues can delay deliveries, affecting project timelines for construction firms. |
| Competition from alternative materials in construction | Structural Pipes | The rise of alternative materials can divert demand away from traditional tube materials, impacting market share. |
| Limited applications for aluminum pipes in the automotive sector | Aluminum | Aluminum pipes are primarily used in specialized applications, limiting their overall market potential. |
China Tube & Pipe Materials Market Challenges
The China Tube & Pipe Materials Market faces a few practical problems, and the first is cost. Rising raw material prices have led to a 15% increase in the price of carbon steel pipes over the past year, which directly burdens buyers in the construction sector. Domestic buyers encounter fierce competition from lower-priced imported materials, forcing local producers to reduce profit margins to maintain market share. Insufficient technological advancements in production methods lead to delivery delays for buyers in the oil and gas industry, where timely access to materials is essential, impacting project timelines and costs.
Trends in the China Tube & Pipe Materials Market
Four trends stand out in the China Tube & Pipe Materials Market.
- Shift towards Sustainable Manufacturing: Construction firms are increasingly prioritising sustainable materials, influenced by the 'Made in China 2025' initiative. This shift is reflected in the targeted 20% reduction in energy consumption by 2025, promoting eco-friendly practices.
- Growing Demand for High-Pressure Applications: High-pressure applications are driving demand for durable tube materials. The oil and gas sector's needs are reflected in the projected growth of tube materials, with investments in infrastructure expected to reach $200 billion by 2025.
- Expansion of Chemical Processing Facilities: The chemical processing industry is rapidly expanding, with projected growth reaching $1 trillion by 2025. This growth is driving demand for tube materials, particularly in applications that require safe chemical transport.
- Increasing HVAC System Installations: The HVAC market in China is projected to reach $80 billion in 2023, boosting demand for tube materials. This growth is driven by the increasing installation of HVAC systems across various sectors.
Investment Opportunities in the China Tube & Pipe Materials Market
Below are the investment opportunities with the strongest case in the China Tube & Pipe Materials Market.
- Investment in Oil & Gas Infrastructure: China's oil and gas sector is expected to invest $200 billion in pipeline infrastructure by 2025. Suppliers can enter this market by forming joint ventures with local contractors to provide necessary materials.
- Expansion of Chemical Processing Capabilities: With the chemical processing industry projected to reach $1 trillion by 2025, there is an opportunity to supply tube materials. Collaborating with industrial manufacturers can facilitate market entry.
- Growth in HVAC System Installations: The HVAC market's growth presents an opportunity to supply tube materials for system installations. Partnering with construction firms can enhance market presence and sales.
- Development of Sustainable Tube Materials: The focus on sustainability in manufacturing creates opportunities for eco-friendly tube materials. Engaging with regulatory bodies to meet new standards can open new market avenues.
Government Initiatives in the China Tube & Pipe Materials Market
The Ministry of Industry and Information Technology launched the 'Made in China 2025' initiative in 2020, aiming to improve the quality of steel products, including tube materials, with a focus on innovation and sustainability. This initiative encourages manufacturers to adopt advanced technologies and improve production processes. The National Development and Reform Commission approved the '13th Five-Year Plan for the Development of the Steel Industry' in 2021, targeting a 20% reduction in energy consumption per ton of steel by 2025. This plan promotes energy efficiency and environmental sustainability in steel production, impacting tube material manufacturing. The Ministry of Ecology and Environment introduced the 'Air Pollution Prevention and Control Action Plan' in 2021, mandating stricter emissions standards for steel production, which affects tube material manufacturers and their compliance costs.
The National Development and Reform Commission oversees the implementation of various initiatives, including the 'Guideline for the Development of the Pipe Industry' issued in 2022. This guideline promotes technological advancements and environmental standards in pipe manufacturing. Furthermore, the National Standardization Administration issued GB/T 3091-2020 for welded steel pipes, effective from 2021, ensuring quality and safety in tube production. This standard mandates compliance with safety protocols, impacting manufacturers and ensuring product reliability. The Ministry of Industry and Information Technology also supports funding for projects aimed at improving production efficiency in the steel sector.
Future Insight of the China Tube & Pipe Materials Market
The China Tube & Pipe Materials Market will undergo significant transformations by 2032, primarily driven by advancements in production technology. The 'Made in China 2025' initiative will elevate steel quality standards, enhancing product offerings for buyers in the automotive and construction sectors. By 2025, the oil and gas industry is projected to invest $200 billion in pipeline infrastructure, creating a robust demand for high-quality tube materials. The HVAC market will also grow, presenting suppliers with opportunities to deliver efficient and durable pipe solutions.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Material Type – Carbon Steel Dominated, Stainless Steel Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, in 2025, Carbon Steel led the material type split with a 37% share. Carbon steel dominates the China Tube & Pipe Materials Market due to its widespread use in structural applications, particularly in construction projects. The material's strength and durability make it the preferred choice, as evidenced by the over 40 million tons of various pipe materials utilized by construction firms in 2023. The quickest growth will come from Stainless Steel, forecast to expand at a CAGR of 6.0% between 2026 and 2032. Stainless steel is rapidly gaining traction, primarily due to its increasing demand in corrosive environments, especially in the chemical processing industry. With this sector projected to reach $1 trillion by 2025, the need for stainless steel pipes is expected to rise significantly, further widening the lead of carbon steel. Suppliers should prioritise enhancing their stainless steel offerings to capture the growing market share driven by rising demands in the chemical processing sector.
By Form Type – Seamless Pipe Dominated, Welded Tubes Expected to Grow Fastest
With a 43% revenue share in 2025, Seamless Pipe was the largest form type category. Seamless pipes hold the largest market share as they are preferred for high-pressure applications, making them vital in critical sectors such as oil and gas. Their reliability in demanding environments has established a strong preference among key buyers, ensuring their leading position in the market. Welded Tubes are set to record the highest CAGR in this split, 7.2% over 2026–2032. Welded tubes are witnessing the fastest growth due to their cost-effectiveness and versatility across various applications. As industries focus on optimising expenses, the demand for welded tubes is projected to increase significantly, allowing them to capture a larger share of the market. Buyers should consider the cost advantages of welded tubes, while suppliers must ensure competitive pricing to effectively capture this growing segment.
By Application Area – Oil & Gas Pipelines Dominated, Chemical Processing Expected to Grow Fastest
Oil & Gas Pipelines took a 39% share of application area in 2025, more than any other category. Oil and gas pipelines represent the largest share of the market, as they are critical for energy transportation across China. The projected $200 billion investment in pipeline infrastructure by the oil and gas industry by 2025 underlines the importance of this segment. Chemical Processing is projected to grow fastest, at a CAGR of 6.4% during 2026–2032. The chemical processing sector is the fastest growing application area, driven by the need for safe transportation of chemicals in various industries. This growth is supported by the overall expansion of the chemical processing industry, projected to reach $1 trillion by 2025. Suppliers should align their product offerings with the specific needs of the chemical processing industry to capture emerging opportunities.
By End User – Construction Firms Dominated, Industrial Manufacturers Expected to Grow Fastest
Construction Firms held a 32% share of the China Tube & Pipe Materials Market by end user in 2025. Construction firms lead the market share as they have substantial demand for tube and pipe materials in infrastructure projects. With the construction sector expected to grow at a rate of 5% annually through 2025, this segment remains crucial for suppliers aiming to maintain their market presence. Over 2026–2032, Industrial Manufacturers are expected to post the fastest growth, at a CAGR of 7.3%. Industrial manufacturers are experiencing the fastest growth as they increasingly rely on tube and pipe materials in diverse manufacturing processes. This trend reflects a broader industrial expansion that will continue to drive demand for these materials in the coming years. Suppliers should focus on tailored solutions for industrial manufacturers to leverage the rapid growth in this user segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Tube & Pipe Materials Market Outlook
- Market Size of China Tube & Pipe Materials Market, 2025
- Forecast of China Tube & Pipe Materials Market, 2032
- Historical Data and Forecast of China Tube & Pipe Materials Revenues & Volume for the Period 2022 - 2032F
- China Tube & Pipe Materials Market Trend Evolution
- China Tube & Pipe Materials Market Drivers and Challenges
- China Tube & Pipe Materials Price Trends
- China Tube & Pipe Materials Porter's Five Forces
- China Tube & Pipe Materials Industry Life Cycle
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Carbon Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Stainless Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Copper for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Form Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Seamless Pipe for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Welded Tubes for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Coiled Tubes for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Structural Pipes for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Oil & Gas Pipelines for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Chemical Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By HVAC Systems for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Automotive Frameworks for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Refinery Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Industrial Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Construction Firms for the Period 2022 - 2032F
- Historical Data and Forecast of China Tube & Pipe Materials Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- China Tube & Pipe Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Form Type
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China Tube & Pipe Materials Top Companies Market Share
- China Tube & Pipe Materials Competitive Benchmarking By Technical and Operational Parameters
- China Tube & Pipe Materials Company Profiles
- China Tube & Pipe Materials Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Material Type
- Carbon Steel
- Stainless Steel
- Copper
- Aluminum
By Form Type
- Seamless Pipe
- Welded Tubes
- Coiled Tubes
- Structural Pipes
By Application Area
- Oil & Gas Pipelines
- Chemical Processing
- HVAC Systems
- Automotive Frameworks
By End User
- Refinery Contractors
- Industrial Manufacturers
- Construction Firms
- Vehicle OEMs































