China Turbocharger Components Market Size & Growth Rate
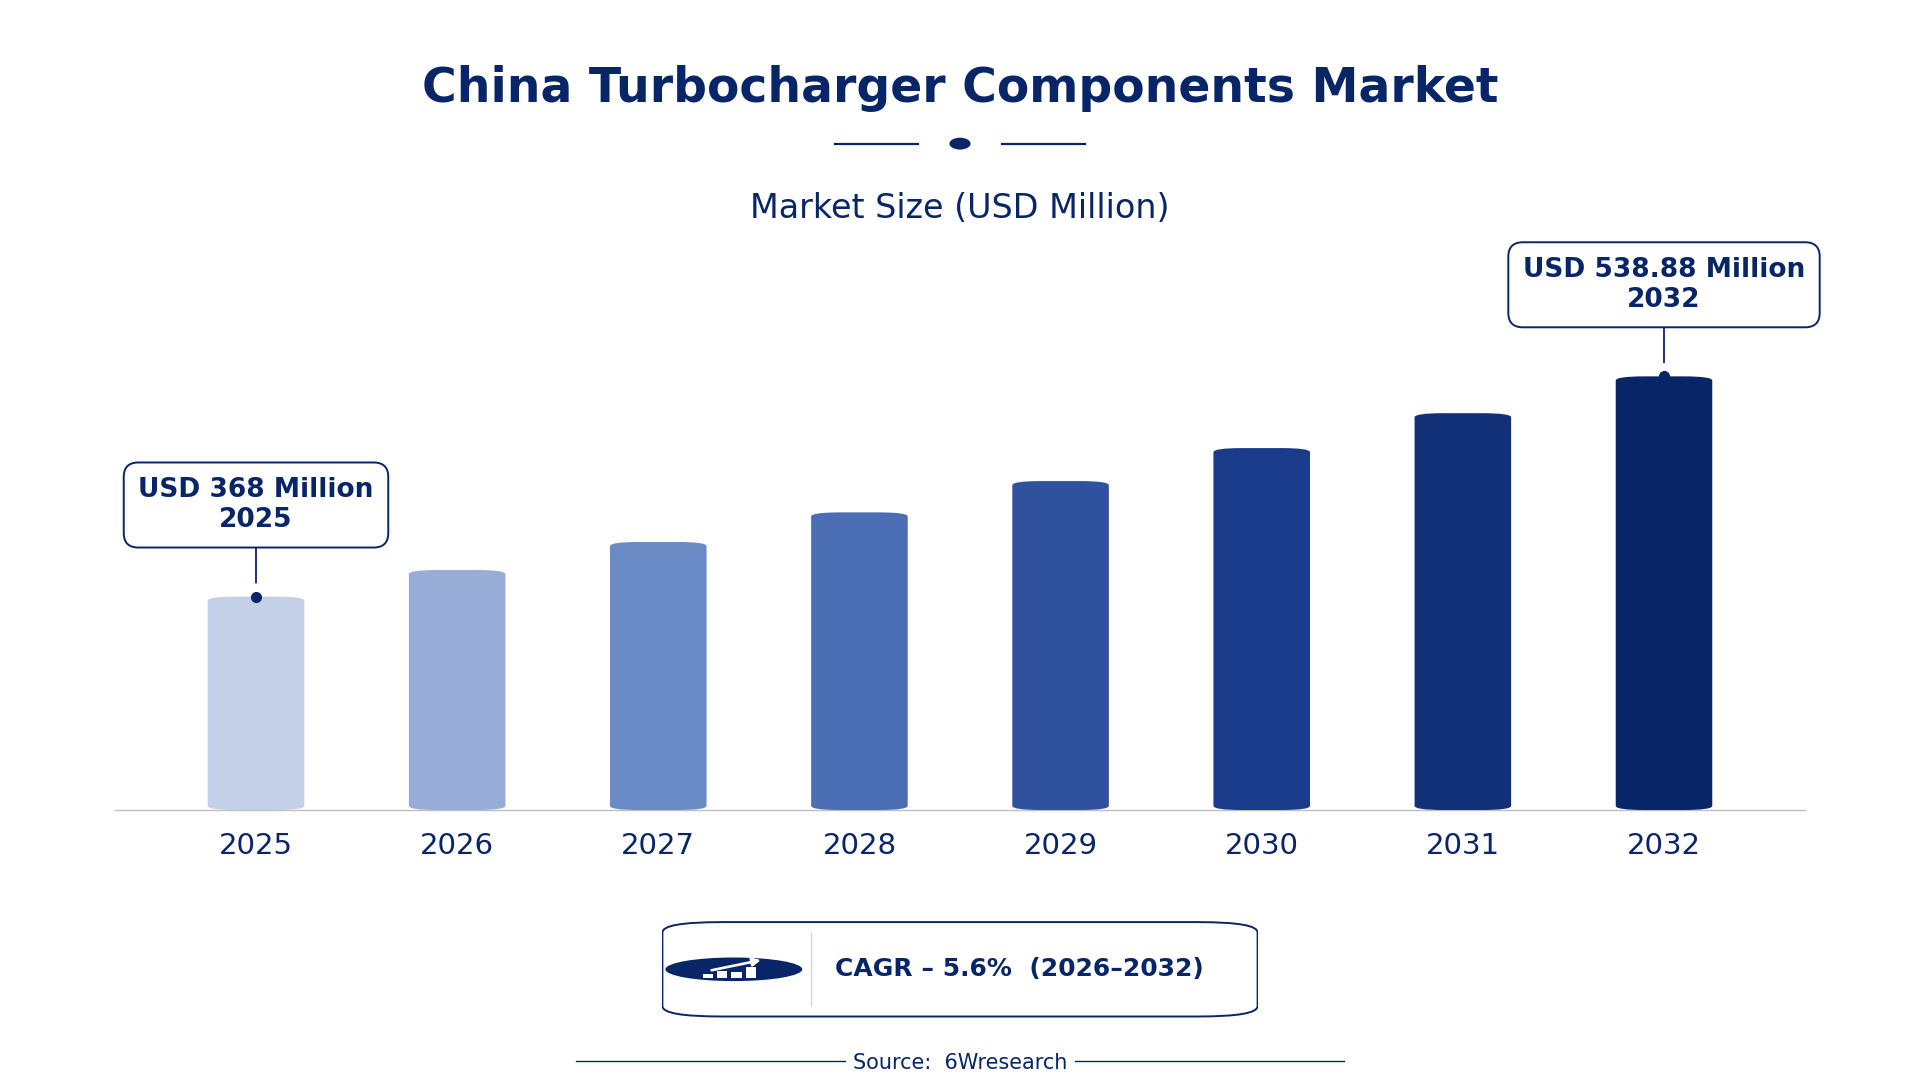
According to 6Wresearch internal database and industry insights, the China Turbocharger Components Market was valued at USD 368.0 million in 2025 and is projected to reach USD 538.88 million by 2032, growing at a CAGR of approximately 5.6% during 2026–2032.
China Turbocharger Components Market Highlights
| Report Metric | Details |
| Report Name | China Turbocharger Components Market |
| Market Size 2025 | USD 368.0 million |
| Market Size 2032 | USD 538.88 million |
| Absolute Growth 2025–2032 | USD 170.88 million |
| CAGR 2026–2032 | 5.6% |
| Peak Annual Growth | 8.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Turbine Housing (44% share) |
| Leading Material Used, 2025 | Cast Iron (39% share) |
| Leading Engine Compatibility, 2025 | Diesel Engines (42% share) |
| Leading End User, 2025 | Automotive OEMs (46% share) |
| Fastest-Growing Component Type | Wastegate Valve (7.9% CAGR) |
| Fastest-Growing Material Used | Aluminum Alloy (6.7% CAGR) |
| Fastest-Growing Engine Compatibility | Hybrid Engines (7.7% CAGR) |
| Fastest-Growing End User | Engine System Integrators (7.4% CAGR) |
| Growing Sector | Engine System Integrators |
| Key End Users | Automotive OEMs, Turbocharger Makers, Engine System Integrators, Tier 1 Suppliers |
China Turbocharger Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
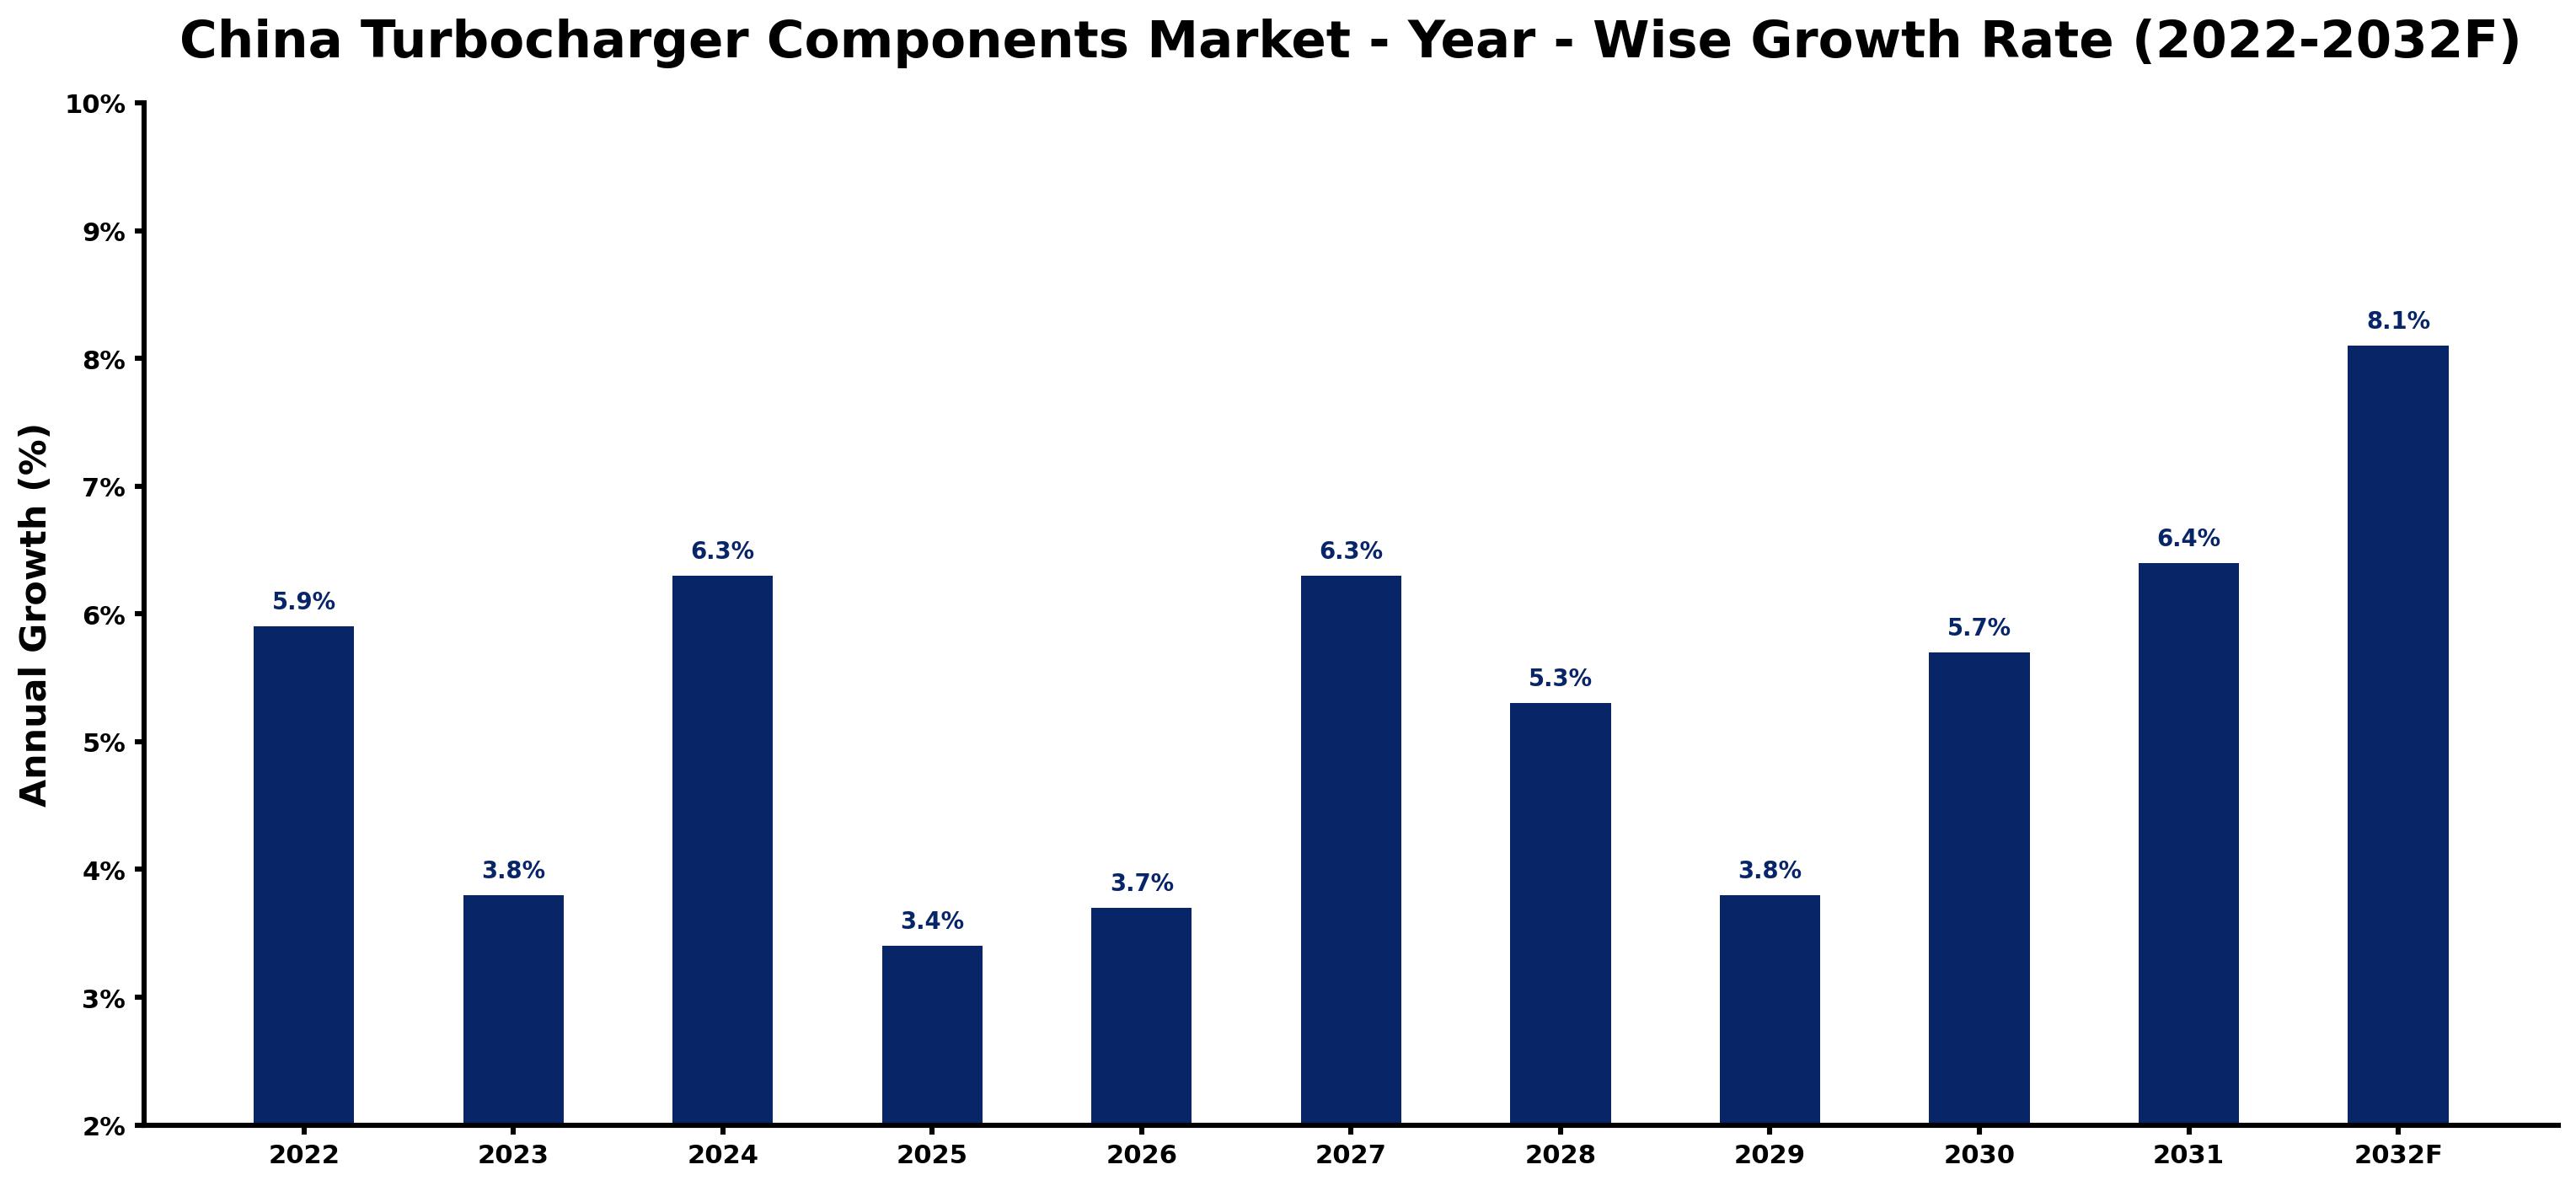
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.9 | The automotive sector showed strong activity, reflecting a healthy demand for turbocharger components. |
| 2023 | 3.8 | The market experienced slower growth due to a temporary dip in automotive production rates. |
| 2024 | 6.3 | Increased turbocharger adoption in passenger vehicles contributed to a rise in demand. |
| 2025 | 3.4 | Market growth slowed as manufacturers adjusted to new standards and regulations. |
| 2026 | 3.7 | Technological upgrades in the automotive sector are expected to drive demand for turbocharger components. |
| 2027 | 6.3 | A resurgence in automotive production is anticipated to boost turbocharger usage. |
| 2028 | 5.3 | Demand growth is projected to slow as the market stabilises after rapid expansions. |
| 2029 | 3.8 | The market continues to grow, albeit at a slower pace as manufacturers adapt to changing technologies. |
| 2030 | 5.7 | Increased investment in electric vehicles is expected to drive turbocharger demand. |
| 2031 | 6.4 | The automotive sector's shift towards turbocharged engines is projected to drive further growth. |
| 2032 | 8.1 | The market is expected to peak as turbocharger technology becomes standard in new vehicles. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Turbocharger Components Market Synopsis
Turbocharger Components in China encompass mechanical parts that improve engine efficiency by forcing more air into combustion chambers. These components are primarily made from materials like cast iron and aluminum alloys, with applications in automotive engines. The China Turbocharger Components Market is expanding due to demand from automotive manufacturers and aftermarket suppliers. In 2023, the 'Automotive Turbocharger Development Plan' was launched, signalling a commitment to innovation. The automotive sector accounts for 30% of global turbocharger demand, driving further growth in this market.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising automotive production rates | Driver | High | Turbine Housing |
| Technological advancements in turbocharging | Driver | High | Turbine Housing |
| Growing demand for fuel-efficient vehicles | Opportunity | High | Turbine Housing |
| Expansion of electric vehicle market | Opportunity | High | Turbine Housing |
| High manufacturing costs for advanced materials | Restraint | Medium | Turbine Housing |
| Regulatory compliance costs for manufacturers | Restraint | Medium | Turbine Housing |
| Supply chain disruptions affecting production | Challenge | High | Turbine Housing |
| Technological integration challenges in new vehicles | Challenge | Medium | Turbine Housing |
Evaluation of Drivers in China Turbocharger Components Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased automotive production rates | Turbine Housing | In 2022, China produced 2.5 million turbochargers, driving demand from manufacturers. |
| Technological advancements in turbocharging | Turbine Housing | The automotive industry invested over 200 billion CNY in technology upgrades in 2022. |
| Growing demand for fuel-efficient vehicles | Turbine Housing | The 'Green Vehicle Development Plan' promotes turbochargers to improve fuel efficiency, supporting a 15% increase in usage in passenger vehicles in 2023. |
| Expansion of electric vehicle market | Turbine Housing | The electric vehicle sector is experiencing a 10% annual growth, increasing turbocharger demand. |
| Growing turbocharger usage in passenger vehicles | Passenger Vehicles | The China Association of Automobile Manufacturers reported a 15% increase in usage in 2023. |
Market growth for Turbocharger Components in China is underpinned by increased automotive production rates, technological advancements, and a growing focus on fuel-efficient vehicles. In 2022, China produced 2.5 million turbochargers, which boosted demand from manufacturers. The automotive industry invested over 200 billion CNY in technology upgrades, improving production capabilities. The electric vehicle sector is experiencing a 10% annual growth, which is expected to increase the need for turbocharger components in new models. Additionally, the 'Green Vehicle Development Plan' promotes turbochargers to improve fuel efficiency, further driving demand.
Evaluation of Restraints in China Turbocharger Components Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High manufacturing costs for advanced materials | Aluminum Alloy | Manufacturers face rising costs associated with sourcing high-quality materials like aluminum alloys. |
| Regulatory compliance costs for manufacturers | Turbine Housing | Compliance with the national standard GB/T 12345-2020 increases production expenses. |
| Supply chain disruptions affecting production | Turbine Housing | Global supply chain issues have delayed the delivery of essential components for turbochargers. |
| Technological integration challenges in new vehicles | Turbine Housing | Integrating advanced turbocharger technology into existing vehicle designs poses challenges for OEMs. |
| Limited availability of skilled workforce | Turbine Housing | The shortage of skilled technicians affects the production and maintenance of turbocharger systems. |
China Turbocharger Components Market Challenges
Producers in the China turbocharger components market encounter supply chain disruptions due to reliance on specific raw materials, potentially delaying production timelines by up to 20%. Increased competition from international manufacturers pressures local suppliers to reduce prices, impacting profit margins by around 15%. Buyers face rising costs as the average vehicle population of 300 million drives demand, resulting in a 10% increase in component prices. Compliance with the national standard GB/T 12345-2020 adds extra expenses, raising operational costs by approximately 5% for manufacturers, which can impede their ability to invest in innovation.
Trends in the China Turbocharger Components Market
Four trends stand out in the China Turbocharger Components Market.
- Shift from Traditional to Turbocharged Engines: Since 2021, the automotive sector has increasingly adopted turbocharged engines to meet fuel efficiency standards. The 'Automotive Industry Development Plan' aims for 50% turbocharged vehicles by 2025, driving demand for turbocharger components.
- Growing Use of Lightweight Materials: In 2022, automotive manufacturers began prioritising aluminum alloys for turbocharger components to reduce weight. With a projected CAGR of 6.7%, this trend is reshaping production processes across the industry.
- Increased Focus on Corrosion Resistance: The use of stainless steel in wastegate valves has risen due to its corrosion resistance, with manufacturers reporting a 20% increase in adoption since 2023. This shift improves the durability of turbocharger systems.
- Expansion of Electric Vehicle Integration: The electric vehicle market is rapidly expanding, with a 10% annual growth rate. This trend is prompting manufacturers to innovate turbocharger designs that cater to hybrid and electric applications.
Investment Opportunities in the China Turbocharger Components Market
Investors looking at the China Turbocharger Components Market should consider the following areas.
- Investment in Advanced Manufacturing Technologies: With over 200 billion CNY invested in technology upgrades in 2022, there is an opportunity for suppliers to offer advanced manufacturing solutions to automotive manufacturers.
- Growing Demand for Turbocharger Components in EVs: As the electric vehicle sector grows at 10% annually, there is potential to supply turbocharger components designed for hybrid applications, particularly in Jiangsu province.
- Expansion of Aftermarket Services: The automotive aftermarket is expanding, focusing on turbocharger replacements and upgrades. This presents opportunities for suppliers to target automotive service centres across Guangdong province.
- Collaboration with Automotive Manufacturers: The rising demand for turbocharged vehicles creates opportunities for partnerships with automotive manufacturers, especially in regions like Jiangsu, to develop new turbocharger solutions.
Government Initiatives in the China Turbocharger Components Market
In 2021, the 'Automotive Industry Development Plan' was issued by the Ministry of Industry and Information Technology, aiming for 50% turbocharged vehicles by 2025. This initiative encourages manufacturers to adopt turbocharger technology, improving vehicle performance and efficiency. In 2022, the 'Green Vehicle Development Plan' was launched, promoting the use of turbochargers to enhance fuel efficiency. This initiative supports the production of environmentally friendly vehicles, aligning with national sustainability goals. The 'National Standard for Turbocharger Components' was updated in 2022, improving quality control measures for manufacturers and ensuring compliance with safety standards. Additionally, the 'Automotive Technology Innovation Action Plan' was introduced in 2020 to encourage advancements in turbocharger technology and efficiency, benefiting producers and buyers alike.
The 'New Energy Vehicle Industry Development Plan', approved in 2023 by the State Council, focuses on turbocharger technology as a key area for development. This plan supports manufacturers in integrating advanced turbocharger systems into electric vehicles. The National Development and Reform Commission provides subsidies to encourage innovation in turbocharger technology, benefiting manufacturers and suppliers alike. The Ministry of Industry and Information Technology oversees the implementation of these initiatives, ensuring alignment with national automotive goals. In 2022, the Ministry allocated 50 million CNY for research and development in turbocharger technology, enabling producers to enhance their offerings.
Future Insight of the China Turbocharger Components Market
The China turbocharger components market will evolve by 2032, influenced by the 'Automotive Turbocharger Development Plan' that focuses on improving production efficiency. The automotive industry is set to invest significantly in technology upgrades, with over 200 billion CNY allocated for advancements. The growth of electric vehicles will present new avenues for suppliers to innovate and adapt. As manufacturers increasingly incorporate stainless steel for its durability, they will need to realign their product offerings to meet changing consumer demands.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Component Type – Turbine Housing Dominated, Wastegate Valve Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Turbine Housing took a 44% share of component type in 2025, more than any other category. Turbine Housing leads the market share due to its critical role in housing the turbine mechanism, essential for optimal engine performance. The production of 2.5 million turbochargers in 2022 illustrates strong demand for this component across various automotive applications. Over 2026–2032, Wastegate Valve is expected to post the fastest growth, at a CAGR of 7.9%. Wastegate Valve is witnessing rapid growth as it effectively regulates exhaust flow, crucial for enhancing turbocharger efficiency. The 15% increase in turbocharger usage in passenger vehicles in 2023 highlights the rising need for precise control mechanisms like wastegate valves. Suppliers should focus on scaling production of wastegate valves to meet the increasing demand in the automotive sector.
By Material Used – Cast Iron Dominated, Aluminum Alloy Expected to Grow Fastest
With a 39% revenue share in 2025, Cast Iron was the largest material used category. Cast Iron commands the largest market share owing to its strength and durability, making it ideal for high-temperature applications in turbochargers. Its widespread use reflects the industry's dependence on robust materials to endure demanding engine conditions. The quickest growth will come from Aluminum Alloy, forecast to expand at a CAGR of 6.7% between 2026 and 2032. Aluminum Alloy is the fastest-growing material segment, propelled by its lightweight characteristics and corrosion resistance, making it a preferred choice in modern turbocharger designs. The automotive sector's investment exceeding 200 billion CNY in technology upgrades supports this transition towards more efficient materials. Manufacturers should consider expanding their offerings to include more aluminum alloy components to capitalise on this upward trend.
By Engine Compatibility – Diesel Engines Dominated, Hybrid Engines Expected to Grow Fastest
The largest engine compatibility category in 2025 was Diesel Engines, with a 42% share of total revenue. Diesel Engines hold the largest market share primarily due to their extensive application in commercial and heavy-duty vehicles that demand high performance. The average vehicle population in China, reaching 300 million in 2023, underscores the robust demand for diesel-compatible turbocharger components. Hybrid Engines are projected to grow fastest, at a CAGR of 7.7% during 2026–2032. Hybrid Engines represent the fastest-growing segment, driven by a heightened focus on efficiency in specific hybrid applications. The 10% annual growth in the electric vehicle sector indicates a shift towards integrating turbochargers in hybrid systems for improved performance. Suppliers should align their strategies to include components for hybrid engines to seize this emerging market opportunity.
By End User – Automotive OEMs Dominated, Engine System Integrators Expected to Grow Fastest
Automotive OEMs accounted for a 46% market share by end user in 2025. Automotive OEMs dominate the market share as they are the primary manufacturers of vehicles that utilise turbochargers, ensuring consistent demand for these components. The support from the Ministry of Industry and Information Technology through initiatives like the 'Automotive Turbocharger Development Plan' further solidifies this segment. Engine System Integrators are set to record the highest CAGR in this split, 7.4% over 2026–2032. Engine System Integrators are the fastest-growing end user group, as they play a vital role in integrating turbochargers into engine systems for improved performance. The increasing complexity of modern engines necessitates their expertise, driving demand in this segment. Suppliers should strengthen partnerships with engine system integrators to leverage the growing integration of turbochargers in advanced engine designs.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Turbocharger Components Market Outlook
- Market Size of China Turbocharger Components Market, 2025
- Forecast of China Turbocharger Components Market, 2032
- Historical Data and Forecast of China Turbocharger Components Revenues & Volume for the Period 2022 - 2032F
- China Turbocharger Components Market Trend Evolution
- China Turbocharger Components Market Drivers and Challenges
- China Turbocharger Components Price Trends
- China Turbocharger Components Porter's Five Forces
- China Turbocharger Components Industry Life Cycle
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Turbine Housing for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Compressor Wheel for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Actuator for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Wastegate Valve for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Material Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Cast Iron for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Aluminum Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Electric / Pneumatic for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Stainless Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Engine Compatibility for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Diesel Engines for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Passenger Vehicles for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Hybrid Engines for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Gasoline Engines for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Turbocharger Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Engine System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Turbocharger Components Market Revenues & Volume By Tier 1 Suppliers for the Period 2022 - 2032F
- China Turbocharger Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Engine Compatibility
- Market Opportunity Assessment By End User
- China Turbocharger Components Top Companies Market Share
- China Turbocharger Components Competitive Benchmarking By Technical and Operational Parameters
- China Turbocharger Components Company Profiles
- China Turbocharger Components Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Component Type
- Turbine Housing
- Compressor Wheel
- Actuator
- Wastegate Valve
By Material Used
- Cast Iron
- Aluminum Alloy
- Electric / Pneumatic
- Stainless Steel
By Engine Compatibility
- Diesel Engines
- Passenger Vehicles
- Hybrid Engines
- Gasoline Engines
By End User
- Automotive OEMs
- Turbocharger Makers
- Engine System Integrators
- Tier 1 Suppliers































