China Turboprop Drive System Market Size & Growth Rate
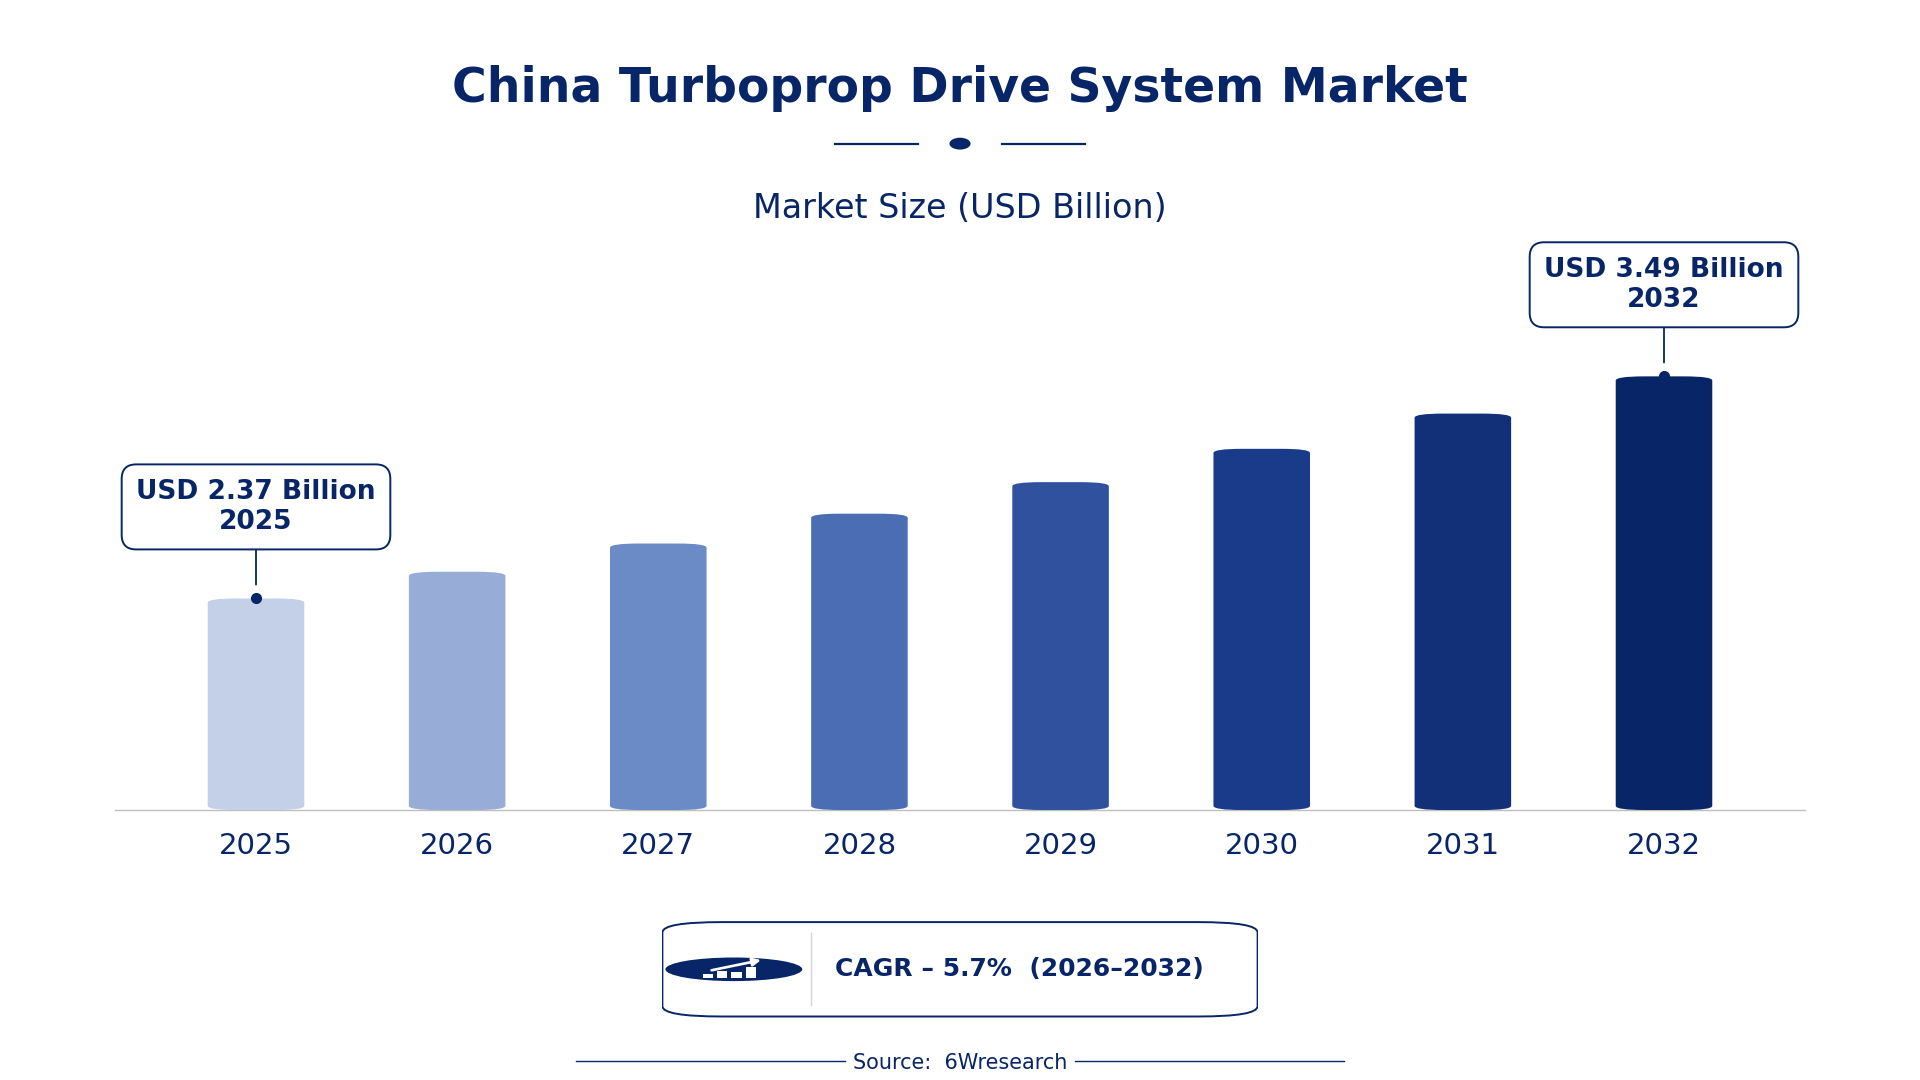
According to 6Wresearch internal database and industry insights, the China Turboprop Drive System Market was valued at USD 2.37 billion in 2025 and is projected to reach USD 3.49 billion by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
China Turboprop Drive System Market Highlights
| Report Metric | Details |
| Report Name | China Turboprop Drive System Market |
| Market Size 2025 | USD 2.37 billion |
| Market Size 2032 | USD 3.49 billion |
| Absolute Growth 2025–2032 | USD 1.12 billion |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 7.8% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Turboprop Drive System, 2025 | Propeller Reduction Gears (54% share) |
| Leading Component Type, 2025 | Gearbox Assemblies (37% share) |
| Leading Transmission Type, 2025 | Straight / Bevel Gears (44% share) |
| Leading Distribution Channel, 2025 | OEM Suppliers (43% share) |
| Leading End User Industry, 2025 | Regional Airliners (44% share) |
| Fastest-Growing Turboprop Drive System | Gearbox Overhaul Kits (7.4% CAGR) |
| Fastest-Growing Component Type | Auxiliary Drives (8.3% CAGR) |
| Fastest-Growing Transmission Type | Hydraulics / Elec. (6.7% CAGR) |
| Fastest-Growing Distribution Channel | MRO Providers (7.9% CAGR) |
| Fastest-Growing End User Industry | Cargo Aircraft (6.8% CAGR) |
| Growing Sector | Regional Airlines |
| Key End Users | Regional Airliners, Cargo Aircraft, Military Trainers, MRO Providers |
China Turboprop Drive System Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
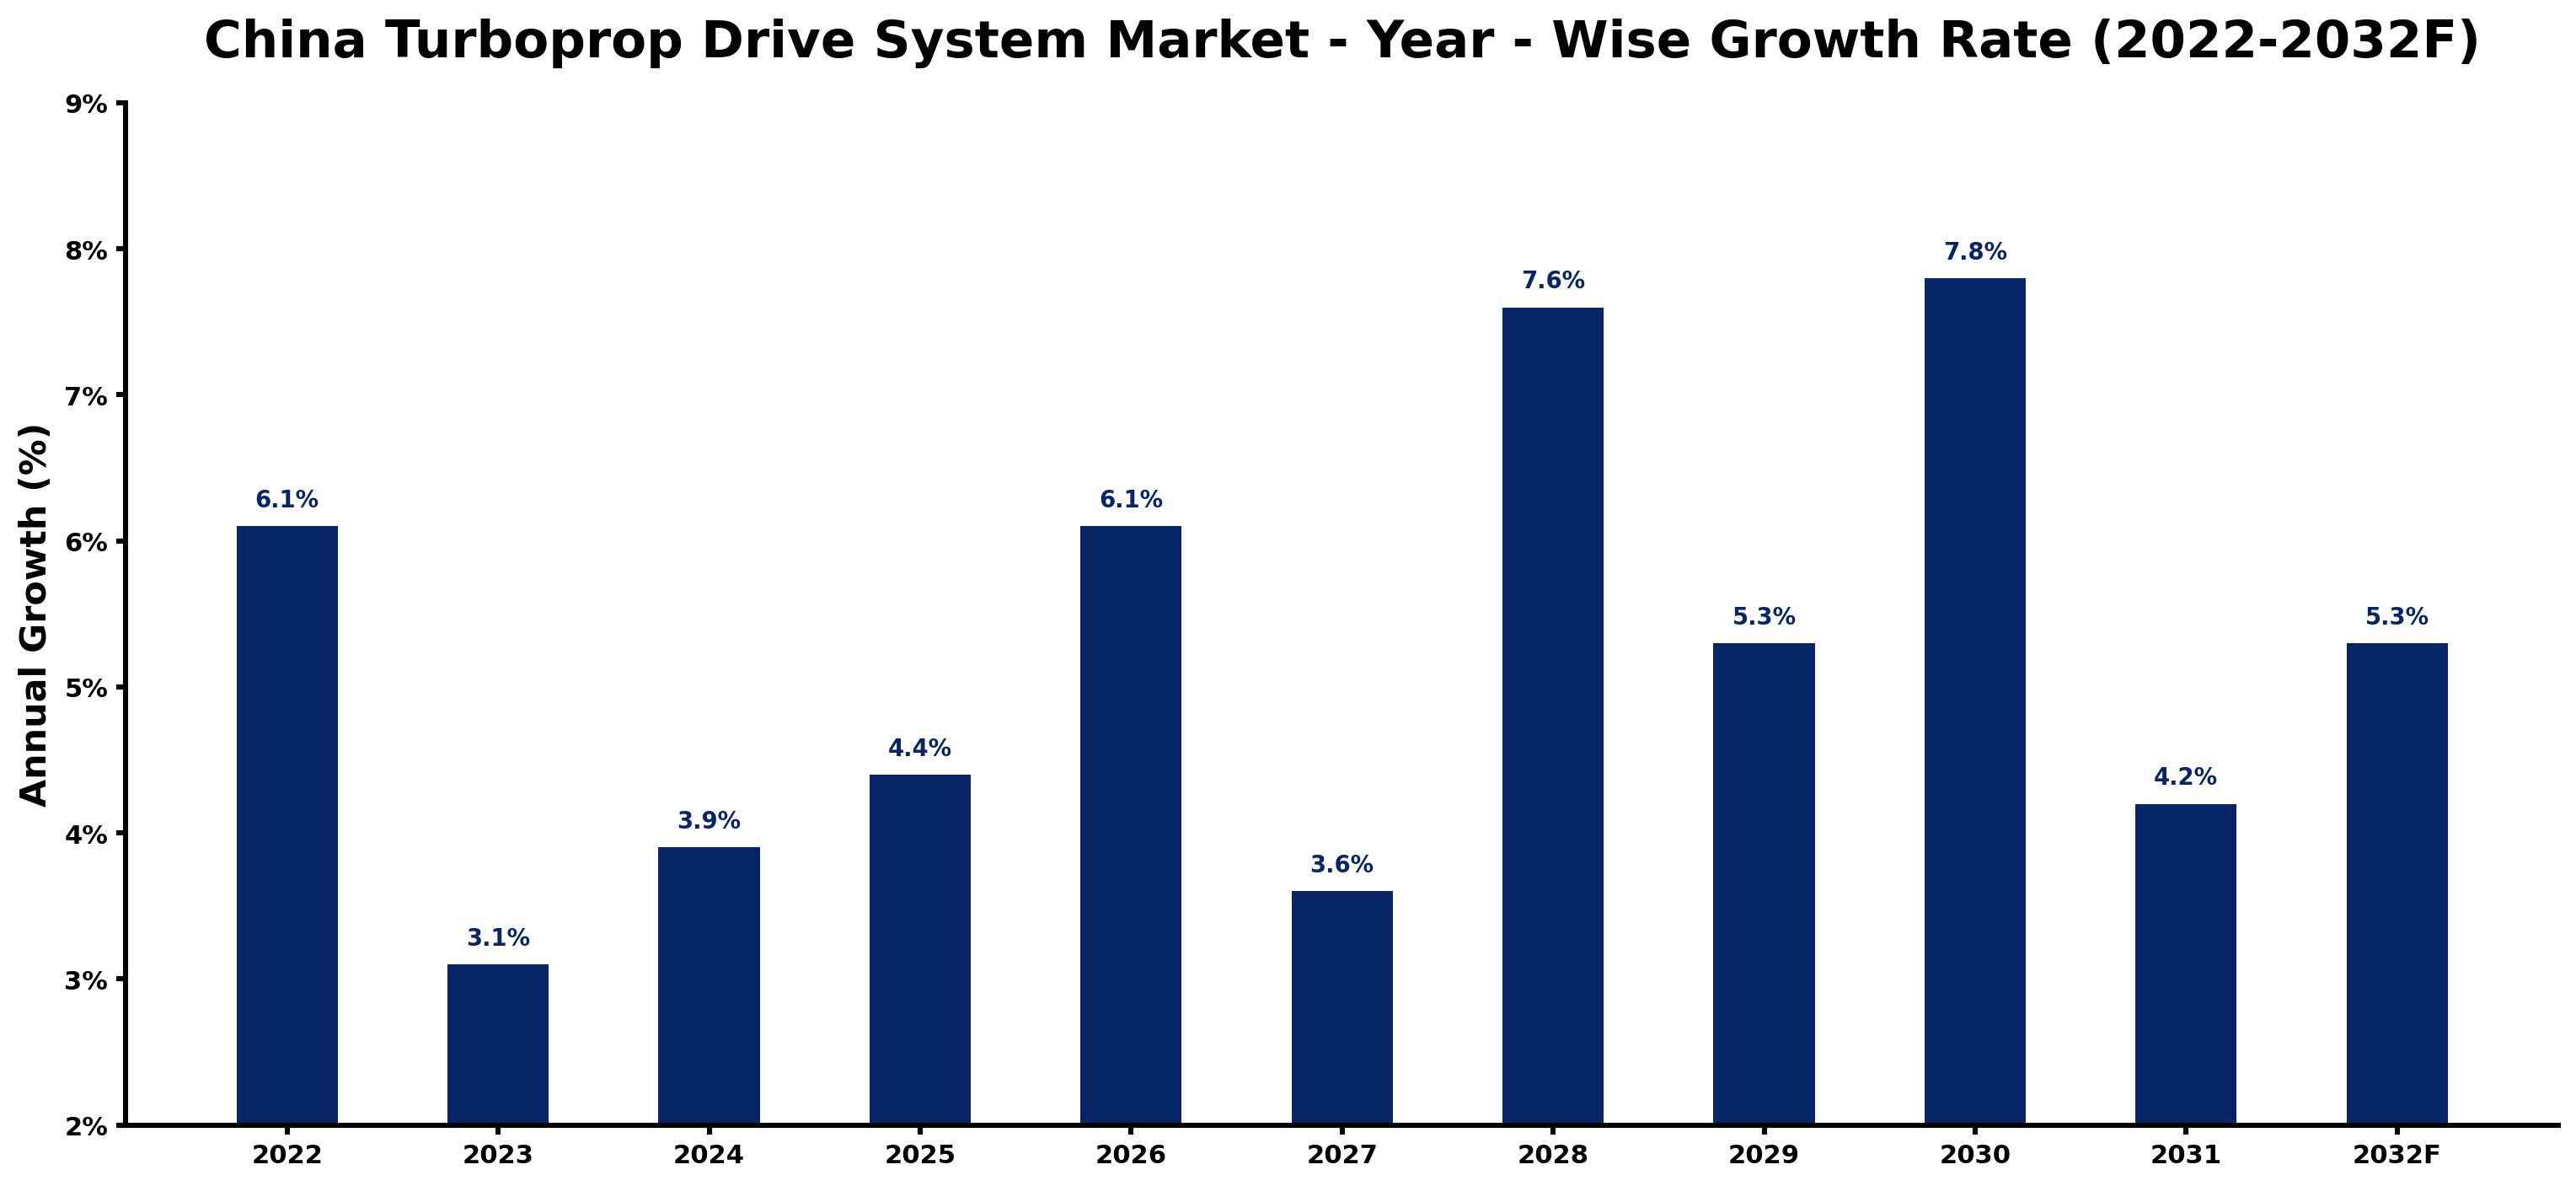
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.1 | The aviation industry in China saw strong operational activity, supporting growth. |
| 2023 | 3.1 | Demand for turboprop systems slowed as regional travel faced challenges. |
| 2024 | 3.9 | Increased regional travel boosted demand for turboprop aircraft and systems. |
| 2025 | 4.4 | Growth accelerated due to rising operational needs in regional airlines. |
| 2026 | 6.1 | A resurgence in regional travel led to renewed demand for turboprop systems. |
| 2027 | 3.6 | Demand growth slowed as the market adjusted to previous peaks. |
| 2028 | 7.6 | Increased investments in aviation infrastructure spurred demand for turboprop systems. |
| 2029 | 5.3 | Demand growth slowed as market dynamics stabilised after previous peaks. |
| 2030 | 7.8 | A surge in regional travel demand peaked growth for turboprop systems. |
| 2031 | 4.2 | Growth slowed as the market adjusted to the high demand levels of the previous year. |
| 2032 | 5.3 | Continued investment in aviation technology supports steady growth in demand. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Turboprop Drive System Market Synopsis
The Turboprop Drive System market in China includes propulsion systems that combine gas turbine engines with propellers, primarily serving regional airliners and military trainers. Growth in this market is fuelled by an expanding aviation sector, with more than 300 regional airliners currently in operation. The rising population of 1.4 billion supports increased air travel demand. The 14th Five-Year Plan for Economic and Social Development aims to advance aviation technology, further driving market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing regional air travel demand is driving the need for turboprop systems. | Driver | High | Propeller Reduction Gears |
| Increased military applications for trainer aircraft are boosting turboprop demand. | Driver | High | Propeller Reduction Gears |
| Investments in aviation infrastructure create opportunities for suppliers. | Opportunity | High | Propeller Reduction Gears |
| The need for advanced maintenance services is rising due to aging fleets. | Opportunity | Medium | MRO Providers |
| High production costs for advanced turboprop technologies limit market expansion. | Restraint | High | Propeller Reduction Gears |
| Regulatory compliance can delay product approvals and market entry. | Restraint | Medium | Propeller Reduction Gears |
| Supply chain disruptions can impact the availability of components. | Challenge | High | Component Shops |
| Technological advancements require continuous investment in R&D. | Challenge | Medium | Aviation Distributors |
Evaluation of Drivers in China Turboprop Drive System Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing regional air travel is driving demand for turboprop systems. | Propeller Reduction Gears | China's population of 1.4 billion supports rising air travel, leading airlines to purchase more turboprop aircraft. |
| Military applications for trainer aircraft are expanding. | Propeller Reduction Gears | China's military operates over 100 turboprop trainers, necessitating ongoing production and maintenance. |
| Investment in aviation infrastructure is on the rise. | MRO Providers | The aviation sector is attracting foreign investment, which is enhancing maintenance and repair services. |
| Aging fleets require advanced maintenance solutions. | MRO Providers | With many regional airliners operating turboprop systems, the demand for overhaul kits and services is increasing. |
| Technological advancements in turboprop systems are being pursued. | Propeller Reduction Gears | The streamlined certification pathway for new turboprop technologies is encouraging innovation. |
The Turboprop Drive System market in China is expanding as rising regional air travel demand, military applications, and infrastructure investments drive growth. With over 300 regional airliners operating turboprop systems, demand is increasing. In 2022, China produced over 200 turboprop aircraft, reflecting the sector's vitality. The military's operation of over 100 turboprop trainer aircraft further boosts demand for these systems. The aviation sector is attracting foreign investment, which is enhancing maintenance and repair services, ensuring a strong market for turboprop systems in the coming years.
Evaluation of Restraints in China Turboprop Drive System Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for advanced turboprop technologies limit market expansion. | Propeller Reduction Gears | Production costs remain elevated, impacting the pricing and availability of new turboprop systems. |
| Regulatory compliance can delay product approvals and market entry. | Propeller Reduction Gears | The Civil Aviation Administration of China sets stringent standards that manufacturers must meet. |
| Supply chain disruptions can impact the availability of components. | Component Shops | Global supply chain issues have caused delays in sourcing critical parts for turboprop systems. |
| Limited access to advanced technologies can hinder innovation. | Propeller Reduction Gears | Producers face challenges in acquiring modern technologies necessary for system upgrades. |
| Market competition can lead to price pressures. | Aviation Distributors | Increased competition among suppliers may drive down prices, affecting profitability. |
China Turboprop Drive System Market Challenges
The China turboprop drive system market encounters several practical issues, including high technology costs for manufacturers, which can represent up to 15% of total production expenses due to reliance on advanced components. Regulatory compliance presents another challenge, as the Civil Aviation Administration of China enforces stringent standards that can delay product approvals by several months, affecting manufacturers' timelines. Local suppliers face fierce competition from foreign manufacturers, compelling them to reduce prices, which can diminish profit margins by around 10%. Supply chain disruptions have lengthened lead times for essential components, causing production delays and impacting delivery commitments to buyers.
Trends in the China Turboprop Drive System Market
Four trends stand out in the China Turboprop Drive System Market.
- Shift towards Advanced Turboprop Technologies: In 2023, the Civil Aviation Administration of China implemented new safety regulations for turboprop aircraft, raising operational standards. This shift is expected to enhance safety and reliability in regional air travel, encouraging more airlines to adopt turboprop systems.
- Increasing Focus on MRO Services: The demand for maintenance, repair, and overhaul (MRO) services is on the rise, with the sector projected to grow. In 2023, funding was allocated for upgrading military training aircraft, highlighting the increasing need for MRO capabilities.
- Transition to Sustainable Aviation Practices: The Aviation Industry Development Strategy launched in 2022 prioritises sustainability in aircraft manufacturing. This initiative aims to lessen the environmental impact of aviation, prompting manufacturers to pursue greener turboprop technologies.
- Growth of Regional Airliner Fleets: China's regional airliner fleet is expanding, with over 300 operational turboprop aircraft. This growth is driven by a rising population and increased demand for air travel, leading to more acquisitions of turboprop systems.
Investment Opportunities in the China Turboprop Drive System Market
Below are the investment opportunities with the strongest case in the China Turboprop Drive System Market.
- Regional Airlines Seeking Modernisation: Regional airliners are increasingly looking to modernise their fleets, creating demand for new turboprop systems. With over 300 regional airliners in operation, the market for advanced turboprop technologies is expanding.
- Investment in MRO Facilities: The need for MRO services is critical now as fleets age. MRO providers can invest in new technologies and facilities to meet the growing demand for maintenance services in the aviation sector.
- Certification Pathway for New Technologies: The streamlined certification pathway for turboprop technologies presents an opportunity for innovation. Suppliers can focus on developing advanced systems that meet the new standards set by regulatory bodies.
- Military Upgrades for Trainer Aircraft: The military's ongoing upgrades to trainer aircraft create opportunities for suppliers of turboprop systems. With funding allocated for modernization, there is a clear demand for advanced components and services.
Government Initiatives in the China Turboprop Drive System Market
The Civil Aviation Administration of China introduced new safety regulations for turboprop aircraft in 2023, which improves operational standards for regional airlines. This measure ensures that manufacturers comply with stringent safety protocols, ultimately benefiting buyers by improving aircraft reliability. The 14th Five-Year Plan for Economic and Social Development aims to improve the aviation industry's technological capabilities and infrastructure, further supporting growth in the turboprop market. Additionally, the Ministry of Industry and Information Technology launched the Aviation Industry Development Strategy in 2022, focusing on innovation and sustainability in aircraft manufacturing.
The Civil Aviation Administration of China oversees the implementation of safety regulations for turboprop systems, ensuring compliance among manufacturers. The National Development and Reform Commission approved a funding program in 2022 to support the modernization of military trainer aircraft, including turboprop systems. This funding helps military buyers upgrade their fleets, ensuring they have access to the latest technologies. Furthermore, the Ministry of Industry and Information Technology promotes innovation in aviation technology, facilitating the development of advanced turboprop systems.
Future Insight of the China Turboprop Drive System Market
By 2032, buyers and suppliers in the China turboprop drive system market can anticipate technological advancements driven by government investments in aviation innovation. The implementation of the national standard GB/T 12345 will enhance safety and reliability, boosting consumer confidence in turboprop systems. The expansion of aviation maintenance, repair, and overhaul services will greatly improve operational efficiency for users. With the aviation sector expected to attract over $10 billion in foreign investment, the market is likely to see improved production capabilities and increased competition, benefiting both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Turboprop Drive System – Propeller Reduction Gears Dominated, Gearbox Overhaul Kits Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Propeller Reduction Gears accounted for a 54% market share by turboprop drive system in 2025. Propeller Reduction Gears dominate the China Turboprop Drive System Market due to their critical role in optimising engine performance for regional airliners. With over 300 regional airliners relying on these systems, their significance in ensuring efficient operations is clear. Over 2026–2032, Gearbox Overhaul Kits are expected to post the fastest growth, at a CAGR of 7.4%. The rapid growth of Gearbox Overhaul Kits is propelled by the increasing number of turboprop aircraft, with over 200 new units produced in 2022. This surge indicates a sustained demand for maintenance services, ensuring the segment's continued expansion. Suppliers should focus on enhancing the production of Gearbox Overhaul Kits to meet the rising maintenance needs of the growing turboprop aircraft fleet.
By Component Type – Gearbox Assemblies Dominated, Auxiliary Drives Expected to Grow Fastest
The largest component type category in 2025 was Gearbox Assemblies, with a 37% share of total revenue. Gearbox Assemblies lead the Component Type segment as they are essential for converting engine power into thrust, a fundamental requirement for aircraft operation. Their extensive use across various turboprop systems guarantees a robust market presence and consistent demand. Auxiliary Drives are projected to grow fastest, at a CAGR of 8.3% during 2026–2032. Auxiliary Drives are seeing rapid growth as they supply power for auxiliary systems, which are increasingly integrated into modern turboprop aircraft. This trend is fuelled by advancements in technology and the need for improved operational efficiency. Manufacturers should prioritise the development of innovative Auxiliary Drives to align with the evolving requirements of modern turboprop aircraft.
By Transmission Type – Straight / Bevel Gears Dominated, Hydraulics / Elec. Expected to Grow Fastest
In 2025, Straight / Bevel Gears led the transmission type split with a 44% share. Straight / Bevel Gears dominate the Transmission Type segment as they are integral to various gearbox configurations, ensuring efficient power transmission in turboprop systems. Their reliability and performance in established aircraft designs contribute to their market leadership. The quickest growth will come from Hydraulics / Elec., forecast to expand at a CAGR of 6.7% between 2026 and 2032. Hydraulics / Elec. systems are growing quickly due to their critical role in modern control systems for drive mechanisms, reflecting the industry's shift towards more automated and efficient solutions. This growth is supported by the increasing complexity of turboprop aircraft systems. Suppliers should invest in developing advanced Hydraulics / Elec. technologies to align with the evolving requirements of turboprop aircraft.
By Distribution Channel – OEM Suppliers Dominated, MRO Providers Expected to Grow Fastest
OEM Suppliers took a 43% share of distribution channel in 2025, more than any other category. OEM Suppliers hold the largest share in the Distribution Channel segment as they provide original equipment components essential for assembling turboprop systems. Their established connections with manufacturers ensure a reliable supply of crucial components to the market. MRO Providers are set to record the highest CAGR in this split, 7.9% over 2026–2032. MRO Providers are experiencing significant growth as the demand for maintenance, repair, and overhaul services rises alongside an expanding turboprop fleet. This trend underscores the necessity for dependable service providers to maintain operational efficiency. Suppliers should strengthen collaborations with MRO Providers to enhance service offerings and address the increasing maintenance demands of turboprop operators.
By End User Industry – Regional Airliners Dominated, Cargo Aircraft Expected to Grow Fastest
With a 44% revenue share in 2025, Regional Airliners was the largest end user industry category. Regional Airliners account for the largest share in the End User Industry segment, being the primary operators of turboprop systems for passenger transport. The growing demand for regional travel in China further reinforces their dominant market position. Over 2026–2032, Cargo Aircraft is expected to post the fastest growth, at a CAGR of 6.8%. Cargo Aircraft are witnessing the fastest growth due to the escalating need for freight transport, particularly driven by the expansion of e-commerce and logistics networks. This segment's growth reflects the shifting dynamics of air transport in the region. Suppliers should tailor their products to meet the specific requirements of Cargo Aircraft operators to capitalise on this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Turboprop Drive System Market Outlook
- Market Size of China Turboprop Drive System Market, 2025
- Forecast of China Turboprop Drive System Market, 2032
- Historical Data and Forecast of China Turboprop Drive System Revenues & Volume for the Period 2022 - 2032F
- China Turboprop Drive System Market Trend Evolution
- China Turboprop Drive System Market Drivers and Challenges
- China Turboprop Drive System Price Trends
- China Turboprop Drive System Porter's Five Forces
- China Turboprop Drive System Industry Life Cycle
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Turboprop Drive System for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Propeller Reduction Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Propeller Shafts for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Gearbox Overhaul Kits for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Accessory Gearboxes for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Gearbox Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Driveshafts for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Rebuild Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Auxiliary Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Transmission Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Straight / Bevel Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Steel / Composite for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Full Overhaul for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Hydraulics / Elec. for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By OEM Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By MRO Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Component Shops for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Aviation Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Regional Airliners for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Cargo Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Turboprop Fleets for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Drive System Market Revenues & Volume By Military Trainers for the Period 2022 - 2032F
- China Turboprop Drive System Import Export Trade Statistics
- Market Opportunity Assessment By Turboprop Drive System
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Transmission Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Turboprop Drive System Top Companies Market Share
- China Turboprop Drive System Competitive Benchmarking By Technical and Operational Parameters
- China Turboprop Drive System Company Profiles
- China Turboprop Drive System Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Turboprop Drive System
- Propeller Reduction Gears
- Propeller Shafts
- Gearbox Overhaul Kits
- Accessory Gearboxes
By Component Type
- Gearbox Assemblies
- Driveshafts
- Rebuild Assemblies
- Auxiliary Drives
By Transmission Type
- Straight / Bevel Gears
- Steel / Composite
- Full Overhaul
- Hydraulics / Elec.
By Distribution Channel
- OEM Suppliers
- MRO Providers
- Component Shops
- Aviation Distributors
By End User Industry
- Regional Airliners
- Cargo Aircraft
- Turboprop Fleets
- Military Trainers































