China Turboprop Reduction Gearbox Market Size & Growth Rate
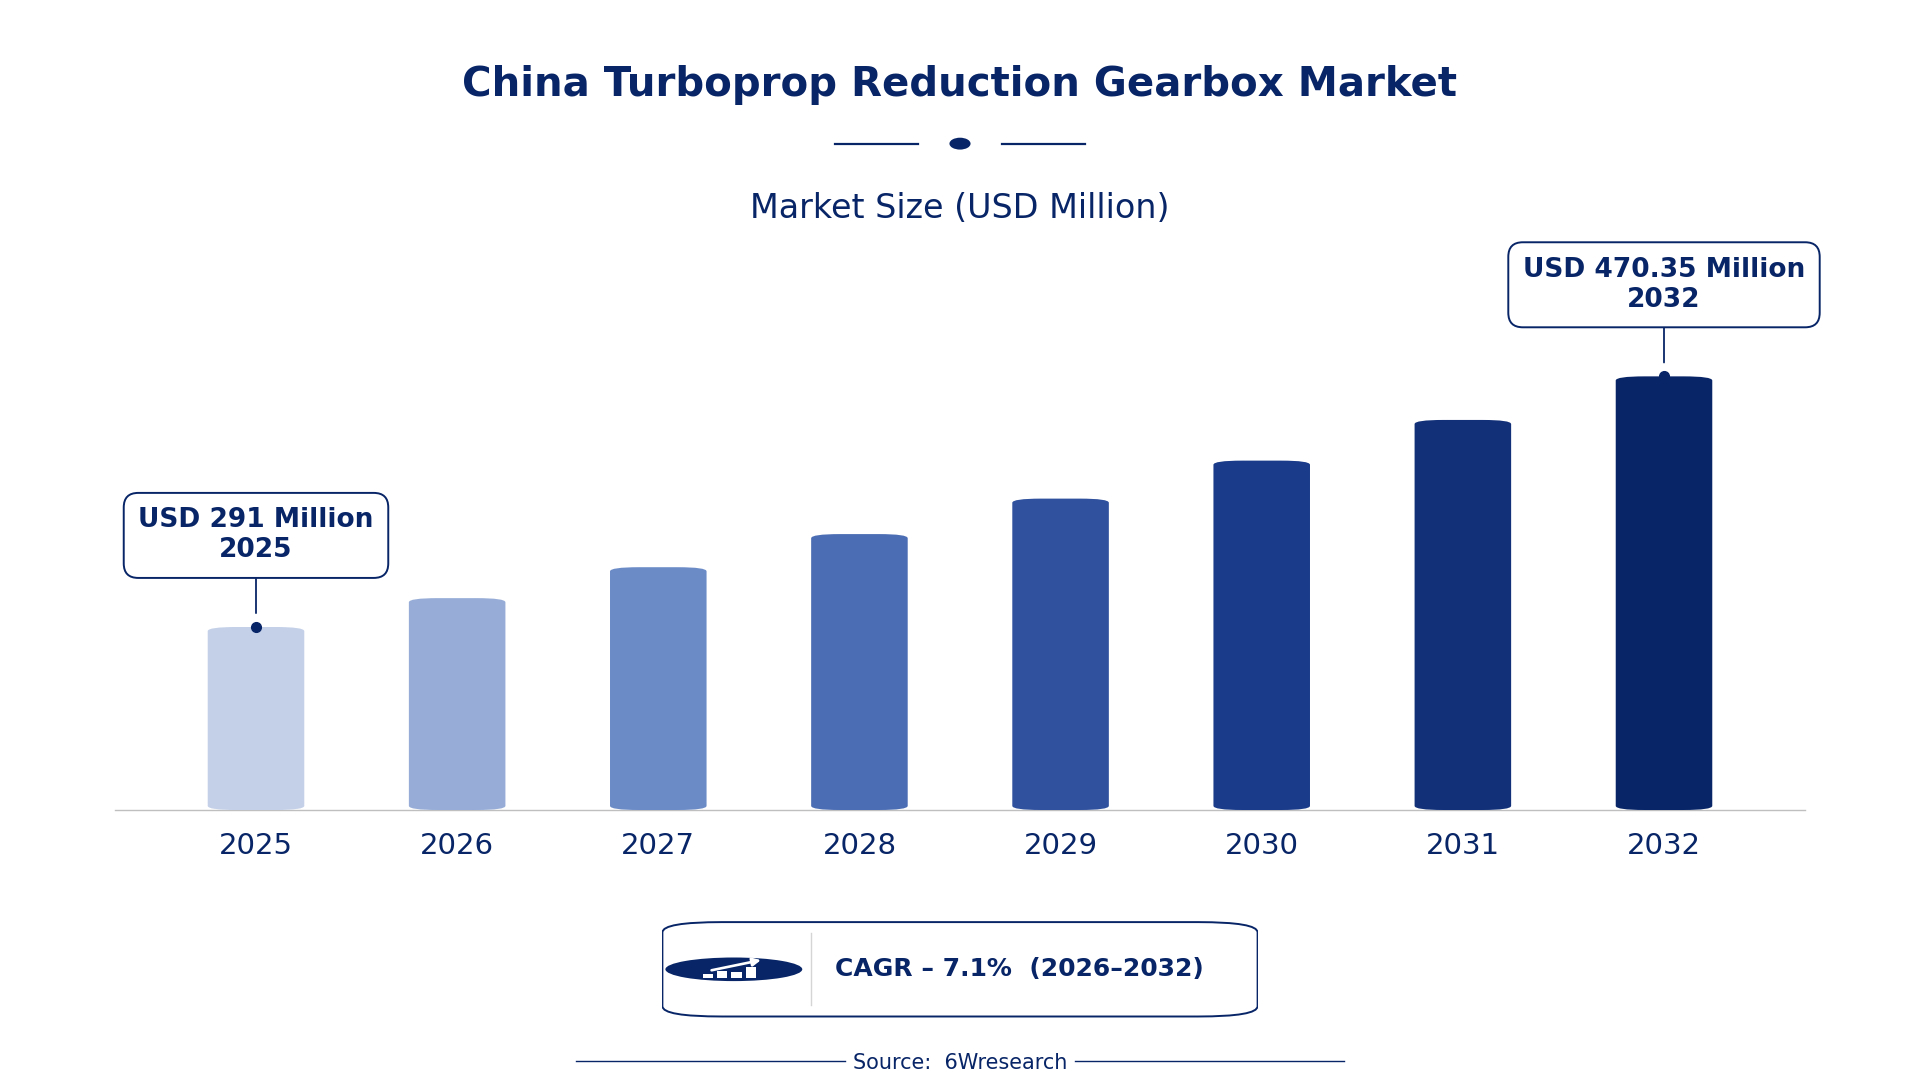
According to 6Wresearch internal database and industry insights, the China Turboprop Reduction Gearbox Market was valued at USD 291.0 million in 2025 and is projected to reach USD 470.35 million by 2032, growing at a CAGR of approximately 7.1% during 2026–2032.
China Turboprop Reduction Gearbox Market Highlights
| Report Metric | Details |
| Report Name | China Turboprop Reduction Gearbox Market |
| Market Size 2025 | USD 291.0 million |
| Market Size 2032 | USD 470.35 million |
| Absolute Growth 2025–2032 | USD 179.35 million |
| CAGR 2026–2032 | 7.1% |
| Peak Annual Growth | 9.0% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Turboprop Reduction Gearbox, 2025 | Conventional Gearboxes (43% share) |
| Leading Gearbox Type, 2025 | Straight Bevel (51% share) |
| Leading Gear Design, 2025 | Steel Gears (37% share) |
| Leading Distribution Channel, 2025 | OEM Engine Suppliers (46% share) |
| Leading End User Industry, 2025 | Regional Carriers (42% share) |
| Fastest-Growing Turboprop Reduction Gearbox | Composite Gearboxes (8.6% CAGR) |
| Fastest-Growing Gearbox Type | Hybrid Gears (8.5% CAGR) |
| Fastest-Growing Gear Design | Steel/Composite (9.2% CAGR) |
| Fastest-Growing Distribution Channel | MRO Providers (9.7% CAGR) |
| Fastest-Growing End User Industry | Military Training (8.8% CAGR) |
| Growing Sector | Military Training |
| Key End Users | Regional Carriers, Military Training, Charter Operators |
China Turboprop Reduction Gearbox Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
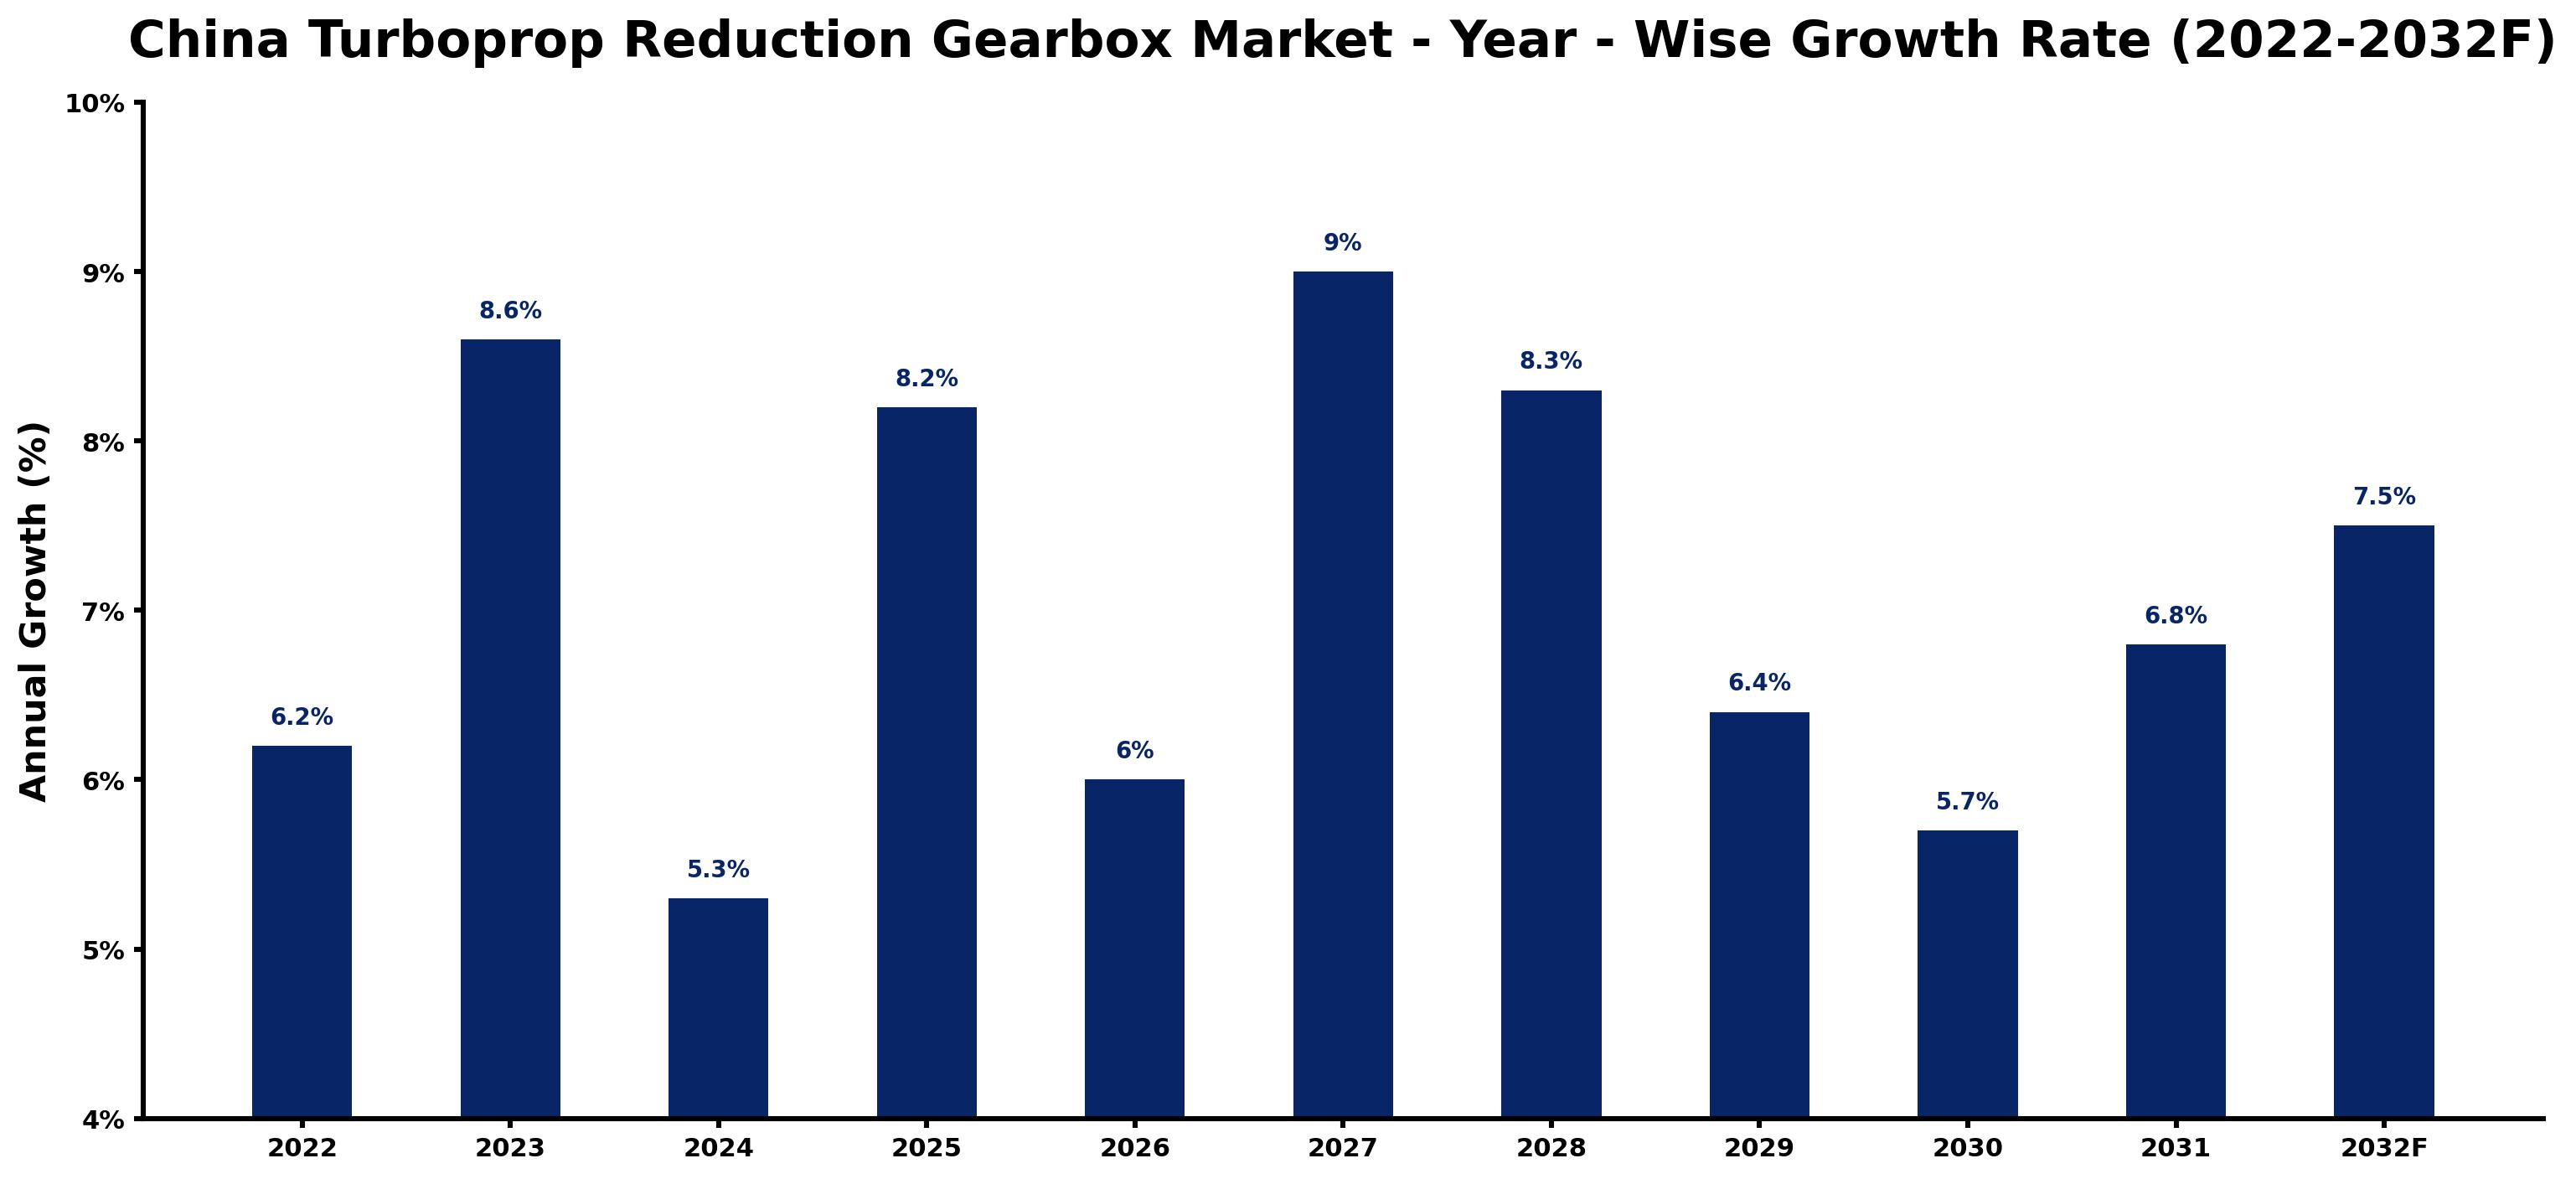
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.2 | The market experienced solid demand due to existing turboprop aircraft operations. |
| 2023 | 8.6 | Growth accelerated as military training programs expanded their use of turboprop aircraft. |
| 2024 | 5.3 | A slowdown occurred as new aircraft deliveries were delayed by supply chain issues. |
| 2025 | 8.2 | Demand increased as regional carriers expanded their fleets to meet rising passenger numbers. |
| 2026 | 6.0 | Growth is expected to slow due to a temporary reduction in military training budgets. |
| 2027 | 9.0 | A peak in growth is projected as the military adopts more turboprop aircraft for training. |
| 2028 | 8.3 | Growth is anticipated to slow again as the market adjusts to previous high levels of demand. |
| 2029 | 6.4 | The market is expected to continue growing, albeit at a slower pace, driven by regional airline expansion. |
| 2030 | 5.7 | Growth is projected to moderate as the average age of turboprop aircraft increases, necessitating maintenance. |
| 2031 | 6.8 | A rebound in growth is expected as regional carriers invest in fleet modernisation. |
| 2032 | 7.5 | The market is projected to grow as the government targets a 30% increase in regional air traffic. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Turboprop Reduction Gearbox Market Synopsis
The Turboprop Reduction Gearbox Market in China encompasses devices that reduce engine speed for propeller operation in aircraft. These gearboxes are made from high-strength steel and composite materials, primarily used in regional aircraft and military training planes. The market is expected to grow due to rising demand from regional carriers and military applications, supported by government initiatives such as the Aerospace Industry Development Plan launched in 2021, which aims to improve domestic production capabilities.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand from regional carriers for new turboprop aircraft leads to higher gearbox orders. | Driver | High | Conventional Gearboxes |
| Military training programs expanding their fleet of turboprop aircraft boosts gearbox demand. | Driver | High | Military Training |
| The shift towards composite gearboxes for weight-sensitive aircraft creates new supply opportunities. | Opportunity | High | Composite Gearboxes |
| Investment in regional aviation infrastructure is increasing, creating demand for new gearboxes. | Opportunity | High | OEM Engine Suppliers |
| High maintenance costs of older turboprop gearboxes can limit replacement purchases. | Restraint | Medium | Overhauled Assemblies |
| Supply chain disruptions have delayed new gearbox deliveries, affecting market growth. | Restraint | Medium | Conventional Gearboxes |
| Buyers face challenges in sourcing high-quality components for gearbox production. | Challenge | High | MRO Providers |
| Competition from international suppliers can hinder local manufacturers' market share. | Challenge | High | OEM Engine Suppliers |
Evaluation of Drivers in China Turboprop Reduction Gearbox Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising fleet expansion among regional carriers drives demand for new gearboxes. | Conventional Gearboxes | With over 200 regional carriers operating turboprop aircraft, demand for gearboxes is increasing significantly. |
| Military training programs are expanding their use of turboprop aircraft. | Military Training | The military training sector's budget for aviation was approximately $1 billion in 2023, boosting gearbox demand. |
| Investment in regional aviation infrastructure supports the growth of turboprop aircraft. | OEM Engine Suppliers | The National Development and Reform Commission announced a 20% increase in investment for regional aviation infrastructure. |
| The average lifespan of turboprop gearboxes necessitates regular replacements and overhauls. | Overhauled Assemblies | The average lifespan of a turboprop gearbox is around 5,000 flight hours, leading to consistent demand for replacements. |
| Adoption of composite gearboxes is increasing due to weight reduction requirements. | Composite Gearboxes | Composite gearboxes are increasingly adopted for weight-sensitive applications in modern aircraft designs, enhancing performance. |
Expansion of the Turboprop Reduction Gearbox market in China is backed by rising fleet expansion among regional carriers, which operate over 200 turboprop aircraft. The military training sector's budget for aviation reached approximately $1 billion in 2023, driving demand for gearboxes. Investment in regional aviation infrastructure supports the growth of turboprop aircraft, with a 20% increase announced in 2023. The average lifespan of turboprop gearboxes necessitates regular replacements and overhauls, as they typically last around 5,000 flight hours. The increasing adoption of composite gearboxes for weight-sensitive applications in modern aircraft designs further boosts demand.
Evaluation of Restraints in China Turboprop Reduction Gearbox Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High maintenance costs of older turboprop gearboxes limit replacement purchases. | Overhauled Assemblies | The average age of turboprop aircraft in China is around 15 years, leading to higher maintenance costs. |
| Supply chain disruptions have delayed new gearbox deliveries, affecting market growth. | Conventional Gearboxes | Recent global supply chain issues have impacted the timely delivery of components, delaying production schedules. |
| Limited availability of high-quality components can hinder gearbox production. | MRO Providers | Manufacturers often struggle to source reliable parts for gearbox assembly, affecting production timelines. |
| Competition from international suppliers can hinder local manufacturers' market share. | OEM Engine Suppliers | Local manufacturers face challenges in competing with established international brands, limiting their market penetration. |
| Regulatory compliance costs can increase operational expenses for producers. | Composite Gearboxes | Compliance with ISO 9001 standards raises production costs for manufacturers, impacting pricing strategies. |
China Turboprop Reduction Gearbox Market Challenges
Buyers and suppliers in the China turboprop reduction gearbox market encounter fierce competition that pressures profit margins and compels price reductions. This competition arises from over 200 regional carriers operating turboprop aircraft, increasing the supply of gearboxes and diminishing manufacturers' pricing power. Supply chain disruptions continue due to reliance on high-strength steel and composite materials, resulting in production delays that can cost producers up to 20% in lost revenue. Skills shortages in precision machining complicate the situation, as the average lifespan of a turboprop gearbox is around 5,000 flight hours, leading to maintenance delays for buyers that could extend service downtime by weeks.
Trends in the China Turboprop Reduction Gearbox Market
Several trends are reshaping the China Turboprop Reduction Gearbox Market; the most important are set out below.
- Shift towards Composite Gearboxes: The adoption of composite gearboxes is rising among military training programmes, improving aircraft performance while reducing weight. In 2022, composite gearboxes accounted for a notable share of new turboprop aircraft designs.
- Growing Investment in Regional Aviation Infrastructure: Investment in regional aviation infrastructure is increasing, with a 20% rise announced in 2023. This funding supports the expansion of regional carriers and boosts demand for turboprop gearboxes.
- Expansion of Military Training Programs: Military training programmes are increasingly incorporating turboprop aircraft, improving pilot training efficiency. The annual budget for military aviation training reached approximately $1 billion in 2023.
- Increased Focus on Gearbox Overhauls: The market is seeing a growing emphasis on overhauling existing turboprop gearboxes to extend their lifespan. With an average lifespan of around 5,000 flight hours, refurbishment is becoming crucial.
Investment Opportunities in the China Turboprop Reduction Gearbox Market
Several openings in the China Turboprop Reduction Gearbox Market merit attention from investors.
- Investment in Composite Gearbox Production: The demand for composite gearboxes is on the rise, with a projected growth of 8.6% from 2026 to 2032. Investing in production capabilities can attract regional carriers seeking weight-sensitive solutions.
- Expansion of MRO Services in Shanghai: The Shanghai region serves as a hub for turboprop aircraft maintenance and repair services. With over 200 regional carriers operating, there is a significant opportunity for MRO providers to expand their services.
- Partnerships with Military Training Programs: Collaborating with military training programmes can boost gearbox sales, as they increasingly adopt turboprop aircraft. Establishing partnerships with military agencies can facilitate market entry.
- Growing Demand for Overhauled Assemblies: The need for overhauled assemblies is rising, with many aircraft nearing the end of their operational lifespan. Investing in refurbishment services can meet the demand from military and regional operators.
Government Initiatives in the China Turboprop Reduction Gearbox Market
The Civil Aviation Administration of China updated the 'Regulations on the Airworthiness of Aircraft' in 2022, introducing new standards for turboprop aircraft. This regulation ensures that all turboprop gearboxes meet stringent safety and performance criteria, benefiting both manufacturers and operators by improving reliability and safety in operations. Compliance with these regulations is essential for producers and can lead to increased market confidence among buyers.
The Ministry of Industry and Information Technology oversees the implementation of the 'Aerospace Industry Development Plan' launched in 2021, which aims to enhance domestic production capabilities for aerospace components. This plan allocates substantial funding to support innovation and improve manufacturing standards, directly benefiting producers of turboprop gearboxes. Additionally, the National Key R&D Program initiated in 2020 aims to boost innovation in aerospace technologies with a budget allocation of $500 million over five years.
Future Insight of the China Turboprop Reduction Gearbox Market
The China turboprop reduction gearbox market will undergo notable changes by 2032, driven by the 'Aerospace Industry Development Plan' aimed at enhancing local manufacturing capabilities. Military training programmes will expand, increasing the demand for turboprop aircraft and contributing to a rise in the installed base of approximately 1,500 units. Advancements in research and development in the Beijing-Tianjin-Hebei region will refine gearbox technology, boosting efficiency and performance. The 'Made in China 2025' initiative will support the creation of advanced materials, allowing suppliers to better address the aviation sector's specific requirements.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Turboprop Reduction Gearbox – Conventional Gearboxes Dominated, Composite Gearboxes Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, the largest turboprop reduction gearbox category in 2025 was Conventional Gearboxes, with a 43% share of total revenue. Conventional gearboxes dominate the market due to their proven reliability and performance in regional aircraft, which are essential for China's extensive short-haul travel network. With over 200 regional carriers operating turboprop aircraft, this segment's established presence solidifies its leading market share. The quickest growth will come from Composite Gearboxes, forecast to expand at a CAGR of 8.6% between 2026 and 2032. The rise of composite gearboxes is attributed to the industry's shift towards lightweight materials that enhance fuel efficiency in modern aircraft designs. As the aviation sector increasingly prioritises cost reduction, the demand for these advanced gearboxes is expected to grow significantly. Suppliers should prioritise the development of lightweight composite gearboxes to align with the increasing demand in the turboprop market.
By Gearbox Type – Straight Bevel Dominated, Hybrid Gears Expected to Grow Fastest
Straight Bevel held a 51% share of the China Turboprop Reduction Gearbox Market by gearbox type in 2025. Straight bevel gears are prevalent in turboprop applications due to their efficiency and compatibility with various aircraft designs. Their established use across multiple platforms contributes to their leading market share in China. Over 2026–2032, Hybrid Gears are expected to post the fastest growth, at a CAGR of 8.5%. Hybrid gears are gaining traction in niche applications that require unique performance characteristics, driving their rapid growth. As manufacturers seek to optimise performance, the demand for hybrid gears is likely to increase. Suppliers may need to diversify their offerings to include hybrid gears to capture the growing interest in specialised turboprop applications.
By Gear Design – Steel Gears Dominated, Steel/Composite Expected to Grow Fastest
In 2025, Steel Gears led the gear design split with a 37% share. Steel gears are the preferred choice for turboprop gearboxes due to their durability and strength, which are crucial for reliable operation in aviation. Their extensive application across approximately 1,500 turboprop aircraft in China reinforces their dominant market share. Steel/Composite is set to record the highest CAGR in this split, 9.2% over 2026–2032. The steel/composite gear design is gaining traction for its ability to merge the strengths of both materials, catering to specific performance requirements. As manufacturers focus on optimising aircraft weight and efficiency, this segment is set for rapid growth. Manufacturers should invest in R&D for steel/composite gear designs to meet the evolving performance needs of the turboprop market.
By Distribution Channel – OEM Engine Suppliers Dominated, MRO Providers Expected to Grow Fastest
OEM Engine Suppliers took a 46% share of distribution channel in 2025, more than any other category. OEM engine suppliers are the primary source for new turboprop gearboxes, playing a vital role in the manufacturing of aircraft. Their established relationships with manufacturers ensure a consistent demand, securing their leading market share. MRO Providers are projected to grow fastest, at a CAGR of 9.7% during 2026–2032. MRO providers are experiencing significant growth as they become essential for maintenance, repair, and overhaul services for the existing turboprop fleet. With the average age of turboprop aircraft in China around 15 years, the demand for MRO services is on the rise. Suppliers should strengthen collaborations with MRO providers to leverage the increasing demand for maintenance services in the turboprop market.
By End User Industry – Regional Carriers Dominated, Military Training Expected to Grow Fastest
Regional Carriers accounted for a 42% market share by end user industry in 2025. Regional carriers are the primary users of turboprop aircraft, relying on them for efficient short-haul flights throughout China. Their substantial operational needs ensure that they maintain the largest market share in the turboprop sector. The quickest growth will come from Military Training, forecast to expand at a CAGR of 8.8% between 2026 and 2032. Military training programs are expanding their utilisation of turboprop aircraft, supported by a budget of approximately $1 billion for aviation training in 2023. This emphasis on efficiency in pilot training is driving rapid growth in this segment. Suppliers should engage with military training sectors to explore opportunities for providing tailored turboprop gearboxes that meet their specific operational requirements.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Turboprop Reduction Gearbox Market Outlook
- Market Size of China Turboprop Reduction Gearbox Market, 2025
- Forecast of China Turboprop Reduction Gearbox Market, 2032
- Historical Data and Forecast of China Turboprop Reduction Gearbox Revenues & Volume for the Period 2022 - 2032F
- China Turboprop Reduction Gearbox Market Trend Evolution
- China Turboprop Reduction Gearbox Market Drivers and Challenges
- China Turboprop Reduction Gearbox Price Trends
- China Turboprop Reduction Gearbox Porter's Five Forces
- China Turboprop Reduction Gearbox Industry Life Cycle
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Turboprop Reduction Gearbox for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Conventional Gearboxes for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Composite Gearboxes for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Overhauled Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Experimental Gearboxes for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Gearbox Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Straight Bevel for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Hybrid Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Refurbished Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Prototype Designs for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Gear Design for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Steel Gears for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Steel/Composite for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Performance Upgrades for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Custom Gear Ratios for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By OEM Engine Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Tier-1 Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By MRO Providers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By R&D Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Regional Carriers for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Military Training for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Charter Operators for the Period 2022 - 2032F
- Historical Data and Forecast of China Turboprop Reduction Gearbox Market Revenues & Volume By Test Programs for the Period 2022 - 2032F
- China Turboprop Reduction Gearbox Import Export Trade Statistics
- Market Opportunity Assessment By Turboprop Reduction Gearbox
- Market Opportunity Assessment By Gearbox Type
- Market Opportunity Assessment By Gear Design
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- China Turboprop Reduction Gearbox Top Companies Market Share
- China Turboprop Reduction Gearbox Competitive Benchmarking By Technical and Operational Parameters
- China Turboprop Reduction Gearbox Company Profiles
- China Turboprop Reduction Gearbox Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Turboprop Reduction Gearbox
- Conventional Gearboxes
- Composite Gearboxes
- Overhauled Assemblies
- Experimental Gearboxes
By Gearbox Type
- Straight Bevel
- Hybrid Gears
- Refurbished Units
- Prototype Designs
By Gear Design
- Steel Gears
- Steel/Composite
- Performance Upgrades
- Custom Gear Ratios
By Distribution Channel
- OEM Engine Suppliers
- Tier-1 Suppliers
- MRO Providers
- R&D Suppliers
By End User Industry
- Regional Carriers
- Military Training
- Charter Operators
- Test Programs































