China Urological Disorders Market Size & Growth Rate
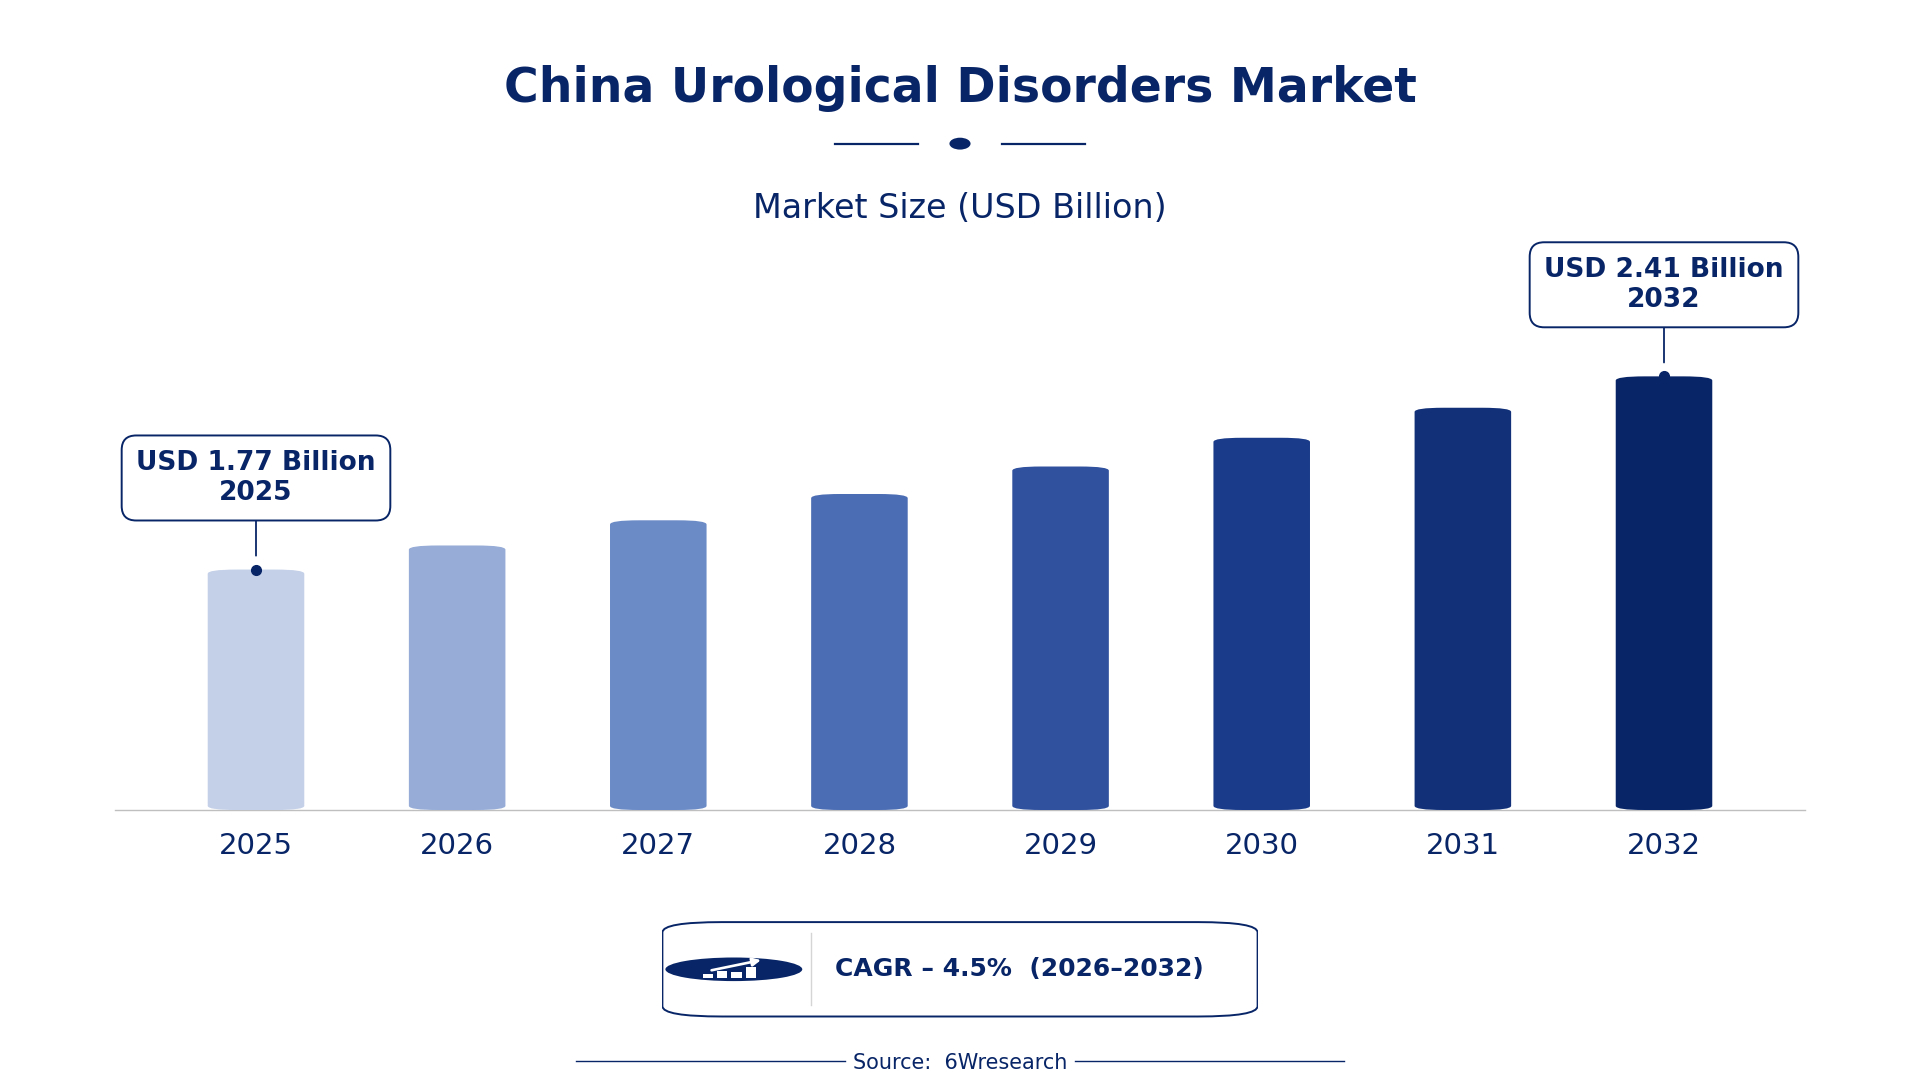
According to 6Wresearch internal database and industry insights, the China Urological Disorders Market was valued at USD 1.77 billion in 2025 and is projected to reach USD 2.41 billion by 2032, growing at a CAGR of approximately 4.5% during 2026–2032.
China Urological Disorders Market Highlights
| Report Metric | Details |
| Report Name | China Urological Disorders Market |
| Market Size 2025 | USD 1.77 billion |
| Market Size 2032 | USD 2.41 billion |
| Absolute Growth 2025–2032 | USD 0.64 billion |
| CAGR 2026–2032 | 4.5% |
| Peak Annual Growth | 7.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Disorder Type, 2025 | BPH (50% share) |
| Leading Treatment Approach, 2025 | Medication + Surgery (47% share) |
| Leading Diagnosis Type, 2025 | Imaging & Labs (45% share) |
| Leading End User, 2025 | Nephrology Clinics (33% share) |
| Fastest-Growing Disorder Type | Incontinence (5.9% CAGR) |
| Fastest-Growing Treatment Approach | Behavioral + Devices (5.9% CAGR) |
| Fastest-Growing End User | Elderly Patients (7.1% CAGR) |
| Growing Sector | Elderly Patients |
| Key End Users | Nephrology Clinics, Men over 50, Elderly Patients, Primary Care |
China Urological Disorders Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
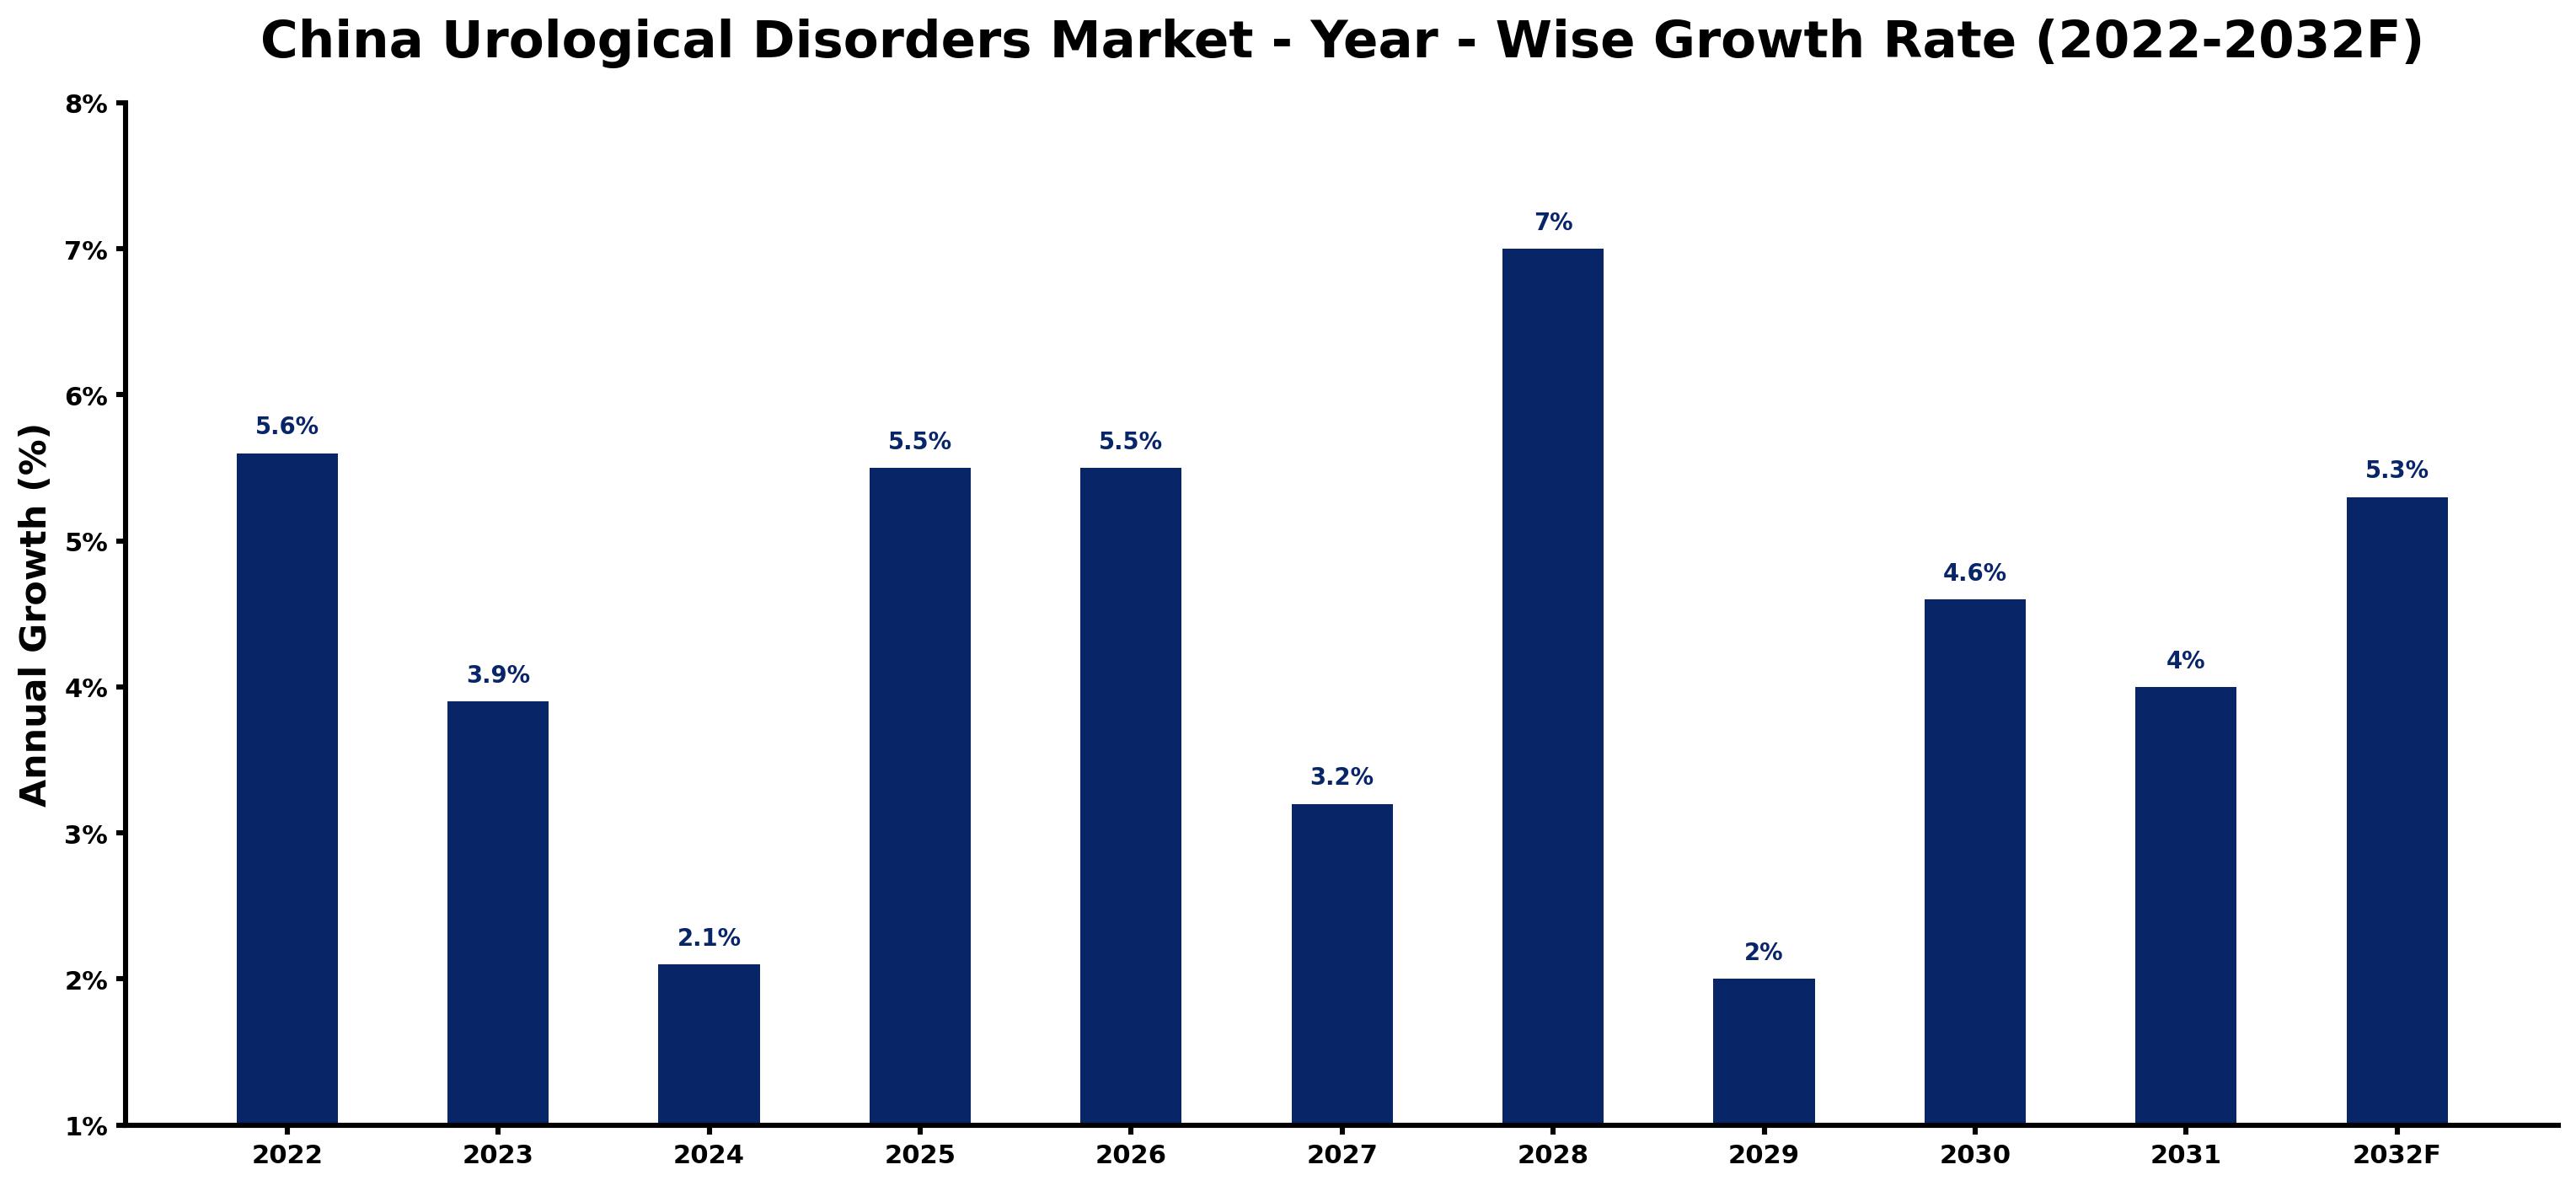
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.6 | The market experienced strong growth due to increased awareness of urological health prompted by the National Health Commission's initiatives. |
| 2023 | 3.9 | Demand growth slowed as the healthcare system adjusted to new treatment protocols established by the Ministry of Health. |
| 2024 | 2.1 | Continued adjustments in service delivery led to further slowdown in growth rates, affecting patient access to care. |
| 2025 | 5.5 | The introduction of new treatment options spurred faster growth in the market, particularly in urban healthcare facilities. |
| 2026 | 5.5 | Growth is expected to remain steady as urban healthcare facilities expand their services and improve patient access. |
| 2027 | 3.2 | Market growth is projected to slow due to resource allocation challenges in healthcare affecting service delivery. |
| 2028 | 7.0 | A surge in demand for urological services is expected to drive significant growth this year, particularly in major cities. |
| 2029 | 2.0 | Growth is projected to slow as market saturation begins to affect purchasing patterns among healthcare providers. |
| 2030 | 4.6 | Increased investments in healthcare technology are expected to boost market growth again, enhancing treatment options for patients. |
| 2031 | 4.0 | Growth is projected to slow as the market stabilises after several years of rapid expansion, affecting service availability. |
| 2032 | 5.3 | A renewed focus on elderly health care is expected to drive growth, particularly through targeted health programs. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Urological Disorders Market Synopsis
The China Urological Disorders Market encompasses a range of conditions affecting the urinary tract and male reproductive system. Treatments include medication, surgery, and lifestyle modifications. The market is expanding due to rising patient numbers, particularly among the elderly, with approximately 120 million diagnosed in 2022. Urban healthcare systems are increasing access to urological services, driven by initiatives like the Urological Health Improvement Plan launched in 2023. This plan aims to improve awareness and treatment accessibility nationwide, further stimulating market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising prevalence of BPH among older men drives demand for regular medical attention. | Driver | High | BPH |
| Increased access to imaging services enhances diagnostic capabilities for urological disorders. | Driver | High | Imaging & Labs |
| Growing demand for incontinence management solutions creates opportunities for new therapies. | Opportunity | High | Incontinence |
| Investment in nephrology clinics is rising, expanding treatment capacity in urban areas. | Opportunity | High | Nephrology Clinics |
| Limited access to urological care in rural regions hinders overall market growth. | Restraint | High | BPH |
| High average wait times for consultations can deter patients from seeking treatment. | Restraint | Medium | BPH |
| The Urological Disorders Market in China faces challenges from resource allocation issues. | Challenge | High | BPH |
| Competition among healthcare providers can lead to inconsistent service quality. | Challenge | Medium | BPH |
Evaluation of Drivers in China Urological Disorders Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing prevalence of kidney stones drives demand for lithotripsy treatments. | Kidney Stones | With a prevalence of 10% in urban adults, demand for effective treatment options is rising. |
| Growing elderly population increases the need for urological services. | Elderly Patients | Approximately 30% of elderly patients in urban areas require urological care, boosting service demand. |
| Imaging technologies improve diagnosis and treatment planning. | Imaging & Labs | Imaging services are available in 95% of tertiary hospitals, facilitating accurate diagnoses and treatment. |
| Standardised antibiotic treatment protocols streamline urological care. | Antibiotic Treatment | Protocols established by the Ministry of Health ensure effective management of infections related to urological conditions. |
| Regular PSA testing promotes early detection of prostate issues among men over 50. | PSA | Annual recommendations by the Chinese Urological Association encourage proactive health checks among men. |
Growth across the Urological Disorders market in China is anchored in rising patient numbers, expanding healthcare infrastructure, and increased awareness of urological health. Approximately 120 million patients were diagnosed with urological disorders in 2022, highlighting strong demand. The prevalence of kidney stones in urban areas is about 10% among adults, driving the need for lithotripsy treatments. Imaging technologies are available in 95% of tertiary hospitals, improving diagnostic accuracy and treatment planning. Standardised antibiotic treatment protocols ensure effective management of infections, further supporting market growth.
Evaluation of Restraints in China Urological Disorders Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited access to urological care in rural regions restricts patient treatment options. | BPH | Despite initiatives, many rural areas still lack adequate healthcare facilities for urological disorders, affecting patient outcomes. |
| High average wait times for consultations can deter patients from seeking treatment. | BPH | In urban centers, the average wait time for urological consultations is about two weeks, impacting timely care. |
| Resource allocation issues in healthcare can affect service delivery and patient care. | BPH | Healthcare facilities face challenges in distributing resources effectively across services, leading to delays in treatment. |
| Inconsistent service quality among providers can lead to patient dissatisfaction. | BPH | Competition among healthcare providers sometimes results in varied treatment experiences, affecting patient trust. |
| Awareness gaps about urological health persist among certain demographics. | BPH | Some patients remain unaware of available treatments and preventive measures, limiting their access to care. |
China Urological Disorders Market Challenges
The China Urological Disorders Market faces intense competition from established healthcare providers, which hampers smaller clinics' ability to attract patients. High treatment costs for advanced procedures, particularly in rural areas, can deter individuals from seeking necessary care, impacting their health outcomes. Limited access to advanced diagnostic technology results in care quality disparities, causing delays in diagnoses for buyers in less urbanised regions. Urban buyers experience an average wait time of two weeks for consultations, which can postpone treatments and worsen conditions for those affected.
Trends in the China Urological Disorders Market
Several trends are reshaping the China Urological Disorders Market; the most important are set out below.
- Shift Towards Advanced Imaging Services: Urban healthcare facilities are increasingly adopting advanced imaging technologies for urological diagnosis. In 2022, imaging services were available in 95% of tertiary hospitals, improving diagnostic accuracy and treatment planning for patients.
- Focus on Urological Care for the Elderly: The healthcare sector is prioritising urological care for the elderly, with the Elderly Health Promotion Program launched in 2022. This initiative has a budget of 300 million RMB, aimed at improving access to treatment for older patients.
- Standardisation of Treatment Protocols: Standardised protocols for antibiotic treatment of urological infections have been implemented nationwide. This change, initiated by the Ministry of Health, ensures consistent care across healthcare facilities, improving patient outcomes.
- Increasing Demand for Lithotripsy Treatments: The prevalence of kidney stones, estimated at 10% in urban adults, is driving demand for lithotripsy. The installed base of lithotripsy machines in hospitals is around 1,500 units nationwide, facilitating treatment access.
Investment Opportunities in the China Urological Disorders Market
The following opportunities in the China Urological Disorders Market pair current demand with a clear way in.
- Investment in Nephrology Clinics: With the growing need for urological services, investing in nephrology clinics is timely. Major cities like Beijing and Shanghai are ideal locations, where demand for kidney-related treatments is high, supported by a growing patient base.
- Supply of Advanced Imaging Technologies: Now is the time to supply advanced imaging technologies to healthcare providers. Urban hospitals are expanding their diagnostic capabilities, and partnerships with local distributors can facilitate market entry.
- Development of Incontinence Management Solutions: The increasing elderly population creates an opportunity for incontinence management solutions. Targeting elderly patients in urban areas, suppliers can enter through collaborations with healthcare facilities.
- Expansion of Urological Health Education Programs: The Urological Health Improvement Plan launched in 2023 presents an opportunity to develop educational programs. Collaborating with local health authorities can improve awareness and treatment accessibility.
Government Initiatives in the China Urological Disorders Market
In 2023, the National Health Commission introduced the 'Urological Health Improvement Plan' to increase awareness and access to treatment for urological disorders nationwide. This initiative builds on previous measures, such as the 'National Guidelines for Prostate Health' updated in 2021, which standardised screening practices for men over 50. The new plan focuses on education and outreach, ensuring that more patients receive timely care for urological conditions, ultimately benefiting producers and healthcare providers alike.
The 'Elderly Health Promotion Program' introduced in 2022 allocates 300 million RMB to improve urological care for the elderly population. This program supports training initiatives for healthcare professionals and enhances access to treatment facilities. Additionally, the 'Training Program for Primary Care Physicians' initiated by the Chinese Urological Association in 2020 aims to improve diagnosis and treatment of urological conditions, ensuring that primary care providers are equipped to manage these disorders effectively.
Future Insight of the China Urological Disorders Market
Several forward-looking factors should support the China Urological Disorders Market over the coming years. The National Health Commission's 2023 initiative to improve access to urological care in rural areas will likely benefit millions of individuals. Enhanced imaging services will enable faster diagnoses, while government funding of 500 million RMB for urological initiatives is expected to spur advancements in treatment options. New educational strategies will empower patients, fostering better management of their conditions and increasing demand for services from healthcare providers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Disorder Type – BPH Dominated, Incontinence Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, the largest disorder type category in 2025 was BPH, with a 50% share of total revenue. BPH holds the largest share because it affects nearly 50% of men over 50, necessitating regular medical care. This demographic's significant need for treatment options drives demand in urban healthcare facilities across China. The quickest growth will come from Incontinence, forecast to expand at a CAGR of 5.9% between 2026 and 2032. Incontinence is experiencing rapid growth, impacting about 30% of elderly patients in urban areas, which creates an urgent requirement for effective management solutions. The rising awareness and availability of diverse treatment approaches are contributing to its swift demand increase. Suppliers should develop targeted solutions for BPH and incontinence to effectively capture the growing market share.
By Treatment Approach – Medication + Surgery Dominated, Behavioral + Devices Expected to Grow Fastest
Medication + Surgery took a 47% share of treatment approach in 2025, more than any other category. The combination of Medication and Surgery dominates the market as it is the standard treatment for various urological disorders, ensuring consistent demand from healthcare providers. This approach is vital for effectively managing conditions like BPH and incontinence in clinical settings. Behavioral + Devices are projected to grow fastest, at a CAGR of 5.9% during 2026–2032. Behavioral therapies and devices for incontinence are gaining traction as they address a significant issue among the elderly, leading to their increased adoption in community health programs. This trend indicates a shift towards more comprehensive management strategies for urological disorders. Providers must innovate in developing behavioural therapies and devices to meet the rising demand in the treatment landscape.
By Diagnosis Type – Imaging & Labs Dominated and Is Expected to Record the Fastest Growth
Imaging & Labs held a 45% share of the China Urological Disorders Market by diagnosis type in 2025. Imaging & Labs command the largest share because they are essential for accurate diagnosis of urological disorders, with services available in 95% of tertiary hospitals. The reliance on these diagnostic methods solidifies their leading position in the market, ensuring effective patient care. Imaging & Labs are also forecast to expand faster than any other category, at a CAGR of 5.9% over 2026–2032. Imaging & Labs are also the fastest-growing segment, driven by advancements in technology and enhanced diagnostic capabilities. Continuous improvements in imaging techniques ensure that this segment remains at the forefront of the market. Investing in advanced imaging technologies will be crucial for suppliers to maintain a competitive edge in diagnosing urological disorders.
By End User – Nephrology Clinics Dominated, Elderly Patients Expected to Grow Fastest
In 2025, Nephrology Clinics led the end user split with a 33% share. Nephrology Clinics lead the market due to their specialization in treating kidney-related disorders, making them essential for managing urological health. The concentration of these clinics in major cities like Beijing and Shanghai supports their substantial market share and accessibility to patients. Elderly Patients are set to record the highest CAGR in this split, 7.1% over 2026–2032. Elderly Patients represent the fastest-growing segment as they constitute a major demographic requiring urological care, particularly in urban settings. The increasing prevalence of urological disorders in this age group drives the demand for tailored services and solutions. Suppliers should tailor their offerings to meet the specific needs of elderly patients to capture the expanding market share.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Urological Disorders Market Outlook
- Market Size of China Urological Disorders Market, 2025
- Forecast of China Urological Disorders Market, 2032
- Historical Data and Forecast of China Urological Disorders Revenues & Volume for the Period 2022 - 2032F
- China Urological Disorders Market Trend Evolution
- China Urological Disorders Market Drivers and Challenges
- China Urological Disorders Price Trends
- China Urological Disorders Porter's Five Forces
- China Urological Disorders Industry Life Cycle
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Disorder Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Kidney Stones for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By BPH for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Prostatitis for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Incontinence for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Treatment Approach for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Lithotripsy for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Medication + Surgery for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Antibiotic Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Behavioral + Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Diagnosis Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Imaging & Labs for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By PSA, DRE for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Culture & Exam for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Clinical History for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Nephrology Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Men over 50 for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Primary Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Urological Disorders Market Revenues & Volume By Elderly Patients for the Period 2022 - 2032F
- China Urological Disorders Import Export Trade Statistics
- Market Opportunity Assessment By Disorder Type
- Market Opportunity Assessment By Treatment Approach
- Market Opportunity Assessment By Diagnosis Type
- Market Opportunity Assessment By End User
- China Urological Disorders Top Companies Market Share
- China Urological Disorders Competitive Benchmarking By Technical and Operational Parameters
- China Urological Disorders Company Profiles
- China Urological Disorders Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Disorder Type
- Kidney Stones
- BPH
- Prostatitis
- Incontinence
By Treatment Approach
- Lithotripsy
- Medication + Surgery
- Antibiotic Treatment
- Behavioral + Devices
By Diagnosis Type
- Imaging & Labs
- PSA
- DRE
- Culture & Exam
- Clinical History
By End User
- Nephrology Clinics
- Men over 50
- Primary Care
- Elderly Patients































