China Urology Diagnostics Market Size & Growth Rate
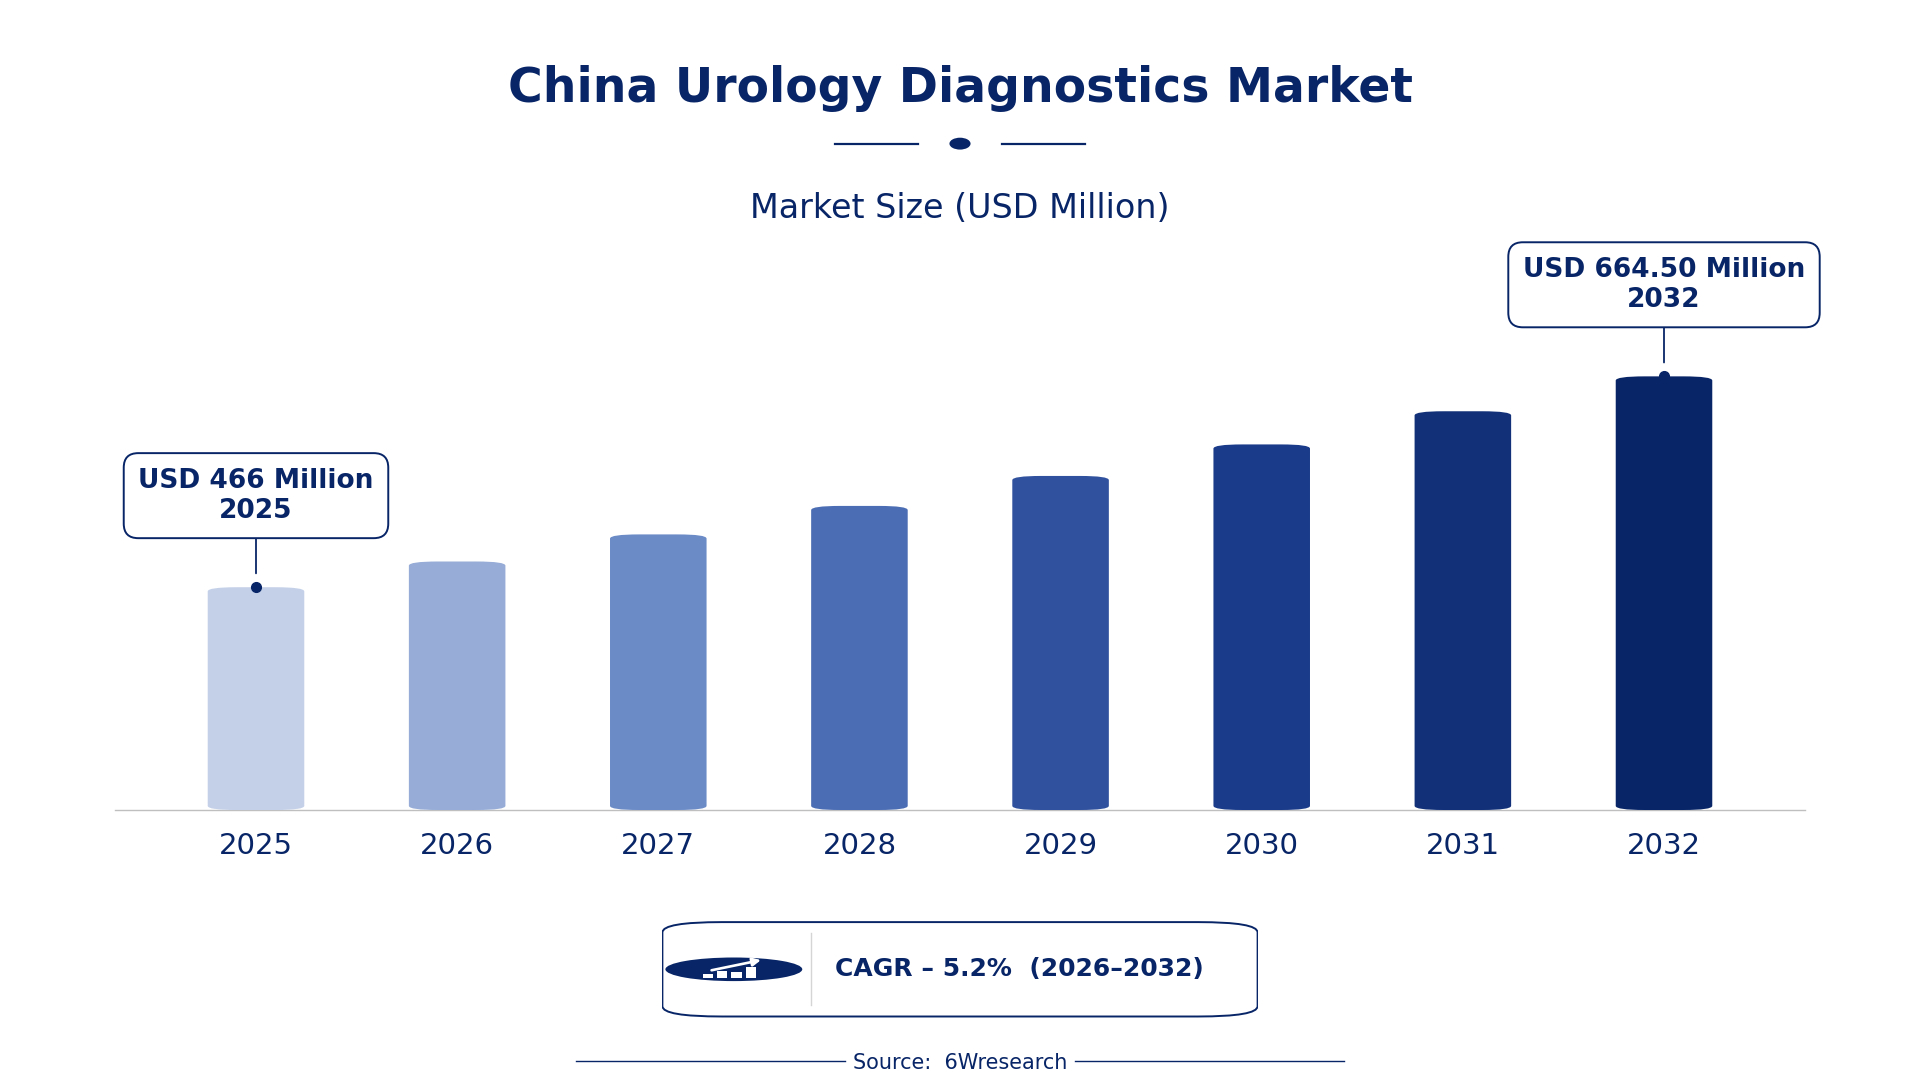
According to 6Wresearch internal database and industry insights, the China Urology Diagnostics Market was valued at USD 466.0 million in 2025 and is projected to reach USD 664.50 million by 2032, growing at a CAGR of approximately 5.2% during 2026–2032.
China Urology Diagnostics Market Highlights
| Report Metric | Details |
| Report Name | China Urology Diagnostics Market |
| Market Size 2025 | USD 466.0 million |
| Market Size 2032 | USD 664.50 million |
| Absolute Growth 2025–2032 | USD 198.50 million |
| CAGR 2026–2032 | 5.2% |
| Peak Annual Growth | 8.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Diagnostic Type, 2025 | Urinalysis (38% share) |
| Leading Test Method, 2025 | Dipstick Test (42% share) |
| Leading Setting, 2025 | Clinics (41% share) |
| Leading End User, 2025 | Urologists (42% share) |
| Fastest-Growing Diagnostic Type | Uroflowmetry (7.6% CAGR) |
| Fastest-Growing Test Method | Endoscopic Imaging (7.2% CAGR) |
| Fastest-Growing Setting | Outpatient (7.2% CAGR) |
| Fastest-Growing End User | Urology Practices (7.0% CAGR) |
| Growing Sector | Urology Practices |
| Key End Users | Urologists, Clinics, Diagnostic Labs, General Physicians |
China Urology Diagnostics Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
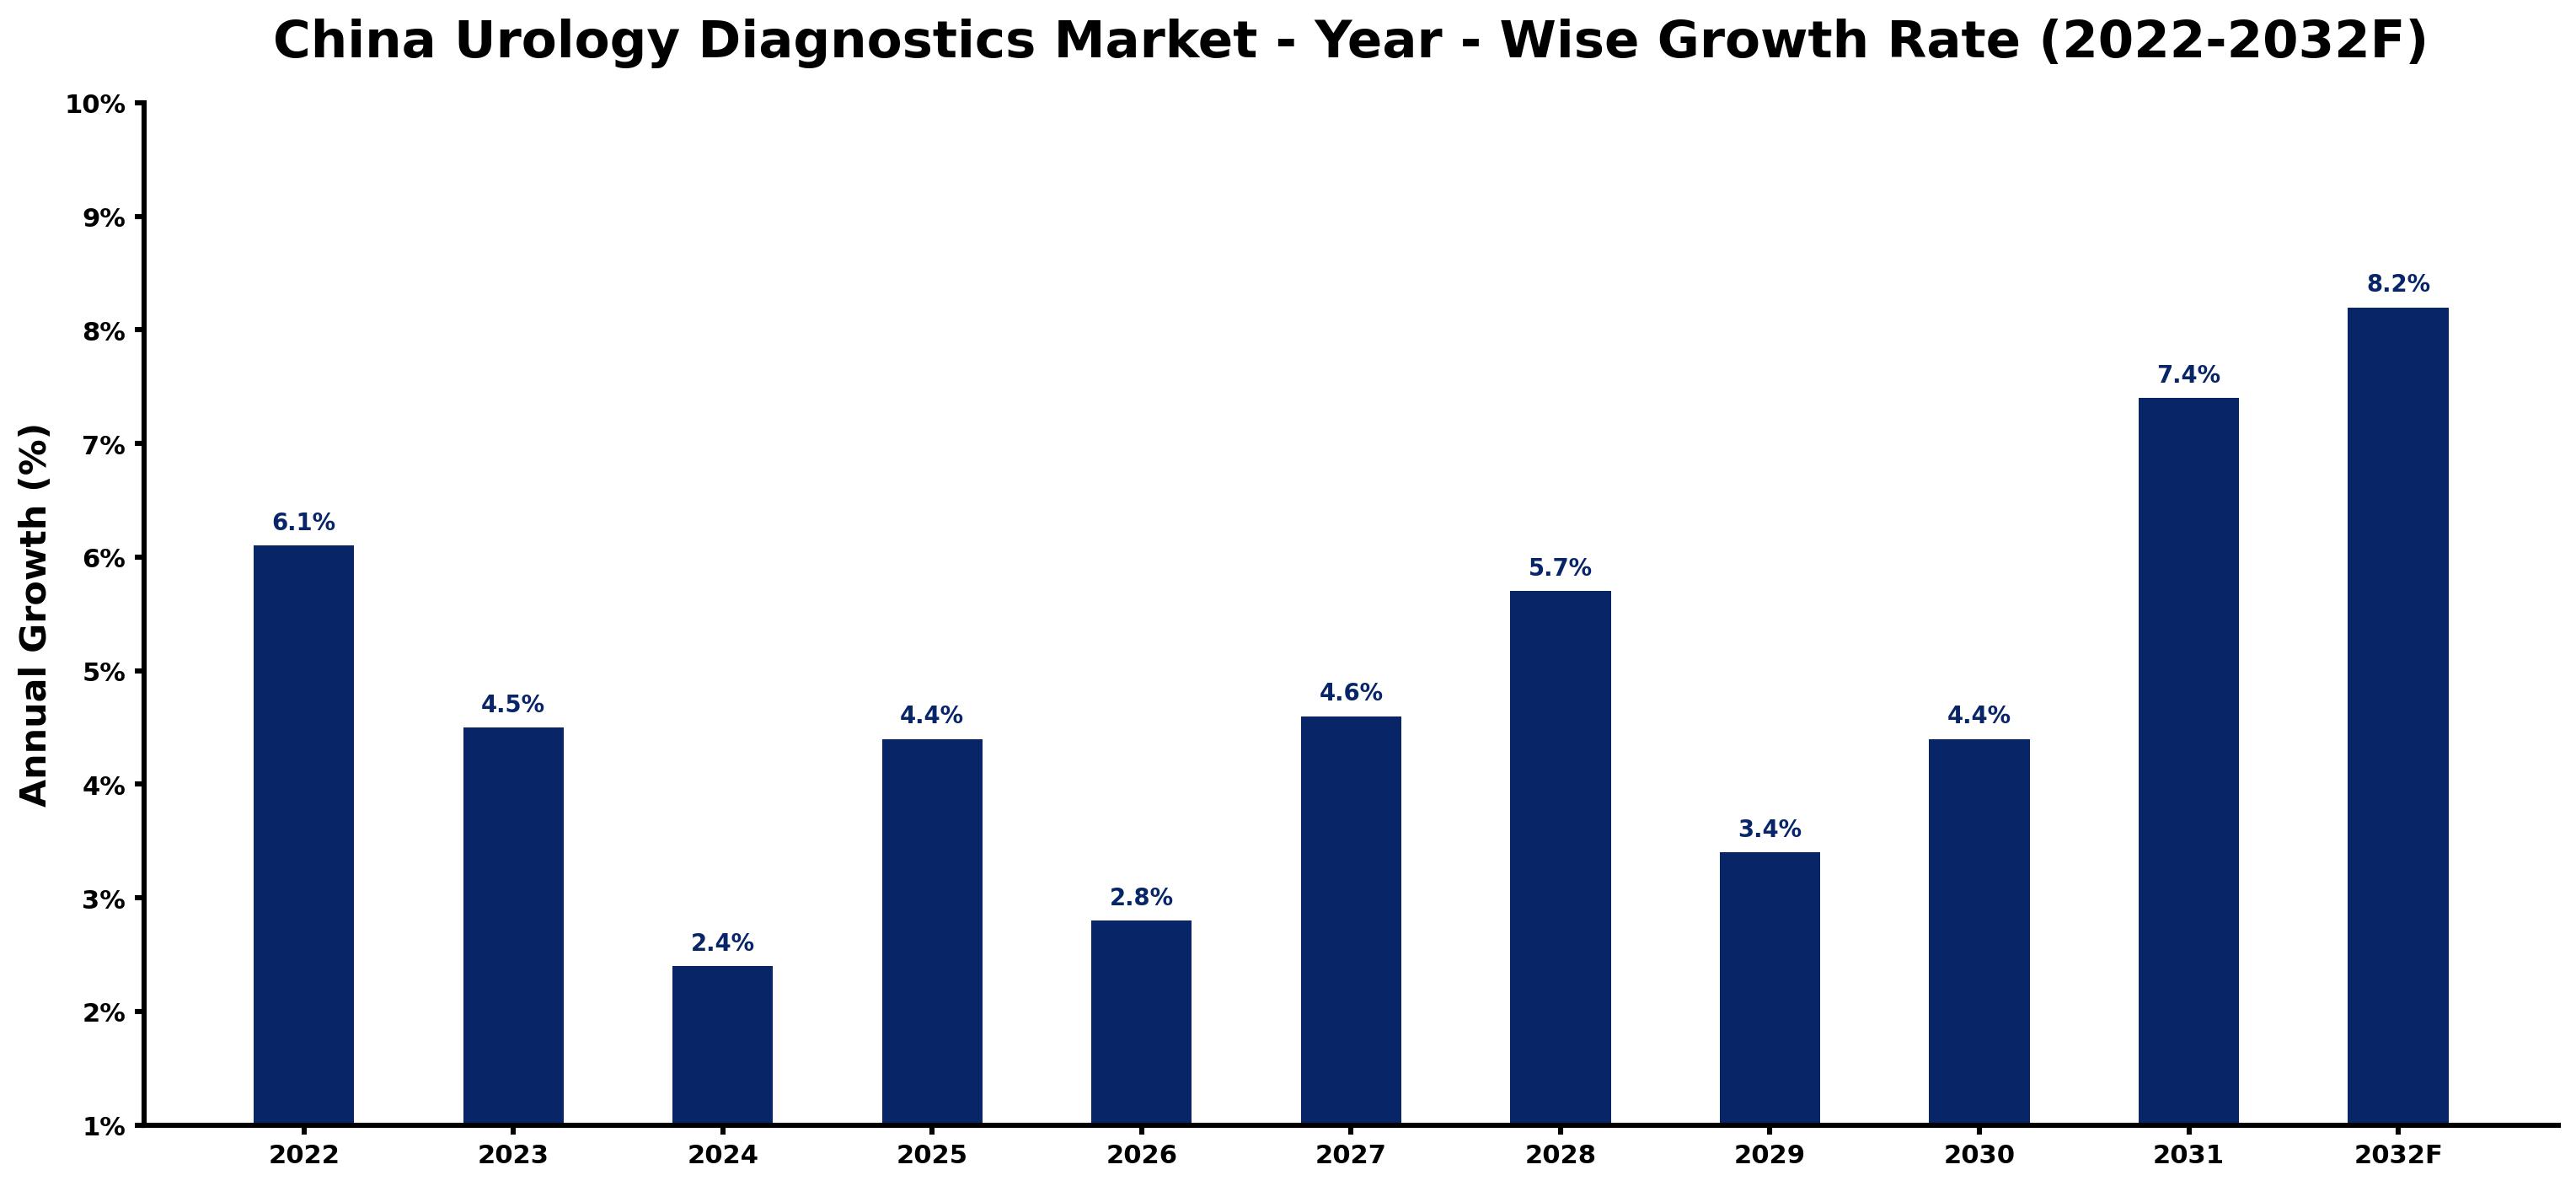
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.1 | The market experienced a strong demand due to increased awareness of urological health. |
| 2023 | 4.5 | Growth slowed as the market adjusted to new healthcare policies and standards. |
| 2024 | 2.4 | Continued awareness efforts led to a further slowdown in growth rates. |
| 2025 | 4.4 | A rise in outpatient services contributed to a faster growth rate this year. |
| 2026 | 2.8 | Growth slowed again as healthcare providers faced resource constraints. |
| 2027 | 4.6 | Increased adoption of Uroflowmetry devices spurred demand in outpatient settings. |
| 2028 | 5.7 | A growing focus on preventive care boosted growth in urology diagnostics. |
| 2029 | 3.4 | Market growth slowed as hospitals faced staffing shortages affecting services. |
| 2030 | 4.4 | A resurgence in urology consultations contributed to higher growth rates. |
| 2031 | 7.4 | Increased investments in diagnostic technologies led to accelerated growth. |
| 2032 | 8.2 | The market is expected to peak due to advancements in diagnostic methods. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Urology Diagnostics Market Synopsis
Urology Diagnostics in China encompasses various tests and methods to diagnose urinary tract conditions. These diagnostics are primarily conducted through laboratory testing and imaging techniques. The China Urology Diagnostics Market is growing due to rising demand from healthcare providers and hospitals. The National Health Commission reported a 15% increase in urology-related consultations in 2023, highlighting the need for improved diagnostic capabilities. Additionally, investment in urology diagnostic technologies is prioritized in the 14th Five-Year Plan, further driving market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased awareness of urological health issues drives demand for diagnostics. | Driver | High | Uroflowmetry |
| The growing number of urology clinics expands access to diagnostic services. | Driver | High | Clinics |
| Investment in advanced diagnostic technologies creates opportunities for suppliers. | Opportunity | High | Diagnostic Labs |
| The rise in outpatient services opens new avenues for diagnostic testing. | Opportunity | Medium | Outpatient |
| Resource constraints in healthcare facilities limit diagnostic capabilities. | Restraint | High | Urology Practices |
| Long wait times for diagnostic tests hinder patient access to care. | Restraint | Medium | General Physicians |
| Staffing shortages in healthcare facilities slow down service delivery. | Challenge | High | Clinics |
| Regulatory hurdles for new diagnostic devices delay market entry. | Challenge | Medium | Diagnostic Labs |
Evaluation of Drivers in China Urology Diagnostics Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased awareness of urological health issues drives demand for diagnostics. | Uroflowmetry | This awareness leads to more patients seeking diagnostic services, increasing test volumes annually. |
| The growing number of urology clinics expands access to diagnostic services. | Clinics | More clinics result in higher patient footfall, boosting demand for urology diagnostics across the board. |
| The PSA test is widely used, with millions conducted annually in hospitals. | PSA Test | High testing volumes for prostate abnormalities increase demand for related diagnostic services each year. |
| Cystoscopy procedures have seen a rise due to increasing awareness of urological health. | Cystoscopy | As awareness grows, more patients opt for cystoscopy, driving demand for this diagnostic method considerably. |
| Investment in advanced diagnostic technologies creates opportunities for suppliers. | Diagnostic Labs | Funding for new technologies improves testing capabilities, attracting more healthcare providers to upgrade their services. |
Expansion of the Urology Diagnostics market in China is backed by rising end-use demand and a responsive supply chain. Increased awareness of urological health issues has led to millions of PSA tests conducted annually in hospitals, boosting testing volumes. The growing number of urology clinics expands access to diagnostics, resulting in higher patient footfall. Investment in advanced diagnostic technologies is prioritised in the 14th Five-Year Plan, which aims to improve testing capabilities across the country. The rise in cystoscopy procedures reflects a growing focus on urological health, driving further demand for these services.
Evaluation of Restraints in China Urology Diagnostics Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Resource constraints in healthcare facilities limit diagnostic capabilities. | Urology Practices | Limited resources lead to fewer tests being conducted, impacting patient care. |
| Long wait times for diagnostic tests hinder patient access to care. | General Physicians | Extended wait times discourage patients from seeking timely diagnostics, affecting treatment outcomes. |
| Staffing shortages in healthcare facilities slow down service delivery. | Clinics | Fewer staff members result in longer processing times for diagnostic tests, delaying patient care. |
| Regulatory hurdles for new diagnostic devices delay market entry. | Diagnostic Labs | Strict regulations can prolong the approval process for new technologies, affecting availability of advanced diagnostics. |
| High operational costs for diagnostic labs limit service expansion. | Diagnostic Labs | Increased costs can restrict the ability to invest in new testing technologies, impacting service offerings. |
China Urology Diagnostics Market Challenges
The China Urology Diagnostics Market encounters regulatory obstacles that delay the approval of new testing methods, costing producers valuable time and limiting innovation. Compliance with ISO 15189 standards raises operational costs, compelling diagnostic laboratories to allocate up to 20% of their budgets to quality assurance, which diminishes profit margins. Intense competition among over 4,000 diagnostic laboratories drives prices down, making it difficult for smaller entities to sustain operations and invest in advanced technologies. Hospitals face average wait times of 2-3 weeks for diagnostics, delaying timely treatment for patients with urgent urological conditions.
Trends in the China Urology Diagnostics Market
The trends below show where the China Urology Diagnostics Market is heading.
- Shift Towards Outpatient Urology Diagnostics: The trend towards outpatient diagnostics is gaining momentum, with outpatient services projected to grow at a CAGR of 7.2% from 2026 to 2032. This shift is particularly evident in urban areas where clinics are increasingly providing diagnostic services to meet patient needs.
- Increasing Adoption of Uroflowmetry Devices: Uroflowmetry devices are being more widely adopted in outpatient settings, reflecting a change in diagnostic practices. As of 2023, over 500 outpatient facilities have incorporated these devices into their services, improving diagnostic accuracy.
- Rise of Telemedicine in Urology Diagnostics: Telemedicine is becoming more common in urology diagnostics, especially in major cities. Pilot programs are in progress, with a reported 20% increase in telemedicine consultations in 2023, enhancing access for patients.
- Enhanced Focus on Preventive Urology Care: There is an increasing emphasis on preventive care in urology, driven by updated clinical guidelines for prostate cancer screening. The revised guidelines in 2023 aim to improve early detection rates and patient outcomes.
Investment Opportunities in the China Urology Diagnostics Market
Investors looking at the China Urology Diagnostics Market should consider the following areas.
- Investment in Advanced Diagnostic Technologies: With a projected investment of USD 100 million in urology diagnostic technologies, suppliers can target diagnostic labs needing modern equipment. Collaborating with local partners can facilitate market entry and enhance service delivery.
- Expansion of Outpatient Services: The increasing demand for outpatient services presents an opportunity to supply diagnostic equipment. Clinics in urban areas are seeking advanced testing solutions to meet patient needs, creating a market for suppliers.
- Growing Need for Urology Training Programs: The Ministry of Health's training program for urologists presents an opportunity to invest in educational resources. This initiative aims to improve diagnostic capabilities across the country, benefiting healthcare providers and patients alike.
- Improving Access to Urology Diagnostics in Rural Areas: The Urology Diagnostics Improvement Plan aims to enhance access in rural regions, creating a need for mobile diagnostic units. Suppliers can engage with local health authorities to provide necessary equipment and services.
Government Initiatives in the China Urology Diagnostics Market
The Urology Diagnostics Improvement Plan launched by the National Health Commission in 2021 aims to enhance diagnostic capabilities in rural areas. This initiative focuses on increasing access to testing facilities and improving overall healthcare quality. The plan includes funding for new diagnostic equipment and training programs for healthcare professionals. Additionally, the National Medical Products Administration approved new regulations for urology diagnostic devices in 2023, ensuring safety and efficacy in clinical settings. These measures aim to improve diagnostic services across the country and support healthcare providers in delivering quality care.
Healthcare providers utilise the Urology Diagnostics Improvement Plan to enhance service delivery. The plan supports clinics and diagnostic labs in rural areas by providing funding for advanced diagnostic technologies. The Ministry of Health also oversees training programs for urologists, ensuring they are equipped with the latest knowledge and skills. These initiatives aim to standardise diagnostic practices and improve patient outcomes across the healthcare system.
Future Insight of the China Urology Diagnostics Market
By 2032, buyers and suppliers in the China Urology Diagnostics Market can anticipate substantial advancements driven by increased investment in diagnostic technologies, as prioritised in the 14th Five-Year Plan. The integration of electronic monitoring systems in over 500 hospitals will streamline workflows and enhance patient outcomes. Expansion of health insurance coverage will facilitate greater access to urology diagnostics, encouraging more patients to seek timely evaluations. The rise of telemedicine pilot programs in major cities will improve remote consultations, enhancing accessibility for patients in rural areas.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Diagnostic Type – Urinalysis Dominated, Uroflowmetry Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, in 2025, Urinalysis led the diagnostic type split with a 38% share. Urinalysis holds the largest share in the China Urology Diagnostics Market due to its role as a common initial test for urinary issues, with over 10 million tests performed annually. This widespread use among healthcare providers ensures a robust installed base across the country. Uroflowmetry is set to record the highest CAGR in this split, 7.6% over 2026–2032. Uroflowmetry is experiencing rapid growth as it measures urine flow rate for diagnosis, responding to the rising demand for non-invasive diagnostic methods. The increasing adoption of these devices in outpatient settings reflects a shift towards more efficient diagnostic approaches. Suppliers should focus on enhancing the availability and accessibility of urology diagnostics, particularly urinalysis and uroflowmetry, to meet growing healthcare demands.
By Test Method – Dipstick Test Dominated, Endoscopic Imaging Expected to Grow Fastest
Dipstick Test accounted for a 42% market share by test method in 2025. The Dipstick Test commands the largest market share in the China Urology Diagnostics Market as it offers a quick assessment of urine composition, making it a preferred choice in many clinics. Its simplicity and rapid results contribute to its widespread adoption among healthcare providers. Over 2026–2032, Endoscopic Imaging is expected to post the fastest growth, at a CAGR of 7.2%. Endoscopic Imaging is the fastest-growing method, providing detailed internal views that enhance diagnostic accuracy. The increasing focus on precision in urology diagnostics is driving this trend, as healthcare professionals seek advanced imaging techniques. Buyers should consider investing in advanced test methods like Endoscopic Imaging to improve diagnostic capabilities and patient outcomes.
By Setting – Clinics Dominated, Outpatient Expected to Grow Fastest
With a 41% revenue share in 2025, Clinics was the largest setting category. Clinics dominate the market share in the China Urology Diagnostics Market as they serve as the primary setting for diagnostics, with over 1,000 urology clinics operating nationwide. Their accessibility and focus on urological care make them essential for patient consultations and tests. The quickest growth will come from Outpatient, forecast to expand at a CAGR of 7.2% between 2026 and 2032. Outpatient settings are witnessing the fastest growth, particularly for non-invasive procedures that align with the increasing preference for convenient healthcare solutions. The rise in urology-related consultations supports this trend, as more patients seek timely diagnostics. Suppliers should target outpatient settings to capitalise on the growing demand for accessible and efficient urology diagnostic services.
By End User – Urologists Dominated, Urology Practices Expected to Grow Fastest
Urologists held a 42% share of the China Urology Diagnostics Market by end user in 2025. Urologists represent the largest share of end users in the China Urology Diagnostics Market, as they are the main specialists performing diagnostics and managing urological conditions. Their expertise ensures that diagnostic tests are effectively utilised in patient care. Urology Practices are projected to grow fastest, at a CAGR of 7.0% during 2026–2032. Urology Practices are the fastest-growing end user segment, reflecting the increasing focus on specialised care and the need for comprehensive diagnostic services. This growth is driven by the rising prevalence of urological disorders and the demand for specialised treatment. Suppliers should strengthen relationships with urology practices to better meet the needs of this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Urology Diagnostics Market Outlook
- Market Size of China Urology Diagnostics Market, 2025
- Forecast of China Urology Diagnostics Market, 2032
- Historical Data and Forecast of China Urology Diagnostics Revenues & Volume for the Period 2022 - 2032F
- China Urology Diagnostics Market Trend Evolution
- China Urology Diagnostics Market Drivers and Challenges
- China Urology Diagnostics Price Trends
- China Urology Diagnostics Porter's Five Forces
- China Urology Diagnostics Industry Life Cycle
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Diagnostic Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Urinalysis for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Uroflowmetry for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By PSA Test for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Cystoscopy for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Test Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Dipstick Test for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Electronic Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Blood Sample for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Endoscopic Imaging for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Setting for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Outpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Diagnostic Labs for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By In-Clinic for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By General Physicians for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Urology Practices for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Oncology Specialists for the Period 2022 - 2032F
- Historical Data and Forecast of China Urology Diagnostics Market Revenues & Volume By Urologists for the Period 2022 - 2032F
- China Urology Diagnostics Import Export Trade Statistics
- Market Opportunity Assessment By Diagnostic Type
- Market Opportunity Assessment By Test Method
- Market Opportunity Assessment By Setting
- Market Opportunity Assessment By End User
- China Urology Diagnostics Top Companies Market Share
- China Urology Diagnostics Competitive Benchmarking By Technical and Operational Parameters
- China Urology Diagnostics Company Profiles
- China Urology Diagnostics Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Diagnostic Type
- Urinalysis
- Uroflowmetry
- PSA Test
- Cystoscopy
By Test Method
- Dipstick Test
- Electronic Monitoring
- Blood Sample
- Endoscopic Imaging
By Setting
- Clinics
- Outpatient
- Diagnostic Labs
- In-Clinic
By End User
- General Physicians
- Urology Practices
- Oncology Specialists
- Urologists































