China Vehicle Body Panel Market Size & Growth Rate
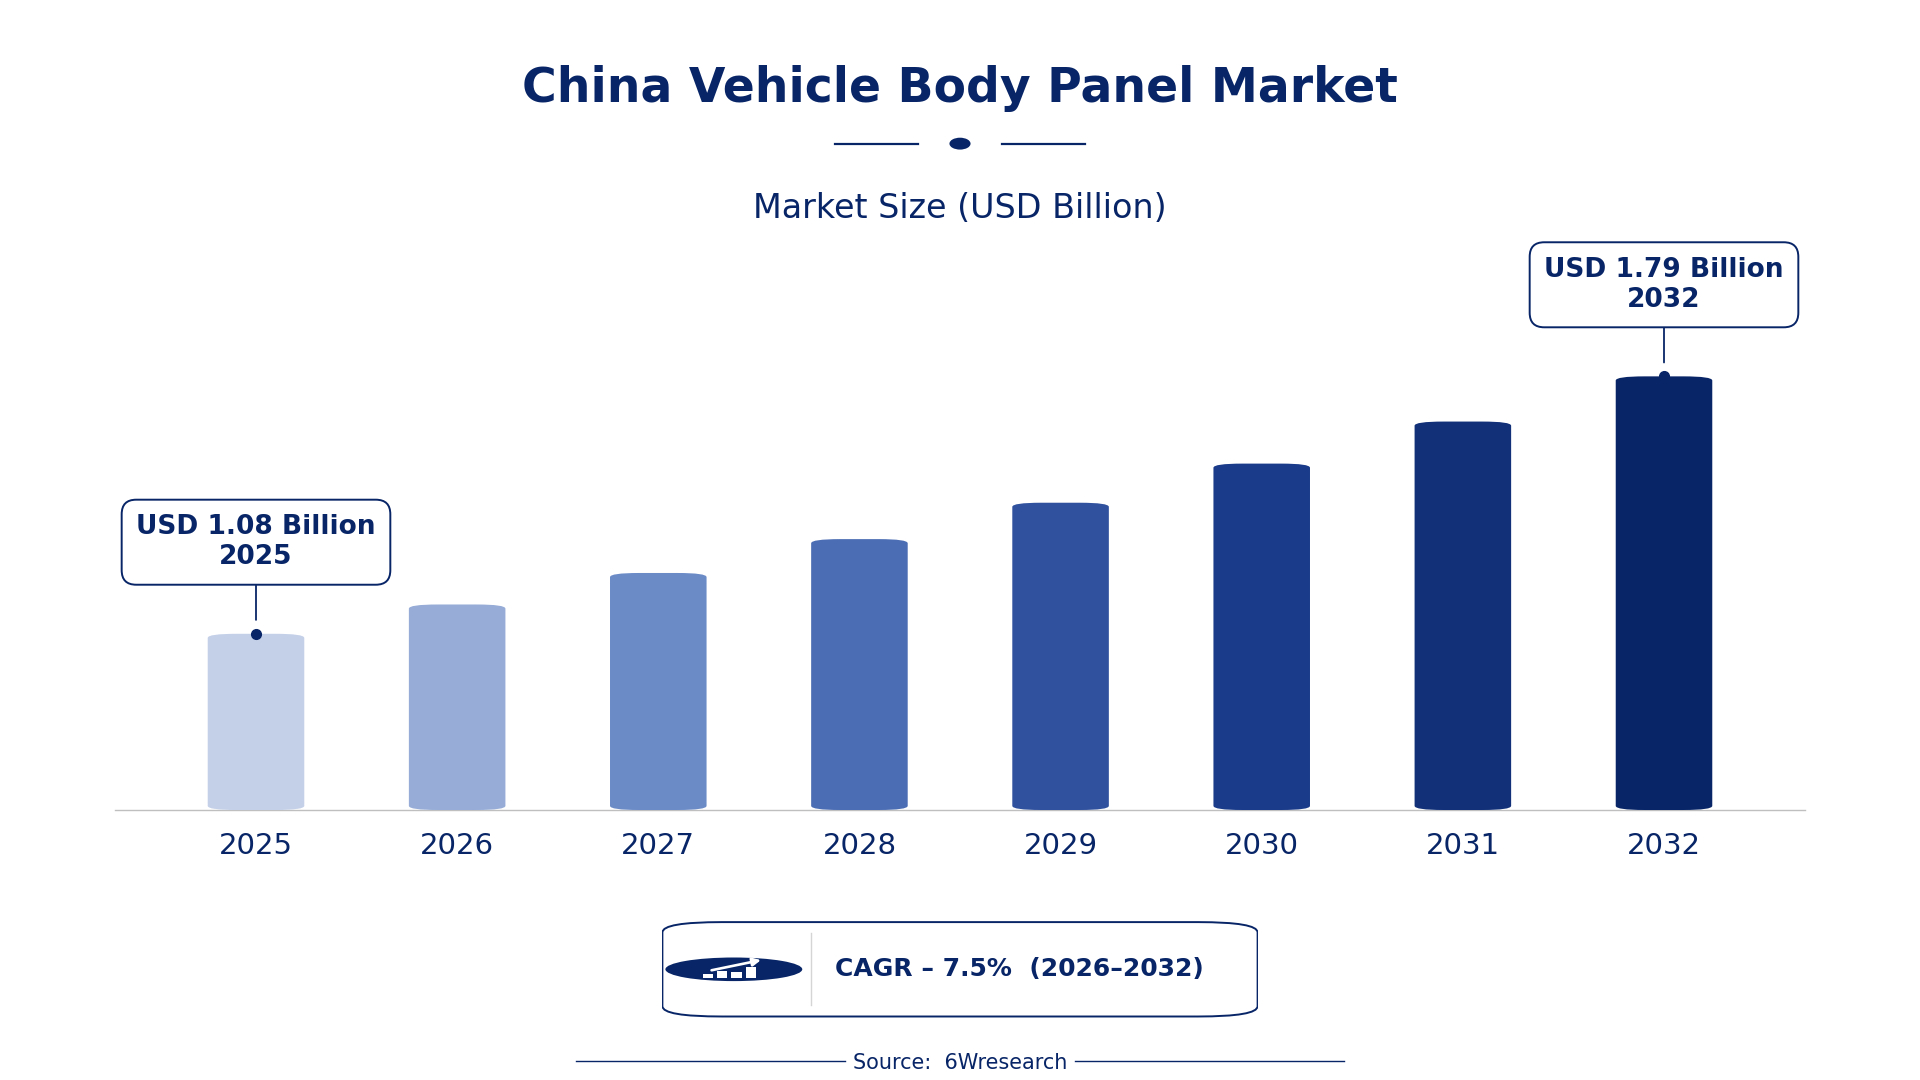
According to 6Wresearch internal database and industry insights, the China Vehicle Body Panel Market was valued at USD 1.08 billion in 2025 and is projected to reach USD 1.79 billion by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Vehicle Body Panel Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Body Panel Market |
| Market Size 2025 | USD 1.08 billion |
| Market Size 2032 | USD 1.79 billion |
| Absolute Growth 2025–2032 | USD 0.71 billion |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 9.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Panel Type, 2025 | Door Panels (44% share) |
| Leading Manufacturing Method, 2025 | Press Formed (38% share) |
| Leading Material Type, 2025 | Aluminum (46% share) |
| Leading End User, 2025 | Vehicle Assemblers (41% share) |
| Fastest-Growing Panel Type | Roof Panels (9.2% CAGR) |
| Fastest-Growing Manufacturing Method | Stamped (9.8% CAGR) |
| Fastest-Growing Material Type | Steel (8.6% CAGR) |
| Fastest-Growing End User | Automotive OEMs (8.6% CAGR) |
| Growing Sector | automotive manufacturing |
| Key End Users | vehicle assemblers, automotive OEMs, auto part suppliers |
China Vehicle Body Panel Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
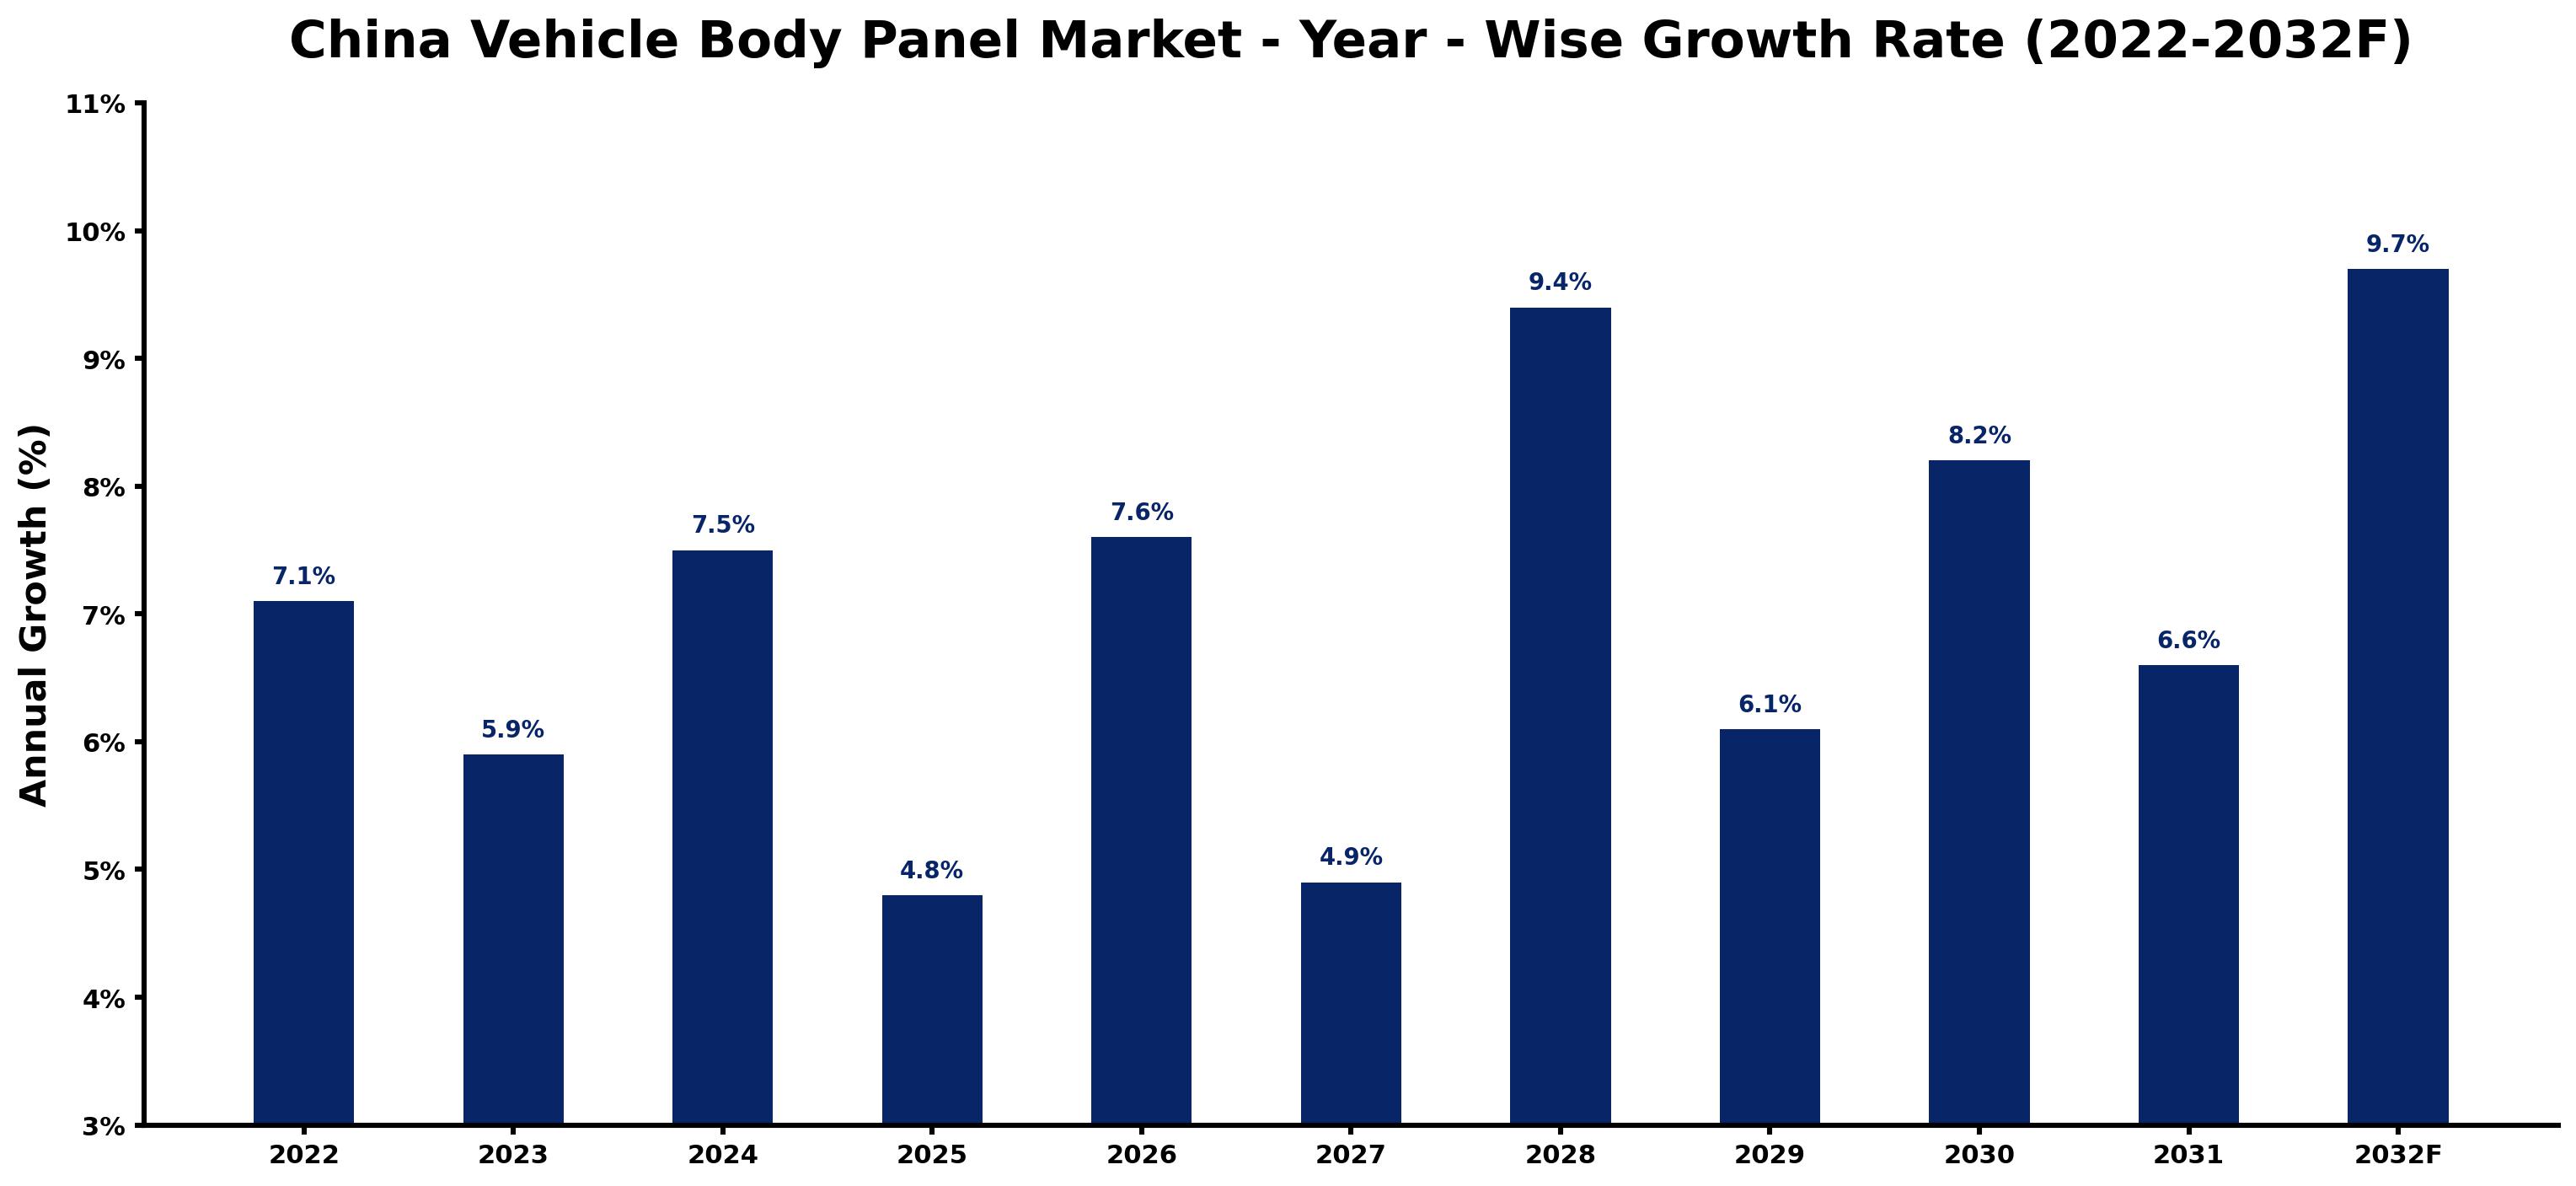
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.1 | The market experienced steady growth supported by consistent vehicle production levels. |
| 2023 | 5.9 | Growth slowed due to supply chain disruptions affecting manufacturing timelines. |
| 2024 | 7.5 | Demand increased as vehicle production rebounded from previous disruptions. |
| 2025 | 4.8 | Manufacturers faced challenges in sourcing materials, slowing growth again. |
| 2026 | 7.6 | Demand rose with increased investments in electric vehicle production facilities. |
| 2027 | 4.9 | The establishment of new automotive plants intensified competition, slowing growth. |
| 2028 | 9.4 | A surge in demand occurred due to rising consumer preference for lightweight materials. |
| 2029 | 6.1 | Manufacturers adjusted to market saturation in certain segments, slowing growth. |
| 2030 | 8.2 | Demand increased as new vehicle models featuring advanced body panels were launched. |
| 2031 | 6.6 | Production stabilised following previous rapid expansions, causing slower growth. |
| 2032 | 9.7 | Demand peaked as innovations in vehicle design drove higher body panel requirements. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Body Panel Market Synopsis
The Vehicle Body Panel in China includes crucial components for automobile manufacturing, such as door and roof panels crafted from materials like aluminium and steel. Key contributors to this expansion are the rising vehicle production numbers and the increasing demand for lightweight materials in vehicle assembly. Vehicle manufacturers are concentrating on improving production efficiency while adapting to changing consumer preferences.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing vehicle production levels drive demand for Vehicle Body Panels, as manufacturers require more components to meet assembly needs. | Driver | High | Door Panels |
| Growing investments in electric vehicle manufacturing are creating a need for specialised body panels, enhancing market demand. | Driver | High | Door Panels |
| The rising demand for lightweight materials presents an opportunity for suppliers to innovate and provide advanced materials for body panels. | Opportunity | High | Door Panels |
| The shift towards sustainable manufacturing practices opens avenues for suppliers to offer eco-friendly body panel solutions. | Opportunity | High | Door Panels |
| Raw material shortages are constraining production capabilities, leading to delays and increased costs for manufacturers. | Restraint | High | Door Panels |
| Regulatory compliance challenges can incur significant fines, impacting financial resources and operational efficiency for producers. | Restraint | High | Door Panels |
| A shortage of skilled labour limits the adoption of advanced manufacturing methods, resulting in productivity losses for manufacturers. | Challenge | High | Door Panels |
| Rising costs of raw materials are leading to increased prices for vehicle body panels, affecting overall market affordability for buyers. | Challenge | High | Door Panels |
Evaluation of Drivers in China Vehicle Body Panel Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing vehicle production levels drive demand for body panels. | Vehicle Assemblers | In 2025, vehicle production is expected to reach 28 million units, leading to higher purchases of body panels. |
| The transition to electric vehicles boosts demand for advanced body panels. | Vehicle Assemblers | Electric vehicle sales are projected to account for 20% of total sales by 2030, increasing demand for specialized panels. |
| Investment in manufacturing facilities supports increased production capacity. | Door Panels | The establishment of new automotive plants in regions like Jiangsu is set to increase body panel production. |
| Technological advancements in manufacturing processes improve panel quality. | Door Panels | The adoption of stamping techniques, expected to grow at a CAGR of 9.8%, improves production efficiency. |
| Growing consumer preference for lightweight materials drives innovation in body panels. | Vehicle Assemblers | With aluminum body panels projected to hold a 46% market share in 2025, demand for lightweight materials is rising. |
Market growth for Vehicle Body Panel in China is supported by increasing vehicle production levels, heightened investments in electric vehicle manufacturing, and a shift towards lightweight materials. By 2025, vehicle production is projected to hit 28 million units, leading to a surge in body panel purchases. The move towards electric vehicles, with sales expected to represent 20% of total sales by 2030, will stimulate demand for specialised panels. In addition, advancements in manufacturing processes, particularly stamping techniques, are likely to boost production efficiency, increasing overall output.
Evaluation of Restraints in China Vehicle Body Panel Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder timely production and delivery of body panels. | Vehicle Assemblers | In 2023, delays in raw material supply affected 30% of manufacturers' schedules. |
| High production costs limit profit margins for manufacturers. | Door Panels | Rising energy prices increased production costs by 15% in 2022. |
| Regulatory compliance requirements increase operational complexities. | Door Panels | New environmental regulations require additional certifications, impacting production timelines. |
| Intense competition among suppliers drives down prices. | Door Panels | Price wars among 50+ suppliers have reduced margins by 10% over the past year. |
| Limited access to skilled labour affects production efficiency. | Vehicle Assemblers | A shortage of skilled workers has led to a 15% drop in productivity for manufacturers. |
China Vehicle Body Panel Market Challenges
Producers in the China Vehicle Body Panel market face raw material shortages that delay production timelines by 20%, impacting their ability to meet demand. Regulatory compliance presents another hurdle, as non-adherence to environmental standards can incur fines in the millions, straining financial resources. A shortage of skilled labour limits the adoption of advanced manufacturing methods, resulting in productivity losses estimated at 15% for manufacturers. Buyers are experiencing rising costs, with vehicle body panel prices increasing by 10% as producers pass on these expenses, affecting overall market affordability.
Trends in the China Vehicle Body Panel Market
Four trends stand out in the China Vehicle Body Panel Market.
- Shift towards Lightweight Materials in Vehicle Production: The automotive sector is increasingly adopting lightweight materials, particularly aluminium, to enhance fuel efficiency. By 2025, aluminium body panels are expected to command a 46% market share, reflecting a change in production strategies.
- Transition from Traditional to Advanced Manufacturing Techniques: Manufacturers are shifting towards advanced stamping techniques, projected to grow at a CAGR of 9.8% from 2026 to 2032. This change improves efficiency and reduces waste in production.
- Growing Demand for Electric Vehicle Body Panels: Vehicle manufacturers are concentrating on electric vehicle body panels, with forecasts indicating that electric vehicle sales will reach 20% of total sales by 2030. This trend encourages innovation in body panel design.
- Emergence of Customised Body Panels for Niche Markets: There is a growing trend towards customised body panels tailored for niche markets, such as sports cars. This segment is anticipated to expand as consumer preferences evolve towards unique vehicle designs.
Investment Opportunities in the China Vehicle Body Panel Market
Some of the investment opportunities in the China Vehicle Body Panel Market are mentioned below.
- Vehicle Assemblers seeking lightweight body panels: With vehicle production expected to reach 28 million units in 2025, there is an opportunity to supply lightweight body panels, especially aluminum, to vehicle assemblers.
- Supply of Advanced Manufacturing Equipment: The demand for advanced manufacturing techniques is increasing, with a projected growth of 9.8% in stamping technology. Suppliers of advanced equipment can capitalise on this trend.
- Investment in Electric Vehicle Production Facilities: With electric vehicle sales anticipated to account for 20% of total sales by 2030, there is a need for specialised body panels. Investing in production facilities for these panels presents a valuable opportunity.
- Expansion of Automotive Manufacturing in Jiangsu: The establishment of new automotive plants in Jiangsu, projected to increase production capacity, offers opportunities for suppliers to meet rising demand for body panels.
Government Initiatives in the China Vehicle Body Panel Market
The regulatory framework for vehicle body panels is shaped by several key laws, including the Environmental Protection Law (2014) and the Implementation Plan for the Green Development of the Automotive Industry (2022). These regulations require manufacturers to adhere to strict environmental standards and promote the use of lightweight materials, driving innovation in the sector. The Automotive Industry Development Policy (2020) further emphasises sustainability and efficiency in production processes, influencing design choices for body panels.
The Ministry of Industry and Information Technology oversees the implementation of various automotive policies, including the Green Development Plan, which allocates funding for projects aimed at improving production efficiency. In 2021, the ministry approved 50 projects focused on sustainable manufacturing practices, providing financial support to manufacturers transitioning to eco-friendly production methods.
Future Insight of the China Vehicle Body Panel Market
The China Vehicle Body Panel market is projected to evolve by 2032, propelled by advancements in automation technology. The adoption of smart manufacturing techniques will improve production efficiency, enabling suppliers to better meet consumer demands. A shift towards sustainable materials will align with international standards, promoting eco-friendly practices. By 2032, production waste is expected to decrease by 30%, benefiting both producers and buyers through lower costs and improved product quality.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Panel Type – Door Panels Dominated, Roof Panels Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Door Panels held a 44% share of the China Vehicle Body Panel Market by panel type in 2025. Door panels hold the largest share in the China Vehicle Body Panel Market due to their essential role in vehicle aesthetics and functionality. Their extensive use across diverse vehicle categories, including sedans and SUVs, underscores their significance in the automotive sector. Over 2026–2032, Roof Panels are expected to post the fastest growth, at a CAGR of 9.2%. Roof panels are witnessing the fastest growth, driven by increasing consumer demand for enhanced vehicle features such as sunroofs. This trend is prompting manufacturers to innovate and expand their roof panel offerings to meet evolving consumer preferences. Suppliers should focus on developing advanced roof panel technologies to leverage the rising interest in premium vehicle features.
By Manufacturing Method – Press Formed Dominated, Stamped Expected to Grow Fastest
Press Formed accounted for a 38% market share by manufacturing method in 2025. Press formed panels dominate the market share in China due to their efficiency in producing complex shapes and high-volume outputs. This method is widely adopted in mass production facilities, ensuring a strong installed base. Stamped is projected to grow fastest, at a CAGR of 9.8% during 2026–2032. Stamped panels are growing at a remarkable rate, largely because of advancements in stamping technology that allow for faster production cycles. As manufacturers seek to optimise production efficiency, this method is becoming increasingly popular. Buyers should consider suppliers that utilise advanced stamping techniques to ensure timely delivery and cost-effectiveness.
By Material Type – Aluminum Dominated, Steel Expected to Grow Fastest
With a 46% revenue share in 2025, Aluminum was the largest material type category. Aluminum commands the largest market share in the China Vehicle Body Panel Market because of its lightweight nature, which plays a vital role in improving fuel efficiency. The automotive industry increasingly adopts aluminum to adhere to stringent environmental regulations and enhance vehicle performance. The quickest growth will come from Steel, forecast to expand at a CAGR of 8.6% between 2026 and 2032. Steel is the fastest-growing material type, as it offers a balance of strength and cost-effectiveness for vehicle body applications. The rising need for robust and economical body panels is propelling this segment's rapid growth. Suppliers should explore opportunities to enhance steel production processes to cater to the increasing demand for durable vehicle body panels.
By End User – Vehicle Assemblers Dominated, Automotive OEMs Expected to Grow Fastest
Vehicle Assemblers took a 41% share of end user in 2025, more than any other category. Vehicle assemblers represent the largest share in the China Vehicle Body Panel Market as they are the main purchasers for mass production. Their extensive manufacturing operations necessitate a consistent supply of diverse body panels to satisfy market demand. Automotive OEMs are set to record the highest CAGR in this split, 8.6% over 2026–2032. Automotive OEMs are the fastest-growing end user segment, propelled by the increase in electric vehicle production and the requirement for specialised body panels. This transition towards electrification positions this segment for swift growth. Suppliers must adapt their offerings to align with the specific needs of automotive OEMs to seize new market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Body Panel Market Outlook
- Market Size of China Vehicle Body Panel Market, 2025
- Forecast of China Vehicle Body Panel Market, 2032
- Historical Data and Forecast of China Vehicle Body Panel Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Body Panel Market Trend Evolution
- China Vehicle Body Panel Market Drivers and Challenges
- China Vehicle Body Panel Price Trends
- China Vehicle Body Panel Porter's Five Forces
- China Vehicle Body Panel Industry Life Cycle
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Panel Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Door Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Roof Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Quarter Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Hood Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Manufacturing Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Press Formed for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Stamped for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Injection Molded for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Composite Fabricated for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Aluminum for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Steel for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Thermoplastics for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Vehicle Assemblers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Automotive OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Auto Part Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Body Panel Market Revenues & Volume By Sports Car OEMs for the Period 2022 - 2032F
- China Vehicle Body Panel Import Export Trade Statistics
- Market Opportunity Assessment By Panel Type
- Market Opportunity Assessment By Manufacturing Method
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By End User
- China Vehicle Body Panel Top Companies Market Share
- China Vehicle Body Panel Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Body Panel Company Profiles
- China Vehicle Body Panel Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Panel Type
- Door Panels
- Roof Panels
- Quarter Panels
- Hood Panels
By Manufacturing Method
- Press Formed
- Stamped
- Injection Molded
- Composite Fabricated
By Material Type
- Aluminum
- Steel
- Thermoplastics
- Carbon Fiber
By End User
- Vehicle Assemblers
- Automotive OEMs
- Auto Part Suppliers
- Sports Car OEMs































