China Vehicle Camera Systems Market Size & Growth Rate
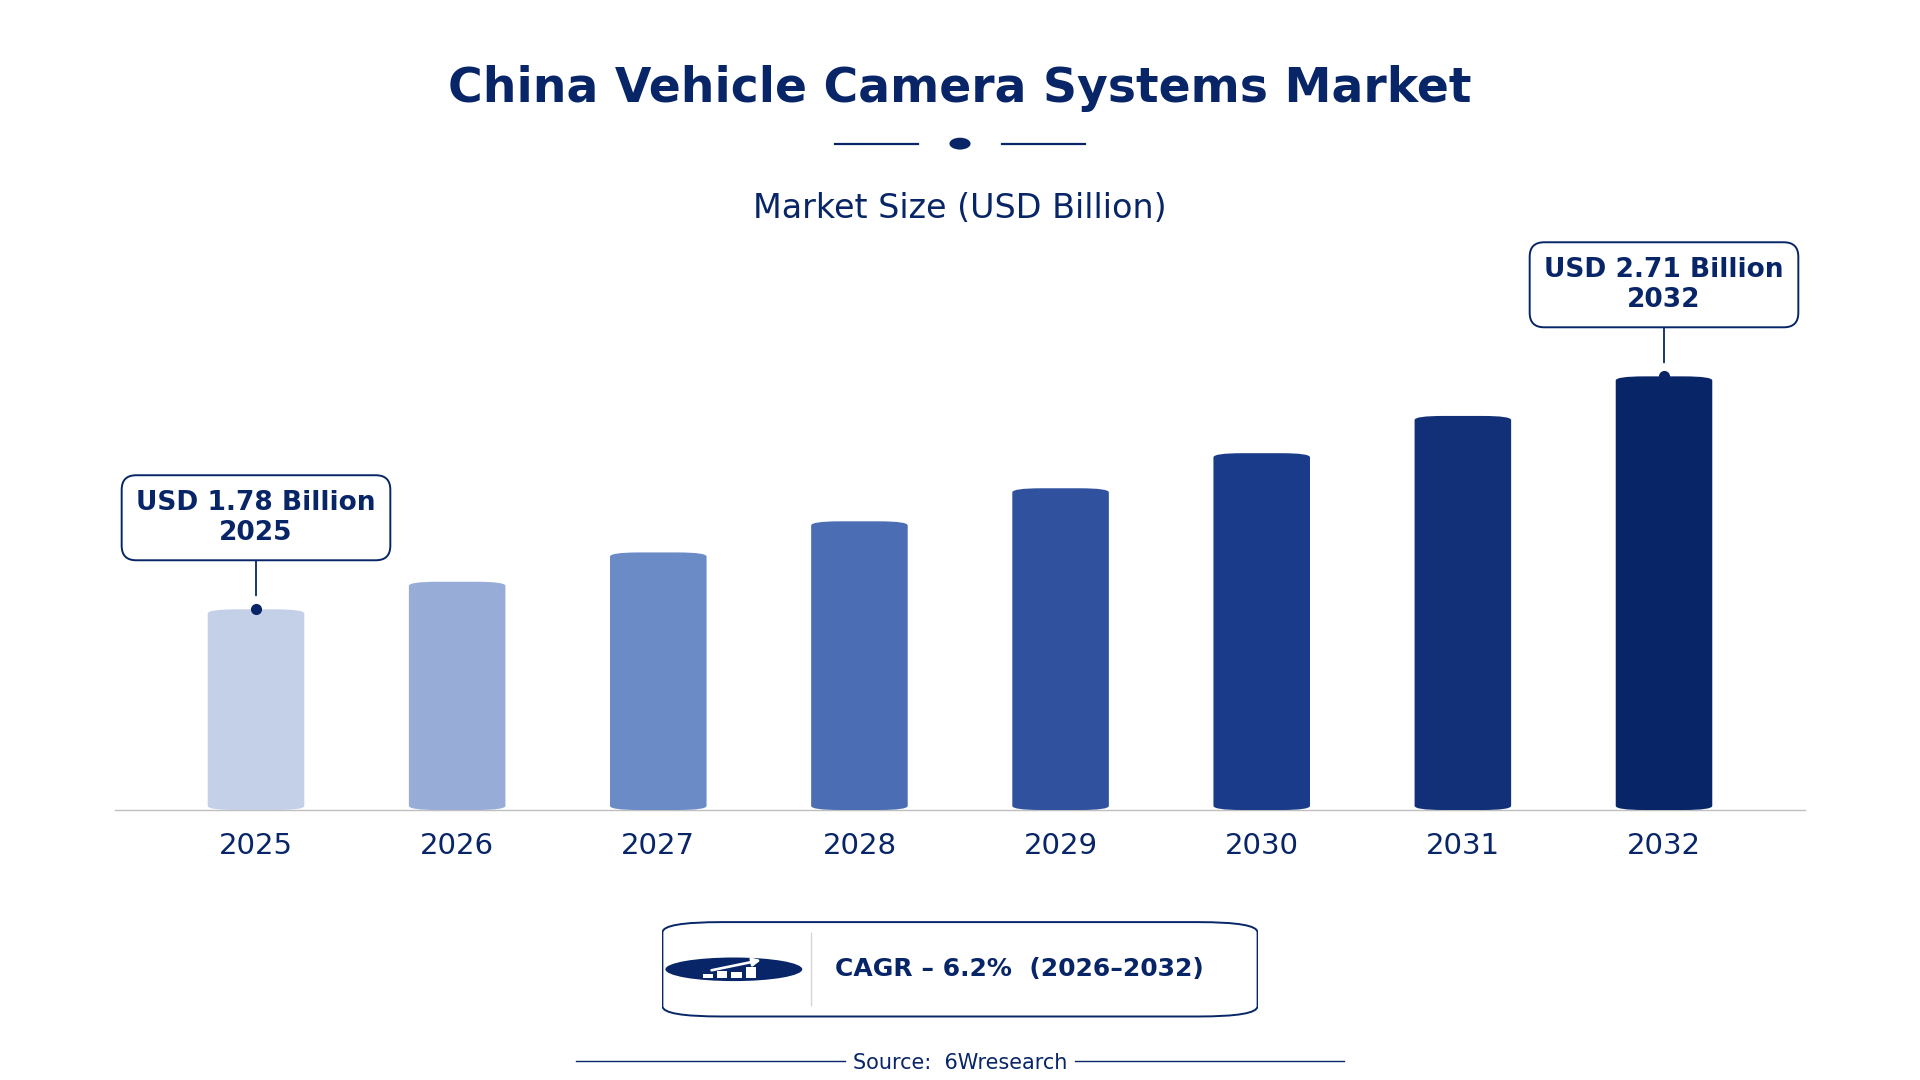
According to 6Wresearch internal database and industry insights, the China Vehicle Camera Systems Market was valued at USD 1.78 billion in 2025 and is projected to reach USD 2.71 billion by 2032, growing at a CAGR of approximately 6.2% during 2026–2032.
China Vehicle Camera Systems Market Highlights
| Report Metric | Details |
| Report Name | China Vehicle Camera Systems Market |
| Market Size 2025 | USD 1.78 billion |
| Market Size 2032 | USD 2.71 billion |
| Absolute Growth 2025–2032 | USD 0.93 billion |
| CAGR 2026–2032 | 6.2% |
| Peak Annual Growth | 8.7% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Camera Type, 2025 | Rear-View Cameras (52% share) |
| Leading Mounting Location, 2025 | Rear Bumper (38% share) |
| Leading Feature Functionality, 2025 | Reverse Assistance (43% share) |
| Leading End User, 2025 | Passenger Car OEMs (45% share) |
| Fastest-Growing Camera Type | Surround View Cameras (8.2% CAGR) |
| Fastest-Growing Mounting Location | All Sides (8.5% CAGR) |
| Fastest-Growing Feature Functionality | Driver Monitoring (8.8% CAGR) |
| Fastest-Growing End User | ADAS System Integrators (8.7% CAGR) |
| Growing Sector | ADAS System Integrators |
| Key End Users | Passenger Car OEMs, Premium Vehicle Brands, ADAS System Integrators, Autonomous Fleet Operators |
China Vehicle Camera Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
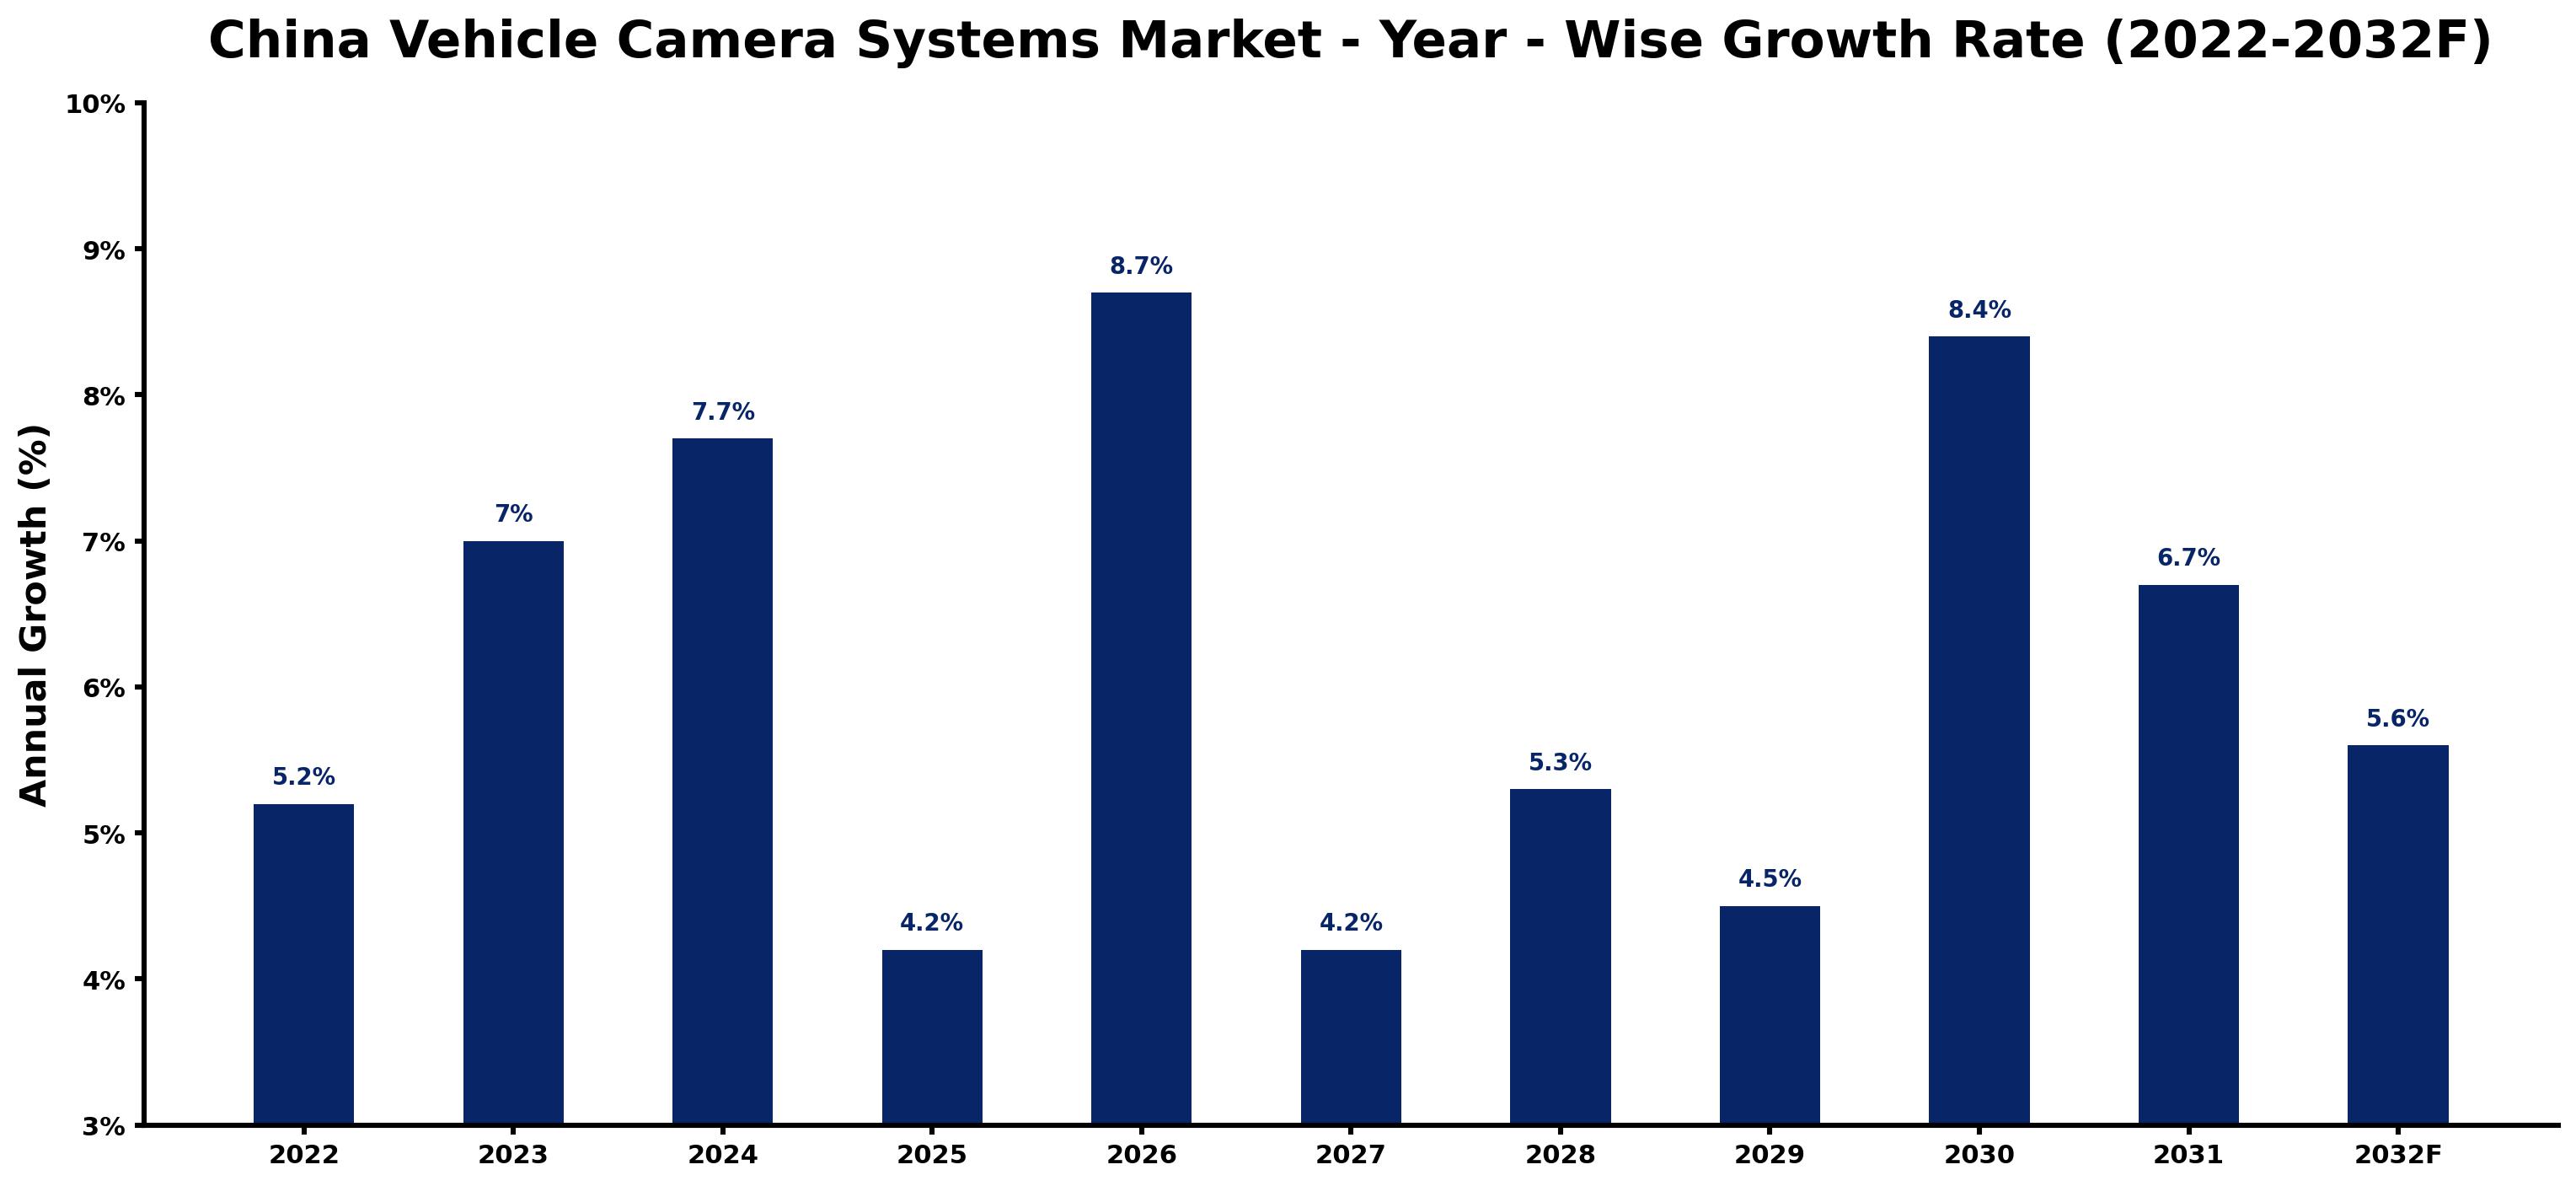
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.2 | The market experienced steady growth due to increasing vehicle production and the 'New Energy Vehicle Industry Development Plan'. |
| 2023 | 7.0 | Demand accelerated as the adoption rate of ADAS features reached approximately 30%, driven by safety regulations. |
| 2024 | 7.7 | Growth continued as 60% of new vehicles were equipped with rear-view cameras, reflecting heightened safety standards. |
| 2025 | 4.2 | A slowdown occurred as production growth moderated, yet demand for safety features remained strong, influenced by the Automotive Industry Policy. |
| 2026 | 8.7 | The market rebounded with significant growth driven by rising safety regulations and the reaffirmation of the National Standard GB/T 34590-2017. |
| 2027 | 4.2 | Growth slowed as the market adjusted to previous peaks, but demand for advanced systems persisted, supported by the Road Traffic Safety Law Revision. |
| 2028 | 5.3 | Demand increased again as consumers sought enhanced safety features in new vehicles, particularly driver monitoring systems. |
| 2029 | 4.5 | A slowdown was noted as growth stabilised, reflecting market maturation and competition in the automotive sector. |
| 2030 | 8.4 | The market surged again, driven by the integration of driver monitoring systems in new models, aligning with government targets. |
| 2031 | 6.7 | Growth decelerated as the market reached a more stable phase, with ongoing demand for safety enhancements from passenger car OEMs. |
| 2032 | 5.6 | The market continued to grow, supported by sustained investments in vehicle safety technologies and the Smart Vehicle Innovation Development Strategy. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Vehicle Camera Systems Market Synopsis
Vehicle Camera Systems in China encompass advanced electronic devices that enhance vehicle safety and assist drivers by providing visual information. These systems are made using high-resolution cameras, sensors, and software algorithms, primarily used for improving rear visibility and assisting with parking. The China Vehicle Camera Systems Market is growing due to rising vehicle production and increasing integration of advanced driver-assistance systems (ADAS). In 2022, the production of passenger vehicles reached 23 million units, while the adoption rate of ADAS features was approximately 30% in 2023. This trend reflects a strong demand from domestic manufacturers and a focus on safety regulations.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing integration of ADAS features in vehicles | Driver | High | Rear-View Cameras |
| Growing consumer preference for enhanced safety features | Driver | High | Surround View Cameras |
| Rising demand for 360-degree monitoring systems | Opportunity | Medium | 360-Degree Monitoring |
| Expansion of automotive manufacturing in Guangdong province | Opportunity | Medium | Passenger Car OEMs |
| High costs associated with advanced technology integration | Restraint | High | Front Cameras |
| Regulatory compliance challenges for new camera systems | Restraint | Medium | Cabin Cameras |
| Supply chain disruptions affecting component availability | Challenge | High | All Sides |
| Intense competition among manufacturers for market share | Challenge | Medium | Inside Vehicle |
Evaluation of Drivers in China Vehicle Camera Systems Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in advanced safety technologies | Rear-View Cameras | In 2023, 60% of new vehicles were equipped with rear-view cameras, driving demand from manufacturers. |
| Rising production of passenger vehicles | Surround View Cameras | In 2022, production reached 23 million units, increasing the need for safety features. |
| Growing regulatory requirements for vehicle safety | 360-Degree Monitoring | The National Standard GB/T 34590-2017 was reaffirmed in 2023, mandating safety enhancements. |
| Consumer demand for enhanced driving experiences | Front Cameras | Approximately 30% of new vehicles adopted ADAS features in 2023, boosting camera system sales. |
| Technological advancements in camera systems | Cabin Cameras | The integration of driver monitoring systems is expected to rise significantly by 2025. |
Market growth for Vehicle Camera Systems in China is underpinned by substantial investments in advanced safety technologies, which have led to an increase in vehicle production. In 2022, the production of passenger vehicles reached 23 million units, prompting manufacturers to adopt new safety features. The implementation of the 'Mandatory National Standard for Vehicle Camera Systems' in 2023 has driven demand for rear-view cameras, with 60% of new vehicles equipped. The rising adoption of ADAS features, estimated at approximately 30% in 2023, has created a market for surround view cameras. Consumer preferences for improved driving experiences continue to support the growth of front cameras, while technological advancements are projected to boost the cabin camera segment significantly by 2025.
Evaluation of Restraints in China Vehicle Camera Systems Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of integrating advanced camera systems | Front Cameras | The integration of advanced camera systems can increase vehicle production costs, affecting manufacturers' pricing strategies. |
| Regulatory compliance challenges for new technologies | Cabin Cameras | Manufacturers face hurdles in meeting stringent safety regulations, delaying product launches and increasing costs. |
| Supply chain disruptions impacting component availability | All Sides | Ongoing supply chain issues have led to delays in obtaining necessary components for camera systems, impacting production timelines. |
| Intense competition among manufacturers | Inside Vehicle | Competition has led to price wars, affecting profitability for producers of vehicle camera systems and limiting investment in innovation. |
| Market saturation in certain segments | Rear-View Cameras | A high penetration rate of rear-view cameras in new vehicles limits further growth opportunities, constraining market expansion. |
China Vehicle Camera Systems Market Challenges
In 2022, the production of passenger vehicles in China reached 23 million units, but buyers face high costs due to the limited availability of vehicle camera systems, which can delay vehicle deliveries by up to three months. Regulatory hurdles slow market progress; the reaffirmation of the National Standard GB/T 34590-2017 in 2023 necessitates compliance that can take manufacturers an additional six months to implement. Competition among suppliers is fierce, as 60% of new vehicles are equipped with rear-view cameras, forcing producers to lower prices, which squeezes their profit margins. Supply chain disruptions are common; the automotive sector in Guangdong struggles with sourcing high-quality components, leading to increased lead times for camera systems.
Trends in the China Vehicle Camera Systems Market
Below mentioned are some of the trends shaping the China Vehicle Camera Systems Market growth.
- Increase in Surround View Camera Adoption: The market for surround view cameras is seeing rising demand due to strict safety regulations. In 2023, a 15% increase in the use of these systems was recorded, indicating a shift towards comprehensive vehicle monitoring.
- Growth of 360-Degree Monitoring Systems: The adoption of 360-degree monitoring systems has surged, with a reported 15% increase in 2023. This trend is driven by consumer demand for enhanced safety features in new vehicles, especially in urban settings.
- Expansion of ADAS Features in New Vehicles: The integration of ADAS features in new vehicles has been a primary focus, with approximately 30% adoption in 2023. This trend is supported by the Smart Vehicle Innovation Development Strategy launched in 2023.
- Shift towards Driver Monitoring Systems: In 2023, the Ministry of Transport set a goal for all new vehicles to include driver monitoring systems by 2025. This shift reflects a growing emphasis on driver safety, with an anticipated increase in demand for related camera technologies.
Investment Opportunities in the China Vehicle Camera Systems Market
Several openings in the China Vehicle Camera Systems Market merit attention from investors.
- Guangdong Province as a Manufacturing Hub: Guangdong province stands out as a major hub for vehicle camera system production, with a notable rise in demand for advanced safety technologies. The province produced 23 million passenger vehicles in 2022, creating opportunities for investment in manufacturing facilities.
- Growing Demand for Driver Monitoring Systems: With the aim for all new vehicles to incorporate driver monitoring systems by 2025, there is a strong opportunity for suppliers. This demand is particularly pronounced among passenger car OEMs seeking to enhance safety features.
- Investment in Advanced Safety Technologies: The market gap for surround view cameras presents an opportunity for investment, as safety regulations continue to tighten. The automotive sector in Shanghai is concentrating on research and development of these technologies.
- ADAS System Integrators Seeking Partnerships: ADAS system integrators are increasingly pursuing local partners to enhance their offerings. With the market projected to grow significantly, collaboration can lead to better integration of camera systems.
Government Initiatives in the China Vehicle Camera Systems Market
In 2021, the Ministry of Industry and Information Technology launched the 'New Energy Vehicle Industry Development Plan' to promote advanced vehicle technologies, including camera systems. This initiative aims to improve safety and efficiency in the automotive sector. Additionally, the National Development and Reform Commission updated the 'Automotive Industry Policy' in 2022, supporting the integration of ADAS features in vehicles. These measures encourage manufacturers to embrace new technologies and elevate vehicle safety standards. In 2023, the State Administration for Market Regulation implemented the 'Mandatory National Standard for Vehicle Camera Systems', mandating compliance with specific safety criteria, ensuring that all new vehicles meet enhanced safety requirements. Furthermore, the Ministry of Transport initiated the 'Road Traffic Safety Law Revision' in 2022, underscoring the need for advanced safety technologies in vehicles.
The State Administration for Market Regulation oversees the approval of vehicle camera systems, ensuring compliance with safety standards. This agency plays a crucial role in maintaining quality and safety in the automotive sector. The Ministry of Transport also funds initiatives aimed at enhancing road safety, including the integration of advanced safety technologies in vehicles. Their efforts focus on promoting compliance with regulations and supporting manufacturers in adopting progressive solutions.
Future Insight of the China Vehicle Camera Systems Market
The vehicle camera systems market in China is set to evolve by 2032, primarily driven by the government's 'Smart Vehicle Innovation Development Strategy' that promotes advanced technologies. By 2025, all new vehicles must include monitoring systems, which will increase demand for integrated camera solutions. The adoption rate of ADAS features is anticipated to rise significantly, driving the need for sophisticated camera technologies. The growing emphasis on safety regulations will boost the demand for advanced visual solutions, aligning with consumer expectations for improved vehicle safety.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Camera Type – Rear-View Cameras Dominated, Surround View Cameras Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Rear-View Cameras accounted for a 52% market share by camera type in 2025. Rear-view cameras lead the China Vehicle Camera Systems Market as they are essential for reversing safety, with approximately 60% of new vehicles equipped with them. This widespread adoption is driven by passenger car manufacturers prioritising safety features in their designs, ensuring a strong market presence. The quickest growth will come from Surround View Cameras, forecast to expand at a CAGR of 8.2% between 2026 and 2032. Surround view cameras are experiencing rapid growth due to increasing safety regulations and the rising demand for enhanced parking assistance, evidenced by a 15% increase in 360-degree monitoring systems in 2023. As rear-view cameras maintain their lead, their growth will further solidify their market share. Suppliers should focus on developing advanced surround view camera technologies to capitalise on the growing safety regulations.
By Mounting Location – Rear Bumper Dominated, All Sides Expected to Grow Fastest
With a 38% revenue share in 2025, Rear Bumper was the largest mounting location category. The rear bumper serves as the primary mounting location for vehicle camera systems, particularly for rear-view cameras, which are crucial for safe reversing. This preference arises from the design of passenger vehicles, where rear visibility is a significant safety concern. All Sides are set to record the highest CAGR in this split, 8.5% over 2026–2032. Mounting cameras on all sides is gaining traction as it offers comprehensive vehicle monitoring, increasingly important for safety and convenience. This trend reflects the industry's shift towards more integrated camera systems that enhance overall vehicle safety. Buyers should consider the advantages of all sides mounting to improve vehicle safety and monitoring capabilities.
By Feature Functionality – Reverse Assistance Dominated, Driver Monitoring Expected to Grow Fastest
Reverse Assistance held a 43% share of the China Vehicle Camera Systems Market by feature functionality in 2025. Reverse assistance features dominate the market as they are vital for safe reversing, making them standard in many new vehicles. This functionality is particularly valued by passenger car manufacturers, who aim to enhance safety in their offerings. Driver Monitoring is projected to grow fastest, at a CAGR of 8.8% during 2026–2032. Driver monitoring systems are rapidly gaining traction as they address rising safety concerns, with government targets pushing for their inclusion in all new vehicles by 2025. The emphasis on reverse assistance will continue to support its leading position in the market. Suppliers need to invest in driver monitoring technologies to meet regulatory targets and consumer expectations.
By End User – Passenger Car OEMs Dominated, ADAS System Integrators Expected to Grow Fastest
In 2025, Passenger Car OEMs led the end user split with a 45% share. Passenger car OEMs hold the largest share of the market as they are the primary users of vehicle camera systems, integrating them into new models to enhance safety features. The robust automotive industry in China ensures a steady demand from these manufacturers. Over 2026–2032, ADAS System Integrators are expected to post the fastest growth, at a CAGR of 8.7%. ADAS system integrators are experiencing the fastest growth due to their role in embedding advanced camera systems into vehicles, aligning with the increasing adoption of ADAS features. As passenger car OEMs continue to integrate these systems, the demand for ADAS integration will also rise. Suppliers should strengthen partnerships with ADAS system integrators to align with the growing trend of advanced vehicle technologies.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Vehicle Camera Systems Market Outlook
- Market Size of China Vehicle Camera Systems Market, 2025
- Forecast of China Vehicle Camera Systems Market, 2032
- Historical Data and Forecast of China Vehicle Camera Systems Revenues & Volume for the Period 2022 - 2032F
- China Vehicle Camera Systems Market Trend Evolution
- China Vehicle Camera Systems Market Drivers and Challenges
- China Vehicle Camera Systems Price Trends
- China Vehicle Camera Systems Porter's Five Forces
- China Vehicle Camera Systems Industry Life Cycle
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Camera Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Rear-View Cameras for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Surround View Cameras for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Front Cameras for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Cabin Cameras for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Mounting Location for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Rear Bumper for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By All Sides for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Windshield for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Inside Vehicle for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Feature Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Reverse Assistance for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By 360-Degree Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Lane Assist for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Driver Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Passenger Car OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Premium Vehicle Brands for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By ADAS System Integrators for the Period 2022 - 2032F
- Historical Data and Forecast of China Vehicle Camera Systems Market Revenues & Volume By Autonomous Fleet Operators for the Period 2022 - 2032F
- China Vehicle Camera Systems Import Export Trade Statistics
- Market Opportunity Assessment By Camera Type
- Market Opportunity Assessment By Mounting Location
- Market Opportunity Assessment By Feature Functionality
- Market Opportunity Assessment By End User
- China Vehicle Camera Systems Top Companies Market Share
- China Vehicle Camera Systems Competitive Benchmarking By Technical and Operational Parameters
- China Vehicle Camera Systems Company Profiles
- China Vehicle Camera Systems Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Camera Type
- Rear-View Cameras
- Surround View Cameras
- Front Cameras
- Cabin Cameras
By Mounting Location
- Rear Bumper
- All Sides
- Windshield
- Inside Vehicle
By Feature Functionality
- Reverse Assistance
- 360-Degree Monitoring
- Lane Assist
- Driver Monitoring
By End User
- Passenger Car OEMs
- Premium Vehicle Brands
- ADAS System Integrators
- Autonomous Fleet Operators































