India 3D Semiconductor Market Size & Growth Rate
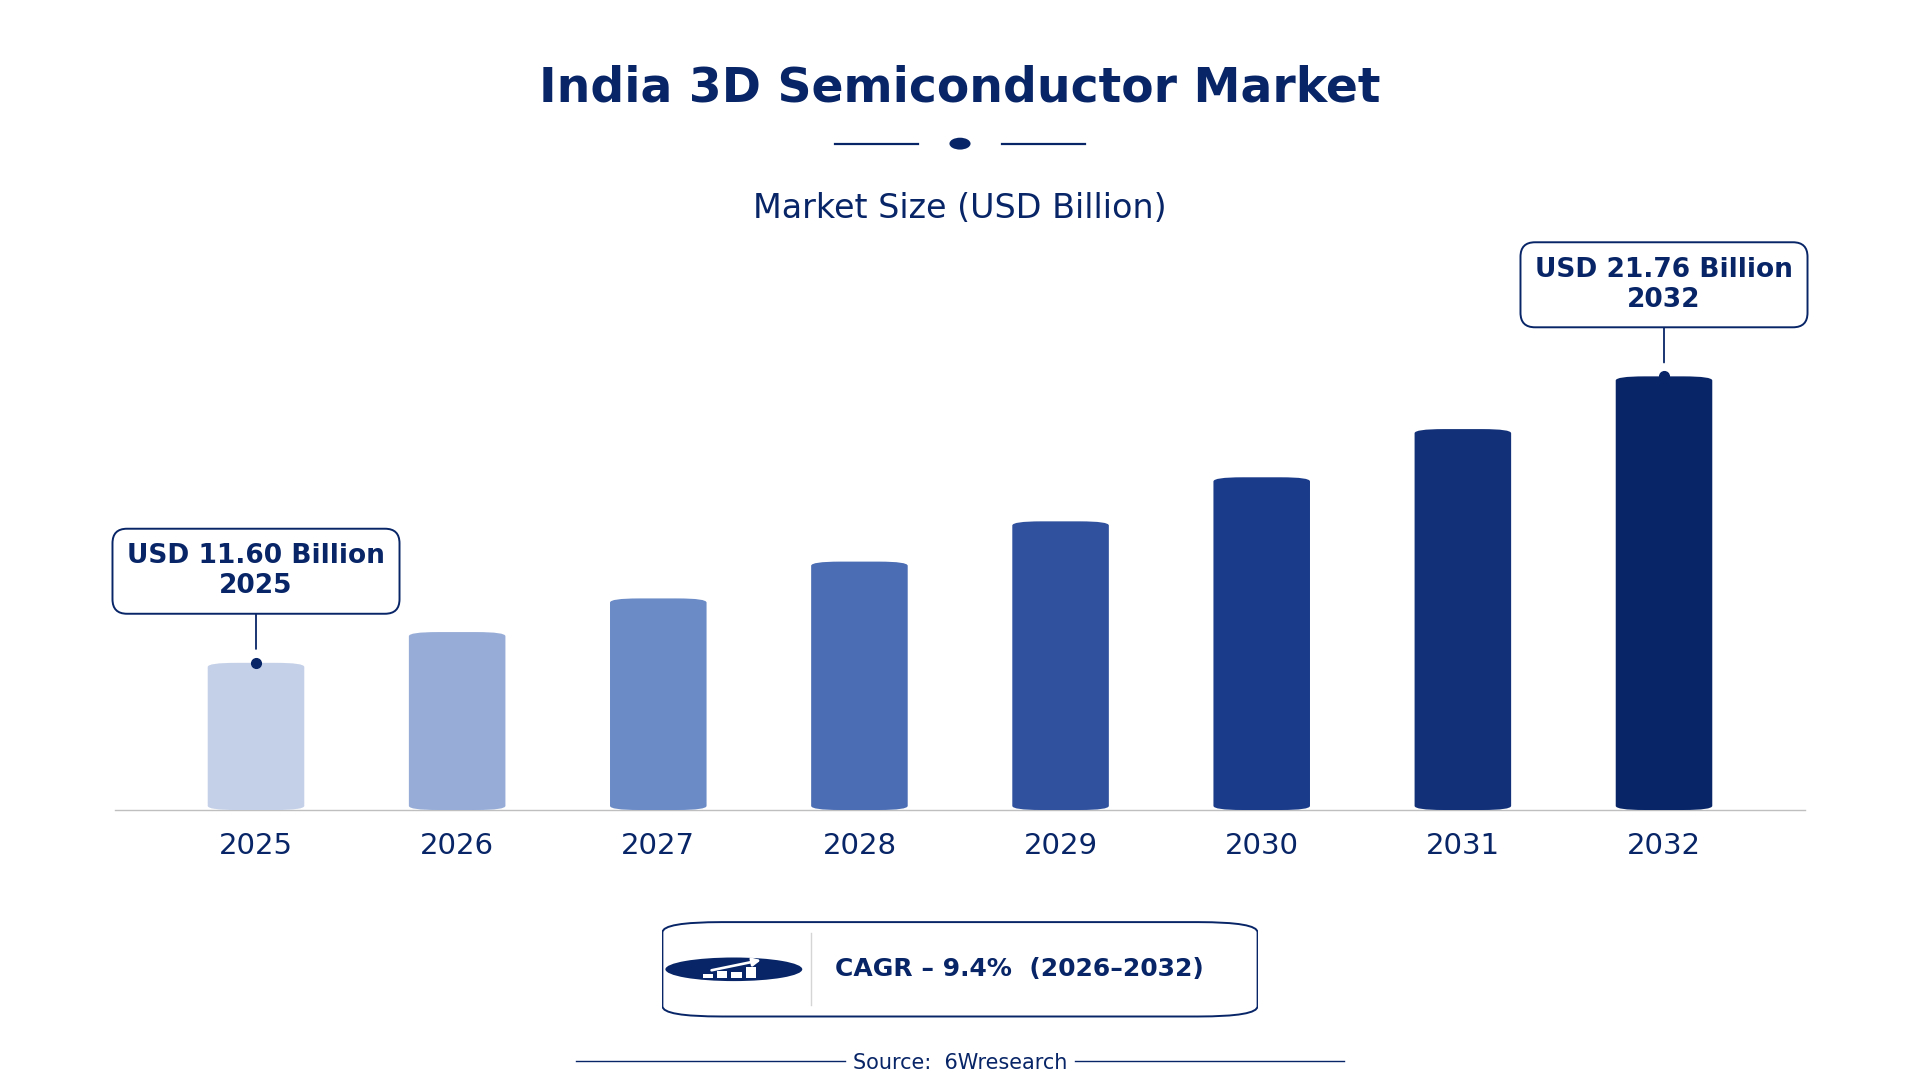
According to 6Wresearch internal database and industry insights, the India 3D Semiconductor Market was valued at USD 11.60 billion in 2025 and is projected to reach USD 21.76 billion by 2032, growing at a CAGR of approximately 9.4% during 2026–2032.
India 3D Semiconductor Market Highlights
| Report Metric | Details |
| Report Name | India 3D Semiconductor Market |
| Market Size 2025 | USD 11.60 billion |
| Market Size 2032 | USD 21.76 billion |
| Absolute Growth 2025–2032 | USD 10.16 billion |
| CAGR 2026–2032 | 9.4% |
| Peak Annual Growth | 11.2% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Technology Type, 2025 | 3D TSV (36% share) |
| Leading Packaging Type, 2025 | Chip-Stacking (42% share) |
| Leading Wafer Type, 2025 | Silicon Wafer (45% share) |
| Leading Distribution Channel, 2025 | Direct Sales (47% share) |
| Leading End User Industry, 2025 | Data Centers (35% share) |
| Fastest-Growing Technology Type | Hybrid Bonding (11.6% CAGR) |
| Fastest-Growing Wafer Type | Epitaxial Wafer (11.2% CAGR) |
| Fastest-Growing Distribution Channel | Contract Manufacturing (11.4% CAGR) |
| Fastest-Growing End User Industry | IoT Devices (10.6% CAGR) |
| Growing Sector | Data Centers |
| Key End Users | Data Centers, Consumer Electronics, Automotive Electronics, IoT Devices |
India 3D Semiconductor Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
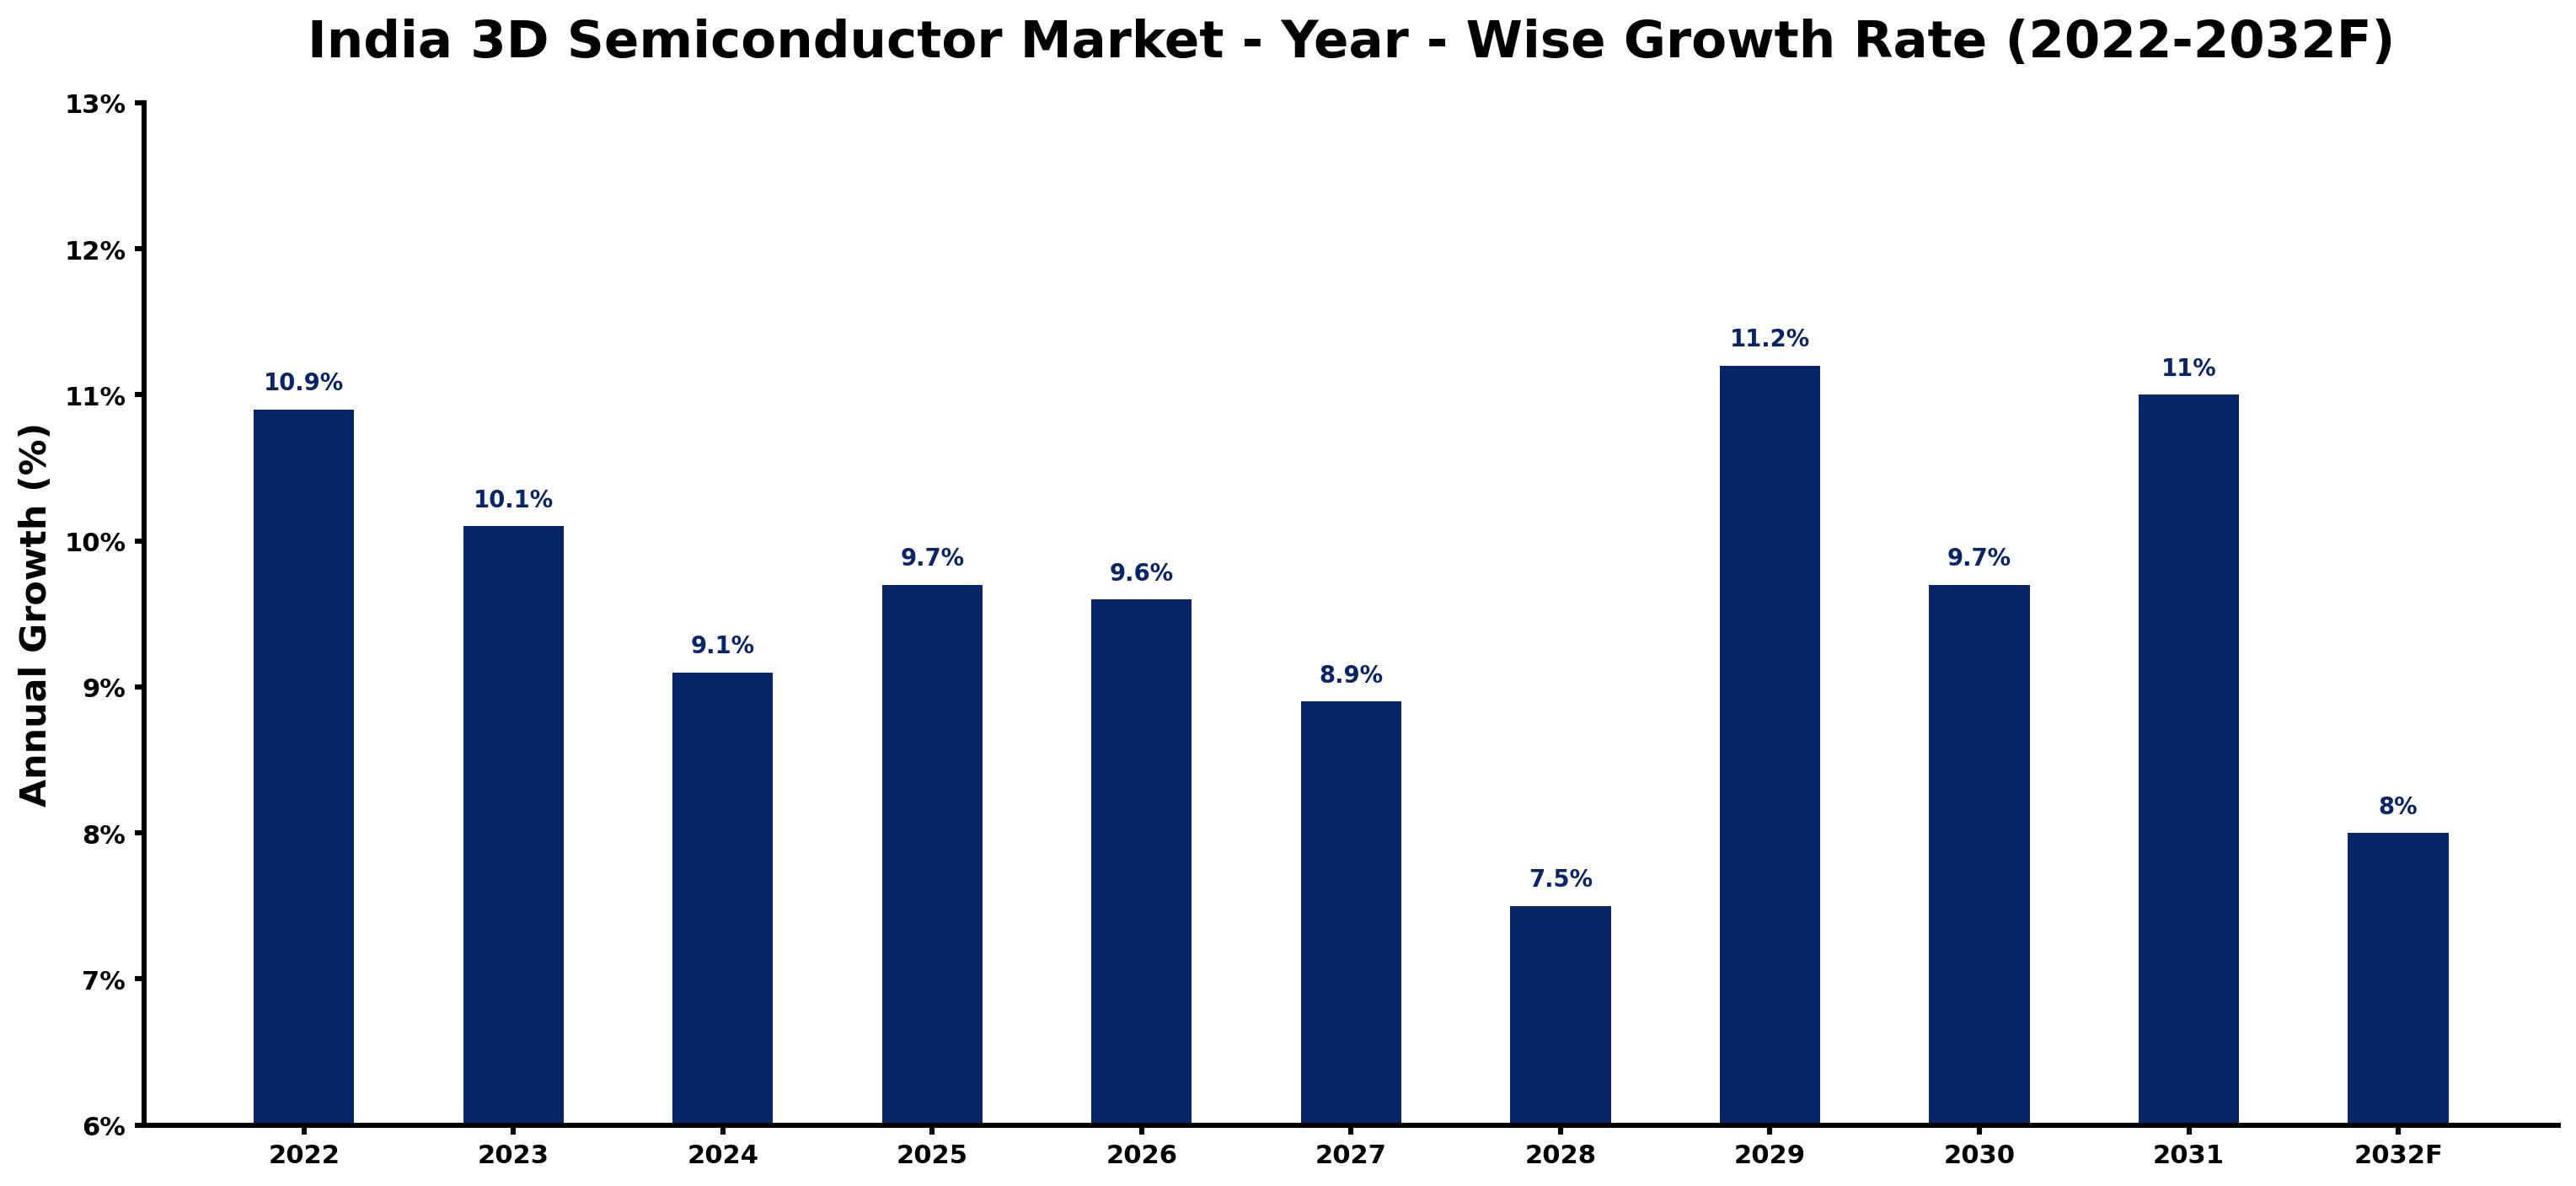
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 10.9 | The market experienced strong demand from data centers and consumer electronics sectors. |
| 2023 | 10.1 | Growth slowed due to supply chain disruptions affecting semiconductor production. |
| 2024 | 9.1 | Demand continued to slow as manufacturers adjusted to market conditions. |
| 2025 | 9.7 | A rebound in consumer electronics and automotive electronics drove growth. |
| 2026 | 9.6 | The market is expected to face a slowdown as production capacities stabilise due to the Semiconductor Mission's implementation. |
| 2027 | 8.9 | Demand growth will decelerate as the market adjusts to new technologies and the National Electronics Policy takes effect. |
| 2028 | 7.5 | A continued slowdown is expected as competition intensifies in the semiconductor sector. |
| 2029 | 11.2 | Growth will accelerate as investments in semiconductor fabs increase, supported by the government's initiatives. |
| 2030 | 9.7 | The market will decelerate as global supply chain issues persist, impacting production timelines. |
| 2031 | 11.0 | Demand will surge again due to rising investments in IoT devices and automotive electronics. |
| 2032 | 8.0 | The market is expected to slow as it reaches a more mature phase with established local manufacturing. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India 3D Semiconductor Market Synopsis
The 3D Semiconductor market in India encompasses advanced electronic components designed to improve performance and efficiency. These semiconductors are produced using techniques like 3D TSV and hybrid bonding, primarily serving data centers, consumer electronics, and automotive electronics. Strong domestic demand drives market expansion, supported by over 1.3 billion mobile subscribers and government initiatives like the Semiconductor Mission launched in 2021, which aims to boost local manufacturing and attract investments.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand from data centers for high-performance computing drives semiconductor purchases. | Driver | High | Data Centers |
| Increasing adoption of IoT devices creates a need for advanced semiconductors. | Driver | High | IoT Devices |
| Investment in semiconductor manufacturing facilities presents opportunities for growth. | Opportunity | High | 3D TSV |
| The growing automotive electronics sector is seeking advanced semiconductor solutions. | Opportunity | Medium | Automotive Electronics |
| Supply chain disruptions have delayed semiconductor production timelines. | Restraint | High | 3D TSV |
| High production costs limit the competitiveness of local manufacturers. | Restraint | Medium | 3D TSV |
| Talent shortages in the semiconductor workforce hinder production capabilities. | Challenge | High | 3D TSV |
| Technological advancements require continuous investment, straining budgets. | Challenge | Medium | 3D TSV |
Evaluation of Drivers in India 3D Semiconductor Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investment in data centers is driving demand for 3D semiconductors. | Data Centers | The data center sector is projected to grow by 20% annually, increasing semiconductor purchases for high-performance computing. |
| The rise of IoT devices is boosting the need for advanced semiconductor solutions. | IoT Devices | With over 1.5 billion smart devices expected by 2025, manufacturers are investing in high-performance semiconductors. |
| Government initiatives are enhancing local semiconductor manufacturing capabilities. | 3D TSV | The Semiconductor Mission aims to attract $10 billion in investments, improving local production capacity. |
| The automotive electronics sector is expanding, requiring advanced semiconductor technologies. | Automotive Electronics | With electric vehicle sales projected to reach 1 million units by 2025, demand for semiconductors in automotive applications is increasing. |
| Consumer electronics demand is propelling semiconductor sales across various applications. | Consumer Electronics | India's large mobile subscriber base, exceeding 1.3 billion, fuels the need for advanced semiconductor components. |
The 3D Semiconductor market in India is expanding as demand from data centers, IoT devices, and consumer electronics rises. In 2021, the Semiconductor Mission attracted $10 billion in investments, boosting local manufacturing capabilities. Rapid growth in the data center sector leads to increased semiconductor purchases for high-performance computing. The automotive electronics sector is evolving, requiring advanced semiconductor technologies to support the rise of electric vehicles. With over 1.5 billion smart devices expected by 2025, consumer electronics demand continues to drive sales across various applications.
Evaluation of Restraints in India 3D Semiconductor Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions have delayed semiconductor production timelines. | 3D TSV | In recent years, global supply issues have caused delays in semiconductor manufacturing, impacting delivery schedules. |
| High production costs limit the competitiveness of local manufacturers. | 3D TSV | Manufacturers face rising costs, with production expenses increasing by 15% over the past year, affecting their ability to compete. |
| Talent shortages in the semiconductor workforce hinder production capabilities. | 3D TSV | The Electronics Sector Skill Council of India trains over 100,000 individuals annually, but demand still exceeds supply, leading to a skills gap. |
| Technological advancements require continuous investment, straining budgets. | 3D TSV | Manufacturers must invest heavily in R&D, with costs rising to 10% of revenue to keep pace with rapid technological changes. |
| Regulatory compliance can delay product launches and increase costs. | 3D TSV | The Bureau of Indian Standards has set specifications that manufacturers must adhere to, impacting timelines and increasing compliance costs. |
India 3D Semiconductor Market Challenges
The 3D semiconductor market in India still has to solve a few problems, starting with competition from established global players, which pressures local producers to lower prices and can reduce their profit margins. Buyers face procurement delays due to inconsistent supply chains, which can extend lead times for crucial components and postpone product launches by several weeks. A shortage of skilled workers in the industry results in training costs that can increase expenses for producers by approximately 20%. Supply chain disruptions further complicate matters, as delays in material availability can set back production schedules by weeks, negatively affecting sales for buyers.
Trends in the India 3D Semiconductor Market
The trends below show where the India 3D Semiconductor Market is heading.
- Shift Towards Hybrid Bonding: The adoption of hybrid bonding technology is increasing, improving performance in semiconductor packaging. This shift is evident as the hybrid bonding segment is expected to grow at 11.6% CAGR, reflecting the industry's focus on efficiency.
- Rise of IoT Devices: The demand for IoT devices is surging, resulting in increased semiconductor sales. With a projected growth rate of 10.6% for IoT devices, manufacturers are focusing on developing advanced semiconductors to meet this demand.
- Expansion of Data Center Infrastructure: Investment in data center infrastructure is accelerating, driving the need for high-performance semiconductors. The data center segment is expected to hold a 35% market share, highlighting its critical role in the semiconductor market.
- Growth in Automotive Electronics: The automotive electronics sector is evolving rapidly, with increasing demand for advanced semiconductors. This sector is anticipated to grow significantly, driven by the rise of electric and connected vehicles.
Investment Opportunities in the India 3D Semiconductor Market
Investors looking at the India 3D Semiconductor Market should consider the following areas.
- Karnataka as a Semiconductor Hub: Karnataka is emerging as a major hub for semiconductor research and development, attracting investments. With $10 billion earmarked for semiconductor manufacturing, local partnerships can facilitate entry into this growing market.
- Investment in Semiconductor Manufacturing: The current demand for local semiconductor manufacturing presents substantial investment opportunities. The Semiconductor Mission aims to attract significant investments, making it an ideal time for stakeholders to engage.
- Growing Demand from Automotive Sector: The automotive sector is increasingly seeking advanced semiconductor solutions, creating opportunities for suppliers. With the rise in electric vehicles, manufacturers can focus on developing tailored semiconductor products.
- Expansion of Consumer Electronics Market: The consumer electronics market is expanding rapidly, driven by over 1.3 billion mobile subscribers. Suppliers can capitalise on this growth by providing innovative semiconductor solutions tailored to consumer needs.
Government Initiatives in the India 3D Semiconductor Market
The Semiconductor Mission launched by the Ministry of Electronics and Information Technology in 2021 aims to attract $10 billion in investments for semiconductor manufacturing. This initiative is crucial for enhancing local production capabilities and boosting the industry. The National Electronics Policy, updated in 2020, focuses on making India a global hub for electronics manufacturing, including semiconductors, and aims to create around 1 million jobs by 2025. This policy supports the growth of the semiconductor sector by promoting self-reliance and reducing import dependency.
The Electronics Sector Skill Council of India is responsible for enhancing skills in the semiconductor workforce. This agency trains over 100,000 individuals annually, ensuring a skilled workforce is available for future demands. The Ministry oversees various funding initiatives to support local manufacturing and innovation in the semiconductor sector, facilitating the development of advanced technologies and capabilities.
Future Insight of the India 3D Semiconductor Market
The 3D semiconductor market in India will evolve significantly by 2032, driven by several key factors. The Semiconductor Mission will bolster local manufacturing capabilities and promote self-sufficiency in production. Collaborations with global firms to establish semiconductor fabs will increase production capacity and efficiency. The National Policy on Electronics targets $300 billion in electronics manufacturing by 2025, which is projected to generate around 1 million jobs, thereby expanding the workforce and facilitating market growth.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Technology Type – 3D TSV Dominated, Hybrid Bonding Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, 3D TSV accounted for a 36% market share by technology type in 2025. 3D TSV technology holds the largest share in India due to its extensive use in high-density interconnects, which are vital for enhancing performance in advanced electronic applications. This technology is especially prevalent in data centres, where efficiency and reliability are paramount. The quickest growth will come from Hybrid Bonding, forecast to expand at a CAGR of 11.6% between 2026 and 2032. Hybrid Bonding is seeing rapid growth as it allows for high-performance stacking of chips, essential for compact designs in consumer electronics. This method meets the industry's increasing demand for maximising space and efficiency in product development. Suppliers should focus on advancing 3D TSV and Hybrid Bonding technologies to meet the rising demand in the Indian 3D semiconductor market.
By Packaging Type – Chip-Stacking Dominated and Is Expected to Record the Fastest Growth
In 2025, Chip-Stacking led the packaging type split with a 42% share. Chip-Stacking leads the packaging segment because it significantly enhances functionality while reducing the footprint of electronic devices. This method is particularly beneficial in sectors that require compact designs, such as consumer electronics. The same category is also set to grow fastest, at a CAGR of 11.6% during 2026–2032. Chip-Stacking is also the fastest-growing packaging type, driven by the ongoing trend towards miniaturisation in electronic devices. As manufacturers aim for greater efficiency and compactness, the demand for this packaging solution is expected to increase. Investing in advanced Chip-Stacking technologies will be crucial for suppliers to capture the growing market opportunities in India.
By Wafer Type – Silicon Wafer Dominated, Epitaxial Wafer Expected to Grow Fastest
With a 45% revenue share in 2025, Silicon Wafer was the largest wafer type category. Silicon Wafer commands the largest share as it serves as the primary substrate for semiconductor fabrication, essential across various applications in the industry. Its established role in manufacturing processes reinforces its position within the semiconductor supply chain. Epitaxial Wafer is set to record the highest CAGR in this split, 11.2% over 2026–2032. Epitaxial Wafer is experiencing rapid growth due to its ability to enhance performance for specific applications, particularly in high-performance computing. This trend reflects the industry's shift towards more specialised semiconductor solutions. Vendors should consider expanding their product offerings to include Epitaxial Wafers to address the evolving requirements of the semiconductor market.
By Distribution Channel – Direct Sales Dominated, Contract Manufacturing Expected to Grow Fastest
Direct Sales held a 47% share of the India 3D Semiconductor Market by distribution channel in 2025. Direct Sales is the leading distribution channel as it allows manufacturers to engage directly with clients, ensuring effective communication and tailored solutions. This approach is particularly advantageous in the semiconductor industry, where technical specifications are crucial. Over 2026–2032, Contract Manufacturing is expected to post the fastest growth, at a CAGR of 11.4%. Contract Manufacturing is the fastest-growing channel, as companies increasingly outsource production to specialised firms to improve efficiency and reduce costs. This trend indicates a shift towards more flexible production strategies within the industry. Suppliers should explore partnerships with contract manufacturers to enhance their market presence and operational efficiency.
By End User Industry – Data Centers Dominated, IoT Devices Expected to Grow Fastest
The largest end user industry category in 2025 was Data Centers, with a 35% share of total revenue. Data Centers represent the largest end-user industry, driven by the demand for high-performance computing and storage solutions. The rapid growth of cloud services and data processing needs has solidified their position in the market. The quickest growth will come from IoT Devices, forecast to expand at a CAGR of 10.6% between 2026 and 2032. IoT Devices are the fastest-growing segment, reflecting the surge in smart devices and connectivity solutions. As the Internet of Things continues to expand, the demand for advanced semiconductor technologies in this sector will grow substantially. For suppliers, focusing on IoT applications will be vital to capture the burgeoning opportunities in the Indian 3D semiconductor market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India 3D Semiconductor Market Outlook
- Market Size of India 3D Semiconductor Market, 2025
- Forecast of India 3D Semiconductor Market, 2032
- Historical Data and Forecast of India 3D Semiconductor Revenues & Volume for the Period 2022 - 2032F
- India 3D Semiconductor Market Trend Evolution
- India 3D Semiconductor Market Drivers and Challenges
- India 3D Semiconductor Price Trends
- India 3D Semiconductor Porter's Five Forces
- India 3D Semiconductor Industry Life Cycle
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By 3D TSV for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Monolithic 3D IC for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Hybrid Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Fan-Out Packaging for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Chip-Stacking for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Wire Bonded for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Flip-Chip for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Package-on-Package for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Wafer Type for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Silicon-On-Insulator for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Silicon Wafer for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Bulk Silicon for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Epitaxial Wafer for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Online Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Contract Manufacturing for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Semiconductor Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By End User Industry for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Data Centers for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Consumer Electronics for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By IoT Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India 3D Semiconductor Market Revenues & Volume By Automotive Electronics for the Period 2022 - 2032F
- India 3D Semiconductor Import Export Trade Statistics
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By Wafer Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User Industry
- India 3D Semiconductor Top Companies Market Share
- India 3D Semiconductor Competitive Benchmarking By Technical and Operational Parameters
- India 3D Semiconductor Company Profiles
- India 3D Semiconductor Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Technology Type
- 3D TSV
- Monolithic 3D IC
- Hybrid Bonding
- Fan-Out Packaging
By Packaging Type
- Chip-Stacking
- Wire Bonded
- Flip-Chip
- Package-on-Package
By Wafer Type
- Silicon-On-Insulator
- Silicon Wafer
- Bulk Silicon
- Epitaxial Wafer
By Distribution Channel
- Direct Sales
- Online Distributors
- Contract Manufacturing
- Semiconductor Suppliers
By End User Industry
- Data Centers
- Consumer Electronics
- IoT Devices
- Automotive Electronics































