India 5G Cloud Service Market Size & Growth Rate
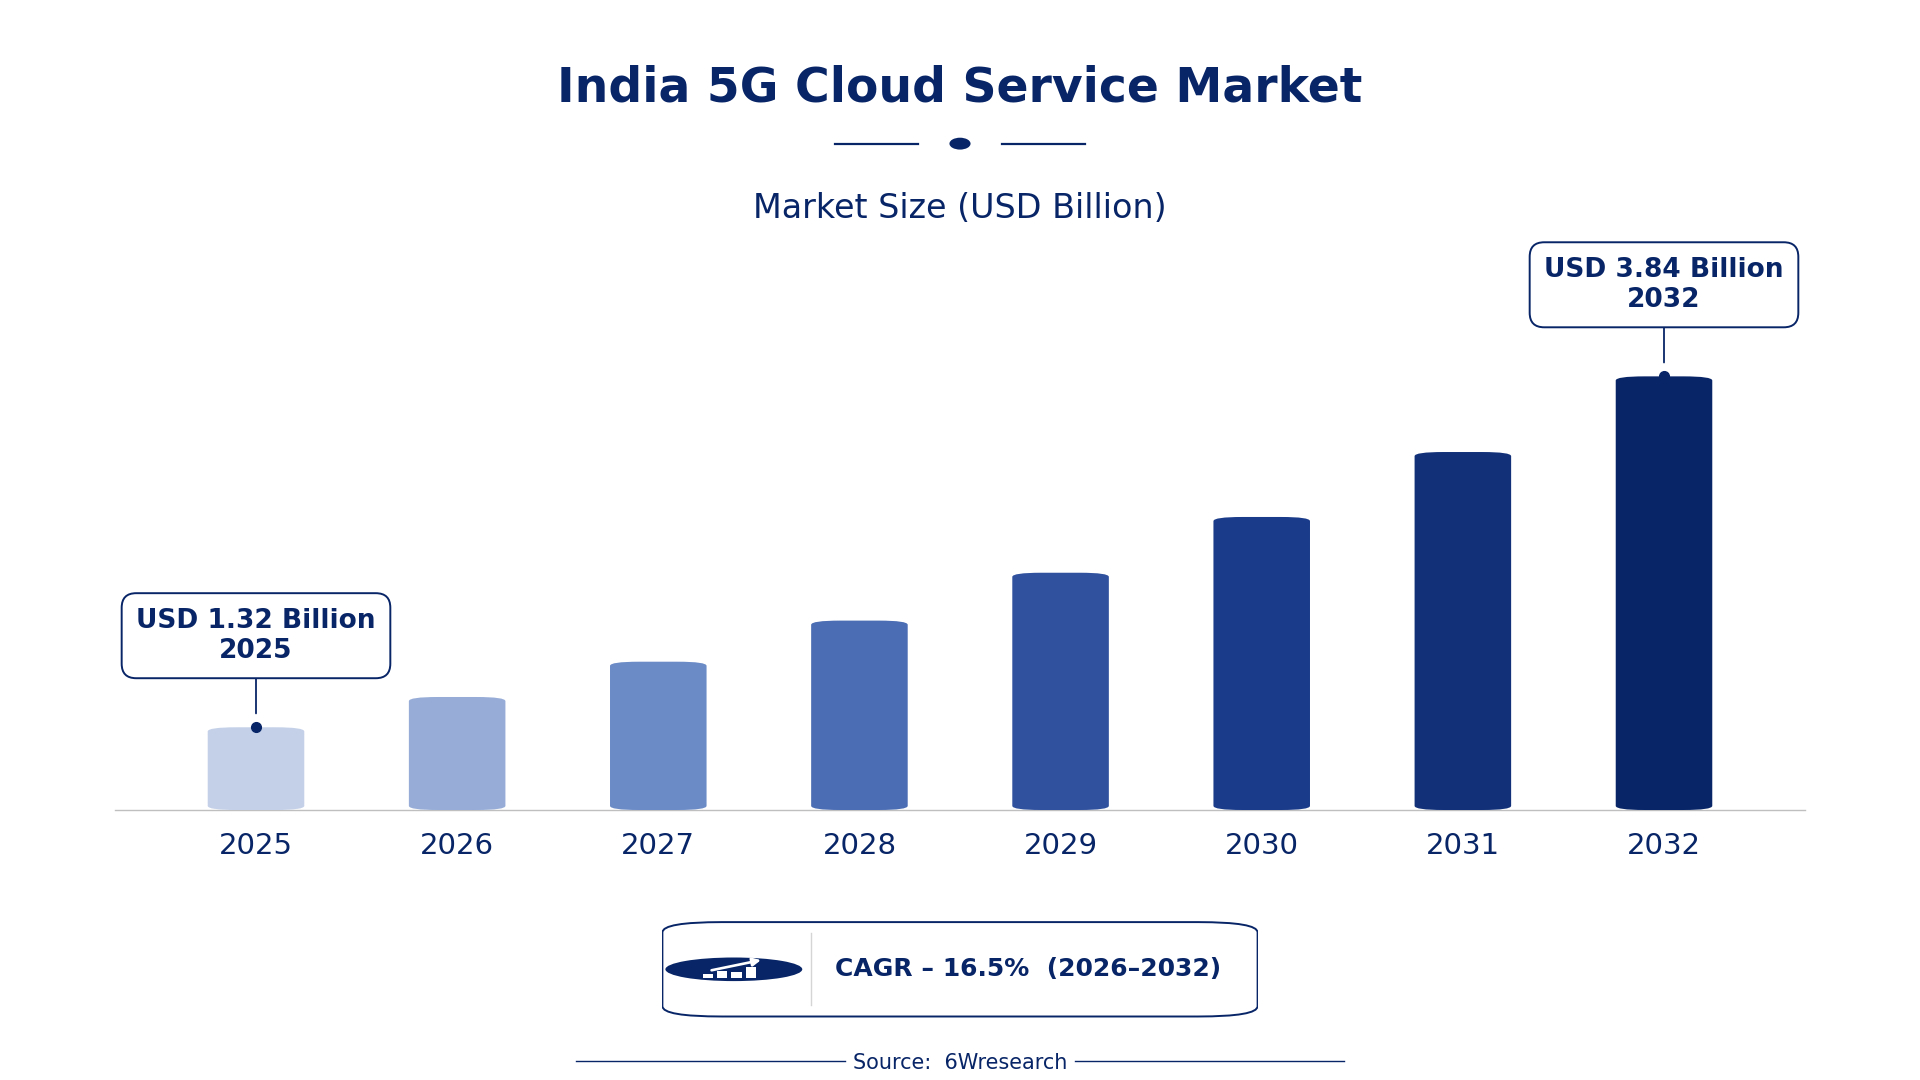
According to 6Wresearch internal database and industry insights, the India 5G Cloud Service Market was valued at USD 1.32 billion in 2025 and is projected to reach USD 3.84 billion by 2032, growing at a CAGR of approximately 16.5% during 2026–2032.
India 5G Cloud Service Market Highlights
| Report Metric | Details |
| Report Name | India 5G Cloud Service Market |
| Market Size 2025 | USD 1.32 billion |
| Market Size 2032 | USD 3.84 billion |
| Absolute Growth 2025–2032 | USD 2.52 billion |
| CAGR 2026–2032 | 16.5% |
| Peak Annual Growth | 18.2% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Service Type, 2025 | Network Slicing (47% share) |
| Leading Cloud Model, 2025 | IaaS (41% share) |
| Leading Deployment Type, 2025 | Public Cloud (53% share) |
| Leading End User, 2025 | Telecom Providers (35% share) |
| Leading Distribution Channel, 2025 | Direct Sales (38% share) |
| Fastest-Growing Service Type | Edge Cloud Services (18.5% CAGR) |
| Fastest-Growing Cloud Model | PaaS (18.6% CAGR) |
| Fastest-Growing Deployment Type | Hybrid Cloud (18.1% CAGR) |
| Fastest-Growing End User | Enterprise Customers (18.7% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (17.7% CAGR) |
| Growing Sector | Telecommunications |
| Key End Users | Telecom Providers, Enterprise Customers, Industrial Plants |
India 5G Cloud Service Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
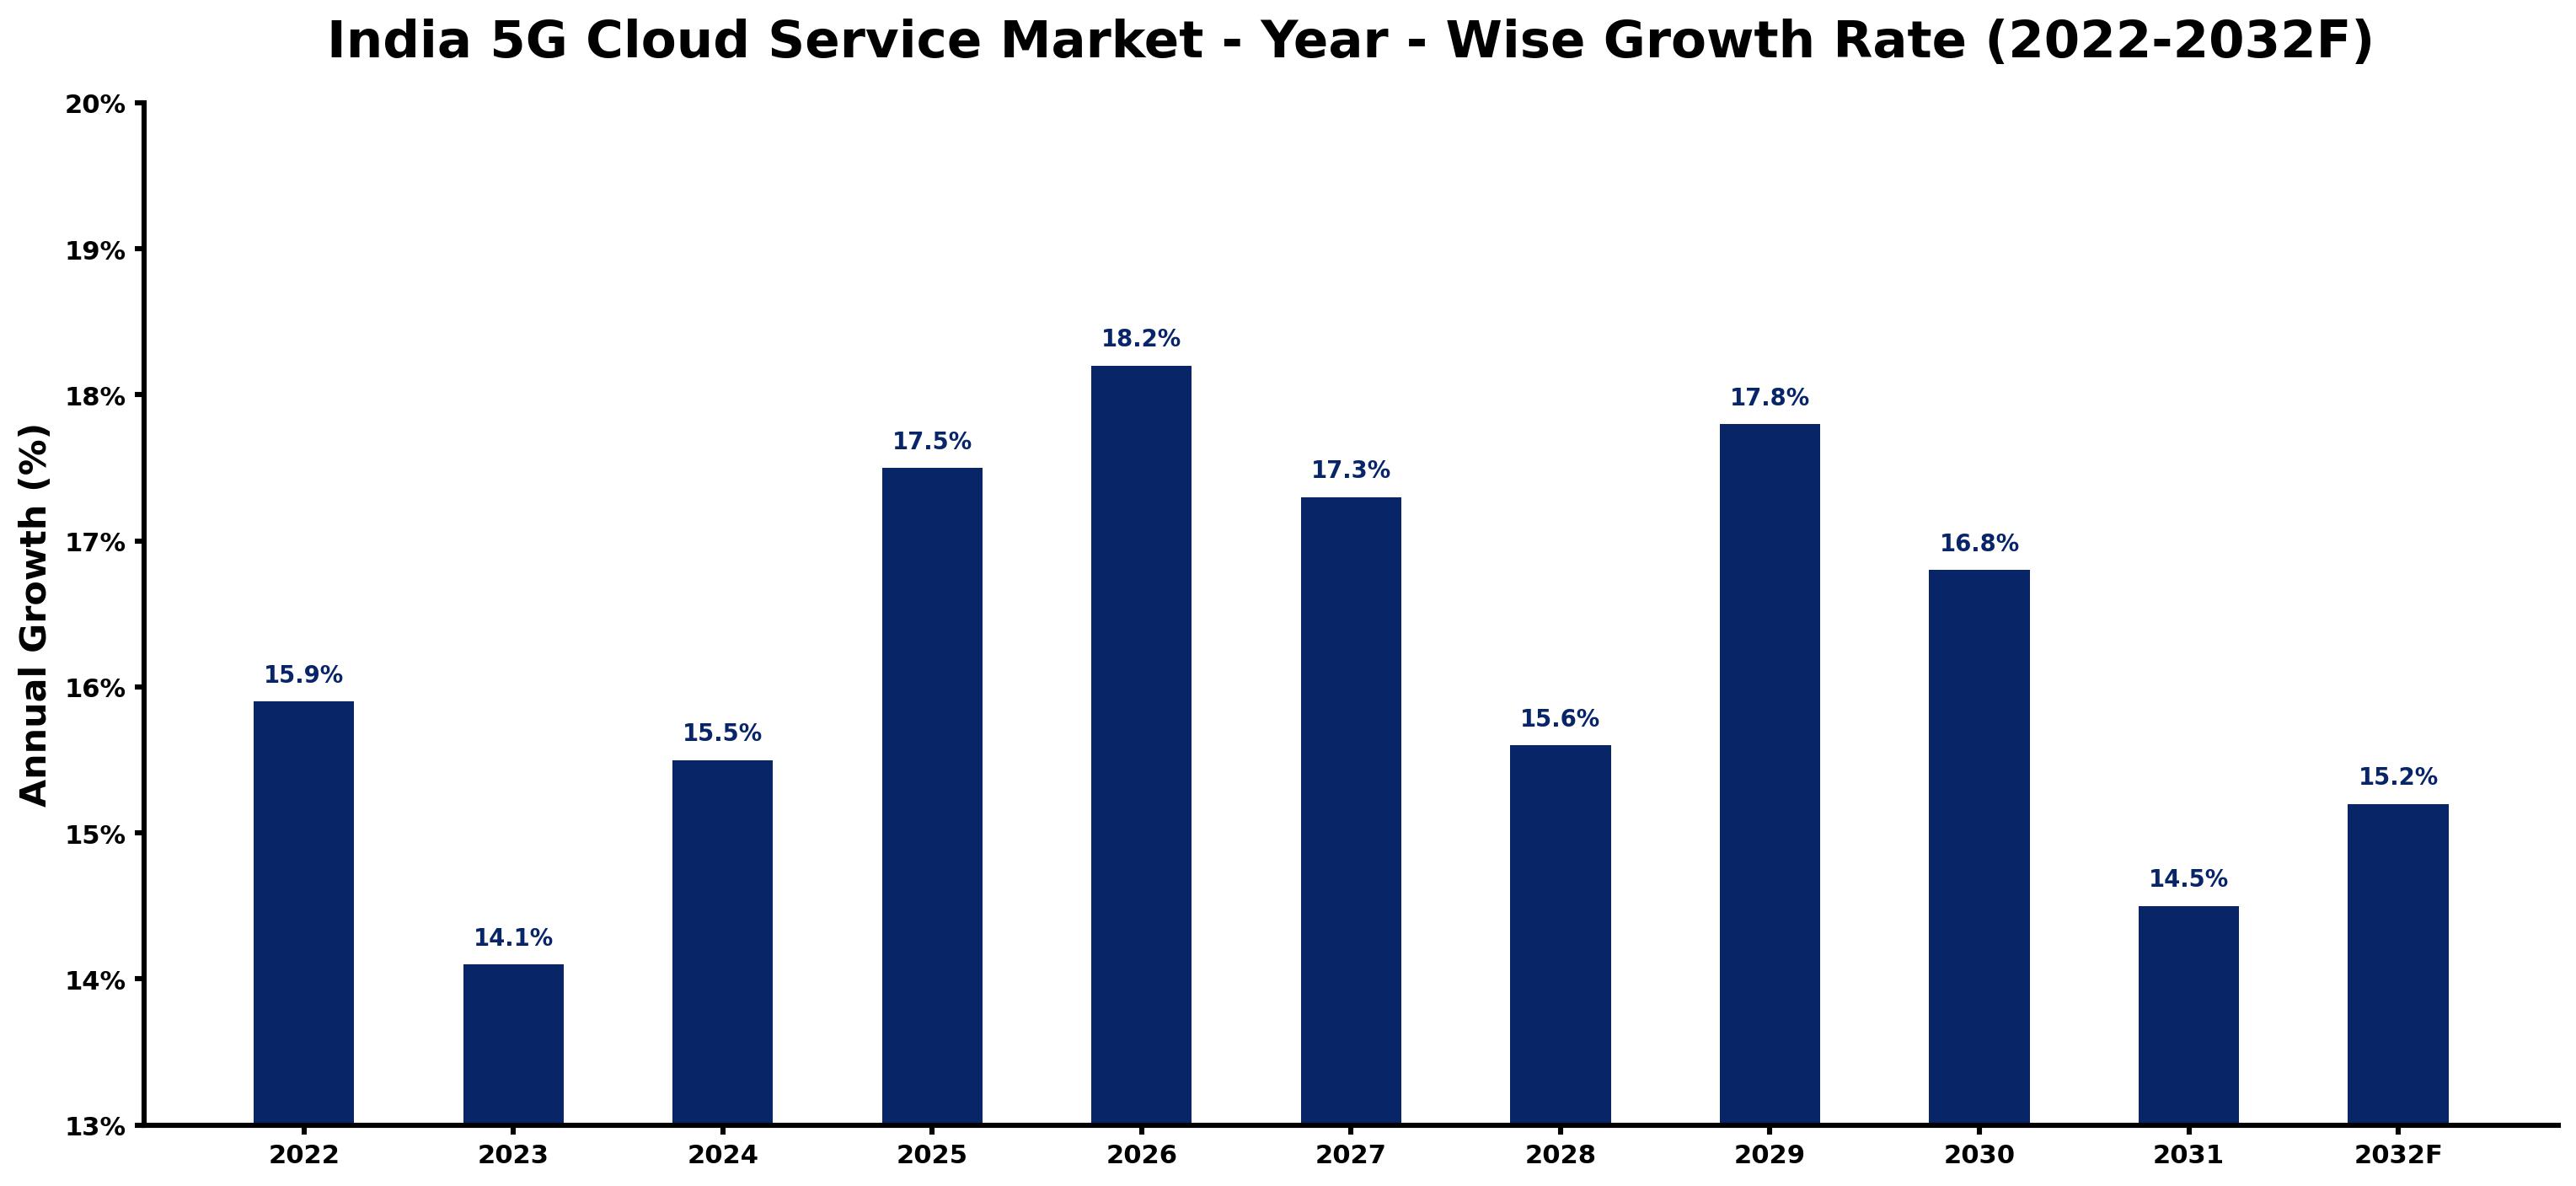
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 15.9 | The market displayed strong activity, driven by initial 5G deployments and infrastructure investments. |
| 2023 | 14.1 | Growth slowed as operators adjusted strategies following the 2022 spectrum auction. |
| 2024 | 15.5 | A rise in enterprise demand for 5G applications boosted growth rates. |
| 2025 | 17.5 | Increased adoption of 5G technology led to a surge in subscriber numbers and service uptake. |
| 2026 | 18.2 | The peak growth year is expected to see extensive investments in digital infrastructure and services, aided by the National Digital Communications Policy. |
| 2027 | 17.3 | A slight slowdown is projected as the market matures and competition intensifies, influenced by the growing number of telecom providers. |
| 2028 | 15.6 | Growth will continue but at a slower pace due to market saturation in urban areas, particularly among enterprise customers. |
| 2029 | 17.8 | Renewed interest in 5G applications for industrial automation is expected to spur demand again, particularly from industrial plants. |
| 2030 | 16.8 | A further slowdown is anticipated as the market stabilises after rapid expansion, influenced by the need for real-time data processing. |
| 2031 | 14.5 | Growth will continue to decelerate as the focus shifts to optimising existing networks, particularly for telecom providers. |
| 2032 | 15.2 | A slight uptick in growth is anticipated as new applications emerge and gain traction, driven by government support. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India 5G Cloud Service Market Synopsis
5G Cloud Service in India integrates advanced telecommunications with cloud computing, enabling faster data processing and storage. This market is projected to grow significantly, driven by a rapidly expanding 5G subscriber base expected to reach 500 million by 2025. Factors contributing to this growth include substantial government investments in digital infrastructure and the ongoing rollout of 5G services across urban and rural areas. The Telecom Regulatory Authority of India plays a key role in setting standards that facilitate this expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in digital infrastructure | Driver | High | Network Slicing |
| Increased demand from telecom providers for efficient network management | Driver | High | Virtual RAN |
| Growing need for low-latency applications in industries | Opportunity | High | Edge Cloud Services |
| Expanding urban population requiring enhanced connectivity | Opportunity | High | Telecom Providers |
| Challenges in spectrum allocation affecting service deployment | Restraint | High | Public Cloud |
| High initial investment costs for infrastructure development | Restraint | Medium | Private 5G Cloud |
| The 5G Cloud Service market in India faces regulatory hurdles | Challenge | High | Edge Cloud Services |
| Competition from alternative technologies can hinder market growth | Challenge | Medium | Network Slicing |
Evaluation of Drivers in India 5G Cloud Service Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Government investment in digital infrastructure | Public Cloud | The government plans to invest INR 1 trillion in digital infrastructure by 2025, stimulating demand for cloud services. |
| Growth in 5G subscriber base | Telecom Providers | India's 5G subscriber base is expected to reach 500 million by 2025, driving demand for enhanced services. |
| Adoption of IoT applications | Edge Cloud Services | The need for real-time data processing in IoT applications is pushing telecom providers to adopt edge solutions. |
| Enterprise demand for operational efficiency | Private 5G Cloud | Enterprise customers are increasingly utilising dedicated networks to improve operational efficiency and security. |
| Development of 5G standards | Network Slicing | The Telecom Regulatory Authority of India sets standards that facilitate the deployment of 5G services. |
The 5G Cloud Service market in India is growing on the back of substantial investments in digital infrastructure, expanding capabilities, and increasing end-use demand. The anticipated surge in 5G subscribers, projected to reach 500 million by 2025, compels telecom providers to enhance their service offerings. Additionally, the rise in industrial automation is driving demand for dedicated private 5G networks, enabling enterprises to improve operational efficiency.
Evaluation of Restraints in India 5G Cloud Service Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory hurdles in spectrum allocation | Public Cloud | Delays in spectrum allocation can hinder timely deployment of 5G services, affecting service availability. |
| High initial investment costs for infrastructure | Private 5G Cloud | The substantial upfront costs deter smaller enterprises from adopting private 5G solutions. |
| Limited awareness among potential enterprise users | Edge Cloud Services | Many enterprises remain unaware of the benefits of edge computing, slowing adoption rates. |
| Competition from alternative technologies like Wi-Fi 6 | Network Slicing | The availability of alternative technologies can limit the appeal of 5G solutions for some users. |
| Market saturation in urban areas | Telecom Providers | As urban markets mature, growth opportunities become limited, affecting overall market expansion. |
India 5G Cloud Service Market Challenges
The India 5G Cloud Service market encounters high infrastructure costs that impose significant capital burdens on telecom operators, delaying service rollouts and restricting access for businesses and consumers. Producers face challenges due to rapid technological advancements, necessitating frequent updates to meet the standards set by the Telecom Regulatory Authority of India, complicating operations and raising costs. Buyers experience difficulties stemming from inconsistent service availability, as supply chain disruptions related to specific components hinder timely deployment of 5G capabilities. These issues limit enterprises' ability to fully leverage 5G for advanced mobile broadband and IoT applications.
Trends in the India 5G Cloud Service Market
Several trends are reshaping the India 5G Cloud Service Market; the most important are set out below.
- Shift towards Edge Computing in Urban Areas: Urban areas in India are experiencing a shift towards edge computing as demand for low-latency applications rises. The establishment of a 5G testbed in 2020 has supported this trend, with edge cloud services projected to grow at a CAGR of 18.5%.
- Transition from Traditional to Virtual RAN: The telecom sector is transitioning to Virtual RAN technologies, enabling more flexible network management. This shift is evidenced by the growing interest in virtual solutions, with a projected CAGR of 17.3% for this segment.
- Telecom Providers Prioritising Network Slicing: Telecom providers are increasingly prioritising network slicing to offer customised services. This approach is gaining traction, with network slicing expected to capture 47% of the market share by 2025.
- Rise of Hybrid Cloud Solutions: Hybrid cloud solutions are gaining popularity as businesses seek flexibility in their cloud strategies. The hybrid cloud segment is projected to grow at a CAGR of 18.1%, reflecting changing preferences among enterprises.
Investment Opportunities in the India 5G Cloud Service Market
Some of the investment opportunities in the India 5G Cloud Service Market are mentioned below.
- Telecom Providers Seeking Advanced Connectivity Solutions: Telecom providers are actively seeking advanced connectivity solutions to meet growing demand. With the urban population projected to reach 600 million by 2031, there is a significant opportunity for suppliers to provide tailored 5G solutions.
- Entry through Strategic Partnerships with Local Firms: Strategic partnerships with local firms present a viable entry route for new players in the market. With a projected market size of USD 3.84 billion by 2032, establishing collaborations can facilitate market entry.
- Gap in Low-Latency Solutions for Enterprises: There is a notable gap in low-latency solutions for enterprises, with increasing demand for real-time applications. Suppliers can target this gap by offering edge cloud services to enterprise customers.
- Investment in 5G Infrastructure Development: Investment in 5G infrastructure development is critical as demand continues to rise. With government backing and a growing subscriber base, suppliers can focus on providing innovative solutions for telecom providers.
Government Initiatives in the India 5G Cloud Service Market
The National Digital Communications Policy 2018 aims to facilitate the rollout of 5G services by 2022, improving access to digital services and encouraging innovation in telecommunications. The government plans to invest INR 1 trillion in digital infrastructure by 2025, which will greatly enhance capabilities for 5G Cloud Service buyers. This policy, backed by the Digital India programme, promotes the expansion of digital infrastructure across urban and rural areas, ensuring a thorough approach to 5G deployment.
The 5G Testbed initiative launched in 2020 promotes innovation and research in 5G technology, providing a platform for testing and validating 5G applications. The Department of Telecommunications ensures compliance and progress in 5G deployment, while the Ministry of Electronics and Information Technology supports 5G initiatives, focusing on improving the software ecosystem for 5G applications. This collaborative approach encourages stakeholders to develop new applications and services, benefiting both producers and buyers.
Future Insight of the India 5G Cloud Service Market
By 2032, buyers and suppliers in the India 5G Cloud Service market can anticipate transformative changes driven by government initiatives and technological advancements. The National Digital Communications Policy aims for a comprehensive 5G rollout, while the government's planned investment of INR 1 trillion in digital infrastructure will significantly enhance capabilities. The establishment of a 5G testbed will encourage innovation, enabling startups to create new applications. With India's 5G subscriber base projected to reach 500 million by 2025, the surge in demand will create substantial opportunities for telecom operators and improve user experiences.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Service Type – Network Slicing Dominated, Edge Cloud Services Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Network Slicing took a 47% share of service type in 2025, more than any other category. Network Slicing holds the largest share in the India 5G Cloud Service Market as it allows telecom providers to allocate network resources tailored for various applications. This capability is crucial for sectors like IoT, where specific performance requirements must be met. The quickest growth will come from Edge Cloud Services, forecast to expand at a CAGR of 18.5% between 2026 and 2032. Edge Cloud Services is experiencing rapid growth due to its ability to reduce latency by processing data closer to the source, which is essential for real-time applications. As the demand for immediate data processing increases, this segment is set for significant expansion. Suppliers should focus on developing solutions that enhance network slicing and edge cloud capabilities to meet the rising market demand.
By Cloud Model – IaaS Dominated, PaaS Expected to Grow Fastest
IaaS held a 41% share of the India 5G Cloud Service Market by cloud model in 2025. IaaS commands the largest market share as it meets the infrastructure needs of telecom providers, facilitating the deployment of essential 5G services. Its role in providing scalable resources is critical for the ongoing development of cloud capabilities within the telecom sector. Over 2026–2032, PaaS are expected to post the fastest growth, at a CAGR of 18.6%. PaaS is witnessing the fastest growth as it enables enterprise customers to efficiently develop and deploy applications, aligning with the increasing demand for tailored solutions. This trend signals a shift towards more integrated cloud services in the 5G ecosystem. Buyers should consider PaaS solutions to leverage the benefits of rapid application development and deployment.
By Deployment Type – Public Cloud Dominated, Hybrid Cloud Expected to Grow Fastest
Public Cloud accounted for a 53% market share by deployment type in 2025. Public Cloud leads in market share as it provides scalable resources essential for telecom providers implementing 5G services. Its widespread adoption highlights the need for flexible infrastructure in a rapidly changing digital landscape. Hybrid Cloud is set to record the highest CAGR in this split, 18.1% over 2026–2032. Hybrid Cloud is growing quickly as it combines the benefits of both public and private clouds, allowing enterprises to optimise operations while protecting sensitive data. This flexibility is increasingly attractive to businesses navigating the complexities of 5G. Suppliers should enhance their hybrid cloud offerings to cater to the diverse needs of businesses transitioning to 5G.
By End User – Telecom Providers Dominated, Enterprise Customers Expected to Grow Fastest
The largest end user category in 2025 was Telecom Providers, with a 35% share of total revenue. Telecom Providers dominate the market share as they are the primary users of 5G Cloud Services, directly utilising these technologies to enhance their service offerings. Their considerable investments in 5G infrastructure significantly drive the demand for cloud services tailored to their operational requirements. Enterprise Customers are projected to grow fastest, at a CAGR of 18.7% during 2026–2032. Enterprise Customers represent the fastest-growing segment, leveraging 5G Cloud Services to improve operational efficiency and stimulate innovation within their organisations. As more enterprises recognise the advantages of these services, their adoption is expected to surge. Suppliers must tailor their offerings to address the specific needs of enterprise customers to capture this growing market segment.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
With a 38% revenue share in 2025, Direct Sales was the largest distribution channel category. Direct Sales accounts for the largest share in the distribution of 5G Cloud Services, enabling direct engagement with telecom providers and customised solutions. This method ensures clients receive personalised support and services that meet their unique requirements. The quickest growth will come from Online Platforms, forecast to expand at a CAGR of 17.7% between 2026 and 2032. Online Platforms are rapidly gaining popularity as they offer convenient access to 5G Cloud Services, appealing to a wider audience and facilitating quicker transactions. The ease of online purchasing is becoming increasingly important in today's digital environment. Suppliers should invest in online sales strategies to broaden their customer base and enhance service accessibility.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India 5G Cloud Service Market Outlook
- Market Size of India 5G Cloud Service Market, 2025
- Forecast of India 5G Cloud Service Market, 2032
- Historical Data and Forecast of India 5G Cloud Service Revenues & Volume for the Period 2022 - 2032F
- India 5G Cloud Service Market Trend Evolution
- India 5G Cloud Service Market Drivers and Challenges
- India 5G Cloud Service Price Trends
- India 5G Cloud Service Porter's Five Forces
- India 5G Cloud Service Industry Life Cycle
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Network Slicing for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Edge Cloud Services for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Private 5G Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Virtual RAN for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Cloud Model for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By IaaS for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By PaaS for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By SaaS for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Custom Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Deployment Type for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Public Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Hybrid Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Private Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Community Cloud for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Telecom Providers for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Enterprise Customers for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Industrial Plants for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Network Infrastructure Firms for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Industrial Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India 5G Cloud Service Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- India 5G Cloud Service Import Export Trade Statistics
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Cloud Model
- Market Opportunity Assessment By Deployment Type
- Market Opportunity Assessment By End User
- Market Opportunity Assessment By Distribution Channel
- India 5G Cloud Service Top Companies Market Share
- India 5G Cloud Service Competitive Benchmarking By Technical and Operational Parameters
- India 5G Cloud Service Company Profiles
- India 5G Cloud Service Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Service Type
- Network Slicing
- Edge Cloud Services
- Private 5G Cloud
- Virtual RAN
By Cloud Model
- IaaS
- PaaS
- SaaS
- Custom Cloud
By Deployment Type
- Public Cloud
- Hybrid Cloud
- Private Cloud
- Community Cloud
By End User
- Telecom Providers
- Enterprise Customers
- Industrial Plants
- Network Infrastructure Firms
By Distribution Channel
- Direct Sales
- Online Platforms
- Industrial Suppliers
- Specialty Stores































