India Agri-Tech Software Market Size & Growth Rate
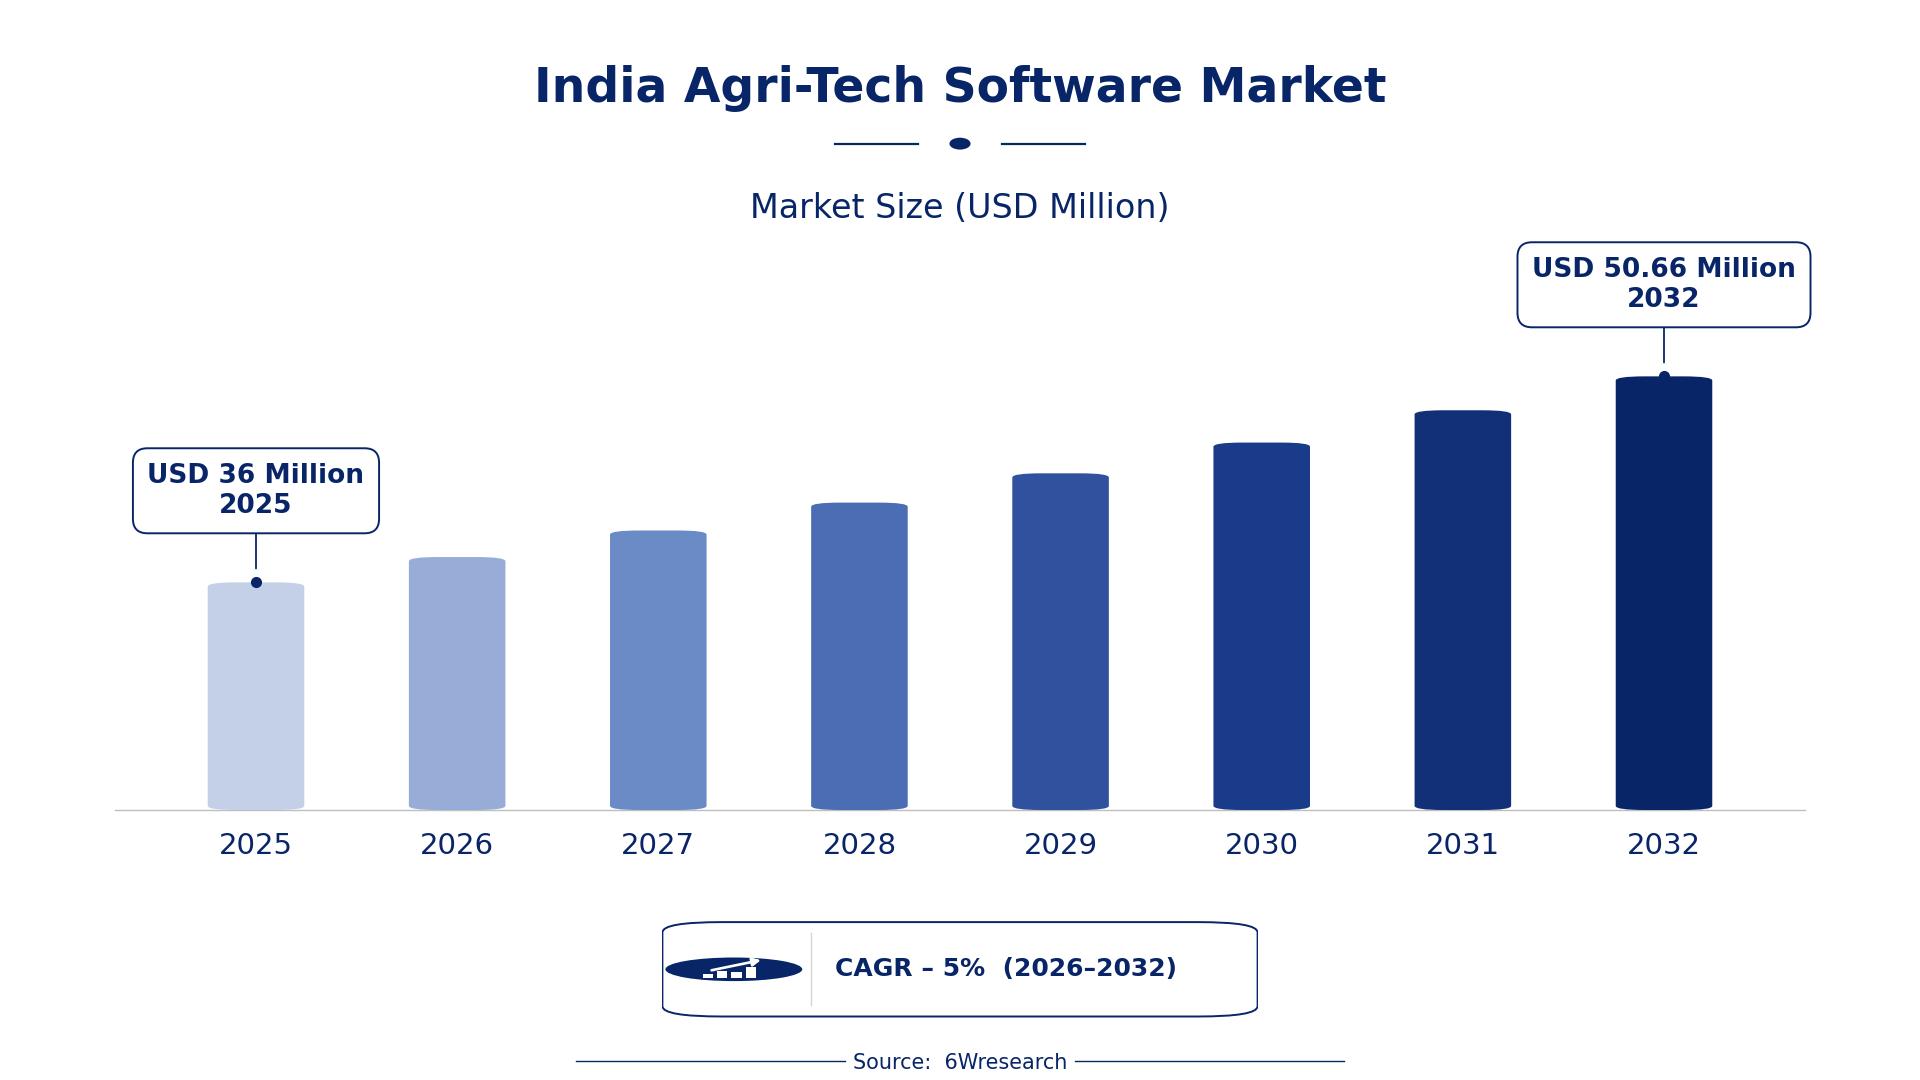
According to 6Wresearch internal database and industry insights, the India Agri-Tech Software Market was valued at USD 36.0 million in 2025 and is projected to reach USD 50.66 million by 2032, growing at a CAGR of approximately 5% during 2026–2032.
India Agri-Tech Software Market Highlights
| Report Metric | Details |
| Report Name | India Agri-Tech Software Market |
| Market Size 2025 | USD 36.0 million |
| Market Size 2032 | USD 50.66 million |
| Absolute Growth 2025–2032 | USD 14.66 million |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.2% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Software Type, 2025 | Farm Management System (38% share) |
| Leading Feature Focus, 2025 | Crop Planning (48% share) |
| Leading Distribution Channel, 2025 | Online Subscription (42% share) |
| Leading End User, 2025 | Agronomists & Farmers (47% share) |
| Fastest-Growing Software Type | Precision Ag Software (6.1% CAGR) |
| Fastest-Growing Feature Focus | Sensor Integration (7.1% CAGR) |
| Fastest-Growing Distribution Channel | B2B Platforms (7.7% CAGR) |
| Fastest-Growing End User | Smart Farm Operators (6.3% CAGR) |
| Growing Sector | Agriculture |
| Key End Users | Agronomists, Farmers, Agri Enterprises, Smart Farm Operators |
India Agri-Tech Software Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
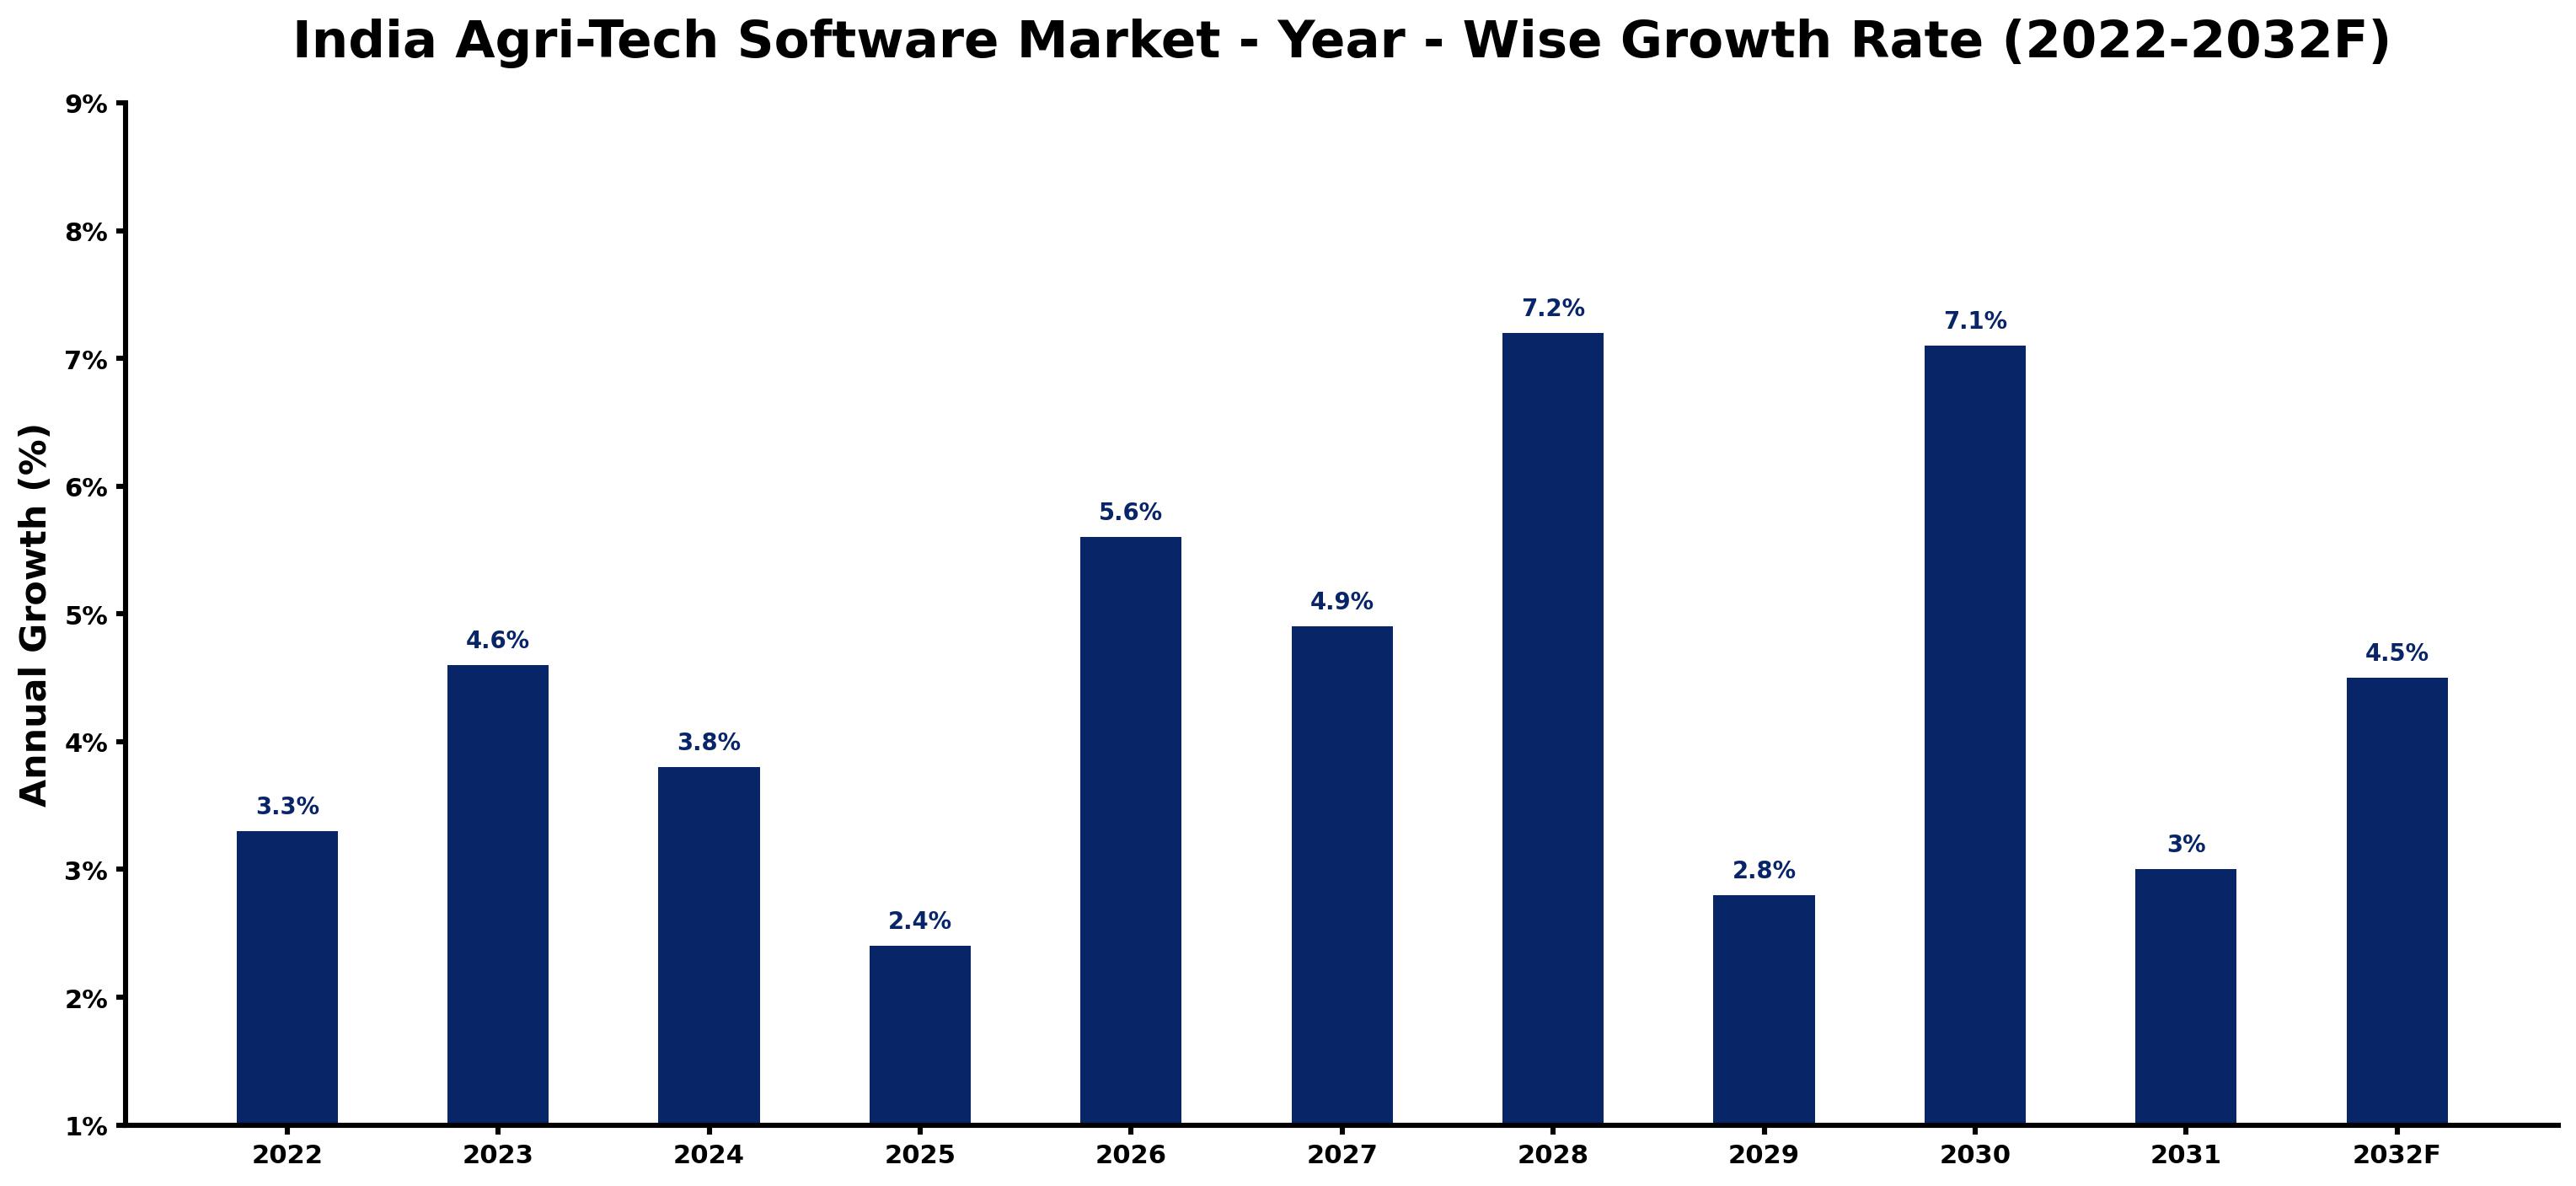
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.3 | The market experienced steady growth due to increased adoption of digital tools among farmers. |
| 2023 | 4.6 | Growth was driven by rising interest in precision agriculture tools in Punjab and Haryana. |
| 2024 | 3.8 | The market saw a slowdown as farmers adjusted to new technologies and practices. |
| 2025 | 2.4 | Growth slowed further as the 'Digital India' initiative began to take effect, promoting technology adoption. |
| 2026 | 5.6 | A resurgence in growth is expected with the introduction of new software solutions for farm management. |
| 2027 | 4.9 | The market is projected to experience a slight slowdown as existing users optimise their software usage. |
| 2028 | 7.2 | Growth is expected to peak as demand surges for advanced precision agriculture solutions. |
| 2029 | 2.8 | A slowdown is projected as the market begins to stabilise after peak adoption rates. |
| 2030 | 7.1 | Growth will accelerate again with increasing digital infrastructure and connectivity for farmers. |
| 2031 | 3.0 | The market is expected to slow as farmers focus on integrating existing tools into their operations. |
| 2032 | 4.5 | Growth is projected to rise as the government aims to digitise all agricultural records. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Agri-Tech Software Market Synopsis
Agri-Tech Software in India includes digital tools aimed at boosting agricultural productivity and efficiency. These solutions play a crucial role in farm management, precision agriculture, and optimising supply chains. The India Agri-Tech Software Market is growing as more farmers adopt digital farming tools, with over 70% currently using them. The 'Digital India' initiative, launched in 2020, has accelerated this trend by promoting technology in agriculture and improving access to these important resources.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing adoption of precision agriculture tools among farmers | Driver | High | Precision Ag Software |
| Growing demand for farm management solutions to optimise operations | Driver | High | Farm Management System |
| Emerging need for advanced data analytics in agriculture | Opportunity | High | Forecasting & Analysis |
| Rising interest in software integration for supply chain management | Opportunity | High | Supply Chain Mgmt |
| Limited digital literacy among some farmer demographics | Restraint | Medium | Farm Management System |
| High initial costs of implementing Agri-Tech solutions | Restraint | Medium | Farm Management System |
| Challenges in ensuring consistent internet connectivity in rural areas | Challenge | High | Precision Ag Software |
| Slow adaptation to new technologies by traditional farmers | Challenge | Medium | Agri Enterprises |
Evaluation of Drivers in India Agri-Tech Software Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising adoption of precision agriculture tools | Precision Ag Software | Over 70% of Indian farmers are using digital farming tools, increasing demand for precision solutions. |
| Growing interest in farm management systems | Farm Management System | Farm Management Systems are popular in Maharashtra and Karnataka, driving demand for effective resource management. |
| Government initiatives promoting technology in agriculture | Crop Planning | The 'Digital India' initiative has improved access to Agri-Tech solutions, boosting market growth. |
| Increasing mobile phone penetration facilitating software access | B2B Platforms | India's 600 million mobile phone users are enhancing connectivity for Agri-Tech software solutions. |
| Demand for data-driven insights in farming practices | Forecasting & Analysis | The National Agricultural Innovation Project supports research in Agri-Tech software, driving demand for analytical tools. |
Over 70% of farmers are now using digital tools, reshaping agricultural practices and leading to a surge in demand for precision solutions. Mobile connectivity is facilitating access to these tools, particularly among agronomists and farmers. The popularity of farm management systems in key agricultural regions is driving effective resource management. Ongoing support from the National Agricultural Innovation Project is ensuring that software solutions remain relevant and effective, further boosting market demand.
Evaluation of Restraints in India Agri-Tech Software Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited digital literacy among farmers | Farm Management System | Many farmers lack the necessary skills to utilise advanced digital tools effectively, hindering adoption rates. |
| High initial costs of Agri-Tech solutions | Farm Management System | The investment required for implementing these systems can be a barrier for small-scale farmers. |
| Inconsistent internet connectivity in rural areas | Precision Ag Software | Poor connectivity limits the effectiveness of cloud-based Agri-Tech solutions, affecting user experience. |
| Slow adaptation to technology by traditional farmers | Agri Enterprises | Some farmers are hesitant to shift from traditional practices to digital solutions, impacting market growth. |
| Regulatory hurdles in software approvals | ERP Solutions | Complex approval processes can delay the introduction of new Agri-Tech software to the market. |
India Agri-Tech Software Market Challenges
The India Agri-Tech Software market encounters high development costs, with expenses reaching up to ₹10 lakhs, which discourages small producers from adopting necessary technologies. Intense competition among software developers leads to price wars, compromising quality and ultimately affecting productivity for farmers. Rapid technological advancements necessitate frequent updates, making it challenging for producers to keep pace with innovations, which can hinder their growth. Furthermore, inconsistent internet connectivity in rural areas impacts over 70% of farmers, limiting their access to digital tools and restricting effective use of Agri-Tech solutions.
Trends in the India Agri-Tech Software Market
The trends below show where the India Agri-Tech Software Market is heading.
- Shift towards Precision Agriculture in Punjab and Haryana: Punjab and Haryana are increasingly adopting precision agriculture tools, with over 70% of farmers utilising digital solutions. This trend is reshaping farming practices and improving productivity.
- Transition from Traditional to Digital Farming Practices: Since 2020, farmers have been shifting from traditional methods to digital farming tools, driven by the 'Digital India' initiative. This transition has led to increased efficiency and productivity in agriculture.
- Agronomists Embracing Data-Driven Insights: Agronomists are increasingly using data analytics for crop forecasting and planning, supported by initiatives like the National Agricultural Innovation Project. This trend is improving decision-making in farming.
- Rise of B2B Platforms for Agri-Tech Solutions: B2B platforms are gaining traction as a distribution channel for Agri-Tech software, with a projected CAGR of 7.7%. This shift is facilitating better connections between software providers and users.
Investment Opportunities in the India Agri-Tech Software Market
Investors looking at the India Agri-Tech Software Market should consider the following areas.
- Supply of Precision Ag Software: The demand for precision agriculture tools is growing, with many farmers adopting digital solutions. Agronomists and farmers are key buyers, and partnerships with local firms can facilitate market entry.
- Investment in Farm Management Systems: The market for Farm Management Systems is expanding, driven by the need for efficient resource management. Collaborating with agricultural cooperatives can help reach farmers effectively.
- Development of Data Analytics Tools: There is a gap in data-driven insights for farmers, with increasing demand for forecasting tools. Agri research institutes are potential buyers, and certification can enhance credibility.
- Expansion of Digital Infrastructure: The government aims to digitise all agricultural records by 2025, creating opportunities for software providers. Engaging with local partners can facilitate access to this growing market.
Government Initiatives in the India Agri-Tech Software Market
The 'Digital India' initiative by the Ministry of Electronics and Information Technology, launched in 2020, aims to improve digital infrastructure in agriculture. This initiative promotes the use of technology in farming, enabling farmers to access digital tools and resources more effectively. The government has allocated ₹1,50,000 crores for agricultural development in 2023 to support this initiative, which is expected to drive the adoption of Agri-Tech solutions across the country. Furthermore, the 'National Mission on Agricultural Extension and Technology', initiated in 2021, focuses on integrating technology into farming practices, further supporting the growth of Agri-Tech software.
The Ministry of Agriculture and Farmers' Welfare oversees several schemes that facilitate technology adoption among farmers. The 'Soil Health Card Scheme', updated in 2022, provides farmers with data-driven insights into soil health, enabling better crop management. The 'Kisan Credit Card Scheme', revised in 2021, allows farmers to access credit through digital applications, easing financial constraints. These initiatives aim to empower farmers with the necessary tools and resources to improve productivity and efficiency in agriculture.
Future Insight of the India Agri-Tech Software Market
The India Agri-Tech Software market is set for transformative changes by 2032, driven by several pivotal factors. The 'Digital India' initiative will continue to propel technology adoption, targeting full digitisation of agricultural records by 2025. Improved mobile connectivity will enhance access to Agri-Tech solutions for the over 600 million mobile phone users in the country. Ongoing support from the National Agricultural Innovation Project will ensure that software development remains relevant, while the rise of precision agriculture will empower farmers through advanced data analytics and farm management tools.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Software Type – Farm Management System Dominated, Precision Ag Software Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the largest software type category in 2025 was Farm Management System, with a 38% share of total revenue. Farm Management Systems hold the largest share in the India Agri-Tech Software Market as they are crucial for managing farm operations and resources effectively. For instance, farmers in Maharashtra and Karnataka rely on these systems to streamline their agricultural practices and boost productivity. Precision Ag Software is set to record the highest CAGR in this split, 6.1% over 2026–2032. Precision Ag Software is experiencing rapid growth due to its ability to optimise crop yields and resource use, particularly in Punjab and Haryana where precision agriculture tools are becoming increasingly popular. This growth trend indicates a shift towards data-driven farming methods that will likely continue to expand. Suppliers should prioritise the development of precision agriculture solutions to meet the rising demand in the market.
By Feature Focus – Crop Planning Dominated, Sensor Integration Expected to Grow Fastest
With a 48% revenue share in 2025, Crop Planning was the largest feature focus category. Crop Planning leads the feature focus in the India Agri-Tech Software Market as it is essential for scheduling planting and harvesting activities, enabling farmers to maximise productivity. This is particularly important in India, where timely agricultural operations can significantly influence success rates. The quickest growth will come from Sensor Integration, forecast to expand at a CAGR of 7.1% between 2026 and 2032. Sensor Integration is the fastest-growing feature, as it enhances data collection and decision-making in agriculture, becoming vital for farmers aiming to leverage technology for improved efficiency. The increasing adoption of digital farming tools underscores the importance of sensor integration in modern agriculture. Buyers should seek software that incorporates advanced sensor integration features to stay competitive in the agricultural sector.
By Distribution Channel – Online Subscription Dominated, B2B Platforms Expected to Grow Fastest
Online Subscription took a 42% share of distribution channel in 2025, more than any other category. Online Subscription is the leading distribution channel in the India Agri-Tech Software Market, offering a primary method for users to conveniently access software solutions. This model is well-suited to the growing number of mobile phone users in India, facilitating easier access to digital agricultural tools. B2B Platforms are projected to grow fastest, at a CAGR of 7.7% during 2026–2032. B2B Platforms are rapidly growing as they effectively connect businesses with software solutions, reflecting the trend of collaborative farming and shared resources among agricultural enterprises. This indicates a broader shift towards integrated agricultural practices that enhance efficiency. Suppliers need to strengthen their presence on B2B platforms to effectively engage their target audience and maximise market share.
By End User – Agronomists & Farmers Dominated, Smart Farm Operators Expected to Grow Fastest
Agronomists & Farmers accounted for a 47% market share by end user in 2025. Agronomists & Farmers represent the largest user group in the India Agri-Tech Software Market, as they are the primary users of these tools aimed at improving agricultural practices. Their direct involvement in farming makes the adoption of Agri-Tech software essential for advancing the industry. Over 2026–2032, Smart Farm Operators are expected to post the fastest growth, at a CAGR of 6.3%. Smart Farm Operators are the fastest-growing user segment, utilising software for advanced farming techniques that enhance productivity and sustainability. This trend signifies a movement towards more technologically proficient farming operations that can adapt to modern challenges. Suppliers should customise their offerings to cater to the specific needs of smart farm operators to capture this emerging market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Agri-Tech Software Market Outlook
- Market Size of India Agri-Tech Software Market, 2025
- Forecast of India Agri-Tech Software Market, 2032
- Historical Data and Forecast of India Agri-Tech Software Revenues & Volume for the Period 2022 - 2032F
- India Agri-Tech Software Market Trend Evolution
- India Agri-Tech Software Market Drivers and Challenges
- India Agri-Tech Software Price Trends
- India Agri-Tech Software Porter's Five Forces
- India Agri-Tech Software Industry Life Cycle
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Software Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Farm Management System for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By ERP Solutions for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Precision Ag Software for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Crop Modeling Tools for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Feature Focus for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Crop Planning for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Supply Chain Mgmt for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Sensor Integration for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Forecasting & Analysis for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Online Subscription for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By App Stores for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By B2B Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Agronomists & Farmers for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Agri Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Smart Farm Operators for the Period 2022 - 2032F
- Historical Data and Forecast of India Agri-Tech Software Market Revenues & Volume By Agri Research Institutes for the Period 2022 - 2032F
- India Agri-Tech Software Import Export Trade Statistics
- Market Opportunity Assessment By Software Type
- Market Opportunity Assessment By Feature Focus
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- India Agri-Tech Software Top Companies Market Share
- India Agri-Tech Software Competitive Benchmarking By Technical and Operational Parameters
- India Agri-Tech Software Company Profiles
- India Agri-Tech Software Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Software Type
- Farm Management System
- ERP Solutions
- Precision Ag Software
- Crop Modeling Tools
By Feature Focus
- Crop Planning
- Supply Chain Mgmt
- Sensor Integration
- Forecasting & Analysis
By Distribution Channel
- Online Subscription
- Direct Sales
- App Stores
- B2B Platforms
By End User
- Agronomists & Farmers
- Agri Enterprises
- Smart Farm Operators
- Agri Research Institutes































