India AgTech Market Size & Growth Rate
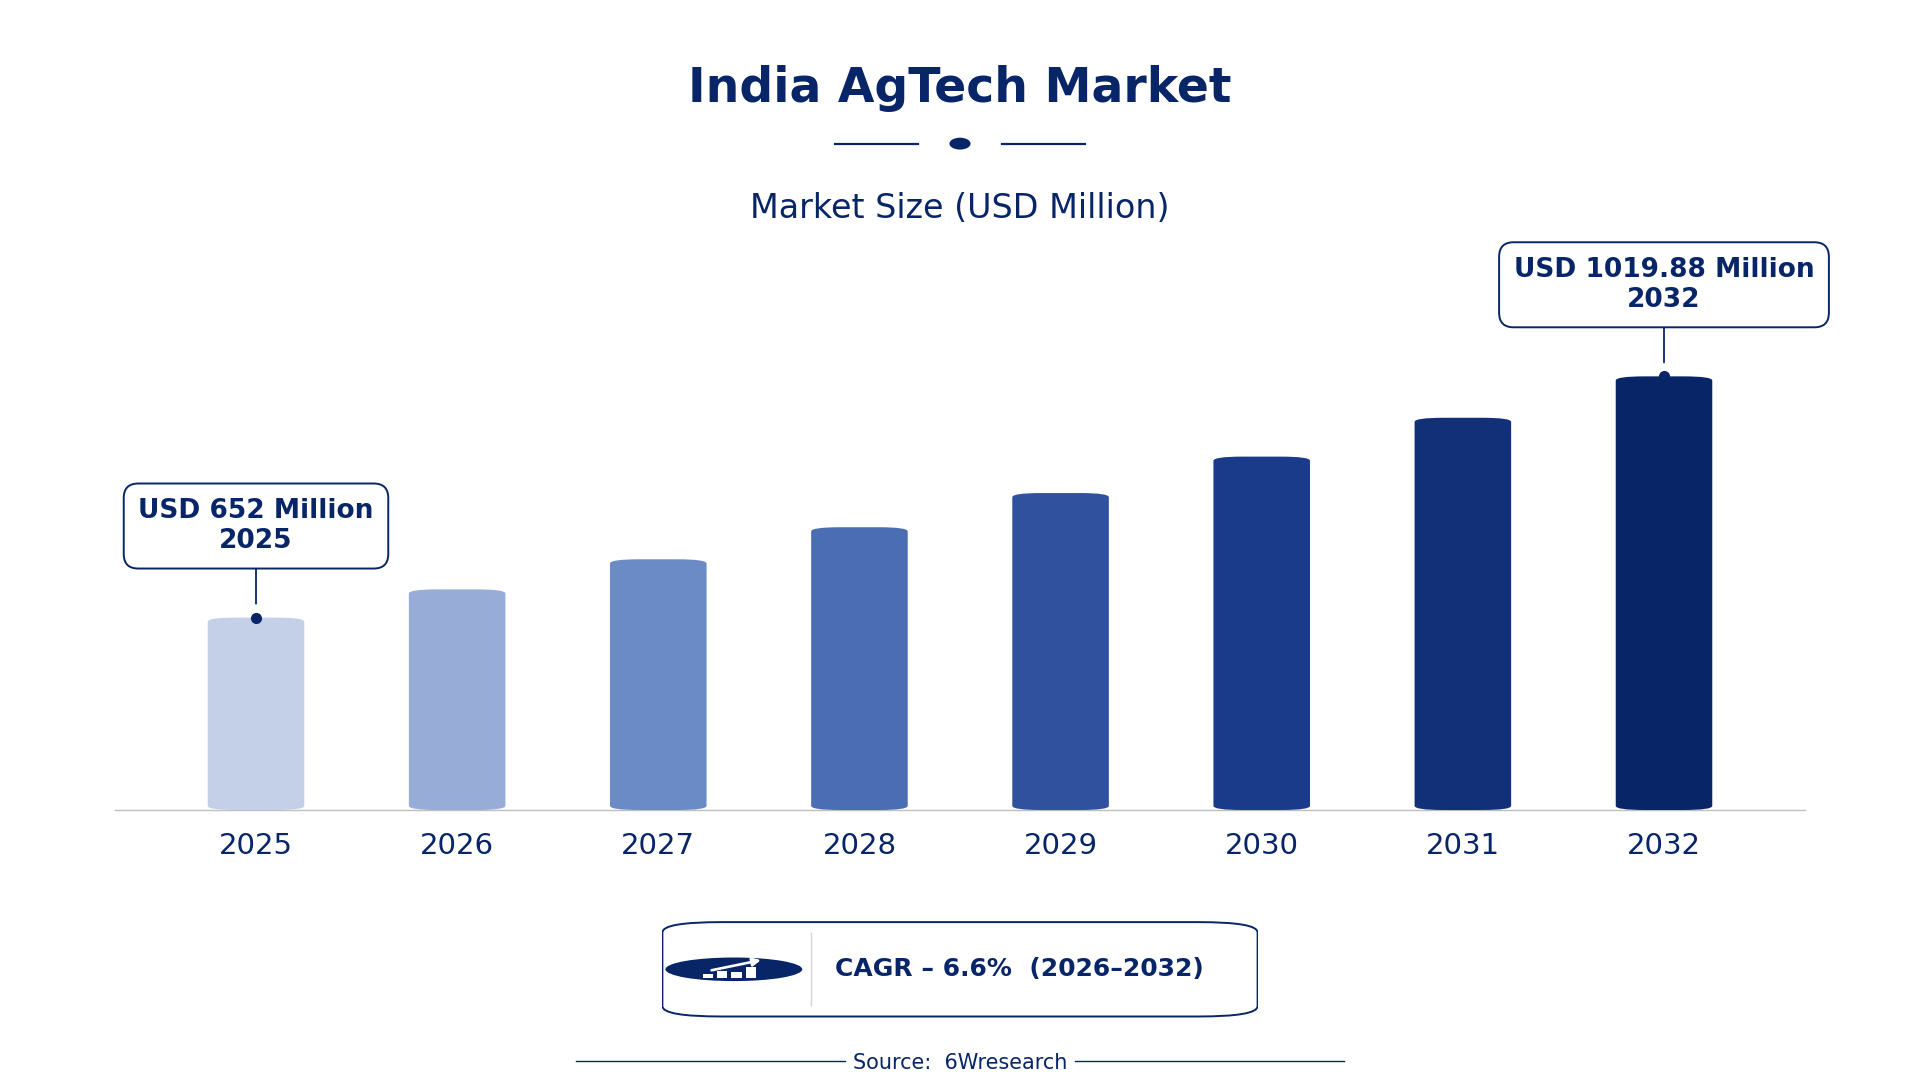
According to 6Wresearch internal database and industry insights, the India AgTech Market was valued at USD 652.0 million in 2025 and is projected to reach USD 1,019.88 million by 2032, growing at a CAGR of approximately 6.6% during 2026–2032.
India AgTech Market Highlights
| Report Metric | Details |
| Report Name | India AgTech Market |
| Market Size 2025 | USD 652.0 million |
| Market Size 2032 | USD 1,019.88 million |
| Absolute Growth 2025–2032 | USD 367.88 million |
| CAGR 2026–2032 | 6.6% |
| Peak Annual Growth | 9.1% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Farm Automation Tools (36% share) |
| Leading Technology Type, 2025 | IoT-enabled Devices (35% share) |
| Leading Distribution Channel, 2025 | Direct Sales (42% share) |
| Leading End User, 2025 | Commercial Farms (44% share) |
| Fastest-Growing Product Type | Drones & Robotics (9.0% CAGR) |
| Fastest-Growing Distribution Channel | Online Platforms (9.2% CAGR) |
| Fastest-Growing End User | Smart Farming Units (8.1% CAGR) |
| Growing Sector | Smart Farming Units |
| Key End Users | Commercial Farms, Agribusiness Companies, Smart Farming Units, Horticulture Enterprises |
India AgTech Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
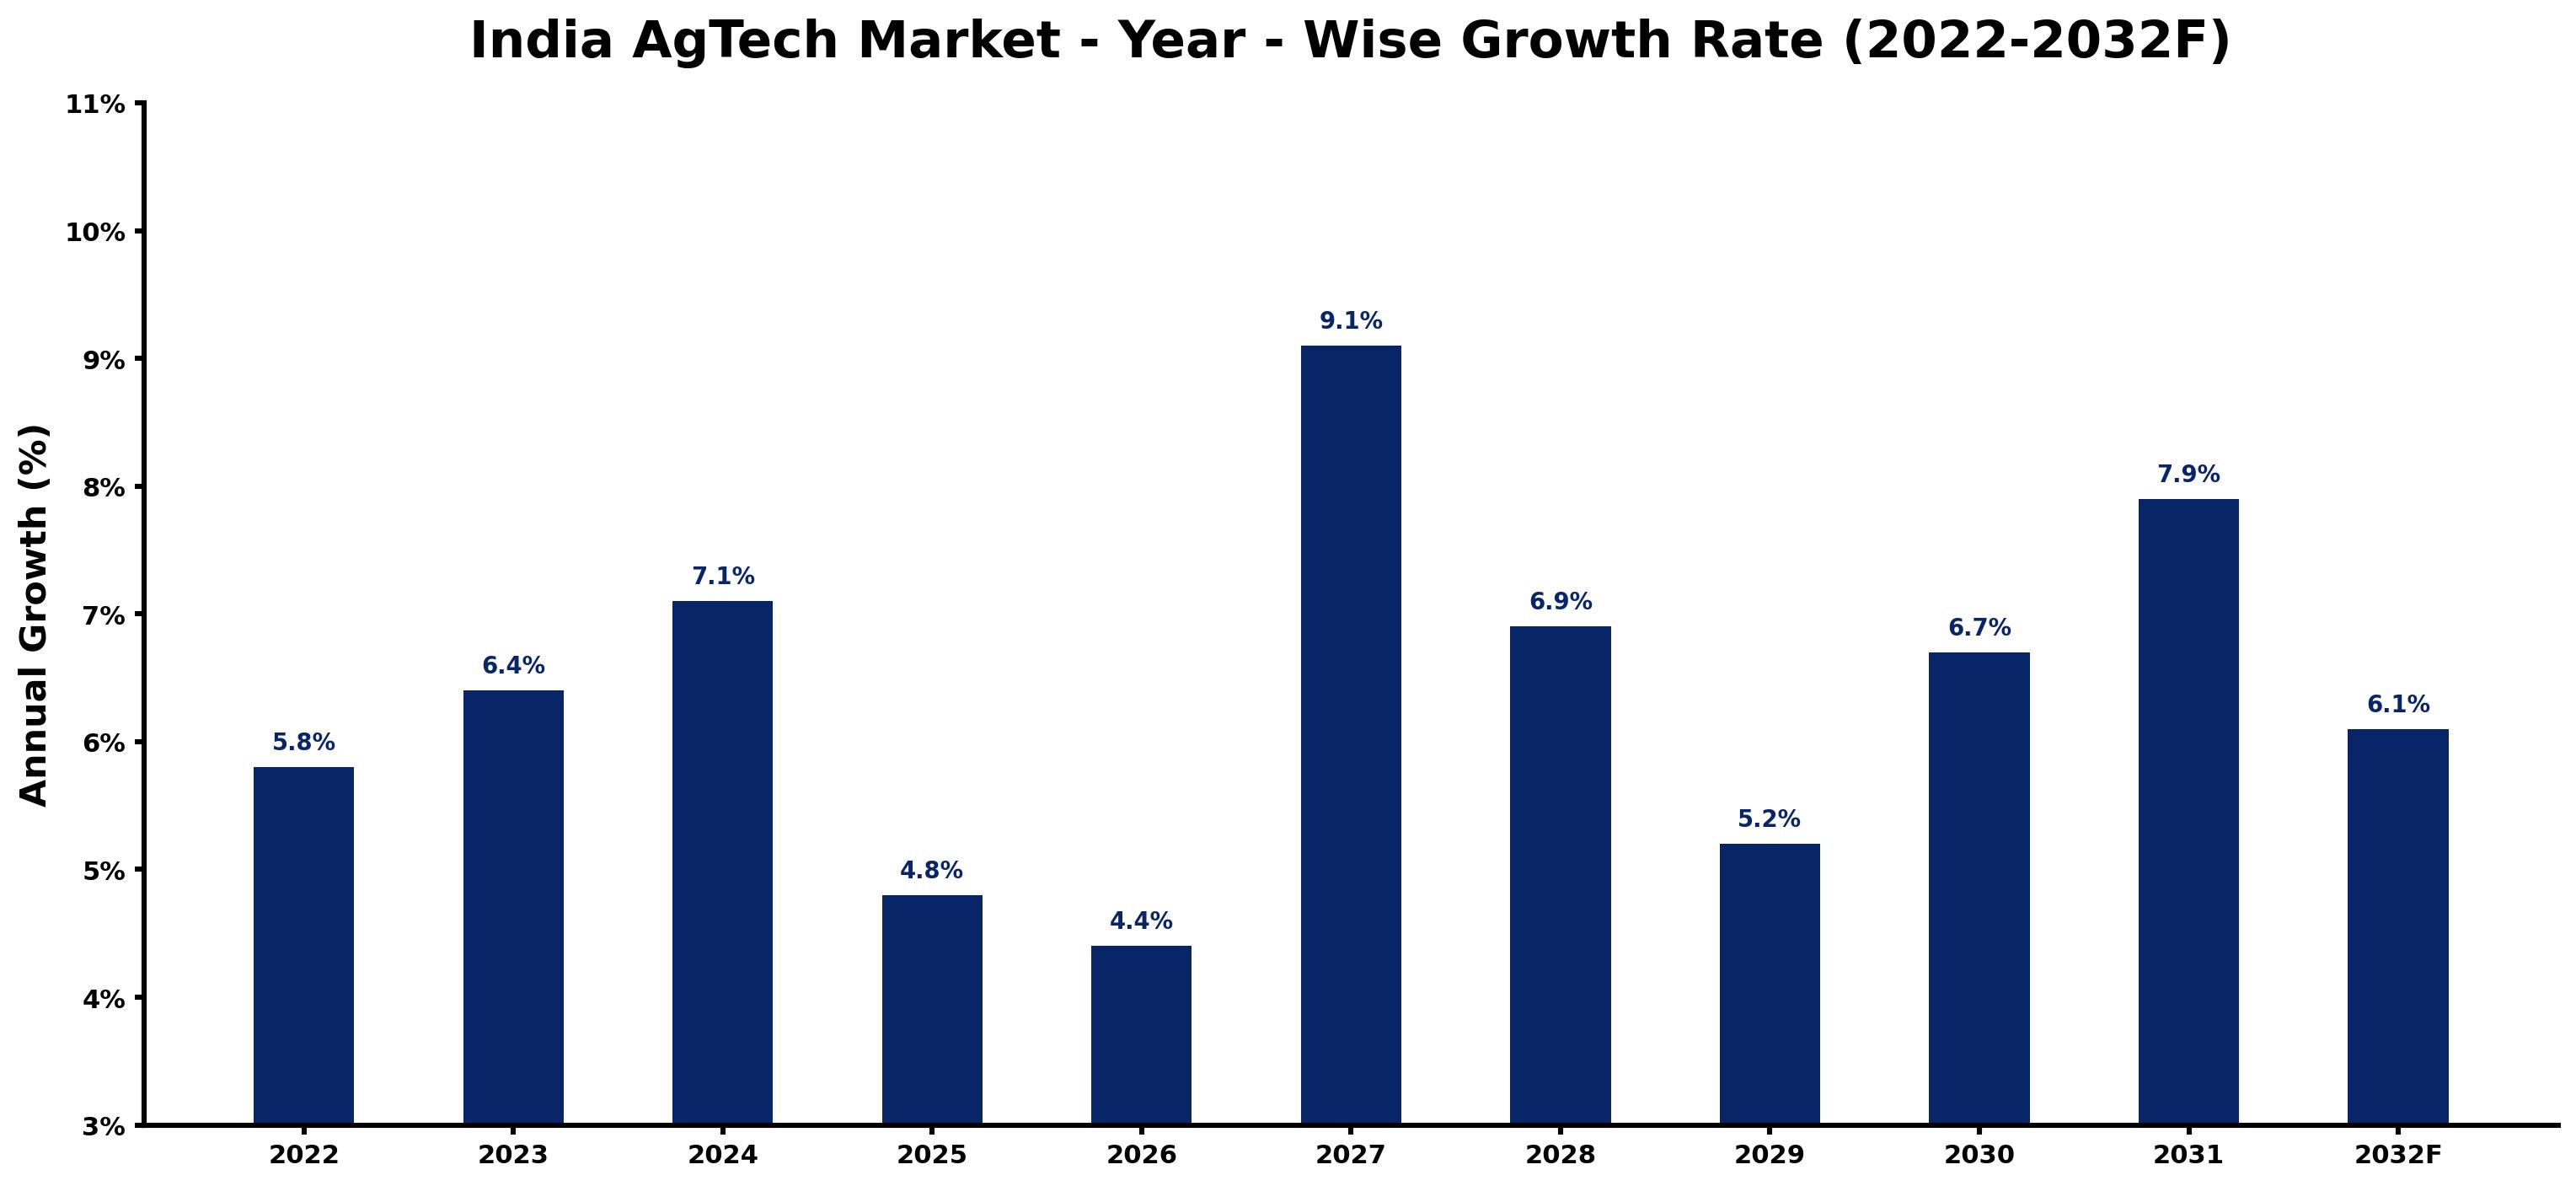
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.8 | The market showed steady growth driven by ongoing agricultural initiatives like the National Agriculture Market. |
| 2023 | 6.4 | Demand increased due to the implementation of the Pradhan Mantri Krishi Sinchai Yojana. |
| 2024 | 7.1 | Growth accelerated as farmers widely adopted precision farming technologies. |
| 2025 | 4.8 | A slight slowdown occurred as farmers adjusted to changing agricultural demands. |
| 2026 | 4.4 | Growth is expected to decelerate as market conditions normalise after previous peaks. |
| 2027 | 9.1 | A surge in demand is projected with the introduction of new AgTech solutions. |
| 2028 | 6.9 | Growth is expected to slow again as market conditions stabilise post-peak. |
| 2029 | 5.2 | Demand is projected to decrease slightly as the market adjusts to technological advancements. |
| 2030 | 6.7 | Growth is expected to pick up again as farmers increasingly adopt smart farming practices. |
| 2031 | 7.9 | A rise in demand is projected as agribusinesses expand their operations. |
| 2032 | 6.1 | The market is expected to show a slight slowdown as it stabilises after rapid growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India AgTech Market Synopsis
The India AgTech Market focuses on technologies that improve agricultural productivity and sustainability. Innovations such as precision farming and farm automation are essential for enhancing crop yields. The market is projected to grow significantly, driven by the increasing adoption of smart farming solutions and government initiatives. For instance, the National Mission on Sustainable Agriculture promotes sustainable practices, which boosts demand. With over 58% of the population engaged in agriculture, commercial farms and agribusinesses are expected to drive substantial growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing investment in agricultural technology solutions | Driver | High | Farm Automation Tools |
| Growing adoption of precision farming technologies | Driver | High | Precision Farming Kits |
| Expansion of digital platforms for AgTech solutions | Opportunity | Medium | Online Platforms |
| Rising demand for sustainable farming practices | Opportunity | Medium | Smart Farming Units |
| Limited access to funding for small-scale farmers | Restraint | High | Commercial Farms |
| Challenges in technology adoption among traditional farmers | Restraint | Medium | Agribusiness Companies |
| Infrastructure deficits in rural areas | Challenge | High | Agricultural Equipment Suppliers |
| Regulatory hurdles in technology implementation | Challenge | Medium | Tech Solution Providers |
Evaluation of Drivers in India AgTech Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased funding for agricultural technology initiatives | Farm Automation Tools | This funding supports the efficiency of farming operations, leading to higher demand for automation solutions and technologies. |
| Rising adoption of data-driven farming practices | Precision Farming Kits | Farmers are increasingly investing in precision tools to improve crop yields and resource management, enhancing productivity. |
| Growing interest in IoT applications in agriculture | IoT-enabled Devices | The demand for real-time data collection drives purchases of IoT solutions among agribusinesses, improving decision-making. |
| Expansion of e-commerce platforms for agricultural products | Online Platforms | This trend facilitates easier access to AgTech solutions, boosting sales through digital channels and enhancing market reach. |
| Increased focus on sustainable agricultural practices | Smart Farming Units | Sustainability initiatives encourage farmers to invest in advanced technologies for better productivity and resource management. |
The expansion of the AgTech market in India is supported by a surge in investment in agricultural technology solutions that enhance efficiency and productivity. The agricultural sector accounts for approximately 17-18% of the GDP, motivating farmers to embrace precision farming technologies that can elevate yields by as much as 30%. With over 140 million hectares of arable land, the demand for IoT-enabled devices is increasing as farmers seek real-time data for informed decision-making. The rise of online platforms for AgTech solutions is making these technologies more accessible, further stimulating purchases.
Evaluation of Restraints in India AgTech Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited access to financing for smallholder farmers | Commercial Farms | Many small-scale farmers struggle to secure funding, hindering their ability to invest in AgTech solutions. |
| Resistance to adopting new technologies among traditional farmers | Agribusiness Companies | Some farmers prefer conventional methods, which slows the uptake of modern agricultural technologies. |
| Insufficient rural infrastructure for technology deployment | Agricultural Equipment Suppliers | Infrastructure deficits delay the implementation of advanced farming solutions in rural areas, affecting productivity. |
| Regulatory challenges affecting technology implementation | Tech Solution Providers | Complex regulations can complicate the introduction of new agricultural technologies, delaying market entry. |
| Lack of awareness regarding AgTech benefits | Smart Farming Units | Many farmers are unaware of the advantages of adopting modern agricultural technologies, limiting market growth. |
India AgTech Market Challenges
The India AgTech market still has to solve a few problems, and the first is a shortage of skilled agricultural workers. Many producers cannot find trained personnel, which delays the adoption of essential technologies and reduces overall productivity. Regulatory compliance poses another challenge; meeting agricultural standards can take up to six months, delaying product launches for suppliers. The slow integration of technology, such as sensor-based irrigation systems, limits efficiency gains and costs farmers potential crop yield increases of up to 30%. High initial costs of implementing AgTech solutions deter many buyers, especially small-scale farmers, from making necessary investments.
Trends in the India AgTech Market
The trends below show where the India AgTech Market is heading.
- Shift towards Precision Farming: The adoption of precision farming technologies is increasing, with precision farming kits expected to improve crop yields significantly. This trend is particularly evident among commercial farms seeking to optimise resource use.
- Rise of IoT in Agriculture: IoT-enabled devices are becoming integral to farming practices, improving real-time data collection. The Smart Agriculture initiative promotes this shift, with a notable increase in the use of IoT solutions across India.
- Growth of E-commerce in AgTech: The rise of online platforms for purchasing AgTech solutions is transforming the market. With a projected growth rate of 9.2%, this trend is making it easier for farmers to access modern technologies.
- Increasing Use of Drones in Agriculture: The use of drones for monitoring crops is on the rise, with regulations being established to facilitate this trend. The expected growth in drone usage aligns with the government's push for modern agricultural practices.
Investment Opportunities in the India AgTech Market
Some of the investment opportunities in the India AgTech Market are mentioned below.
- Investment in Farm Automation Tools: With the market projected to reach USD 652.0 million by 2025, there is a prime opportunity to supply farm automation tools. Commercial farms are increasingly focused on improving efficiency and productivity.
- Expansion into Online Sales Channels: The growth of online platforms presents an opportunity to invest in digital sales channels. Agribusiness companies are keen to adopt these channels for enhanced market access and customer engagement.
- Development of Precision Farming Solutions: The rising demand for precision farming kits creates an opportunity to develop advanced solutions. Farmers are actively searching for tools that can boost crop yields and optimise resource management.
- Focus on Sustainable Farming Practices: The emphasis on sustainable agriculture opens avenues for supplying innovative technologies. The National Mission on Sustainable Agriculture encourages investments in eco-friendly farming solutions.
Government Initiatives in the India AgTech Market
The Pradhan Mantri Kisan Samman Nidhi, launched in 2019, provides direct income support to farmers, benefiting over 10 crore farmers annually. This initiative aims to improve the financial stability of farmers, encouraging them to invest in AgTech solutions. The National Mission on Sustainable Agriculture, initiated in 2020, promotes sustainable farming practices and improves productivity through innovative technologies, further supporting the AgTech sector. The Soil Health Card Scheme, updated in 2021, provides farmers with essential information on soil health, enabling better nutrient management and crop productivity.
The government allocated USD 1.5 billion for rural infrastructure development under the Pradhan Mantri Gram Sadak Yojana. The Ministry of Agriculture and Farmers' Welfare oversees this funding, facilitating better access to AgTech solutions for farmers. The Agricultural Technology Management Agency plays a key role in technology transfer, ensuring farmers receive the necessary training and resources to adopt modern practices.
Future Insight of the India AgTech Market
The India AgTech market is poised for transformative changes by 2032, driven by various factors. The government's commitment to initiatives like the Pradhan Mantri Krishi Sinchai Yojana will enhance irrigation efficiency, benefiting farmers. The emergence of over 2,000 agritech startups indicates a vibrant sector focused on advanced agricultural solutions. Progress in precision farming and IoT technologies will lead to smarter farming practices, ultimately improving resource management. These trends will contribute to a more sustainable agricultural environment for both buyers and suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Product Type – Farm Automation Tools Dominated, Drones & Robotics Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, in 2025, Farm Automation Tools led the product type split with a 36% share. Farm Automation Tools dominate the market share due to their widespread application among commercial farms aiming to improve operational efficiency. Their significance is particularly pronounced in regions like Punjab and Haryana, where large-scale farming operations benefit extensively from these technologies. Drones & Robotics are projected to grow fastest, at a CAGR of 9.0% during 2026–2032. Drones & Robotics are experiencing rapid growth because they offer effective solutions for crop monitoring and management, which can significantly enhance yields. The establishment of regulatory frameworks for drone usage in agriculture is further accelerating the expansion of this segment. Suppliers should focus on advancing drone technologies to meet the rising demand from farmers seeking efficient farming solutions.
By Technology Type – IoT-enabled Devices Dominated and Is Expected to Record the Fastest Growth
IoT-enabled Devices took a 35% share of technology type in 2025, more than any other category. IoT-enabled Devices hold the largest share as they are essential for real-time data collection and analysis, which is critical for modern farming practices. Their integration into existing agricultural systems has been widely adopted across various states in India. The same category are also set to grow fastest, at a CAGR of 8.0% during 2026–2032. The growth of IoT-enabled Devices is accelerating as more farmers recognise the benefits of data-driven decision-making in agriculture. This trend is expected to continue as the government promotes digital agriculture initiatives. Buyers should invest in IoT technologies to optimise their farming practices and improve productivity.
By Distribution Channel – Direct Sales Dominated, Online Platforms Expected to Grow Fastest
Direct Sales accounted for a 42% market share by distribution channel in 2025. Direct Sales is the leading distribution channel, allowing manufacturers to connect directly with end users, particularly commercial farms that require tailored solutions. This method ensures that farmers receive immediate support and guidance on how to utilise products effectively. Online Platforms are set to record the highest CAGR in this split, 9.2% over 2026–2032. Online Platforms are emerging as the fastest-growing distribution channel, driven by increasing internet access and digital literacy among farmers. The trend is evident as a growing number of AgTech solutions become available online, appealing to a more tech-savvy audience. Suppliers must enhance their online strategies to effectively engage the expanding segment of tech-savvy farmers.
By End User – Commercial Farms Dominated, Smart Farming Units Expected to Grow Fastest
With a 44% revenue share in 2025, Commercial Farms was the largest end user category. Commercial Farms represent the largest user group of AgTech solutions, utilising these technologies to significantly boost productivity and operational efficiency. Their scale of operations necessitates the adoption of advanced agricultural tools and practices for optimal results. Over 2026–2032, Smart Farming Units are expected to post the fastest growth, at a CAGR of 8.1%. Smart Farming Units are the fastest-growing segment, focusing on the implementation of advanced technologies to maximise agricultural output. This growth is propelled by a heightened emphasis on sustainable farming practices among smaller farming operations. Suppliers should tailor their products to meet the specific needs of Smart Farming Units to capitalise on this growth trend.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India AgTech Market Outlook
- Market Size of India AgTech Market, 2025
- Forecast of India AgTech Market, 2032
- Historical Data and Forecast of India AgTech Revenues & Volume for the Period 2022 - 2032F
- India AgTech Market Trend Evolution
- India AgTech Market Drivers and Challenges
- India AgTech Price Trends
- India AgTech Porter's Five Forces
- India AgTech Industry Life Cycle
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Farm Automation Tools for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Precision Farming Kits for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Drones & Robotics for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Greenhouse Controllers for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Technology Type for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By IoT-enabled Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By GPS & GIS for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Aerial Monitoring for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Sensor-based Control for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Direct Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Online Platforms for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Tech Solution Providers for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Agricultural Equipment Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Commercial Farms for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Agribusiness Companies for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Smart Farming Units for the Period 2022 - 2032F
- Historical Data and Forecast of India AgTech Market Revenues & Volume By Horticulture Enterprises for the Period 2022 - 2032F
- India AgTech Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Technology Type
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- India AgTech Top Companies Market Share
- India AgTech Competitive Benchmarking By Technical and Operational Parameters
- India AgTech Company Profiles
- India AgTech Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Product Type
- Farm Automation Tools
- Precision Farming Kits
- Drones & Robotics
- Greenhouse Controllers
By Technology Type
- IoT-enabled Devices
- GPS & GIS
- Aerial Monitoring
- Sensor-based Control
By Distribution Channel
- Direct Sales
- Online Platforms
- Tech Solution Providers
- Agricultural Equipment Suppliers
By End User
- Commercial Farms
- Agribusiness Companies
- Smart Farming Units
- Horticulture Enterprises































