India AI Computing Market Size & Growth Rate
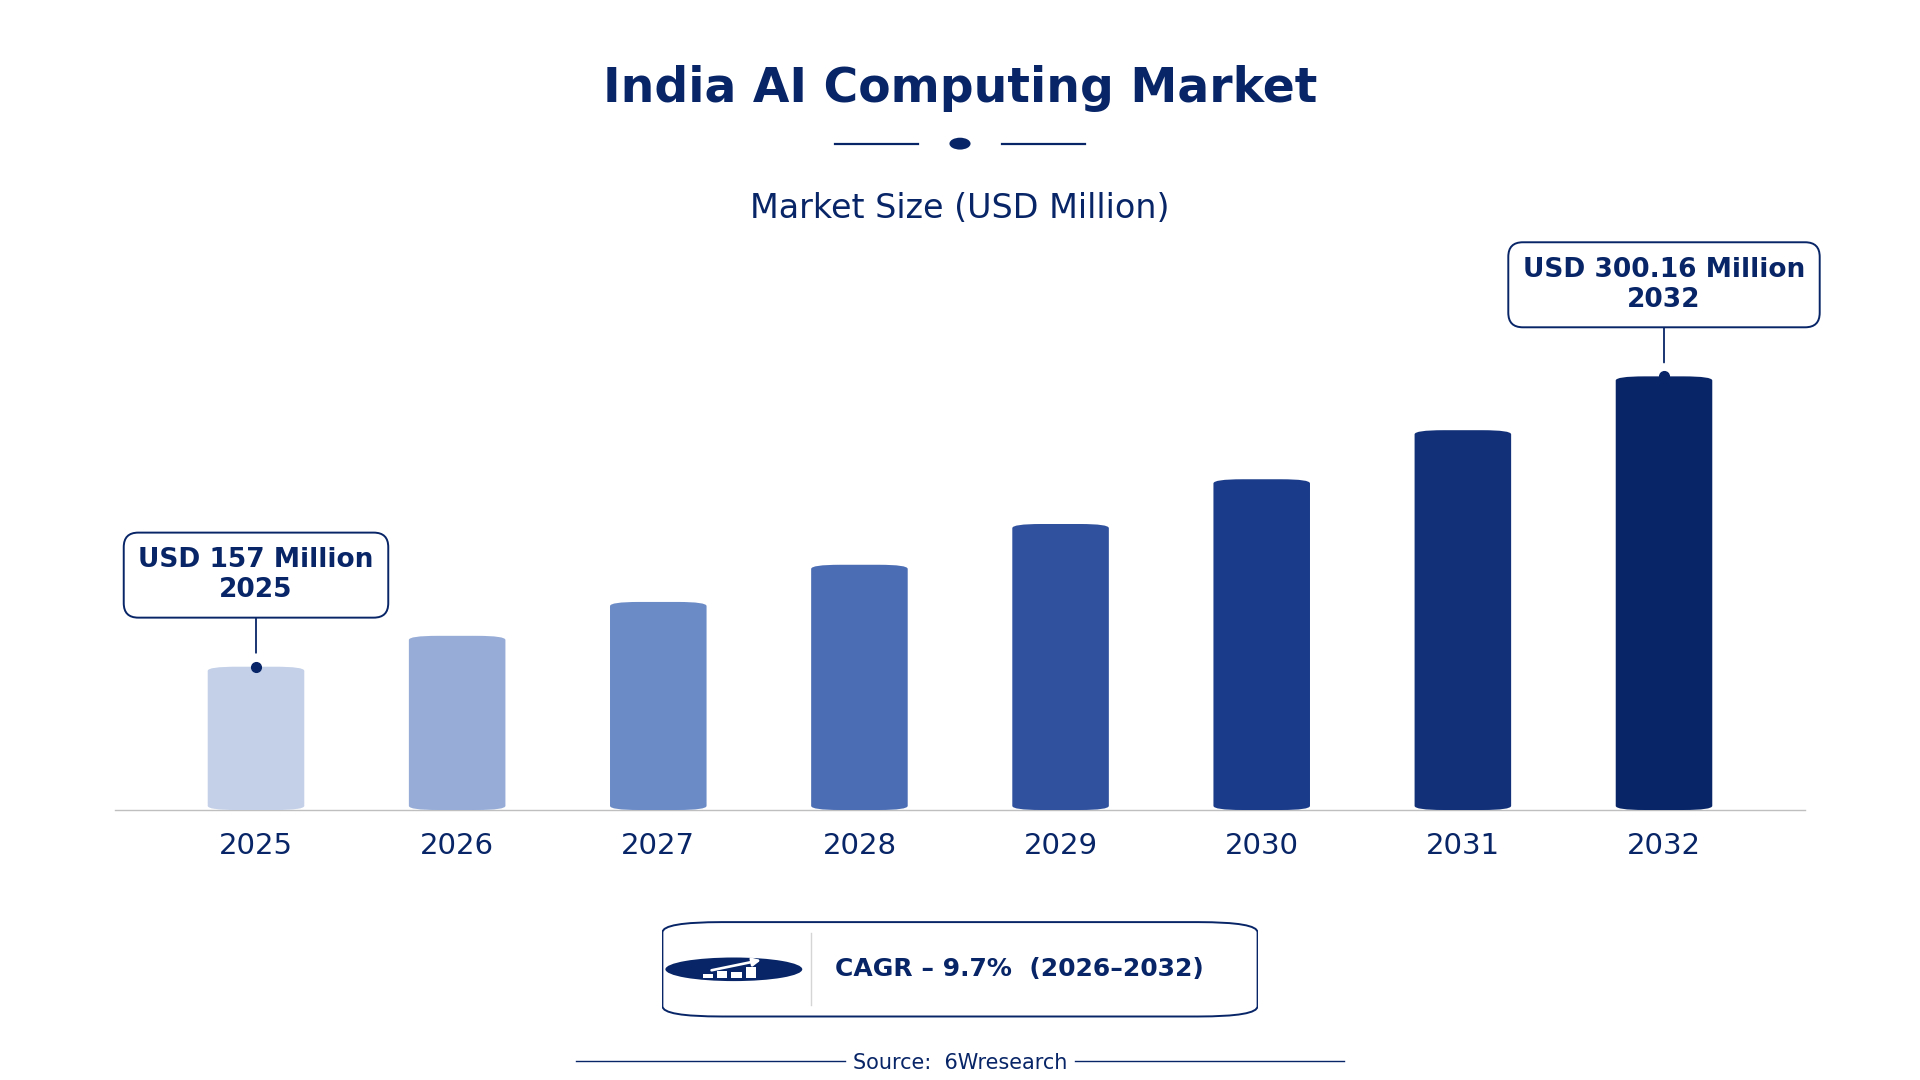
According to 6Wresearch internal database and industry insights, the India AI Computing Market was valued at USD 157.0 million in 2025 and is projected to reach USD 300.16 million by 2032, growing at a CAGR of approximately 9.7% during 2026–2032.
India AI Computing Market Highlights
| Report Metric | Details |
| Report Name | India AI Computing Market |
| Market Size 2025 | USD 157.0 million |
| Market Size 2032 | USD 300.16 million |
| Absolute Growth 2025–2032 | USD 143.16 million |
| CAGR 2026–2032 | 9.7% |
| Peak Annual Growth | 11.8% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Computing Type, 2025 | Cloud AI Infrastructure (42% share) |
| Leading Hardware Platform, 2025 | High-performance GPUs (36% share) |
| Leading Distribution Channel, 2025 | Cloud Service Providers (47% share) |
| Leading End User, 2025 | Large Enterprises (44% share) |
| Fastest-Growing Computing Type | Edge AI Computing (12.2% CAGR) |
| Fastest-Growing Hardware Platform | NPUs/SoCs (11.6% CAGR) |
| Fastest-Growing Distribution Channel | OEM Distributors (11.5% CAGR) |
| Fastest-Growing End User | Smart Device Manufacturers (11.8% CAGR) |
| Growing Sector | Technology and Manufacturing |
| Key End Users | Large Enterprises, Industrial IoT Firms, Research Institutes, Smart Device Manufacturers |
India AI Computing Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
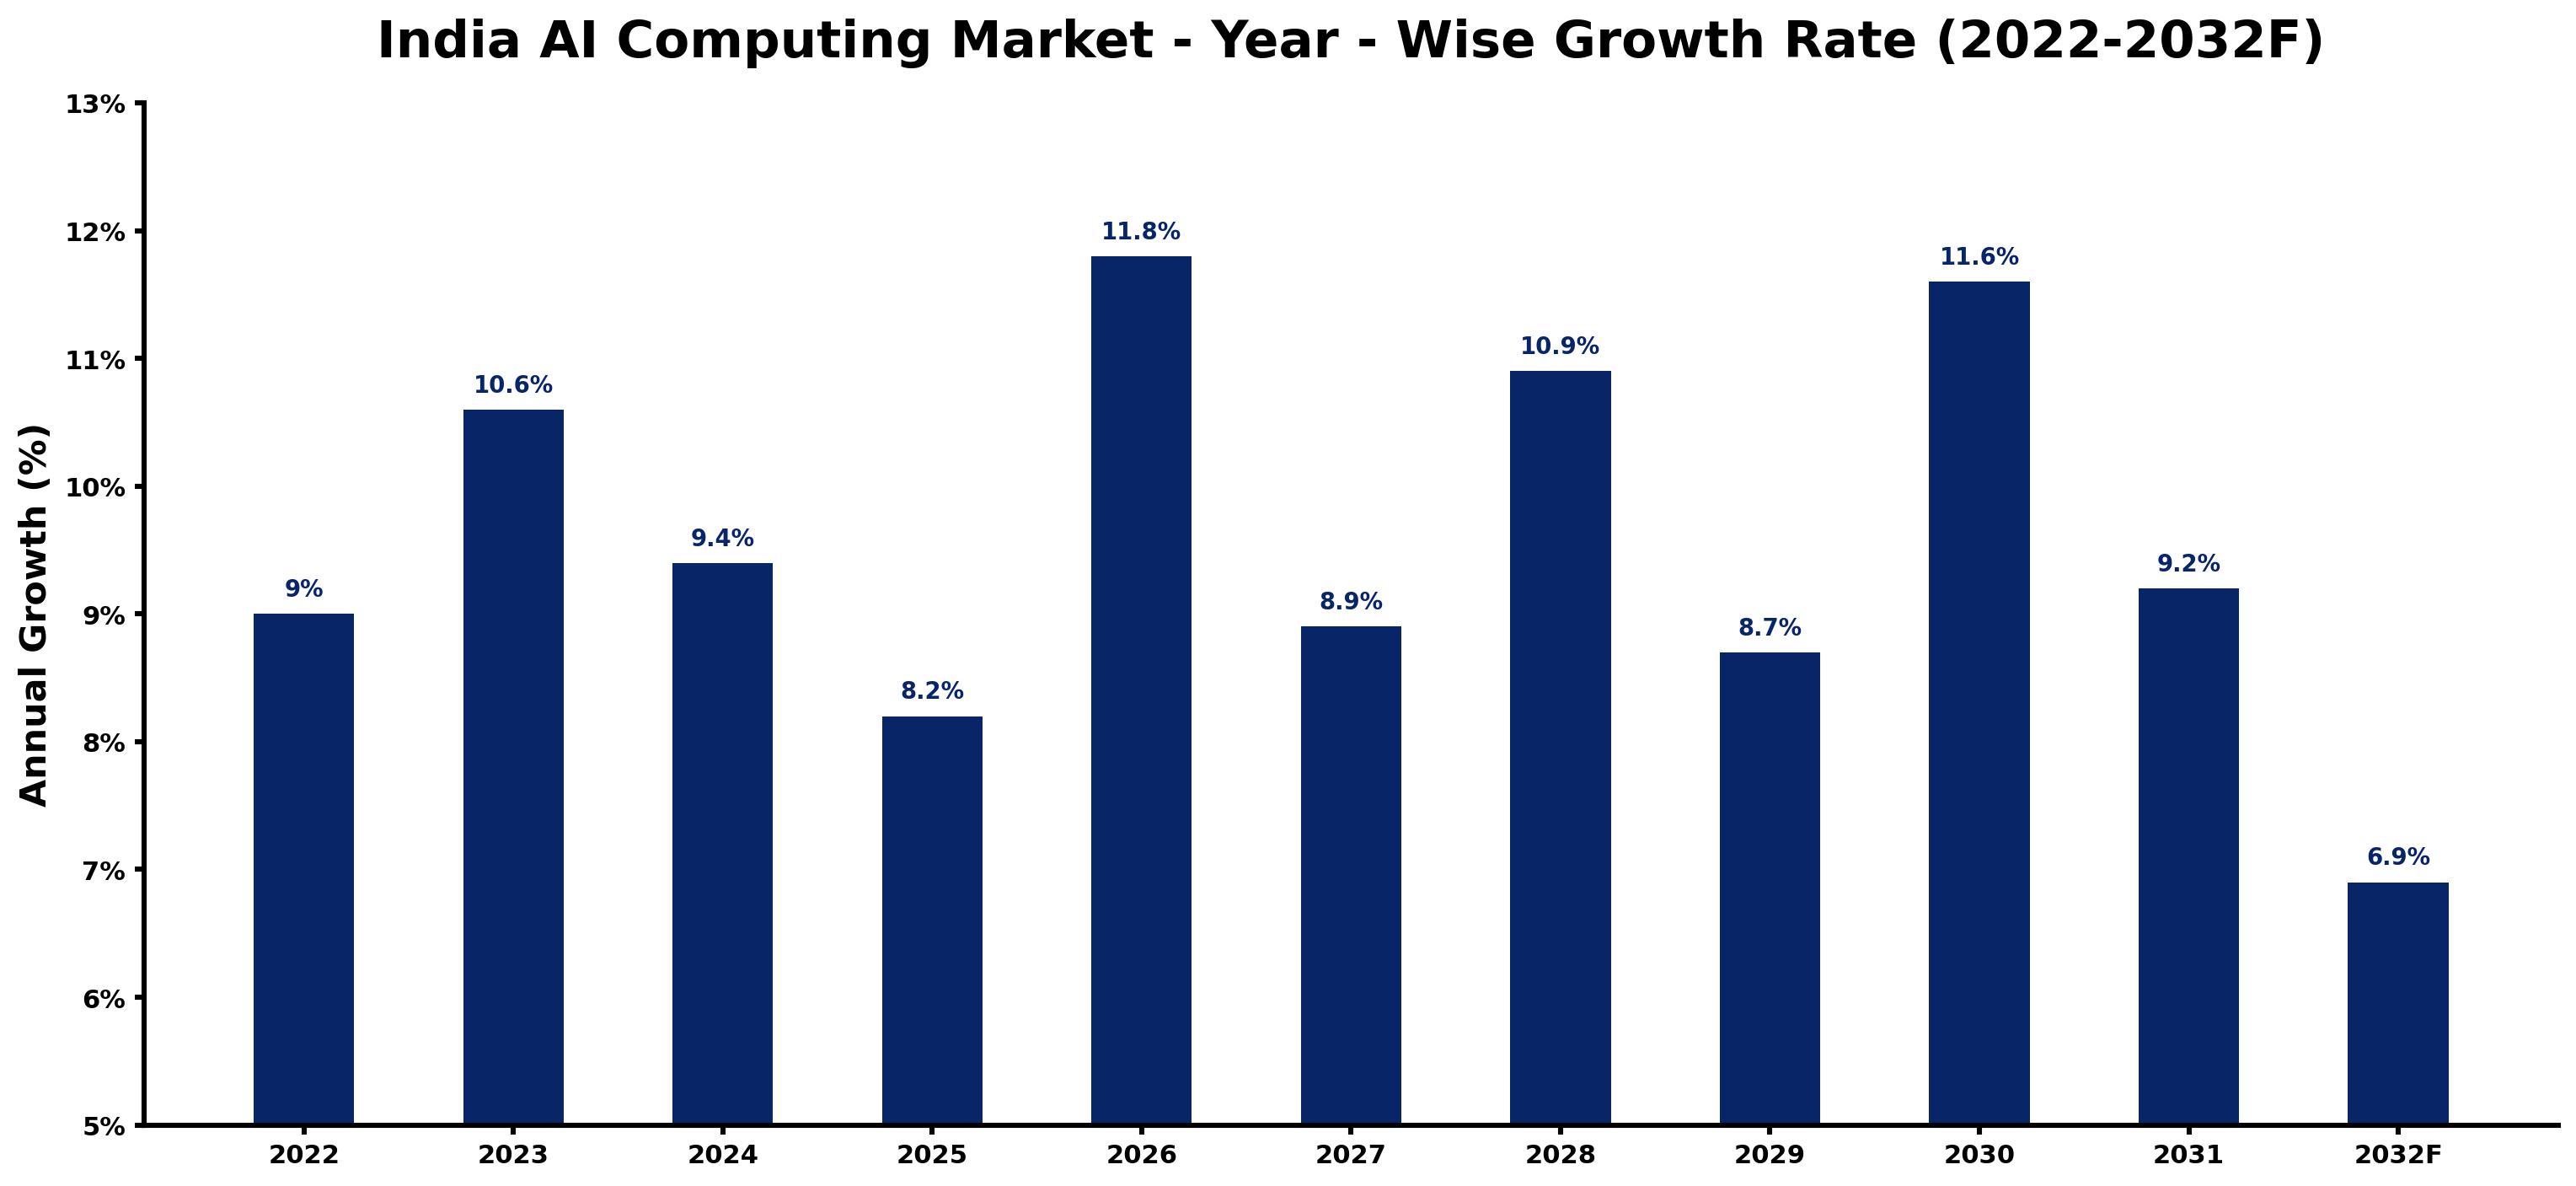
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 9.0 | The market experienced steady growth, driven by increasing AI adoption across sectors. |
| 2023 | 10.6 | Growth accelerated due to heightened investment in AI technologies and infrastructure. |
| 2024 | 9.4 | Growth slowed slightly as the market adjusted following rapid expansion. |
| 2025 | 8.2 | The market continued to grow, but at a slower rate due to maturing demand. |
| 2026 | 11.8 | A surge in demand for AI solutions is expected to lead to a significant growth spike. |
| 2027 | 8.9 | Growth will decelerate as the market stabilises after peak demand. |
| 2028 | 10.9 | An increase in AI applications across industries is projected to result in renewed growth. |
| 2029 | 8.7 | Growth will slow again as the market adjusts to new technology standards. |
| 2030 | 11.6 | A resurgence in AI investments is expected to lead to a notable increase in growth. |
| 2031 | 9.2 | The market will see a slowdown as growth stabilises following previous peaks. |
| 2032 | 6.9 | Growth is projected to slow as market saturation begins to take effect. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India AI Computing Market Synopsis
The AI Computing Market in India encompasses technologies that enable machines to perform tasks requiring human intelligence. It is developed through advanced algorithms and neural networks, with applications in data analysis, automation, and user experience improvement. The market is experiencing growth driven by significant demand from large enterprises and technology sectors. The National AI Strategy and the Digital India programme are key in promoting AI infrastructure and capabilities, creating a conducive environment for innovation and investment, with over 500 AI startups contributing to the ecosystem.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for AI solutions in technology and manufacturing sectors | Driver | High | Cloud AI Infrastructure |
| Growing number of AI startups focusing on diverse applications | Driver | High | Edge AI Computing |
| Investment opportunities in AI hardware manufacturing | Opportunity | High | High-performance GPUs |
| Rising need for AI training programs to meet workforce demands | Opportunity | High | AI Supercomputing |
| Challenges in scaling AI infrastructure across regions | Restraint | Medium | Cloud AI Infrastructure |
| Limited access to advanced AI training resources | Restraint | Medium | Edge AI Computing |
| Shortage of skilled professionals in the AI sector | Challenge | High | AI Supercomputing |
| High costs associated with AI technology adoption | Challenge | Medium | On-device AI Processing |
Evaluation of Drivers in India AI Computing Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising investment in AI infrastructure | Cloud AI Infrastructure | This investment supports scalable resources for AI applications, leading to increased purchases from large enterprises. |
| Growing demand for real-time data processing | Edge AI Computing | This demand enhances operational efficiency, prompting industries to adopt advanced AI solutions. |
| Focus on workforce development | High-performance GPUs | Training initiatives boost the need for advanced computing resources, driving purchases for AI applications. |
| Increased research output in AI | AI Supercomputing | India's strong research capabilities encourage investments in high-performance computing for complex simulations. |
| Expansion of AI startups | On-device AI Processing | The proliferation of startups fosters innovation, creating demand for integrated AI capabilities in consumer devices. |
Growth in the AI Computing market in India comes from rising demand for scalable solutions, increased investment in real-time data processing, and a focus on training professionals. India's strong position in AI research output is creating a thriving market for high-performance GPUs, essential for AI applications. As a result, the market is set to expand in the coming years, driven by these factors.
Evaluation of Restraints in India AI Computing Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in scaling AI infrastructure across diverse regions | Cloud AI Infrastructure | Infrastructure gaps hinder effective deployment, limiting access for potential buyers in rural areas. |
| Limited access to advanced AI training resources | Edge AI Computing | Insufficient training programs restrict the workforce's ability to adopt new technologies effectively. |
| High costs associated with AI technology adoption | On-device AI Processing | Budget constraints for small enterprises can delay the integration of AI capabilities. |
| Regulatory hurdles in AI hardware manufacturing | High-performance GPUs | Compliance with stringent standards can slow down production and increase costs. |
| Shortage of skilled professionals in the AI sector | AI Supercomputing | The lack of trained personnel affects the ability of research institutes to effectively utilise AI. |
India AI Computing Market Challenges
Buyers and suppliers in the India AI Computing market encounter intense competition from over 500 AI startups, pressuring producers to innovate swiftly while squeezing profit margins. This competitive environment forces producers to reduce costs, which may compromise quality and reliability for buyers. High integration costs for advanced AI technologies can inflate project budgets by up to 30%, causing delays that disrupt buyers' project timelines. Regulatory challenges, particularly concerning data protection laws, complicate compliance and slow the deployment of AI solutions, limiting buyers' ability to leverage these technologies effectively.
Trends in the India AI Computing Market
Buyers and suppliers in the India AI Computing Market are adjusting to the following trends.
- Karnataka Emerging as an Edge AI Hub: Karnataka is becoming a key region for Edge AI Computing, with local firms focusing on real-time data processing. The state hosts over 200 AI startups, showcasing a notable increase in Edge AI applications in 2023.
- Large Enterprises Increasing AI Investments: Large Enterprises are increasing their investments in AI technologies, with a projected rise in spending by 25% by 2025. This trend is driven by the need for competitive advantage and innovation.
- Growing Adoption of AI Training Programs: The demand for AI training programs is growing, with the Skill India initiative aiming to train 1 million professionals by 2025. This effort is expected to improve the workforce's capabilities in AI applications.
- Rise of AI Supercomputing in Research Institutes: Research Institutes are increasingly adopting AI Supercomputing for complex simulations, with a notable growth in usage reported in 2023. This trend is supported by funding from the AI Research and Development Fund.
Investment Opportunities in the India AI Computing Market
Investors looking at the India AI Computing Market should consider the following areas.
- Investment in AI Hardware Manufacturing: Investing in AI hardware manufacturing presents a strong opportunity, with the Electronics Policy 2020 aiming to boost local production. This initiative is expected to create a market worth USD 50 million by 2025.
- Development of AI Training Programs: The growing need for AI training programs presents an opportunity for educational institutions to develop specialized courses. With over 500 AI startups in India, partnerships with these firms can improve program relevance.
- Expansion of Cloud AI Services: The demand for Cloud AI services is rising, particularly among large enterprises seeking scalable solutions. The market is projected to grow by 20% in 2025, creating opportunities for service providers.
- Development of Edge AI Solutions: The increasing need for real-time data processing opens opportunities for developing Edge AI solutions. With a projected growth rate of 12.2% for Edge AI Computing, suppliers can benefit from this trend.
Government Initiatives in the India AI Computing Market
The Electronics Policy 2020 promotes domestic manufacturing of AI hardware, which is essential for reducing dependency on imports. The National AI Strategy, launched by NITI Aayog in 2021, aims to enhance AI capabilities across sectors, focusing on research and development. Additionally, the Skill India initiative seeks to train 1 million AI professionals by 2025, addressing the workforce gap in the AI sector. These measures collectively support the growth of AI computing in India.
The AI Research and Development Fund, established in 2022, allocates resources for innovative AI projects and startups. Managed by the Ministry of Electronics and Information Technology, this fund aims to stimulate research and development in AI technologies. The Digital India programme, initiated in 2023, focuses on improving AI infrastructure nationwide, facilitating better access to AI resources. Furthermore, the National Institute of Electronics and Information Technology (NIELIT) offers AI training programs, improving the skill set of the workforce in this sector. These initiatives are vital for building a strong AI ecosystem in India.
Future Insight of the India AI Computing Market
The India AI Computing market is set for significant evolution by 2032, driven by the Digital India programme, which will improve AI infrastructure across the country. The establishment of the AI Research and Development Fund will stimulate innovative projects, contributing to India's position as the 3rd largest in global AI research output as of 2023. The Skill India initiative aims to equip 1 million professionals by 2025, fostering a skilled workforce that will facilitate broader AI adoption. These developments will empower buyers and suppliers to fully harness AI capabilities, improving the market's overall efficiency.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Computing Type – Cloud AI Infrastructure Dominated, Edge AI Computing Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, Cloud AI Infrastructure accounted for a 42% market share by computing type in 2025. Cloud AI Infrastructure holds the largest share in India due to its ability to provide scalable resources for applications and data storage, which is essential for large enterprises engaged in extensive data analysis. The National AI Strategy launched in 2021 has further solidified the need for robust cloud solutions across various sectors. Edge AI Computing is set to record the highest CAGR in this split, 12.2% over 2026–2032. Edge AI Computing is experiencing rapid growth because it enables real-time data processing at the source, which is crucial for sectors demanding quick response times. The increasing adoption of edge solutions in manufacturing and healthcare is significantly driving this segment's expansion. Suppliers should prioritise scalable cloud solutions while buyers must invest in edge computing technologies to enhance operational efficiency.
By Hardware Platform – High-performance GPUs Dominated, NPUs/SoCs Expected to Grow Fastest
The largest hardware platform category in 2025 was High-performance GPUs, with a 36% share of total revenue. High-performance GPUs command the largest market share as they are essential for training models and processing large datasets, particularly in technology and finance sectors. Their extensive use in research institutions and enterprises underscores their leading position in the hardware platform segment. The quickest growth will come from NPUs/SoCs, forecast to expand at a CAGR of 11.6% between 2026 and 2032. NPUs/SoCs are witnessing rapid growth as they integrate capabilities directly into devices, which fosters innovation in consumer electronics. The surge in smart device production is a key factor driving this segment's expansion. Suppliers must focus on advancing NPU technology, while buyers should assess hardware that optimises performance in their applications.
By Distribution Channel – Cloud Service Providers Dominated, OEM Distributors Expected to Grow Fastest
With a 47% revenue share in 2025, Cloud Service Providers was the largest distribution channel category. Cloud Service Providers lead the distribution channel segment by offering essential infrastructure for applications and services across diverse industries. Their extensive networks and capabilities are crucial for businesses aiming to leverage technology effectively. OEM Distributors are projected to grow fastest, at a CAGR of 11.5% during 2026–2032. OEM Distributors are growing quickly as they play a vital role in distributing hardware across various sectors, addressing the increasing demand for integrated solutions. Their adaptability to market needs is a driving force behind their rapid expansion. Suppliers need to strengthen partnerships with OEM distributors, while buyers should explore varied distribution channels for hardware solutions.
By End User – Large Enterprises Dominated, Smart Device Manufacturers Expected to Grow Fastest
Large Enterprises held a 44% share of the India AI Computing Market by end user in 2025. Large Enterprises capture the largest share as they invest significantly in technology for competitive advantage across multiple sectors. Their substantial budgets and resources allow them to implement advanced solutions effectively, reinforcing their dominant position. Over 2026–2032, Smart Device Manufacturers are expected to post the fastest growth, at a CAGR of 11.8%. Smart Device Manufacturers are the fastest-growing end user group, driven by the integration of advanced capabilities into consumer products to meet rising expectations. The trend towards smart home devices significantly contributes to this growth. Suppliers should tailor their offerings for large enterprises, while buyers in consumer electronics must prioritise integration to enhance product appeal.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India AI Computing Market Outlook
- Market Size of India AI Computing Market, 2025
- Forecast of India AI Computing Market, 2032
- Historical Data and Forecast of India AI Computing Revenues & Volume for the Period 2022 - 2032F
- India AI Computing Market Trend Evolution
- India AI Computing Market Drivers and Challenges
- India AI Computing Price Trends
- India AI Computing Porter's Five Forces
- India AI Computing Industry Life Cycle
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Computing Type for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Edge AI Computing for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Cloud AI Infrastructure for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By AI Supercomputing for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By On-device AI Processing for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Hardware Platform for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Microcontrollers for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By High-performance GPUs for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By HPC Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By NPUs/SoCs for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By OEM Distributors for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Cloud Service Providers for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Direct Hardware Sales for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Online Electronics Stores for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Industrial IoT Firms for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Large Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Research Institutes for the Period 2022 - 2032F
- Historical Data and Forecast of India AI Computing Market Revenues & Volume By Smart Device Manufacturers for the Period 2022 - 2032F
- India AI Computing Import Export Trade Statistics
- Market Opportunity Assessment By Computing Type
- Market Opportunity Assessment By Hardware Platform
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- India AI Computing Top Companies Market Share
- India AI Computing Competitive Benchmarking By Technical and Operational Parameters
- India AI Computing Company Profiles
- India AI Computing Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Computing Type
- Edge AI Computing
- Cloud AI Infrastructure
- AI Supercomputing
- On-device AI Processing
By Hardware Platform
- Microcontrollers
- High-performance GPUs
- HPC Systems
- NPUs/SoCs
By Distribution Channel
- OEM Distributors
- Cloud Service Providers
- Direct Hardware Sales
- Online Electronics Stores
By End User
- Industrial IoT Firms
- Large Enterprises
- Research Institutes
- Smart Device Manufacturers































