India Data Center Market Size & Growth Rate
According to 6Wresearch internal database and industry insights, the India Data Center Market was valued at USD 4.69 Billion in 2025 and is projected to reach USD 10.05 Billion by 2032, growing at a CAGR of approximately 11.5% during 2026–2032.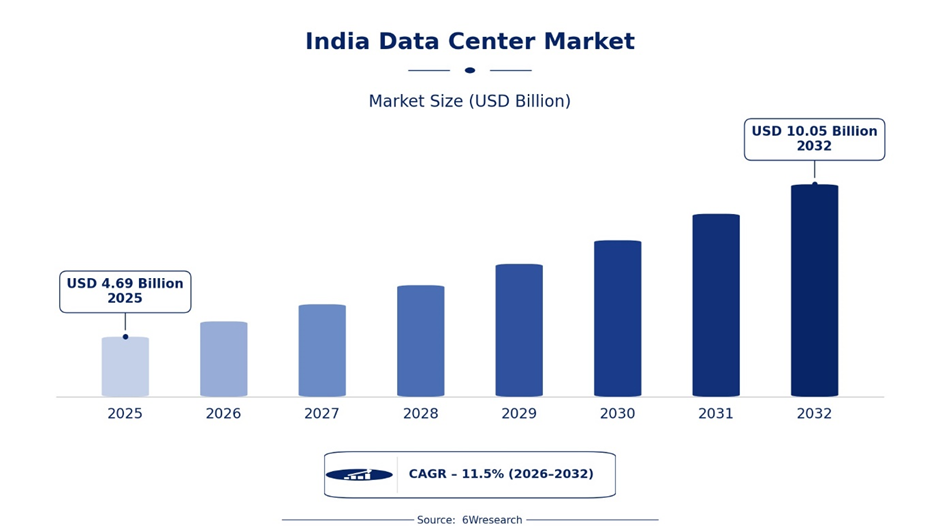
India Data Center Market Highlights
|
Report Metric |
Details |
|
Report Name |
India Data Center Market (2026-2032) |
|
Market Size 2025 |
USD 4.69 Billion |
|
Market Size 2032 |
USD 10.05 Billion |
|
Absolute Growth 2025–2032 |
USD 5.36 Billion |
|
CAGR 2026–2032 |
11.5% |
|
Peak Annual Growth |
12.6% (2026) |
|
Forecast Period |
2026–2032 |
|
Historical Data |
2022–2025 |
|
Base Year |
2025 |
|
Leading Type, 2025 |
Colocation Data Center (40%) |
|
Fastest-Growing Type |
Cloud Data Center (14.2% CAGR) |
|
Leading Infrastructure Type, 2025 |
Tier III (60%) |
|
Fastest-Growing Infrastructure Type |
Tier IV (15.8% CAGR) |
|
Leading Application, 2025 |
Telecom & IT (40%) |
|
Fastest-Growing Application |
Healthcare (15.4% CAGR) |
|
Leading Region, 2025 |
Western (40%) |
|
Fastest-Growing Region |
Eastern (14.7% CAGR) |
|
Growing Sector |
AI-ready and hyperscale infrastructure |
|
Key End Users |
Banks and insurers, telecom operators and IT services providers, central and state government departments, hospitals and healthcare providers, hyperscale platform operators, retail and hospitality chains |
India Data Center Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting gradual market development in the historical period and stronger expansion during the forecast period.
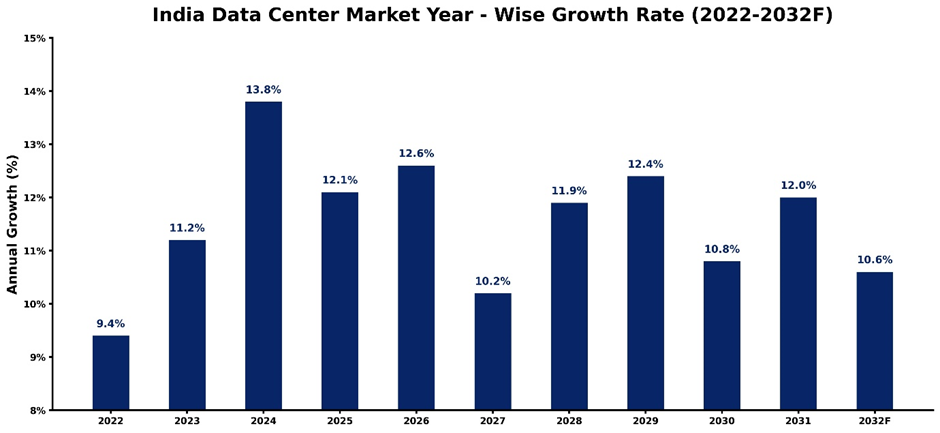 The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
|
Year |
Estimated Annual Growth (%) |
Market Rationale |
|
2022 |
9.4% |
Recovery in technology budgets and the 5G spectrum auction of 2022 revived demand for hosted capacity after pandemic disruptions. |
|
2023 |
11.2% |
Expansion of hyperscale campuses in Mumbai and Chennai and rising video streaming volumes lifted leasing momentum through 2023. |
|
2024 |
13.8% |
Record leasing by cloud providers and the emergence of generative artificial intelligence workloads lifted growth to its historical peak. |
|
2025 |
12.1% |
Power availability and land constraints in Mumbai and Chennai moderated new launches after the exceptional leasing recorded during 2024. |
|
2026 |
12.6% |
Commissioning of GPU clusters under national programmes is expected to accelerate commitments for AI-ready halls through 2026. |
|
2027 |
10.2% |
Absorption of capacity delivered in 2026 is expected to slow leasing, and grid connection queues are likely to delay commissioning. |
|
2028 |
11.9% |
Edge facilities in smaller cities are expected to lift demand as low-latency applications and wider network coverage mature. |
|
2029 |
12.4% |
Renewable power purchase agreements and new transmission corridors are expected to enable larger campuses at competitive electricity costs. |
|
2030 |
10.8% |
Self-build programmes by hyperscale users are expected to temper third-party leasing growth as capacity additions reach higher volumes. |
|
2031 |
12% |
Enterprise inference workloads are expected to require liquid-cooled racks across existing and new campuses, renewing facility upgrade spending. |
|
2032 |
10.6% |
A larger installed base is expected to moderate percentage growth as the market matures and new additions normalise. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch’s proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Data Center Market Synopsis
India data center market is projected to attain notable expansion, propelled by growing digital adoption, cloud computing, e-governance initiatives, and the demand for secure, localized data storage. Generally, a data center is a facility that houses critical IT infrastructure, including servers, storage systems, networking equipment, and backup power, enabling organizations to store, manage, and process large volumes of data securely and efficiently. The market is witnessing a surge in hyperscale data centers from global cloud providers and a parallel rise in edge data centers to support emerging technologies such as 5G, IoT, and AI.
Market Dynamics Impact Analysis (2026–2032)
|
Factor |
Type |
Impact |
Primary Segment Affected |
|
Rising digital payments and data consumption |
Driver |
High |
Colocation Data Center |
|
Hyperscale and AI compute expansion |
Driver |
High |
Cloud Data Center |
|
Edge capacity in emerging cities |
Opportunity |
Medium |
Tier II |
|
Renewable-linked campuses and energy storage |
Opportunity |
High |
Tier III |
|
Grid power and water limitations |
Restraint |
High |
Colocation Data Center |
|
Import dependence of IT and cooling equipment |
Restraint |
Medium |
Enterprise Data Center |
|
High-density cooling retrofits |
Challenge |
High |
Tier III |
|
Data protection compliance overhead |
Challenge |
Medium |
BFSI |
Evaluation of Drivers in India Data Center Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
|
Drivers |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Surge in digital payments and data consumption |
Colocation Data Center |
Each transaction, stream and application call generates storage and processing needs that operators serve through leased racks, and monthly UPI volumes exceeded 20 billion in 2025. |
|
Hyperscale region expansion |
Cloud Data Center |
Global platforms add regions to meet latency and residency needs, drawing large leases and ancillary suppliers, as shown by the launch of the AWS Hyderabad region in November 2022 alongside Mumbai. |
|
Demand for AI training and inference capacity |
Tier III |
GPU clusters need dense power and cooling, pushing buyers towards specialised halls, and Yotta’s Shakti Cloud was announced with a cluster of more than 16,000 GPUs. |
|
Payment and financial data localisation rules |
BFSI |
Regulators require regulated entities to store transaction data within India, which converts compliance into hosting contracts, following the Reserve Bank of India payment data storage directive of April 2018. |
|
5G rollout and edge content delivery |
Telecom & IT |
Lower-latency networks and video traffic push operators to place compute and caches closer to users, and 5G services launched in October 2022 have since reached most districts. |
India Data Center Market is expected to grow in the coming years due to high usage of cloud-based services, digital transformation initiatives and increased demand for better data processing and storage facilities. This will be supported by rapid expansion through the introduction of hyperscale data centers by major players such as Amazon Web Services, Microsoft Azure and Google Cloud.
In addition to this, sustainability trends and investments in renewable energy and green data centers will contribute to the ESG goals. International investment by global cloud service providers, technological innovations in areas such as artificial intelligence and blockchain, as well as disaster recovery services, will contribute to India Data Center Market Growth.
Evaluation of Restraints in India Data Center Market
Below mentioned are some major restraints and their influence on market dynamics.
|
Market Restraint |
Primary Segment Affected |
Why It Matters (Evidence) |
|
Grid power constraints in leading hubs |
Colocation Data Center |
Large campuses need dependable multi-megawatt connections, and delays in grid access defer commissioning in Mumbai, which hosts about half of national capacity. |
|
Land and water stress in metropolitan clusters |
Tier III |
Cooling and site selection depend on land and water access, and the 2019 water crisis in Chennai showed how scarcity can raise operating risk for facilities. |
|
Import dependence for IT and cooling equipment |
Enterprise Data Center |
Servers, accelerators and chillers are largely imported, so currency swings and delivery lead times raise project costs, and the rupee touched record lows against the US dollar in 2025. |
|
Fragmented state-level approvals and incentives |
Managed Data Center |
Developers must comply with separate land, power and incentive frameworks in each state, which lengthens planning, as seen in distinct data centre policies issued by Tamil Nadu and Uttar Pradesh in 2021. |
|
Limited pool of critical-infrastructure engineers |
Tier IV |
Fault-tolerant designs targeting 99.995 per cent availability need specialised design and operations staff, and their scarcity slows delivery of the highest-rated facilities. |
India Data Center Market Challenges
However, despite its promising growth prospects, the India data center industry still faces a number of obstacles. One of them is relatively high prices of land and electricity, as data centers need sufficient land plots that will provide reliable electricity. The issue of sustainable and reliable power supply is an essential challenge to overcome as well. Although there is increasing pressure on businesses to incorporate renewables in their activities, it may be quite difficult to make such integration cost-effective. Skilled workforce shortages in data center operations, cloud technologies, and cybersecurity further constrain growth.
Trends in the India Data Center Market
Below mentioned are some of the trends shaping the India Data Center Market growth.
- Shift from Air-Cooled to Liquid-Cooled Halls: New halls in Mumbai and Chennai are being specified for GPU clusters whose heat output exceeds what conventional air systems can remove, and operators such as CtrlS and Yotta have positioned campuses for these tenants. Direct-to-chip and rear-door systems are appearing in new design briefs. Suppliers of coolant distribution units gain, while buyers must plan higher density contracts.
- Transition from Metro Concentration to Distributed Regional Hubs: Capacity is spreading beyond Mumbai and Chennai towards Hyderabad, Noida, Kolkata and Visakhapatnam, where Google has announced a large AI hub. Lower land costs and state incentives support the move, and edge sites are being placed nearer to users. Operators gain access to new buyers, while enterprises obtain lower latency and disaster-recovery options.
- Renewable Power Procurement Prioritised over Grid-Only Supply: Operators are signing open-access solar and wind agreements to secure cheaper and lower-carbon electricity, and CtrlS has committed to a 100 per cent renewable power target. Hyperscale tenants increasingly specify clean energy in leases. Developers with captive renewable supply gain pricing stability, while buyers see sustainability reporting become part of vendor selection.
Investment Opportunities in the India Data Center Market
Some of the investment opportunities in the India Data Center Market are mentioned below.
- AI-Ready High-Density Halls: Demand for GPU hosting is outpacing the supply of halls built for dense loads, creating room for new capacity in Mumbai, Chennai and Hyderabad. Investors can fund liquid-cooled halls with high-capacity power feeds and supply coolant distribution equipment. Entry is practical through joint ventures with established domestic developers that already hold land and grid connections.
- Edge Facilities in Emerging Cities: Low-latency services and state incentives make sites in Kolkata, Bhubaneswar, Lucknow and Visakhapatnam attractive. Investors can build modular facilities of a few megawatts and supply racks, power and connectivity services. Entry works through partnerships with state industrial development agencies and local telecom and fibre owners to secure land and network access.
- Renewable-Linked Campuses and Storage: Operators need cheaper and cleaner power to protect margins, which favours solar-wind hybrid supply and battery energy storage located near campuses. Investors can develop open-access renewable projects and storage systems dedicated to data centre loads. Entry is through power purchase agreements with developers in Tamil Nadu, Gujarat and Maharashtra, supported by transmission approvals.
- Modular and Prefabricated Infrastructure Manufacturing: Compressed delivery timelines are driving demand for factory-built power and cooling modules, which are mostly imported today. Investors can establish assembly of UPS systems, switchgear, busways and containerised halls close to Mumbai, Chennai and Pune. Entry is through licensing or joint ventures with global electrical OEMs, along with BIS certification for locally produced equipment.
Leading Players in India Data Center Market
Stated below are some of the leading companies contributing significantly to the India Data Center Market share.
1. CtrlS Datacenters
| Company Name | Company Name |
|---|---|
| Established Year | 2007 |
| Headquarters | Hyderabad, India |
| Official Website | Click Here |
CtrlS Datacenters is an Indian operator of hyperscale and enterprise-grade facilities offering colocation, managed hosting, and disaster recovery services. It serves banks, technology companies, and public-sector clients across India.
2. NTT Global Data Centers & Cloud Infrastructure India
| Company Name | Company Name |
|---|---|
| Established Year | 1998 |
| Headquarters | Mumbai, India |
| Official Website | Click Here |
NTT operates colocation and cloud-ready data centre campuses as part of its global data centre business. It supports enterprise and hyperscale customers through facilities in major Indian metropolitan areas.
3. ST Telemedia Global Data Centres (STT GDC India)
| Company Name | Company Name |
|---|---|
| Established Year | 2014 (STT GDC group) |
| Headquarters | Singapore |
| Official Website | Click Here |
STT GDC India develops and operates hyperscale and colocation facilities serving cloud providers, enterprises, and digital businesses. It has an established presence across India's major data centre markets.
4. Yotta Infrastructure
| Company Name | Company Name |
|---|---|
| Established Year | 2019 |
| Headquarters | Mumbai, India |
| Official Website | Click Here |
Yotta Infrastructure builds and manages large-scale data centre parks and offers colocation and GPU-based computing services. It serves hyperscale, enterprise, and AI-focused workloads.
5. Sify Technologies
| Company Name | Company Name |
|---|---|
| Established Year | 1995 |
| Headquarters | Chennai, India |
| Official Website | Click Here |
Sify Technologies is an Indian information and communications technology provider operating data centres alongside network, cloud, and managed services. It serves enterprise, financial services, and government customers across India.
Government Initiatives in the India Data Center Market
In India, the promotion of data centers as a major element of digital infrastructure has been taken up seriously by the Government. The IT Act of India includes certain data localization requirements while the RBI has certain regulations that mandate the storage of sensitive data within India. This makes it important to develop data centers in India. Other such initiatives at the national level include the program 'Digital India', which promotes cloud computing and e-governance.
India’s government has initiated several initiatives to promote PLIs in electronics manufacturing, which helps indirectly in promoting data centers. At the state-level, competition among the states has increased in terms of attracting hyperscale data centers, which include initiatives such as land subsides, tax rebates, and single window clearance policy, including the Maharashtra's Data Center Policy 2023 and Telangana's Data Center Policy 2022.
Future Insight of the India Data Center Market
Future growth will be supported by expanding renewable generation, which will lower the power cost of large campuses, as India targets 500 GW of non-fossil capacity by 2030 after solar capacity passed 100 GW. New subsea cable landings on the western and eastern coasts will improve international latency and attract global platforms seeking regional capacity. Evolving data protection and sovereignty norms will keep sensitive workloads within national borders, sustaining demand for domestically hosted infrastructure. Rising institutional capital and listed real-estate platforms will fund the development of larger and more efficient campuses.
Market Segmentation Analysis
The report offers a comprehensive study of the market across its key segments. The chart below highlights the leading segment by market share in 2025 and the fastest-growing segment by CAGR over 2026–2032, followed by a detailed analysis of each segment. By Types – Colocation Data Center Leads, Cloud Data Center Expected to Grow Fastest
According to Ravi Bhandari, Research Head at 6Wresearch, the Colocation Data Center segment held the largest share of 40% in 2025, as enterprises and platforms lease racks in Mumbai, Chennai and Delhi NCR campuses to avoid building and powering their own facilities. The Cloud Data Center segment is expected to record the fastest CAGR of 14.2% during 2026–2032, driven by hyperscaler region additions and the growing use of GPU-based services across the country.
By Infrastructure Types – Tier III Leads, Tier IV Expected to Grow Fastest
Tier III facilities led with a 60% share in 2025, because their concurrent maintainability offers an economical balance of uptime and cost for most domestic and hyperscale tenants. Tier IV is expected to expand at the fastest CAGR of 15.8% through 2032, as payment networks and AI clusters demand fault-tolerant capacity that cannot tolerate planned downtime.
By Applications – Telecom & IT Leads, Healthcare Expected to Grow Fastest
Telecom & IT accounted for 40% of 2025 revenue, supported by India’s large IT services exporters and mobile operators serving over 900 million subscribers. Healthcare is projected to post the fastest CAGR of 15.4% in 2026–2032, as digitised patient records, telemedicine and the Ayushman Bharat Digital Mission raise demand for secure hosting.
By Regions – Western Leads, Eastern Expected to Grow Fastest
Western India commanded 40% of 2025 revenue, anchored by Mumbai and Navi Mumbai, which combine subsea cable landings, dense financial activity and the country’s largest hyperscale campuses. Eastern India is expected to grow at the fastest CAGR of 14.7% during 2026–2032, as Kolkata and Bhubaneswar attract edge and disaster-recovery capacity at lower land costs.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Data Center Market Outlook
- Market Size of India Data Center Market, 2025
- Forecast of India Data Center Market, 2032
- Historical Data and Forecast of India Data Center Revenues & Capacity for the Period 2022-2032
- India Data Center Market Trend Evolution
- India Data Center Market Drivers and Challenges
- India Data Center Price Trends
- India Data Center Porter's Five Forces
- India Data Center Industry Life Cycle
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Types for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Enterprise Data Center for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Managed Data Center for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Cloud Data Center for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Colocation Data Center for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Infrastructure Types for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Tier I for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Tier II for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Tier III for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Tier IV for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Applications for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By BFSI for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Telecom & IT for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Government for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Healthcare for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Others (Hospitality, Retail) for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Regions for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Northern India for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Southern India for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Western India for the Period 2022-2032
- Historical Data and Forecast of India Data Center Market Revenues & Capacity By Eastern India for the Period 2022-2032
- India Data Center Import Export Trade Statistics
- Market Opportunity Assessment By Types
- Market Opportunity Assessment By Infrastructure Types
- Market Opportunity Assessment By Applications
- Market Opportunity Assessment By Regions
- India Data Center Top Companies Market Share
- India Data Center Competitive Benchmarking By Technical and Operational Parameters
- India Data Center Company Profiles
- India Data Center Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments:
By Types
- Enterprise Data Center
- Managed Data Center
- Cloud Data Center
- Colocation Data Center
By Infrastructure Types
- Tier I
- Tier II
- Tier III
- Tier IV
By Applications
- BFSI
- Telecom & IT
- Government
- Healthcare
- Others (Hospitality, Retail)
By Regions
- Northern
- Southern
- Western
- Eastern































