India In-Flight Connectivity Market Size & Growth Rate
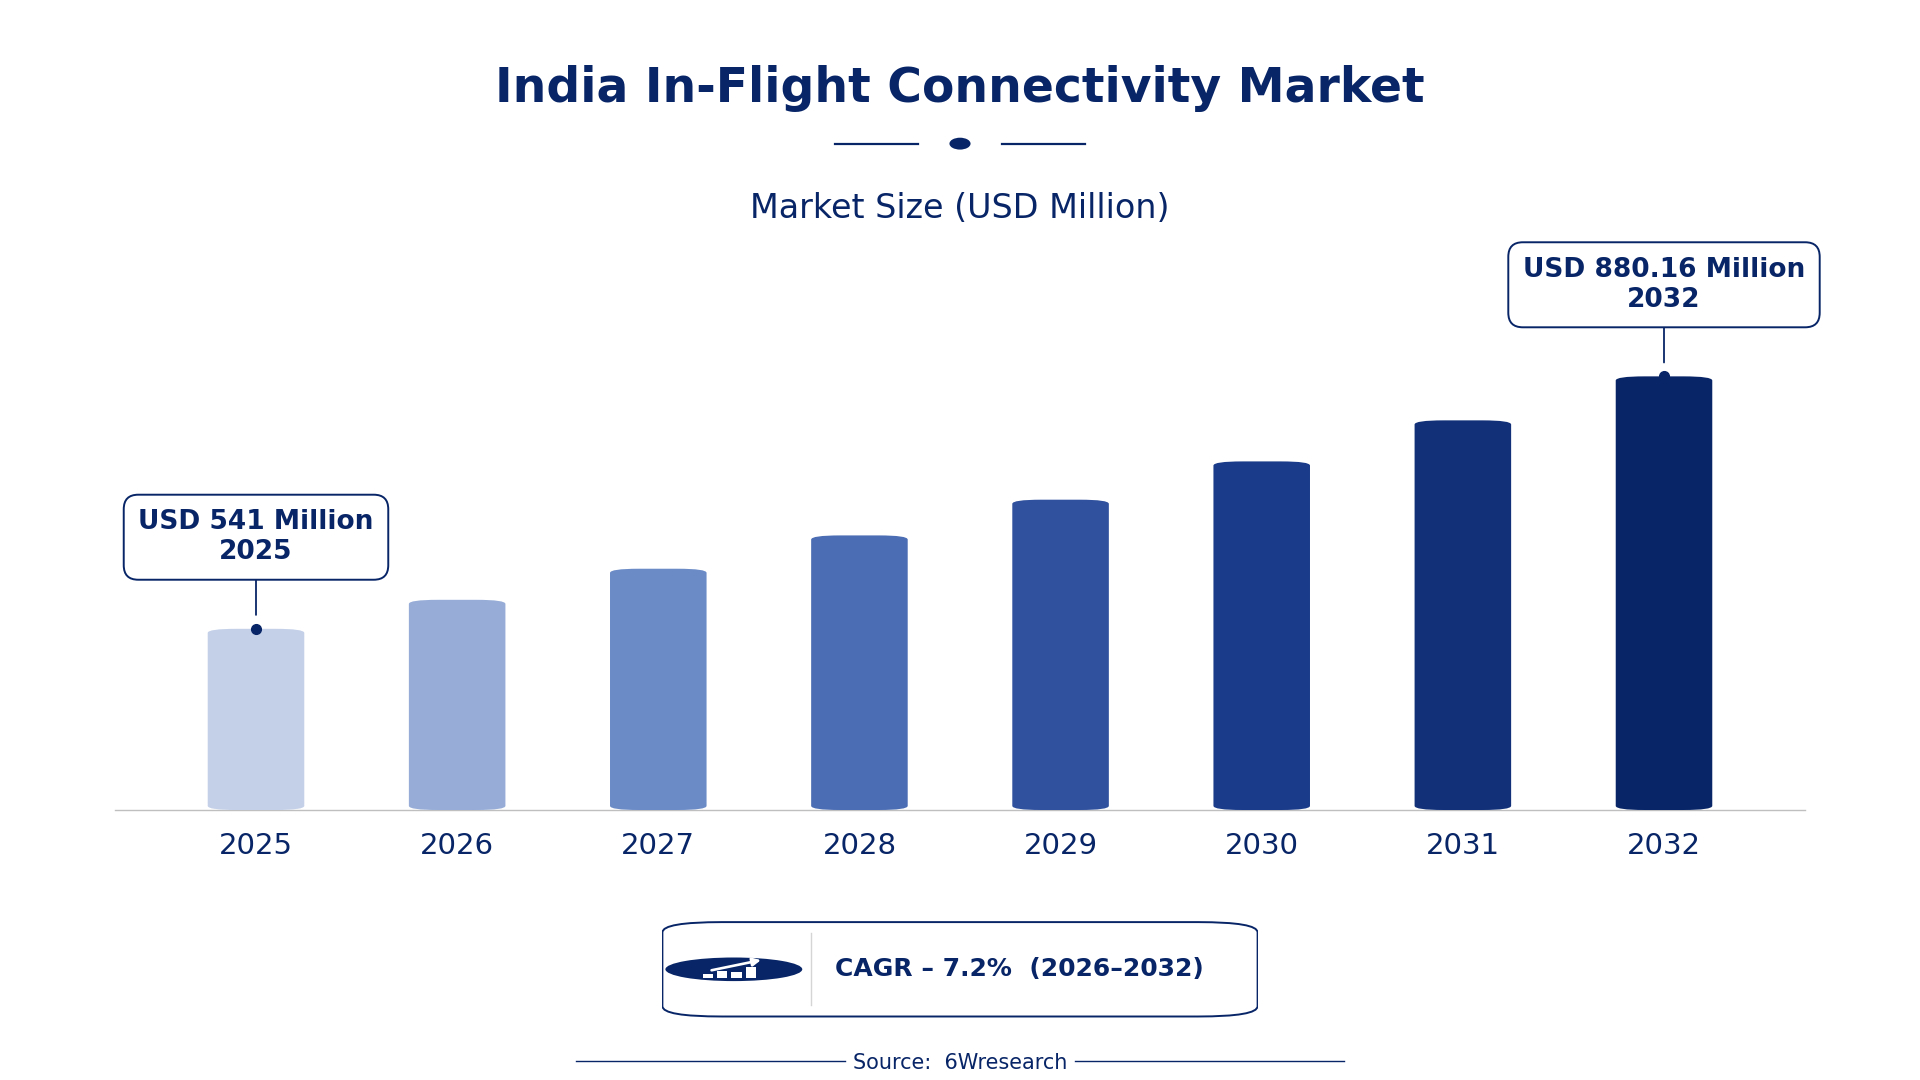
According to 6Wresearch internal database and industry insights, the India In-Flight Connectivity Market was valued at USD 541.0 million in 2025 and is projected to reach USD 880.16 million by 2032, growing at a CAGR of approximately 7.2% during 2026–2032.
India In-Flight Connectivity Market Highlights
| Report Metric | Details |
| Report Name | India In-Flight Connectivity Market |
| Market Size 2025 | USD 541.0 million |
| Market Size 2032 | USD 880.16 million |
| Absolute Growth 2025–2032 | USD 339.16 million |
| CAGR 2026–2032 | 7.2% |
| Peak Annual Growth | 9.2% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Connectivity Type, 2025 | Satellite-Based (52% share) |
| Leading Frequency Band, 2025 | Ku / Ka / L Band (38% share) |
| Leading Service Type, 2025 | Wi-Fi / VPN (40% share) |
| Leading Distribution Channel, 2025 | Satellite Network Vendors (46% share) |
| Fastest-Growing Connectivity Type | Hybrid Systems (9.4% CAGR) |
| Fastest-Growing Frequency Band | ATG / LTE (9.4% CAGR) |
| Fastest-Growing Service Type | Real-Time Browsing (9.9% CAGR) |
| Fastest-Growing Distribution Channel | Telecom Operators (9.3% CAGR) |
| Growing Sector | Aviation |
| Key End Users | Airlines, Passengers, Airport Authorities, Connectivity Service Providers |
India In-Flight Connectivity Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
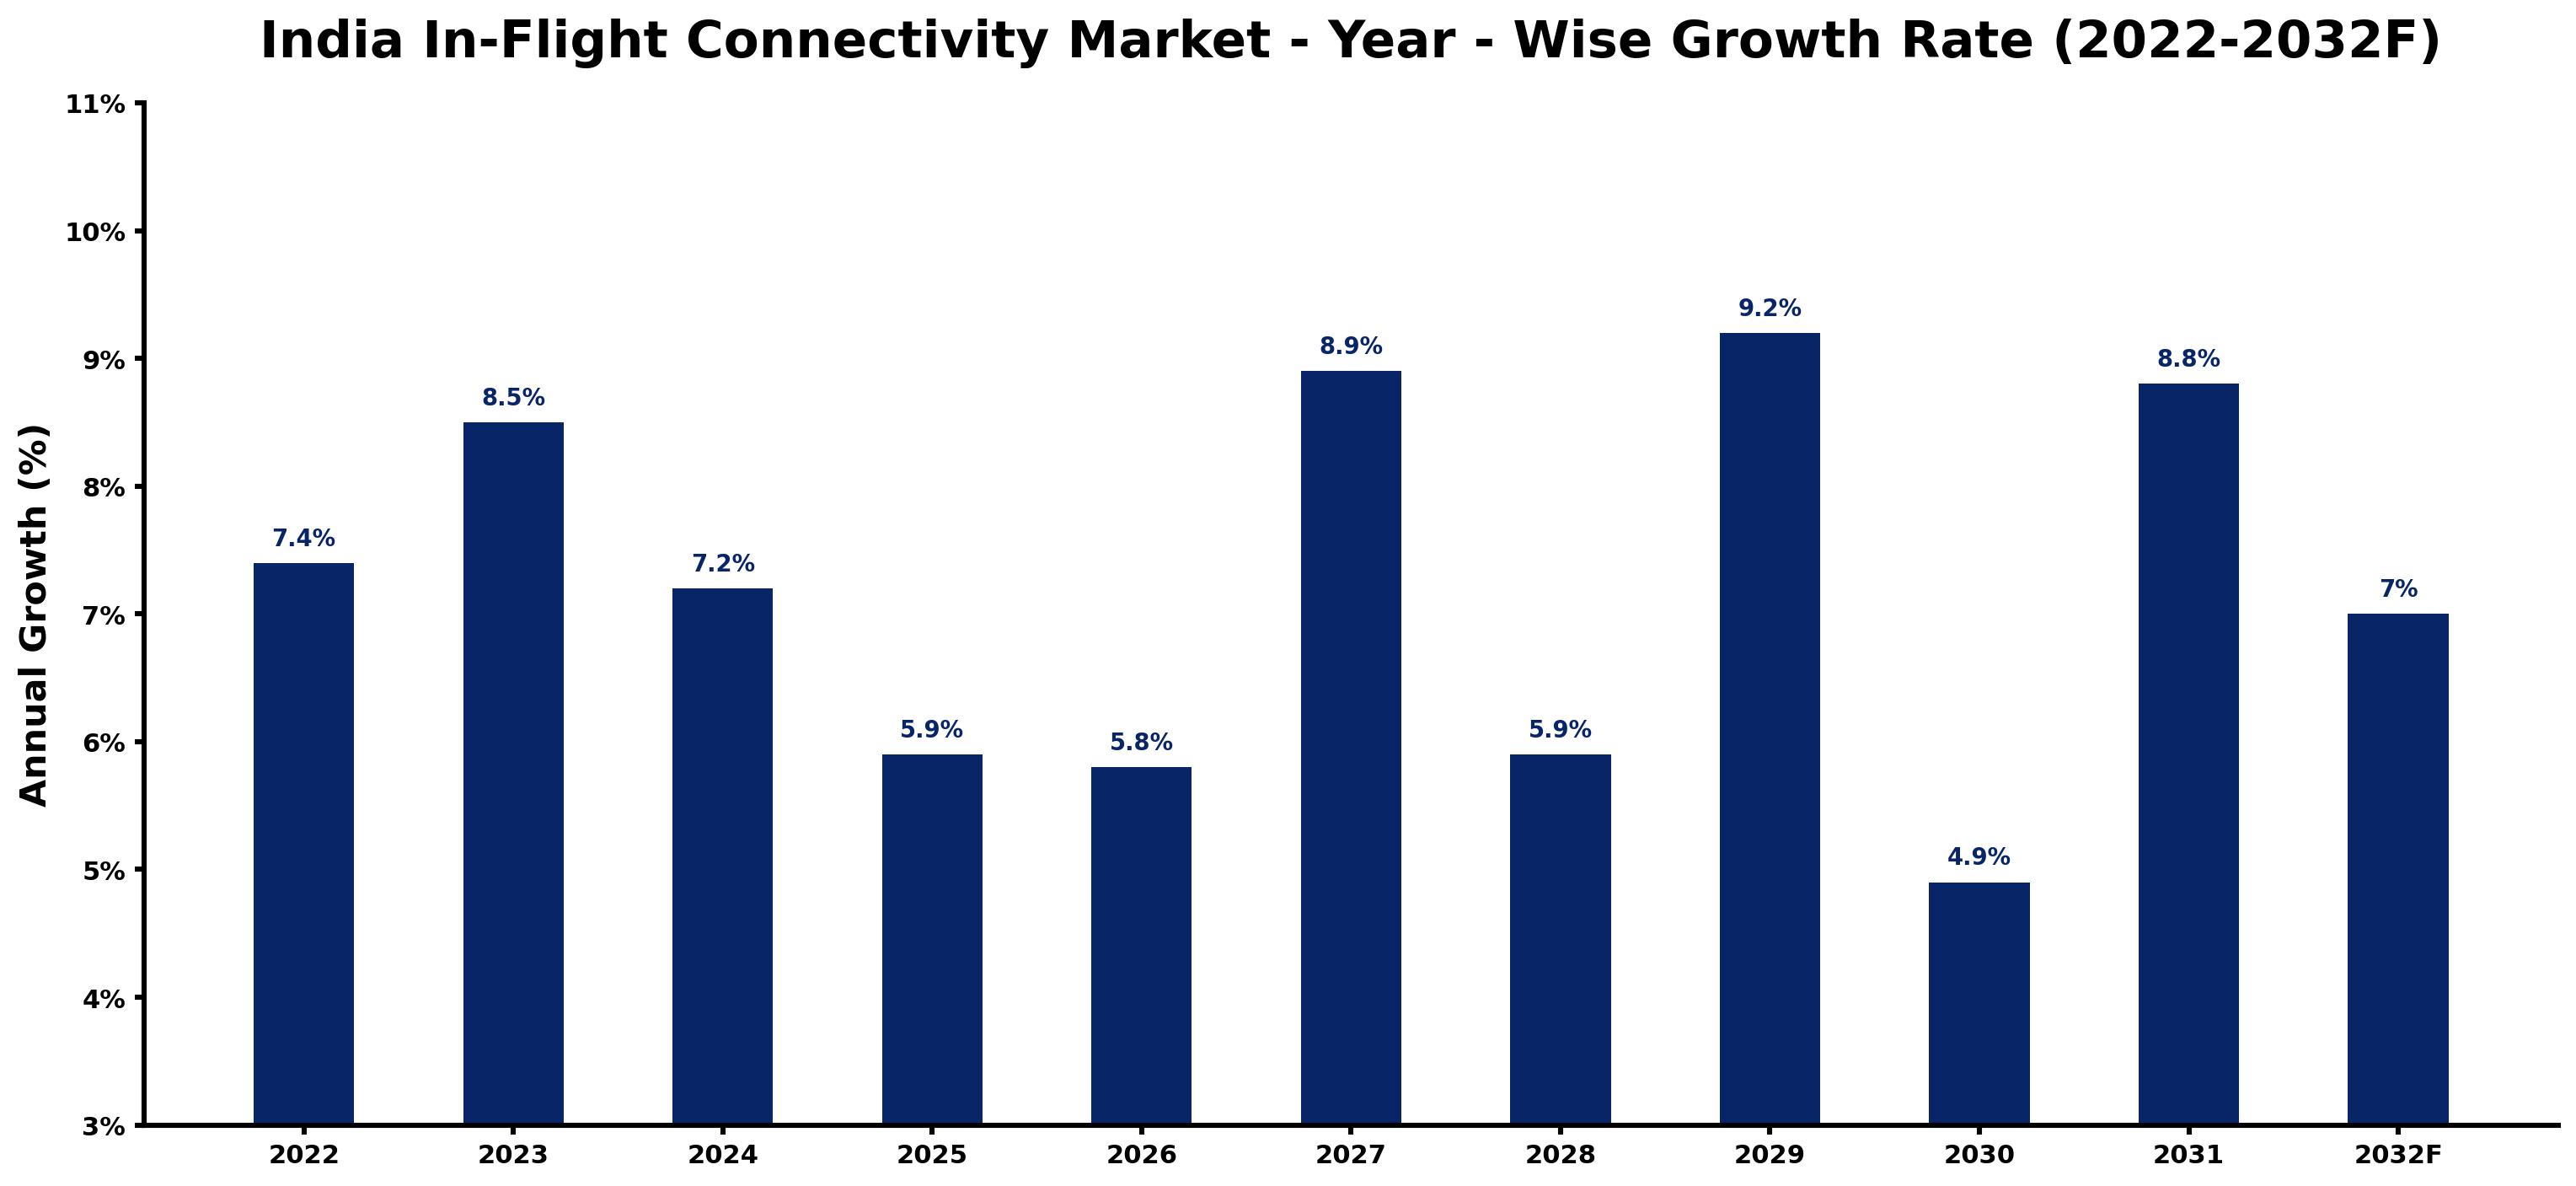
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.4 | The market saw a steady demand for in-flight connectivity services among airlines. |
| 2023 | 8.5 | Increased passenger traffic and service offerings led to faster growth than in 2022. |
| 2024 | 7.2 | A slight slowdown occurred as airlines adjusted to new service standards and regulations. |
| 2025 | 5.9 | The market experienced further slowdown due to the 'UDAN' scheme's implementation for regional connectivity. |
| 2026 | 5.8 | Growth is expected to slow as airlines focus on cost management and service efficiency. |
| 2027 | 8.9 | An uptick in demand will be driven by rising air travel and new service offerings. |
| 2028 | 5.9 | The market will slow as airlines manage existing service contracts and infrastructure. |
| 2029 | 9.2 | A peak growth rate is expected due to heightened demand for connectivity during flights. |
| 2030 | 4.9 | Growth is projected to slow as airlines focus on maintaining service quality amid rising costs. |
| 2031 | 8.8 | An increase in growth will be driven by new service introductions and passenger expectations. |
| 2032 | 7.0 | The market is expected to slow as competition intensifies and service differentiation becomes important. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India In-Flight Connectivity Market Synopsis
In-Flight Connectivity in India enables internet access and communication services on aircraft through satellite systems or air-to-ground networks. This technology provides passengers with Wi-Fi, streaming services, and real-time browsing capabilities. The India In-Flight Connectivity Market is expanding due to increasing passenger traffic, projected to reach 1.1 billion by 2030, alongside government initiatives like the 'UDAN' scheme, which aims for 100% connectivity in regional air transport by 2025. As more airlines adopt these services, demand for reliable connectivity continues to grow.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising passenger traffic and demand for connectivity services | Driver | High | Managed Connectivity |
| Government initiatives promoting regional connectivity | Driver | High | Satellite-Based |
| Growing demand for high-speed internet during flights | Opportunity | High | Wi-Fi / VPN |
| Investment in airport infrastructure to support connectivity | Opportunity | High | Air-to-Ground |
| High costs associated with implementing advanced connectivity systems | Restraint | High | Hybrid Systems |
| Limited availability of satellite bandwidth in certain regions | Restraint | Medium | Satellite-Based |
| In-Flight Connectivity market in India faces regulatory hurdles | Challenge | High | Managed Connectivity |
| Competition from alternative connectivity solutions | Challenge | Medium | Air-to-Ground |
Evaluation of Drivers in India In-Flight Connectivity Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased passenger traffic | Managed Connectivity | India's aviation sector is projected to reach 1.1 billion passengers by 2030, driving demand for connectivity services. |
| Government initiatives like 'UDAN' | Satellite-Based | The 'UDAN' scheme aims for 100% connectivity in regional air transport by 2025, driving demand for in-flight services. |
| Demand for high-speed internet | Wi-Fi / VPN | Over 70% of Indian airlines now offer in-flight Wi-Fi services, reflecting passenger expectations for reliable internet access. |
| Investment in airport infrastructure | Air-to-Ground | The Indian government allocated INR 500 crore for airport upgrades by 2023, supporting connectivity systems and improving service quality. |
| Adoption of ITU standards | Ku / Ka / L Band | India's adoption of ITU standards improves satellite communication capabilities, increasing service reliability. |
The aviation sector is projected to reach 1.1 billion passengers by 2030, prompting airlines to improve connectivity services. The 'UDAN' scheme aims for 100% connectivity in regional air transport by 2025, further driving demand. More than 70% of airlines now offer Wi-Fi, reflecting the need for reliable internet access.
Evaluation of Restraints in India In-Flight Connectivity Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High implementation costs for advanced systems | Hybrid Systems | The costs associated with integrating hybrid systems can deter airlines from adopting new technologies. |
| Limited satellite bandwidth availability | Satellite-Based | Certain regions face bandwidth limitations, restricting the quality of in-flight connectivity services. |
| Regulatory hurdles in service provision | Managed Connectivity | The regulatory environment can complicate the approval process for new connectivity services. |
| Operational challenges in maintaining service quality | Air-to-Ground | Airlines often struggle to maintain consistent service quality due to ground-based limitations. |
| Competition from alternative connectivity solutions | Air-to-Ground | Emerging technologies may divert investment away from traditional in-flight connectivity systems. |
India In-Flight Connectivity Market Challenges
The India In-Flight Connectivity market encounters a major technological barrier due to limited satellite coverage, which disrupts consistent service for airlines. This issue arises from reliance on outdated satellite systems, leading to connectivity interruptions that frustrate passengers. High installation costs for in-flight systems hinder smaller airlines from adopting these technologies, limiting service options for buyers and potentially increasing ticket prices. A shortage of skilled technicians in the aviation sector further delays the rollout of connectivity solutions, causing extended implementation timelines that negatively impact airlines' ability to meet customer expectations.
Trends in the India In-Flight Connectivity Market
Buyers and suppliers in the India In-Flight Connectivity Market are adjusting to the following trends.
- Shift towards High-Speed Connectivity: Indian airlines are increasingly adopting high-speed in-flight connectivity solutions, with over 80% offering Wi-Fi services as of 2023. This shift reflects growing passenger demand for reliable internet access during flights.
- Increased Government Support for Connectivity: The Indian government is promoting in-flight connectivity through initiatives like the 'UDAN' scheme, aiming for 100% connectivity in regional air transport by 2025. This support is expected to improve service availability across the country.
- Emergence of Real-Time Browsing Services: Real-time browsing services are gaining popularity among passengers, with a projected CAGR of 9.9% for this segment from 2026 to 2032. This trend highlights the demand for improved in-flight internet experiences.
- Growing Adoption of ITU Standards: India's adoption of ITU standards for satellite communications is streamlining in-flight connectivity services, ensuring compliance and reliability. This shift is important for improving service quality and passenger satisfaction.
Investment Opportunities in the India In-Flight Connectivity Market
The following opportunities in the India In-Flight Connectivity Market pair current demand with a clear way in.
- Airlines seeking advanced connectivity solutions: With a projected 1.1 billion passengers by 2030, airlines are looking for advanced in-flight connectivity solutions to meet demand. Investing in high-speed Wi-Fi services can attract more customers.
- Investment in satellite technology: The growing need for reliable connectivity presents an opportunity to invest in satellite technology. The government’s focus on indigenous technology can benefit local suppliers and service providers.
- Entry into regional markets: The push for 100% connectivity in regional air transport by 2025 creates opportunities for companies to supply connectivity solutions. Partnering with local airlines can facilitate market entry.
- Focus on infrastructure upgrades: The Indian government's allocation of INR 500 crore for airport infrastructure upgrades presents a chance to supply advanced connectivity systems. Collaborating with airport authorities can improve service offerings.
Government Initiatives in the India In-Flight Connectivity Market
In 2022, the Indian government launched the 'National In-Flight Connectivity Policy' to streamline regulations for service providers. This policy aims to enhance service quality and ensure compliance with international standards. The Telecom Regulatory Authority of India (TRAI) established guidelines for in-flight connectivity in 2021 to improve passenger services. These measures are designed to create a more efficient regulatory environment for connectivity services and enhance the overall passenger experience.
In 2023, the Indian government approved a budget of INR 500 crore for upgrading airport technology, including in-flight connectivity systems. The Airports Authority of India (AAI) oversees the implementation of these upgrades, ensuring that connectivity services meet regulatory standards. The Bureau of Civil Aviation Security (BCAS) updated security protocols for in-flight connectivity in 2023 to ensure passenger safety. These measures are essential for maintaining service quality and improving the overall passenger experience.
Future Insight of the India In-Flight Connectivity Market
The India In-Flight Connectivity market is poised for transformation by 2032, driven by several key developments. The government's target of achieving 100% connectivity in regional air transport by 2025 will enhance service availability nationwide. With India's aviation sector projected to reach 1.1 billion passengers by 2030, the demand for connectivity will rise sharply. The upcoming national policy for in-flight connectivity, expected in 2024, will streamline regulations and elevate service quality. Additionally, the promotion of indigenous technology will encourage local innovations and reduce dependence on foreign solutions.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Connectivity Type – Satellite-Based Dominated, Hybrid Systems Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, in 2025, Satellite-Based led the connectivity type split with a 52% share. Satellite-based connectivity holds the largest market share due to its critical role in ensuring global coverage, especially in remote regions. This is essential for airlines operating in diverse geographical areas, providing uninterrupted service for passengers throughout their flights. The quickest growth will come from Hybrid Systems, forecast to expand at a CAGR of 9.4% between 2026 and 2032. Hybrid systems are rapidly gaining traction as they effectively combine the strengths of both satellite and ground systems, catering to the increasing demand for reliable connectivity. This integration allows airlines to enhance service quality while managing operational costs more efficiently. Suppliers should focus on developing hybrid solutions to meet the rising expectations of airlines and passengers.
By Frequency Band – Ku / Ka / L Band Dominated, ATG / LTE Expected to Grow Fastest
Ku / Ka / L Band accounted for a 38% market share by frequency band in 2025. The Ku / Ka / L Band dominates the market share as these frequency bands are vital for effective satellite communications, enabling high-speed internet access. This is particularly important for airlines aiming to provide superior connectivity services to their passengers. ATG / LTE is set to record the highest CAGR in this split, 9.4% over 2026–2032. ATG / LTE is experiencing significant growth as it improves ground-based connectivity options, offering a practical alternative for airlines looking to enhance service delivery. The increasing demand for faster and more reliable internet access during flights is driving the adoption of these technologies. Buyers should consider the advantages of integrating ATG / LTE solutions to complement their existing satellite services.
By Service Type – Wi-Fi / VPN Dominated, Real-Time Browsing Expected to Grow Fastest
The largest service type category in 2025 was Wi-Fi / VPN, with a 40% share of total revenue. Wi-Fi / VPN services lead the market due to their widespread adoption as the primary service offered to passengers on flights. This service type has become essential for airlines to meet passenger expectations for connectivity during travel. Real-Time Browsing is projected to grow fastest, at a CAGR of 9.9% during 2026–2032. Real-time browsing is rapidly gaining traction as it allows passengers to access the internet seamlessly, meeting the growing demand for instant connectivity. The rise in passenger expectations for uninterrupted online experiences during flights drives this growth. Suppliers must prioritise real-time browsing capabilities to stay competitive in the in-flight connectivity market.
By Distribution Channel – Satellite Network Vendors Dominated, Telecom Operators Expected to Grow Fastest
Satellite Network Vendors took a 46% share of distribution channel in 2025, more than any other category. Satellite network vendors capture the largest market share as they supply the essential infrastructure for in-flight connectivity, allowing airlines to access reliable services. Their role is pivotal in fulfilling the operational needs of airlines across various routes. Over 2026–2032, Telecom Operators are expected to post the fastest growth, at a CAGR of 9.3%. Telecom operators are witnessing the fastest growth as they increasingly provide connectivity solutions, thereby improving overall service quality for passengers. Their participation is crucial as airlines aim to diversify their connectivity options and enhance operational efficiency. Suppliers should explore partnerships with telecom operators to expand their distribution channels and improve service offerings.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India In-Flight Connectivity Market Outlook
- Market Size of India In-Flight Connectivity Market, 2025
- Forecast of India In-Flight Connectivity Market, 2032
- Historical Data and Forecast of India In-Flight Connectivity Revenues & Volume for the Period 2022 - 2032F
- India In-Flight Connectivity Market Trend Evolution
- India In-Flight Connectivity Market Drivers and Challenges
- India In-Flight Connectivity Price Trends
- India In-Flight Connectivity Porter's Five Forces
- India In-Flight Connectivity Industry Life Cycle
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Connectivity Type for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Satellite-Based for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Air-to-Ground for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Hybrid Systems for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Managed Connectivity for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Frequency Band for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Ku / Ka / L Band for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By ATG / LTE for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Satellite + ATG for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Subscription Model for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Service Type for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Wi-Fi / VPN for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Streaming / Messaging for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Real-Time Browsing for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By B2B Airline Services for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Satellite Network Vendors for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Telecom Operators for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By Aircraft OEM Integration for the Period 2022 - 2032F
- Historical Data and Forecast of India In-Flight Connectivity Market Revenues & Volume By SaaS Platforms for the Period 2022 - 2032F
- India In-Flight Connectivity Import Export Trade Statistics
- Market Opportunity Assessment By Connectivity Type
- Market Opportunity Assessment By Frequency Band
- Market Opportunity Assessment By Service Type
- Market Opportunity Assessment By Distribution Channel
- India In-Flight Connectivity Top Companies Market Share
- India In-Flight Connectivity Competitive Benchmarking By Technical and Operational Parameters
- India In-Flight Connectivity Company Profiles
- India In-Flight Connectivity Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Connectivity Type
- Satellite-Based
- Air-to-Ground
- Hybrid Systems
- Managed Connectivity
By Frequency Band
- Ku / Ka / L Band
- ATG / LTE
- Satellite + ATG
- Subscription Model
By Service Type
- Wi-Fi / VPN
- Streaming / Messaging
- Real-Time Browsing
- B2B Airline Services
By Distribution Channel
- Satellite Network Vendors
- Telecom Operators
- Aircraft OEM Integration
- SaaS Platforms































