India Indoor Entertainment Market Size & Growth Rate
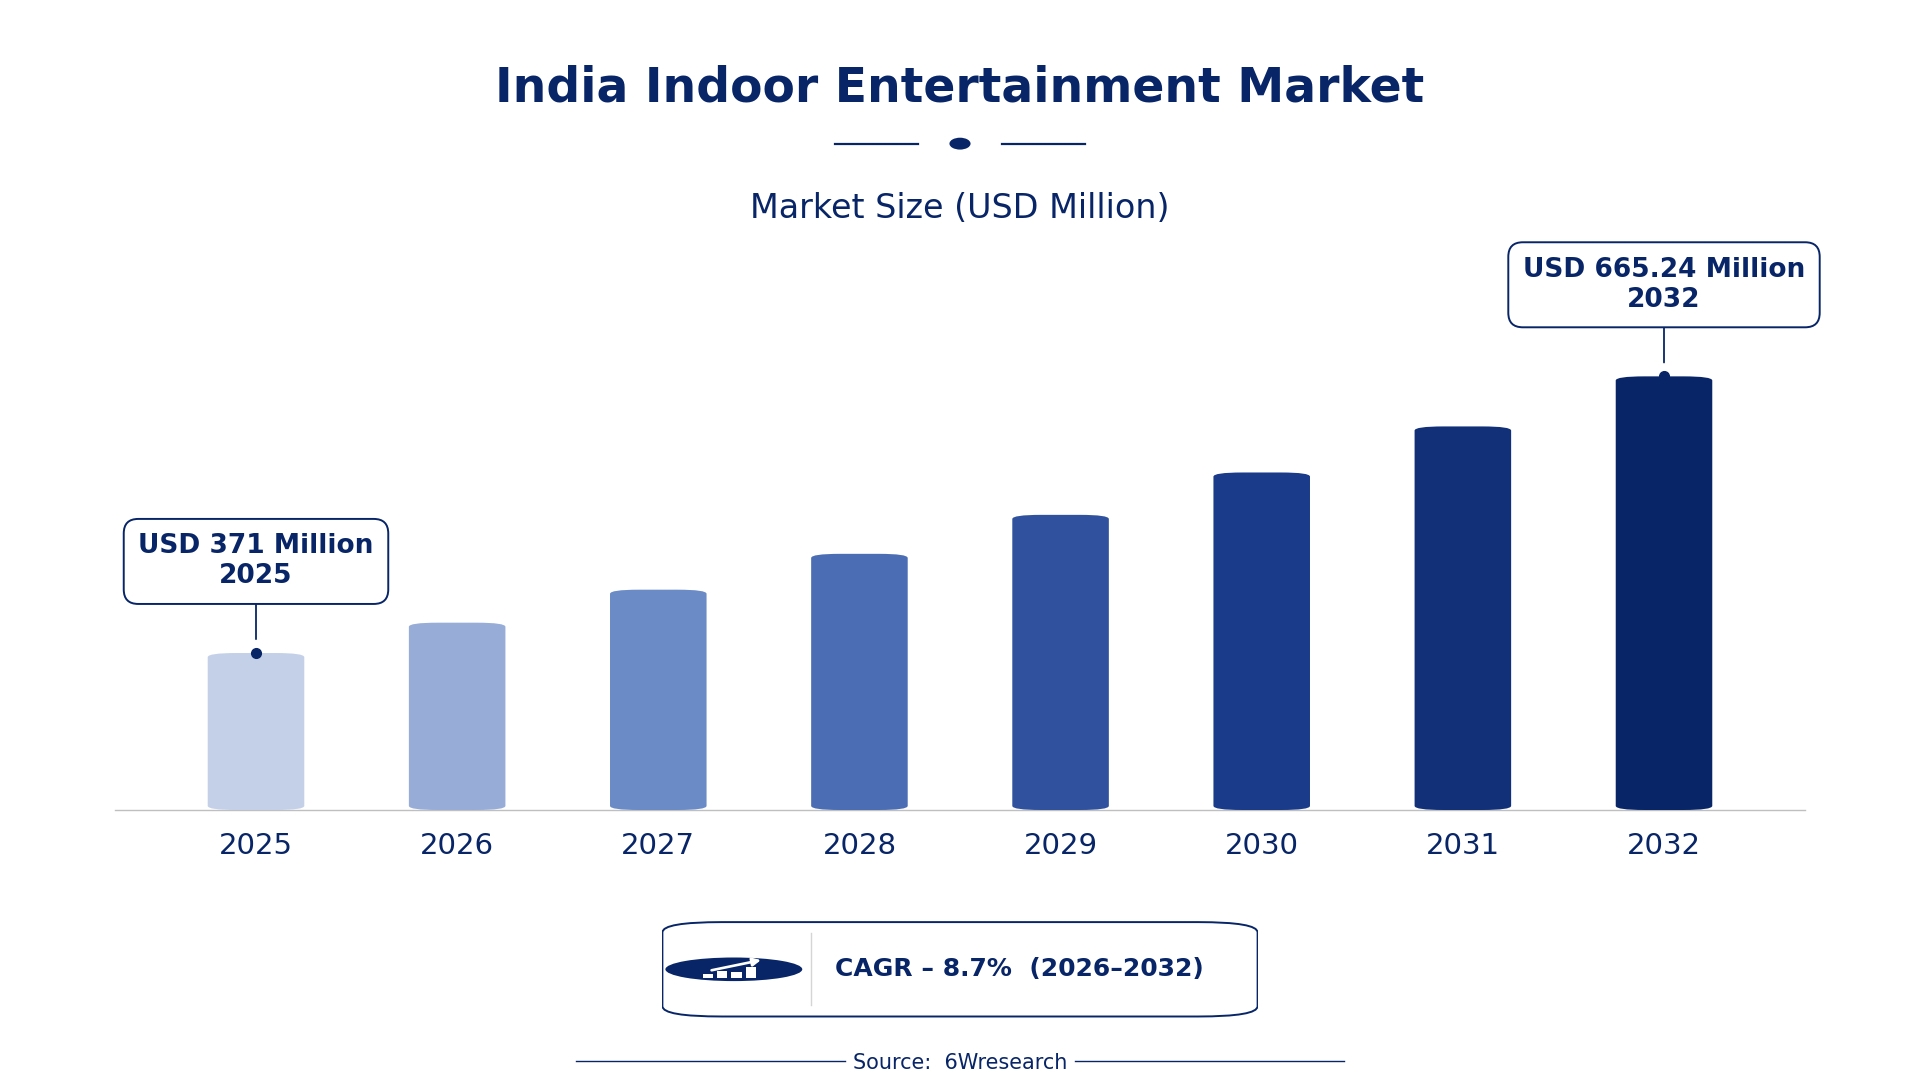
According to 6Wresearch internal database and industry insights, the India Indoor Entertainment Market was valued at USD 371.0 million in 2025 and is projected to reach USD 665.24 million by 2032, growing at a CAGR of approximately 8.7% during 2026–2032.
India Indoor Entertainment Market Highlights
| Report Metric | Details |
| Report Name | India Indoor Entertainment Market |
| Market Size 2025 | USD 371.0 million |
| Market Size 2032 | USD 665.24 million |
| Absolute Growth 2025–2032 | USD 294.24 million |
| CAGR 2026–2032 | 8.7% |
| Peak Annual Growth | 11.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Entertainment Type, 2025 | Indoor Theme Parks (46% share) |
| Leading Venue Type, 2025 | Urban Malls (46% share) |
| Leading Content Type, 2025 | VR Games (43% share) |
| Leading End User, 2025 | Gaming Arcades (38% share) |
| Fastest-Growing Entertainment Type | Virtual Reality Zones (9.9% CAGR) |
| Fastest-Growing Venue Type | Game Centers (10.8% CAGR) |
| Fastest-Growing Content Type | Edutainment (10.4% CAGR) |
| Growing Sector | Indoor Theme Parks |
| Key End Users | Families, Tourists, Urban Malls, Educational Institutions |
India Indoor Entertainment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
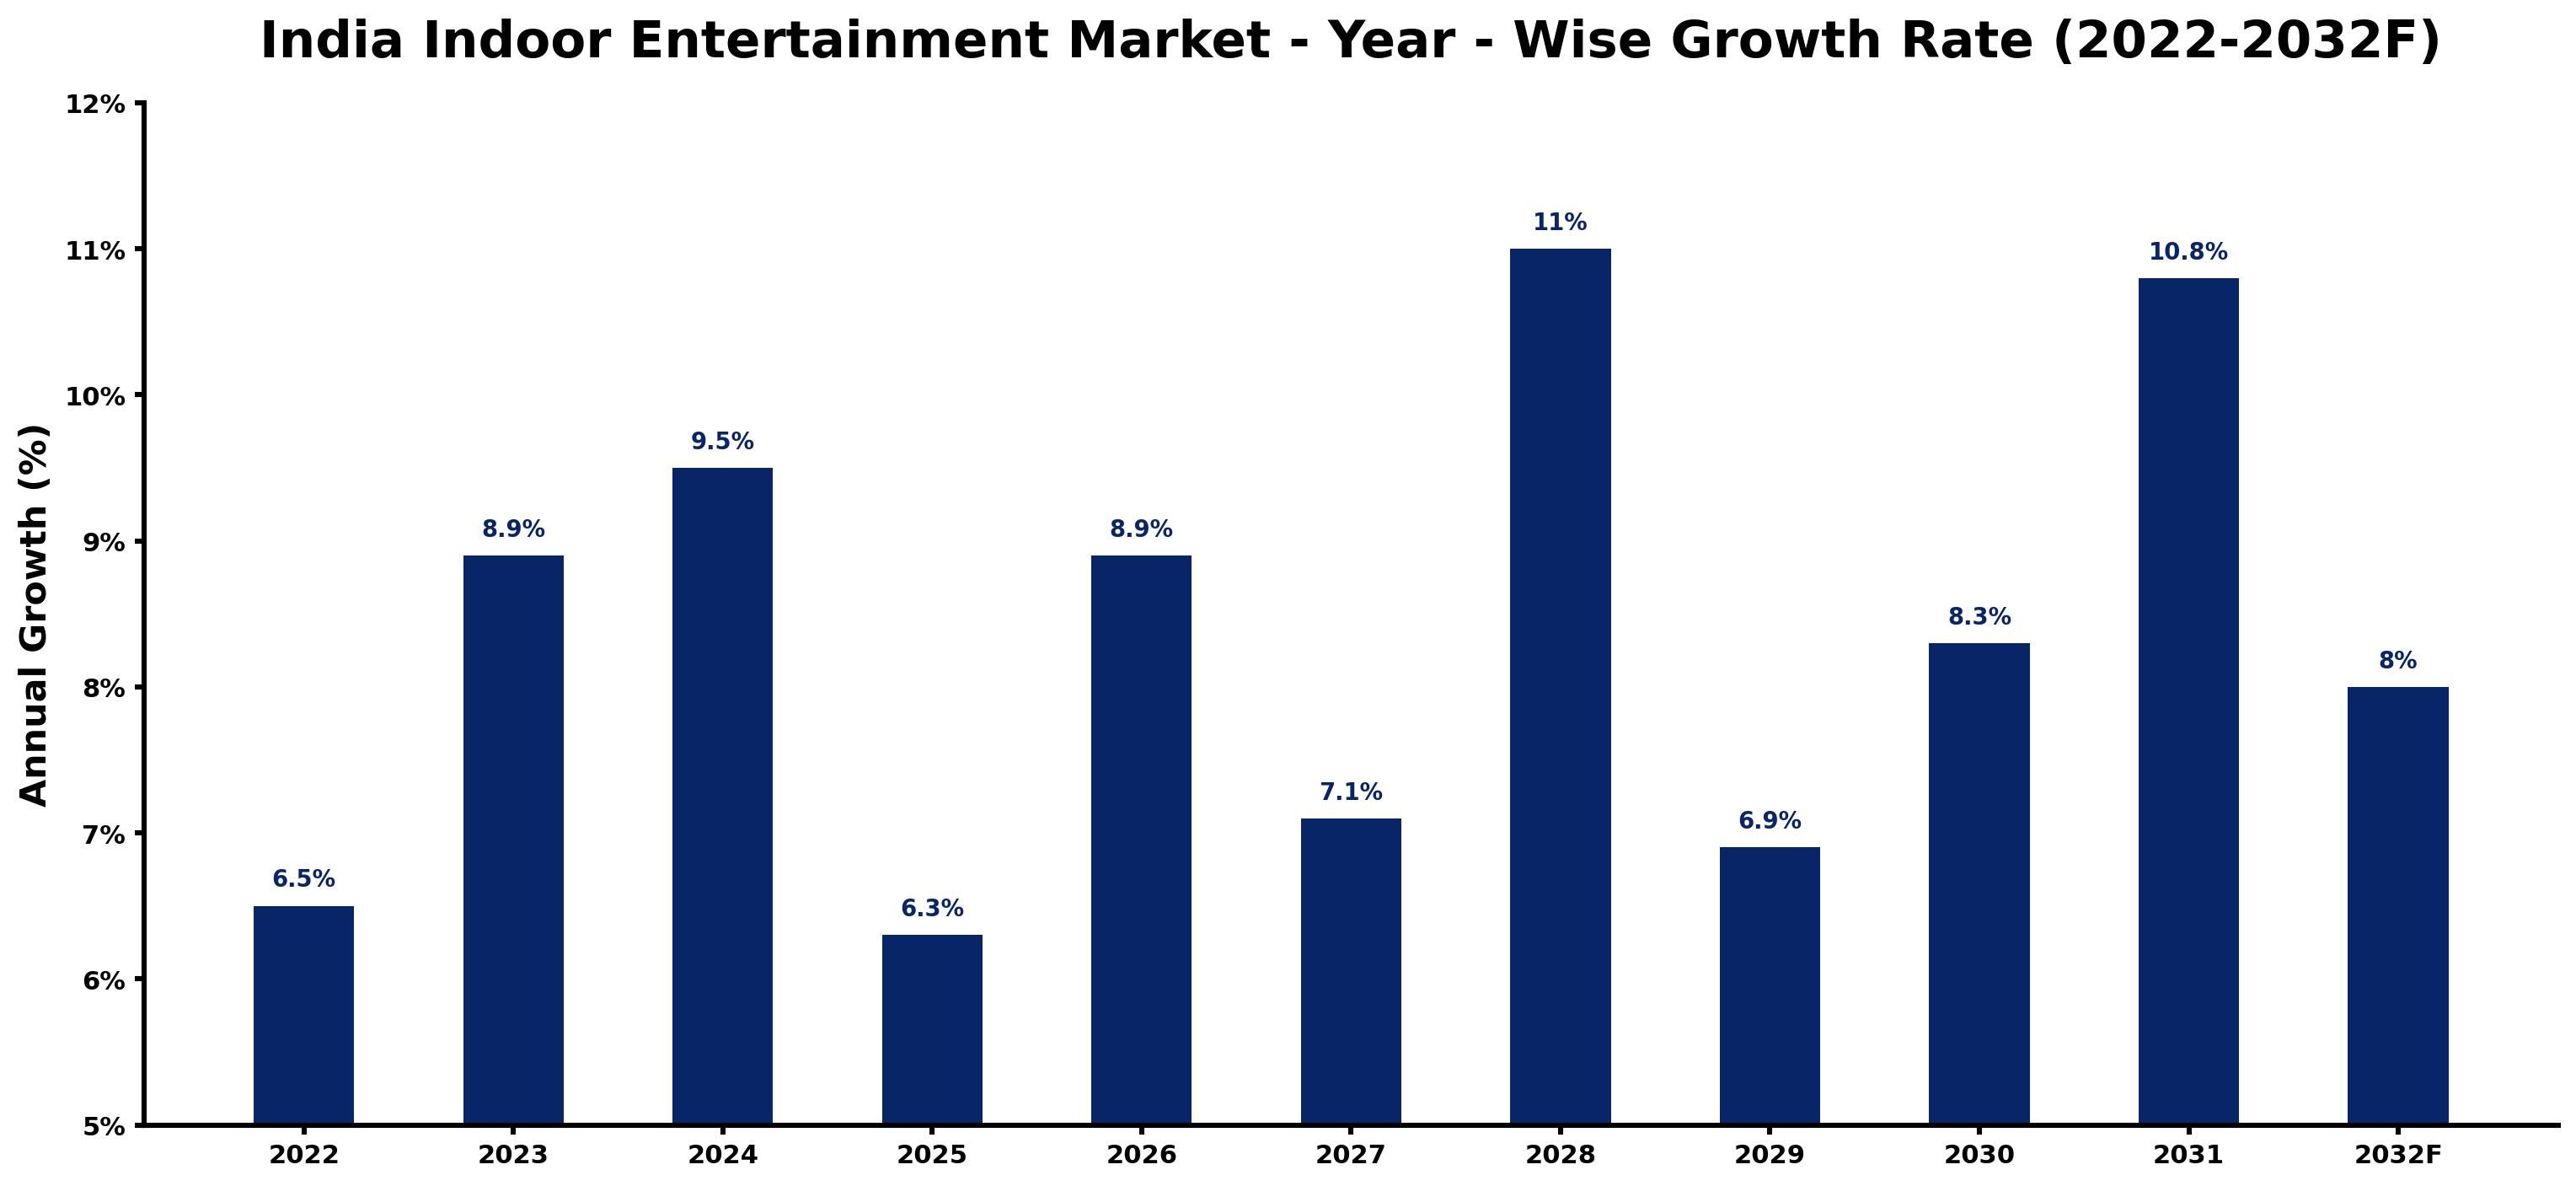
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.5 | The market experienced steady growth, driven by increased urbanisation and leisure activities. |
| 2023 | 8.9 | Demand accelerated due to the rise of indoor entertainment options in urban centres. |
| 2024 | 9.5 | Growth continued as new attractions and facilities opened across major cities. |
| 2025 | 6.3 | A slight slowdown occurred as competition intensified in the entertainment sector. |
| 2026 | 8.9 | Growth picked up again as investments in indoor attractions increased significantly. |
| 2027 | 7.1 | A moderate slowdown was noted as market saturation began in some urban areas. |
| 2028 | 11.0 | The market peaked with the introduction of innovative entertainment technologies and experiences. |
| 2029 | 6.9 | Growth slowed slightly as new developments faced regulatory challenges. |
| 2030 | 8.3 | A rebound in growth was driven by increased consumer spending on leisure activities. |
| 2031 | 10.8 | Demand surged again as urban malls expanded their entertainment offerings. |
| 2032 | 8.0 | Growth decelerated as the market matured and competition intensified. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Indoor Entertainment Market Synopsis
The Indoor Entertainment Market in India includes a range of activities designed for enjoyment in enclosed spaces, such as virtual reality and interactive exhibits. As of 2023, the market is valued at approximately INR 3,000 crore, reflecting a growing interest in leisure and recreational activities. Expansion is driven by urbanisation, a rising tourism sector, and increased investment in entertainment facilities. Urban malls and gaming arcades play a crucial role in this growth, catering to families and individuals seeking diverse entertainment options.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in infrastructure and entertainment facilities. | Driver | High | Urban Malls |
| Growing popularity of immersive experiences among consumers. | Driver | High | Virtual Reality Zones |
| Emerging demand for educational entertainment in schools and institutions. | Opportunity | Medium | Edutainment |
| Expansion of indoor theme parks catering to families and tourists. | Opportunity | High | Indoor Theme Parks |
| High operational costs for maintaining entertainment facilities. | Restraint | High | Indoor Theme Parks |
| Regulatory compliance costs for safety standards in amusement parks. | Restraint | Medium | Indoor Theme Parks |
| Limited availability of skilled workforce in the entertainment sector. | Challenge | High | Gaming Arcades |
| Intense competition among entertainment venues affecting profitability. | Challenge | Medium | Game Centers |
Evaluation of Drivers in India Indoor Entertainment Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Investment in new entertainment technologies and facilities. | Indoor Theme Parks | The average investment in a new indoor entertainment facility is around INR 10 crore, resulting in more attractions opening in urban areas. |
| Rising consumer interest in immersive experiences. | Virtual Reality Zones | The integration of virtual reality experiences in urban malls attracts a growing number of tech-savvy visitors. |
| Expansion of urban malls incorporating entertainment options. | Urban Malls | Indoor entertainment venues are often part of mixed-use developments in cities like Mumbai and Delhi. |
| Growth in tourism leading to increased footfall in entertainment venues. | Indoor Theme Parks | The 'Incredible India' campaign promotes tourism, boosting attendance at indoor entertainment attractions. |
| Emergence of edutainment centers in educational institutions. | Edutainment | With at least 20 new setups reported in 2023, educational institutions are increasingly adopting these facilities. |
The Indoor Entertainment market in India is growing on the back of increased investment in infrastructure, rising consumer interest in immersive experiences, and expanding end-use demand. The average investment in a new indoor entertainment facility is around INR 10 crore, resulting in more attractions opening in urban areas. The Indian gaming industry is projected to reach INR 29,000 crore by 2025, driving higher attendance at gaming arcades. The integration of virtual reality experiences in urban malls attracts a growing number of tech-savvy visitors, enhancing overall engagement. Additionally, the 'Incredible India' campaign promotes tourism, boosting attendance at indoor entertainment attractions.
Evaluation of Restraints in India Indoor Entertainment Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High operational costs for maintaining entertainment facilities. | Indoor Theme Parks | Operational costs can exceed INR 5 crore annually, impacting profitability for operators. |
| Regulatory compliance costs for safety standards in amusement parks. | Indoor Theme Parks | Facilities must comply with the Bureau of Indian Standards, increasing operational expenses. |
| Limited availability of skilled workforce in the entertainment sector. | Gaming Arcades | The 'Skill India Mission' targets training for 500,000 trainees, but demand still outpaces supply, affecting service quality. |
| Intense competition among entertainment venues affecting profitability. | Game Centers | With over 200 gaming arcades in India, competition drives down prices and profit margins for operators. |
| Market saturation in major urban areas limiting growth potential. | Urban Malls | As more malls incorporate entertainment, existing venues face declining foot traffic, impacting revenue. |
India Indoor Entertainment Market Challenges
The India Indoor Entertainment Market still has to solve a few problems, and the first is high operational costs for buyers. Rising expenses for utilities and maintenance can increase overhead by 15% annually, impacting profitability for facility operators. Many venues struggle with outdated technology, as the lack of the latest virtual reality experiences can deter visitors and reduce footfall by 20%. Competition is intense, with over 50 indoor theme parks competing for market share, leading to price wars that diminish margins for producers. Compliance with safety regulations from the Bureau of Indian Standards can delay new facility openings by up to six months, limiting growth opportunities for investors.
Trends in the India Indoor Entertainment Market
Four trends stand out in the India Indoor Entertainment Market.
- Shift towards Virtual Reality Experiences: The integration of virtual reality experiences in urban malls is transforming entertainment offerings. As of 2023, over 50 indoor theme parks operate in India, attracting a diverse range of visitors.
- Expansion of Edutainment Facilities: Edutainment centers are increasingly emerging in educational institutions, with at least 20 new setups reported in 2023. This trend caters to families seeking educational yet entertaining experiences.
- Growth of Indoor Theme Parks: Indoor theme parks are attracting families and tourists, with over 30 new installations in urban malls reported in 2023. This growth is reshaping leisure activities in metropolitan areas.
- Rise of Bowling Alleys in Urban Malls: Bowling alleys are becoming a popular trend in urban malls, with over 30 new installations in 2023. This shift caters to social gatherings and family entertainment.
Investment Opportunities in the India Indoor Entertainment Market
The following opportunities in the India Indoor Entertainment Market pair current demand with a clear way in.
- Urban Malls Seeking Entertainment Options: Urban malls are increasingly looking to expand their entertainment offerings, with the market valued at INR 3,000 crore. Partnering with local developers can facilitate entry into this growing sector.
- Indoor Theme Parks Expansion: Gaming arcades are seeing increased demand, with the Indian gaming industry projected to reach INR 29,000 crore by 2025. Establishing new centers in high-traffic urban areas offers potential for growth.
- Edutainment Centers in Educational Institutions: Educational institutions are increasingly adopting edutainment centers, with at least 20 new setups reported in 2023. Collaborating with schools can create valuable partnerships in this growing market.
- Gaming Arcades Growth: Gaming arcades are expanding rapidly, driven by the increasing popularity of indoor entertainment, with over 200 locations across urban areas. Investing in new gaming technologies can attract more visitors.
Government Initiatives in the India Indoor Entertainment Market
The 'Atmanirbhar Bharat' initiative by the Government of India, launched in 2020, aims to boost domestic industries, including indoor entertainment, through financial support and infrastructure development. This initiative complements existing laws by providing targeted funding for new entertainment projects and improving local manufacturing capabilities. The 'National Tourism Policy' approved in 2022 focuses on enhancing tourism infrastructure, including indoor entertainment facilities, with a target to increase visitor numbers by 20% by 2025.
The 'Skill India Mission' launched in 2020 targets training for 500,000 trainees in the entertainment sector by 2025. The Ministry of Skill Development and Entrepreneurship oversees this initiative, ensuring a skilled workforce to meet the growing demands of the indoor entertainment market. The 'Swadesh Darshan' scheme promotes theme-based tourist circuits, enhancing indoor entertainment attractions since 2021, with a funding allocation of INR 1,500 crore.
Future Insight of the India Indoor Entertainment Market
The India Indoor Entertainment Market is set to evolve by 2032, primarily driven by technological advancements and urban development initiatives. The integration of virtual reality experiences in urban malls will attract more visitors, boosting engagement. The 'Incredible India' campaign will continue to promote tourism, increasing demand for indoor entertainment options. With the Indian gaming industry projected to reach INR 29,000 crore by 2025, investment in new facilities will rise significantly. Collaborative efforts between public and private sectors will further diversify entertainment offerings.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Entertainment Type – Indoor Theme Parks Dominated, Virtual Reality Zones Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, Indoor Theme Parks took a 46% share of entertainment type in 2025, more than any other category. Indoor theme parks dominate the market as they attract families and tourists in metropolitan areas, providing diverse attractions for leisure activities. Their ability to cater to various age groups ensures a consistent flow of visitors, solidifying their market position. Virtual Reality Zones are projected to grow fastest, at a CAGR of 9.9% during 2026–2032. Virtual reality zones are experiencing rapid growth due to their immersive experiences, which are becoming increasingly popular in urban settings. The integration of advanced technology in these zones is expected to drive higher visitor numbers and installations in the coming years. Suppliers should focus on expanding their virtual reality offerings to capitalise on the rising demand for immersive entertainment experiences.
By Venue Type – Urban Malls Dominated, Game Centers Expected to Grow Fastest
With a 46% revenue share in 2025, Urban Malls was the largest venue type category. Urban malls capture the largest share by integrating entertainment options that enhance visitor experiences and increase foot traffic. This strategy has successfully attracted diverse audiences, establishing malls as key destinations for indoor entertainment. Game Centers are set to record the highest CAGR in this split, 10.8% over 2026–2032. Game centers are growing quickly because they offer a wide range of gaming options that appeal to various demographics. The rise in installations within urban areas indicates a strong trend towards interactive entertainment that is likely to continue. Buyers should consider investing in game centers as promising opportunities within urban entertainment venues.
By Content Type – VR Games Dominated, Edutainment Expected to Grow Fastest
The largest content type category in 2025 was VR Games, with a 43% share of total revenue. VR games lead in market share because they are a key attraction in indoor entertainment spaces, drawing in tech-savvy audiences. Their immersive nature makes them a popular choice among visitors seeking unique experiences. Over 2026–2032, Edutainment is expected to post the fastest growth, at a CAGR of 10.4%. Edutainment is rapidly gaining traction as it combines education with entertainment, appealing to families looking for engaging activities. The emergence of new edutainment centers indicates a shift towards educational experiences within the entertainment sector. Suppliers should explore partnerships with educational institutions to develop edutainment offerings that cater to family audiences.
By End User – Gaming Arcades Dominated and Is Expected to Record the Fastest Growth
Gaming Arcades held a 38% share of the India Indoor Entertainment Market by end user in 2025. Gaming arcades are a cornerstone of indoor entertainment, attracting gamers of all ages and maintaining the largest market share. Their established presence in urban areas ensures a steady stream of visitors, making them a reliable revenue source. The same category are also set to grow fastest, at a CAGR of 9.9% during 2026–2032. Gaming arcades are also the fastest-growing segment, with their popularity increasing alongside the demand for interactive entertainment. This dual role as both leader and fastest highlights a robust market position that is expected to expand further. Suppliers should invest in innovative gaming technologies to stay competitive and attract a growing customer base in gaming arcades.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Indoor Entertainment Market Outlook
- Market Size of India Indoor Entertainment Market, 2025
- Forecast of India Indoor Entertainment Market, 2032
- Historical Data and Forecast of India Indoor Entertainment Revenues & Volume for the Period 2022 - 2032F
- India Indoor Entertainment Market Trend Evolution
- India Indoor Entertainment Market Drivers and Challenges
- India Indoor Entertainment Price Trends
- India Indoor Entertainment Porter's Five Forces
- India Indoor Entertainment Industry Life Cycle
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Entertainment Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Virtual Reality Zones for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Bowling Alleys for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Interactive Museums for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Indoor Theme Parks for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Venue Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Game Centers for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Urban Malls for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Public Institutions for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Resorts for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Content Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By VR Games for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Physical Games for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Edutainment for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Rides & Augmented Media for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Gaming Arcades for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Commercial Real Estate for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By City Planners for the Period 2022 - 2032F
- Historical Data and Forecast of India Indoor Entertainment Market Revenues & Volume By Hospitality Industry for the Period 2022 - 2032F
- India Indoor Entertainment Import Export Trade Statistics
- Market Opportunity Assessment By Entertainment Type
- Market Opportunity Assessment By Venue Type
- Market Opportunity Assessment By Content Type
- Market Opportunity Assessment By End User
- India Indoor Entertainment Top Companies Market Share
- India Indoor Entertainment Competitive Benchmarking By Technical and Operational Parameters
- India Indoor Entertainment Company Profiles
- India Indoor Entertainment Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Entertainment Type
- Virtual Reality Zones
- Bowling Alleys
- Interactive Museums
- Indoor Theme Parks
By Venue Type
- Game Centers
- Urban Malls
- Public Institutions
- Resorts
By Content Type
- VR Games
- Physical Games
- Edutainment
- Rides & Augmented Media
By End User
- Gaming Arcades
- Commercial Real Estate
- City Planners
- Hospitality Industry































