India Infotainment Display Systems Market Size & Growth Rate
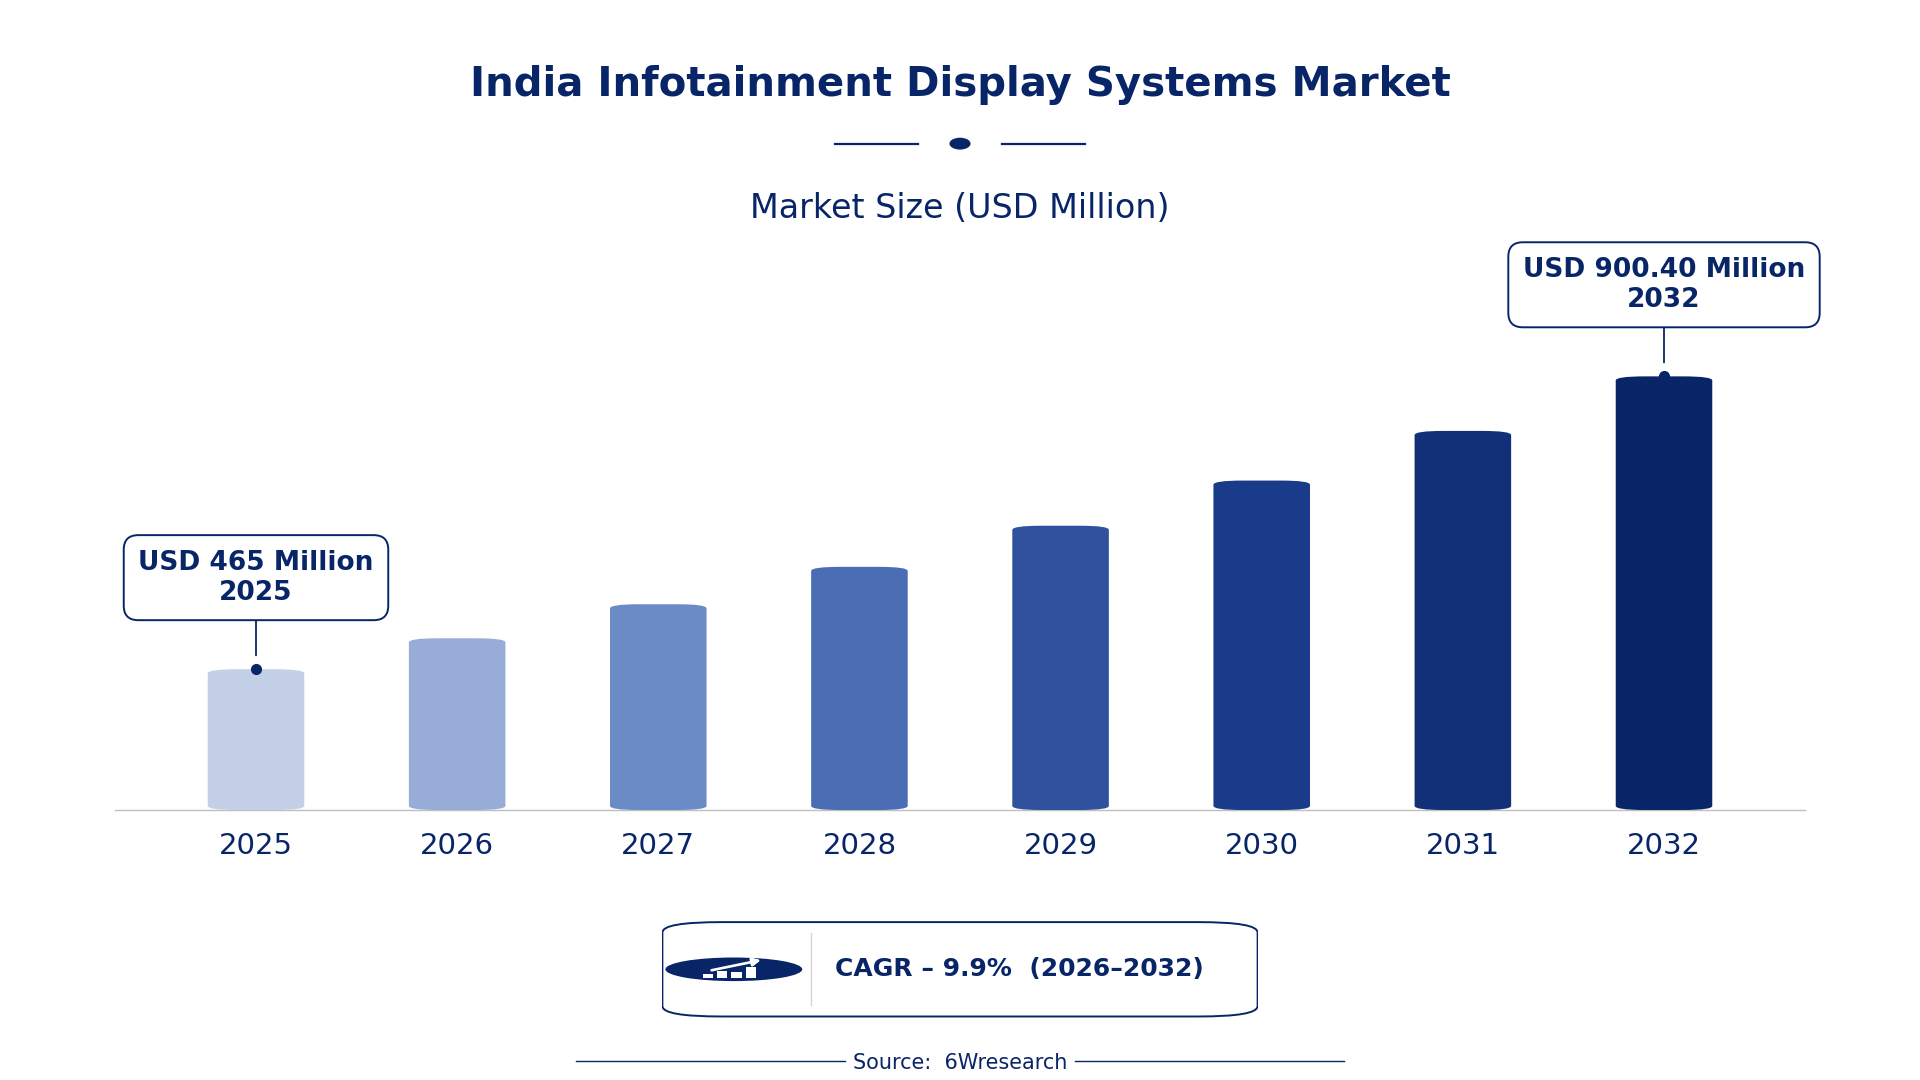
According to 6Wresearch internal database and industry insights, the India Infotainment Display Systems Market was valued at USD 465.0 million in 2025 and is projected to reach USD 900.40 million by 2032, growing at a CAGR of approximately 9.9% during 2026–2032.
India Infotainment Display Systems Market Highlights
| Report Metric | Details |
| Report Name | India Infotainment Display Systems Market |
| Market Size 2025 | USD 465.0 million |
| Market Size 2032 | USD 900.40 million |
| Absolute Growth 2025–2032 | USD 435.40 million |
| CAGR 2026–2032 | 9.9% |
| Peak Annual Growth | 11.8% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Display Type, 2025 | Touchscreen Displays (44% share) |
| Leading Integration Type, 2025 | Center Console (42% share) |
| Leading Vehicle Type, 2025 | Passenger Cars (42% share) |
| Leading Distribution Channel, 2025 | OEM Manufacturers (42% share) |
| Fastest-Growing Display Type | HUD Displays (12.0% CAGR) |
| Fastest-Growing Integration Type | Integrated + Foldable (12.2% CAGR) |
| Fastest-Growing Vehicle Type | EVs / Premium Cars (11.7% CAGR) |
| Fastest-Growing Distribution Channel | In-Vehicle Infotainment OEMs (12.2% CAGR) |
| Growing Sector | In-Vehicle Infotainment OEMs |
| Key End Users | OEM Manufacturers, In-Vehicle Infotainment OEMs, Automotive Dealers, Display Tech Suppliers |
India Infotainment Display Systems Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
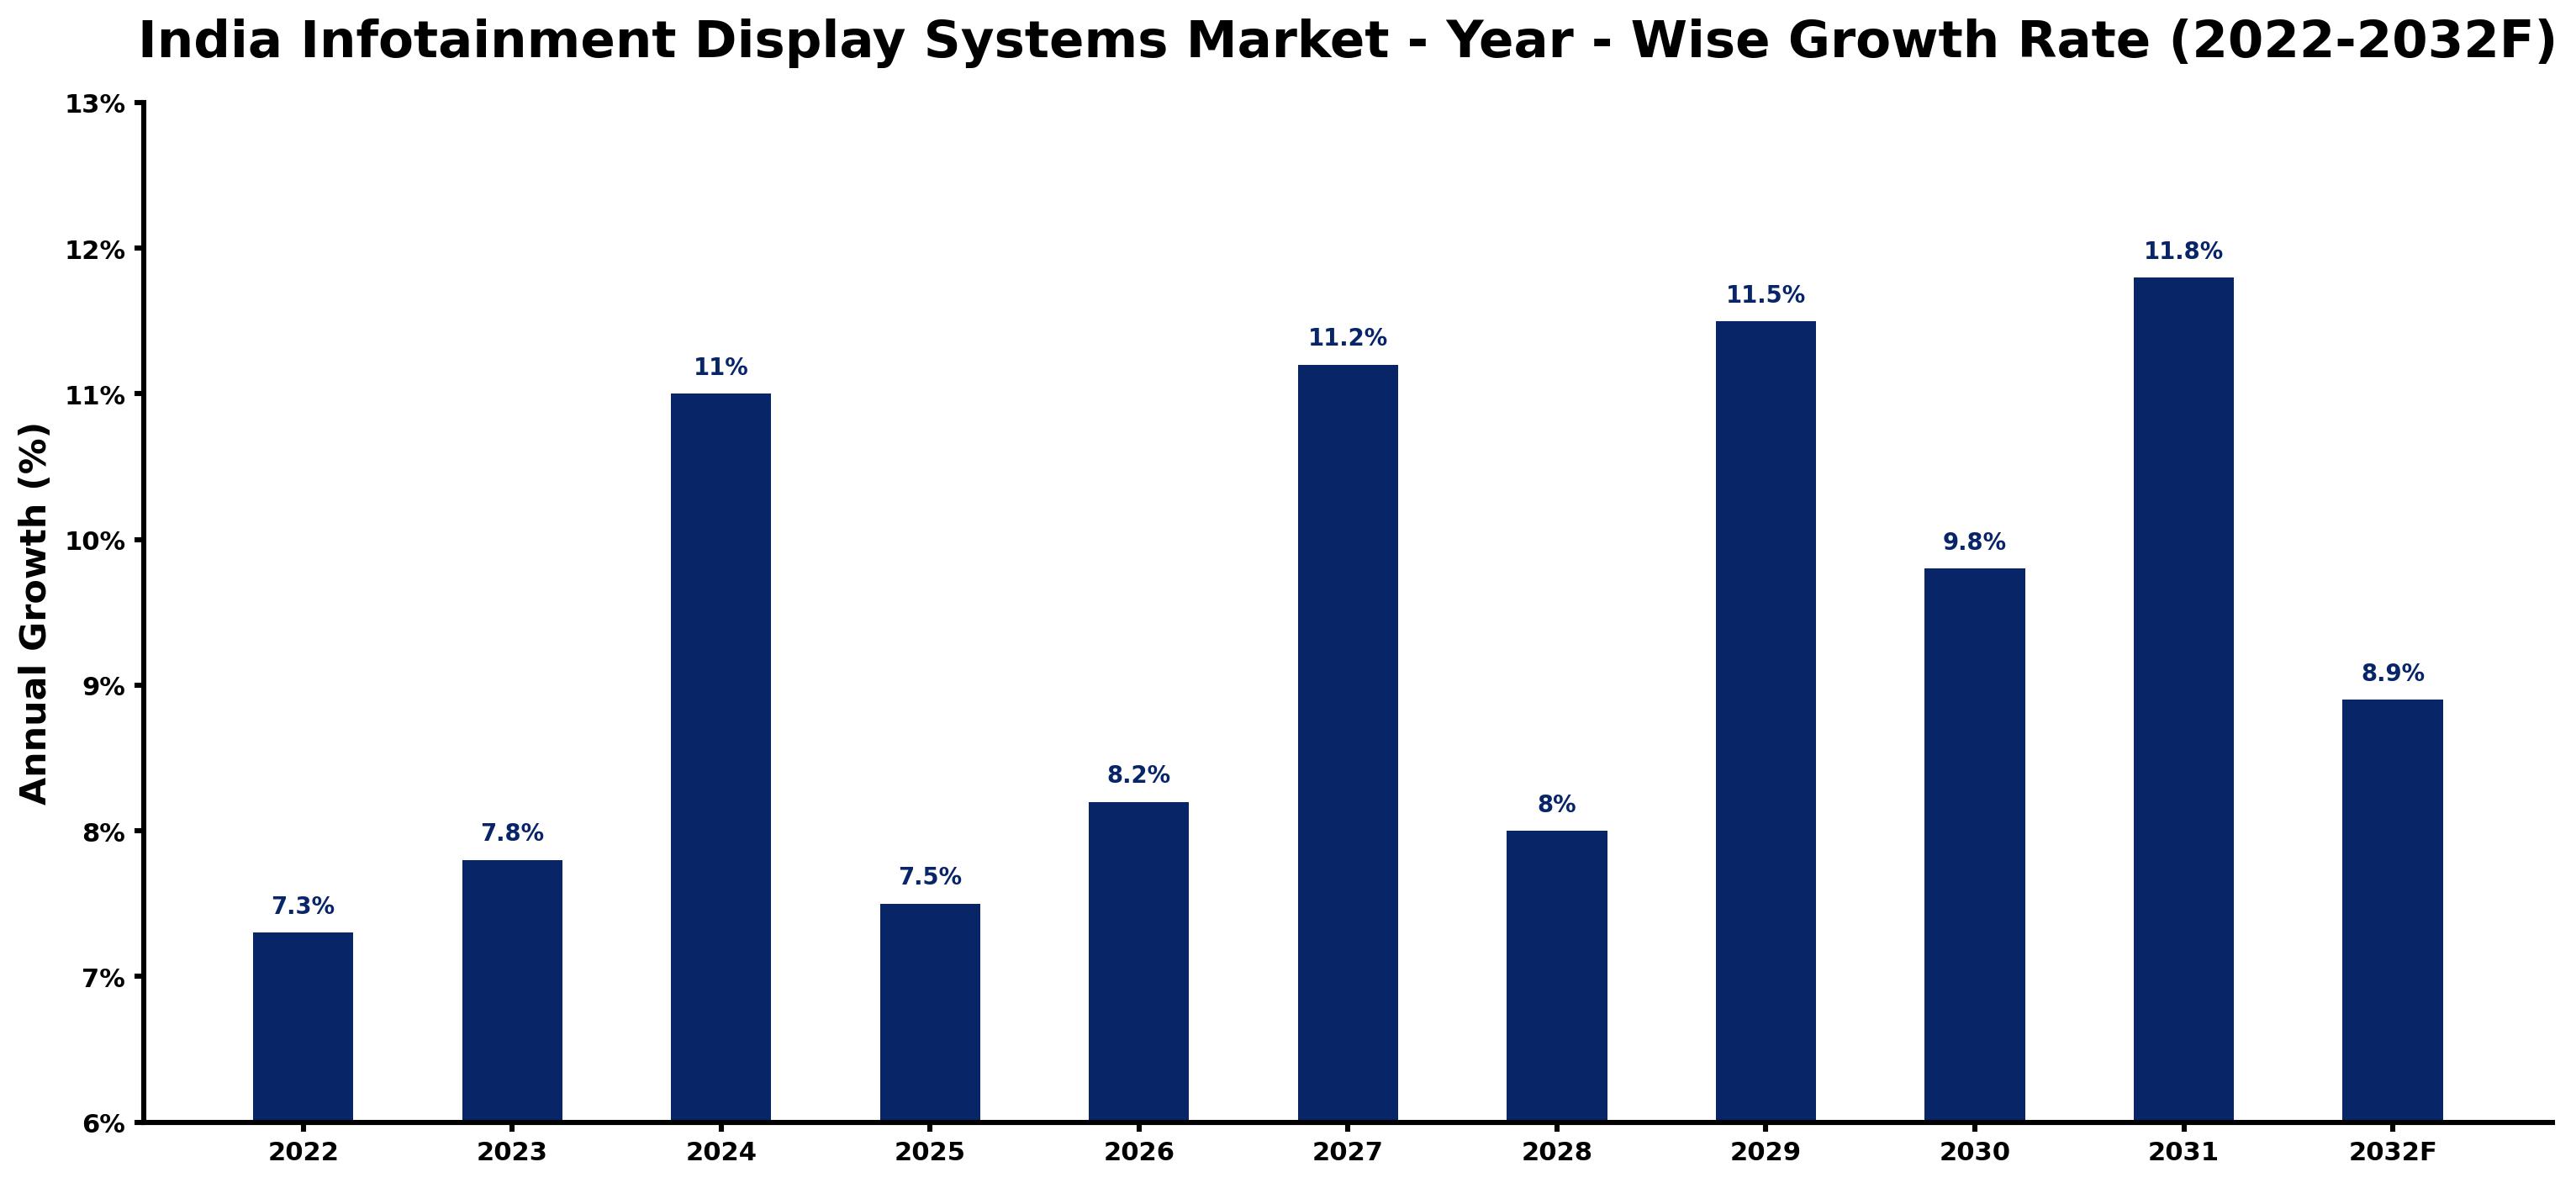
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.3 | The market experienced steady growth as consumer interest in infotainment systems increased, driven by rising sales of passenger cars. |
| 2023 | 7.8 | Demand grew due to increased integration of infotainment features in new vehicle models, particularly among luxury SUVs. |
| 2024 | 11.0 | The introduction of the Bureau of Indian Standards' updated guidelines for infotainment systems boosted integration in vehicles. |
| 2025 | 7.5 | Growth slowed as manufacturers adjusted to supply chain challenges and component shortages affecting production timelines. |
| 2026 | 8.2 | The market is expected to pick up pace with increased investments in R&D for infotainment technologies, particularly in EVs. |
| 2027 | 11.2 | Demand is projected to surge as luxury SUVs incorporate more advanced infotainment systems, attracting affluent buyers. |
| 2028 | 8.0 | Growth is expected to slow again as the market stabilises after rapid expansions in previous years. |
| 2029 | 11.5 | The introduction of innovative HUD technology is projected to drive demand for infotainment systems in luxury vehicles. |
| 2030 | 9.8 | Growth is expected to slow due to market saturation in certain vehicle segments, particularly in passenger cars. |
| 2031 | 11.8 | The market is projected to peak as electric vehicles gain popularity, increasing the integration of infotainment systems. |
| 2032 | 8.9 | Growth is expected to slow as the market matures, but demand for advanced features remains strong. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Infotainment Display Systems Market Synopsis
Infotainment Display Systems serve as sophisticated electronic interfaces in vehicles, offering entertainment, navigation, and information services. These systems consist of both hardware and software components, with touchscreen displays leading the market. The India Infotainment Display Systems Market is growing due to increased sales of passenger cars and the rising adoption of electric vehicles. In 2023, more than 1 million electric vehicles were sold, significantly driving demand for infotainment technologies. Government initiatives aimed at promoting electric vehicle adoption further support this expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand for touchscreen displays in passenger cars | Driver | High | Touchscreen Displays |
| Increasing integration of infotainment systems in luxury SUVs | Driver | High | Luxury / SUVs |
| Investment in R&D for infotainment technologies | Opportunity | High | In-Vehicle Infotainment OEMs |
| Rising demand for integrated dashboards in luxury vehicles | Opportunity | Medium | Integrated + Foldable |
| Supply chain disruptions affecting component availability | Restraint | High | OEM Manufacturers |
| High costs of advanced infotainment systems limiting accessibility | Restraint | Medium | Passenger Cars |
| Challenges in meeting new safety regulations for infotainment systems | Challenge | High | HUD Displays |
| Competition from alternative technologies in vehicle infotainment | Challenge | Medium | Curved OLED Panels |
Evaluation of Drivers in India Infotainment Display Systems Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing consumer preference for touchscreen displays | Touchscreen Displays | Touchscreen displays account for over 50% of infotainment system sales in India, driving demand from OEMs. |
| Rising integration of infotainment systems in luxury vehicles | Luxury / SUVs | Luxury SUVs are seeing a 20% increase in infotainment system integration, attracting affluent buyers. |
| Government initiatives promoting electric vehicles | EVs / Premium Cars | The National Electric Mobility Mission Plan aims for 30% EV adoption by 2030, boosting infotainment needs. |
| Growing demand for HUD technology in luxury vehicles | HUD Displays | HUD technology is gaining traction, capturing a 10% market share as luxury buyers seek advanced features. |
| Investment in local sourcing of infotainment components | OEM Manufacturers | The Automotive Component Manufacturers Association of India promotes local suppliers, enhancing production capabilities. |
Market growth in India for Infotainment Display Systems hinges on the rising consumer preference for touchscreen displays, which represent over 50% of sales. The luxury SUV segment is seeing a 20% increase in infotainment integration, appealing to affluent buyers. The increasing popularity of HUD technology is capturing a 10% market share, as luxury consumers seek advanced features. Investments in local sourcing of infotainment components are further stimulating demand. Additionally, the automotive industry is projected to attract $8 billion in FDI by 2025, boosting production capabilities and market competitiveness.
Evaluation of Restraints in India Infotainment Display Systems Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affecting component availability | OEM Manufacturers | Manufacturers face challenges in sourcing components, leading to delays in production and increased costs. |
| High costs of advanced infotainment systems limiting accessibility | Passenger Cars | The premium pricing of advanced systems restricts adoption among budget-conscious consumers. |
| Challenges in meeting new safety regulations for infotainment systems | HUD Displays | Compliance with updated safety standards increases development costs and time for manufacturers. |
| Competition from alternative technologies in vehicle infotainment | Curved OLED Panels | Emerging technologies may divert consumer interest away from traditional infotainment systems. |
| Limited consumer awareness of advanced infotainment features | Rear Seat Displays | Consumers may not fully understand the benefits of advanced systems, hindering market growth. |
India Infotainment Display Systems Market Challenges
Buyers and suppliers in the India infotainment display systems market encounter a critical skills shortage, hindering innovation and development. This challenge arises from a lack of specialised training programmes, compelling manufacturers to depend on external expertise and raising their operational costs. Supply chain disruptions complicate the situation, as inconsistent availability of key components can lead to production delays, costing manufacturers up to 20% in lost revenue. Regulatory challenges emerge from new guidelines set by the Bureau of Indian Standards, necessitating costly adjustments that strain budgets for OEMs and suppliers, ultimately impacting consumer pricing.
Trends in the India Infotainment Display Systems Market
Several trends are reshaping the India Infotainment Display Systems Market; the most important are set out below.
- Integration of HUD Technology in Luxury Vehicles: The Bureau of Indian Standards updated guidelines for HUD displays in 2021, improving safety and usability. This change is anticipated to increase adoption rates, with HUD technology capturing a 10% market share.
- Shift Towards Electric Vehicles: As of 2023, over 1 million EVs have been sold in India, driving demand for advanced infotainment systems. This trend is likely to persist as the government targets 30% EV adoption by 2030.
- Rise of Integrated Dashboards in Luxury Segment: The demand for integrated dashboards is on the rise in the luxury segment, accounting for 30% of sales. This shift reflects consumer preference for streamlined, multifunctional interfaces.
- Growth of Touchscreen Displays: Touchscreen displays dominate the infotainment market, making up over 50% of sales. This trend is propelled by consumer demand for interactive and user-friendly interfaces.
Investment Opportunities in the India Infotainment Display Systems Market
Investors looking at the India Infotainment Display Systems Market should consider the following areas.
- Partnerships with Local Suppliers: With the Automotive Component Manufacturers Association promoting local sourcing, now is an opportune moment for partnerships. Investing in local suppliers can enhance production capabilities and lower costs.
- Focus on EV Market: The rising sales of electric vehicles present a timely opportunity for infotainment systems. Targeting EV manufacturers can lead to substantial contracts, especially as adoption increases.
- Investment in R&D for Advanced Technologies: Investing in R&D for advanced infotainment technologies is crucial. The government aims to support local manufacturers, creating opportunities for collaboration and funding.
- Expansion into Luxury Segment: The increasing demand for advanced infotainment features in luxury vehicles presents an opportunity for suppliers. Concentrating on high-end models can yield considerable returns.
Government Initiatives in the India Infotainment Display Systems Market
The National Electric Mobility Mission Plan 2020 promotes electric vehicles and their infotainment systems, aiming for a 30% EV adoption by 2030. This initiative encourages manufacturers to innovate and integrate advanced infotainment features into EVs, supporting market growth. Additionally, the Automotive Mission Plan 2026 seeks to enhance the automotive sector's global competitiveness and innovation, further promoting the development of infotainment systems.
The Bureau of Indian Standards oversees updated standards for automotive infotainment systems, ensuring safety and usability for consumers. This agency plays a key role in approving new infotainment technologies. The Faster Adoption and Manufacturing of Hybrid and Electric Vehicles scheme, with a budget of ₹10,000 crores, funds initiatives to support EV technology, including infotainment integration. These measures enable manufacturers to improve their product offerings and comply with safety regulations.
Future Insight of the India Infotainment Display Systems Market
The India infotainment display systems market is poised for substantial evolution by 2032, driven by technological advancements and government support. The National Automotive Testing and R&D Infrastructure Project will encourage innovation, while the Ministry of Heavy Industries' initiatives will increase demand for integrated infotainment solutions. By 2025, the market for infotainment systems in passenger cars is expected to grow by 15% annually, reflecting shifting consumer preferences. The Automotive Mission Plan 2026 aims to position India as a global manufacturing hub, attracting investments that will strengthen local production capabilities.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Display Type – Touchscreen Displays Dominated, HUD Displays Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Touchscreen Displays held a 44% share of the India Infotainment Display Systems Market by display type in 2025. Touchscreen displays dominate the infotainment display systems market due to their essential role in user interaction within vehicles. Their widespread adoption is reflected in over 50% of infotainment system sales in India, making them a top choice for consumers. The quickest growth will come from HUD Displays, forecast to expand at a CAGR of 12.0% between 2026 and 2032. HUD displays are experiencing rapid growth as they deliver critical information to drivers without distraction, appealing to safety-conscious users. The 10% market share of HUD technology in luxury vehicles underscores its rising significance in automotive design. Suppliers must prioritise the development of HUD technology to meet the increasing demand for safer driving experiences.
By Integration Type – Center Console Dominated, Integrated + Foldable Expected to Grow Fastest
Center Console accounted for a 42% market share by integration type in 2025. The center console secures the largest market share as it serves as the main control hub for infotainment systems, essential for user interaction in vehicles. Its established presence in passenger cars solidifies its leading position in the integration type segment. Over 2026–2032, Integrated + Foldable is expected to post the fastest growth, at a CAGR of 12.2%. Integrated and foldable designs are the fastest-growing integration type, providing innovative solutions that maximise space and functionality in vehicles. Their unique features are attracting attention from manufacturers looking to differentiate themselves in a competitive landscape. Buyers should explore integrated designs that offer modern aesthetics and flexibility, while suppliers need to invest in R&D for these advanced solutions.
By Vehicle Type – Passenger Cars Dominated, EVs / Premium Cars Expected to Grow Fastest
The largest vehicle type category in 2025 was Passenger Cars, with a 42% share of total revenue. Passenger cars represent the largest market share for infotainment systems, extensively utilising these technologies to enhance user experience. This dominance is supported by high sales volumes and a strong installed base of vehicles equipped with advanced infotainment features. EVs / Premium Cars are projected to grow fastest, at a CAGR of 11.7% during 2026–2032. EVs and premium cars are the fastest-growing segments, highlighting the increasing integration of sophisticated infotainment technologies in these vehicles. The sale of over 1 million EVs in India signals a rising demand for advanced infotainment functionalities. Suppliers should concentrate on developing infotainment solutions tailored for EVs and premium vehicles to capitalise on this rapidly expanding market opportunity.
By Distribution Channel – OEM Manufacturers Dominated, In-Vehicle Infotainment OEMs Expected to Grow Fastest
In 2025, OEM Manufacturers led the distribution channel split with a 42% share. OEM manufacturers lead the distribution channel for infotainment systems, as they are the primary producers responsible for integrating these technologies into vehicles. Their established relationships with automotive manufacturers ensure a strong market presence. In-Vehicle Infotainment OEMs are set to record the highest CAGR in this split, 12.2% over 2026–2032. In-vehicle infotainment OEMs are rapidly expanding as specialised manufacturers of infotainment solutions, catering to the specific needs of modern vehicles. Their focused approach allows them to innovate quickly and meet the demands of a tech-savvy consumer base. Suppliers must establish partnerships with in-vehicle infotainment OEMs to stay competitive and meet the evolving needs of the automotive market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Infotainment Display Systems Market Outlook
- Market Size of India Infotainment Display Systems Market, 2025
- Forecast of India Infotainment Display Systems Market, 2032
- Historical Data and Forecast of India Infotainment Display Systems Revenues & Volume for the Period 2022 - 2032F
- India Infotainment Display Systems Market Trend Evolution
- India Infotainment Display Systems Market Drivers and Challenges
- India Infotainment Display Systems Price Trends
- India Infotainment Display Systems Porter's Five Forces
- India Infotainment Display Systems Industry Life Cycle
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Display Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Touchscreen Displays for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Rear Seat Displays for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By HUD Displays for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Curved OLED Panels for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Integration Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Center Console for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Integrated + Foldable for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Windshield Projection for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Custom Dashboards for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Vehicle Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Passenger Cars for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Luxury / SUVs for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By EVs / Premium Cars for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Concept / EVs for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By OEM Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Automotive Dealers for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By Display Tech Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of India Infotainment Display Systems Market Revenues & Volume By In-Vehicle Infotainment OEMs for the Period 2022 - 2032F
- India Infotainment Display Systems Import Export Trade Statistics
- Market Opportunity Assessment By Display Type
- Market Opportunity Assessment By Integration Type
- Market Opportunity Assessment By Vehicle Type
- Market Opportunity Assessment By Distribution Channel
- India Infotainment Display Systems Top Companies Market Share
- India Infotainment Display Systems Competitive Benchmarking By Technical and Operational Parameters
- India Infotainment Display Systems Company Profiles
- India Infotainment Display Systems Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Display Type
- Touchscreen Displays
- Rear Seat Displays
- HUD Displays
- Curved OLED Panels
By Integration Type
- Center Console
- Integrated + Foldable
- Windshield Projection
- Custom Dashboards
By Vehicle Type
- Passenger Cars
- Luxury / SUVs
- EVs / Premium Cars
- Concept / EVs
By Distribution Channel
- OEM Manufacturers
- Automotive Dealers
- Display Tech Suppliers
- In-Vehicle Infotainment OEMs































