India Injectable Diabetes Treatment Market Size & Growth Rate
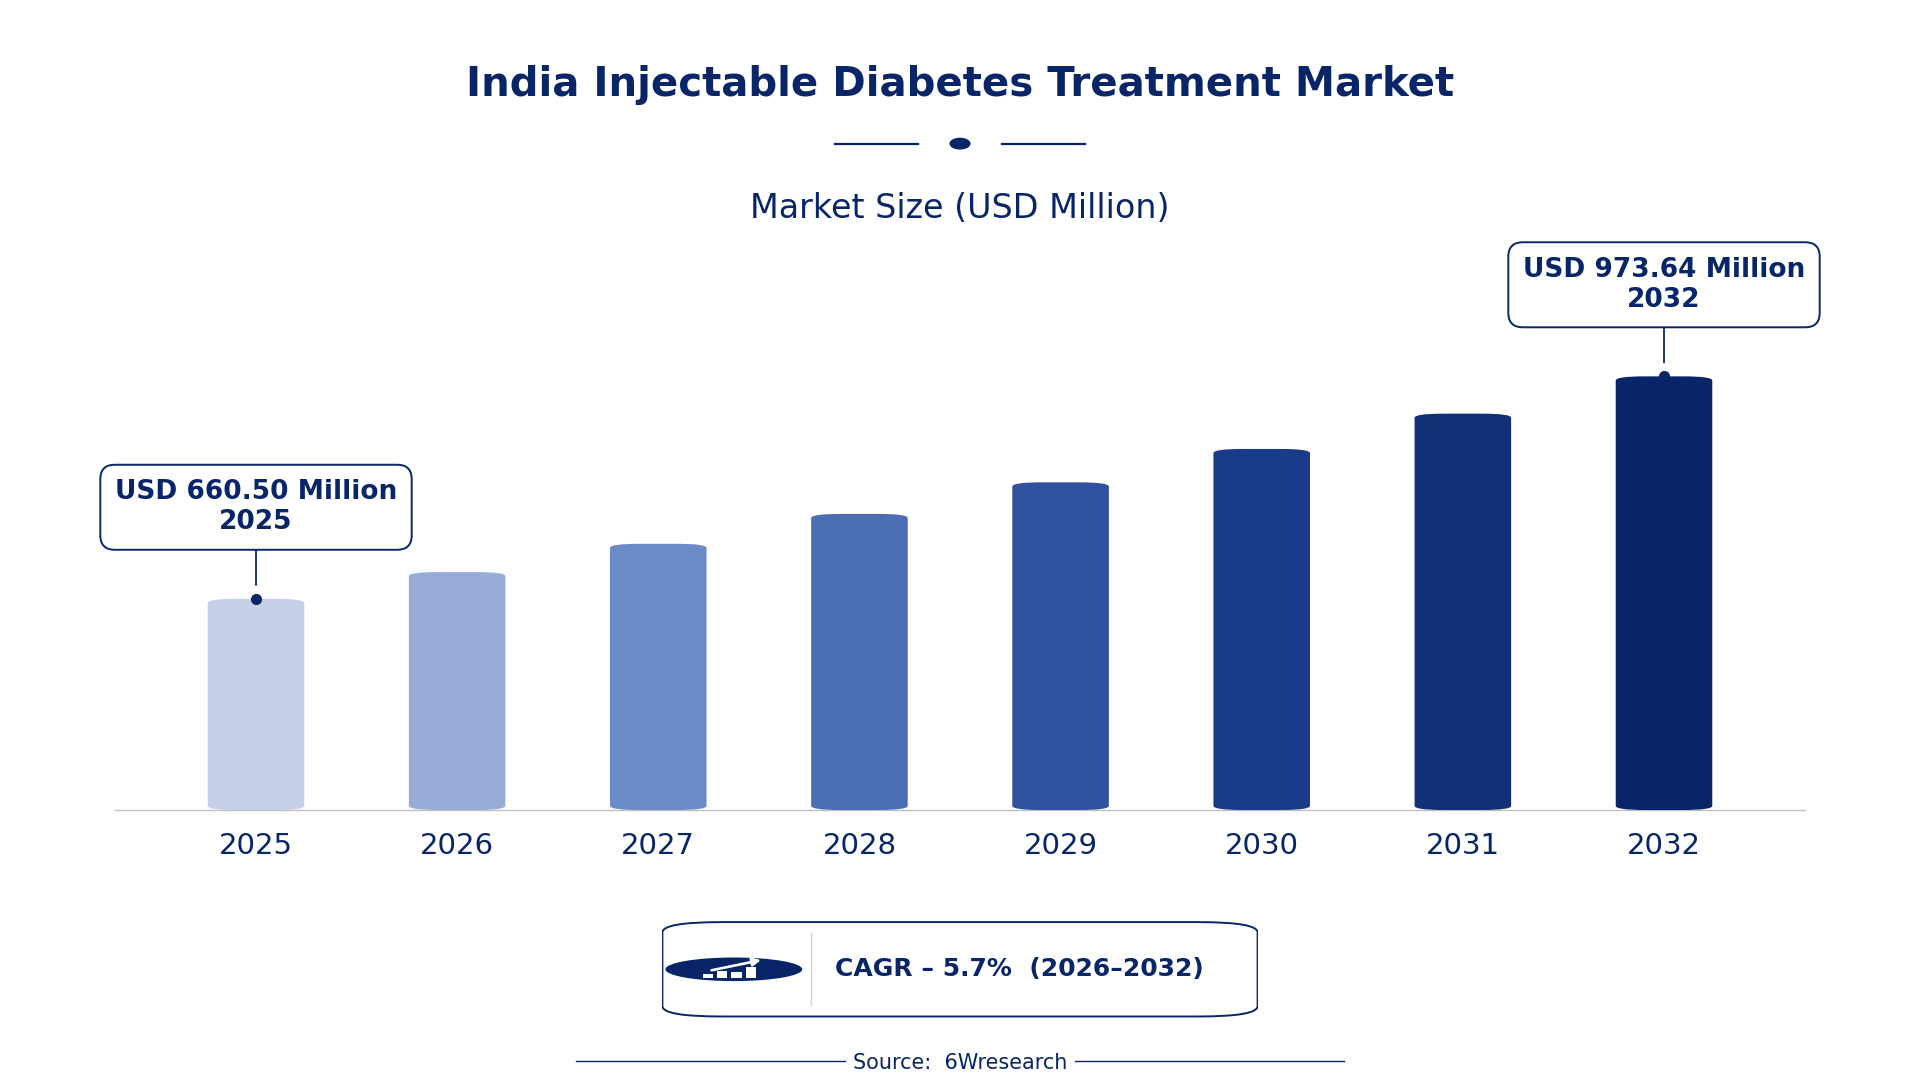
According to 6Wresearch internal database and industry insights, the India Injectable Diabetes Treatment Market was valued at USD 660.5 million in 2025 and is projected to reach USD 973.64 million by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
India Injectable Diabetes Treatment Market Highlights
| Report Metric | Details |
| Report Name | India Injectable Diabetes Treatment Market |
| Market Size 2025 | USD 660.5 million |
| Market Size 2032 | USD 973.64 million |
| Absolute Growth 2025–2032 | USD 313.14 million |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 8.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Drug Class, 2025 | Basal Insulin (38% share) |
| Leading Type, 2025 | Long-Acting Insulin (35% share) |
| Leading Delivery Device, 2025 | Vials & Syringes (42% share) |
| Leading Patient Type, 2025 | Type 1 Diabetics (46% share) |
| Leading Distribution Channel, 2025 | Hospital Pharmacies (33% share) |
| Fastest-Growing Drug Class | Bolus Insulin (7.9% CAGR) |
| Fastest-Growing Type | Rapid-Acting Insulin (8.4% CAGR) |
| Fastest-Growing Delivery Device | Pre-filled Pens (8.4% CAGR) |
| Fastest-Growing Patient Type | Type 2 Diabetics (8.3% CAGR) |
| Fastest-Growing Distribution Channel | Retail Pharmacies (7.6% CAGR) |
| Growing Sector | Healthcare |
| Key End Users | Diabetes patients, healthcare providers, hospitals, pharmacies |
India Injectable Diabetes Treatment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
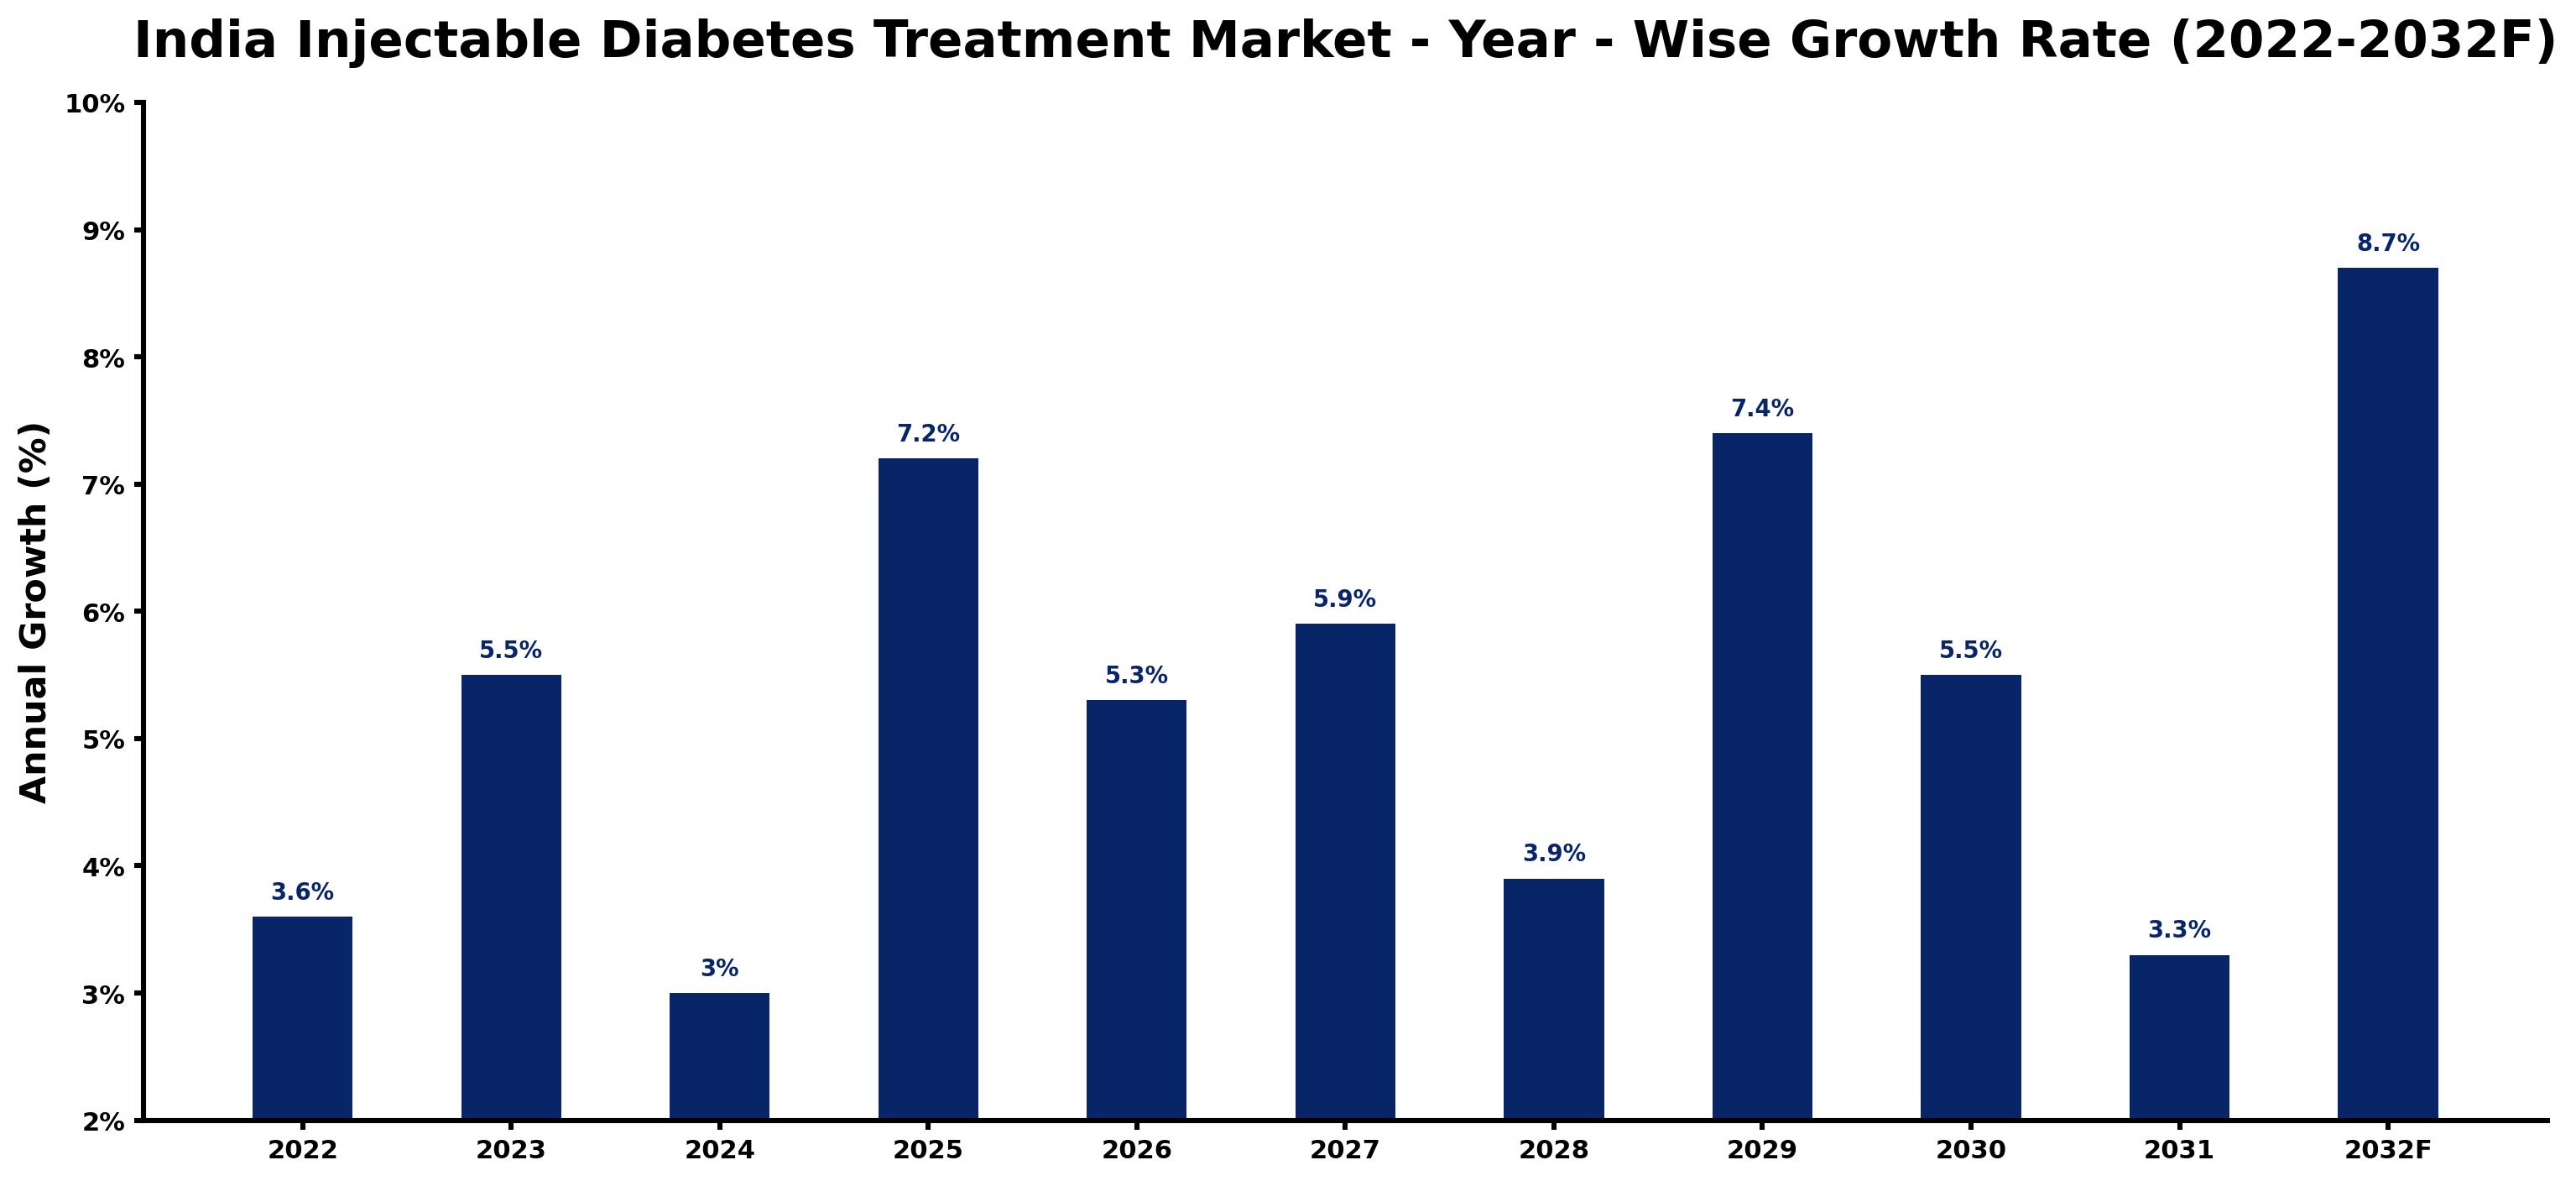
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.6 | The market showed steady demand with approximately 77 million diabetes patients in India. |
| 2023 | 5.5 | Growth accelerated due to increased awareness from the National Diabetes Control Programme launched in 2021. |
| 2024 | 3.0 | A slowdown occurred as consumer preferences shifted towards more convenient treatment options. |
| 2025 | 7.2 | The market rebounded with strong demand for basal insulin in urban areas like Delhi and Mumbai. |
| 2026 | 5.3 | Growth is expected to slow as competition among various delivery devices increases. |
| 2027 | 5.9 | Demand is projected to rise as more patients shift to bolus insulin for meal management. |
| 2028 | 3.9 | A slowdown is anticipated as the market stabilises after rapid growth phases. |
| 2029 | 7.4 | Growth is expected to pick up again with rising popularity of GLP-1 receptor agonists among patients. |
| 2030 | 5.5 | The market is projected to grow slower as established products face pricing pressures. |
| 2031 | 3.3 | Demand will continue to slow as the market matures and options expand. |
| 2032 | 8.7 | The market is expected to peak with increased adoption of innovative delivery devices. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Injectable Diabetes Treatment Market Synopsis
Injectable Diabetes Treatment Market in India encompasses insulin and GLP-1 receptor agonists, designed to manage blood sugar levels effectively. These treatments are produced using advanced recombinant DNA technology and are essential for both Type 1 and Type 2 diabetes management. The market is expanding due to rising diabetes prevalence, with approximately 77 million patients as of 2023. Increased investment in healthcare facilities and awareness programmes further drives demand. The National Diabetes Control Programme aims to improve diabetes management across the country.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising prevalence of diabetes among urban populations drives demand for effective treatments. | Driver | High | Basal Insulin |
| Growing adoption of GLP-1 receptor agonists for weight management boosts market potential. | Driver | High | GLP-1 Receptor Agonists |
| Increased demand for insulin pens as a convenient delivery method presents opportunities. | Opportunity | High | Pre-filled Pens |
| The expanding online pharmacy sector opens new channels for injectable diabetes treatments. | Opportunity | Medium | Online Pharmacies |
| High costs of innovative treatments may limit access for some patients. | Restraint | High | Insulin Biosimilars |
| Regulatory hurdles for new product approvals can slow market entry. | Restraint | Medium | GLP-1 Receptor Agonists |
| Supply chain disruptions can affect availability of essential diabetes treatments. | Challenge | High | Hospital Pharmacies |
| Increasing competition among various delivery devices can impact pricing strategies. | Challenge | Medium | Vials & Syringes |
Evaluation of Drivers in India Injectable Diabetes Treatment Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising diabetes prevalence among urban populations increases demand for treatments. | Basal Insulin | India has approximately 77 million diabetes patients as of 2023. |
| Growing popularity of GLP-1 receptor agonists expands treatment options for patients. | GLP-1 Receptor Agonists | The prevalence of Type 2 diabetes is rising, especially among urban populations aged 30-60. |
| Increased investment in healthcare facilities supports the availability of injectable treatments. | Hospital Pharmacies | The Indian government allocated funds for diabetes awareness campaigns targeting rural areas in 2023. |
| Convenience of insulin pens drives their adoption among patients. | Pre-filled Pens | Insulin pens account for over 40% of the injectable diabetes treatment market in India. |
| Rising awareness from national programmes boosts demand for diabetes management. | GLP-1 Receptor Agonists | The National Programme for Prevention and Control of Diabetes launched in 2021 aims to improve management. |
The Injectable Diabetes Treatment market in India is expanding as rising diabetes prevalence, increased healthcare investment and growing adoption of convenient delivery methods drive demand. Approximately 77 million diabetes patients in India create a substantial market for effective treatments. Insulin pens, accounting for over 40% of the market, are increasingly preferred for their convenience. The rising popularity of GLP-1 receptor agonists, particularly among urban populations, boosts market potential.
Evaluation of Restraints in India Injectable Diabetes Treatment Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of treatments limit access for some patients. | Insulin Biosimilars | Many patients struggle to afford newer, more effective diabetes treatments. |
| Regulatory hurdles for new product approvals can slow market entry. | GLP-1 Receptor Agonists | Strict guidelines can delay the availability of new therapies. |
| Supply chain disruptions can affect availability of essential diabetes treatments. | Hospital Pharmacies | Recent global events have highlighted vulnerabilities in supply chains. |
| Increasing competition among various delivery devices can impact pricing strategies. | Vials & Syringes | Price wars may lead to reduced profit margins for suppliers. |
| Limited awareness in rural areas can hinder market growth. | Online Pharmacies | Patients in remote regions may not have access to online purchasing options. |
India Injectable Diabetes Treatment Market Challenges
The India Injectable Diabetes Treatment Market faces notable technological challenges, as many healthcare facilities still depend on outdated diabetes management tools, which delays effective care for around 77 million diabetes patients. Compliance with guidelines from the Indian Council of Medical Research can extend approval times for new treatments, resulting in supply delays for producers. Rising raw material costs, influenced by unstable supply chains, have escalated prices for buyers, making treatments less accessible. Additionally, supply chain disruptions hinder the timely availability of essential insulin products, adversely affecting patient adherence to prescribed treatment plans.
Trends in the India Injectable Diabetes Treatment Market
Several trends are reshaping the India Injectable Diabetes Treatment Market; the most important are set out below.
- Shift Towards Pre-filled Pens: Patients are increasingly opting for pre-filled pens due to their convenience and ease of use. In 2023, pre-filled pens accounted for over 40% of the market, reflecting changing preferences among users.
- Growing Acceptance of GLP-1 Receptor Agonists: Urban populations are embracing GLP-1 receptor agonists for their dual benefits in diabetes management and weight loss. As of 2023, these treatments are gaining traction, particularly among Type 2 diabetics.
- Increase in Online Pharmacy Purchases: The rise of online pharmacies is transforming how patients access diabetes treatments. In 2023, this channel saw a notable increase in sales, catering to tech-savvy consumers.
- Expansion of Diabetes Awareness Campaigns: The Indian government has intensified diabetes awareness campaigns, particularly in rural areas. In 2023, allocated funds aimed to educate communities about diabetes management.
Investment Opportunities in the India Injectable Diabetes Treatment Market
Several openings in the India Injectable Diabetes Treatment Market merit attention from investors.
- Investment in Delivery Devices: There is a growing opportunity to supply delivery devices like auto-injectors. The rising demand for convenience among patients suggests a market potential of USD 973.64 million by 2032.
- Focus on Biosimilars Development: The Indian Pharmaceutical Alliance backs the development of biosimilars, creating opportunities for suppliers. With a growing patient base, targeting Type 2 diabetics can yield promising returns.
- Partnerships with Healthcare Institutions: Collaborating with hospitals and clinics can improve distribution channels for injectable treatments. The increasing number of diabetes patients presents a timely opportunity for partnerships.
- Expansion into Rural Markets: Investing in outreach programs targeting rural areas can access an underserved market. With funding allocated for diabetes awareness in 2023, there is a clear path for entry.
Government Initiatives in the India Injectable Diabetes Treatment Market
The Ministry of Health and Family Welfare launched the 'National Programme for Prevention and Control of Diabetes' in 2021, which improves existing frameworks for diabetes management. This programme aims to enhance access to treatments and raise awareness among patients, addressing the growing diabetes crisis in India. Additionally, the Indian Council of Medical Research established guidelines for diabetes management in 2022, ensuring that healthcare providers adhere to best practices in treatment protocols.
Various schemes under the Ministry of Health and Family Welfare provide funding and support for diabetes management initiatives, focusing on both urban and rural populations. The National Diabetes Control Programme allocates resources that assist healthcare providers in improving access to injectable diabetes treatments, ensuring that patients receive necessary care. In 2023, the government allocated funds specifically for diabetes awareness campaigns targeting rural areas, enhancing education and outreach efforts.
Future Insight of the India Injectable Diabetes Treatment Market
By 2032, buyers and suppliers in the India Injectable Diabetes Treatment Market can expect improved access to advanced diabetes management technologies, driven by initiatives like the National Diabetes Control Programme. The rising popularity of GLP-1 receptor agonists will transform treatment strategies, as these products address both diabetes management and weight loss. Government funding for diabetes awareness campaigns will enhance patient education and early diagnosis, while adherence to ISO 13485:2016 standards will ensure higher quality for diabetes treatment devices. Insulin pens, which currently represent a substantial portion of the market, will see advancements in delivery methods that improve patient compliance.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Drug Class – Basal Insulin Dominated, Bolus Insulin Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, in 2025, Basal Insulin led the drug class split with a 38% share. Basal insulin holds the largest market share because it is essential for long-term blood sugar control, particularly in urban areas with high diabetes rates. Its widespread use in cities like Delhi and Mumbai highlights its importance in managing diabetes effectively. Bolus Insulin is projected to grow fastest, at a CAGR of 7.9% during 2026–2032. Bolus insulin is experiencing rapid growth due to the rising need for immediate blood sugar control during meals, especially as Type 2 diabetes cases increase. This segment's growth is expected to continue as awareness of its benefits spreads among healthcare providers and patients. Suppliers should focus on enhancing the availability of bolus insulin to meet the growing demand for immediate diabetes management solutions.
By Type – Long-Acting Insulin Dominated, Rapid-Acting Insulin Expected to Grow Fastest
With a 35% revenue share in 2025, Long-Acting Insulin was the largest type category. Long-acting insulin captures the largest market share as it effectively maintains stable blood sugar levels throughout the day, making it a preferred choice for many diabetes patients. This consistent demand is particularly evident among Type 1 diabetics who rely on it for optimal management. Rapid-Acting Insulin is set to record the highest CAGR in this split, 8.4% over 2026–2032. Rapid-acting insulin is growing swiftly as it provides quick blood sugar control after meals, a feature increasingly sought after by patients. Changing dietary habits suggest that the demand for this type of insulin will continue to rise significantly. Buyers should integrate rapid-acting insulin into their treatment plans to improve glycemic control, especially during meal times.
By Delivery Device – Vials & Syringes Dominated, Pre-filled Pens Expected to Grow Fastest
Vials & Syringes held a 42% share of the India Injectable Diabetes Treatment Market by delivery device in 2025. Vials and syringes dominate the market share as they represent the traditional and widely accepted method for insulin administration among patients. Their established presence in healthcare facilities ensures familiarity and consistent supply for users. The quickest growth will come from Pre-filled Pens, forecast to expand at a CAGR of 8.4% between 2026 and 2032. Pre-filled pens are gaining popularity rapidly due to their convenience and ease of use, appealing to an increasing number of patients seeking simpler administration methods. This trend is expected to accelerate as patient preferences shift towards user-friendly delivery options. Suppliers must improve the distribution of pre-filled pens to meet the rising demand for convenient insulin delivery solutions.
By Patient Type – Type 1 Diabetics Dominated, Type 2 Diabetics Expected to Grow Fastest
Type 1 Diabetics took a 46% share of patient type in 2025, more than any other category. Type 1 diabetics represent the largest share of the market as they are the primary users of insulin therapies, necessitating consistent and effective treatment options. This group’s reliance on insulin for survival drives sustained demand in the market. Over 2026–2032, Type 2 Diabetics are expected to post the fastest growth, at a CAGR of 8.3%. The fastest growth is seen in Type 2 diabetics, who are increasingly adopting both insulin and GLP-1 therapies for better management of their condition. As the prevalence of Type 2 diabetes continues to rise, this segment is expected to expand rapidly. Suppliers should target Type 2 diabetic patients with tailored solutions to address their specific treatment needs and preferences.
By Distribution Channel – Hospital Pharmacies Dominated, Retail Pharmacies Expected to Grow Fastest
The largest distribution channel category in 2025 was Hospital Pharmacies, with a 33% share of total revenue. Hospital pharmacies dominate the market share as they serve as the primary distribution point for injectable diabetes treatments, ensuring patients receive essential medications during hospital visits. Their established role in the healthcare system reinforces their market position. Retail Pharmacies are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. Retail pharmacies are witnessing the fastest growth due to their convenience and accessibility for patients seeking immediate access to diabetes treatments. As more patients opt to manage their conditions outside of hospitals, this channel is likely to see further expansion. Suppliers should strengthen collaborations with retail pharmacies to improve product availability and address the increasing demand from patients.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Injectable Diabetes Treatment Market Outlook
- Market Size of India Injectable Diabetes Treatment Market, 2025
- Forecast of India Injectable Diabetes Treatment Market, 2032
- Historical Data and Forecast of India Injectable Diabetes Treatment Revenues & Volume for the Period 2022 - 2032F
- India Injectable Diabetes Treatment Market Trend Evolution
- India Injectable Diabetes Treatment Market Drivers and Challenges
- India Injectable Diabetes Treatment Price Trends
- India Injectable Diabetes Treatment Porter's Five Forces
- India Injectable Diabetes Treatment Industry Life Cycle
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Drug Class for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Basal Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Bolus Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By GLP-1 Receptor Agonists for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Fixed-Dose Combinations for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Insulin Biosimilars for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Long-Acting Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Rapid-Acting Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Liraglutide, Semaglutide for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Insulin + GLP-1 for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Recombinant Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Delivery Device for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Vials & Syringes for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Pre-filled Pens for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Auto-Injectors for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Dual Chamber Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Disposable Pens for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Patient Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Type 1 Diabetics for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Type 2 Diabetics for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Obese or Elderly Adults for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By High-Risk Diabetics for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By General Patient Base for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Hospital Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Retail Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Online Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Clinics & Specialty Stores for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Diabetes Treatment Market Revenues & Volume By Institutional Sales (B2B) for the Period 2022 - 2032F
- India Injectable Diabetes Treatment Import Export Trade Statistics
- Market Opportunity Assessment By Drug Class
- Market Opportunity Assessment By Type
- Market Opportunity Assessment By Delivery Device
- Market Opportunity Assessment By Patient Type
- Market Opportunity Assessment By Distribution Channel
- India Injectable Diabetes Treatment Top Companies Market Share
- India Injectable Diabetes Treatment Competitive Benchmarking By Technical and Operational Parameters
- India Injectable Diabetes Treatment Company Profiles
- India Injectable Diabetes Treatment Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Drug Class
- Basal Insulin
- Bolus Insulin
- GLP-1 Receptor Agonists
- Fixed-Dose Combinations
- Insulin Biosimilars
By Type
- Long-Acting Insulin
- Rapid-Acting Insulin
- Liraglutide
- Semaglutide
- Insulin + GLP-1
- Recombinant Insulin
By Delivery Device
- Vials & Syringes
- Pre-filled Pens
- Auto-Injectors
- Dual Chamber Devices
- Disposable Pens
By Patient Type
- Type 1 Diabetics
- Type 2 Diabetics
- Obese or Elderly Adults
- High-Risk Diabetics
- General Patient Base
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Clinics & Specialty Stores
- Institutional Sales (B2B)































