India Injectable Pharmaceuticals Market Size & Growth Rate
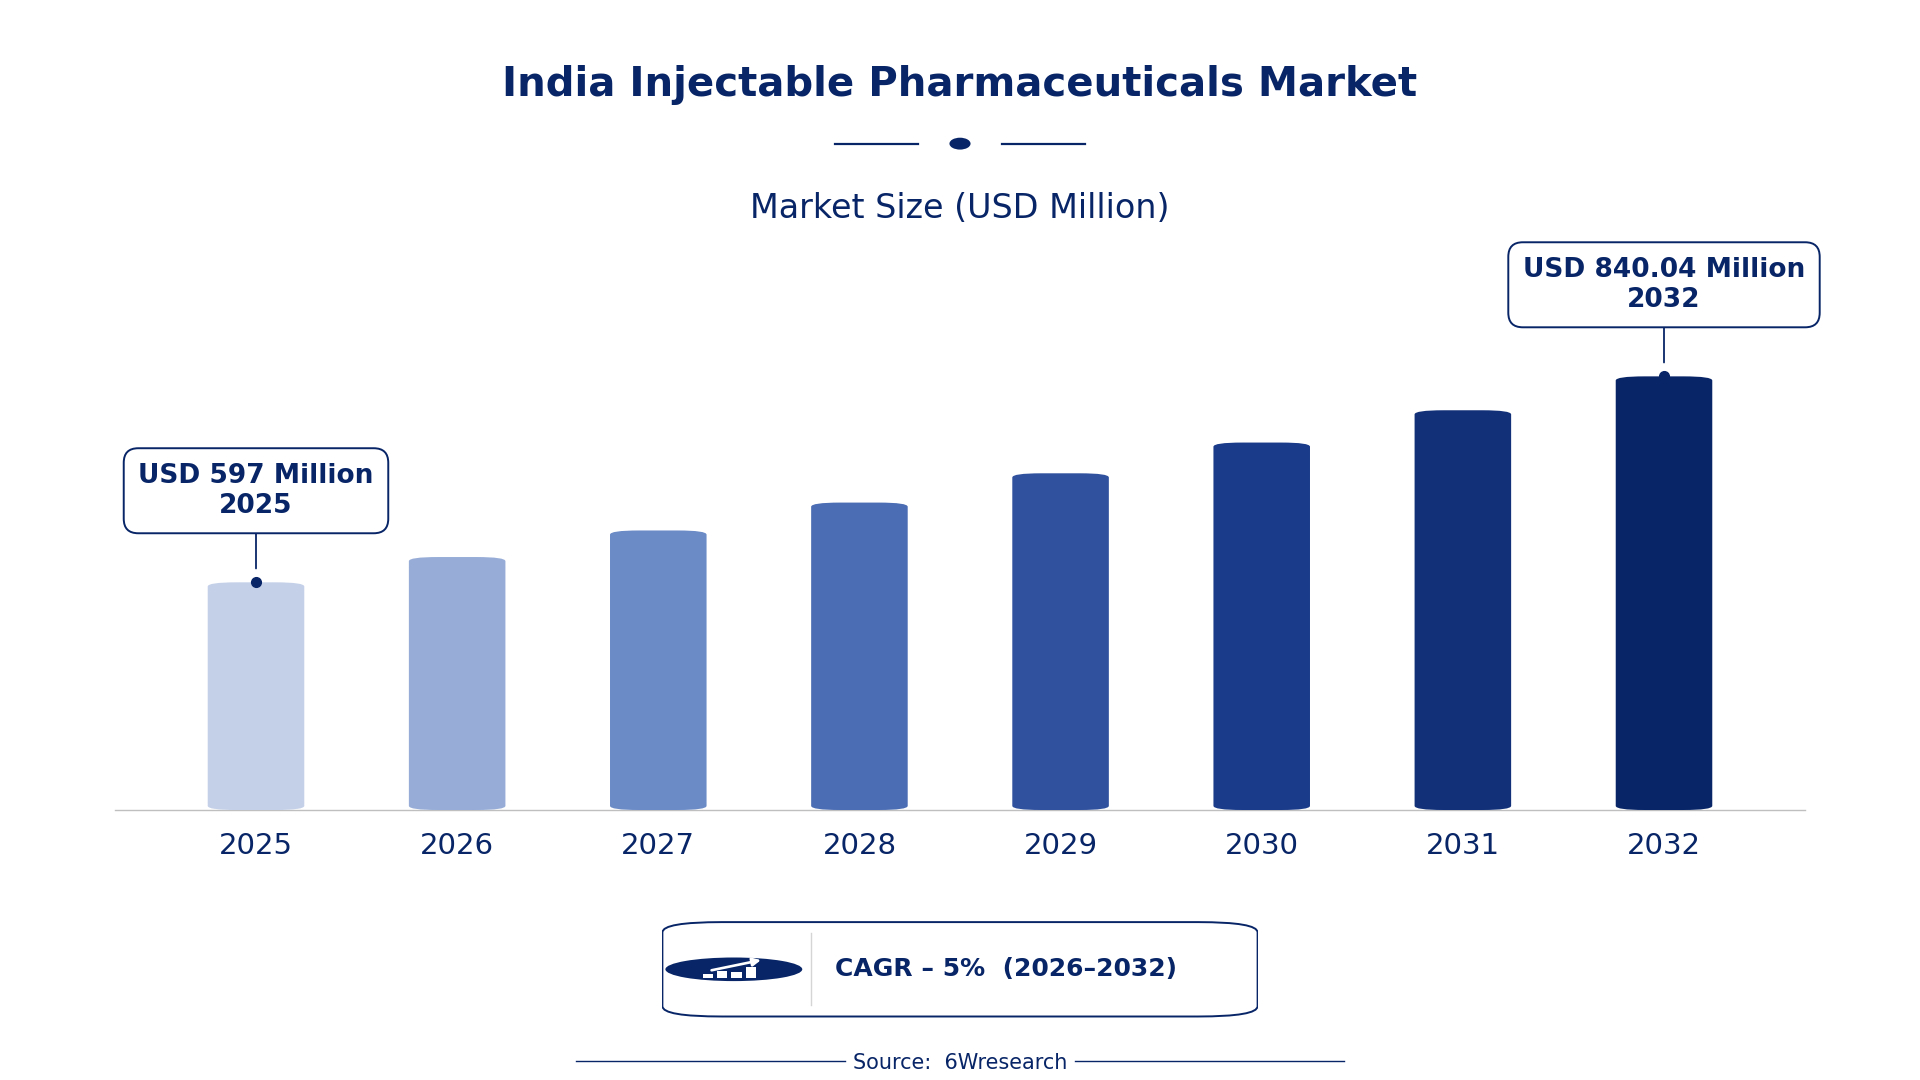
According to 6Wresearch internal database and industry insights, the India Injectable Pharmaceuticals Market was valued at USD 597.0 million in 2025 and is projected to reach USD 840.04 million by 2032, growing at a CAGR of approximately 5% during 2026–2032.
India Injectable Pharmaceuticals Market Highlights
| Report Metric | Details |
| Report Name | India Injectable Pharmaceuticals Market |
| Market Size 2025 | USD 597.0 million |
| Market Size 2032 | USD 840.04 million |
| Absolute Growth 2025–2032 | USD 243.04 million |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.3% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Drug Class, 2025 | Antibiotics (39% share) |
| Leading Route of Administration, 2025 | Intravenous (44% share) |
| Leading Usage Type, 2025 | Acute Infections (46% share) |
| Leading Product Form, 2025 | Solution/Vials (43% share) |
| Leading Distribution Channel, 2025 | Hospital Pharmacies (37% share) |
| Fastest-Growing Drug Class | Biologics (6.4% CAGR) |
| Fastest-Growing Route of Administration | Subcutaneous (6.5% CAGR) |
| Fastest-Growing Usage Type | Long-term Use (6.1% CAGR) |
| Fastest-Growing Product Form | Prefilled Syringes (6.6% CAGR) |
| Fastest-Growing Distribution Channel | Clinics (6.3% CAGR) |
| Growing Sector | Chronic Disease Management |
| Key End Users | Hospitals, Clinics, Specialty Care Facilities |
India Injectable Pharmaceuticals Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
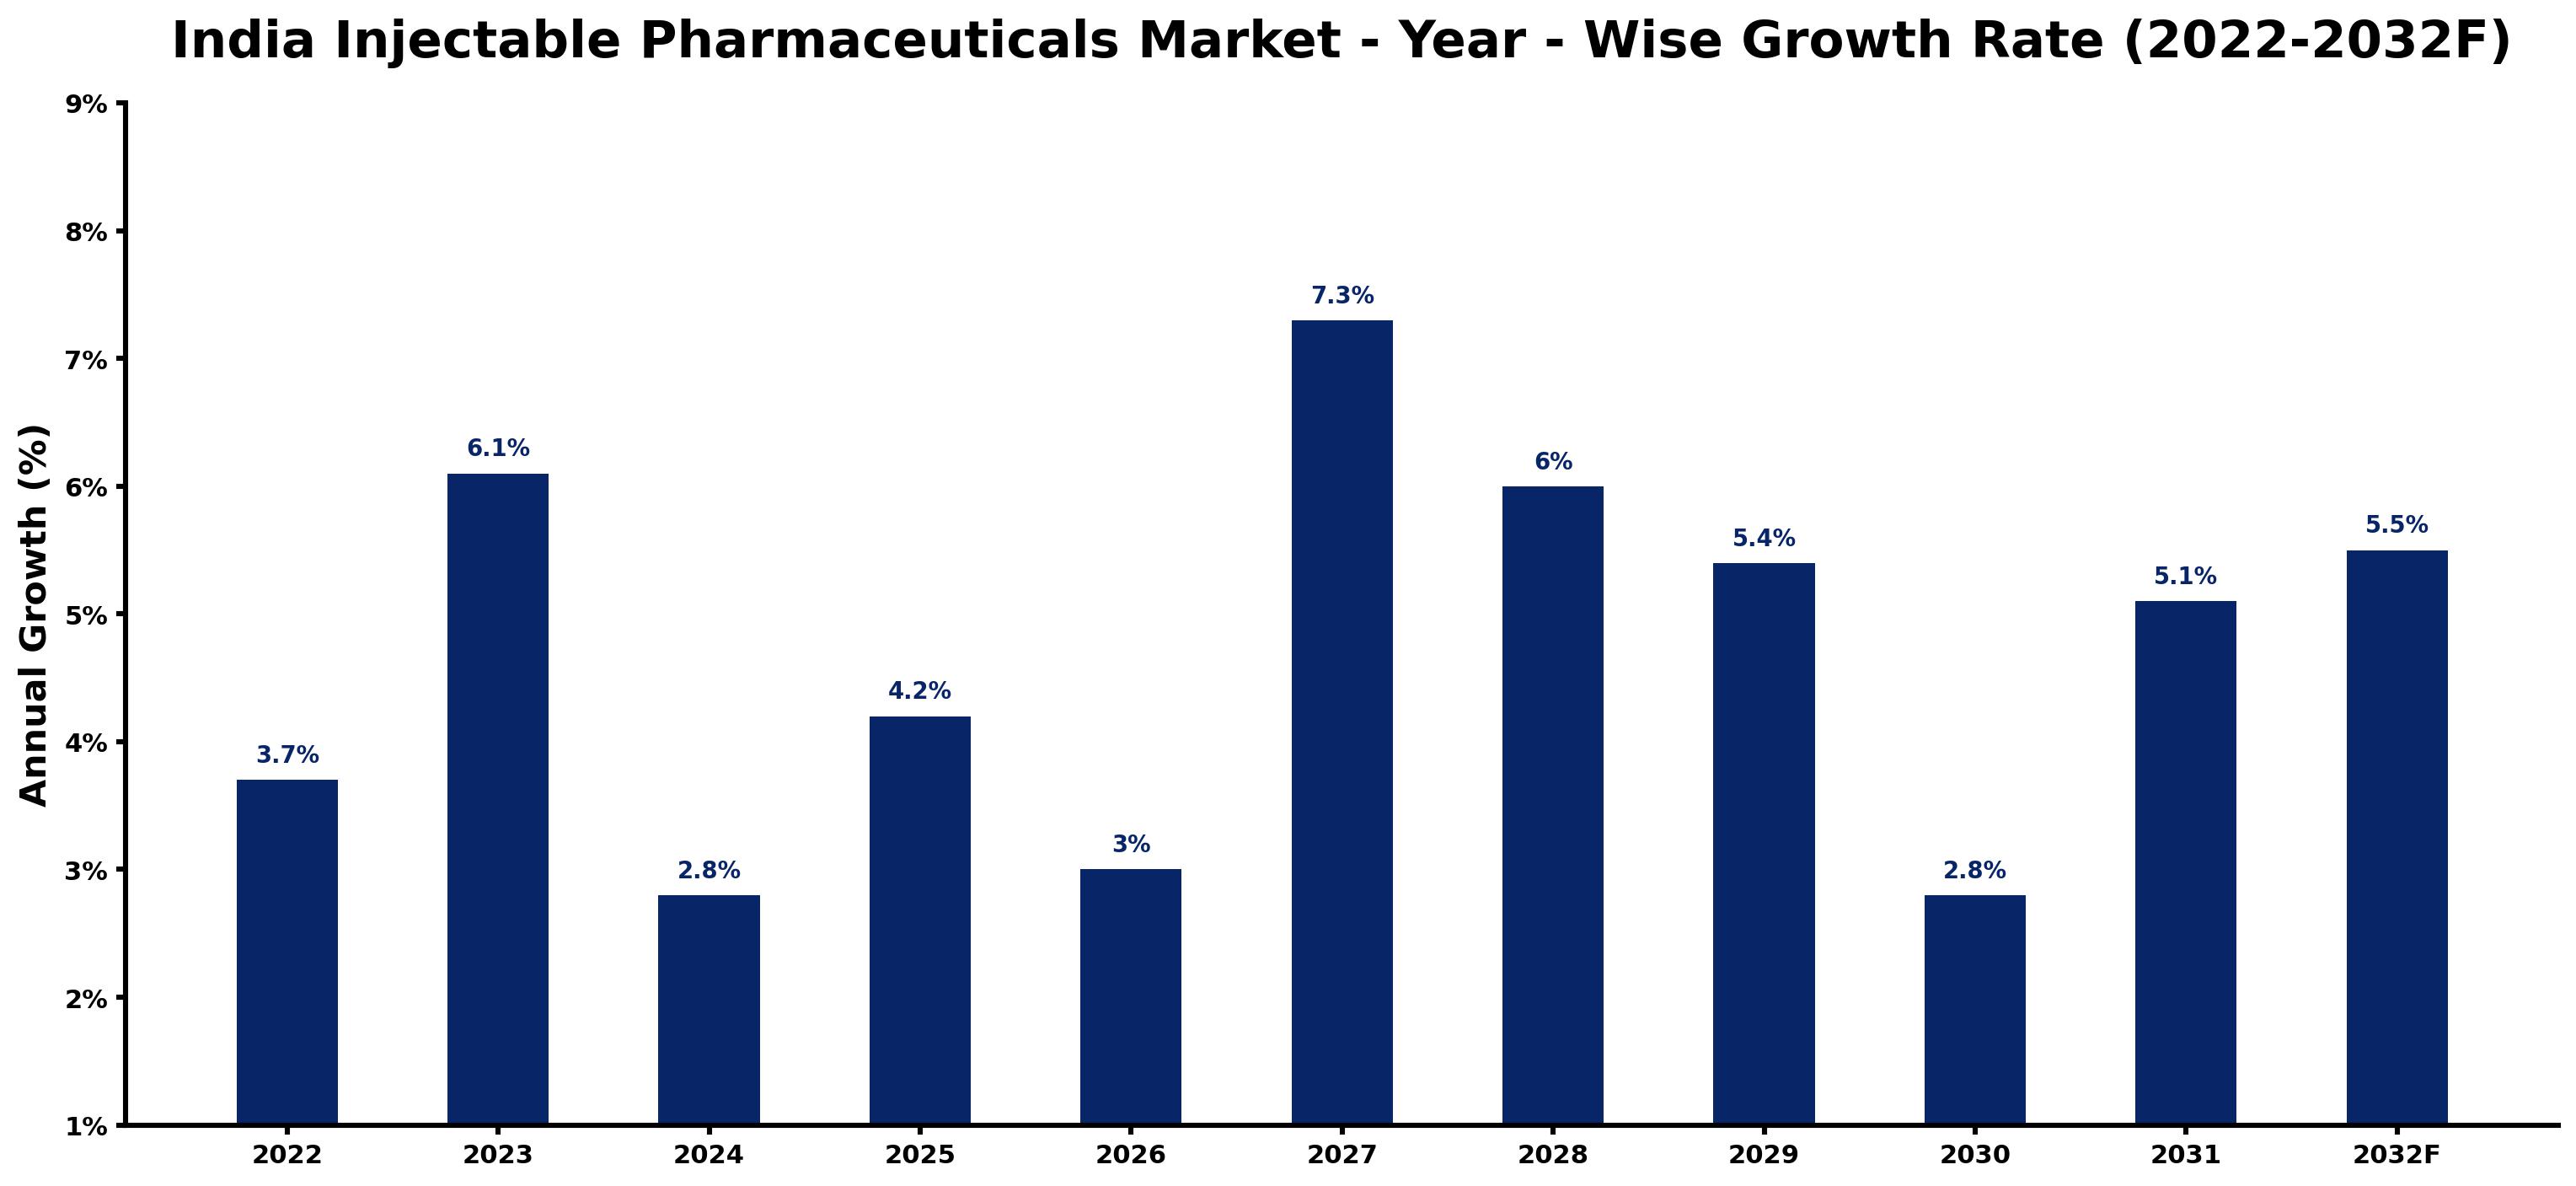
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.7 | The market experienced steady growth, reflecting ongoing healthcare demands from hospitals and clinics. |
| 2023 | 6.1 | Growth accelerated due to increased investments in healthcare infrastructure and the National Health Mission. |
| 2024 | 2.8 | A slowdown occurred as market adjustments took place following rapid expansion in the previous year. |
| 2025 | 4.2 | Demand surged as hospitals and clinics increased orders for injectable treatments following the National Health Mission's initiatives. |
| 2026 | 3.0 | The market is projected to see a slowdown as competition intensifies among suppliers. |
| 2027 | 7.3 | A surge in growth is expected due to the introduction of new treatment protocols for chronic diseases. |
| 2028 | 6.0 | Growth is projected to slow again as market saturation begins to take effect in key segments. |
| 2029 | 5.4 | Demand is expected to continue rising, supported by increasing patient populations and healthcare access. |
| 2030 | 2.8 | The market is projected to grow at a slower pace as regulatory adjustments are implemented. |
| 2031 | 5.1 | Growth is expected to pick up due to advancements in injectable drug technologies and production capabilities. |
| 2032 | 5.5 | A rise in demand is projected as healthcare access improves through government initiatives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Injectable Pharmaceuticals Market Synopsis
The Injectable Pharmaceuticals Market in India includes sterile medications delivered via injection, produced through complex processes involving formulation and sterilisation. These pharmaceuticals are primarily used in hospitals and clinics for treating various medical conditions, including infections and chronic diseases. The India Injectable Pharmaceuticals Market is expanding due to rising demand from hospitals, clinics, and specialty care facilities, driven by a population of approximately 1.4 billion and government initiatives like the National Health Mission launched in 2023, which aim to improve healthcare services and access to essential medicines.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased healthcare investments are driving demand for injectable pharmaceuticals. | Driver | High | Antibiotics |
| Growing patient populations are creating a higher demand for injectable medications. | Driver | High | Oncology Drugs |
| The gap in domestic production presents opportunities for new entrants. | Opportunity | High | Biologics |
| Rising chronic diseases create a need for long-term injectable therapies. | Opportunity | High | Pain Management |
| Regulatory hurdles can delay product approvals and market entry. | Restraint | High | Intravenous |
| High production costs can limit the competitiveness of local manufacturers. | Restraint | Medium | Subcutaneous |
| The Injectable Pharmaceuticals Market in India faces a few practical problems, including regulatory complexities. | Challenge | High | Acute Infections |
| Supply chain disruptions can affect the timely delivery of injectable products. | Challenge | Medium | Cancer Treatment |
Evaluation of Drivers in India Injectable Pharmaceuticals Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased foreign direct investment in healthcare is boosting production capacity. | Biologics | In 2022, the Indian healthcare sector received ₹37,000 crores in foreign direct investment, enhancing production capabilities. |
| Rising prevalence of chronic diseases is driving demand for injectables. | Pain Management | Over 200 million patients receive injectable treatments annually, increasing the need for effective pain management solutions. |
| Government initiatives are facilitating access to essential medicines. | Antibiotics | The National Health Policy 2020 aims to increase access to essential medicines, including injectables. |
| Technological advancements in drug formulation are enhancing product offerings. | Oncology Drugs | ISO 13485 standards for quality management are improving the reliability of injectable pharmaceuticals. |
| Growing healthcare infrastructure is expanding distribution channels for injectables. | Intravenous | India has over 1,500 hospitals equipped with injectable drug facilities, increasing availability. |
In 2022, the Indian healthcare sector received ₹37,000 crores in foreign direct investment, which is boosting production capacity for injectable drugs. With over 200 million patients receiving injectable treatments annually, healthcare providers are increasingly investing in effective solutions. Technological advancements in drug formulation are improving product offerings, encouraging healthcare providers to invest in new injectable options.
Evaluation of Restraints in India Injectable Pharmaceuticals Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory complexities can delay product approvals and market entry. | Intravenous | The Drug Controller General of India regulates injectable pharmaceuticals, which can slow down the approval process. |
| High production costs can limit the competitiveness of local manufacturers. | Subcutaneous | Manufacturers face challenges in maintaining cost-effective production while adhering to stringent quality standards. |
| Limited access to advanced technology can hinder innovation in the sector. | Biologics | Some manufacturers lack the necessary technology to produce high-quality biologics, impacting market growth. |
| Supply chain disruptions can affect the timely delivery of injectable products. | Cancer Treatment | Logistical challenges can delay shipments, impacting patient access to critical treatments and therapies. |
| Market saturation may restrict growth opportunities for new entrants. | Pain Management | Established players dominate the market, making it difficult for newcomers to gain a foothold and compete effectively. |
India Injectable Pharmaceuticals Market Challenges
The India Injectable Pharmaceuticals Market faces several practical challenges, starting with a shortage of skilled professionals. The intricate processes involved in producing injectable pharmaceuticals require trained personnel, which is limited in India, delaying production timelines for hospitals and clinics. Regulatory hurdles complicate matters; compliance with the Drug Controller General of India’s regulations is essential, yet many facilities struggle to meet these requirements, resulting in potential penalties and increased costs. Technological gaps also persist, as outdated equipment can lead to inefficiencies, impacting the quality and availability of injectables for over 200 million patients annually. Intense competition among local manufacturers drives down prices, which can compromise quality and lead to reduced margins for suppliers.
Trends in the India Injectable Pharmaceuticals Market
Several trends are reshaping the India Injectable Pharmaceuticals Market; the most important are set out below.
- Shift towards Biologics in Injectable Treatments: The trend towards biologics has been reinforced by the increasing prevalence of autoimmune disorders, with an expected growth of 6.4% in this segment. This shift reflects the demand for more effective treatment options among healthcare providers.
- Transition to Prefilled Syringes: The market is transitioning towards prefilled syringes, which offer convenience and reduce preparation time. This change is supported by a projected growth rate of 6.6% for this product form, enhancing patient compliance and satisfaction.
- Emergence of Long-term Use Injectables: Long-term use injectables are gaining traction as chronic diseases rise, with a growth rate of 6.1%. This trend highlights the need for sustained treatment regimens in patient care and management.
- Increased Focus on Hospital Pharmacies: Hospital pharmacies are becoming the primary distribution channel, holding a 37% market share. This focus is driven by the need for immediate access to injectable medications in clinical settings, ensuring timely patient care.
Investment Opportunities in the India Injectable Pharmaceuticals Market
Below are the investment opportunities with the strongest case in the India Injectable Pharmaceuticals Market.
- Gap in Domestic Production: With a significant gap in domestic production, there is an opportunity to invest in local manufacturing facilities. The market is expected to grow to USD 597.0 million by 2025, reflecting rising healthcare demands and the need for local supply.
- Timing for Expansion in Maharashtra: Now is an ideal time to expand operations in Maharashtra, a key state for injectable manufacturing. The region's growth potential is evident as it attracts investments to enhance production capabilities and meet local demand.
- Supply of Advanced Injectable Technologies: Investing in advanced injectable technologies presents a promising opportunity. The growing demand for innovative solutions aligns with the increasing patient population seeking effective treatments, creating a market for new entrants.
- Entry through Joint Ventures: Entering the market through joint ventures with local manufacturers can facilitate quicker access. This approach allows for utilising existing distribution networks and regulatory knowledge, easing market entry.
Government Initiatives in the India Injectable Pharmaceuticals Market
In 2022, the Ministry of Health and Family Welfare launched the 'Pharmaceuticals Vision 2025' aimed at boosting the production of injectable drugs. This initiative complements the National Health Policy 2020, which emphasises increasing access to essential medicines. Together, these measures aim to streamline production and distribution processes, ensuring injectable pharmaceuticals are more readily available to healthcare providers and patients alike.
The Central Drugs Standard Control Organization oversees the approval of injectable pharmaceuticals, ensuring compliance with safety and efficacy standards. This agency regulates the market, approving new products and monitoring existing ones to maintain high-quality standards. The Drug Technical Advisory Board also supports this framework by recommending updates to regulations, enhancing the sector's operational efficiency and ensuring that manufacturers meet compliance requirements.
Future Insight of the India Injectable Pharmaceuticals Market
The India Injectable Pharmaceuticals Market is set for transformation by 2032, driven by several key factors. The National Health Mission will improve healthcare services, increasing the demand for injectables across hospitals and specialty care facilities. By 2032, foreign direct investment in the healthcare sector is projected to reach ₹50,000 crores, facilitating advancements in technology and production capabilities. The implementation of the Pradhan Mantri Jan Arogya Yojana will improve access to essential injectable medications for the growing population, ensuring that more patients receive timely treatments.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Drug Class – Antibiotics Dominated, Biologics Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Antibiotics held a 39% share of the India Injectable Pharmaceuticals Market by drug class in 2025. Antibiotics hold the largest share in the Indian injectable pharmaceuticals market due to their critical role in treating infections across more than 1,500 hospitals. Their widespread use in healthcare facilities ensures a consistent demand, reinforcing their dominant position. Biologics are set to record the highest CAGR in this split, 6.4% over 2026–2032. Biologics are experiencing rapid growth, largely driven by the increasing prevalence of autoimmune disorders that necessitate advanced injectable therapies. The government's initiatives to improve healthcare services for biologics are expected to significantly boost this segment's expansion. Suppliers should focus on expanding their biologics offerings to take advantage of the growing market share.
By Route of Administration – Intravenous Dominated, Subcutaneous Expected to Grow Fastest
The largest route of administration category in 2025 was Intravenous, with a 44% share of total revenue. Intravenous administration leads the market as it is commonly used in hospitals for quick drug delivery, particularly in emergencies. Its crucial role in treating acute conditions solidifies its dominant market share. Over 2026–2032, Subcutaneous is expected to post the fastest growth, at a CAGR of 6.5%. Subcutaneous administration is the fastest-growing route, primarily due to its convenience for patients, especially in managing chronic diseases like diabetes. As self-administration becomes more prevalent, this segment's growth is anticipated to continue. Suppliers should consider developing more subcutaneous delivery options to meet the increasing demand for patient-friendly administration methods.
By Usage Type – Acute Infections Dominated, Long-term Use Expected to Grow Fastest
Acute Infections accounted for a 46% market share by usage type in 2025. Acute infections lead the usage type segment, necessitating immediate treatment across various healthcare settings, including hospitals and clinics. This urgent requirement for injectable medications guarantees sustained demand within this category. Long-term Use is projected to grow fastest, at a CAGR of 6.1% during 2026–2032. Long-term use is the fastest-growing segment, propelled by the increasing prevalence of chronic conditions that require ongoing injectable therapies. This trend indicates a shift towards sustained treatment approaches, highlighting the need for continuous care solutions. Suppliers must adjust their strategies to address the growing demand for long-term injectable solutions.
By Product Form – Solution/Vials Dominated, Prefilled Syringes Expected to Grow Fastest
Solution/Vials took a 43% share of product form in 2025, more than any other category. Solution/vials are the leading product form in the injectable pharmaceuticals market, serving as the standard for effective drug delivery in healthcare environments. Their established presence in hospitals guarantees a steady demand for this format. The quickest growth will come from Prefilled Syringes, forecast to expand at a CAGR of 6.6% between 2026 and 2032. Prefilled syringes are witnessing the fastest growth, driven by their convenience for patient self-administration, particularly in managing chronic conditions. This trend is likely to persist as patients increasingly prefer user-friendly options. Suppliers should invest in the development of prefilled syringes to align with market preferences for convenience and ease of use.
By Distribution Channel – Hospital Pharmacies Dominated, Clinics Expected to Grow Fastest
With a 37% revenue share in 2025, Hospital Pharmacies was the largest distribution channel category. Hospital pharmacies are the main distribution channel for injectable drugs, providing essential access points for healthcare providers. Their established networks ensure that injectable medications are readily available to patients in need of treatment. Clinics are set to record the highest CAGR in this split, 6.3% over 2026–2032. Clinics are rapidly becoming a significant distribution channel, reflecting the shift towards outpatient care and the growing role of primary healthcare providers in administering injectables. This trend indicates a promising market opportunity in the clinic sector. Suppliers should enhance their distribution strategies to include clinics, capitalising on the expanding role of outpatient care.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Injectable Pharmaceuticals Market Outlook
- Market Size of India Injectable Pharmaceuticals Market, 2025
- Forecast of India Injectable Pharmaceuticals Market, 2032
- Historical Data and Forecast of India Injectable Pharmaceuticals Revenues & Volume for the Period 2022 - 2032F
- India Injectable Pharmaceuticals Market Trend Evolution
- India Injectable Pharmaceuticals Market Drivers and Challenges
- India Injectable Pharmaceuticals Price Trends
- India Injectable Pharmaceuticals Porter's Five Forces
- India Injectable Pharmaceuticals Industry Life Cycle
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Drug Class for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Antibiotics for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Oncology Drugs for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Biologics for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Pain Management for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Route of Administration for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Intravenous for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Intramuscular for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Subcutaneous for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Intrathecal for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Usage Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Acute Infections for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Cancer Treatment for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Long-term Use for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Emergency Use for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Product Form for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Solution/Vials for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Reconstitutable Powders for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Prefilled Syringes for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Ampoules for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Hospital Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Specialty Stores for the Period 2022 - 2032F
- Historical Data and Forecast of India Injectable Pharmaceuticals Market Revenues & Volume By Retail Pharmacies for the Period 2022 - 2032F
- India Injectable Pharmaceuticals Import Export Trade Statistics
- Market Opportunity Assessment By Drug Class
- Market Opportunity Assessment By Route of Administration
- Market Opportunity Assessment By Usage Type
- Market Opportunity Assessment By Product Form
- Market Opportunity Assessment By Distribution Channel
- India Injectable Pharmaceuticals Top Companies Market Share
- India Injectable Pharmaceuticals Competitive Benchmarking By Technical and Operational Parameters
- India Injectable Pharmaceuticals Company Profiles
- India Injectable Pharmaceuticals Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Drug Class
- Antibiotics
- Oncology Drugs
- Biologics
- Pain Management
By Route of Administration
- Intravenous
- Intramuscular
- Subcutaneous
- Intrathecal
By Usage Type
- Acute Infections
- Cancer Treatment
- Long-term Use
- Emergency Use
By Product Form
- Solution/Vials
- Reconstitutable Powders
- Prefilled Syringes
- Ampoules
By Distribution Channel
- Hospital Pharmacies
- Clinics
- Specialty Stores
- Retail Pharmacies































