India Insulin and Oral Hypoglycemics Market Size & Growth Rate
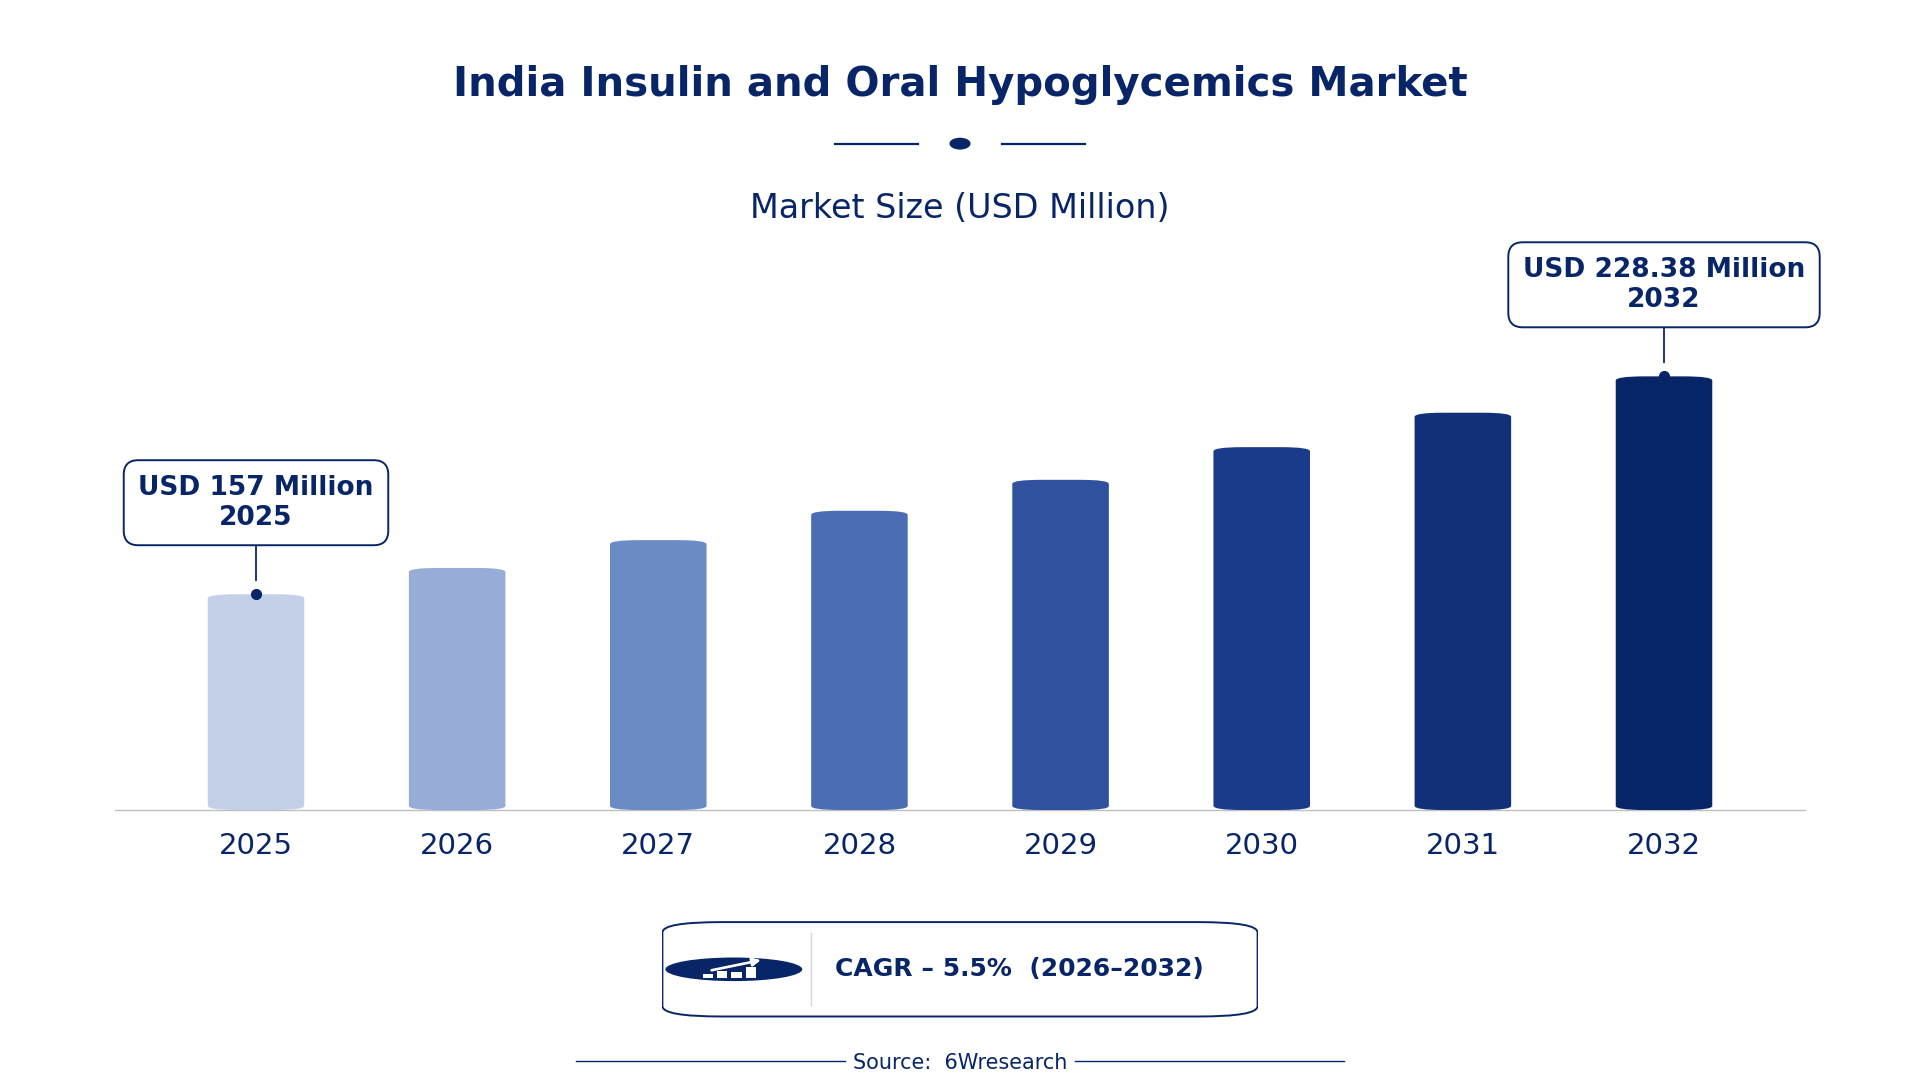
According to 6Wresearch internal database and industry insights, the India Insulin and Oral Hypoglycemics Market was valued at USD 157.0 million in 2025 and is projected to reach USD 228.38 million by 2032, growing at a CAGR of approximately 5.5% during 2026–2032.
India Insulin and Oral Hypoglycemics Market Highlights
| Report Metric | Details |
| Report Name | India Insulin and Oral Hypoglycemics Market |
| Market Size 2025 | USD 157.0 million |
| Market Size 2032 | USD 228.38 million |
| Absolute Growth 2025–2032 | USD 71.38 million |
| CAGR 2026–2032 | 5.5% |
| Peak Annual Growth | 7.6% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Product Type, 2025 | Rapid-Acting Insulin (50% share) |
| Leading Drug Class, 2025 | Insulin Analogues (50% share) |
| Leading Distribution Channel, 2025 | Hospital Pharmacies (36% share) |
| Leading Patient Type, 2025 | Type 1 Diabetes (43% share) |
| Leading End User, 2025 | Hospitals (41% share) |
| Fastest-Growing Product Type | Long-Acting Insulin (7.3% CAGR) |
| Fastest-Growing Drug Class | Recombinant Human Insulin (8.1% CAGR) |
| Fastest-Growing Distribution Channel | Retail Pharmacies (6.9% CAGR) |
| Fastest-Growing Patient Type | Type 2 Diabetes (7.4% CAGR) |
| Fastest-Growing End User | Clinics (7.8% CAGR) |
| Growing Sector | Clinics |
| Key End Users | Hospitals, Clinics, Home Care Settings, Endocrinology Centers |
India Insulin and Oral Hypoglycemics Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
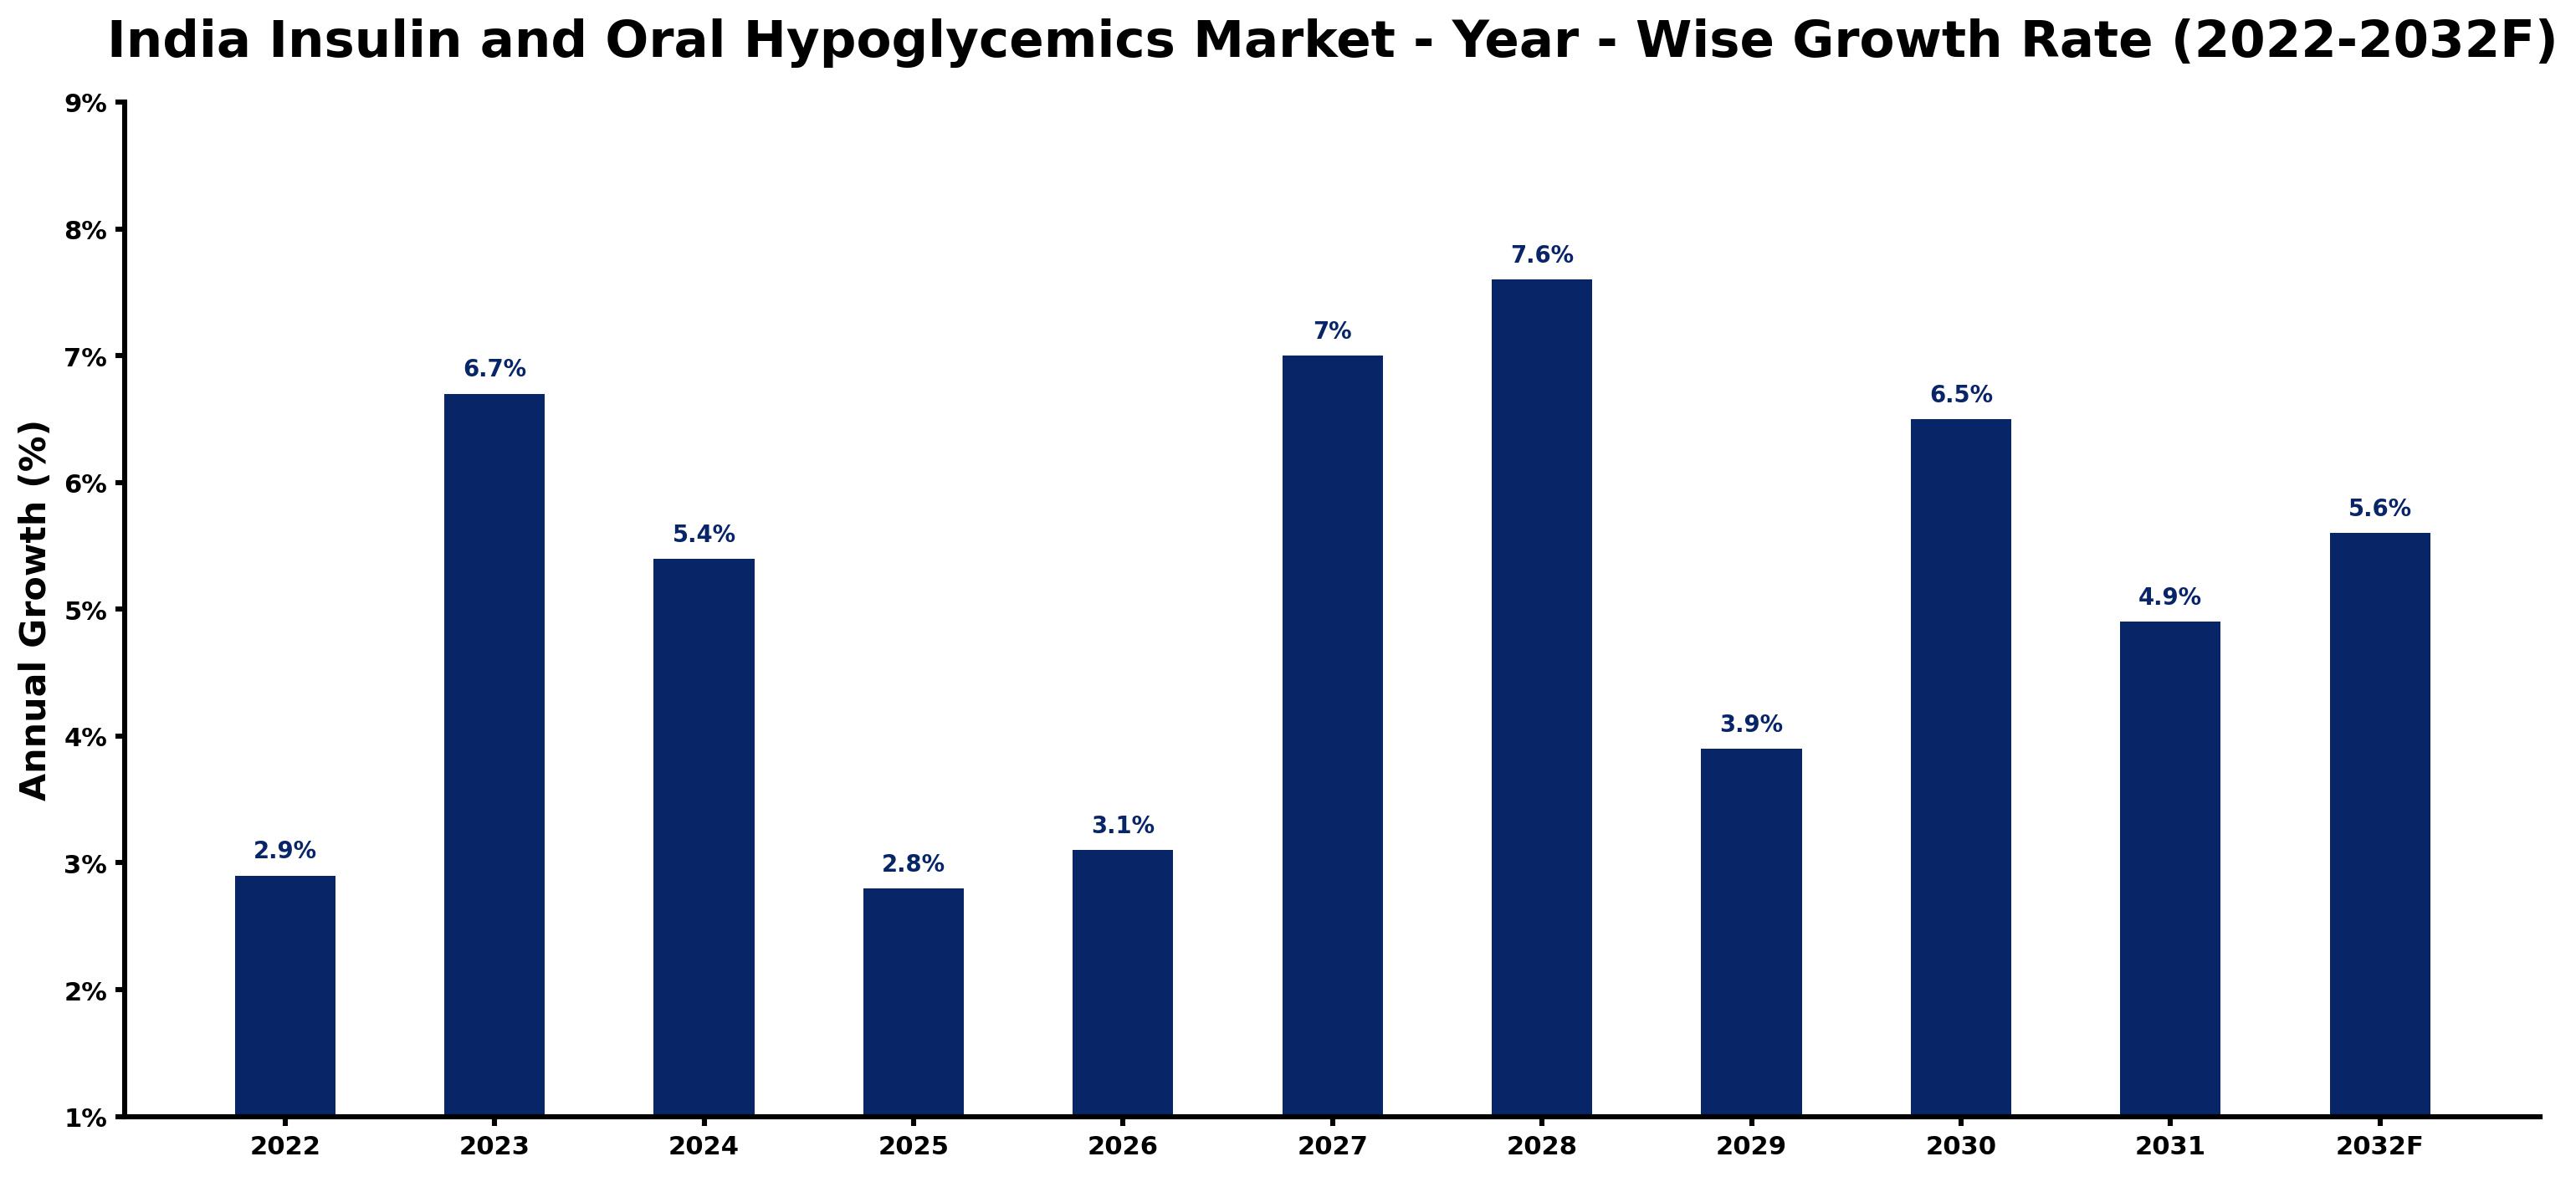
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.9 | The market experienced steady growth due to increased awareness of diabetes management. |
| 2023 | 6.7 | Demand surged as the average age of diabetes onset reached 45 years. |
| 2024 | 5.4 | Growth slowed as the market adjusted to increased competition among treatment options. |
| 2025 | 2.8 | The market continued to grow, driven by the National Diabetes Control Programme's initiatives. |
| 2026 | 3.1 | Growth accelerated with rising prescriptions for long-acting insulin among healthcare providers. |
| 2027 | 7.0 | Demand increased as healthcare facilities expanded diabetes management programs. |
| 2028 | 7.6 | The peak growth occurred due to heightened patient awareness and education initiatives. |
| 2029 | 3.9 | Growth slowed as market saturation began to affect new patient acquisition. |
| 2030 | 6.5 | Demand rebounded with the implementation of new diabetes care guidelines. |
| 2031 | 4.9 | Growth decelerated as the market stabilised with established treatment protocols. |
| 2032 | 5.6 | The market is expected to grow as more patients seek effective diabetes management solutions. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Insulin and Oral Hypoglycemics Market Synopsis
Insulin and Oral Hypoglycemics Market in India includes pharmaceutical products that regulate blood sugar levels in diabetes patients. These products consist of insulin and oral medications, primarily used by Type 1 and Type 2 diabetes patients. The market is expanding due to a rising number of diabetes patients, with over 77 million reported in 2023, and initiatives like the National Diabetes Control Programme aiming to reduce prevalence by 25% by 2030. Healthcare providers are driving demand as they seek effective treatment options for their patients.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising prevalence of diabetes is driving demand for effective management solutions. | Driver | High | Insulin Analogues |
| Increasing preference for insulin analogues due to their pharmacokinetic advantages. | Driver | High | Insulin Analogues |
| Growing demand for diabetes medications among geriatric patients presents a significant opportunity. | Opportunity | High | Geriatric Patients |
| The rise of online pharmacies offers a convenient channel for diabetes medication access. | Opportunity | Medium | Online Pharmacies |
| High cost of diabetes medications can limit access for lower-income patients. | Restraint | High | Type 2 Diabetes |
| Limited awareness about diabetes management among certain demographics can hinder growth. | Restraint | Medium | Type 1 Diabetes |
| The market faces challenges due to inconsistent supply chains affecting medication availability. | Challenge | High | Oral Hypoglycemics |
| Regulatory hurdles can delay the introduction of new diabetes medications. | Challenge | Medium | Oral Hypoglycemics |
Evaluation of Drivers in India Insulin and Oral Hypoglycemics Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased healthcare spending is driving demand for diabetes management products. | Type 2 Diabetes | Healthcare providers are expanding their offerings, leading to a 30% rise in online pharmacy sales of diabetes medications. |
| The National Diabetes Control Programme aims to reduce diabetes prevalence, boosting medication demand. | Insulin Analogues | This initiative encourages healthcare providers to prescribe more effective treatment options for patients. |
| Rising awareness of diabetes management is driving greater patient engagement. | Geriatric Patients | Education initiatives from the Indian Diabetes Association have increased treatment adherence among older patients. |
| Technological advancements in drug formulation are improving product efficacy. | Recombinant Human Insulin | These innovations are attracting more prescriptions from healthcare professionals seeking effective solutions. |
| Growing prevalence of obesity is increasing the incidence of Type 2 diabetes. | Type 2 Diabetes | This trend drives demand for both insulin and oral hypoglycemics among affected individuals. |
The Insulin and Oral Hypoglycemics market in India is growing on the back of rising healthcare spending, increasing patient engagement, and advancements in drug formulation. Over 77 million diabetes patients in India are driving demand for effective management solutions. Technological advancements in drug formulation are improving product efficacy, resulting in a higher volume of prescriptions from healthcare professionals seeking effective solutions.
Evaluation of Restraints in India Insulin and Oral Hypoglycemics Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of diabetes medications limit access for lower-income patients. | Type 2 Diabetes | Approximately 90% of diabetes cases are Type 2, where cost barriers significantly impact treatment access. |
| Limited awareness about diabetes management can hinder growth in certain demographics. | Type 1 Diabetes | Many patients lack knowledge about available treatment options, affecting adherence to prescribed therapies. |
| Inconsistent supply chains affect medication availability, impacting patient care. | Oral Hypoglycemics | Disruptions in logistics can lead to stock shortages in pharmacies, delaying treatment for patients. |
| Regulatory hurdles can delay the introduction of new diabetes medications. | Oral Hypoglycemics | Lengthy approval processes can slow down access to innovative treatment options for patients. |
| Market saturation can limit growth opportunities for new entrants. | Insulin Analogues | Established brands dominate the market, making it challenging for new products to gain traction. |
India Insulin and Oral Hypoglycemics Market Challenges
The India Insulin and Oral Hypoglycemics Market faces a few practical problems, starting with supply chain disruptions that limit access to critical raw materials, causing production delays for manufacturers. Many healthcare providers continue to rely on outdated diabetes management techniques, resulting in suboptimal treatment outcomes for patients. Buyers in rural regions struggle to find affordable medications, which leads to inadequate diabetes control for millions. Rising production costs for insulin have driven up prices for consumers, with some patients facing a 20% increase in expenses, complicating their ability to manage their diabetes effectively.
Trends in the India Insulin and Oral Hypoglycemics Market
Several trends are reshaping the India Insulin and Oral Hypoglycemics Market; the most important are set out below.
- Shift from Traditional to Online Pharmacies: India is experiencing a shift towards online pharmacies for diabetes medication purchases. In 2023, online pharmacies saw a 30% increase in sales, driven by convenience and accessibility for patients.
- Increased Preference for Insulin Analogues: Since 2022, insulin analogues have gained popularity among healthcare providers due to their pharmacokinetic advantages. This trend is reflected in the growing market share of insulin analogues, which reached 50% in 2025.
- Focus on Geriatric Diabetes Management: The emphasis on tailored diabetes management for geriatric patients has intensified. In 2023, geriatric patients accounted for approximately 30% of diabetes cases, prompting healthcare providers to develop specific treatment protocols.
- Rising Awareness Campaigns: Awareness campaigns led by the Indian Diabetes Association have increased knowledge about diabetes management. In 2023, these initiatives significantly improved patient engagement and adherence to treatment.
Investment Opportunities in the India Insulin and Oral Hypoglycemics Market
Below are the investment opportunities with the strongest case in the India Insulin and Oral Hypoglycemics Market.
- Geriatric Patients Seeking Effective Diabetes Management: With 30% of diabetes cases attributed to geriatric patients, there is a growing need for tailored treatment solutions. Investing in specialised diabetes programs can attract this buyer group and improve patient outcomes.
- Expanding Online Pharmacy Market: The online pharmacy sector is experiencing a 30% increase in sales. Supplying diabetes medications through this channel can capture a larger market share among tech-savvy consumers seeking convenience.
- New Diabetes Treatment Solutions: The demand for new diabetes treatments is rising, with a significant gap in the market. Collaborating with healthcare providers to offer effective therapies can meet this demand and improve patient management.
- Increased Focus on Diabetes Education: With rising awareness of diabetes management, there is a need for educational programs. Partnering with healthcare institutions to provide training can enhance patient outcomes and adherence to treatment.
Government Initiatives in the India Insulin and Oral Hypoglycemics Market
The Drugs and Cosmetics Act, 1940, establishes the regulatory framework for pharmaceuticals, ensuring that insulin and oral hypoglycemics meet safety and efficacy standards. The National Health Mission, launched in 2013, aims to improve healthcare delivery, including diabetes management, by allocating funds for community health initiatives. The National Diabetes Control Programme, initiated in 2020, focuses on reducing diabetes prevalence by 25% by 2030, promoting awareness and access to treatment. Additionally, the Indian Council of Medical Research has set guidelines for diabetes management to standardise treatment protocols across the country. These measures collectively improve the quality of diabetes care and enhance access to essential medications for patients.
The Ministry of Health and Family Welfare oversees the implementation of healthcare policies, including those related to diabetes management. It funds various initiatives aimed at improving diabetes care, such as the National Health Mission, which supports community health programmes. The Indian Diabetes Association plays a crucial role in promoting awareness and education on diabetes management, assisting healthcare providers and patients alike. Additionally, the Indian Council of Medical Research approves research projects that focus on diabetes treatment and management, ensuring that advancements in the field are effectively integrated into clinical practice. These agencies are key in shaping the future of diabetes care in India.
Future Insight of the India Insulin and Oral Hypoglycemics Market
The India Insulin and Oral Hypoglycemics Market is set for notable changes by 2032, primarily driven by the National Health Mission's efforts to improve diabetes care nationwide. Advancements in drug delivery technologies will support better patient adherence to treatment plans. Increased funding for diabetes research will lead to the development of more effective management solutions. Online pharmacies are expected to experience a 30% increase in sales, enhancing medication accessibility for consumers across the country.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Product Type – Rapid-Acting Insulin Dominated, Long-Acting Insulin Expected to Grow Fastest
According to Shubham Deep, Research Manager at 6Wresearch, Rapid-Acting Insulin accounted for a 50% market share by product type in 2025. Rapid-Acting Insulin captures a substantial market share because it is essential for managing postprandial glucose levels in diabetes patients. The increasing number of diabetes patients in India necessitates effective solutions for immediate blood sugar control. The quickest growth will come from Long-Acting Insulin, forecast to expand at a CAGR of 7.3% between 2026 and 2032. The rapid growth of Long-Acting Insulin is driven by a rising preference among healthcare providers for sustained blood sugar management. This trend is evident as more patients seek long-acting formulations for improved glycaemic control. Suppliers should prioritise the development of long-acting insulin options to address the growing demand for effective diabetes management.
By Drug Class – Insulin Analogues Dominated, Recombinant Human Insulin Expected to Grow Fastest
Insulin Analogues held a 50% share of the India Insulin and Oral Hypoglycemics Market by drug class in 2025. Insulin Analogues hold a leading market share due to their ability to provide tailored action profiles that meet the diverse needs of diabetes patients. Their pharmacokinetic advantages make them a preferred choice for healthcare providers managing diabetes effectively. Over 2026–2032, Recombinant Human Insulin is expected to post the fastest growth, at a CAGR of 8.1%. Recombinant Human Insulin is witnessing rapid growth as it serves as a reliable synthetic alternative to natural insulin. This is increasingly important as the diabetes patient population continues to expand in India. Buyers will benefit from a wider array of insulin options, allowing for more personalised diabetes treatment plans.
By Distribution Channel – Hospital Pharmacies Dominated, Retail Pharmacies Expected to Grow Fastest
Hospital Pharmacies took a 36% share of distribution channel in 2025, more than any other category. Hospital Pharmacies dominate the market share as they play a crucial role in dispensing medications to both inpatients and outpatients, ensuring timely access to diabetes treatments. This is particularly vital in a country with a high prevalence of diabetes. Retail Pharmacies are projected to grow fastest, at a CAGR of 6.9% during 2026–2032. Retail Pharmacies are experiencing the fastest growth as they meet the public's demand for accessible diabetes medications. The 30% increase in sales through these channels indicates a shift towards more convenient medication access. Suppliers should focus on strengthening relationships with retail pharmacies to effectively capture this expanding market segment.
By Patient Type – Type 1 Diabetes Dominated, Type 2 Diabetes Expected to Grow Fastest
In 2025, Type 1 Diabetes led the patient type split with a 43% share. Type 1 Diabetes represents a significant market share as it requires insulin therapy for effective management. The specific treatment needs of this patient group ensure a consistent demand for insulin products. Type 2 Diabetes are set to record the highest CAGR in this split, 7.4% over 2026–2032. Type 2 Diabetes is growing rapidly, accounting for approximately 90% of diabetes cases in India, with many patients needing both insulin and oral medications. This trend is likely to persist as lifestyle factors contribute to rising incidence rates. Healthcare providers must prepare for an increasing demand for comprehensive diabetes management solutions tailored specifically for Type 2 patients.
By End User – Hospitals Dominated, Clinics Expected to Grow Fastest
With a 41% revenue share in 2025, Hospitals was the largest end user category. Hospitals command the largest market share as they are the primary setting for diabetes treatment, providing essential care to a large patient population. Their critical role in managing severe diabetes cases ensures a steady demand for related products. The quickest growth will come from Clinics, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Clinics are experiencing the fastest growth as they provide outpatient care, making diabetes management more accessible to patients. This trend is expected to continue as more individuals seek convenient healthcare options. Suppliers should enhance their distribution strategies to effectively target clinics, capitalising on the growing outpatient care market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Insulin and Oral Hypoglycemics Market Outlook
- Market Size of India Insulin and Oral Hypoglycemics Market, 2025
- Forecast of India Insulin and Oral Hypoglycemics Market, 2032
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Revenues & Volume for the Period 2022 - 2032F
- India Insulin and Oral Hypoglycemics Market Trend Evolution
- India Insulin and Oral Hypoglycemics Market Drivers and Challenges
- India Insulin and Oral Hypoglycemics Price Trends
- India Insulin and Oral Hypoglycemics Porter's Five Forces
- India Insulin and Oral Hypoglycemics Industry Life Cycle
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Rapid-Acting Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Long-Acting Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Sulfonylureas for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By DPP-4 Inhibitors for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Drug Class for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Insulin Analogues for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Recombinant Human Insulin for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Oral Hypoglycemics for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Oral Hypoglycemics for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Distribution Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Hospital Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Retail Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Online Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Mail-Order Pharmacies for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Patient Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Type 1 Diabetes for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Type 2 Diabetes for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Geriatric Patients for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Obese Patients for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Home Care Settings for the Period 2022 - 2032F
- Historical Data and Forecast of India Insulin and Oral Hypoglycemics Market Revenues & Volume By Endocrinology Centers for the Period 2022 - 2032F
- India Insulin and Oral Hypoglycemics Import Export Trade Statistics
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Drug Class
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By Patient Type
- Market Opportunity Assessment By End User
- India Insulin and Oral Hypoglycemics Top Companies Market Share
- India Insulin and Oral Hypoglycemics Competitive Benchmarking By Technical and Operational Parameters
- India Insulin and Oral Hypoglycemics Company Profiles
- India Insulin and Oral Hypoglycemics Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Product Type
- Rapid-Acting Insulin
- Long-Acting Insulin
- Sulfonylureas
- DPP-4 Inhibitors
By Drug Class
- Insulin Analogues
- Recombinant Human Insulin
- Oral Hypoglycemics
By Distribution Channel
- Hospital Pharmacies
- Retail Pharmacies
- Online Pharmacies
- Mail-Order Pharmacies
By Patient Type
- Type 1 Diabetes
- Type 2 Diabetes
- Geriatric Patients
- Obese Patients
By End User
- Hospitals
- Clinics
- Home Care Settings
- Endocrinology Centers































