India Insurance Distribution Market Size & Growth Rate
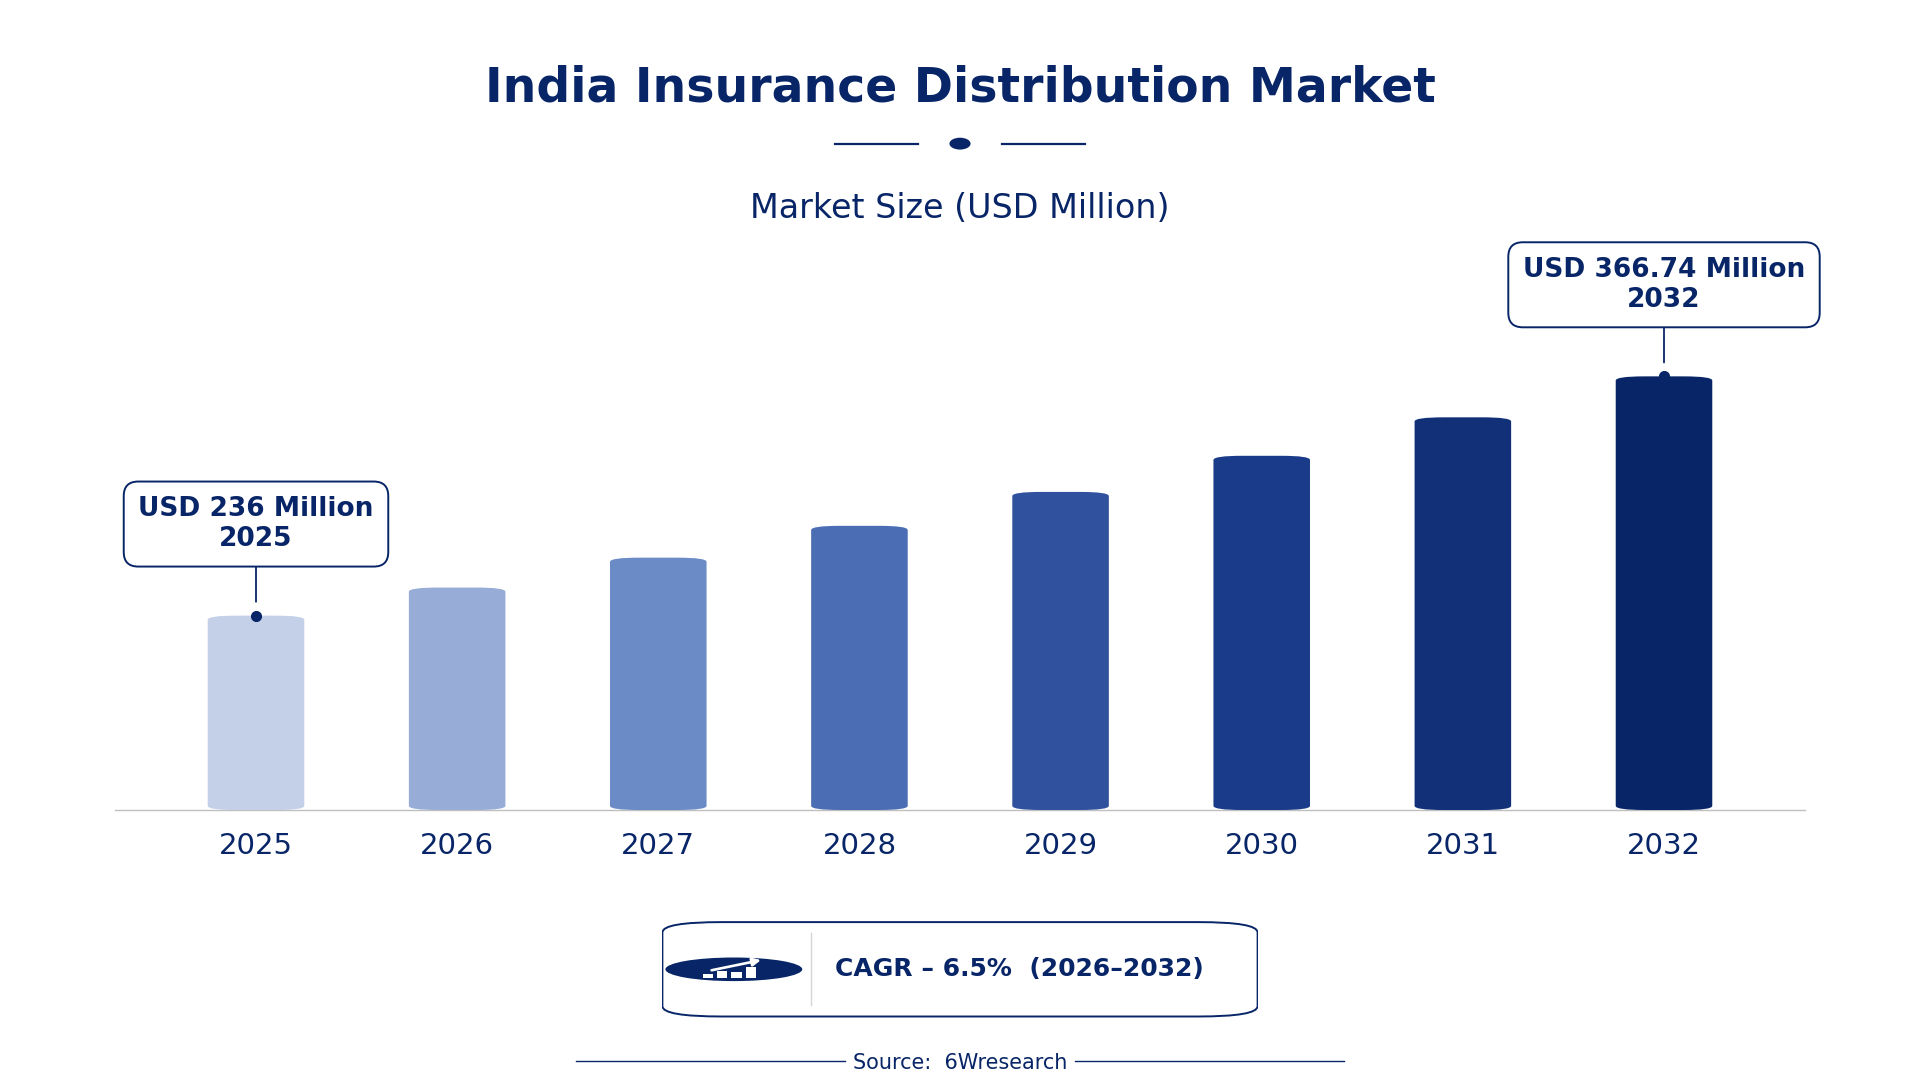
According to 6Wresearch internal database and industry insights, the India Insurance Distribution Market was valued at USD 236.0 million in 2025 and is projected to reach USD 366.74 million by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
India Insurance Distribution Market Highlights
| Report Metric | Details |
| Report Name | India Insurance Distribution Market |
| Market Size 2025 | USD 236.0 million |
| Market Size 2032 | USD 366.74 million |
| Absolute Growth 2025–2032 | USD 130.74 million |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 8.5% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Channel Type, 2025 | Direct Online (45% share) |
| Leading Product Type, 2025 | Life Insurance (41% share) |
| Leading Customer Segment, 2025 | Individual (41% share) |
| Leading Technology Mode, 2025 | Digital (39% share) |
| Leading End User, 2025 | General Public (40% share) |
| Fastest-Growing Product Type | Health Insurance (8.6% CAGR) |
| Fastest-Growing Customer Segment | SMEs (9.0% CAGR) |
| Fastest-Growing Technology Mode | Hybrid (8.9% CAGR) |
| Fastest-Growing End User | Enterprises (8.8% CAGR) |
| Growing Sector | Health Insurance |
| Key End Users | General Public, SMEs, Retail Customers, Enterprises |
India Insurance Distribution Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
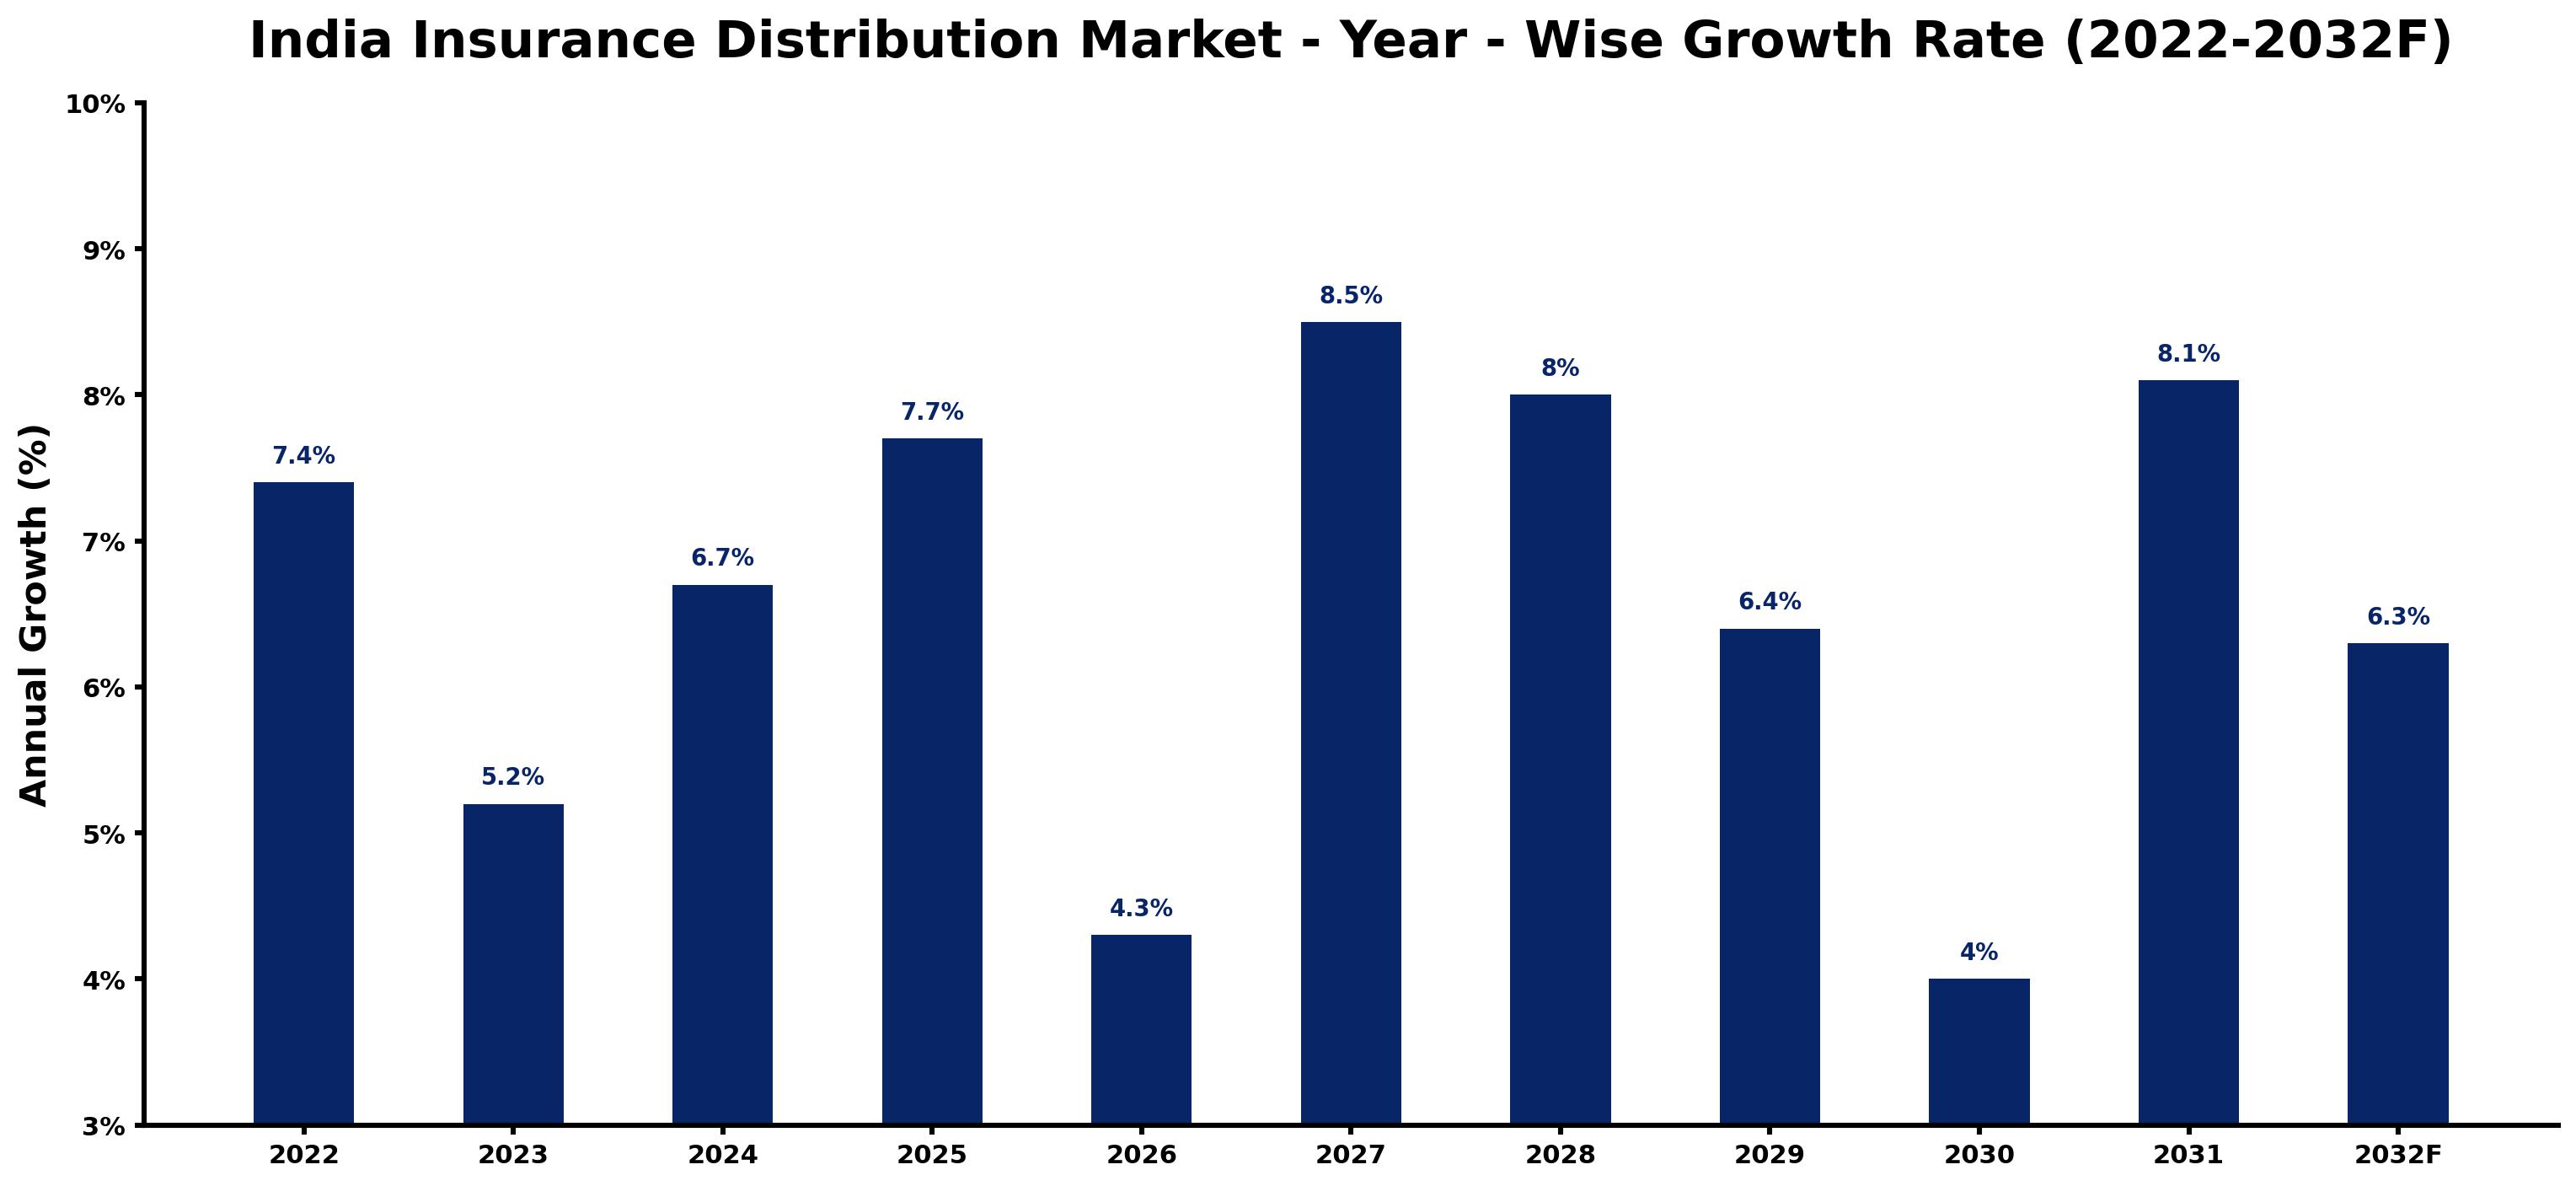
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 7.4 | The market experienced steady demand from urban consumers seeking financial security through insurance. |
| 2023 | 5.2 | Growth slowed as the market adjusted to regulatory changes affecting distribution channels. |
| 2024 | 6.7 | Increased adoption of digital platforms drove faster growth as consumers preferred online purchasing. |
| 2025 | 7.7 | The market saw a surge in life insurance purchases, reflecting heightened financial planning awareness. |
| 2026 | 4.3 | Growth slowed due to market saturation in urban areas, impacting new customer acquisition. |
| 2027 | 8.5 | A revival in demand occurred as innovative insurance products attracted more consumers. |
| 2028 | 8.0 | Growth moderated as competition intensified among digital insurance providers in urban markets. |
| 2029 | 6.4 | The market continued to grow, driven by increasing awareness of health insurance needs. |
| 2030 | 4.0 | Growth slowed as economic factors led to cautious spending on insurance products. |
| 2031 | 8.1 | Demand surged again as new initiatives improved access to insurance for underserved populations. |
| 2032 | 6.3 | Growth slowed as market maturity set in, stabilising demand across various segments. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Insurance Distribution Market Synopsis
Insurance Distribution in India includes various methods and channels for selling insurance products, such as agencies, banks, and online platforms. Rising demand from urban populations and the increasing use of digital platforms fuel the growth of the Insurance Distribution Market. With an urban population estimated at 470 million in 2023, insurance purchases are heavily influenced by this demographic. Initiatives like the Digital India programme are promoting online insurance services, further accelerating market expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing urban population drives demand for insurance products. | Driver | High | General Public |
| Growing preference for digital platforms enhances distribution efficiency. | Driver | High | Digital |
| Rising health insurance needs create opportunities for tailored products. | Opportunity | High | Health Insurance |
| Expanding insurance awareness among SMEs opens new market segments. | Opportunity | Medium | SMEs |
| Regulatory challenges hinder the speed of market expansion. | Restraint | High | Agency-Based |
| Market saturation in urban areas limits growth potential. | Restraint | Medium | Direct Online |
| The Insurance Distribution market in India faces intense competition among providers. | Challenge | High | Broker Channel |
| Technological barriers may slow the adoption of digital insurance services. | Challenge | Medium | Hybrid |
Evaluation of Drivers in India Insurance Distribution Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing urban population increases the need for insurance products. | General Public | With approximately 470 million urban residents in India, demand for financial security drives insurance purchases. |
| Rising digital adoption expands distribution channels. | Digital | The Digital India initiative promotes online insurance services, leading to a projected 39% share in technology mode by 2025. |
| Health insurance demand rises due to increasing healthcare costs. | Health Insurance | The health insurance market was valued at approximately $20 billion in 2021, prompting insurers to develop new products. |
| Increased awareness of financial planning boosts life insurance sales. | Life Insurance | The life insurance penetration rate in India was 3.2% in 2022, indicating a growing market for personal insurance. |
| SMEs seeking tailored insurance solutions expand the market. | SMEs | The focus on providing customized insurance products for SMEs is expected to drive growth in this segment. |
The Insurance Distribution market in India is expanding due to increasing end-use demand, the rise of digital platforms, and heightened awareness of financial products. The health insurance market, valued at approximately $20 billion in 2021, has prompted insurers to innovate and create new offerings. Urban consumers are showing a clear preference for digital platforms when purchasing insurance, indicating a shift in buying habits. As the urban population is projected to reach 470 million by 2023, the demand for insurance products is expected to increase, encouraging providers to refine their offerings.
Evaluation of Restraints in India Insurance Distribution Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory challenges slow down the expansion of distribution channels. | Agency-Based | The Insurance Regulatory and Development Authority of India oversees compliance, which can delay market entry for new players. |
| Market saturation limits growth potential in urban areas. | Direct Online | As urban consumers become more insurance-savvy, acquiring new customers becomes increasingly challenging. |
| Intense competition among providers compresses margins. | Broker Channel | With over 50 registered insurance companies, competition drives down prices, affecting profitability. |
| Technological barriers hinder the adoption of digital services. | Hybrid | Some consumers remain hesitant to transition to digital platforms, impacting overall market growth. |
| Lack of awareness among rural populations restricts market reach. | Health Insurance | Despite initiatives, many rural consumers remain unaware of available health insurance options. |
India Insurance Distribution Market Challenges
Producers in the India Insurance Distribution Market face technological challenges, as many agents lack access to modern digital tools, limiting their efficiency and sales potential. This issue arises from the slow adoption of digital platforms, resulting in missed opportunities for over 2 million agents. Distributors also contend with supply chain issues stemming from regulatory delays in product approvals, which impede timely launches of new offerings and frustrate buyers seeking immediate coverage. Rising operational costs place additional burdens on consumers, as the health insurance market, valued at approximately $20 billion, experiences increasing premiums that restrict affordability for many individuals.
Trends in the India Insurance Distribution Market
The trends below show where the India Insurance Distribution Market is heading.
- Shift to Digital Insurance Services: Consumers are increasingly choosing digital insurance services, driven by the Digital India initiative that promotes online platforms. This trend is expected to capture a 39% share in technology mode by 2025.
- Growing Demand for Health Insurance: Health insurance is becoming more popular due to rising healthcare costs, with the market valued at approximately $20 billion in 2021. This shift reflects a growing awareness of health risks among consumers.
- Increased Focus on SMEs: SMEs are emerging as a key target for insurance providers, as tailored solutions are being developed to meet their specific needs. This trend is projected to drive growth in the SME segment, expected to grow at a CAGR of 9.0%.
- Expansion of Life Insurance Offerings: Life insurance products are diversifying to cater to various demographics, particularly younger consumers. The average age of policyholders is around 30 years, indicating a shift towards a younger audience.
Investment Opportunities in the India Insurance Distribution Market
The following opportunities in the India Insurance Distribution Market pair current demand with a clear way in.
- Supply of Tailored Health Insurance Products: The health insurance market presents opportunities for tailored products, valued at approximately $20 billion in 2021. Insurers can focus on urban populations requiring comprehensive coverage.
- Investment in Digital Platforms: The increasing emphasis on SMEs creates opportunities for tailored insurance solutions. Investing in this segment is timely, as SMEs are projected to experience significant growth.
- Expansion of Life Insurance Coverage: The life insurance segment, projected to account for a 41% share in 2025, offers opportunities for new products. Insurers can target young consumers with creative offerings.
- Development of Customized Insurance Solutions: The demand for customised insurance solutions is on the rise, particularly among SMEs. Insurers can capitalise on this trend to develop products that address specific business needs.
Government Initiatives in the India Insurance Distribution Market
In 2023, the Insurance Regulatory and Development Authority of India (IRDAI) introduced new guidelines for licensing insurance brokers, streamlining the process and improving market access. This initiative builds on the Insurance Act of 1938, which regulates the insurance industry, ensuring that distribution channels operate efficiently and meet modern standards. The new framework aims to enhance service delivery and increase competition among brokers, ultimately benefiting consumers.
The Pradhan Mantri Jeevan Jyoti Bima Yojana provides life insurance coverage to underprivileged populations, ensuring that low-income families can access financial security. Administered by the Ministry of Finance, this scheme oversees various insurance initiatives. In 2023, the government allocated $1 billion for health insurance schemes under the National Health Mission, further supporting the expansion of insurance coverage among vulnerable populations.
Future Insight of the India Insurance Distribution Market
The India Insurance Distribution Market is set for transformative changes by 2032, driven by the government's commitment to 100% digital insurance services. This shift will allow buyers to easily access products through online platforms, improving their purchasing experience. The National Health Authority's Ayushman Bharat scheme will broaden health coverage for low-income families, enhancing access to essential services. Additionally, the Micro Insurance Regulation will facilitate better access for underserved populations, creating new opportunities for suppliers to connect with a wider customer base.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Channel Type – Direct Online Dominated and Is Expected to Record the Fastest Growth
According to Shubham Deep, Research Manager at 6Wresearch, Direct Online accounted for a 45% market share by channel type in 2025. Direct online channels command a substantial market share in India due to the growing preference for the convenience of online purchasing. The Digital India initiative plays a crucial role in facilitating access to insurance products, particularly among the urban population. Direct Online is also forecast to expand faster than any other category, at a CAGR of 8.6% over 2026–2032. The direct online segment will continue to experience rapid growth as more consumers embrace digital platforms for their insurance needs. With the government's ambition for 100% digital insurance services by 2025, this segment's lead is likely to expand further. Suppliers must refine their online strategies to effectively engage the expanding consumer base seeking digital insurance solutions.
By Product Type – Life Insurance Dominated, Health Insurance Expected to Grow Fastest
Life Insurance took a 41% share of product type in 2025, more than any other category. Life insurance maintains the largest market share as it is vital for financial planning and security among individuals. The impressive average claim settlement ratio of 97% in 2022 reinforces consumer confidence in life insurance products. Health Insurance is projected to grow fastest, at a CAGR of 8.6% during 2026–2032. Health insurance is witnessing the fastest growth, primarily due to rising healthcare costs that prompt individuals to seek comprehensive coverage. The government's allocation of $1 billion for health insurance schemes under the National Health Mission underscores the increasing importance of this product type. Suppliers should focus on expanding health insurance offerings to effectively address the rising demand driven by healthcare concerns.
By Customer Segment – Individual Dominated, SMEs Expected to Grow Fastest
In 2025, Individual led the customer segment split with a 41% share. The individual customer segment represents the largest share due to the widespread personal insurance needs among the population. This segment's growth is supported by the increasing awareness of the importance of insurance for financial security. Over 2026–2032, SMEs are expected to post the fastest growth, at a CAGR of 9.0%. SMEs are emerging as the fastest-growing segment, with a rising focus on tailored insurance solutions that address their specific needs. This trend highlights the potential for suppliers to develop customised offerings for this market. Suppliers should consider developing specialised products and services that cater to the unique requirements of SMEs.
By Technology Mode – Digital Dominated, Hybrid Expected to Grow Fastest
With a 39% revenue share in 2025, Digital was the largest technology mode category. Digital technology is the predominant mode in the insurance distribution market, reflecting the increasing adoption of technology among consumers. This trend is highlighted by the surge in online transactions, which enhance efficiency and accessibility for users. Hybrid is set to record the highest CAGR in this split, 8.9% over 2026–2032. The hybrid technology mode is rapidly gaining traction as it effectively combines traditional and digital methods, appealing to a broader audience. This growth suggests that suppliers can benefit from integrating both approaches to cater to diverse customer preferences. Suppliers should invest in hybrid solutions to effectively reach and serve a wider range of customers in the evolving market.
By End User – General Public Dominated, Enterprises Expected to Grow Fastest
General Public held a 40% share of the India Insurance Distribution Market by end user in 2025. The general public constitutes the largest share of insurance purchases, driven by a heightened demand for personal insurance products. This segment's growth is bolstered by increasing awareness of the importance of insurance in everyday life. The quickest growth will come from Enterprises, forecast to expand at a CAGR of 8.8% between 2026 and 2032. Enterprises are emerging as the fastest-growing end user segment as they increasingly seek comprehensive insurance packages to manage risks effectively. This trend presents a significant market opportunity for suppliers to address the evolving needs of businesses. Suppliers should tailor their offerings to better serve the enterprise segment, capitalising on the growing demand for comprehensive coverage solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Insurance Distribution Market Outlook
- Market Size of India Insurance Distribution Market, 2025
- Forecast of India Insurance Distribution Market, 2032
- Historical Data and Forecast of India Insurance Distribution Revenues & Volume for the Period 2022 - 2032F
- India Insurance Distribution Market Trend Evolution
- India Insurance Distribution Market Drivers and Challenges
- India Insurance Distribution Price Trends
- India Insurance Distribution Porter's Five Forces
- India Insurance Distribution Industry Life Cycle
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Channel Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Agency-Based for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Bancassurance for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Direct Online for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Broker Channel for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Product Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Life Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Health Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Auto/Home Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Travel/Property Insurance for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Customer Segment for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Individual for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Corporate for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Retail Customers for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By SMEs for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Technology Mode for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Manual for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Assisted Digital for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Digital for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Hybrid for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By General Public for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By Enterprises for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By E-Commerce Users for the Period 2022 - 2032F
- Historical Data and Forecast of India Insurance Distribution Market Revenues & Volume By SMEs for the Period 2022 - 2032F
- India Insurance Distribution Import Export Trade Statistics
- Market Opportunity Assessment By Channel Type
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Customer Segment
- Market Opportunity Assessment By Technology Mode
- Market Opportunity Assessment By End User
- India Insurance Distribution Top Companies Market Share
- India Insurance Distribution Competitive Benchmarking By Technical and Operational Parameters
- India Insurance Distribution Company Profiles
- India Insurance Distribution Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Channel Type
- Agency-Based
- Bancassurance
- Direct Online
- Broker Channel
By Product Type
- Life Insurance
- Health Insurance
- Auto/Home Insurance
- Travel/Property Insurance
By Customer Segment
- Individual
- Corporate
- Retail Customers
- SMEs
By Technology Mode
- Manual
- Assisted Digital
- Digital
- Hybrid
By End User
- General Public
- Enterprises
- E-Commerce Users
- SMEs































