India Semiconductor Chemicals Market Size & Growth Rate
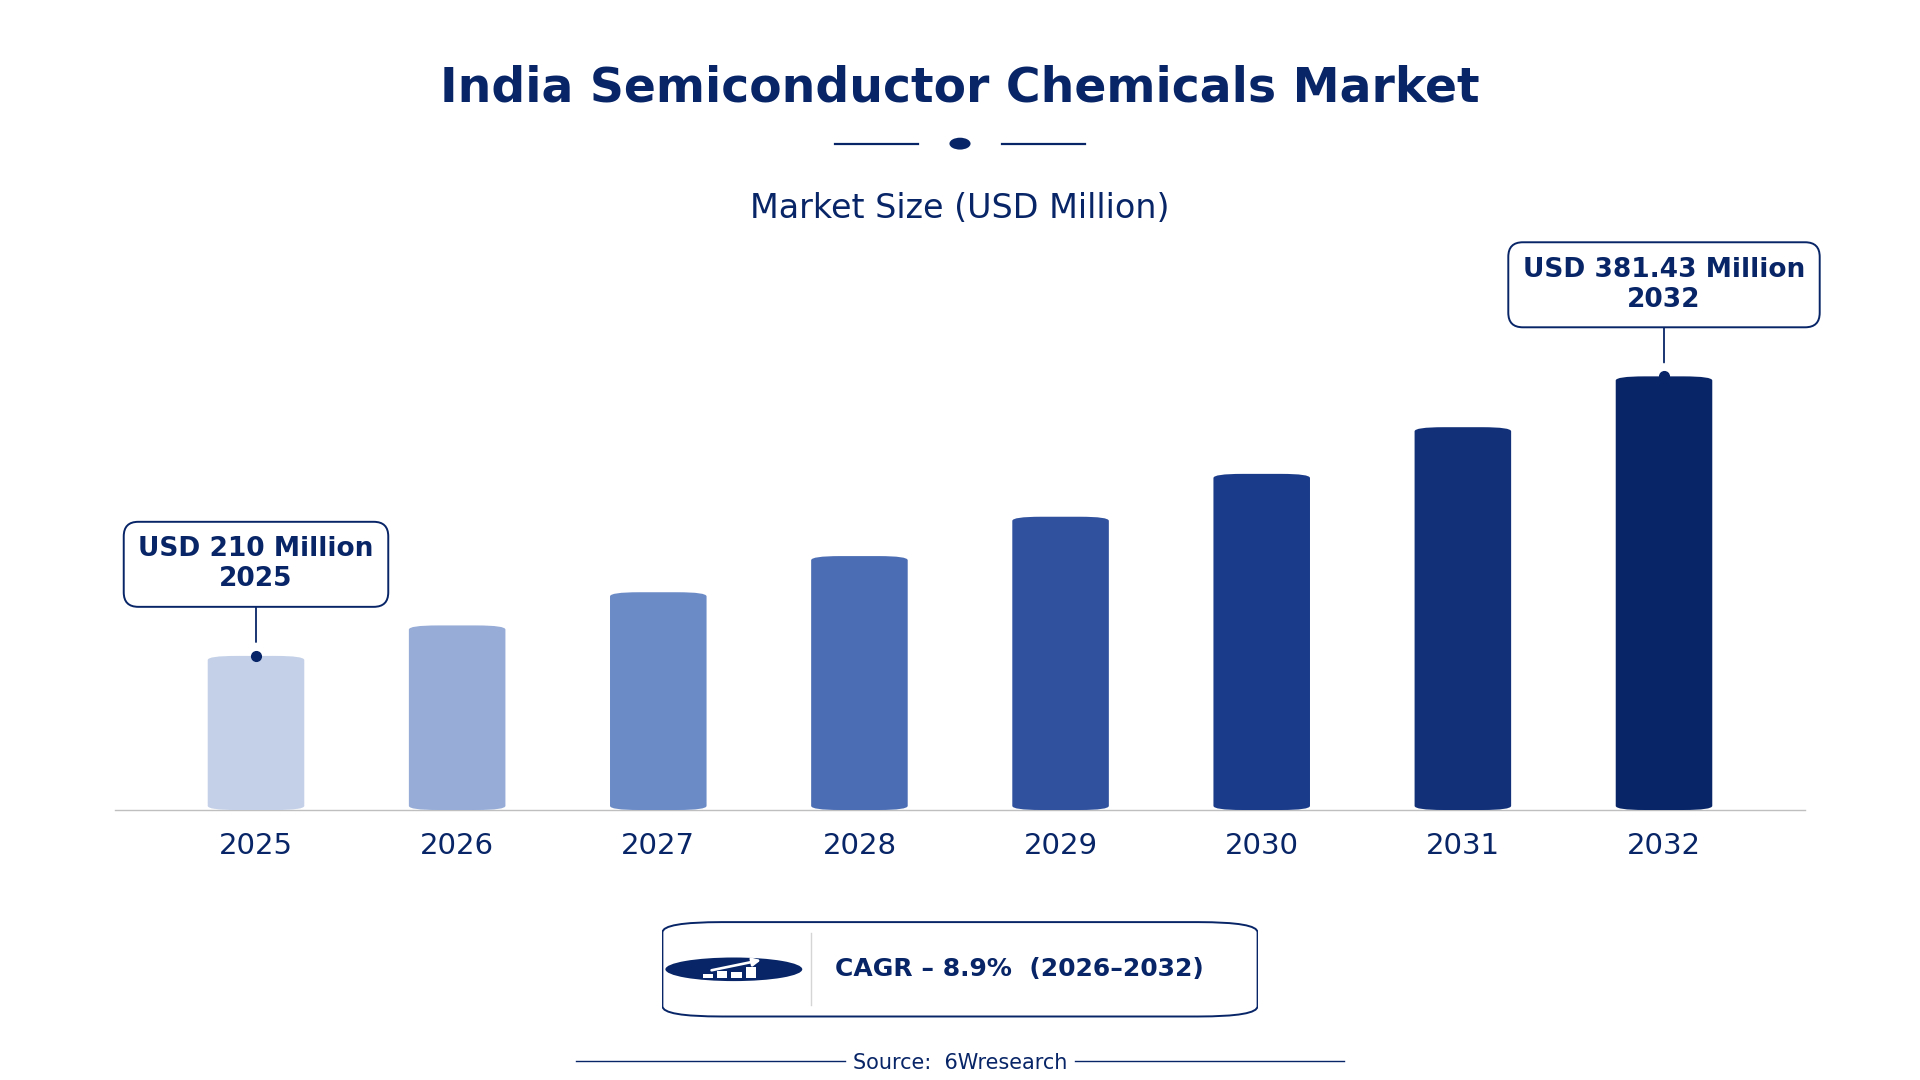
According to 6Wresearch internal database and industry insights, the India Semiconductor Chemicals Market was valued at USD 210.0 million in 2025 and is projected to reach USD 381.43 million by 2032, growing at a CAGR of approximately 8.9% during 2026–2032.
India Semiconductor Chemicals Market Highlights
| Report Metric | Details |
| Report Name | India Semiconductor Chemicals Market |
| Market Size 2025 | USD 210.0 million |
| Market Size 2032 | USD 381.43 million |
| Absolute Growth 2025–2032 | USD 171.43 million |
| CAGR 2026–2032 | 8.9% |
| Peak Annual Growth | 10.6% in 2029 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Chemical Type, 2025 | Etchants (40% share) |
| Leading Process Stage, 2025 | Lithography (41% share) |
| Leading Purity Level, 2025 | Ultra-High Purity (46% share) |
| Leading End User, 2025 | Semiconductor Fabs (37% share) |
| Fastest-Growing Chemical Type | Photoresists (10.0% CAGR) |
| Fastest-Growing Process Stage | Doping/Implantation (10.8% CAGR) |
| Fastest-Growing Purity Level | Ultra-Low Metal (10.3% CAGR) |
| Fastest-Growing End User | Wafer Manufacturers (11.3% CAGR) |
| Growing Sector | Wafer Manufacturers |
| Key End Users | Semiconductor Fabs, Chip Foundries, Fab Facilities, Wafer Manufacturers |
India Semiconductor Chemicals Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
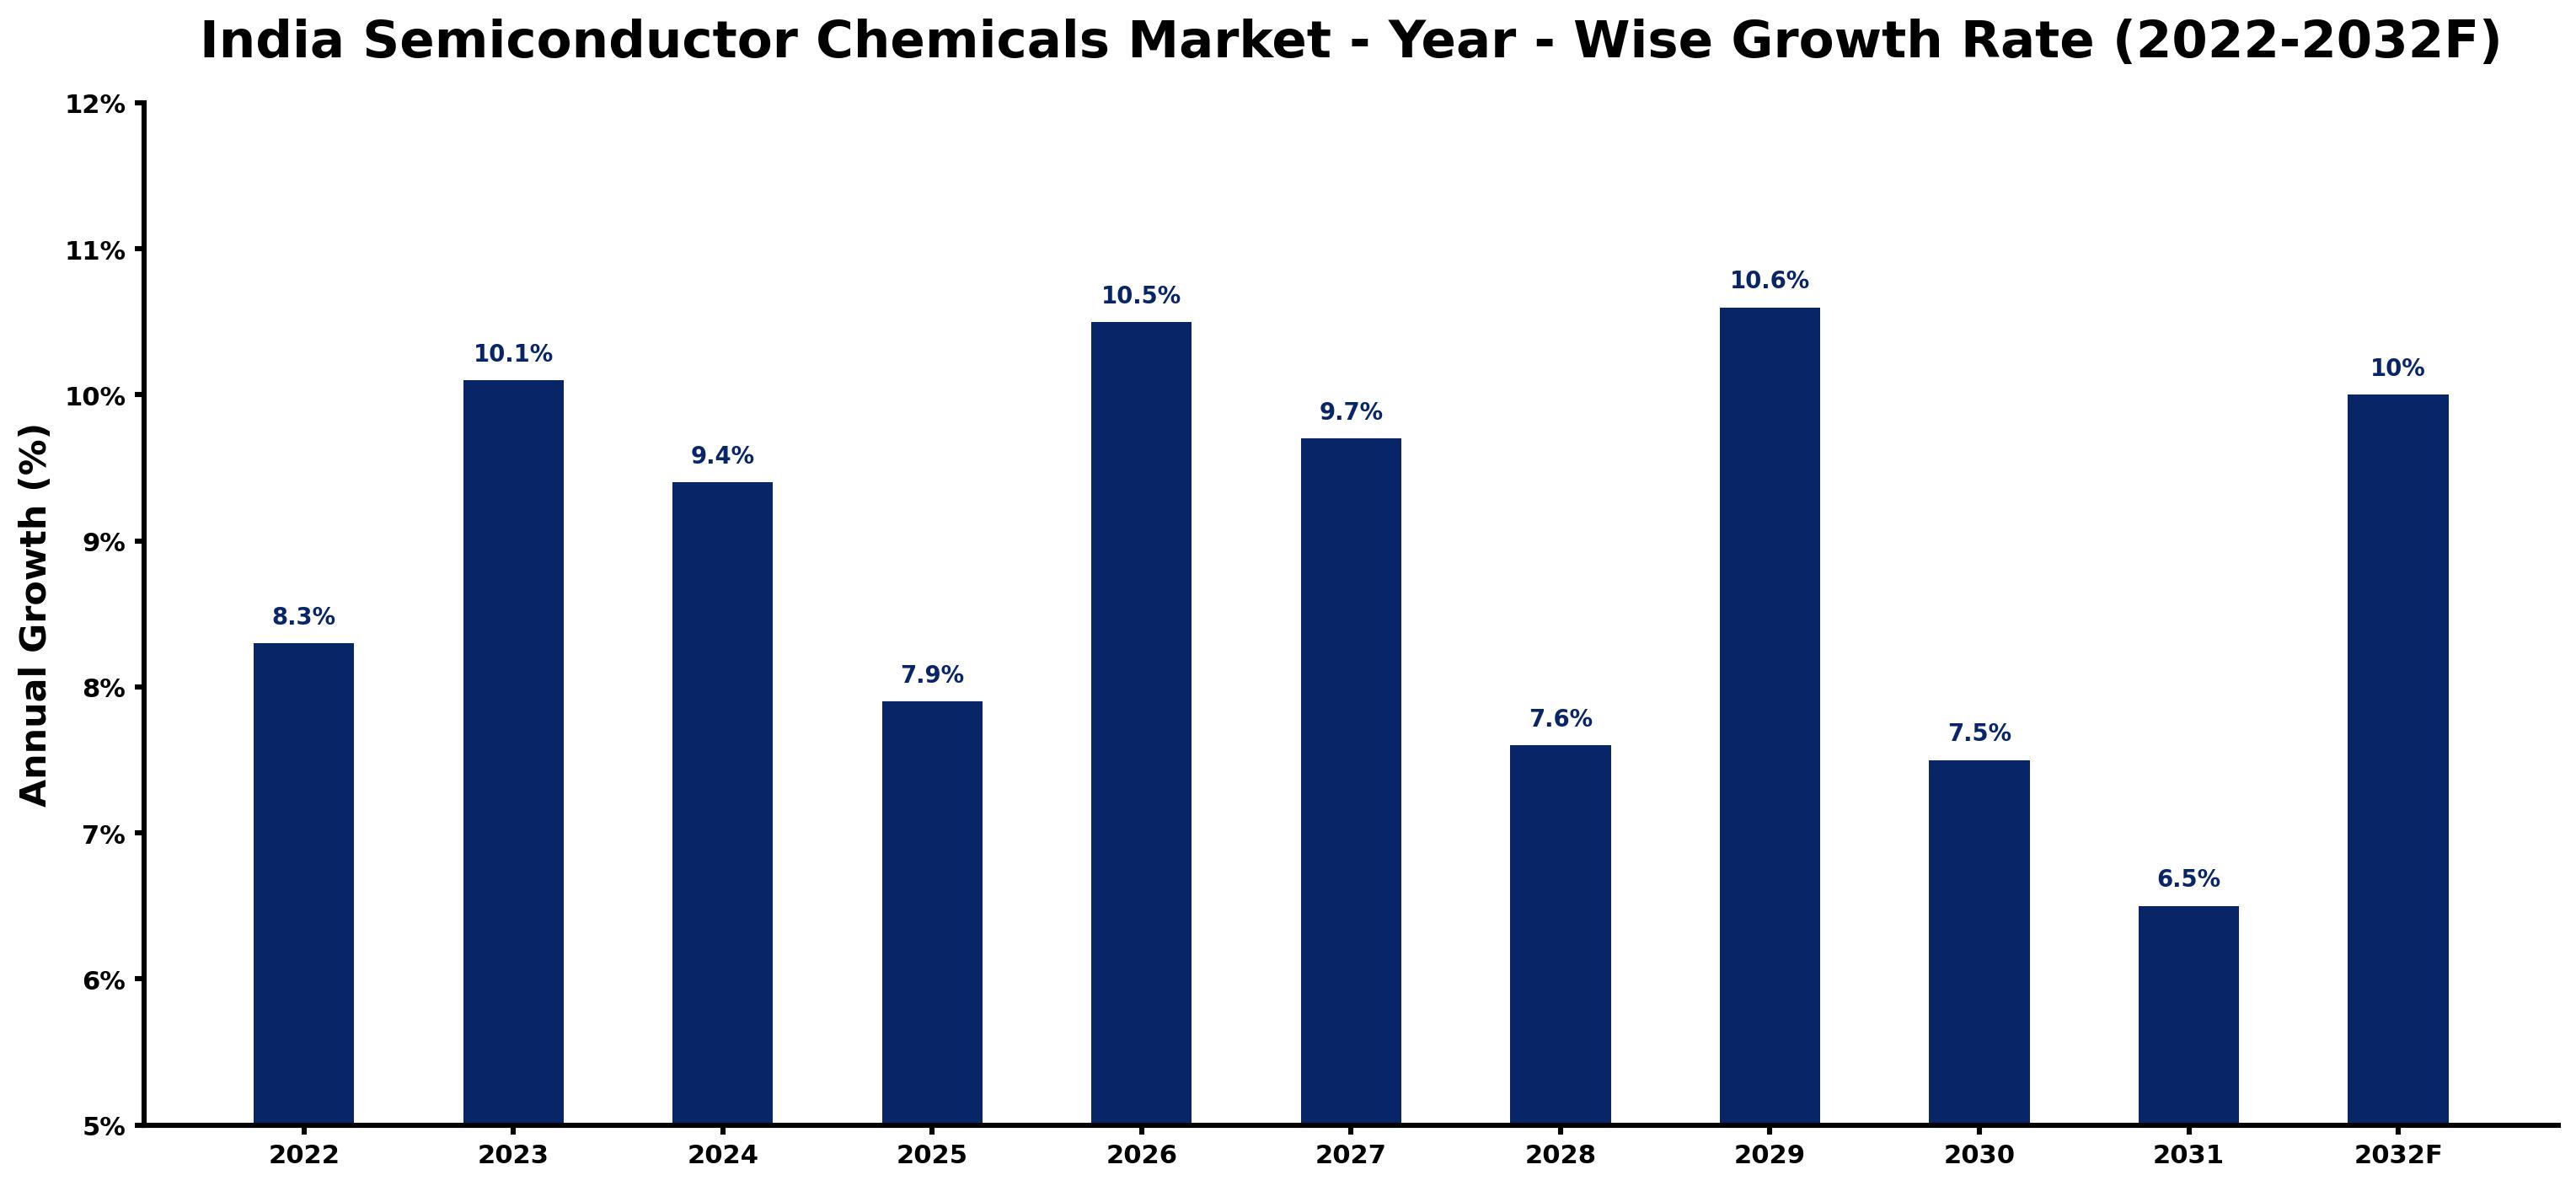
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.3 | The market showed steady growth due to increasing domestic semiconductor demand. |
| 2023 | 10.1 | Growth accelerated as investments in semiconductor fabs rose sharply. |
| 2024 | 9.4 | A slight slowdown occurred as the Semiconductor Mission began to influence the market. |
| 2025 | 7.9 | Continued investments in technology led to further growth, albeit at a slower pace. |
| 2026 | 10.5 | Growth is expected to rebound as new semiconductor initiatives take effect. |
| 2027 | 9.7 | A slowdown is projected as the market adjusts to previous high growth rates. |
| 2028 | 7.6 | Market growth is anticipated to slow further as demand stabilises in the semiconductor sector. |
| 2029 | 10.6 | A resurgence in growth is expected due to heightened investments in semiconductor technology. |
| 2030 | 7.5 | Growth will decelerate as the market adjusts to the peak growth period. |
| 2031 | 6.5 | A further slowdown is projected as the market stabilises after previous peaks. |
| 2032 | 10.0 | Growth is expected to rise again as new semiconductor projects come online. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Semiconductor Chemicals Market Synopsis
The Semiconductor Chemicals Market in India encompasses specialized materials essential for semiconductor device fabrication. These chemicals, produced through precise processes, are used for etching, doping, and cleaning in semiconductor manufacturing. The market is expanding due to rising domestic demand and substantial investments, with the Semiconductor Mission aiming to attract $10 billion by 2025 and the Electronics Policy targeting a $300 billion electronics manufacturing ecosystem by 2025. Key buyer groups include semiconductor fabs and chip foundries, which are driving the demand for these chemicals.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing domestic semiconductor production capacity | Driver | High | Semiconductor Fabs |
| Growing demand for advanced semiconductor technologies | Driver | High | Photoresists |
| Investment opportunities in semiconductor manufacturing | Opportunity | High | Fab Facilities |
| Expansion of semiconductor research initiatives | Opportunity | Medium | Etchants |
| High initial investment costs for semiconductor fabs | Restraint | High | Semiconductor Fabs |
| Limited availability of skilled semiconductor engineers | Restraint | Medium | Semiconductor Fabs |
| Competition from established semiconductor markets | Challenge | High | Chip Foundries |
| Technological advancements requiring constant adaptation | Challenge | Medium | Wafer Manufacturers |
Evaluation of Drivers in India Semiconductor Chemicals Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising investments in semiconductor fabs | Semiconductor Fabs | The country has over 20 semiconductor fabs operational as of 2023, driving demand for chemicals. |
| Increased demand for ultra-high purity chemicals | Ultra-High Purity | The growth in semiconductor applications necessitates ultra-high purity chemicals for optimal performance. |
| Growth in the electronics manufacturing sector | Fab Facilities | The Electronics Policy 2020 targets a $300 billion electronics manufacturing sector by 2025, boosting demand for semiconductor chemicals. |
| Expansion of chip foundries | Chip Foundries | India's semiconductor consumption is expected to grow at a CAGR of 30% from 2023 to 2026, increasing demand for chemicals. |
| Technological advancements in semiconductor processes | Photoresists | The Semiconductor Research and Development Program aims to boost innovation in semiconductor technology, enhancing demand for specialized chemicals. |
Expansion of the Semiconductor Chemicals market in India is backed by rising investments in semiconductor fabs and increased demand for ultra-high purity chemicals. Semiconductor consumption is projected to grow significantly, further boosting demand.
Evaluation of Restraints in India Semiconductor Chemicals Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High initial investment costs for semiconductor fabs | Semiconductor Fabs | Establishing semiconductor fabs requires substantial capital, limiting market entry for new players. |
| Limited availability of skilled semiconductor engineers | Chip Foundries | The industry aims to produce 1 million semiconductor engineers by 2025, but current shortages hinder growth. |
| Regulatory compliance and standards adherence | Ultra-High Purity | Compliance with Bureau of Indian Standards adds complexity and cost to production processes, affecting profitability. |
| Technological advancements requiring constant adaptation | Photoresists | Rapid technological changes necessitate continuous investment in R&D, straining resources for smaller firms and delaying product launches. |
| Market competition from established semiconductor markets | Wafer Manufacturers | Established markets pose challenges for Indian manufacturers, affecting their market share and pricing strategies. |
India Semiconductor Chemicals Market Challenges
Buyers in the India Semiconductor Chemicals market encounter high costs due to limited local production, compelling them to depend on imports that can elevate prices by up to 25%. Many semiconductor fabs lack advanced manufacturing techniques, creating technology gaps and resulting in production delays that impede the ability to satisfy domestic demand. Local suppliers face tough competition from established global players, pushing them to reduce prices and risking profit margins by 15%. Regulatory hurdles, including compliance with standards from the Bureau of Indian Standards, lead to additional delays for producers, complicating the introduction of new semiconductor chemicals.
Trends in the India Semiconductor Chemicals Market
Several trends are reshaping the India Semiconductor Chemicals Market; the most important are set out below.
- Shift towards Ultra-Low Metal Chemicals: The Semiconductor Research and Development Program initiated in 2022 supports a shift towards Ultra-Low Metal chemicals, which are vital for reducing contamination in semiconductor processes. This trend is expected to enhance product quality and yield, attracting more investments.
- Transition from Traditional to Advanced Resist Grades: Since 2021, the industry has been moving towards Advanced Resist Grades in lithography, driven by the need for higher precision in chip design. This shift is projected to increase the demand for specialized photoresists, improving production efficiency.
- Emergence of Doping/Implantation Techniques: The Doping/Implantation process has gained prominence since 2023, as it is essential for enhancing the electrical properties of semiconductors. This trend reflects the industry's focus on improving device performance and reliability.
- Increase in Semiconductor Manufacturing Facilities: The Electronics Manufacturing Cluster Scheme revised in 2022 supports the establishment of new semiconductor manufacturing facilities across India. This expansion is expected to significantly boost local production capabilities and meet rising demand.
Investment Opportunities in the India Semiconductor Chemicals Market
The following opportunities in the India Semiconductor Chemicals Market pair current demand with a clear way in.
- $10 billion investment gap in semiconductor fabs: With the Semiconductor Mission targeting $10 billion by 2025, there is a considerable opportunity to invest in semiconductor fabs. Collaborating with local governments and industry stakeholders will facilitate market entry and growth.
- Partnerships with semiconductor fabs: The growing number of semiconductor fabs presents an opportunity for joint ventures and partnerships. Engaging with local fabs will strengthen supply chain integration and market presence, driving mutual growth.
- Supply of ultra-high purity chemicals: The increasing demand for ultra-high purity chemicals opens avenues for suppliers. Focusing on high-quality production standards will attract semiconductor fabs seeking reliable sources of these essential materials.
- Development of advanced resist grades: The shift towards advanced resist grades creates opportunities for manufacturers to innovate. Investing in R&D and collaborating with research institutions will enhance product offerings and meet evolving industry needs.
Government Initiatives in the India Semiconductor Chemicals Market
The Semiconductor Mission, initiated by the Ministry of Electronics and Information Technology in 2021, aims to attract $10 billion in investments for semiconductor manufacturing. This initiative complements the National Policy on Electronics 2019, which was updated in 2021 to focus on enhancing domestic manufacturing capabilities. The combination of these measures is set to significantly boost local production and innovation in the semiconductor sector, benefiting producers and buyers alike.
The Bureau of Indian Standards oversees semiconductor initiatives, including the Production-Linked Incentive Scheme for Semiconductors introduced in 2021. This scheme offers incentives to enhance local manufacturing and design capabilities, while the Semiconductor Research and Development Program initiated in 2022 aims to foster innovation in semiconductor technology and applications. These efforts are essential for increasing the competitiveness of Indian semiconductor manufacturers, providing them with the necessary support to thrive.
Future Insight of the India Semiconductor Chemicals Market
The India Semiconductor Chemicals market will undergo transformative changes by 2032, driven by the Semiconductor Mission aiming to attract $10 billion in investments. The Semiconductor Research and Development Program will promote innovation, supporting local manufacturers. A target of producing 1 million semiconductor engineers by 2025 will significantly strengthen the skilled workforce for the industry. The Electronics Policy 2020 will pave the way for a thriving electronics manufacturing ecosystem, opening new opportunities for growth in semiconductor chemicals.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Chemical Type – Etchants Dominated, Photoresists Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, with a 40% revenue share in 2025, Etchants was the largest chemical type category. Etchants hold the largest market share in India as they are essential for etching circuits on wafers, a critical step in semiconductor manufacturing. With over 20 operational semiconductor fabs, the demand for etchants remains robust due to their vital role in the production process. The quickest growth will come from Photoresists, forecast to expand at a CAGR of 10.0% between 2026 and 2032. Photoresists are experiencing the fastest growth because they are crucial for lithography in chip design, which is increasingly important as technology advances. The rising complexity of semiconductor devices drives the need for high-quality photoresists, ensuring their market share will expand rapidly. Suppliers should focus on enhancing their offerings of photoresists to capitalise on this growing demand.
By Process Stage – Lithography Dominated, Doping/Implantation Expected to Grow Fastest
Lithography took a 41% share of process stage in 2025, more than any other category. Lithography dominates the market share due to its vital role in defining circuit patterns, which is essential for the production of semiconductor devices. This process stage is fundamental to the operations of semiconductor fabs, ensuring its leading position in the industry. Doping/Implantation is projected to grow fastest, at a CAGR of 10.8% during 2026–2032. Doping/Implantation is the fastest-growing segment as it is key for semiconductor functionality, particularly with the increasing complexity of chips. As manufacturers strive for enhanced performance, the demand for doping materials is set to rise significantly. Buyers should prioritise sourcing high-quality doping materials to meet the evolving requirements of semiconductor functionality.
By Purity Level – Ultra-High Purity Dominated, Ultra-Low Metal Expected to Grow Fastest
Ultra-High Purity held a 46% share of the India Semiconductor Chemicals Market by purity level in 2025. Ultra-High Purity chemicals command the largest market share as they are required for high-performance semiconductor applications, ensuring device reliability and efficiency. The stringent quality requirements in semiconductor manufacturing make ultra-high purity a necessity for producers. Over 2026–2032, Ultra-Low Metal is expected to post the fastest growth, at a CAGR of 10.3%. Ultra-Low Metal chemicals are growing rapidly due to their importance in reducing metal contamination, which is critical for maintaining the integrity of semiconductor devices. As the industry pushes for higher performance, the demand for ultra-low metal purity will likely surge. Suppliers must invest in ultra-low metal technologies to meet the increasing demand for purity in semiconductor applications.
By End User – Semiconductor Fabs Dominated, Wafer Manufacturers Expected to Grow Fastest
The largest end user category in 2025 was Semiconductor Fabs, with a 37% share of total revenue. Semiconductor Fabs represent the largest market share as they are integral to the semiconductor production process, utilising various chemicals for manufacturing. The growth of India's semiconductor industry, supported by government initiatives, solidifies the position of fabs as key players. Wafer Manufacturers are set to record the highest CAGR in this split, 11.3% over 2026–2032. Wafer Manufacturers are the fastest-growing segment because they require specialized chemicals for wafer production, which is crucial for the semiconductor supply chain. The increasing number of fabs and the push for local manufacturing will drive growth in this area. Suppliers should align their strategies to cater specifically to the needs of wafer manufacturers to leverage this growth opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Semiconductor Chemicals Market Outlook
- Market Size of India Semiconductor Chemicals Market, 2025
- Forecast of India Semiconductor Chemicals Market, 2032
- Historical Data and Forecast of India Semiconductor Chemicals Revenues & Volume for the Period 2022 - 2032F
- India Semiconductor Chemicals Market Trend Evolution
- India Semiconductor Chemicals Market Drivers and Challenges
- India Semiconductor Chemicals Price Trends
- India Semiconductor Chemicals Porter's Five Forces
- India Semiconductor Chemicals Industry Life Cycle
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Chemical Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Etchants for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Dopants for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Photoresists for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Cleaning Agents for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Process Stage for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Etching Process for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Doping/Implantation for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Lithography for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Wet Process for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Purity Level for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Ultra-High Purity for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By 99.9999%+ for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Advanced Resist Grade for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Ultra-Low Metal for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Fab Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Chip Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Wafer Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Chemicals Market Revenues & Volume By Semiconductor Fabs for the Period 2022 - 2032F
- India Semiconductor Chemicals Import Export Trade Statistics
- Market Opportunity Assessment By Chemical Type
- Market Opportunity Assessment By Process Stage
- Market Opportunity Assessment By Purity Level
- Market Opportunity Assessment By End User
- India Semiconductor Chemicals Top Companies Market Share
- India Semiconductor Chemicals Competitive Benchmarking By Technical and Operational Parameters
- India Semiconductor Chemicals Company Profiles
- India Semiconductor Chemicals Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Chemical Type
- Etchants
- Dopants
- Photoresists
- Cleaning Agents
By Process Stage
- Etching Process
- Doping/Implantation
- Lithography
- Wet Process
By Purity Level
- Ultra-High Purity
- 99.9999%+
- Advanced Resist Grade
- Ultra-Low Metal
By End User
- Fab Facilities
- Chip Foundries
- Wafer Manufacturers
- Semiconductor Fabs































