China Semiconductor Chemicals Market Size & Growth Rate
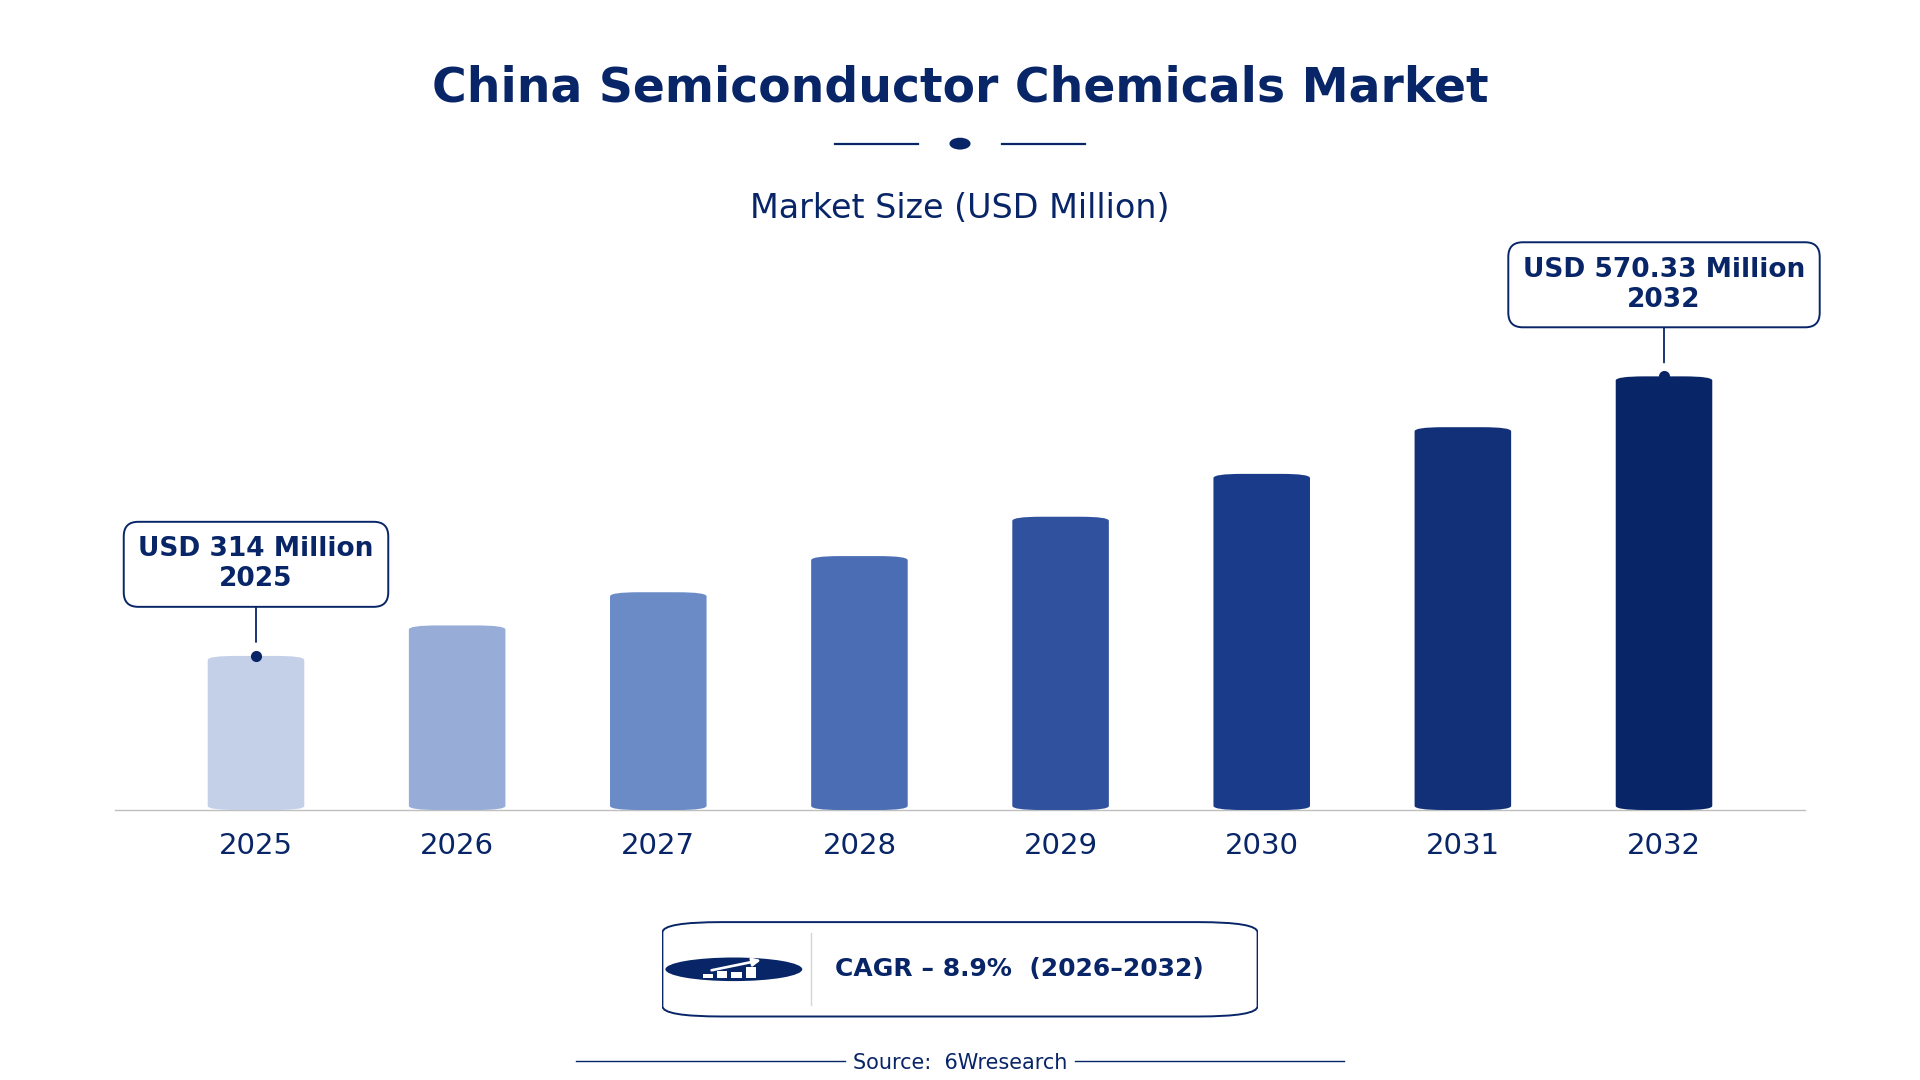
According to 6Wresearch internal database and industry insights, the China Semiconductor Chemicals Market was valued at USD 314.0 million in 2025 and is projected to reach USD 570.33 million by 2032, growing at a CAGR of approximately 8.9% during 2026–2032.
China Semiconductor Chemicals Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Chemicals Market |
| Market Size 2025 | USD 314.0 million |
| Market Size 2032 | USD 570.33 million |
| Absolute Growth 2025–2032 | USD 256.33 million |
| CAGR 2026–2032 | 8.9% |
| Peak Annual Growth | 11.4% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Chemical Type, 2025 | Photoresists (37% share) |
| Leading Process Stage, 2025 | Lithography (49% share) |
| Leading Purity Level, 2025 | Ultra-High Purity (46% share) |
| Leading End User, 2025 | Semiconductor Fabs (47% share) |
| Fastest-Growing Chemical Type | Dopants (10.3% CAGR) |
| Fastest-Growing Process Stage | Wet Process (10.1% CAGR) |
| Fastest-Growing Purity Level | Advanced Resist Grade (11.5% CAGR) |
| Fastest-Growing End User | Wafer Manufacturers (10.4% CAGR) |
| Growing Sector | Wafer Manufacturers |
| Key End Users | Semiconductor Fabs, Chip Foundries, Fab Facilities, Wafer Manufacturers |
China Semiconductor Chemicals Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
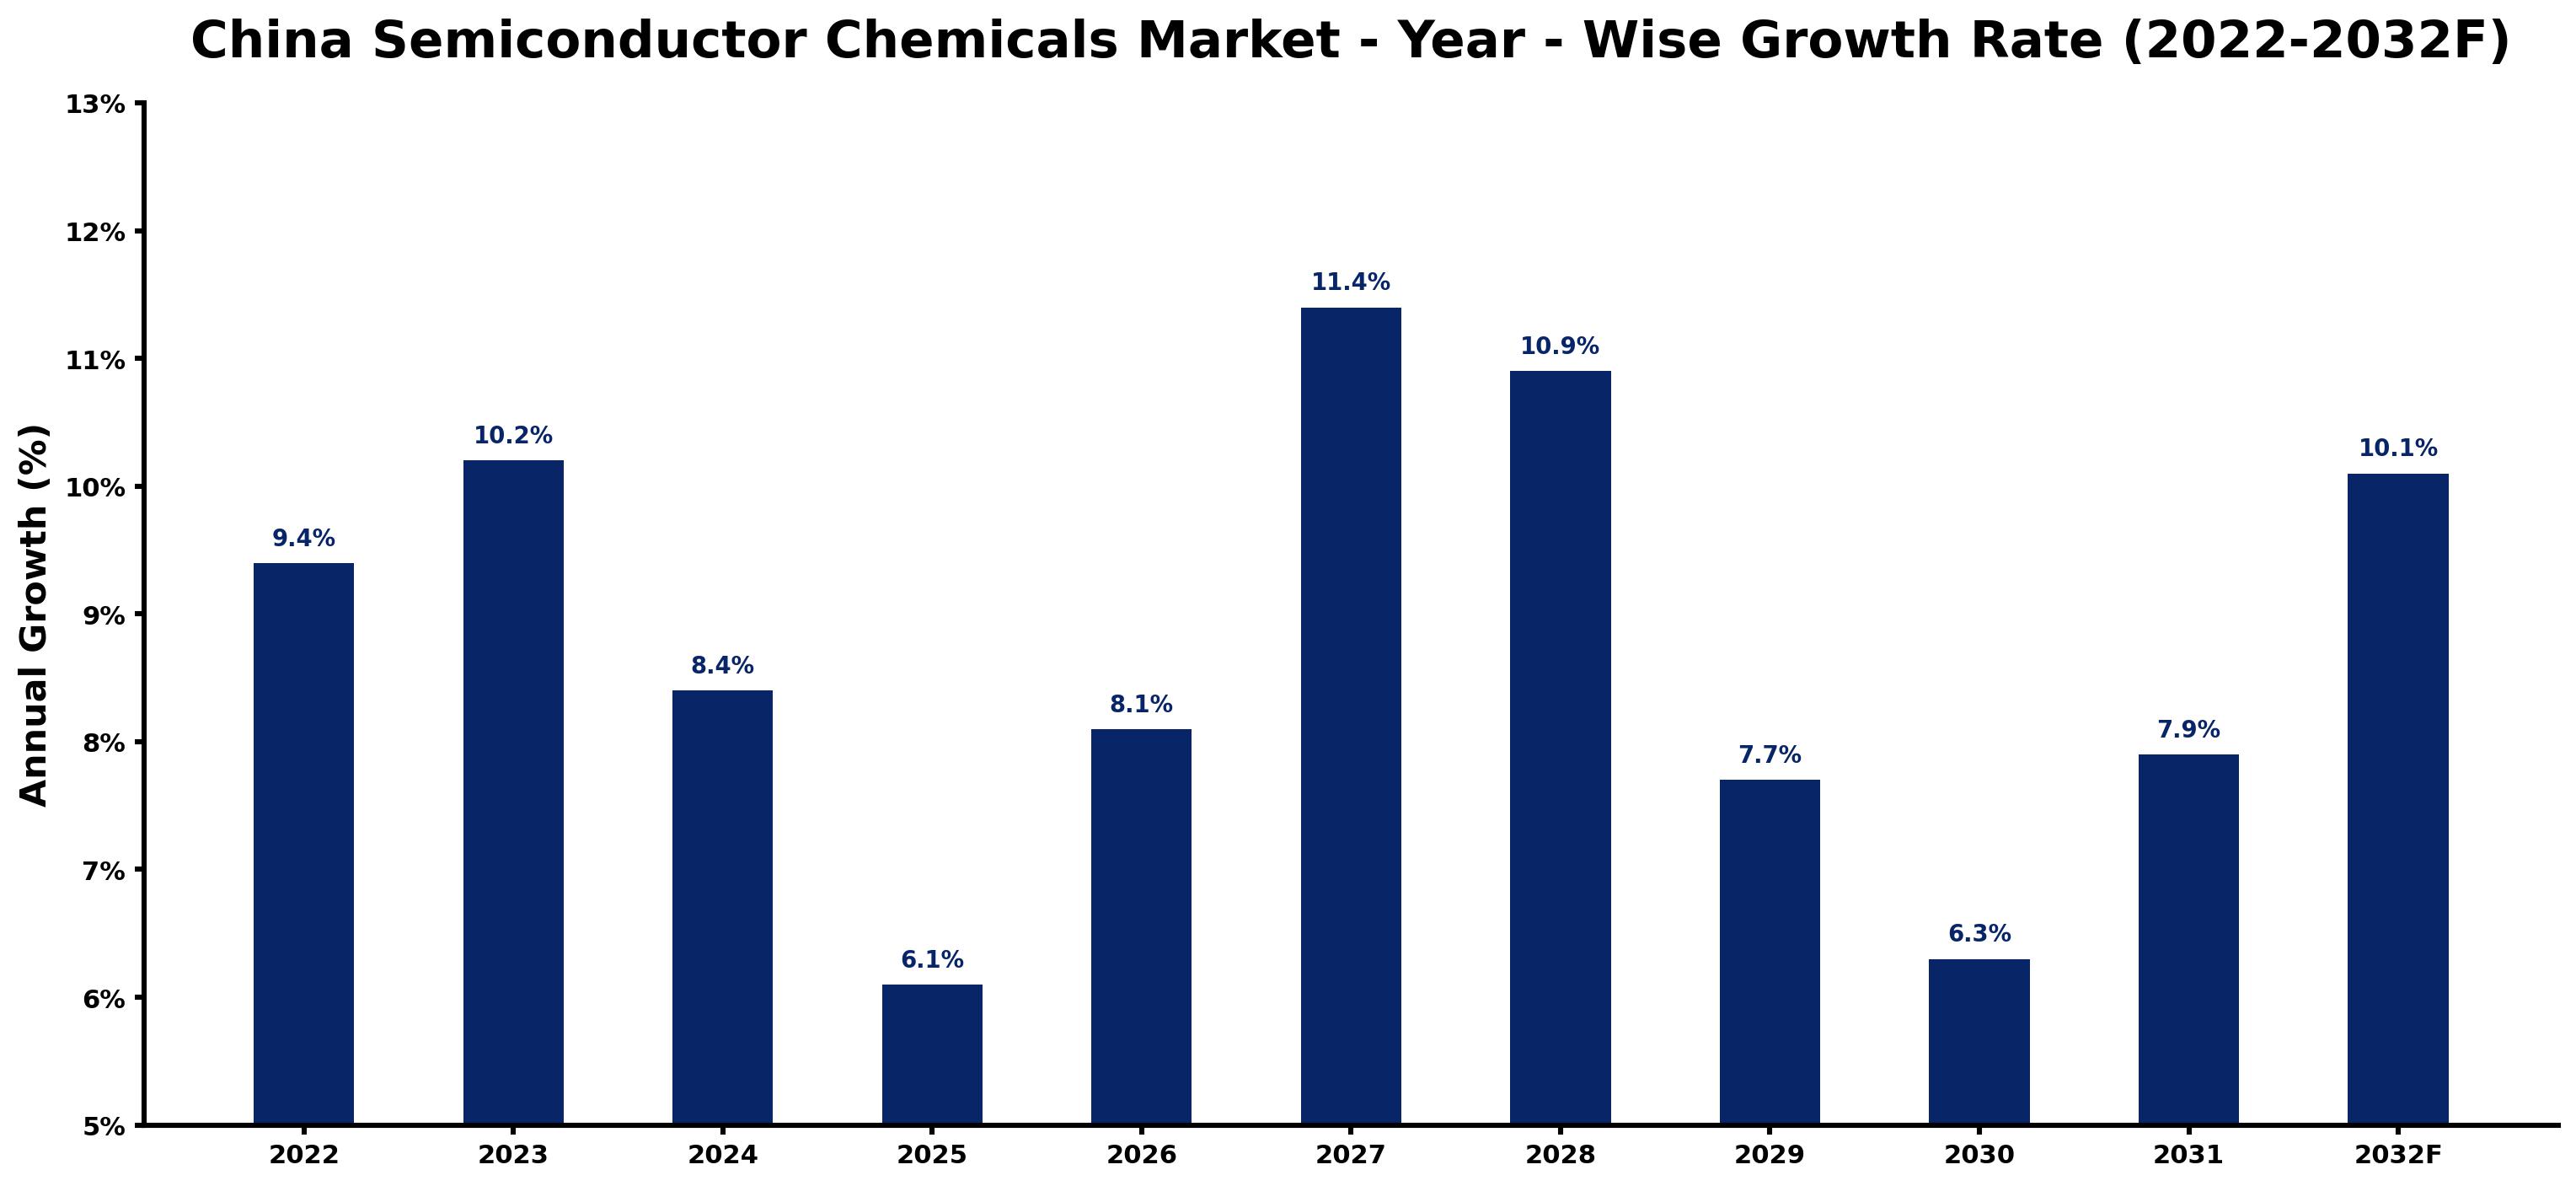
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 9.4 | The semiconductor industry in China experienced strong demand from domestic manufacturers. |
| 2023 | 10.2 | Increased investments in semiconductor technology propelled growth beyond the previous year. |
| 2024 | 8.4 | Growth slowed due to market adjustments following rapid expansion in prior years. |
| 2025 | 6.1 | The market continued to grow, albeit at a slower pace as demand stabilised. |
| 2026 | 8.1 | A resurgence in demand for semiconductor chemicals boosted growth rates. |
| 2027 | 11.4 | The peak growth rate was driven by heightened production capacities in fabs. |
| 2028 | 10.9 | Market growth slowed as the effects of previous investments began to normalise. |
| 2029 | 7.7 | Continued demand from wafer manufacturers contributed to a slower growth rate. |
| 2030 | 6.3 | Growth moderated as the market adjusted to new production levels and technologies. |
| 2031 | 7.9 | An uptick in investment in semiconductor fabs led to faster growth again. |
| 2032 | 10.1 | Growth accelerated as the industry embraced advanced technologies and standards. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Chemicals Market Synopsis
The China Semiconductor Chemicals Market includes specialised materials essential for the fabrication of semiconductor devices, which are integral to integrated circuits. These chemicals undergo complex production processes to achieve high purity and performance, primarily used in etching, doping, and cleaning applications. The market is expanding due to strong domestic demand from local manufacturers and ongoing investments in technology. In 2023, the government introduced the "14th Five-Year Plan for the Semiconductor Industry" to improve production capabilities, further driving market growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from semiconductor fabs for advanced materials | Driver | High | Semiconductor Fabs |
| Increased investments in semiconductor technology development | Driver | High | Chip Foundries |
| Rising need for Ultra-High Purity chemicals in advanced nodes | Opportunity | High | Ultra-High Purity |
| Expansion of wafer manufacturing facilities in key regions | Opportunity | High | Wafer Manufacturers |
| High costs associated with importing semiconductor chemicals | Restraint | Medium | Cleaning Agents |
| Strict regulations on chemical purity levels affecting production | Restraint | Medium | Photoresists |
| The China Semiconductor Chemicals Market faces significant supply chain disruptions | Challenge | High | Dopants |
| Limited access to advanced technologies for local manufacturers | Challenge | High | Etchants |
Evaluation of Drivers in China Semiconductor Chemicals Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased domestic production of semiconductor devices | Semiconductor Fabs | This drives demand for chemicals necessary in the fabrication process, with over 1.5 billion wafers produced in 2022. |
| Government investment in semiconductor technology | Chip Foundries | The $10 billion allocated in 2023 for technology development encourages higher purchases of semiconductor chemicals. |
| Demand for Ultra-High Purity chemicals in advanced technology nodes | Ultra-High Purity | These chemicals are essential for 5nm and below technology nodes, driving purchases from fabs. |
| Expansion of semiconductor manufacturing facilities | Wafer Manufacturers | The Beijing-Tianjin-Hebei region is a major hub, leading to increased demand for semiconductor chemicals. |
| Growing focus on R&D in semiconductor chemicals | Photoresists | The subsidy program for R&D in 2023 promotes innovation and higher consumption of these chemicals. |
Market growth for Semiconductor Chemicals in China is underpinned by rising end-use demand from semiconductor fabs, supported by the production of over 1.5 billion wafers in 2022. Increased investments in semiconductor technology, with a budget of $10 billion in 2023, stimulate higher purchases of essential materials. Demand for Ultra-High Purity chemicals is growing, particularly for advanced technology nodes, as these are critical for 5nm and below processes. The expansion of manufacturing facilities in the Beijing-Tianjin-Hebei region further boosts demand, as local fabs require more chemicals for production. The focus on R&D funding promotes innovation in semiconductor chemicals, resulting in increased consumption across the industry.
Evaluation of Restraints in China Semiconductor Chemicals Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of importing semiconductor chemicals | Cleaning Agents | In 2022, imports were valued at approximately $5 billion, impacting local production costs. |
| Strict regulations on chemical purity levels | Photoresists | Compliance with the National Standard GB/T 19500-2019 requires significant investment in testing and certification. |
| Supply chain disruptions affecting chemical availability | Dopants | These disruptions can delay production schedules for semiconductor manufacturers, impacting overall output. |
| Limited access to advanced manufacturing technologies | Etchants | This restricts local producers' ability to meet the growing demand for high-quality chemicals. |
| Increasing competition from international suppliers | Dopants | This puts pressure on local manufacturers to lower prices, affecting profit margins. |
China Semiconductor Chemicals Market Challenges
China's Semiconductor Chemicals Market faces a critical skills shortage, with over 500,000 trained professionals required to meet the demands of the sector. This gap exists due to limited educational programmes focused on semiconductor chemistry, which delays production timelines for manufacturers. Buyers encounter high costs; semiconductor chemical imports were valued at approximately $5 billion in 2022, compelling them to pay inflated prices for essential materials. Regulatory compliance with the National Standard GB/T 19500-2019 adds another layer of complexity, as these stringent regulations can extend the approval process for new chemicals, hindering suppliers' ability to innovate and deliver products promptly.
Trends in the China Semiconductor Chemicals Market
The trends below show where the China Semiconductor Chemicals Market is heading.
- Shift towards Advanced Resist Grades: China's semiconductor fabs are increasingly adopting Advanced Resist Grades for high-resolution lithography, initiated in 2023. This shift is crucial for meeting the demands of advanced technology nodes, with a projected CAGR of 11.5%.
- Transition from Traditional to Ultra-High Purity Chemicals: The demand for Ultra-High Purity chemicals is rising as fabs aim for lower contamination levels. This trend began in 2022, with Ultra-High Purity holding a 46% market share in 2025.
- Emergence of Wet Process Technologies: Wet Process technologies are gaining traction in semiconductor manufacturing, with a CAGR of 10.1% projected from 2026 to 2032. This change is driven by the need for efficient wafer processing in fabs.
- Growth in Wafer Manufacturing Facilities: The Guangdong province is expanding its wafer manufacturing capabilities, which began in 2022. This growth is expected to increase demand for semiconductor chemicals, particularly in cleaning and etching processes.
Investment Opportunities in the China Semiconductor Chemicals Market
Some of the investment opportunities in the China Semiconductor Chemicals Market are mentioned below.
- Supply of Ultra-High Purity Chemicals: The increasing demand for Ultra-High Purity chemicals presents an opportunity, particularly in the Guangdong province, where fabs require these for advanced nodes. Local partnerships can facilitate entry into this market.
- Investment in R&D for Semiconductor Chemicals: With the government's $2 billion subsidy program for R&D, there is a strong opportunity for innovation in semiconductor chemicals. Engaging with local research institutions can enhance market presence.
- Expansion of Cleaning Agents Production: As demand for cleaning agents rises, particularly in semiconductor fabs, there is an opportunity to establish production facilities in the Beijing-Tianjin-Hebei region. Collaborating with local manufacturers can ease market entry.
- Development of Advanced Resist Grades: The shift towards Advanced Resist Grades offers a chance to invest in production capabilities. Targeting semiconductor fabs in Shanghai can provide a strategic market entry point.
Government Initiatives in the China Semiconductor Chemicals Market
The semiconductor chemicals market in China is shaped by several key policies, including the "National Integrated Circuit Industry Investment Fund" approved in 2021, which allocated $29 billion to support semiconductor projects. The "Semiconductor Industry Development Action Plan (2021-2025)" launched by the Ministry of Industry and Information Technology aims to enhance local manufacturing capabilities. Additionally, the "New Infrastructure Plan" introduced by the National Development and Reform Commission in 2022 promotes semiconductor technology and infrastructure development, ensuring a conducive environment for growth.
Buyers in the semiconductor chemicals market benefit from various government initiatives. The subsidy program for R&D in semiconductor chemicals announced by the Ministry of Science and Technology in 2023 targets $2 billion in funding to support innovation. The Semiconductor Industry Association of China plays a vital role in promoting industry standards and collaboration, facilitating approvals for new products and technologies. These measures collectively enhance the capabilities of local manufacturers and improve the overall supply chain.
Future Insight of the China Semiconductor Chemicals Market
By 2032, buyers and suppliers in China's Semiconductor Chemicals Market can expect transformative changes, primarily due to the "14th Five-Year Plan for the Semiconductor Industry," which aims to enhance domestic production capabilities. The government's $10 billion investment in semiconductor technology development will streamline manufacturing processes and reduce reliance on imports. The formation of the Semiconductor Industry Association of China will encourage collaboration and establish industry standards, resulting in a more efficient supply chain. Consequently, manufacturers will likely see improved productivity and lower operational costs.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Chemical Type – Photoresists Dominated, Dopants Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Photoresists took a 37% share of chemical type in 2025, more than any other category. Photoresists hold the largest share in the China Semiconductor Chemicals Market because they are critical for defining circuit patterns on wafers. Their extensive use in major semiconductor fabs, particularly in Shanghai, highlights their importance in the manufacturing process. Dopants are projected to grow fastest, at a CAGR of 10.3% during 2026–2032. Dopants are experiencing rapid growth due to their essential role in modifying the electrical properties of semiconductors, especially in advanced technology nodes. With the government's $10 billion allocation for semiconductor technology development, the demand for dopants is expected to rise significantly. Suppliers should focus on enhancing their offerings of dopants to capitalise on this growing demand in the semiconductor chemicals market.
By Process Stage – Lithography Dominated, Wet Process Expected to Grow Fastest
With a 49% revenue share in 2025, Lithography was the largest process stage category. Lithography leads the market share as it is a key process for transferring patterns onto semiconductor wafers, which is crucial for integrated circuit fabrication. The prominence of lithography in facilities across the Beijing-Tianjin-Hebei region underscores its essential role in semiconductor manufacturing. Over 2026–2032, Wet Process is expected to post the fastest growth, at a CAGR of 10.1%. The Wet Process segment is growing rapidly due to its involvement in chemical treatments for wafer processing, which are increasingly needed for advanced manufacturing techniques. As semiconductor production scales up, the demand for wet processing chemicals is expected to surge. Buyers must ensure they have a reliable supply of wet process chemicals to meet the increasing demands of modern semiconductor fabrication.
By Purity Level – Ultra-High Purity Dominated, Advanced Resist Grade Expected to Grow Fastest
The largest purity level category in 2025 was Ultra-High Purity, with a 46% share of total revenue. Ultra-High Purity chemicals dominate the market share as they are required for minimising contamination in semiconductor manufacturing, particularly for advanced nodes. Their critical importance in maintaining the integrity of semiconductor devices makes them indispensable in the production process. The quickest growth will come from Advanced Resist Grade, forecast to expand at a CAGR of 11.5% between 2026 and 2032. Advanced Resist Grade chemicals are growing quickly due to their use in high-resolution lithography for advanced nodes, which are becoming more prevalent in the industry. The push towards smaller technology nodes will continue to drive the demand for these high-purity materials. Suppliers should prioritise the development of Advanced Resist Grade chemicals to meet the needs of an evolving semiconductor landscape.
By End User – Semiconductor Fabs Dominated, Wafer Manufacturers Expected to Grow Fastest
Semiconductor Fabs held a 47% share of the China Semiconductor Chemicals Market by end user in 2025. Semiconductor Fabs command the largest market share as they are the main facilities utilising semiconductor chemicals for integrated circuit production. The concentration of semiconductor fabs in regions like Guangdong ensures a steady demand for these essential materials. Wafer Manufacturers are set to record the highest CAGR in this split, 10.4% over 2026–2032. Wafer Manufacturers are experiencing the fastest growth as they increasingly require chemicals in the production of silicon wafers, a foundational component in semiconductor devices. The ongoing expansion of wafer manufacturing capabilities in China is a key driver of this growth. It is vital for suppliers to strengthen their relationships with wafer manufacturers to secure a foothold in this expanding segment of the semiconductor chemicals market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Chemicals Market Outlook
- Market Size of China Semiconductor Chemicals Market, 2025
- Forecast of China Semiconductor Chemicals Market, 2032
- Historical Data and Forecast of China Semiconductor Chemicals Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Chemicals Market Trend Evolution
- China Semiconductor Chemicals Market Drivers and Challenges
- China Semiconductor Chemicals Price Trends
- China Semiconductor Chemicals Porter's Five Forces
- China Semiconductor Chemicals Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Chemical Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Etchants for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Dopants for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Photoresists for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Cleaning Agents for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Process Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Etching Process for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Doping/Implantation for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Lithography for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Wet Process for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Purity Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Ultra-High Purity for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By 99.9999%+ for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Advanced Resist Grade for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Ultra-Low Metal for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Fab Facilities for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Chip Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Wafer Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Chemicals Market Revenues & Volume By Semiconductor Fabs for the Period 2022 - 2032F
- China Semiconductor Chemicals Import Export Trade Statistics
- Market Opportunity Assessment By Chemical Type
- Market Opportunity Assessment By Process Stage
- Market Opportunity Assessment By Purity Level
- Market Opportunity Assessment By End User
- China Semiconductor Chemicals Top Companies Market Share
- China Semiconductor Chemicals Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Chemicals Company Profiles
- China Semiconductor Chemicals Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Chemical Type
- Etchants
- Dopants
- Photoresists
- Cleaning Agents
By Process Stage
- Etching Process
- Doping/Implantation
- Lithography
- Wet Process
By Purity Level
- Ultra-High Purity
- 99.9999%+
- Advanced Resist Grade
- Ultra-Low Metal
By End User
- Fab Facilities
- Chip Foundries
- Wafer Manufacturers
- Semiconductor Fabs































