India Semiconductor Coating Market Size & Growth Rate
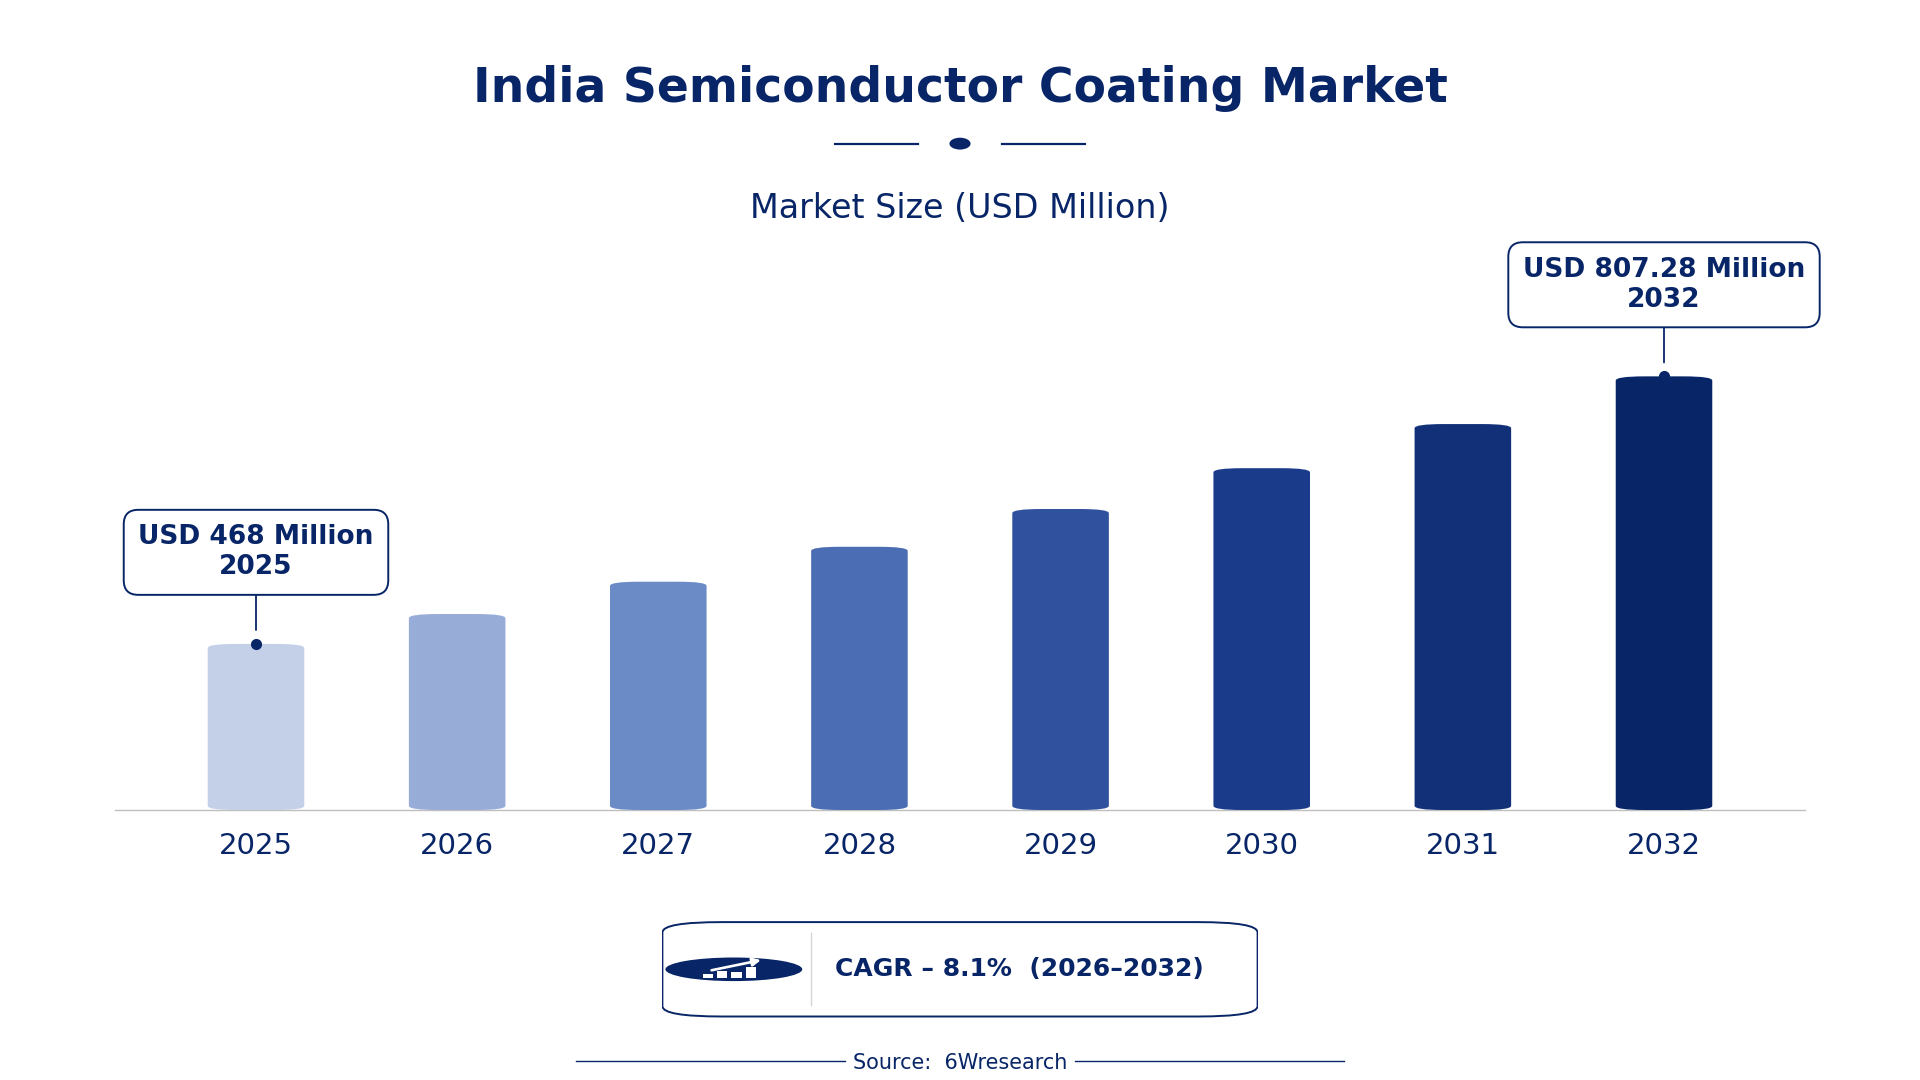
According to 6Wresearch internal database and industry insights, the India Semiconductor Coating Market was valued at USD 468.0 million in 2025 and is projected to reach USD 807.28 million by 2032, growing at a CAGR of approximately 8.1% during 2026–2032.
India Semiconductor Coating Market Highlights
| Report Metric | Details |
| Report Name | India Semiconductor Coating Market |
| Market Size 2025 | USD 468.0 million |
| Market Size 2032 | USD 807.28 million |
| Absolute Growth 2025–2032 | USD 339.28 million |
| CAGR 2026–2032 | 8.1% |
| Peak Annual Growth | 10.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Coating Type, 2025 | Anti-Reflective Coating (41% share) |
| Leading Application Stage, 2025 | Lithography (49% share) |
| Leading Method Used, 2025 | CVD (50% share) |
| Leading End User, 2025 | Foundries (39% share) |
| Fastest-Growing Coating Type | Conformal Coating (9.1% CAGR) |
| Fastest-Growing Application Stage | Final Protection Layer (10.2% CAGR) |
| Fastest-Growing End User | Device Fabricators (9.9% CAGR) |
| Growing Sector | Semiconductor Manufacturing |
| Key End Users | Foundries, Device Fabricators, IDM/Packaging Plants |
India Semiconductor Coating Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
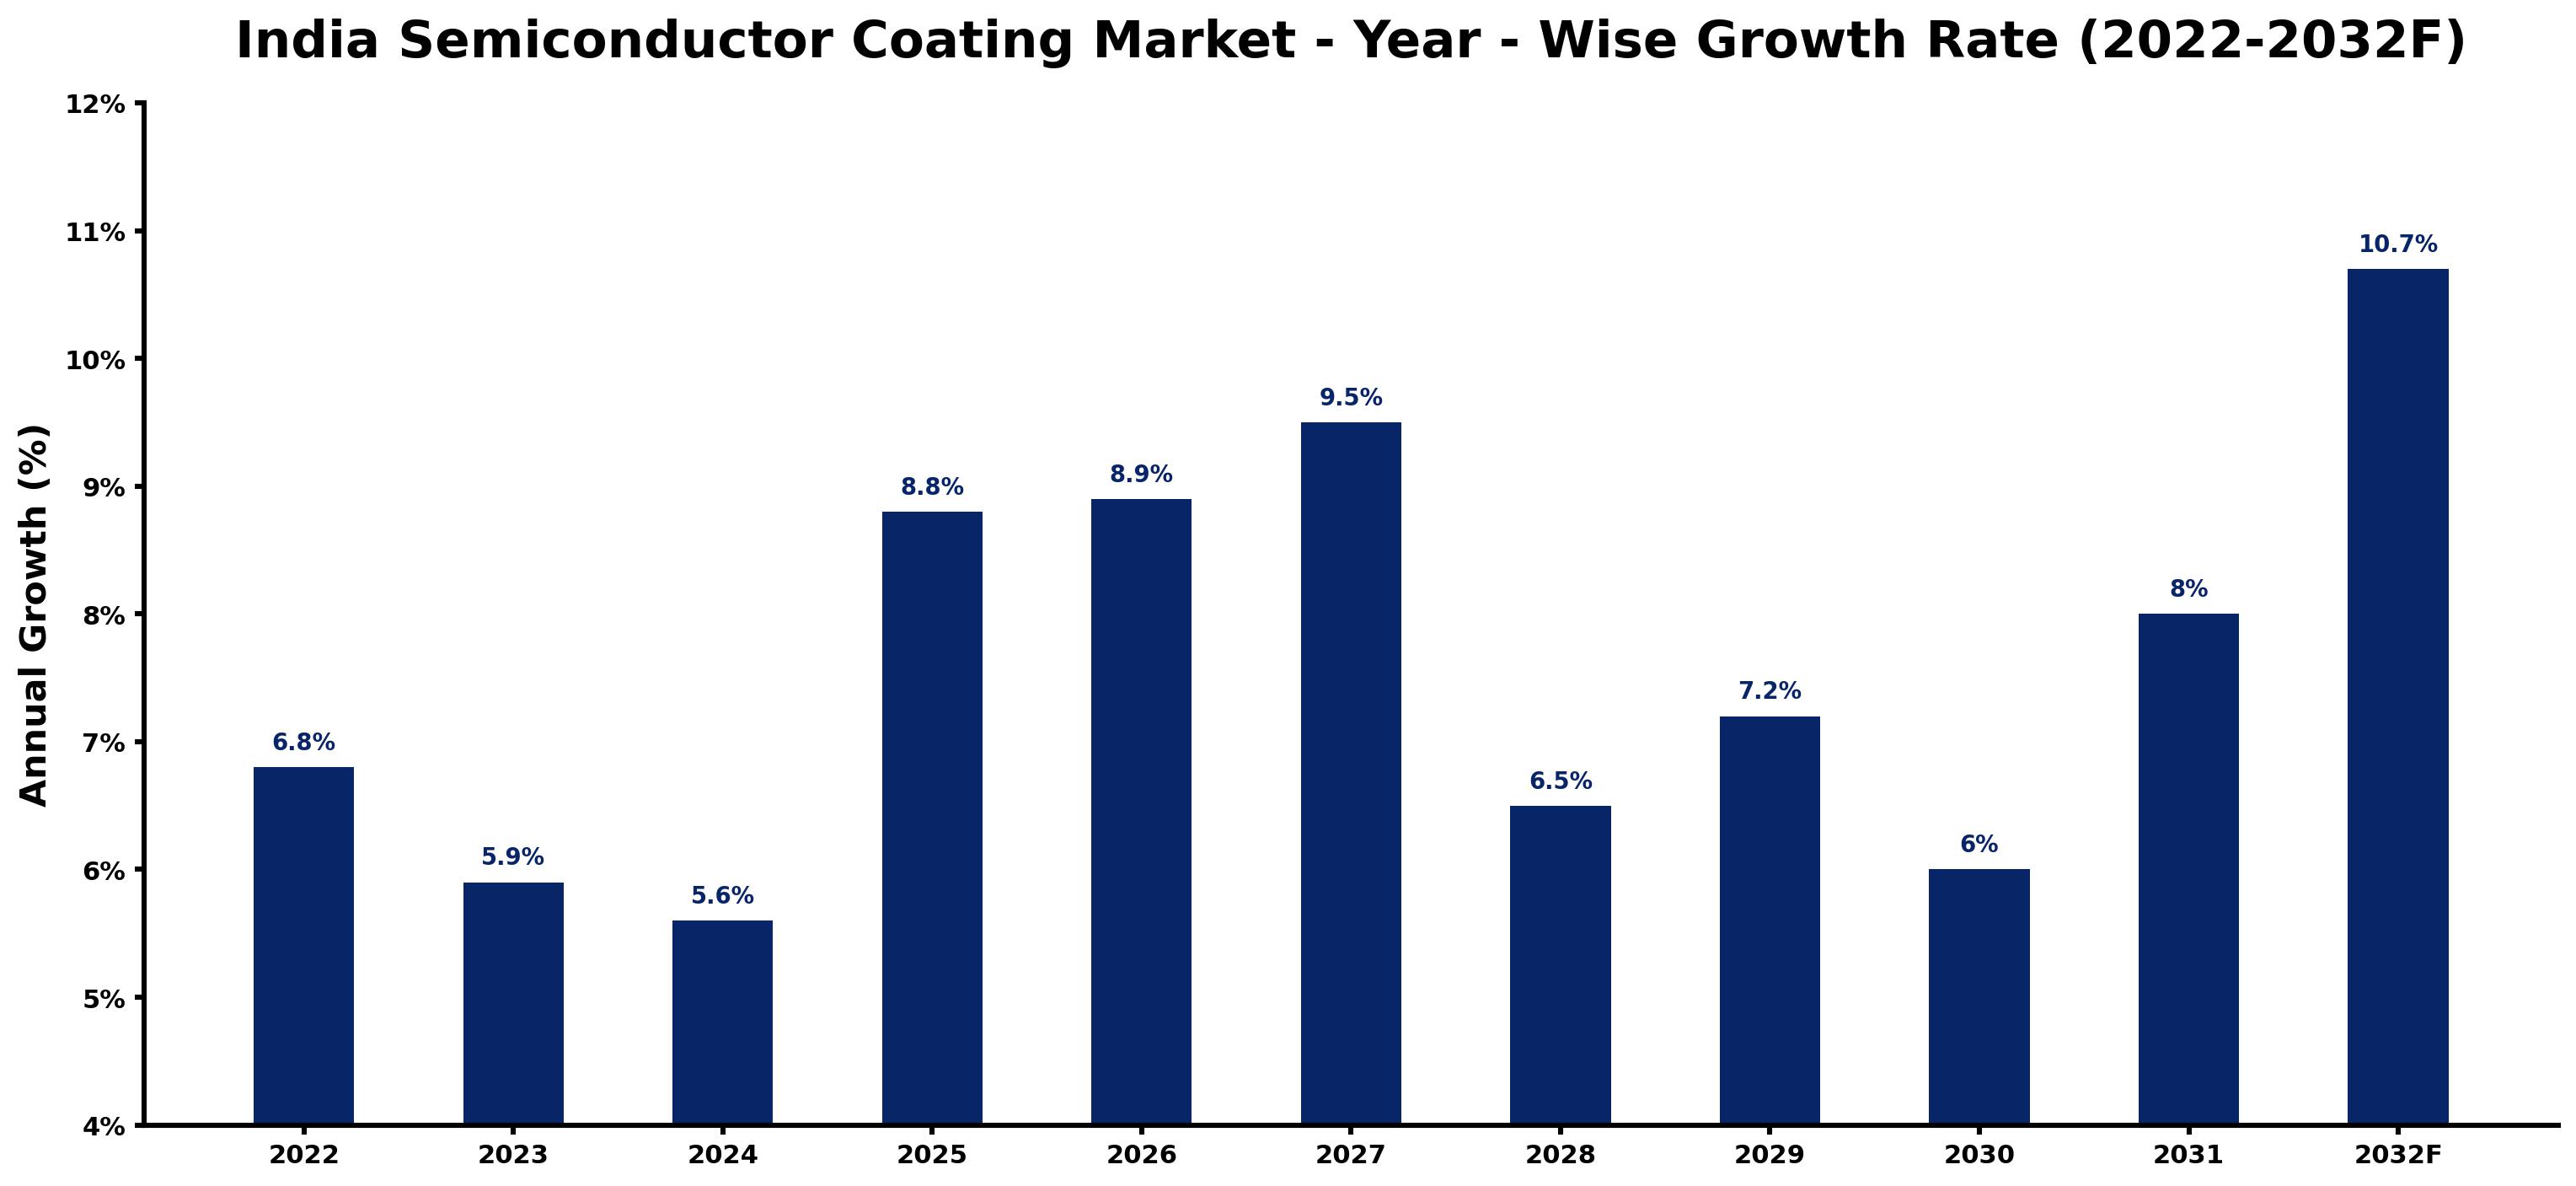
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.8 | The market experienced steady growth driven by increasing domestic demand for semiconductors. |
| 2023 | 5.9 | Growth slowed due to supply chain constraints affecting semiconductor production capabilities. |
| 2024 | 5.6 | Demand continued to grow, albeit at a slower pace, as manufacturers adjusted to market conditions. |
| 2025 | 8.8 | Growth accelerated as investments in semiconductor manufacturing began to yield results. |
| 2026 | 8.9 | The market saw further growth as the Production Linked Incentive Scheme attracted new investments. |
| 2027 | 9.5 | Demand rose significantly due to expanding foundry capacities and technological advancements. |
| 2028 | 6.5 | Growth slowed again as the market adjusted to previous high levels of investment. |
| 2029 | 7.2 | An increase in demand for advanced semiconductor devices spurred market growth. |
| 2030 | 6.0 | Growth decelerated as the market stabilised following rapid expansion in prior years. |
| 2031 | 8.0 | The market rebounded with renewed investments and demand for semiconductor coatings. |
| 2032 | 10.7 | A peak in growth was reached as the semiconductor industry expanded rapidly. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Semiconductor Coating Market Synopsis
The Semiconductor Coating Market in India includes specialised materials used in semiconductor manufacturing to improve device performance. These coatings are created through various deposition techniques and play a crucial role in applications such as photolithography and device protection. The market is expanding due to strong domestic demand and government initiatives, including a $10 billion budget under the Semiconductor Mission, aimed at enhancing local production capabilities. With over 20 operational foundries, the industry is set for considerable growth as investments in manufacturing rise.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing domestic demand for semiconductor devices drives the need for coatings. | Driver | High | Anti-Reflective Coating |
| The government's Semiconductor Mission encourages local production of semiconductor materials. | Driver | High | Dielectric Coating |
| The recent surge in semiconductor exports presents opportunities for local manufacturers. | Opportunity | High | Foundries |
| Karnataka's status as a semiconductor hub creates investment opportunities in the region. | Opportunity | Medium | Device Fabricators |
| Supply chain disruptions have affected the availability of raw materials for coatings. | Restraint | High | Passivation Coating |
| High production costs limit the competitiveness of local manufacturers. | Restraint | Medium | Conformal Coating |
| Buyers face delays in obtaining necessary coatings due to regulatory compliance issues. | Challenge | High | Lithography |
| Suppliers struggle with fluctuating demand and production capacity constraints. | Challenge | Medium | Final Protection Layer |
Evaluation of Drivers in India Semiconductor Coating Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising demand for advanced semiconductor devices increases the need for coatings. | Dielectric Coating | The semiconductor industry employs over 100,000 skilled workers, driving demand for reliable coatings. |
| Government initiatives like the Semiconductor Mission boost local production capabilities. | Anti-Reflective Coating | The mission has a budget of $10 billion, enhancing manufacturing infrastructure. |
| Rising exports of semiconductors create a larger market for coatings. | Passivation Coating | India's semiconductor export value was estimated at $5 billion in 2022. |
| Technological advancements in semiconductor manufacturing processes drive coating innovation. | CVD | ISO 9001:2015 certification is widely adopted, ensuring quality in production. |
| Investment in semiconductor foundries expands the market for coatings. | Foundries | Over 20 semiconductor foundries are operational, increasing demand for various coatings. |
The Semiconductor Mission, with a $10 billion budget, improves local manufacturing capabilities, leading to more purchases. The semiconductor industry employs over 100,000 skilled workers, creating a strong demand for reliable coatings. Technological advancements, supported by ISO 9001:2015 certification, ensure high-quality production processes. The operational status of over 20 foundries boosts the need for coatings across various applications.
Evaluation of Restraints in India Semiconductor Coating Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions hinder the availability of essential materials for coatings. | Passivation Coating | Recent global supply chain issues have affected raw material sourcing, delaying production. |
| High production costs limit the competitiveness of local semiconductor coatings. | Conformal Coating | Rising costs of materials and manufacturing impact pricing strategies. |
| Regulatory compliance issues delay the approval of new coating technologies. | Lithography | Buyers face challenges in meeting stringent standards, affecting procurement timelines. |
| Limited access to advanced manufacturing technologies restricts production capabilities. | Final Protection Layer | Local manufacturers struggle to invest in modern equipment. |
| Market volatility affects demand forecasting for semiconductor coatings. | Dielectric Coating | Fluctuating market conditions create uncertainty for suppliers and buyers. |
India Semiconductor Coating Market Challenges
Buyers and suppliers in the India Semiconductor Coating market encounter fierce competition, which compresses profit margins and compels local manufacturers to reduce prices. The industry faces a skills shortage, as rapid growth outpaces the availability of qualified professionals, making it challenging for producers to recruit essential talent. High production costs arise from the necessity for advanced technologies and specialised materials, creating barriers for smaller firms attempting to enter the market. Frequent supply chain disruptions delay production timelines for critical materials, causing manufacturers to miss deadlines and raising costs for buyers by up to 15%.
Trends in the India Semiconductor Coating Market
Four trends stand out in the India Semiconductor Coating Market.
- Launch of the Semiconductor Mission: The Semiconductor Mission, initiated in 2021, aims to improve domestic production capabilities with a budget of $10 billion. This initiative is anticipated to significantly boost local manufacturing and innovation in semiconductor coatings.
- Growth in Karnataka as a Semiconductor Hub: Karnataka is emerging as a key hub for semiconductor manufacturing, attracting investments and a skilled workforce. The state has over 20 operational foundries, driving demand for semiconductor coatings.
- Device Fabricators Increasing Demand: Device fabricators are increasingly seeking advanced coatings to improve product performance. This trend is supported by a projected CAGR of 9.9% in the device fabricators segment over the next several years.
- Shift Towards Advanced Coating Techniques: The semiconductor industry is moving towards advanced coating techniques, particularly CVD, which holds a 50% market share. This transition is expected to enhance the efficiency and reliability of semiconductor devices.
Investment Opportunities in the India Semiconductor Coating Market
Several openings in the India Semiconductor Coating Market merit attention from investors.
- Current Demand for Semiconductor Coatings: With the semiconductor industry projected to reach $807.28 million by 2032, there is a pressing need for high-quality coatings. Foundries are looking for reliable suppliers to meet this demand.
- Investment Opportunities in Karnataka: Karnataka's growing semiconductor ecosystem presents investment opportunities for manufacturers. Local partnerships can facilitate entry into this expanding market, supported by the state's infrastructure.
- Rising Need for Advanced Packaging Solutions: As device fabricators demand advanced packaging solutions, suppliers can focus on providing innovative coatings. This trend is driven by the increasing complexity of semiconductor devices.
- Focus on Compliance and Quality Standards: The adoption of ISO 9001:2015 among manufacturers creates opportunities for suppliers of compliant coatings. Meeting these standards is essential for gaining market trust and expanding sales.
Government Initiatives in the India Semiconductor Coating Market
The 'Semiconductor Mission' launched in 2021 by the Ministry of Electronics and Information Technology provides substantial funding to enhance domestic semiconductor manufacturing capabilities. This initiative complements the 'National Electronics Policy 2020', which aims to achieve a $400 billion electronics manufacturing output by 2025. Together, these measures create a supportive environment for semiconductor coating producers, encouraging innovation and investment in local production facilities.
The Ministry of Electronics and Information Technology oversees the approval of projects under the Semiconductor Mission, ensuring alignment with national goals. Additionally, the updated 'Production Linked Incentive Scheme' incentivises investments in semiconductor manufacturing, targeting $7 billion by 2025. These initiatives offer financial support and regulatory clarity, fostering a conducive environment for semiconductor coating manufacturers to thrive.
Future Insight of the India Semiconductor Coating Market
Several forward-looking factors should support the India Semiconductor Coating market in the coming years. The 'Semiconductor Mission' aims to enhance domestic production capabilities, encouraging local innovation. By 2025, semiconductor employment is expected to rise to over 150,000 skilled workers, addressing the current skills gap. The 'Make in India' initiative will further promote local manufacturing, strengthening the supply chain and enhancing competitiveness.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Coating Type – Anti-Reflective Coating Dominated, Conformal Coating Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, the largest coating type category in 2025 was Anti-Reflective Coating, with a 41% share of total revenue. Anti-Reflective Coatings capture the largest market share due to their essential role in photolithography processes, which are fundamental in semiconductor manufacturing. With over 20 semiconductor foundries operational in India, the demand for these coatings remains consistently robust. Conformal Coating is projected to grow fastest, at a CAGR of 9.1% during 2026–2032. Conformal Coatings are rapidly growing, primarily because they provide crucial moisture and chemical protection for semiconductor devices, particularly in advanced applications. The increasing complexity of semiconductor manufacturing processes necessitates the use of these protective coatings, driving their market expansion. Suppliers should focus on enhancing their Conformal Coating offerings to leverage the increasing demand within the semiconductor industry.
By Application Stage – Lithography Dominated, Final Protection Layer Expected to Grow Fastest
In 2025, Lithography led the application stage split with a 49% share. Lithography commands the largest market share as it is a critical step in semiconductor fabrication, requiring precise coatings for high-quality production. The importance of this stage is underscored by government initiatives aimed at enhancing domestic semiconductor manufacturing capabilities. The quickest growth will come from Final Protection Layer, forecast to expand at a CAGR of 10.2% between 2026 and 2032. The Final Protection Layer is witnessing rapid growth, driven by the rising demand for improved device durability and performance in the competitive semiconductor sector. This growth reflects a strong emphasis on reliability and longevity in semiconductor applications. Buyers should prioritise sourcing high-quality coatings for the Final Protection Layer to ensure optimal performance and longevity of their devices.
By Method Used – CVD Dominated and Is Expected to Record the Fastest Growth
CVD held a 50% share of the India Semiconductor Coating Market by method used in 2025. CVD dominates the market share as it is the most widely used deposition method for semiconductor coatings, providing consistent quality and performance. Its established presence in over 20 foundries reinforces its leading position in the industry. CVD is also forecast to expand faster than any other category, at a CAGR of 9.7% over 2026–2032. CVD is also the fastest-growing method, as its efficiency and effectiveness in coating applications continue to meet the rising demands of semiconductor production. The method's versatility ensures it remains at the forefront of technological advancements in the sector. Suppliers must invest in improving CVD technologies to maintain their competitive edge in the semiconductor coating market.
By End User – Foundries Dominated, Device Fabricators Expected to Grow Fastest
With a 39% revenue share in 2025, Foundries was the largest end user category. Foundries dominate the market share as they are the primary end users of semiconductor coatings, extensively utilising these materials to enhance device performance. The growth of India's semiconductor industry is closely tied to the increasing demand from foundries for effective coatings. Device Fabricators are set to record the highest CAGR in this split, 9.9% over 2026–2032. Device Fabricators represent the fastest-growing segment, propelled by the escalating need for specialised coatings across various semiconductor devices. As the industry evolves, the focus on tailored solutions for device fabrication is expected to significantly boost this segment's growth. Suppliers should tailor their offerings to meet the specific requirements of Device Fabricators to effectively capture this expanding market segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Semiconductor Coating Market Outlook
- Market Size of India Semiconductor Coating Market, 2025
- Forecast of India Semiconductor Coating Market, 2032
- Historical Data and Forecast of India Semiconductor Coating Revenues & Volume for the Period 2022 - 2032F
- India Semiconductor Coating Market Trend Evolution
- India Semiconductor Coating Market Drivers and Challenges
- India Semiconductor Coating Price Trends
- India Semiconductor Coating Porter's Five Forces
- India Semiconductor Coating Industry Life Cycle
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Coating Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Anti-Reflective Coating for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Passivation Coating for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Conformal Coating for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Dielectric Coating for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Application Stage for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Lithography for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Final Protection Layer for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Wafer Surfaces for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Isolation Layer for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Method Used for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Spin Coating for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By CVD for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Spray or Dip for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Sputtering for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By IDM/Packaging Plants for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Device Fabricators for the Period 2022 - 2032F
- Historical Data and Forecast of India Semiconductor Coating Market Revenues & Volume By Advanced Packaging Units for the Period 2022 - 2032F
- India Semiconductor Coating Import Export Trade Statistics
- Market Opportunity Assessment By Coating Type
- Market Opportunity Assessment By Application Stage
- Market Opportunity Assessment By Method Used
- Market Opportunity Assessment By End User
- India Semiconductor Coating Top Companies Market Share
- India Semiconductor Coating Competitive Benchmarking By Technical and Operational Parameters
- India Semiconductor Coating Company Profiles
- India Semiconductor Coating Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Coating Type
- Anti-Reflective Coating
- Passivation Coating
- Conformal Coating
- Dielectric Coating
By Application Stage
- Lithography
- Final Protection Layer
- Wafer Surfaces
- Isolation Layer
By Method Used
- Spin Coating
- CVD
- Spray or Dip
- Sputtering
By End User
- Foundries
- IDM/Packaging Plants
- Device Fabricators
- Advanced Packaging Units































