China Semiconductor Coating Market Size & Growth Rate
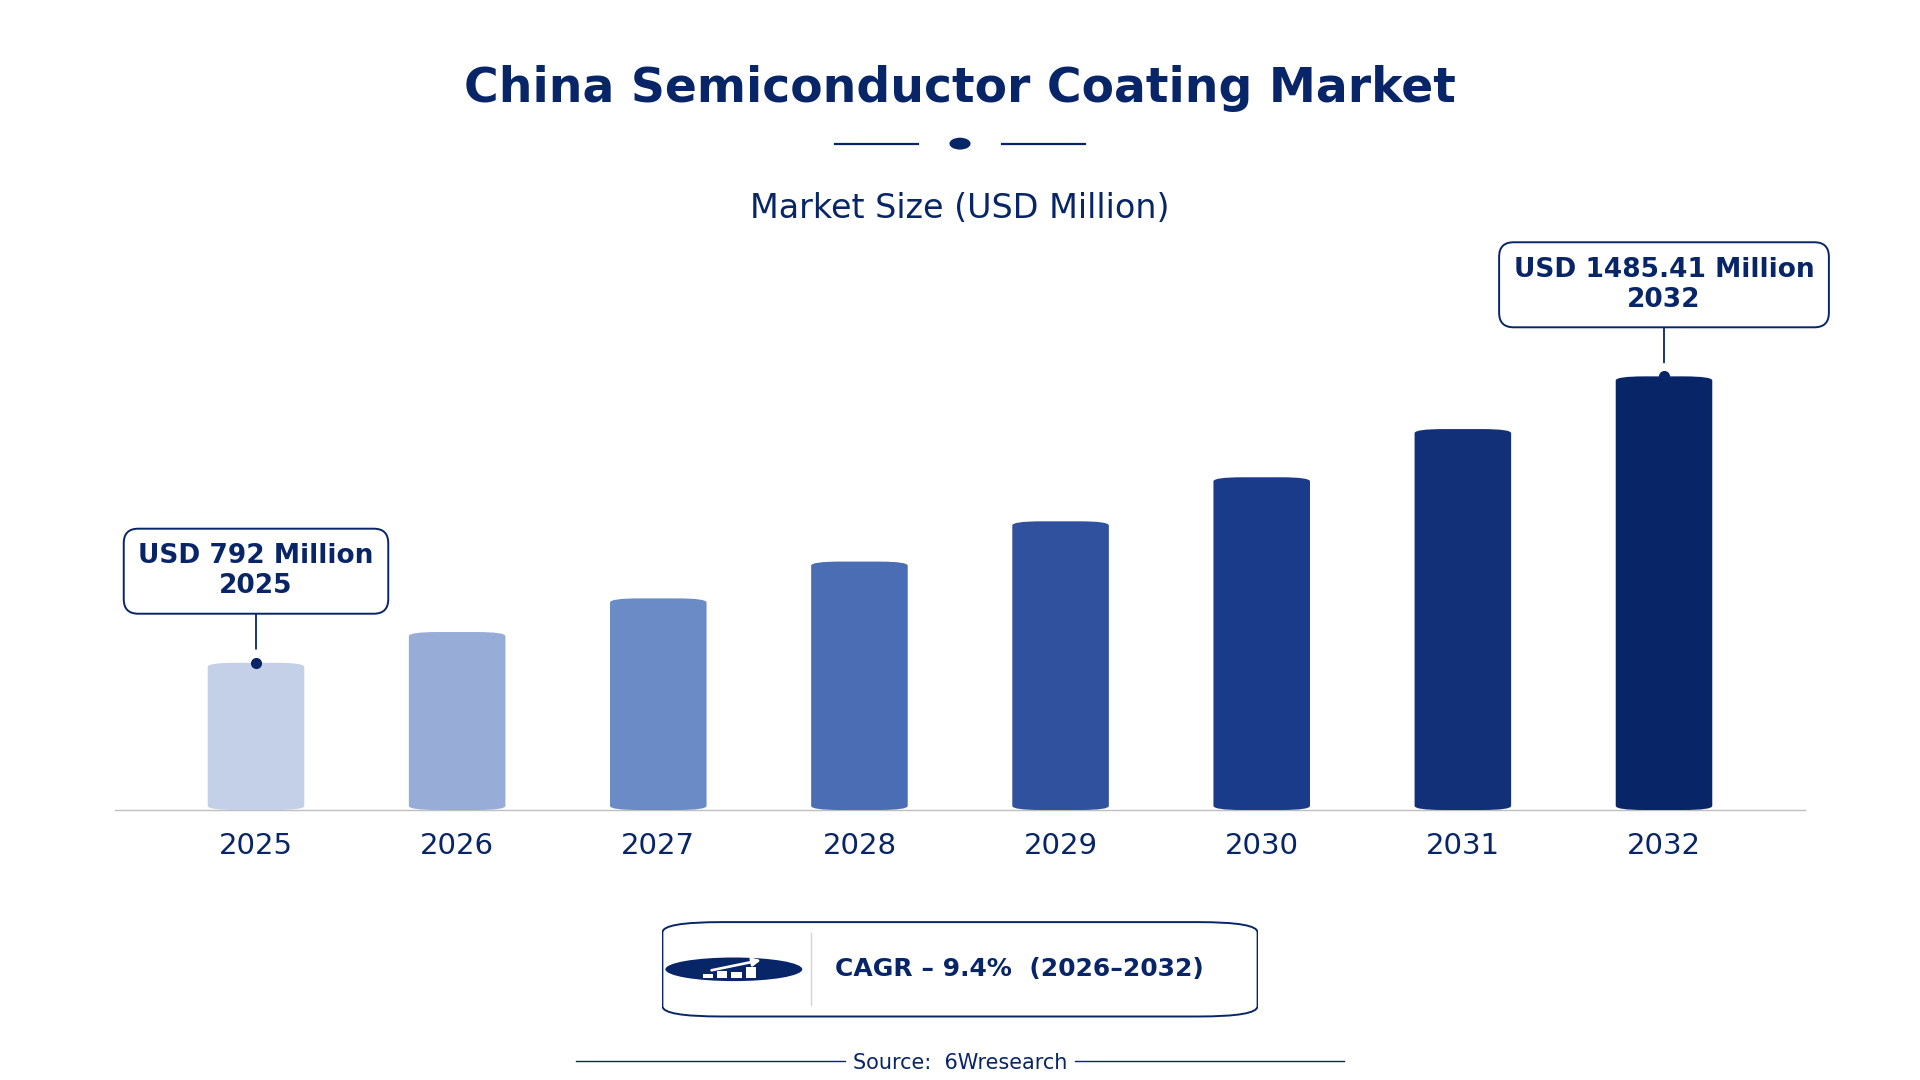
According to 6Wresearch internal database and industry insights, the China Semiconductor Coating Market was valued at USD 792.0 million in 2025 and is projected to reach USD 1,485.41 million by 2032, growing at a CAGR of approximately 9.4% during 2026–2032.
China Semiconductor Coating Market Highlights
| Report Metric | Details |
| Report Name | China Semiconductor Coating Market |
| Market Size 2025 | USD 792.0 million |
| Market Size 2032 | USD 1,485.41 million |
| Absolute Growth 2025–2032 | USD 693.41 million |
| CAGR 2026–2032 | 9.4% |
| Peak Annual Growth | 11.7% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Coating Type, 2025 | Dielectric Coating (36% share) |
| Leading Application Stage, 2025 | Lithography (36% share) |
| Leading Method Used, 2025 | CVD (43% share) |
| Leading End User, 2025 | Foundries (40% share) |
| Fastest-Growing Coating Type | Anti-Reflective Coating (11.1% CAGR) |
| Fastest-Growing Application Stage | Final Protection Layer (11.2% CAGR) |
| Fastest-Growing End User | Advanced Packaging Units (11.0% CAGR) |
| Growing Sector | Semiconductor Manufacturing |
| Key End Users | Foundries, IDM/Packaging Plants, Device Fabricators, Advanced Packaging Units |
China Semiconductor Coating Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
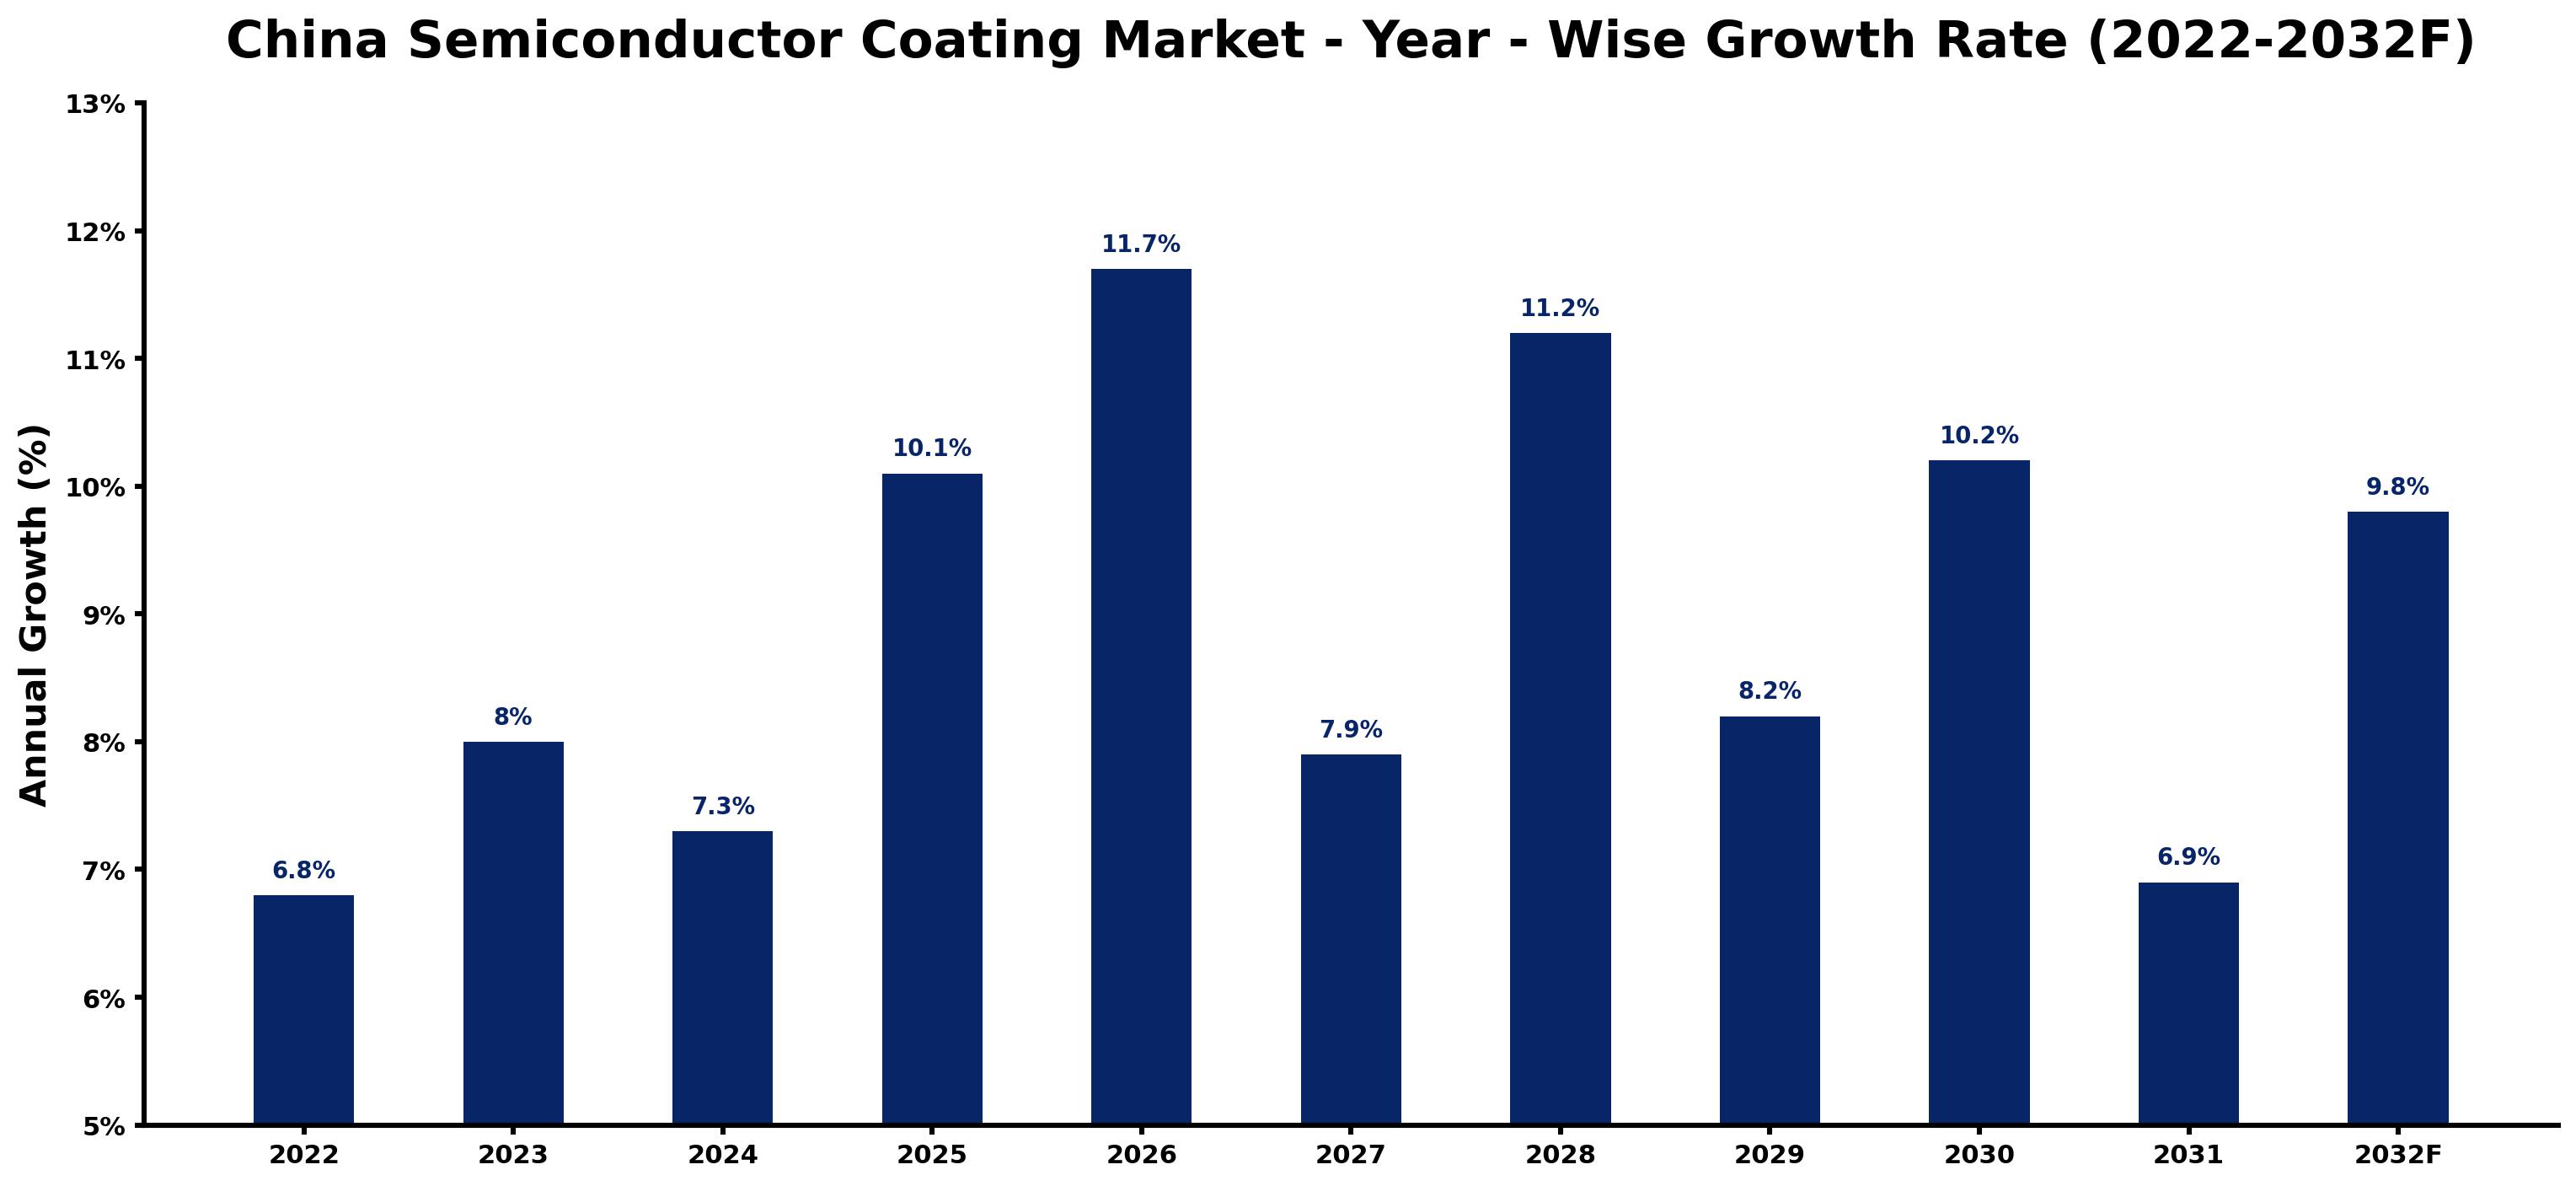
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.8 | The market experienced steady growth due to ongoing demand from domestic manufacturers driven by the 'Made in China 2025' initiative. |
| 2023 | 8.0 | Demand increased as semiconductor production in China rose by 15% in 2023, supported by the 'Semiconductor Innovation Action Plan'. |
| 2024 | 7.3 | Growth slowed as manufacturers adjusted to supply chain challenges affecting production, particularly in the foundries sector. |
| 2025 | 10.1 | Demand surged as the market reached a historical peak driven by advancements in lithography technologies. |
| 2026 | 11.7 | The market is expected to peak due to the implementation of new production standards under the 'Semiconductor Innovation Action Plan'. |
| 2027 | 7.9 | Growth is projected to slow as the market stabilises after rapid expansion in previous years, particularly in advanced packaging units. |
| 2028 | 11.2 | Demand is expected to rise again as the focus on advanced packaging intensifies with new investments in technology. |
| 2029 | 8.2 | The market growth rate is anticipated to slow as production capacities normalise following previous expansions in foundries. |
| 2030 | 10.2 | Growth is expected to pick up as new fabrication facilities come online and increase output in the semiconductor sector. |
| 2031 | 6.9 | The market is projected to grow at a slower rate as it adjusts to market saturation in production capabilities, particularly in dielectric coatings. |
| 2032 | 9.8 | Demand is expected to rise as the industry focuses on self-sufficiency in production, supported by local initiatives like the 'National Semiconductor Innovation Fund'. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Semiconductor Coating Market Synopsis
Semiconductor Coating in China encompasses the application of thin films to semiconductor wafers, improving performance and protection. These coatings are essential for enhancing light absorption and providing electrical insulation. The China Semiconductor Coating Market is growing due to strong demand from foundries and a focus on advanced technologies. The semiconductor sector reached a value of approximately 1 trillion yuan in 2022, with a projected average annual growth rate of 10% through 2025. Domestic manufacturers are increasingly relying on local sources, with over 30% of coatings sourced domestically.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing domestic production capacity driven by local foundries | Driver | High | Foundries |
| Technological advancements in semiconductor manufacturing processes | Driver | High | Lithography |
| Growing demand for high-quality coatings in advanced packaging | Opportunity | High | Advanced Packaging Units |
| Investment in R&D for innovative coating solutions | Opportunity | High | Device Fabricators |
| Supply chain disruptions affecting raw material availability | Restraint | High | Passivation Coating |
| Compliance costs associated with national standards | Restraint | Medium | Dielectric Coating |
| Intense competition from international suppliers | Challenge | High | Anti-Reflective Coating |
| Dependence on imported materials for production | Challenge | Medium | Conformal Coating |
Evaluation of Drivers in China Semiconductor Coating Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Expansion of foundry operations | Foundries | The increase in foundries in regions like Jiangsu leads to heightened demand for coatings, with over 200 foundries currently operating. |
| Technological advancements in semiconductor processes | Lithography | Innovations in lithography are driving demand for coatings, as manufacturers seek to improve light absorption during production. |
| Rising domestic semiconductor production | IDM/Packaging Plants | A 15% increase in domestic production in 2023 has prompted IDM plants to require more coatings for packaging. |
| Investment in advanced packaging technologies | Advanced Packaging Units | The push for high-performance packaging solutions is increasing demand for specialized coatings, with growth projected at 11.0%. |
| Support from government initiatives | Device Fabricators | Government programs like the 'Semiconductor Innovation Action Plan' are enhancing capabilities and driving demand for coatings. |
Market growth in China for Semiconductor Coating rests on increasing production capacity, technological advancements, and a skilled workforce. The semiconductor industry has over 200 foundries, which are expanding their operations, leading to heightened demand for coatings. In 2023, domestic semiconductor production rose by 15%, prompting manufacturers to seek more coatings. The 'Semiconductor Innovation Action Plan' aims to boost production capabilities, driving demand for high-quality coatings. Additionally, China's semiconductor workforce is projected to exceed 1 million skilled professionals by 2025, supporting the growth of the sector.
Evaluation of Restraints in China Semiconductor Coating Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions have led to increased costs for semiconductor manufacturers. | Device Fabricators | In 2023, the semiconductor industry faced challenges that raised production costs by 10%. |
| Quality compliance requirements can limit the speed of production. | Dielectric Coating | The National Standard GB/T 24553-2009 mandates strict quality checks, slowing down processes. |
| Limited access to advanced materials can hinder innovation in coatings. | IDM/Packaging Plants | The semiconductor industry relies on specific materials, which are sometimes hard to source, affecting production timelines. |
| High competition among local manufacturers can lead to price wars. | Foundries | In 2022, over 30% of coatings used were sourced domestically, increasing competition and affecting pricing strategies. |
| Technological barriers in adopting new coating methods can restrict growth. | Advanced Packaging Units | Many manufacturers are hesitant to invest in new technologies due to high initial costs and risks. |
China Semiconductor Coating Market Challenges
Producers in the China semiconductor coating market encounter supply chain disruptions due to dependence on imported raw materials, potentially delaying production timelines by up to three months. Adhering to the National Standard GB/T 24553-2009 raises operational costs, increasing expenses for manufacturers by around 20%. Local producers face intense competition from international suppliers, who often provide lower prices, which may result in a 15% decline in profitability. Consequently, buyers are likely to experience rising costs, with semiconductor coating prices anticipated to increase by 10% in the coming year.
Trends in the China Semiconductor Coating Market
The trends below show where the China Semiconductor Coating Market is heading.
- Shift from Traditional to Advanced Coating Techniques: The semiconductor industry is increasingly adopting advanced coating techniques such as CVD and sputtering. In 2022, over 43% of coatings used were from CVD methods, improving production efficiency.
- Increase in Domestic Sourcing for Coatings: In 2022, over 30% of semiconductor coatings were sourced domestically, reflecting a shift towards local suppliers. This trend supports the government's push for self-sufficiency in chip production.
- Growing Focus on Eco-Friendly Coatings: Manufacturers are prioritising environmentally friendly coatings to comply with new regulations. In 2023, the Ministry of Industry and Information Technology launched initiatives promoting sustainable practices in semiconductor production.
- Expansion of Advanced Packaging Units: The rise of advanced packaging units is reshaping the semiconductor coating sector. By 2025, these units are projected to grow by 11%, driving demand for high-performance coatings.
Investment Opportunities in the China Semiconductor Coating Market
Some of the investment opportunities in the China Semiconductor Coating Market are mentioned below.
- Foundries seeking advanced coatings: Foundries are increasingly searching for high-performance coatings to boost chip production efficiency. With the semiconductor market valued at approximately 1 trillion yuan in 2022, there is a notable opportunity for suppliers to fulfil this demand.
- Entry through local partnerships: Local manufacturers can gain from partnerships with foundries to supply coatings. The 'Semiconductor Equipment Subsidy Program' provides 5 billion yuan in funding, creating an opportune moment for collaboration.
- Investment in R&D for innovative coatings: With the semiconductor industry projected to expand, there is a strong demand for innovative coating solutions. The National Semiconductor Innovation Fund, with a budget of 10 billion yuan, supports R&D efforts in this area.
- Focus on advanced packaging solutions: Advanced Packaging Units are increasingly investing in high-quality coatings to improve device performance. As this segment grows, suppliers can enter the market by offering specialised products tailored to these needs.
Government Initiatives in the China Semiconductor Coating Market
The Ministry of Industry and Information Technology launched the '14th Five-Year Plan for the Semiconductor Industry' in 2021, aiming for a 30% increase in domestic production by 2025. This plan supports semiconductor coating manufacturers by encouraging local sourcing and innovation. Additionally, the 'Semiconductor Innovation Action Plan' was introduced in 2023, focusing on advancing semiconductor technologies and improving production capabilities.
The National Development and Reform Commission oversees the 'Semiconductor Equipment Subsidy Program', which provides 5 billion yuan in funding for local manufacturers to enhance production. The State Council also approved the 'National Semiconductor Innovation Fund' in 2023, allocating 10 billion yuan to support R&D projects in the semiconductor sector. These initiatives aim to improve local production and stimulate innovation in semiconductor coatings.
Future Insight of the China Semiconductor Coating Market
Several forward-looking factors should support the semiconductor coating market in China over the coming years. The 'Semiconductor Innovation Action Plan' is expected to improve domestic production capabilities, reducing reliance on imports. By 2025, the semiconductor workforce is projected to exceed 1 million skilled professionals, driving innovation and efficiency. The 'Made in China 2025' initiative will promote advancements in semiconductor technologies, positioning local producers to compete more effectively.
Market Segmentation Analysis
The report offers a comprehensive study of the following market segments and their leading categories in the market.
By Coating Type – Dielectric Coating Dominated, Anti-Reflective Coating Expected to Grow Fastest
According to Shubham Padhi, Research Analyst at 6Wresearch, Dielectric Coating accounted for a 36% market share by coating type in 2025. Dielectric Coating holds the largest share in China's semiconductor coating market due to its critical role in providing electrical insulation for multilayer devices. This coating type is particularly valued by manufacturers in regions such as Jiangsu and Guangdong, where advanced semiconductor production is a focus. Over 2026–2032, Anti-Reflective Coating is expected to post the fastest growth, at a CAGR of 11.1%. Anti-Reflective Coating is experiencing rapid growth as it significantly enhances light absorption in photolithography processes, essential for semiconductor production. The increasing demand for high-efficiency chips is driving this segment's expansion, indicating a shift towards more advanced manufacturing techniques. Suppliers should prioritise the development of advanced dielectric and anti-reflective coatings to meet the evolving needs of semiconductor manufacturers.
By Application Stage – Lithography Dominated, Final Protection Layer Expected to Grow Fastest
Lithography took a 36% share of application stage in 2025, more than any other category. Lithography is the leading application stage, capturing a substantial share of the semiconductor coating market due to its essential role in patterning layers during semiconductor manufacturing. This process is crucial for foundries that aim to produce high-quality chips efficiently and effectively, reinforcing its market dominance. Final Protection Layer is projected to grow fastest, at a CAGR of 11.2% during 2026–2032. The Final Protection Layer is the fastest-growing application stage, propelled by the increasing demand for enhanced device integrity and reliability in semiconductor products. As chip designs evolve and become more complex, the need for robust protective coatings is surging, driving this segment's growth. Buyers should focus on coatings that ensure durability and reliability in semiconductor devices to keep pace with technological advancements.
By Method Used – CVD Dominated and Is Expected to Record the Fastest Growth
The largest method used category in 2025 was CVD, with a 43% share of total revenue. CVD is the predominant method in the semiconductor coating market, commanding a significant share due to its efficiency in depositing thin films during fabrication. This technique is widely adopted across numerous semiconductor foundries in China, underscoring its importance in the industry. The same category is also set to grow fastest, at a CAGR of 10.9% during 2026–2032. CVD is also the fastest-growing method, as its versatility and efficiency align with the increasing demands of semiconductor production. Continuous advancements in CVD technology are likely to further solidify its leading market position. Suppliers should invest in enhancing CVD technology to maintain competitiveness in the rapidly evolving semiconductor coating landscape.
By End User – Foundries Dominated, Advanced Packaging Units Expected to Grow Fastest
Foundries held a 40% share of the China Semiconductor Coating Market by end user in 2025. Foundries represent the largest end-user segment, holding a considerable share of the semiconductor coating market as they are the primary consumers of coatings for chip production. Their extensive operations in key regions like Jiangsu and Guangdong significantly drive the demand for high-quality coatings, reinforcing their market position. Advanced Packaging Units are set to record the highest CAGR in this split, 11.0% over 2026–2032. Advanced Packaging Units are the fastest-growing end-user segment, as they increasingly require coatings for high-performance packaging solutions. The shift towards more sophisticated packaging technologies is accelerating this segment's growth, indicating a trend towards advanced manufacturing processes. Suppliers must cater to the specific needs of advanced packaging units to capitalise on the growing demand for innovative semiconductor packaging solutions.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Semiconductor Coating Market Outlook
- Market Size of China Semiconductor Coating Market, 2025
- Forecast of China Semiconductor Coating Market, 2032
- Historical Data and Forecast of China Semiconductor Coating Revenues & Volume for the Period 2022 - 2032F
- China Semiconductor Coating Market Trend Evolution
- China Semiconductor Coating Market Drivers and Challenges
- China Semiconductor Coating Price Trends
- China Semiconductor Coating Porter's Five Forces
- China Semiconductor Coating Industry Life Cycle
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Coating Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Anti-Reflective Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Passivation Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Conformal Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Dielectric Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Application Stage for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Lithography for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Final Protection Layer for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Wafer Surfaces for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Isolation Layer for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Method Used for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Spin Coating for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By CVD for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Spray or Dip for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Sputtering for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Foundries for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By IDM/Packaging Plants for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Device Fabricators for the Period 2022 - 2032F
- Historical Data and Forecast of China Semiconductor Coating Market Revenues & Volume By Advanced Packaging Units for the Period 2022 - 2032F
- China Semiconductor Coating Import Export Trade Statistics
- Market Opportunity Assessment By Coating Type
- Market Opportunity Assessment By Application Stage
- Market Opportunity Assessment By Method Used
- Market Opportunity Assessment By End User
- China Semiconductor Coating Top Companies Market Share
- China Semiconductor Coating Competitive Benchmarking By Technical and Operational Parameters
- China Semiconductor Coating Company Profiles
- China Semiconductor Coating Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Coating Type
- Anti-Reflective Coating
- Passivation Coating
- Conformal Coating
- Dielectric Coating
By Application Stage
- Lithography
- Final Protection Layer
- Wafer Surfaces
- Isolation Layer
By Method Used
- Spin Coating
- CVD
- Spray or Dip
- Sputtering
By End User
- Foundries
- IDM/Packaging Plants
- Device Fabricators
- Advanced Packaging Units































