India Specialty Alloys Market Size & Growth Rate
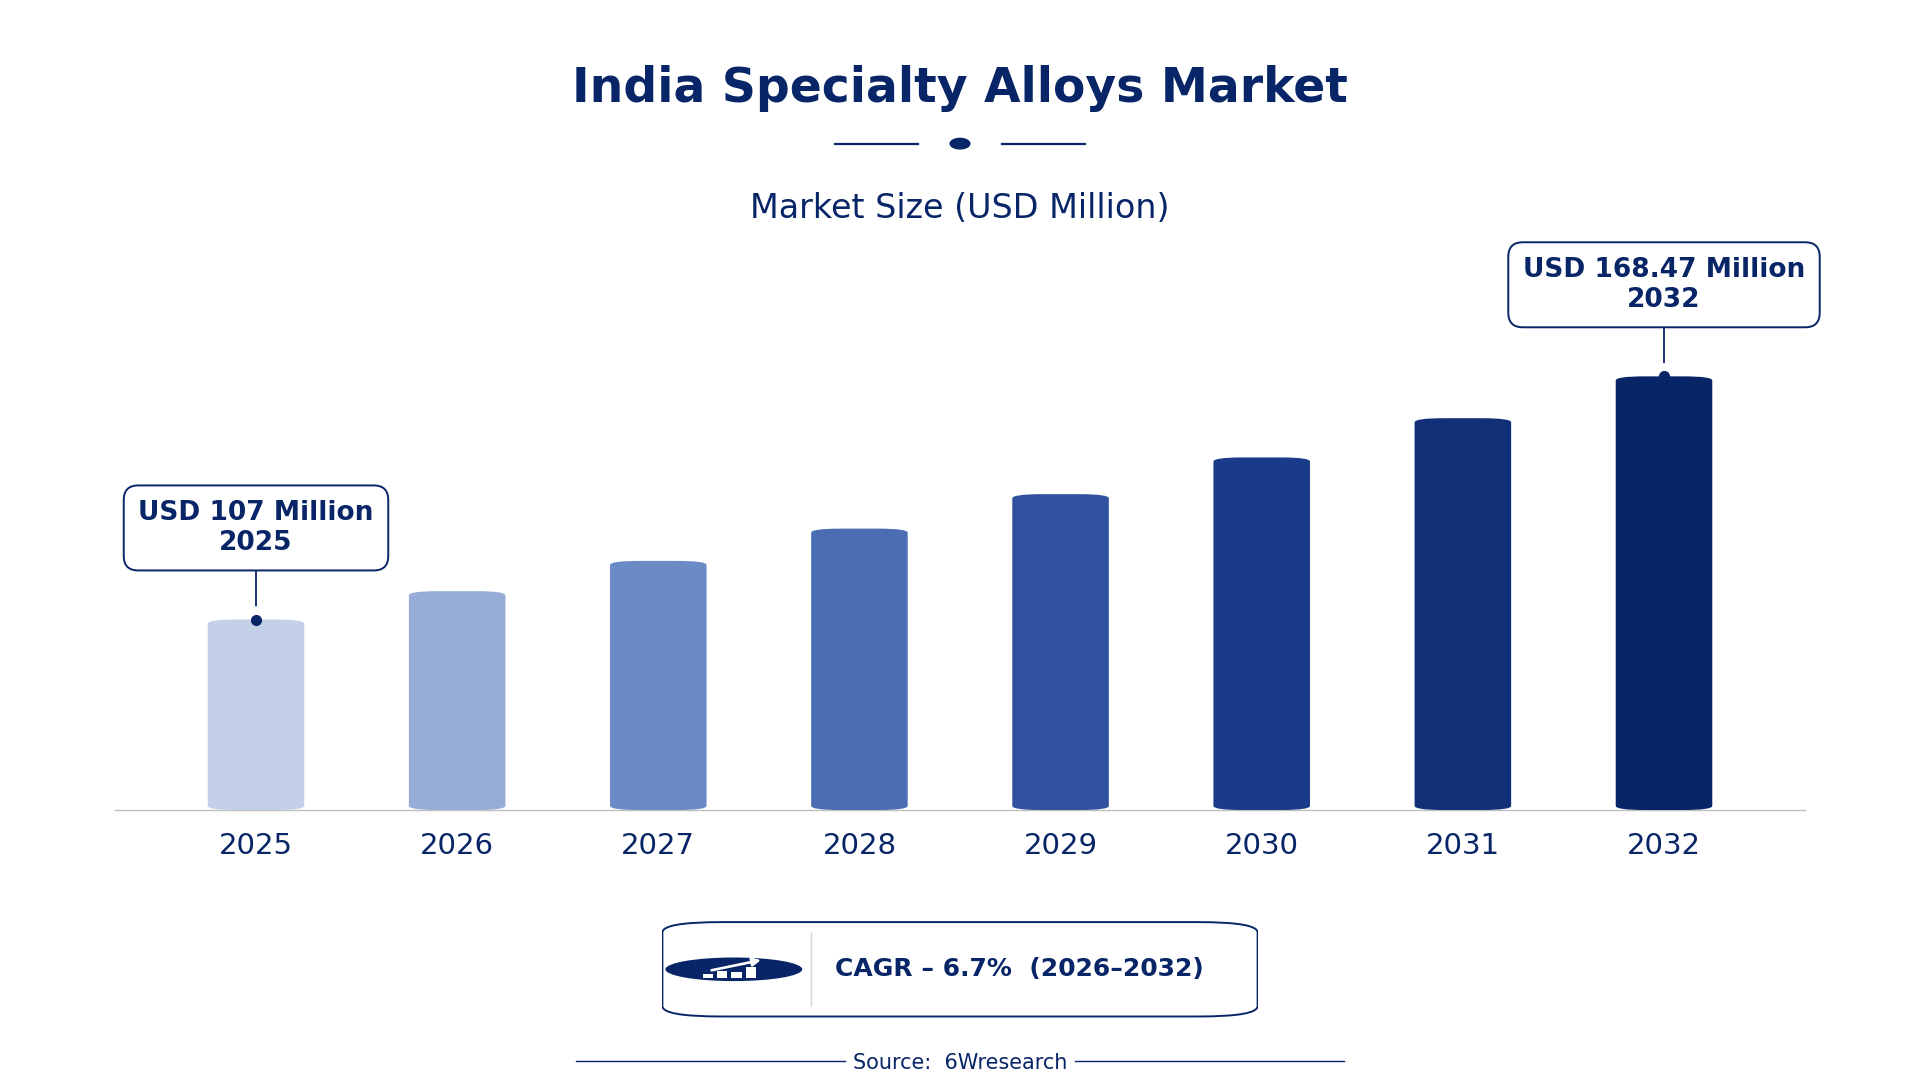
According to 6Wresearch internal database and industry insights, the India Specialty Alloys Market was valued at USD 107.0 million in 2025 and is projected to reach USD 168.47 million by 2032, growing at a CAGR of approximately 6.7% during 2026–2032.
India Specialty Alloys Market Highlights
| Report Metric | Details |
| Report Name | India Specialty Alloys Market |
| Market Size 2025 | USD 107.0 million |
| Market Size 2032 | USD 168.47 million |
| Absolute Growth 2025–2032 | USD 61.47 million |
| CAGR 2026–2032 | 6.7% |
| Peak Annual Growth | 9.3% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Alloy Type, 2025 | Nickel Alloys (45% share) |
| Leading Base Material, 2025 | Nickel-Chromium (46% share) |
| Leading Application Industry, 2025 | Aerospace (38% share) |
| Leading End User, 2025 | Aircraft Manufacturers (40% share) |
| Fastest-Growing Alloy Type | Titanium Alloys (8.9% CAGR) |
| Fastest-Growing Base Material | Titanium/Al-V (8.5% CAGR) |
| Fastest-Growing Application Industry | Medical Implants (9.4% CAGR) |
| Fastest-Growing End User | Healthcare OEMs (9.3% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Aircraft Manufacturers, Automotive Producers, Healthcare OEMs |
India Specialty Alloys Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
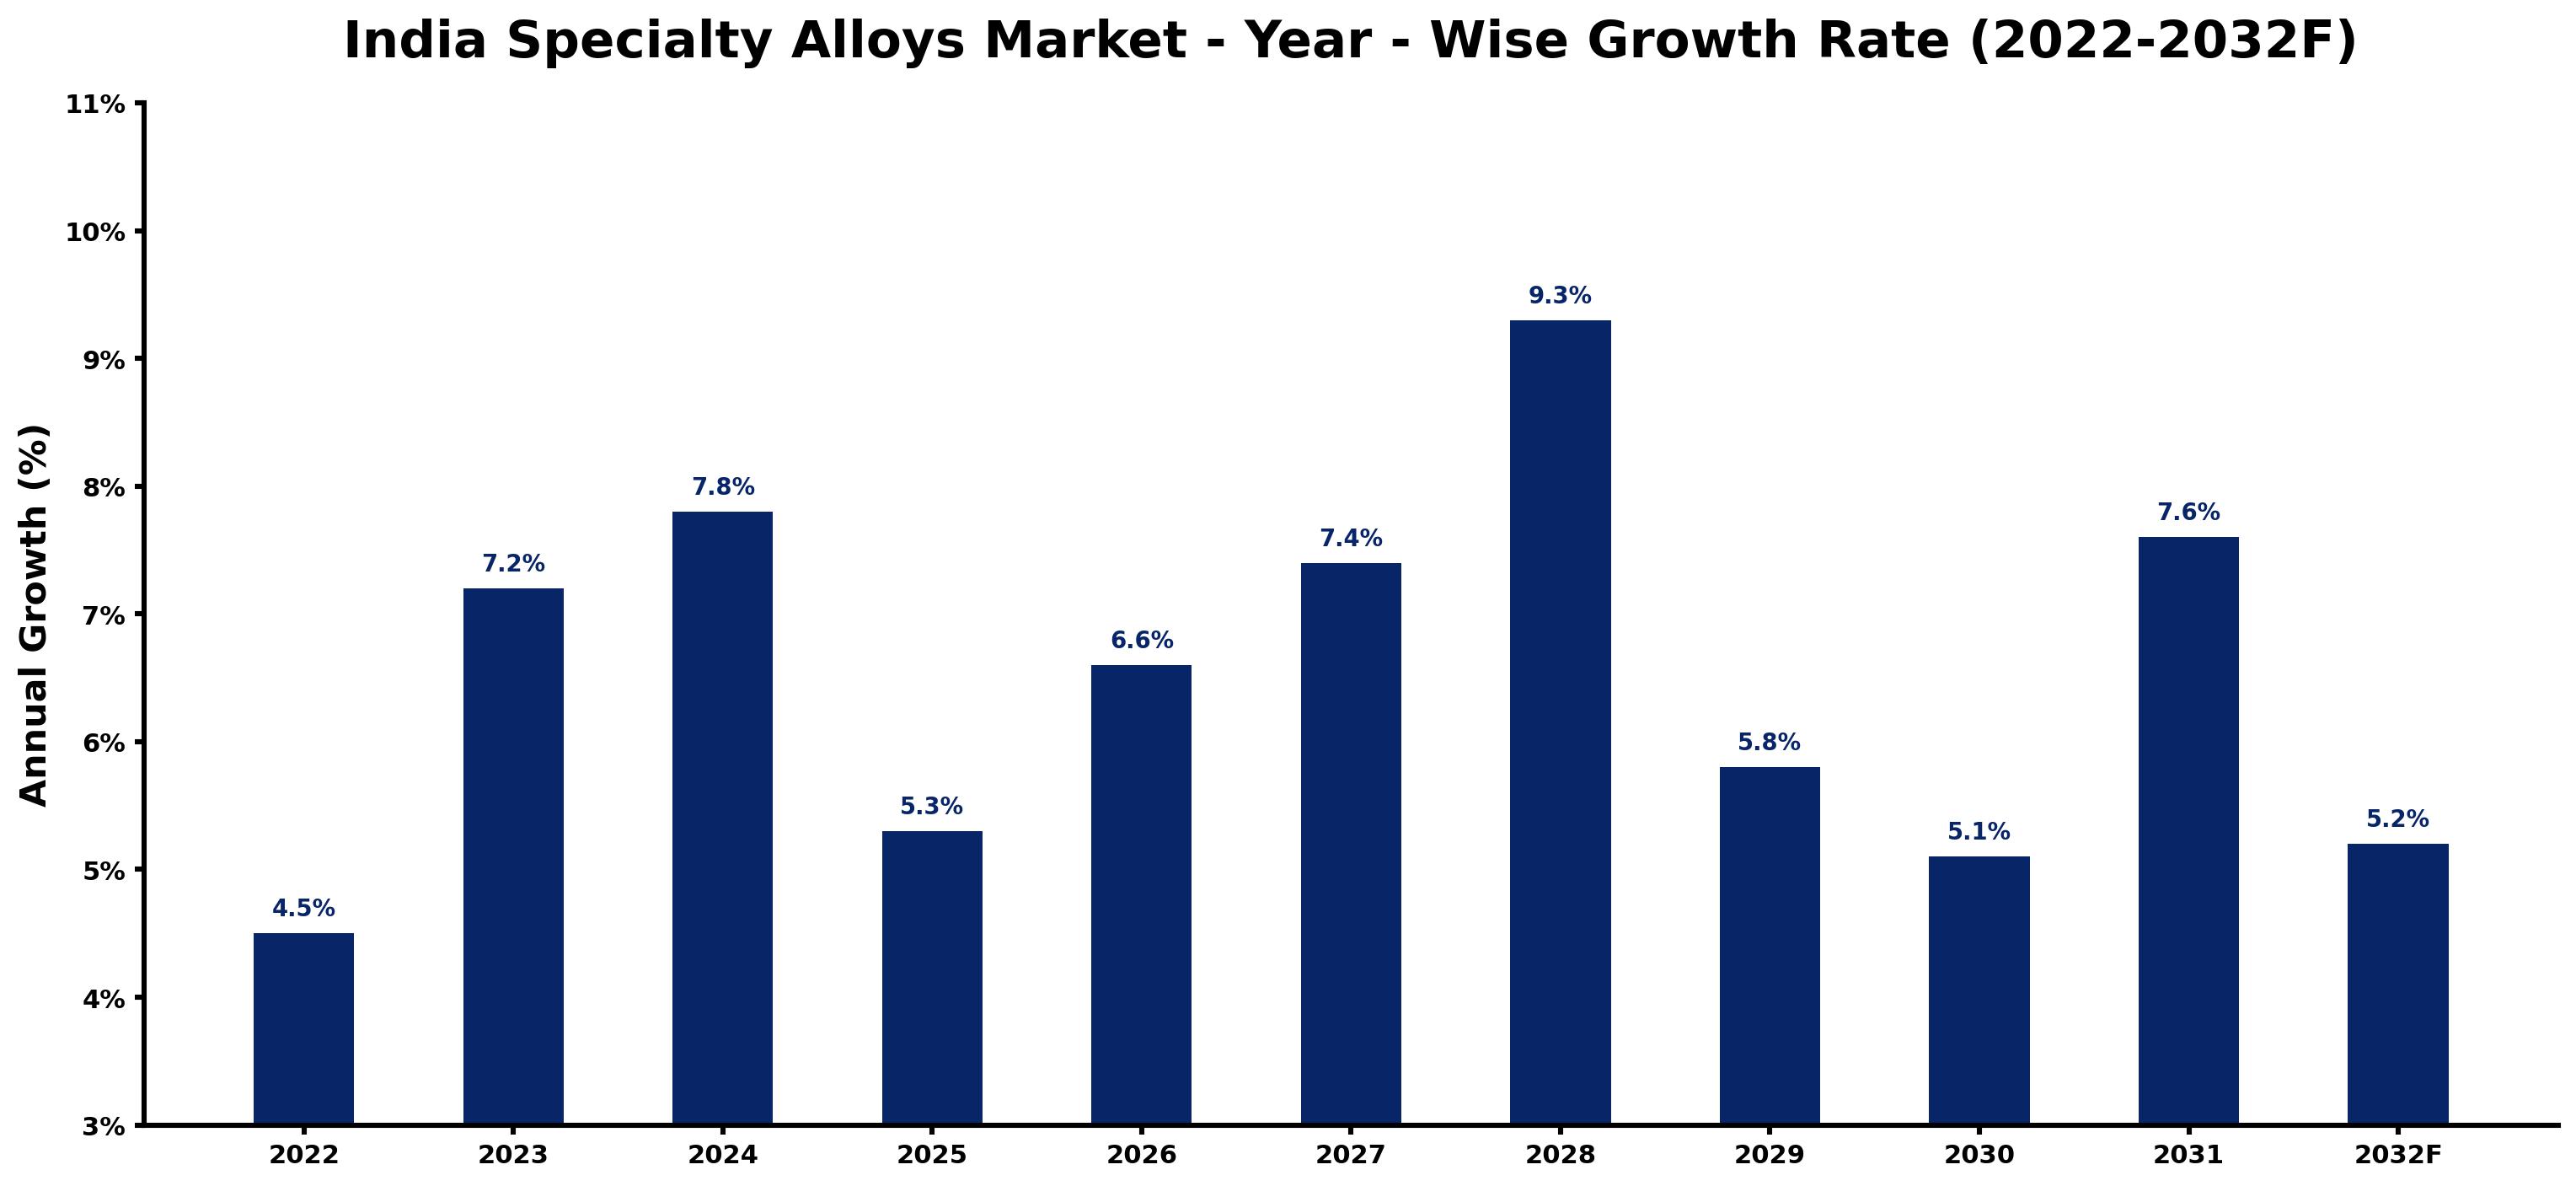
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.5 | The market experienced moderate growth due to steady demand from the aerospace sector. |
| 2023 | 7.2 | Growth accelerated as domestic manufacturers increased production capabilities for specialty alloys. |
| 2024 | 7.8 | Demand continued to rise, driven by significant investments in the aerospace industry. |
| 2025 | 5.3 | Growth slowed slightly as the market adjusted to production capacity limits. |
| 2026 | 6.6 | Demand picked up again with new projects in the automotive sector boosting alloy usage. |
| 2027 | 7.4 | The aerospace sector's expansion contributed to a resurgence in growth rates. |
| 2028 | 9.3 | Peak growth was achieved as the aerospace market surged, increasing alloy requirements. |
| 2029 | 5.8 | Growth moderated as the market stabilised after the peak demand in aerospace. |
| 2030 | 5.1 | A slowdown occurred as the aerospace sector faced temporary production challenges. |
| 2031 | 7.6 | Demand rebounded with aircraft manufacturers ramping up production capacity. |
| 2032 | 5.2 | Growth slowed again as the market reached a more stable phase. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Specialty Alloys Market Synopsis
The Specialty Alloys Market in India includes high-performance materials designed to endure extreme conditions, primarily utilised in aerospace, automotive, and medical applications. These alloys are created through melting, casting, and alloying processes. The market is expanding due to increasing demand from domestic manufacturers, especially in the aerospace and automotive sectors. The aerospace industry is projected to reach $70 billion by 2030, prompting further investment in specialty alloys. Additionally, the automotive sector is expected to grow to $300 billion by 2026, further driving the need for lightweight materials.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing aerospace sector and increased aircraft production | Driver | High | Aerospace |
| Rising demand for lightweight materials in automotive manufacturing | Driver | High | Automotive |
| Investment in advanced manufacturing technologies | Opportunity | High | Nickel Alloys |
| Increasing healthcare needs for medical implants | Opportunity | Medium | Medical Implants |
| High production costs for specialty alloys | Restraint | High | Nickel Alloys |
| Limited availability of raw materials for alloy production | Restraint | Medium | Titanium Alloys |
| Regulatory approvals can delay production timelines | Challenge | High | Aerospace |
| Competition from alternative materials can affect market share | Challenge | Medium | Automotive |
Evaluation of Drivers in India Specialty Alloys Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased aircraft production | Aerospace | The aerospace sector is expected to drive demand for specialty alloys as manufacturers ramp up production to meet market needs. |
| Growing automotive sector | Automotive | The Indian automotive industry is set to increase the need for lightweight materials in vehicle production, enhancing specialty alloy usage. |
| Rising healthcare demand for implants | Medical Implants | The medical implants market is anticipated to grow, boosting the usage of specialty alloys in biocompatible applications. |
| Investment in oil and gas projects | Oil & Gas | The Oil and Gas sector is projected to invest significantly in upstream projects, increasing demand for durable materials. |
| Focus on indigenous production | Nickel Alloys | The 'Make in India' initiative aims to improve domestic manufacturing capabilities for specialty alloys, enhancing local supply. |
Growth across the Specialty Alloys market in India is anchored in rising demand from various sectors, particularly aerospace and automotive. The aerospace industry is set to drive demand for specialty alloys as manufacturers ramp up production to meet market needs. The automotive sector is also expanding, increasing the need for lightweight materials in vehicle production. The medical implants market is anticipated to grow, boosting the usage of specialty alloys in biocompatible applications. Investment in oil and gas projects will contribute to this growth, as these sectors require durable materials for extreme conditions.
Evaluation of Restraints in India Specialty Alloys Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for specialty alloys | Nickel Alloys | Production costs can reach up to 30% higher than standard alloys, affecting pricing strategies for manufacturers. |
| Limited raw material availability | Titanium Alloys | Supply chain constraints have led to a 15% increase in raw material prices, impacting production schedules. |
| Regulatory compliance requirements | Aerospace | Manufacturers face delays due to stringent approval processes, which can extend time-to-market for new products. |
| Competition from alternative materials | Medical Implants | The growing use of alternative materials can limit the market share of specialty alloys. |
| Technological constraints in production | Aluminum Alloys | Current manufacturing technologies can limit the scalability of production, impacting supply and delivery timelines. |
India Specialty Alloys Market Challenges
The India Specialty Alloys Market contends with rising costs as buyers face fluctuating raw material prices, which can elevate production expenses by 15% for local manufacturers. Domestic producers find it challenging to compete with imported specialty alloys that are often priced lower, compelling them to reduce margins and threatening their sustainability. Supply chain issues, particularly in logistics, can delay deliveries by weeks, affecting production schedules for the automotive and aerospace sectors. Regulatory requirements from the Bureau of Indian Standards may prolong the approval timeline for new alloy compositions, potentially resulting in revenue losses for producers.
Trends in the India Specialty Alloys Market
Four trends stand out in the India Specialty Alloys Market.
- Shift towards Lightweight Alloys: There is an increasing preference for lightweight alloys in the automotive sector, spurred by fuel efficiency regulations. In 2022, the automotive industry produced 1.2 million tons of aluminium alloys, reflecting this trend.
- Increased Focus on Aerospace Standards: The National Aerospace and Defense Contractors Accreditation Program (NADCAP) has gained importance since 2021, ensuring quality in aerospace materials. This has resulted in a 20% increase in certified materials used in aircraft manufacturing.
- Growth in Medical Implant Applications: The medical implants market is growing rapidly, with projections indicating it will reach $10 billion by 2025. This demand is prompting manufacturers to innovate in biocompatible specialty alloys.
- Rising Investment in Oil and Gas: The Oil and Gas sector is anticipated to invest $25 billion in upstream projects by 2025, heightening the demand for corrosion-resistant specialty alloys.
Investment Opportunities in the India Specialty Alloys Market
Several openings in the India Specialty Alloys Market merit attention from investors.
- Supply of Lightweight Alloys: There is an opportunity to supply lightweight specialty alloys, particularly in the automotive sector, where demand is on the rise. The automotive industry is projected to reach $300 billion by 2026.
- Investment in Advanced Manufacturing: Now is an opportune time to invest in advanced manufacturing technologies for specialty alloys, as the market is set for substantial growth. The 'Production Linked Incentive Scheme' aims for a $10 billion investment by 2025.
- Partnerships for Aerospace Production: Forming partnerships with aerospace manufacturers can ease entry into this growing market. The aerospace sector's expected growth to $70 billion by 2030 presents a promising opportunity.
- Focus on Medical Implants: The medical implants market is expanding, creating a demand for specialised alloys. With a projected growth to $10 billion by 2025, suppliers can gain from entering this sector.
Government Initiatives in the India Specialty Alloys Market
The 'Production Linked Incentive Scheme' initiated by the Department of Heavy Industry in 2021 aims to boost the manufacturing of specialty alloys, targeting a $10 billion investment by 2025. This initiative supports domestic producers in meeting growing demand and improving quality standards. Additionally, the Ministry of Steel launched the 'National Steel Policy 2020', promoting the use of specialty alloys across various sectors and encouraging innovation in manufacturing processes.
The 'Make in India' initiative encourages local manufacturers to meet the stringent standards set by the Bureau of Indian Standards, improving quality assurance. The updated 'IS 1239' standard for specialty alloys ensures that products meet the necessary requirements for aerospace applications, facilitating smoother market entry for compliant manufacturers. The National Aerospace and Defense Contractors Accreditation Program (NADCAP) also plays a role in ensuring quality in aerospace materials.
Future Insight of the India Specialty Alloys Market
The India Specialty Alloys Market will undergo transformative changes by 2032, driven by advancements in manufacturing technologies and strong government initiatives. The 'Make in India' initiative will strengthen local production capabilities, allowing suppliers to meet domestic needs more effectively. The healthcare market for medical implants is projected to grow to $10 billion by 2025, opening new avenues for specialty alloy applications.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Alloy Type – Nickel Alloys Dominated, Titanium Alloys Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, with a 45% revenue share in 2025, Nickel Alloys was the largest alloy type category. Nickel alloys hold the largest share in the India Specialty Alloys Market due to their essential use in the oil and gas sector, where they provide superior corrosion resistance. The projected $25 billion investment in upstream projects by 2025 underscores the sustained demand for these high-performance materials. Over 2026–2032, Titanium Alloys are expected to post the fastest growth, at a CAGR of 8.9%. Titanium alloys are witnessing rapid growth, particularly in aerospace and medical applications where their high strength-to-weight ratios are crucial. The aerospace sector's expected expansion to $70 billion by 2030 will further drive the demand for titanium alloys, ensuring their market position strengthens. Suppliers need to focus on enhancing production capabilities to cater to the increasing demand for nickel and titanium alloys.
By Base Material – Nickel-Chromium Dominated, Titanium/Al-V Expected to Grow Fastest
In 2025, Nickel-Chromium led the base material split with a 46% share. Nickel-chromium alloys dominate the market due to their critical role in high-temperature applications within the oil and gas industry. Their established reliability under extreme conditions, coupled with significant sector investments, reinforces their leading position. Titanium/Al-V is set to record the highest CAGR in this split, 8.5% over 2026–2032. Titanium/Al-V materials are experiencing notable growth, especially in aerospace applications that demand exceptional performance characteristics. The anticipated growth of the aerospace industry will further elevate the reliance on these advanced materials, driving their market share upwards. Buyers should prioritise sourcing high-quality nickel-chromium and titanium/Al-V materials to meet industry standards and ensure optimal performance.
By Application Industry – Aerospace Dominated, Medical Implants Expected to Grow Fastest
The largest application industry category in 2025 was Aerospace, with a 38% share of total revenue. The aerospace industry commands the largest share of the market, driven by substantial demand for aircraft manufacturing and the need for advanced materials. With the aerospace sector in India projected to reach $70 billion by 2030, the reliance on specialty alloys is set to increase. Medical Implants are projected to grow fastest, at a CAGR of 9.4% during 2026–2032. Medical implants are the fastest-growing application, spurred by the rising demand for biocompatible materials in healthcare. The medical implants market in India is expected to grow to $10 billion by 2025, highlighting the need for specialty alloys in this sector. Suppliers must align their offerings with the growing needs of the medical implants sector to capture emerging opportunities.
By End User – Aircraft Manufacturers Dominated, Healthcare OEMs Expected to Grow Fastest
Aircraft Manufacturers accounted for a 40% market share by end user in 2025. Aircraft manufacturers are the largest end-user group, as they are the primary consumers of specialty alloys necessary for aircraft production. The substantial investments in the aerospace sector guarantee a consistent demand for these high-performance materials, solidifying their market share. The quickest growth will come from Healthcare OEMs, forecast to expand at a CAGR of 9.3% between 2026 and 2032. Healthcare OEMs are the fastest-growing end-users, driven by the increasing demand for specialised medical devices that require advanced materials. The healthcare sector's growth, particularly with over 1,500 hospitals focusing on orthopedic surgeries, significantly boosts this trend. Suppliers should strategically target healthcare OEMs to capitalise on the rising demand for specialty alloys in medical applications.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Specialty Alloys Market Outlook
- Market Size of India Specialty Alloys Market, 2025
- Forecast of India Specialty Alloys Market, 2032
- Historical Data and Forecast of India Specialty Alloys Revenues & Volume for the Period 2022 - 2032F
- India Specialty Alloys Market Trend Evolution
- India Specialty Alloys Market Drivers and Challenges
- India Specialty Alloys Price Trends
- India Specialty Alloys Porter's Five Forces
- India Specialty Alloys Industry Life Cycle
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Alloy Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Titanium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Nickel Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Cobalt Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Base Material for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Titanium/Al-V for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Nickel-Chromium for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Cobalt-Chrome for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Al-Zn-Mg-Cu for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Application Industry for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Oil & Gas for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Medical Implants for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Aircraft Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Turbine Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Healthcare OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Alloys Market Revenues & Volume By Vehicle Component Makers for the Period 2022 - 2032F
- India Specialty Alloys Import Export Trade Statistics
- Market Opportunity Assessment By Alloy Type
- Market Opportunity Assessment By Base Material
- Market Opportunity Assessment By Application Industry
- Market Opportunity Assessment By End User
- India Specialty Alloys Top Companies Market Share
- India Specialty Alloys Competitive Benchmarking By Technical and Operational Parameters
- India Specialty Alloys Company Profiles
- India Specialty Alloys Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Alloy Type
- Titanium Alloys
- Nickel Alloys
- Cobalt Alloys
- Aluminum Alloys
By Base Material
- Titanium/Al-V
- Nickel-Chromium
- Cobalt-Chrome
- Al-Zn-Mg-Cu
By Application Industry
- Aerospace
- Oil & Gas
- Medical Implants
- Automotive
By End User
- Aircraft Manufacturers
- Turbine Manufacturers
- Healthcare OEMs
- Vehicle Component Makers































