China Specialty Alloys Market Size & Growth Rate
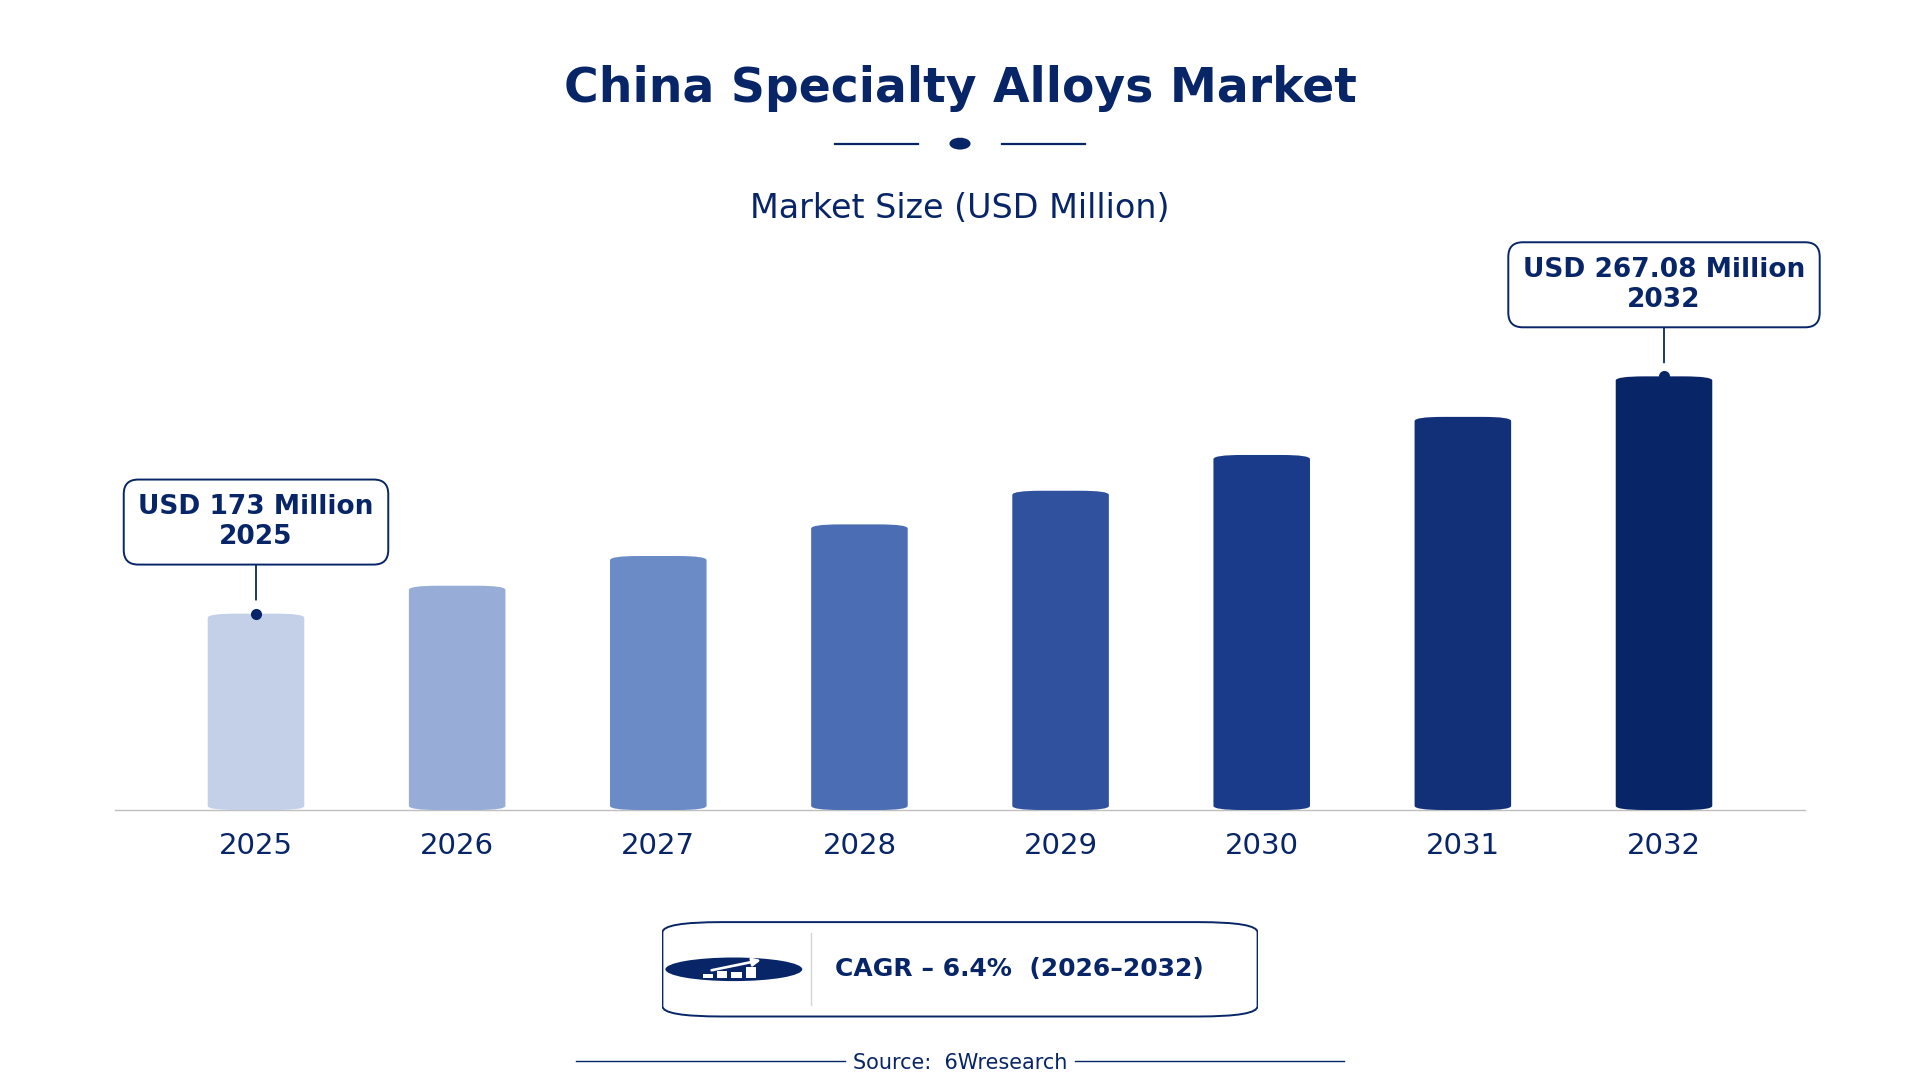
According to 6Wresearch internal database and industry insights, the China Specialty Alloys Market was valued at USD 173.0 million in 2025 and is projected to reach USD 267.08 million by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
China Specialty Alloys Market Highlights
| Report Metric | Details |
| Report Name | China Specialty Alloys Market |
| Market Size 2025 | USD 173.0 million |
| Market Size 2032 | USD 267.08 million |
| Absolute Growth 2025–2032 | USD 94.08 million |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 9.0% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Alloy Type, 2025 | Titanium Alloys (36% share) |
| Leading Base Material, 2025 | Titanium/Al-V (38% share) |
| Leading Application Industry, 2025 | Aerospace (42% share) |
| Leading End User, 2025 | Aircraft Manufacturers (36% share) |
| Fastest-Growing Alloy Type | Nickel Alloys (8.5% CAGR) |
| Fastest-Growing Base Material | Nickel-Chromium (8.2% CAGR) |
| Fastest-Growing Application Industry | Medical Implants (8.2% CAGR) |
| Fastest-Growing End User | Healthcare OEMs (7.6% CAGR) |
| Growing Sector | Medical Implants |
| Key End Users | Aerospace, Oil & Gas, Automotive, Medical Implants |
China Specialty Alloys Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
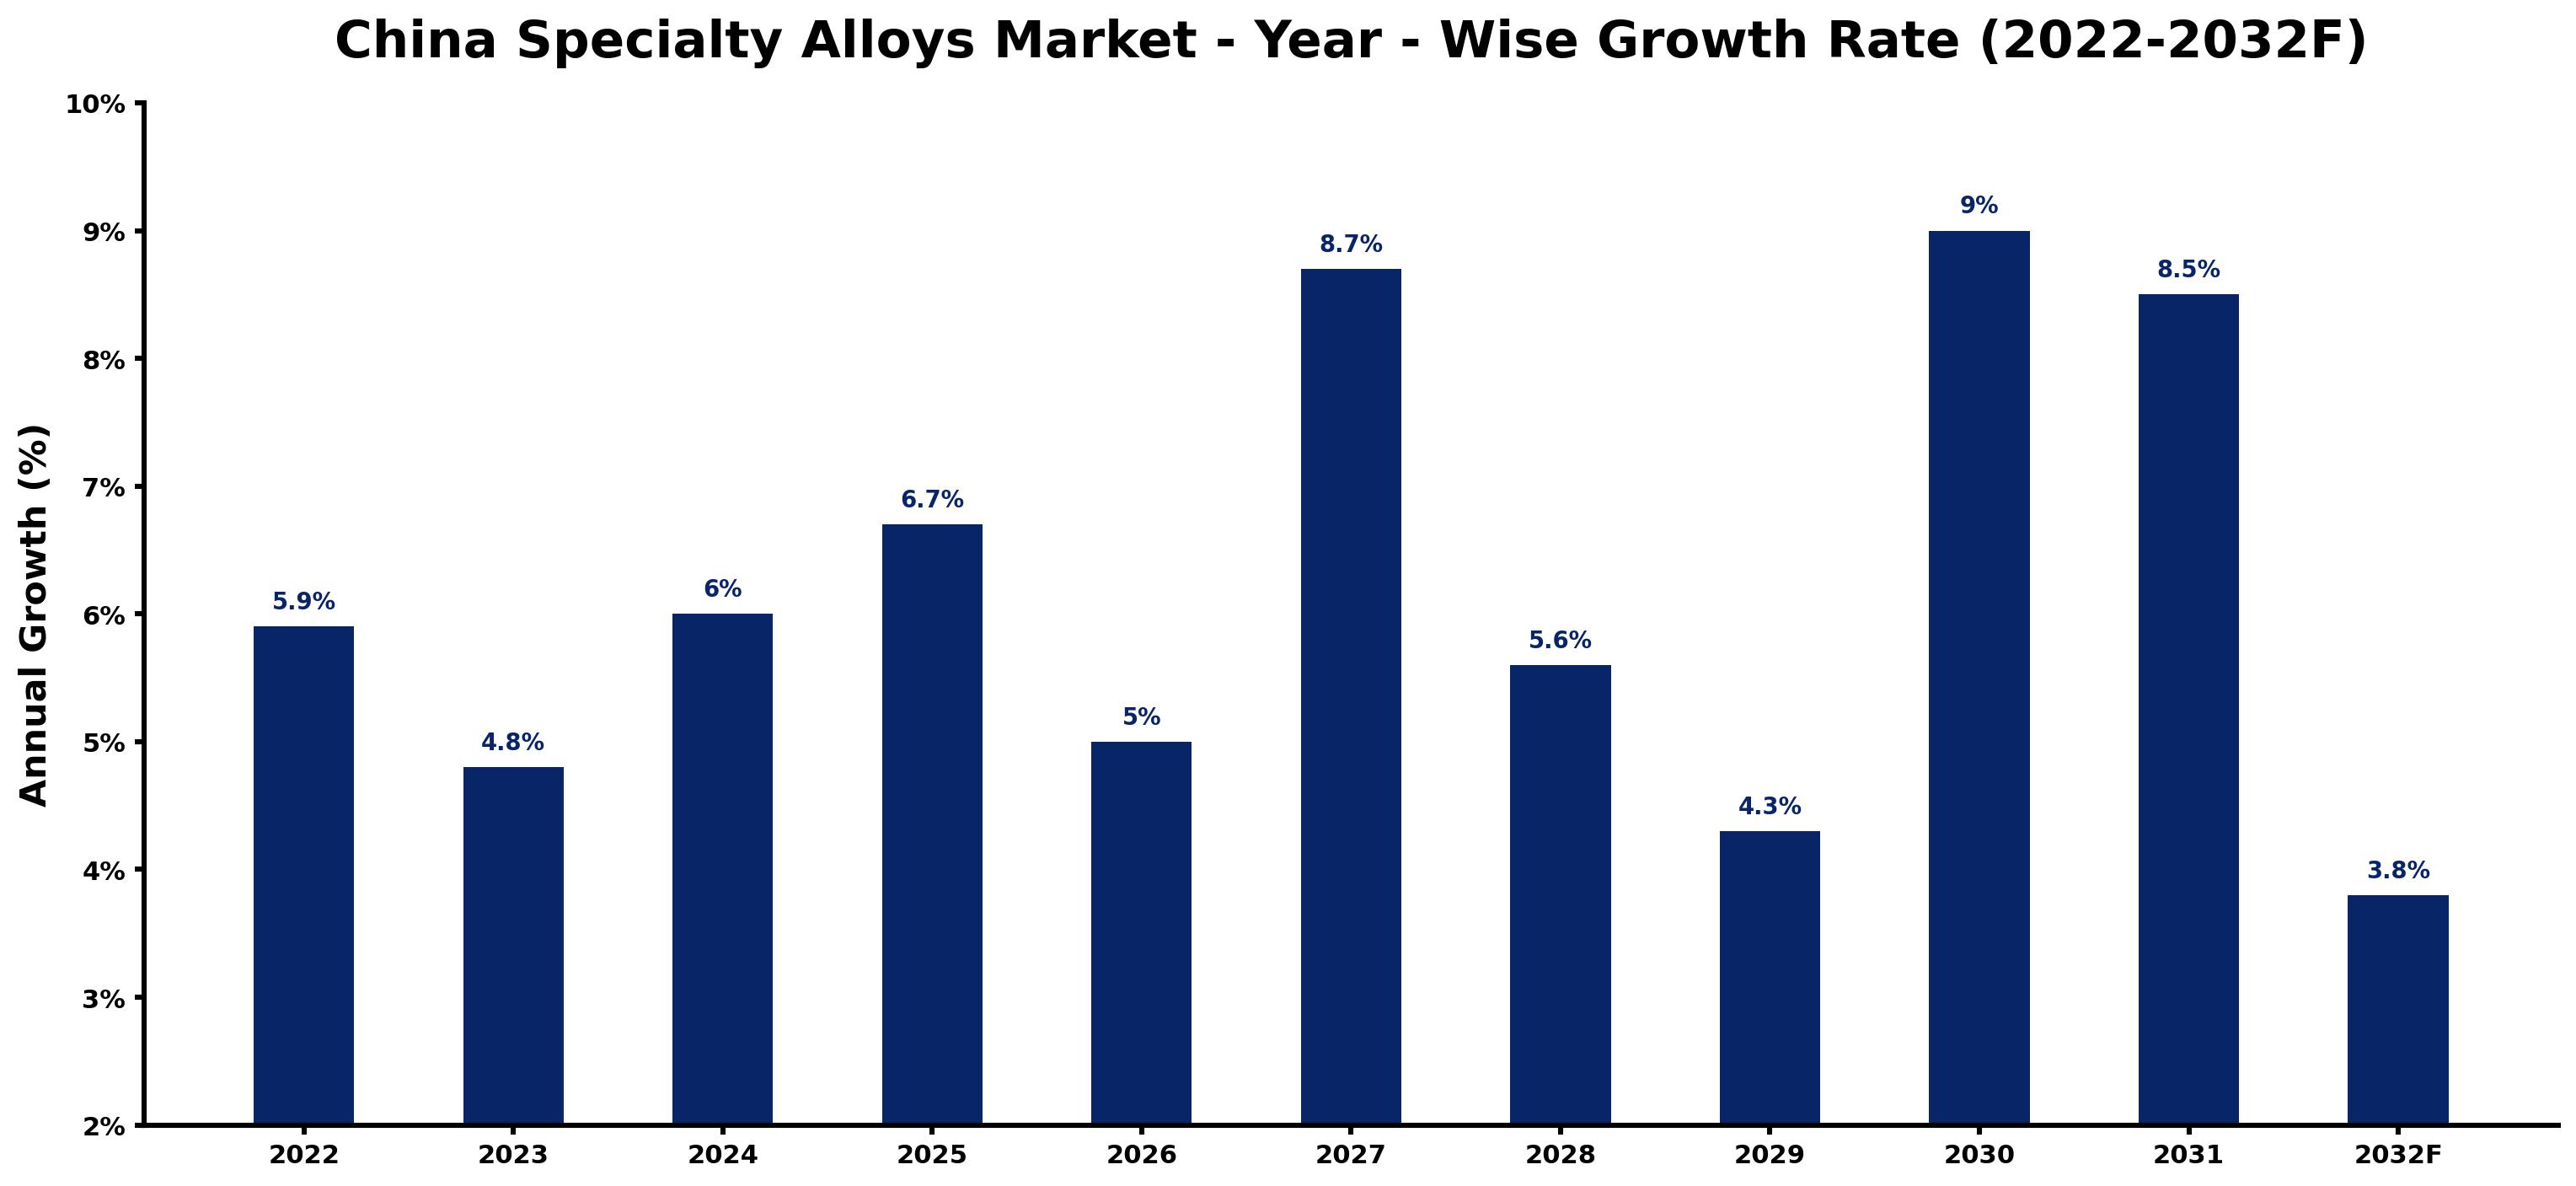
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.9 | Demand from the aerospace sector remained strong, supporting growth in specialty alloys. |
| 2023 | 4.8 | Growth slowed due to supply chain disruptions affecting the aerospace industry. |
| 2024 | 6.0 | Increased production of vehicles boosted demand for aluminum alloys in automotive. |
| 2025 | 6.7 | Aerospace requirements surged, leading to higher consumption of titanium alloys. |
| 2026 | 5.0 | Demand stabilised as manufacturers adjusted to market conditions and supply chains. |
| 2027 | 8.7 | Recovery in aerospace and automotive sectors drove a significant rise in demand. |
| 2028 | 5.6 | Market growth slowed as competition intensified among specialty alloy producers. |
| 2029 | 4.3 | Demand decreased slightly due to fluctuations in the oil and gas sector. |
| 2030 | 9.0 | Aerospace sector's expansion led to a peak in titanium alloy requirements. |
| 2031 | 8.5 | Growth slowed as the market adjusted to new production capacities. |
| 2032 | 3.8 | Demand stabilisation is expected as industries mature and technology evolves. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Specialty Alloys Market Synopsis
Specialty Alloys Market in China includes advanced materials tailored for specific applications, primarily produced through melting and alloying processes. These alloys play a crucial role in sectors such as aerospace, oil and gas, and medical implants. The Specialty Alloys Market is growing due to strong domestic demand from local manufacturers, especially in aerospace and automotive sectors. The aerospace industry is expected to require 50,000 tons of titanium alloys by 2025, driving notable growth. Additionally, the automotive sector's rising production further stimulates demand for lightweight aluminum alloys.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing demand from the aerospace sector drives the need for high-performance titanium alloys. | Driver | High | Titanium Alloys |
| Increasing investments in offshore drilling enhance the demand for nickel alloys in oil and gas. | Driver | High | Nickel Alloys |
| The rising medical implants market presents opportunities for titanium and cobalt alloys. | Opportunity | High | Medical Implants |
| The Guangdong province's focus on aluminum alloy production creates new market avenues. | Opportunity | Medium | Aluminum Alloys |
| Quality control challenges can hinder the production of specialty alloys. | Restraint | High | Titanium Alloys |
| Supply chain disruptions may affect timely delivery of raw materials. | Restraint | Medium | Nickel Alloys |
| Technological advancements in alloy production require continuous investment. | Challenge | High | Cobalt Alloys |
| Competition from low-cost producers in the region pressures pricing strategies. | Challenge | Medium | Aluminum Alloys |
Evaluation of Drivers in China Specialty Alloys Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Strong demand from aircraft manufacturers for lightweight materials increases titanium alloy consumption. | Titanium Alloys | In 2025, the aerospace sector is expected to require 50,000 tons of titanium alloys. |
| The oil and gas industry's expansion necessitates corrosion-resistant nickel alloys. | Nickel Alloys | China's oil and gas sector is projected to invest 100 billion USD in new technologies by 2025. |
| The growing automotive sector drives the need for aluminum alloys in vehicle production. | Aluminum Alloys | China produces over 25 million vehicles annually, boosting aluminum alloy demand. |
| Rising healthcare needs increase the demand for medical implants made from specialty alloys. | Medical Implants | The medical implants market in China is projected to reach 10 billion USD by 2025. |
| Regulatory standards enhance the quality of specialty alloys, driving demand for compliant products. | Titanium Alloys | National Standard GB/T 14957-2018 governs the quality of titanium alloys in China. |
The Specialty Alloys market in China is expanding as demand from aircraft manufacturers, the automotive sector, and the healthcare industry rises. The aerospace sector will require 50,000 tons of titanium alloys by 2025, driving purchases from specialty alloy producers. The automotive industry, producing over 25 million vehicles annually, increasingly utilises aluminum alloys to improve fuel efficiency. Rising healthcare needs will increase the demand for medical implants made from specialty alloys. Investments in the oil and gas sector, with an anticipated 100 billion USD in new technologies by 2025, will also boost demand for nickel alloys.
Evaluation of Restraints in China Specialty Alloys Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Fluctuating raw material prices increase production costs for manufacturers. | Titanium Alloys | Rising costs can increase production expenses by as much as 15%. |
| Technology gaps hinder local producers from adopting advanced manufacturing processes. | Nickel Alloys | This delay affects product development timelines for buyers in key sectors. |
| Supply chain disruptions lead to delays in fulfilling orders for specialty alloys. | Aluminum Alloys | Delays can extend up to three months for suppliers sourcing from remote regions. |
| Intense competition from international markets pressures local producers to lower prices. | Medical Implants | This can erode profit margins by approximately 10% for those unable to innovate. |
| Limited access to advanced manufacturing technologies restricts production capacity. | Cobalt Alloys | This limitation affects the ability to meet growing market demands. |
China Specialty Alloys Market Challenges
Producers in the China specialty alloys market face rising costs due to volatile raw material prices, which can increase production expenses by up to 15%. Many local manufacturers struggle with outdated technology, resulting in delays of up to six months for buyers needing advanced alloys for aerospace applications. Supply chain disruptions frequently occur, especially for alloys sourced from remote regions, causing potential delays of three months for suppliers fulfilling critical orders. Intense competition from international markets pressures local producers to lower prices, which can reduce profit margins by approximately 10% for those unable to adapt.
Trends in the China Specialty Alloys Market
Buyers and suppliers in the China Specialty Alloys Market are adjusting to the following trends.
- Shift Towards Lightweight Materials: China is increasingly adopting lightweight materials in aerospace applications, particularly titanium alloys. The aerospace sector is expected to require 50,000 tons of titanium alloys by 2025, improving aircraft performance.
- Growing Demand for Medical Implants: The medical implants market in China is evolving, with a projected value of 10 billion USD by 2025. This growth is driving increased demand for specialty alloys, particularly titanium and cobalt.
- Expansion of Automotive Lightweighting: The automotive industry is shifting towards lightweight structures to improve fuel efficiency. With over 25 million vehicles produced annually, the demand for aluminum alloys is set to rise significantly.
- Investment in Advanced Manufacturing Technologies: The oil and gas industry is investing heavily in new technologies, projected at 100 billion USD by 2025. This investment will drive demand for corrosion-resistant nickel alloys.
Investment Opportunities in the China Specialty Alloys Market
Investors looking at the China Specialty Alloys Market should consider the following areas.
- Guangdong Province as an Alloy Production Hub: Guangdong province is a key region for aluminum alloy production, with a growing demand for lightweight materials. Investing in local partnerships can facilitate entry into this market.
- Joint Ventures in Aerospace Manufacturing: Now is an opportune time for joint ventures in aerospace manufacturing, given the projected need for 50,000 tons of titanium alloys by 2025. Collaborating with local manufacturers can improve market access.
- Healthcare Sector Expansion: The healthcare sector is experiencing growth, with the medical implants market projected to reach 10 billion USD by 2025. Suppliers can enter this market through certifications and partnerships with healthcare OEMs.
- Oil and Gas Sector Investment Opportunities: With an anticipated investment of 100 billion USD in new technologies by 2025, there are opportunities for suppliers of specialty alloys in the oil and gas sector. Engaging with local producers can facilitate market entry.
Government Initiatives in the China Specialty Alloys Market
In 2020, the National Development and Reform Commission updated the 'Industrial Structure Adjustment Guidance Catalog' to promote the use of high-performance alloys in key industries. This measure encourages manufacturers to adopt advanced materials, improving production capabilities in the specialty alloys sector. In 2021, the Ministry of Industry and Information Technology launched the 'Advanced Materials Industry Development Plan' aiming to increase specialty alloy production by 30% by 2025. This initiative supports local manufacturers in meeting rising domestic demand. In 2022, the State Administration for Market Regulation implemented the 'Quality Supervision and Inspection Measures for Specialty Alloys' to ensure product standards. This regulation mandates compliance with quality benchmarks, benefiting both producers and buyers. The Ministry of Science and Technology initiated the 'National Key R&D Program for Advanced Materials' in 2023, focusing on innovative alloy development with a budget of 500 million RMB. This funding supports research initiatives that can lead to advancements in specialty alloys.
In 2022, the State Administration for Market Regulation implemented the 'Quality Supervision and Inspection Measures for Specialty Alloys' to ensure product standards. This regulation mandates compliance with quality benchmarks, benefiting both producers and buyers. The Ministry of Science and Technology initiated the 'National Key R&D Program for Advanced Materials' in 2023, focusing on innovative alloy development with a budget of 500 million RMB. This funding supports research initiatives that can lead to advancements in specialty alloys.
Future Insight of the China Specialty Alloys Market
The China specialty alloys market is set to evolve by 2032, influenced by substantial advancements in manufacturing processes and increased government support for research and development. The aerospace sector's demand for titanium alloys will reach 50,000 tons by 2025, highlighting the industry's growth. Enhanced initiatives to promote advanced materials will strengthen local production capabilities. Furthermore, the oil and gas sector's planned investment of 100 billion USD in new technologies will create further opportunities for specialty alloys designed for offshore drilling.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Alloy Type – Titanium Alloys Dominated, Nickel Alloys Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Titanium Alloys took a 36% share of alloy type in 2025, more than any other category. Titanium alloys hold a dominant share in the China Specialty Alloys Market due to their indispensable role in aerospace applications, where their strength-to-weight ratio is crucial. The aerospace sector's anticipated need for 50,000 tons of titanium alloys by 2025 highlights their importance in this industry. Nickel Alloys are set to record the highest CAGR in this split, 8.5% over 2026–2032. Nickel alloys are experiencing rapid growth, particularly in the oil and gas sector, where their corrosion resistance is essential for offshore drilling operations. With projected investments of 100 billion USD in new technologies by 2025, the demand for nickel alloys is set to surge. Suppliers should concentrate on developing nickel alloys to cater to the escalating needs of the oil and gas industry.
By Base Material – Titanium/Al-V Dominated, Nickel-Chromium Expected to Grow Fastest
Titanium/Al-V accounted for a 38% market share by base material in 2025. Titanium/Al-V alloys command a significant share in the market due to their high strength, making them vital for aerospace applications. The ongoing expansion of the aerospace sector, which heavily relies on these materials for aircraft manufacturing, reinforces their leading position. Nickel-Chromium is projected to grow fastest, at a CAGR of 8.2% during 2026–2032. Nickel-Chromium alloys are witnessing swift growth, driven by their essential role in high-temperature applications within the oil and gas industry. The increasing emphasis on advanced materials in this sector is likely to accelerate their adoption further. Manufacturers should focus on investing in Nickel-Chromium alloys to meet the rising demand in high-temperature applications.
By Application Industry – Aerospace Dominated, Medical Implants Expected to Grow Fastest
Aerospace held a 42% share of the China Specialty Alloys Market by application industry in 2025. The aerospace industry holds the largest share in the specialty alloys market, primarily due to its extensive use of advanced materials for aircraft construction. This sector's dominance is supported by the continuous expansion of China's aerospace capabilities and production. Over 2026–2032, Medical Implants are expected to post the fastest growth, at a CAGR of 8.2%. Medical implants are emerging as the fastest-growing application for specialty alloys, driven by the increasing demand for advanced healthcare solutions. The projected growth of the medical implants market to 10 billion USD by 2025 highlights this trend. Suppliers should consider expanding their product lines to cater to the growing medical implants sector.
By End User – Aircraft Manufacturers Dominated, Healthcare OEMs Expected to Grow Fastest
The largest end user category in 2025 was Aircraft Manufacturers, with a 36% share of total revenue. Aircraft manufacturers represent the largest share of the market as they extensively utilise specialty alloys in aircraft construction due to their performance characteristics. This robust demand from the aerospace sector solidifies their leading position in the specialty alloys market. The quickest growth will come from Healthcare OEMs, forecast to expand at a CAGR of 7.6% between 2026 and 2032. Healthcare OEMs are rapidly growing as they increasingly integrate specialty alloys into medical devices. The rising population and demand for healthcare products in China are significant factors propelling this growth. Suppliers should aim to establish partnerships with healthcare OEMs to capitalise on the increasing demand for specialty alloys in medical applications.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Specialty Alloys Market Outlook
- Market Size of China Specialty Alloys Market, 2025
- Forecast of China Specialty Alloys Market, 2032
- Historical Data and Forecast of China Specialty Alloys Revenues & Volume for the Period 2022 - 2032F
- China Specialty Alloys Market Trend Evolution
- China Specialty Alloys Market Drivers and Challenges
- China Specialty Alloys Price Trends
- China Specialty Alloys Porter's Five Forces
- China Specialty Alloys Industry Life Cycle
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Alloy Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Titanium Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Nickel Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Cobalt Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Base Material for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Titanium/Al-V for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Nickel-Chromium for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Cobalt-Chrome for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Al-Zn-Mg-Cu for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Application Industry for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Aerospace for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Oil & Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Medical Implants for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Automotive for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Aircraft Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Turbine Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Healthcare OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Specialty Alloys Market Revenues & Volume By Vehicle Component Makers for the Period 2022 - 2032F
- China Specialty Alloys Import Export Trade Statistics
- Market Opportunity Assessment By Alloy Type
- Market Opportunity Assessment By Base Material
- Market Opportunity Assessment By Application Industry
- Market Opportunity Assessment By End User
- China Specialty Alloys Top Companies Market Share
- China Specialty Alloys Competitive Benchmarking By Technical and Operational Parameters
- China Specialty Alloys Company Profiles
- China Specialty Alloys Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Alloy Type
- Titanium Alloys
- Nickel Alloys
- Cobalt Alloys
- Aluminum Alloys
By Base Material
- Titanium/Al-V
- Nickel-Chromium
- Cobalt-Chrome
- Al-Zn-Mg-Cu
By Application Industry
- Aerospace
- Oil & Gas
- Medical Implants
- Automotive
By End User
- Aircraft Manufacturers
- Turbine Manufacturers
- Healthcare OEMs
- Vehicle Component Makers































