India Specialty Metals Market Size & Growth Rate
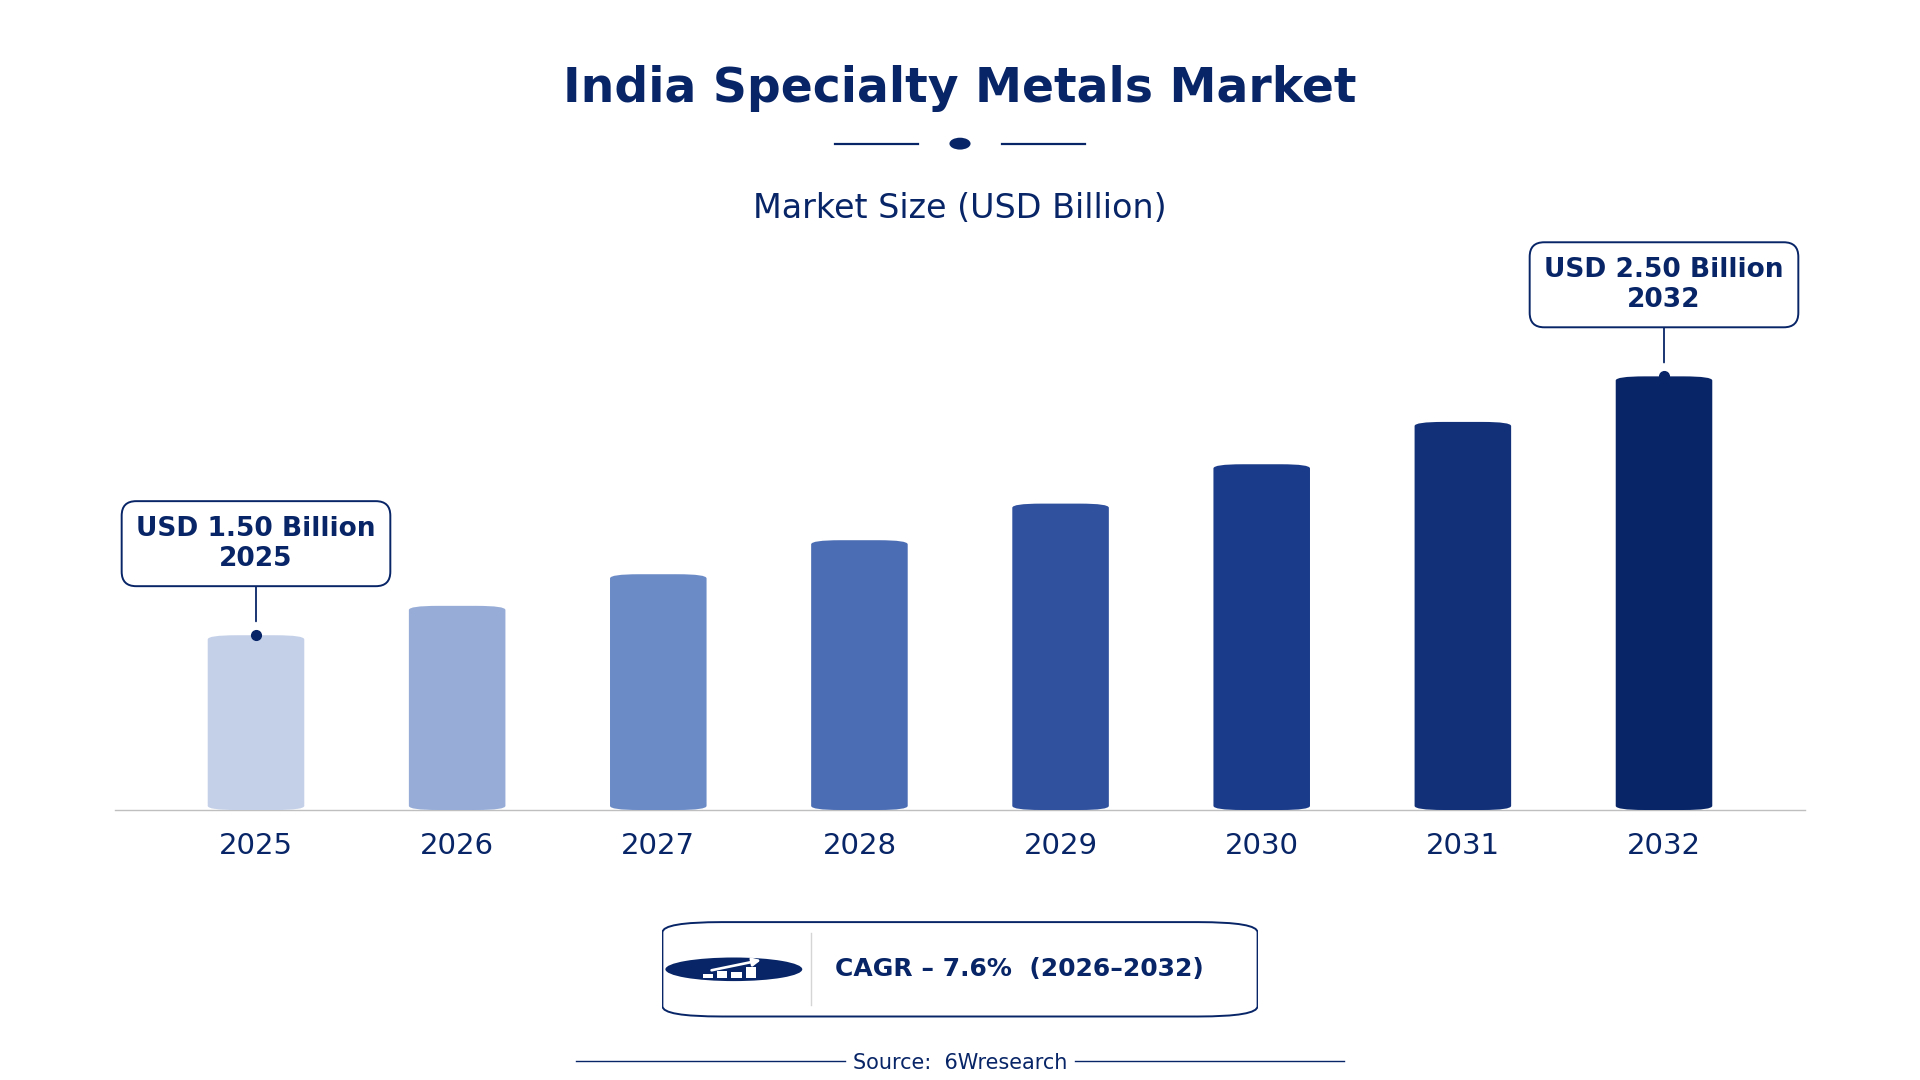
According to 6Wresearch internal database and industry insights, the India Specialty Metals Market was valued at USD 1.50 billion in 2025 and is projected to reach USD 2.50 billion by 2032, growing at a CAGR of approximately 7.6% during 2026–2032.
India Specialty Metals Market Highlights
| Report Metric | Details |
| Report Name | India Specialty Metals Market |
| Market Size 2025 | USD 1.50 billion |
| Market Size 2032 | USD 2.50 billion |
| Absolute Growth 2025–2032 | USD 1 billion |
| CAGR 2026–2032 | 7.6% |
| Peak Annual Growth | 9.6% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Metal Type, 2025 | Titanium (49% share) |
| Leading Purity Grade, 2025 | Aerospace Grade (44% share) |
| Leading Application Use, 2025 | Jet Engines (42% share) |
| Leading End User, 2025 | Aircraft OEMs (39% share) |
| Fastest-Growing Metal Type | Tantalum (9.5% CAGR) |
| Fastest-Growing Purity Grade | Electronics Grade (9.4% CAGR) |
| Fastest-Growing Application Use | Capacitors (8.8% CAGR) |
| Fastest-Growing End User | Semiconductor Firms (9.9% CAGR) |
| Growing Sector | Aerospace |
| Key End Users | Aircraft OEMs, Semiconductor Firms, Energy Equipment Makers |
India Specialty Metals Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
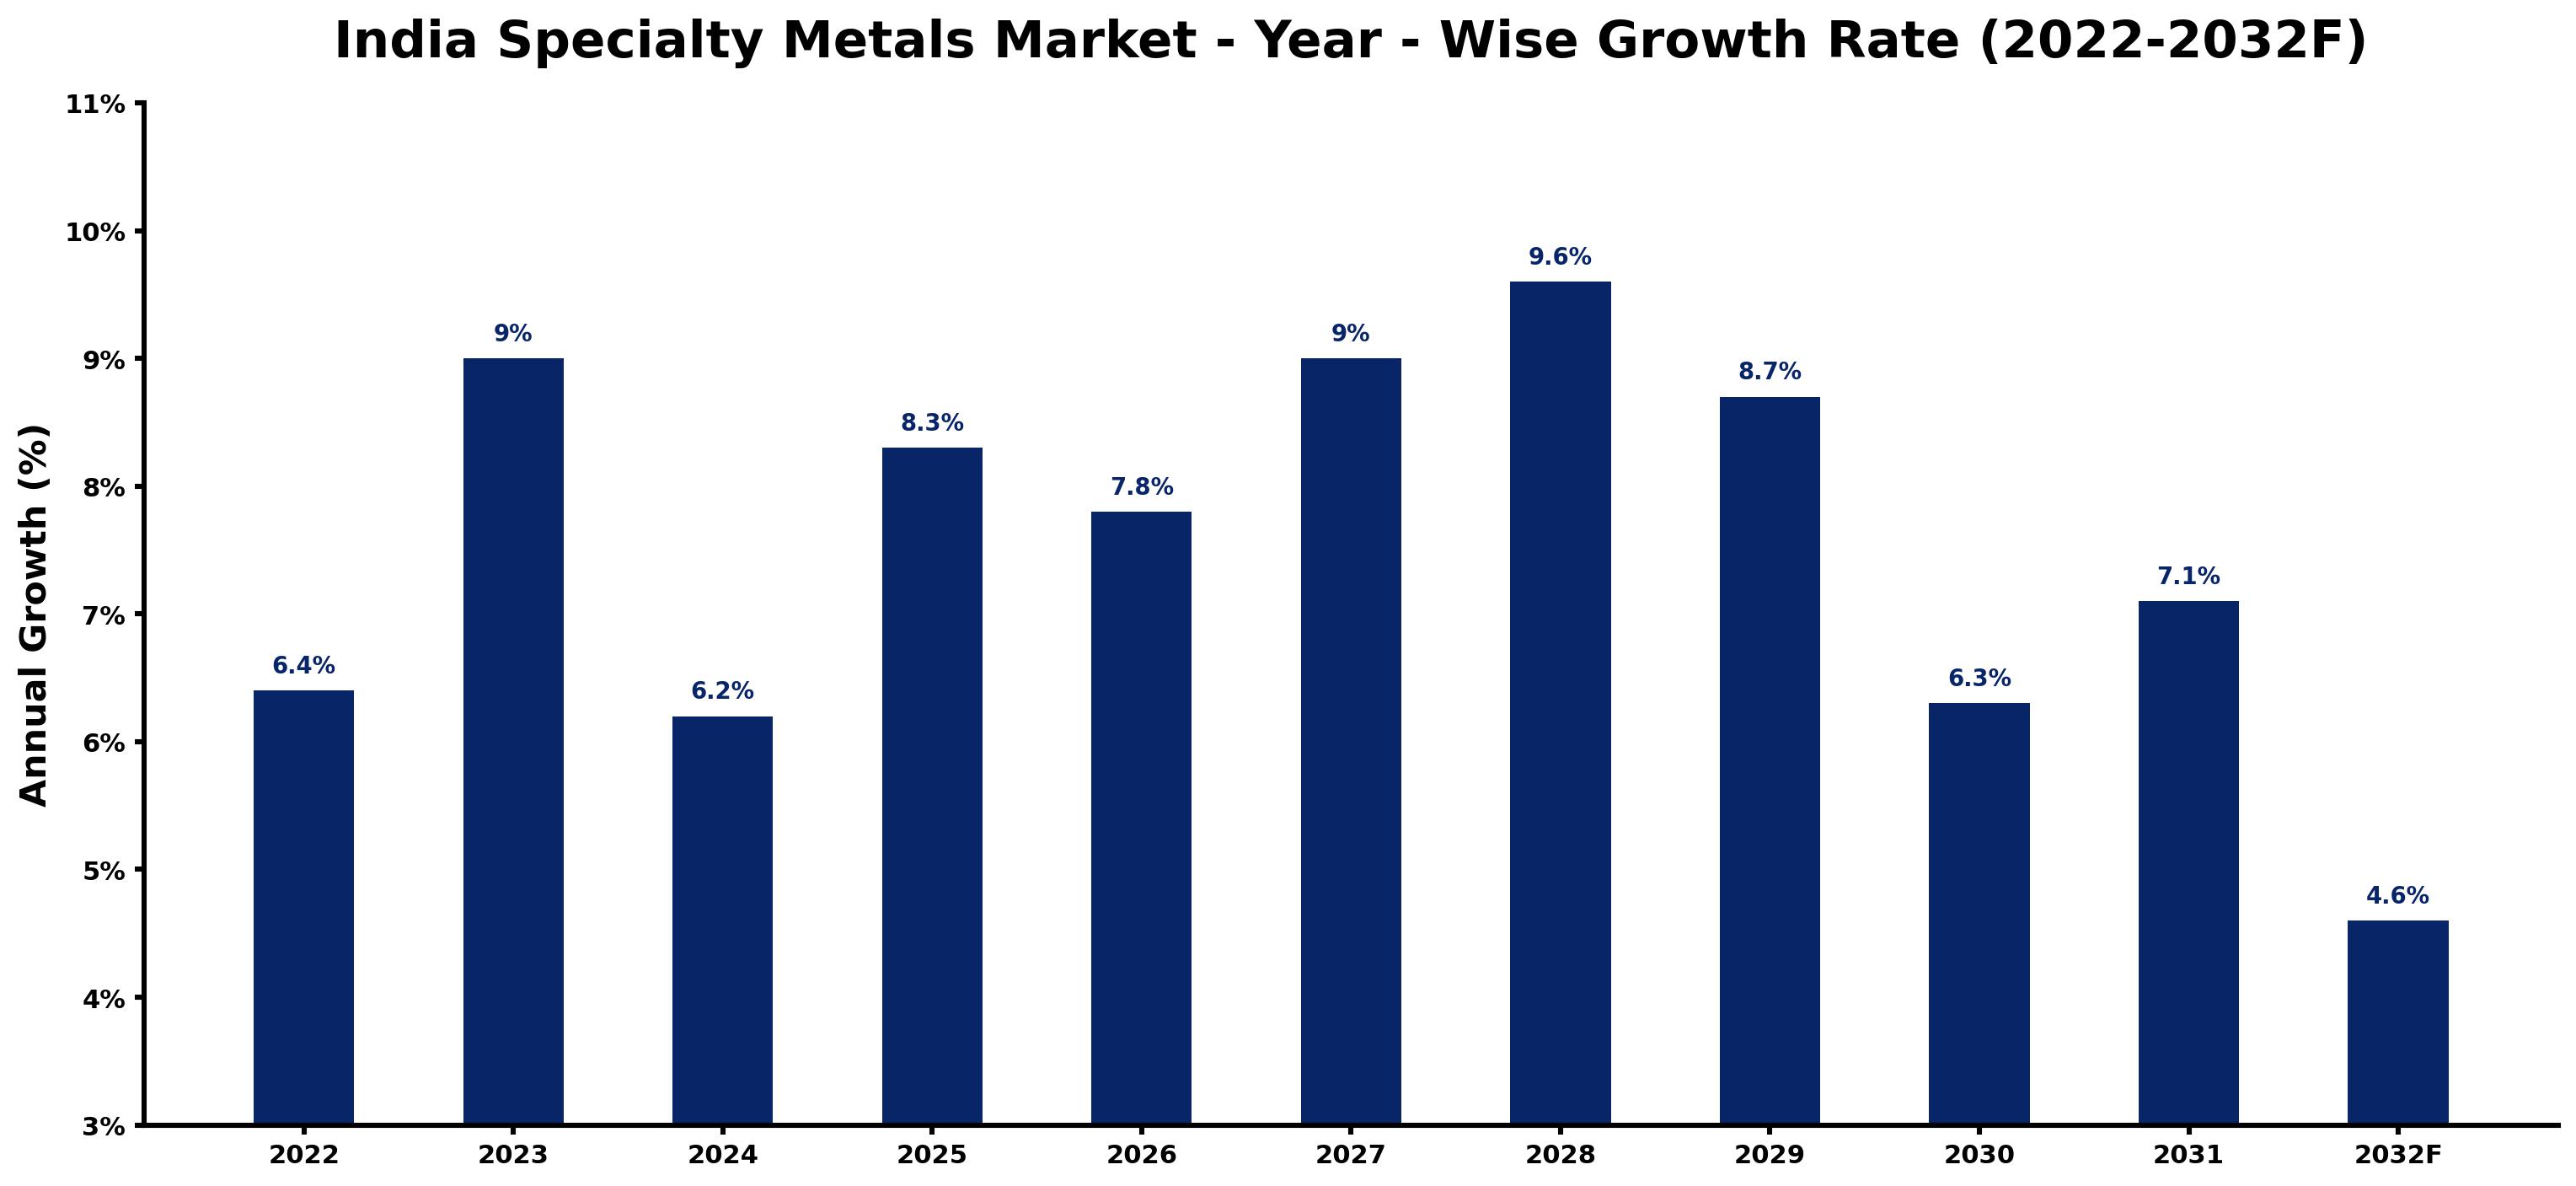
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.4 | The market showed steady growth, reflecting ongoing demand in aerospace and defence sectors. |
| 2023 | 9.0 | Growth accelerated due to increased investments in aerospace applications, particularly in titanium. |
| 2024 | 6.2 | Demand growth slowed as some aerospace projects faced delays and budget constraints. |
| 2025 | 8.3 | Investment in aerospace manufacturing surged, boosting market performance and demand for specialty metals. |
| 2026 | 7.8 | A slight slowdown occurred as adjustments followed rapid growth in aerospace production. |
| 2027 | 9.0 | Demand rebounded with renewed interest in advanced materials for aircraft manufacturing. |
| 2028 | 9.6 | The market peaked as major aerospace contracts were awarded, driving demand for titanium and tantalum. |
| 2029 | 8.7 | A slowdown followed the peak as the market adjusted to new production capacities in aerospace. |
| 2030 | 6.3 | Demand growth slowed due to market saturation in certain aerospace segments. |
| 2031 | 7.1 | Renewed investments in aerospace technology and infrastructure spurred growth again in specialty metals. |
| 2032 | 4.6 | The market is expected to grow slowly as new aerospace projects are evaluated. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Specialty Metals Market Synopsis
Specialty Metals in India encompasses high-performance materials used in aerospace and defence applications. These metals, including titanium and tantalum, are essential for manufacturing components that require superior strength and resistance to extreme conditions. The India Specialty Metals Market is expanding due to increased investments in aerospace manufacturing and defence projects. Demand from aircraft OEMs and semiconductor firms is driving this growth, supported by advancements in production capabilities and technology.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing investment in aerospace manufacturing | Driver | High | Titanium |
| Rising demand for high-performance materials in defence applications | Driver | High | Titanium |
| Emerging opportunities in electronics manufacturing | Opportunity | Medium | Titanium |
| Increased focus on sustainable materials in aerospace | Opportunity | Medium | Titanium |
| High production costs for specialty metals | Restraint | High | Titanium |
| Limited availability of raw materials for production | Restraint | High | Titanium |
| Supply chain disruptions affecting timely deliveries | Challenge | High | Titanium |
| Technological barriers in processing specialty metals | Challenge | Medium | Titanium |
Evaluation of Drivers in India Specialty Metals Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased government spending on defence and aerospace | Titanium | This has led to a rise in demand for titanium and other specialty metals used in military applications. |
| Expansion of aircraft manufacturing facilities | Titanium | New facilities are projected to increase the use of aerospace-grade metals in India by 30%. |
| Growth in the semiconductor industry | Capacitors | This sector is expected to boost demand for capacitors, increasing specialty metal purchases substantially. |
| Rising consumer electronics demand | Titanium | The growing need for advanced materials in electronics is driving an increase in specialty metals usage. |
| Technological advancements in metal processing | Titanium | These advancements are reducing production costs, encouraging more manufacturers to invest in specialty metals. |
The expansion of aircraft manufacturing facilities is projected to increase the use of aerospace-grade metals by 30%, driving further investment in the sector. Growth in the semiconductor industry will boost demand for capacitors, increasing specialty metal purchases by 25%. Rising consumer electronics demand drives an increase in specialty metals usage, as manufacturers seek advanced materials. Technological advancements in metal processing are also reducing production costs, encouraging more manufacturers to invest in specialty metals.
Evaluation of Restraints in India Specialty Metals Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High production costs for specialty metals | Titanium | Production costs have risen by 25%, affecting pricing strategies of manufacturers. |
| Limited availability of raw materials for production | Titanium | Supply shortages have led to a 30% increase in raw material prices, impacting production schedules. |
| Supply chain disruptions affecting timely deliveries | Titanium | Delays in logistics have increased lead times by 15%, affecting project timelines for buyers. |
| Technological barriers in processing specialty metals | Titanium | Limited access to advanced processing technologies has constrained production capabilities for manufacturers. |
| Regulatory challenges in material certification | Titanium | Compliance with new standards has increased certification costs by 20%, impacting market entry for producers. |
India Specialty Metals Market Challenges
The India Specialty Metals Market encounters several practical challenges, starting with fierce competition among local producers. This rivalry can depress prices, shrinking profit margins for suppliers and compelling them to cut back on quality control, which jeopardises product integrity. Another concern is the slow adoption of advanced technology in production processes. Many facilities still depend on outdated methods, causing delays and raising production costs for buyers, with some reporting expenses up to 15% higher. Skills shortages limit operational efficiency, resulting in longer lead times for producers. Regulatory hurdles create compliance challenges that can postpone product approvals by up to six months, affecting timely supply to end-users.
Trends in the India Specialty Metals Market
The trends below show where the India Specialty Metals Market is heading.
- Shift from Conventional to Advanced Materials: Since 2022, the industry has experienced a shift towards advanced materials in aerospace applications. This trend is marked by the increased use of titanium alloys, which have improved performance metrics by 25%.
- Transition from Traditional to Smart Manufacturing: In 2025, smart manufacturing techniques began gaining traction, enhancing production efficiency. Facilities adopting these technologies reported a 20% reduction in waste and improved output.
- Emergence of Sustainable Practices in Aerospace: The introduction of sustainability standards in 2023 has encouraged manufacturers to adopt eco-friendly materials. This shift has led to a 15% increase in the use of recycled metals.
- Increasing Demand for High-Purity Metals: In 2024, the demand for high-purity metals surged, particularly in electronics. This demand has resulted in a 10% growth in the electronics-grade segment, driven by semiconductor firms.
Investment Opportunities in the India Specialty Metals Market
Some of the investment opportunities in the India Specialty Metals Market are mentioned below.
- Partnerships with Local Manufacturers: Investing in partnerships with local manufacturers can enhance production capabilities. The anticipated growth in aerospace spending, projected at 20% over the next five years, presents a notable opportunity.
- Joint Ventures in Emerging Markets: The current market gap for specialty metals in emerging markets is estimated at USD 500 million. Establishing joint ventures in these regions can effectively tap into this unmet demand.
- Investment in Recycling Technologies: With rising raw material costs, investing in recycling technologies for specialty metals is timely. This sector is projected to grow as manufacturers seek sustainable solutions.
- Supply of High-Purity Specialty Metals: There is a growing need for high-purity specialty metals in the semiconductor industry. Focusing on this product line can cater to semiconductor firms, which are expected to experience significant growth.
Government Initiatives in the India Specialty Metals Market
The regulatory framework for the Specialty Metals market is shaped by several key regulations. The Mines and Minerals (Development and Regulation) Act of 1957 mandates sustainable mining practices, impacting raw material sourcing. The National Policy on Electronics, introduced in 2020, aims to boost local manufacturing of electronic components, influencing the demand for specialty metals. Additionally, the Defence Production Policy of 2021 encourages domestic production of defence materials, further supporting the market.
The Department of Defence Production oversees the approval of defence contracts and funding for projects related to specialty metals. The Department of Heavy Industry supports initiatives aimed at improving manufacturing capabilities, providing funding for technology upgrades. The Make in India programme also plays a role by promoting local production and innovation in specialty metals, facilitating access to government grants and incentives.
Future Insight of the India Specialty Metals Market
The India Specialty Metals Market is projected to grow significantly by 2032, driven by advancements in production technology and increased investment in research and development. Automation and smart manufacturing practices will enhance efficiency and reduce costs for suppliers. Government initiatives aimed at boosting local production will create a more robust supply chain, while the introduction of new standards in quality and sustainability will elevate production practices. By 2032, these changes will enable buyers to access higher-quality specialty metals, giving them a stronger competitive advantage.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Metal Type – Titanium Dominated, Tantalum Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Titanium held a 49% share of the India Specialty Metals Market by metal type in 2025. Titanium holds the largest share in the India Specialty Metals Market due to its essential role in aerospace applications, especially in aircraft structures and engines. The aviation sector's demand for lightweight and durable materials solidifies its leading position in the market. The quickest growth will come from Tantalum, forecast to expand at a CAGR of 9.5% between 2026 and 2032. Tantalum is experiencing rapid growth, primarily due to its increasing utilisation in capacitors for electronic devices. The surge in consumer electronics production significantly boosts this demand, indicating a promising trajectory for this metal. Suppliers should focus on enhancing their offerings in titanium and tantalum to capture the growing market share.
By Purity Grade – Aerospace Grade Dominated, Electronics Grade Expected to Grow Fastest
Aerospace Grade accounted for a 44% market share by purity grade in 2025. Aerospace Grade materials dominate the market because they meet the stringent safety and performance standards required in the aviation industry. The high volume of aircraft production in India is a crucial factor contributing to this segment's prominence. Electronics Grade is set to record the highest CAGR in this split, 9.4% over 2026–2032. Electronics Grade materials are expanding swiftly, primarily due to the rising demand for high-performance components in consumer electronics. The anticipated increase in smartphone production acts as a significant driver of this growth. Buyers should prioritise sourcing Aerospace and Electronics Grade materials to ensure compliance with industry standards and meet production demands.
By Application Use – Jet Engines Dominated, Capacitors Expected to Grow Fastest
In 2025, Jet Engines led the application use split with a 42% share. Jet Engines represent the largest share in application use as they necessitate high-performance materials to withstand extreme conditions. The increasing production rates of commercial aircraft in India significantly contribute to this segment's prominence. Over 2026–2032, Capacitors are expected to post the fastest growth, at a CAGR of 8.8%. Capacitors are the fastest-growing application due to the booming electronics market, particularly in smartphones and laptops. The projected growth of the global capacitor market underscores this trend, highlighting the need for advanced materials. Suppliers must align their production capabilities with the growing demand for materials used in jet engines and capacitors.
By End User – Aircraft OEMs Dominated, Semiconductor Firms Expected to Grow Fastest
With a 39% revenue share in 2025, Aircraft OEMs was the largest end user category. Aircraft OEMs command the largest share of the market as they require specialty metals for manufacturing aircraft components. The robust growth in the aviation sector in India supports this segment's dominance, reflecting the need for reliable materials. Semiconductor Firms are projected to grow fastest, at a CAGR of 9.9% during 2026–2032. Semiconductor Firms are the fastest-growing end users, driven by the increasing demand for chips across various applications. The rapid expansion of the semiconductor market in India indicates strong growth potential and opportunities for suppliers. Suppliers should strategically target Aircraft OEMs and Semiconductor Firms to maximise their market share.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Specialty Metals Market Outlook
- Market Size of India Specialty Metals Market, 2025
- Forecast of India Specialty Metals Market, 2032
- Historical Data and Forecast of India Specialty Metals Revenues & Volume for the Period 2022 - 2032F
- India Specialty Metals Market Trend Evolution
- India Specialty Metals Market Drivers and Challenges
- India Specialty Metals Price Trends
- India Specialty Metals Porter's Five Forces
- India Specialty Metals Industry Life Cycle
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Metal Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Titanium for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Tantalum for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Zirconium for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Niobium for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Purity Grade for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Aerospace Grade for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Electronics Grade for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Nuclear Grade for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Superalloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Application Use for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Jet Engines for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Capacitors for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Reactor Components for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Turbine Blades for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Aircraft OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Semiconductor Firms for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Power Utilities for the Period 2022 - 2032F
- Historical Data and Forecast of India Specialty Metals Market Revenues & Volume By Energy Equipment Makers for the Period 2022 - 2032F
- India Specialty Metals Import Export Trade Statistics
- Market Opportunity Assessment By Metal Type
- Market Opportunity Assessment By Purity Grade
- Market Opportunity Assessment By Application Use
- Market Opportunity Assessment By End User
- India Specialty Metals Top Companies Market Share
- India Specialty Metals Competitive Benchmarking By Technical and Operational Parameters
- India Specialty Metals Company Profiles
- India Specialty Metals Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Metal Type
- Titanium
- Tantalum
- Zirconium
- Niobium
By Purity Grade
- Aerospace Grade
- Electronics Grade
- Nuclear Grade
- Superalloys
By Application Use
- Jet Engines
- Capacitors
- Reactor Components
- Turbine Blades
By End User
- Aircraft OEMs
- Semiconductor Firms
- Power Utilities
- Energy Equipment Makers































