India Structural Aerospace Components Market Size & Growth Rate
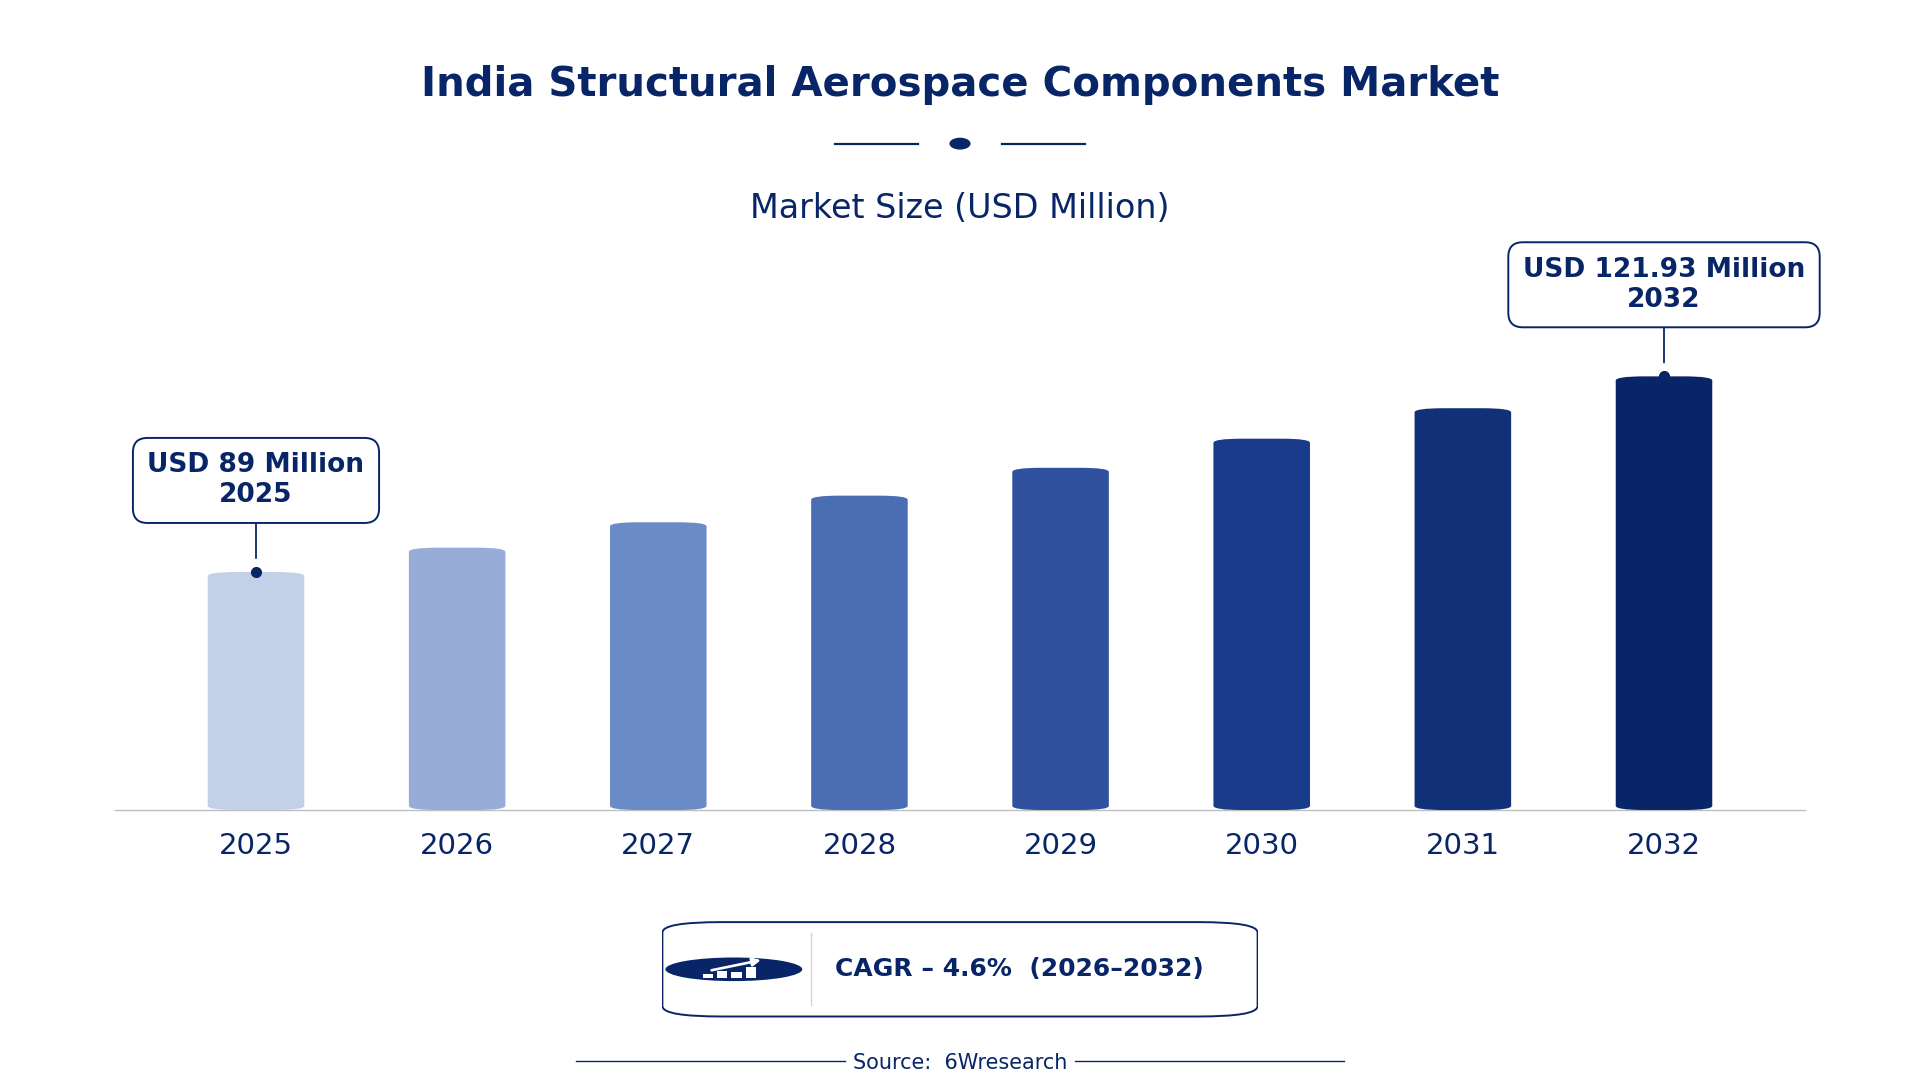
According to 6Wresearch internal database and industry insights, the India Structural Aerospace Components Market was valued at USD 89.0 million in 2025 and is projected to reach USD 121.93 million by 2032, growing at a CAGR of approximately 4.6% during 2026–2032.
India Structural Aerospace Components Market Highlights
| Report Metric | Details |
| Report Name | India Structural Aerospace Components Market |
| Market Size 2025 | USD 89.0 million |
| Market Size 2032 | USD 121.93 million |
| Absolute Growth 2025–2032 | USD 32.93 million |
| CAGR 2026–2032 | 4.6% |
| Peak Annual Growth | 6.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Wing Structures (43% share) |
| Leading Material Type, 2025 | Aluminum Alloys (37% share) |
| Leading Aircraft Type, 2025 | Commercial Aircraft (51% share) |
| Leading End User, 2025 | Aerospace OEMs (51% share) |
| Fastest-Growing Component Type | Tail Assemblies (5.7% CAGR) |
| Fastest-Growing Material Type | Carbon Fiber (6.6% CAGR) |
| Fastest-Growing Aircraft Type | UAVs (6.7% CAGR) |
| Fastest-Growing End User | Drone Manufacturers (6.1% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Aerospace OEMs, Defense Contractors, Drone Manufacturers, Helicopter OEMs |
India Structural Aerospace Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
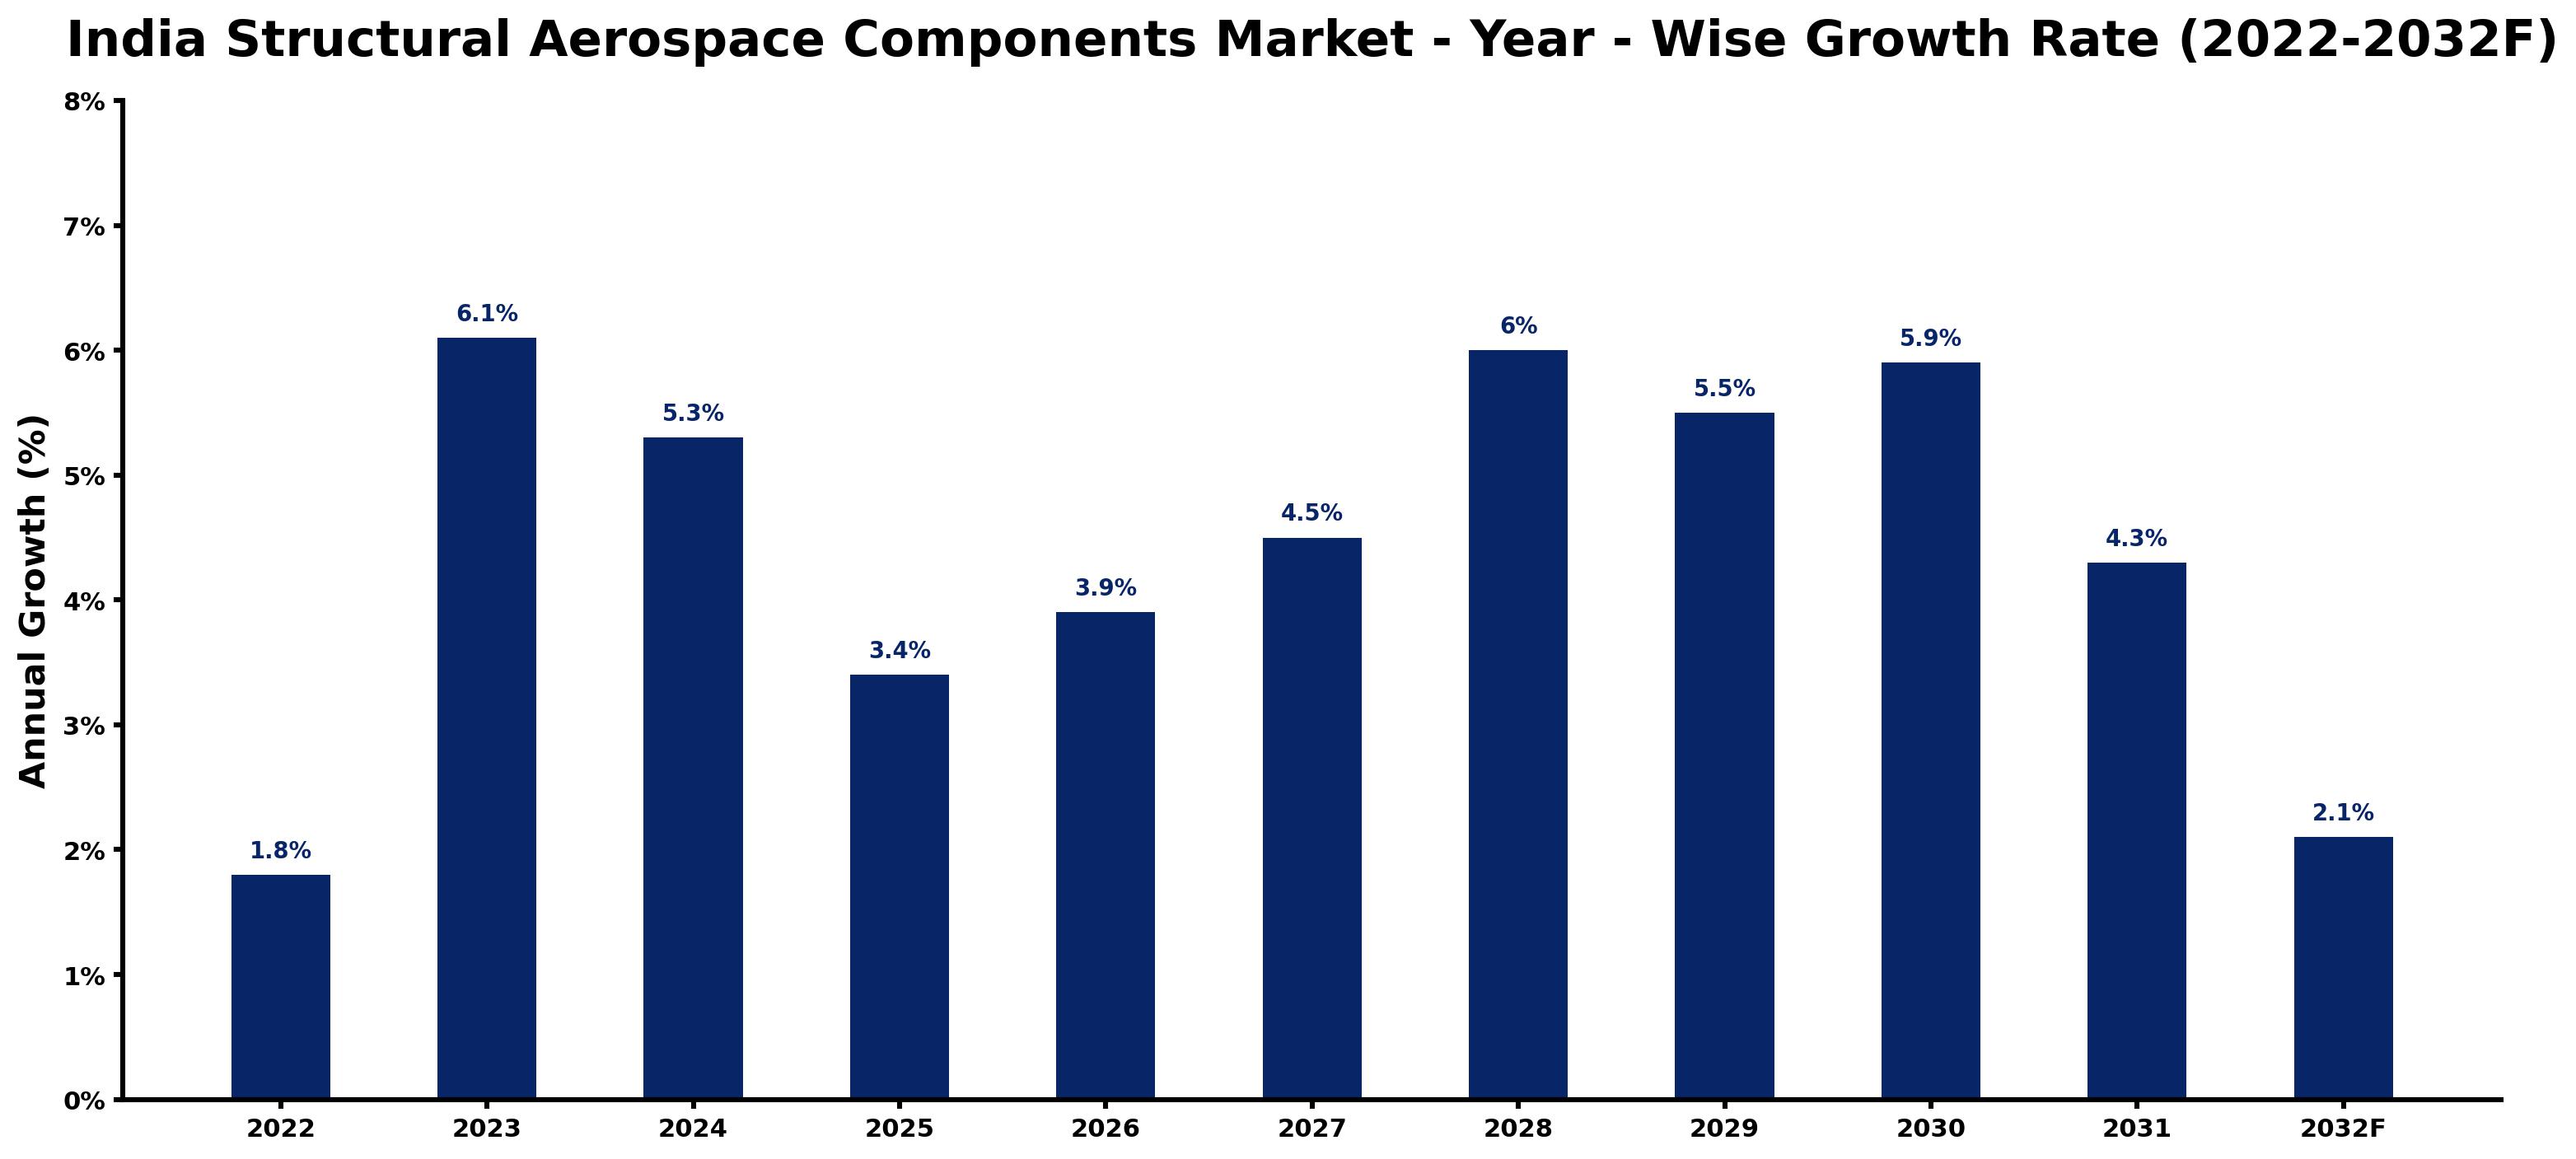
The following table presents the estimated annual growth rate for each year together with the principal factor influencing market performance.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 1.8 | The market experienced modest growth due to ongoing defense contracts and local manufacturing activities. |
| 2023 | 6.1 | Demand surged as the Indian Air Force expanded its fleet, driving component requirements. |
| 2024 | 5.3 | Growth slowed as manufacturers adjusted to supply chain challenges and fluctuating material costs. |
| 2025 | 3.4 | A continued slowdown occurred as the market stabilised following rapid growth in previous years, influenced by the Make in India initiative. |
| 2026 | 3.9 | Demand is expected to rise as the Aerospace and Defense Skill Sector Council improves workforce capabilities. |
| 2027 | 4.5 | The market will grow as the updated National Aerospace and Defense Policy boosts local manufacturing. |
| 2028 | 6.0 | Growth accelerates again as the Indian government aims for 50% indigenization in defense procurement. |
| 2029 | 5.5 | A slight slowdown is anticipated as manufacturers adapt to evolving technological demands. |
| 2030 | 5.9 | Demand is projected to increase as UAV production expands, requiring more structural components. |
| 2031 | 4.3 | The market will see slower growth as competition intensifies among local manufacturers. |
| 2032 | 2.1 | Growth slows further as the market stabilises, reflecting maturity in the aerospace sector. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Structural Aerospace Components Market Synopsis
Structural Aerospace Components in India are critical parts used in aircraft construction, made from high-strength materials like aluminum alloys and composites. These components are essential for maintaining the structural integrity and performance of aircraft. The India Structural Aerospace Components Market is growing due to rising demand from domestic manufacturers and defense contracts, with the Indian defense budget for 2023 set at $76 billion. The updated National Aerospace and Defense Policy aims to boost local manufacturing, driving further demand for these components.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased defense spending is driving demand for structural components in military aircraft. | Driver | High | Fuselage Sections |
| Growing domestic aerospace manufacturing capabilities are creating a need for local sourcing of components. | Driver | High | Wing Structures |
| The Indian government aims to achieve 50% indigenization in defense procurement by 2025, creating opportunities for local suppliers. | Opportunity | High | Aluminum Alloys |
| The expansion of UAV production is opening new markets for structural aerospace components. | Opportunity | High | UAVs |
| Supply chain disruptions and material cost fluctuations can hinder production timelines and increase costs. | Restraint | High | Tail Assemblies |
| Limited availability of skilled labor in aerospace manufacturing can restrict growth potential. | Restraint | Medium | Bulkheads |
| The Structural Aerospace Components Market in India faces challenges related to regulatory compliance and certification processes. | Challenge | Medium | Aluminum Alloys |
| Competition from foreign manufacturers poses a significant challenge for local producers in maintaining market share. | Challenge | High | Commercial Aircraft |
Evaluation of Drivers in India Structural Aerospace Components Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased defense contracts are boosting demand for military aircraft components. | Fuselage Sections | The Indian Air Force operates around 1,700 aircraft, driving demand for components. |
| Local manufacturing initiatives are improving production capabilities for aerospace components. | Wing Structures | The National Aerospace and Defense Policy aims to increase local manufacturing contributions to GDP. |
| Rising UAV production is generating new demand for lightweight structural components. | UAVs | The Indian Space Research Organisation is expanding satellite launch capabilities, increasing demand for components. |
| Growing commercial aircraft orders are driving the need for structural components. | Commercial Aircraft | Aluminum alloys account for approximately 60% of structural aerospace components used in India. |
| Investment in skill development is improving workforce capabilities in aerospace manufacturing. | Tail Assemblies | The Aerospace and Defense Skill Sector Council was established to improve workforce skills. |
Demand for military aircraft components is climbing as the Indian Air Force grows its fleet, currently operating around 1,700 aircraft. Additionally, the Indian Space Research Organisation's expansion of satellite launch capabilities is driving demand for structural components. Investment in skill development through the Aerospace and Defense Skill Sector Council is enhancing workforce capabilities, supporting market growth.
Evaluation of Restraints in India Structural Aerospace Components Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions can delay production timelines for aerospace components. | Tail Assemblies | The ongoing global supply chain issues have affected material availability and costs. |
| Limited skilled labor availability can hinder production efficiency in aerospace manufacturing. | Bulkheads | The aerospace sector faces challenges in attracting and retaining skilled workers. |
| Regulatory compliance costs can increase the financial burden on manufacturers. | Aluminum Alloys | Producers must adhere to stringent certification processes that require significant investment. |
| Competition from foreign manufacturers can impact pricing strategies for local producers. | Commercial Aircraft | Foreign firms often offer competitive pricing due to economies of scale. |
| Material cost fluctuations can affect profit margins for aerospace component manufacturers. | Wing Structures | Volatile prices for raw materials like aluminum and composites create financial uncertainty. |
India Structural Aerospace Components Market Challenges
The India Structural Aerospace Components Market encounters several practical issues, beginning with supply chain disruptions that delay production timelines for manufacturers. These disruptions stem from reliance on imported high-strength materials, resulting in lead times of up to 30 days for critical components. Technological limitations hinder local production capabilities, as many producers lack access to advanced manufacturing techniques, leading to lower quality outputs that can cost buyers up to 15% more in rework expenses. Rising costs of raw materials, especially aluminium alloys which constitute 60% of components, have escalated production costs, compelling buyers to adjust budgets and potentially postpone projects. A skills gap in the workforce remains, as the Aerospace and Defense Skill Sector Council has only recently started addressing training needs, which can slow down production rates for manufacturers.
Trends in the India Structural Aerospace Components Market
Four trends stand out in the India Structural Aerospace Components Market.
- Shift from Traditional Materials to Advanced Composites: India is increasingly adopting advanced composite materials in aerospace manufacturing, particularly in UAVs. This shift began in 2020, with carbon fibre gaining traction due to its strength-to-weight advantages, accounting for a growing share of structural components.
- Transition from Military to Dual-Use Aerospace Technologies: The Indian defence sector is increasingly focusing on dual-use technologies that serve both military and civilian applications. This trend gained momentum in 2021, with defence contractors exploring opportunities in commercial aerospace markets.
- Emergence of UAVs as a Key Segment: UAVs are rapidly becoming a significant segment within the aerospace market in India. This shift started in 2022, driven by increased demand for drone applications in defence and commercial sectors, with growth projected at 6.7%.
- Prioritisation of Local Manufacturing Initiatives: The Indian government is prioritising local manufacturing initiatives to enhance self-reliance in aerospace. This focus began with the Make in India initiative in 2020, aiming for a 50% indigenization target in defence procurement by 2025.
Investment Opportunities in the India Structural Aerospace Components Market
Below are the investment opportunities with the strongest case in the India Structural Aerospace Components Market.
- Joint Ventures with Local Manufacturers: Local manufacturers are seeking partnerships to improve production capabilities, with a target of attracting $1 billion in investments by 2025. Collaborating with aerospace OEMs can facilitate entry into the market.
- Investment in Skill Development Programs: With a growing need for skilled labour, investing in training programs can yield substantial returns. The Aerospace and Defense Skill Sector Council is actively enhancing workforce skills, creating opportunities for training providers.
- Expansion into UAV Production: The UAV segment is rapidly growing, presenting opportunities for component suppliers. The Indian Space Research Organisation's expansion plans indicate a strong demand for structural components, making this an ideal time to invest.
- Focus on High-Strength Alloys: There is a growing demand for high-strength alloys in aerospace applications, driven by the need for durability. Aerospace OEMs are increasingly sourcing these materials to meet performance standards.
Government Initiatives in the India Structural Aerospace Components Market
The National Policy on Aerospace, launched by the Ministry of Civil Aviation in 2021, aims to increase the sector's contribution to GDP by 2025. This policy encourages local manufacturing and innovation within the aerospace sector. The Make in India initiative, updated in 2020, focuses on improving local manufacturing capabilities, further supporting the growth of the structural aerospace components market. The Defense Production and Export Promotion Policy, introduced in 2020, encourages private sector participation in defence manufacturing, fostering a competitive environment.
The Aerospace and Defense Manufacturing Sector Development Program, initiated in 2022, aims to attract $1 billion in investments by 2025. The Ministry of Defense oversees this program, facilitating the development of indigenous capabilities in aerospace manufacturing. Furthermore, the Strategic Partnership Model, revised in 2021, promotes collaboration between Indian and foreign aerospace firms, enhancing technology transfer and local production.
Future Insight of the India Structural Aerospace Components Market
The India Structural Aerospace Components Market is expected to evolve by 2032, with a strong emphasis on indigenization in defence procurement, targeting 50% local sourcing by the government. This shift will prompt local manufacturers to adopt advanced technologies, including composite layup techniques, which will improve production efficiency. The Indian Space Research Organisation's expansion of satellite launch capabilities will stimulate demand for structural aerospace components, as the industry works to meet increasing requirements. The updated National Aerospace and Defense Policy will further support local manufacturing growth, positioning India as a global hub for aerospace by 2025.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Component Type – Wing Structures Dominated, Tail Assemblies Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, with a 43% revenue share in 2025, Wing Structures was the largest component type category. Wing structures dominate the market due to their critical role in aircraft aerodynamics, which is vital for performance. The operational fleet of approximately 1,700 aircraft by the Indian Air Force creates a steady demand for these essential components. Over 2026–2032, Tail Assemblies are expected to post the fastest growth, at a CAGR of 5.7%. Tail assemblies are witnessing rapid growth because they are crucial for ensuring stability and control in aircraft, especially with the surge in UAV production. This focus on drone technology is significantly driving the expansion of this segment. Suppliers must prioritise tail assembly innovations to seize opportunities in this expanding market segment.
By Material Type – Aluminum Alloys Dominated, Carbon Fiber Expected to Grow Fastest
Aluminum Alloys held a 37% share of the India Structural Aerospace Components Market by material type in 2025. Aluminum alloys dominate the market share because they are widely used for lightweight components in the aerospace sector. Their extensive application across various aircraft types guarantees a steady demand from manufacturers. Carbon Fiber is set to record the highest CAGR in this split, 6.6% over 2026–2032. Carbon fiber is experiencing the fastest growth thanks to its exceptional strength-to-weight advantages, making it increasingly sought after in advanced aerospace applications. The industry's push for more efficient aircraft designs is driving this trend. Buyers should consider investing in carbon fiber solutions to improve aircraft performance and meet industry standards.
By Aircraft Type – Commercial Aircraft Dominated, UAVs Expected to Grow Fastest
Commercial Aircraft took a 51% share of aircraft type in 2025, more than any other category. Commercial aircraft represent the largest share of the market, driven by both domestic and international travel demands. The growth of the aviation sector in India solidifies this position and ensures sustained demand for structural components. The quickest growth will come from UAVs, forecast to expand at a CAGR of 6.7% between 2026 and 2032. UAVs are the fastest-growing segment, reflecting the increasing usage of drones across various industries, including surveillance and logistics. This trend is expected to continue as technology advances and applications for UAVs expand. Suppliers must adapt to the growing UAV market by developing specialised components that cater to drone manufacturers.
By End User – Aerospace OEMs Dominated, Drone Manufacturers Expected to Grow Fastest
In 2025, Aerospace OEMs led the end user split with a 51% share. Aerospace OEMs hold the largest market share as they are the primary manufacturers of aircraft, creating a reliable demand for structural components. Their established market presence ensures consistent revenue streams for suppliers in the aerospace sector. Drone Manufacturers are projected to grow fastest, at a CAGR of 6.1% during 2026–2032. Drone manufacturers represent the fastest-growing end user, highlighting the increasing significance of UAV production within the aerospace industry. The rising adoption of drones for various applications is propelling this segment's growth. Suppliers should tailor their offerings to meet the evolving requirements of drone manufacturers to capitalise on this rapidly growing market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Structural Aerospace Components Market Outlook
- Market Size of India Structural Aerospace Components Market, 2025
- Forecast of India Structural Aerospace Components Market, 2032
- Historical Data and Forecast of India Structural Aerospace Components Revenues & Volume for the Period 2022 - 2032F
- India Structural Aerospace Components Market Trend Evolution
- India Structural Aerospace Components Market Drivers and Challenges
- India Structural Aerospace Components Price Trends
- India Structural Aerospace Components Porter's Five Forces
- India Structural Aerospace Components Industry Life Cycle
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Wing Structures for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Fuselage Sections for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Tail Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Bulkheads for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Titanium/Composite for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By High-Strength Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Aircraft Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Commercial Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Military Jets for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By UAVs for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Helicopters for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Defense Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Drone Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of India Structural Aerospace Components Market Revenues & Volume By Helicopter OEMs for the Period 2022 - 2032F
- India Structural Aerospace Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Aircraft Type
- Market Opportunity Assessment By End User
- India Structural Aerospace Components Top Companies Market Share
- India Structural Aerospace Components Competitive Benchmarking By Technical and Operational Parameters
- India Structural Aerospace Components Company Profiles
- India Structural Aerospace Components Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Component Type
- Wing Structures
- Fuselage Sections
- Tail Assemblies
- Bulkheads
By Material Type
- Aluminum Alloys
- Titanium/Composite
- Carbon Fiber
- High-Strength Alloys
By Aircraft Type
- Commercial Aircraft
- Military Jets
- UAVs
- Helicopters
By End User
- Aerospace OEMs
- Defense Contractors
- Drone Manufacturers
- Helicopter OEMs































