China Structural Aerospace Components Market Size & Growth Rate
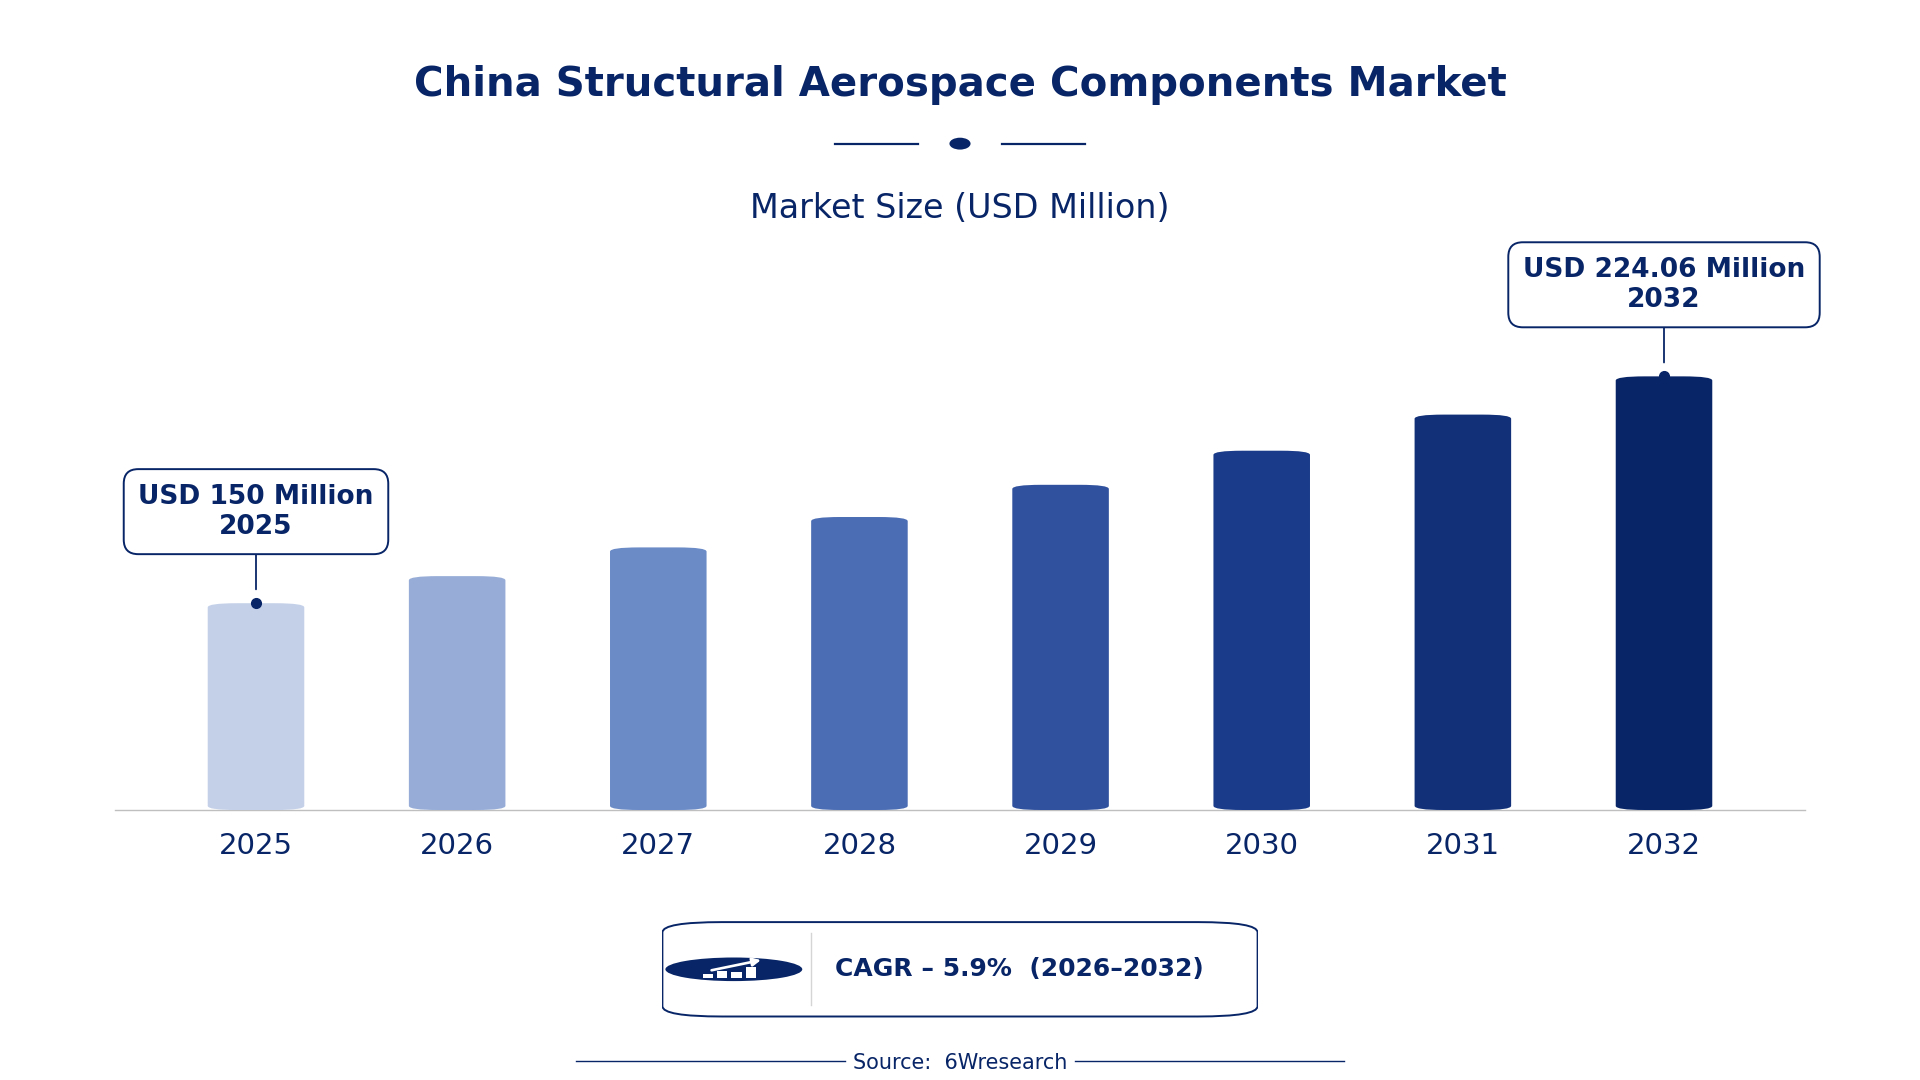
According to 6Wresearch internal database and industry insights, the China Structural Aerospace Components Market was valued at USD 150.0 million in 2025 and is projected to reach USD 224.06 million by 2032, growing at a CAGR of approximately 5.9% during 2026–2032.
China Structural Aerospace Components Market Highlights
| Report Metric | Details |
| Report Name | China Structural Aerospace Components Market |
| Market Size 2025 | USD 150.0 million |
| Market Size 2032 | USD 224.06 million |
| Absolute Growth 2025–2032 | USD 74.06 million |
| CAGR 2026–2032 | 5.9% |
| Peak Annual Growth | 7.9% in 2026 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Wing Structures (45% share) |
| Leading Material Type, 2025 | Aluminum Alloys (42% share) |
| Leading Aircraft Type, 2025 | Commercial Aircraft (47% share) |
| Leading End User, 2025 | Aerospace OEMs (51% share) |
| Fastest-Growing Component Type | Bulkheads (7.6% CAGR) |
| Fastest-Growing Material Type | Carbon Fiber (7.3% CAGR) |
| Fastest-Growing Aircraft Type | UAVs (7.7% CAGR) |
| Fastest-Growing End User | Drone Manufacturers (7.7% CAGR) |
| Growing Sector | Aerospace Manufacturing |
| Key End Users | Aerospace OEMs, Defense Contractors, Drone Manufacturers, Helicopter OEMs |
China Structural Aerospace Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
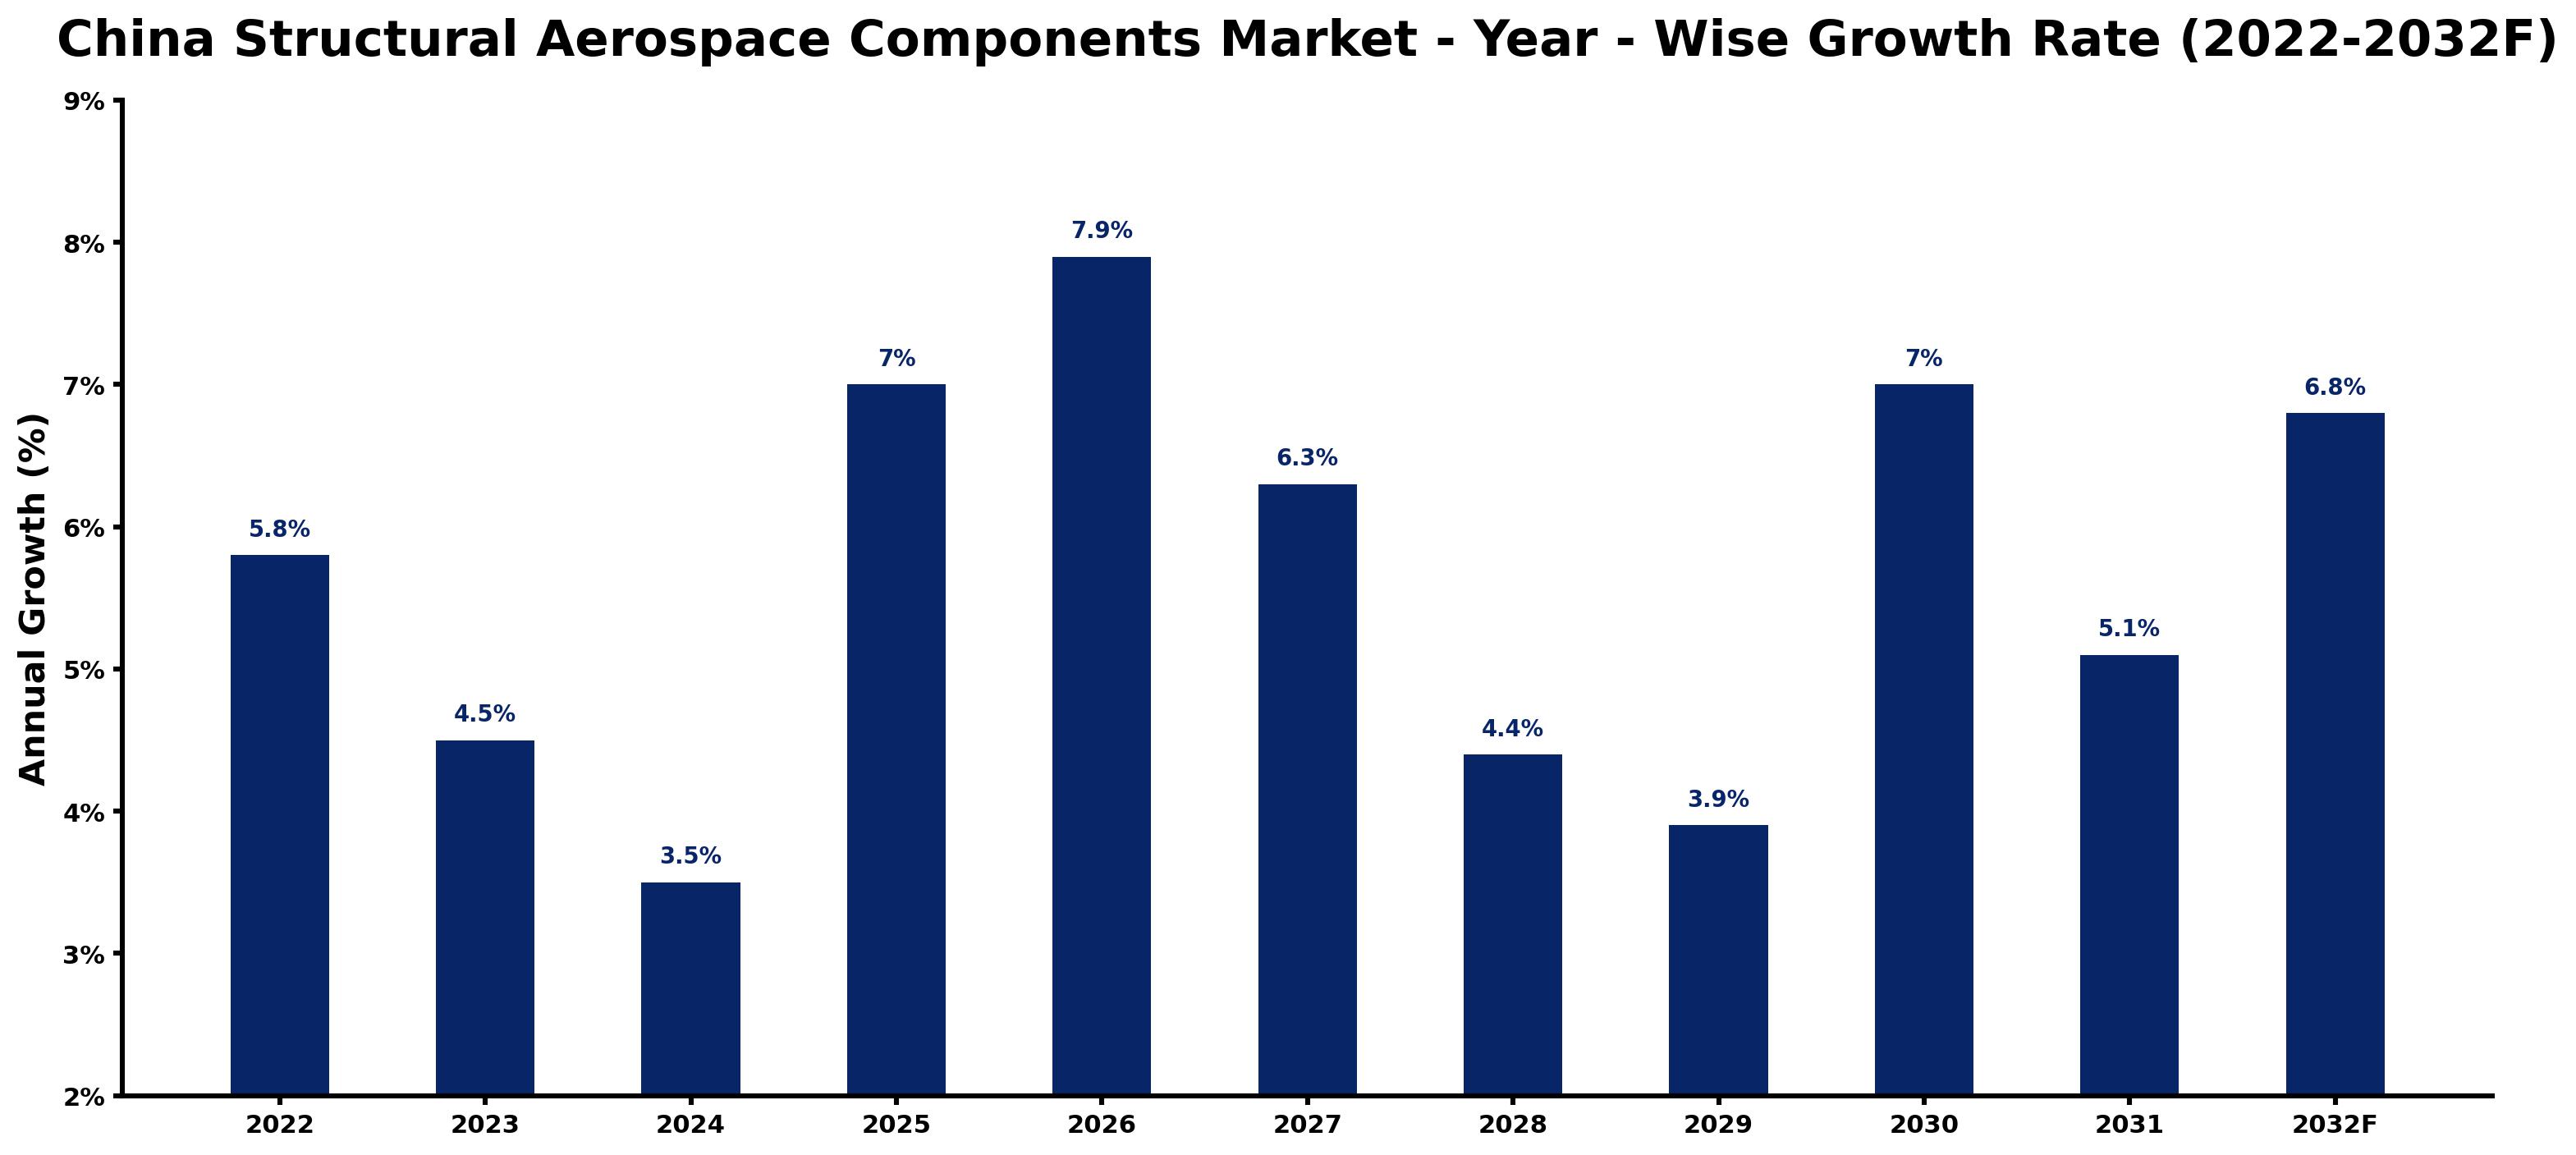
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.8 | Demand from the aerospace sector remained strong, driven by domestic production needs for commercial aircraft. |
| 2023 | 4.5 | Growth slowed as manufacturers faced challenges in scaling up production capacity to meet rising demand. |
| 2024 | 3.5 | Continued demand from commercial aircraft production supported market expansion, albeit at a slower rate due to supply chain issues. |
| 2025 | 7.0 | The market rebounded with increased production of over 300 commercial aircraft, boosting structural component demand. |
| 2026 | 7.9 | A surge in demand for structural components led to the peak growth rate of the forecast period, driven by military contracts. |
| 2027 | 6.3 | Manufacturers are expected to adjust to new production standards and regulations, impacting growth rates. |
| 2028 | 4.4 | The market is projected to continue growing as manufacturers adapt to evolving industry standards and technology. |
| 2029 | 3.9 | Demand is expected to stabilise as manufacturers focus on efficiency and cost management in production processes. |
| 2030 | 7.0 | Increased investments in aerospace technology are projected to spur growth, leading to a faster recovery in production capacity. |
| 2031 | 5.1 | The market is expected to grow slower as regulatory changes impact production timelines and operational efficiency. |
| 2032 | 6.8 | Demand for advanced materials is projected to rise, driven by government initiatives promoting innovation in aerospace. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Aerospace Components Market Synopsis
Structural Aerospace Components in China include crucial parts of aircraft crafted from advanced materials such as aluminium alloys and composites. These components play a key role in improving aircraft strength, lowering weight, and enhancing fuel efficiency. The China Structural Aerospace Components Market is expanding due to strong domestic production and exports, especially in the commercial and military aircraft sectors. In 2022, China produced over 300 commercial aircraft, highlighting robust demand. Increased investments in aerospace technology and a focus on advanced materials are propelling this growth.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing domestic aircraft production capacity | Driver | High | Commercial Aircraft |
| Growing demand for UAVs in various sectors | Driver | High | UAVs |
| Investment in advanced aerospace materials | Opportunity | High | Aluminum Alloys |
| Emerging demand from drone manufacturers | Opportunity | Medium | Drone Manufacturers |
| Regulatory challenges affecting production timelines | Restraint | High | Fuselage Sections |
| High costs associated with advanced materials | Restraint | Medium | Carbon Fiber |
| Limited skilled workforce in aerospace manufacturing | Challenge | High | Wing Structures |
| Supply chain disruptions impacting component availability | Challenge | Medium | Tail Assemblies |
Evaluation of Drivers in China Structural Aerospace Components Market (2026–2032)
The factors lifting demand, and the evidence behind each, are summarised below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased domestic production of commercial aircraft | Commercial Aircraft | China's aerospace industry produced over 300 commercial aircraft in 2022, driving demand for structural components significantly. |
| Rising investments in aerospace technology | Aluminum Alloys | Over $10 billion has been invested in aerospace technology development since 2020, boosting demand for advanced materials. |
| Expanding applications for UAVs across sectors | UAVs | The UAV market is expected to grow rapidly, increasing demand for structural aerospace components substantially. |
| Focus on advanced materials for weight reduction | Carbon Fiber | The Chinese government promotes the use of advanced materials in aerospace, improving performance and efficiency of components. |
| Expansion of military aerospace capabilities | Military Jets | The National Defense Technology Innovation Plan supports military aerospace development, increasing demand for structural components. |
Expansion of the Structural Aerospace Components market in China is backed by increased domestic production of commercial aircraft, significant investments in aerospace technology, and expanding applications for UAVs. In 2022, over 300 commercial aircraft were produced, which boosted demand for structural components. More than $10 billion has been invested in aerospace technology development since 2020, increasing the use of advanced materials. The UAV market is expected to grow rapidly, leading to higher demand for structural components.
Evaluation of Restraints in China Structural Aerospace Components Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Rising material prices | Aluminum Alloys | Material costs have increased significantly, raising production expenses for manufacturers by up to 15%. |
| Intense competition from international suppliers | Fuselage Sections | Local manufacturers struggle to compete with lower-priced imports, affecting market share. |
| Technological advancements require heavy investment | Wing Structures | New processes necessitate significant capital, extending production timelines for manufacturers. |
| Supply chain disruptions due to geopolitical tensions | Tail Assemblies | Geopolitical issues can lead to shortages of critical components, delaying assembly for producers. |
| Regulatory compliance costs | Bulkheads | Meeting stringent safety and quality standards can increase operational costs for manufacturers. |
China Structural Aerospace Components Market Challenges
The China Structural Aerospace Components Market is hindered by escalating production costs, primarily driven by rising material prices that can increase manufacturing expenses by up to 15% for producers. Local suppliers face fierce competition from international manufacturers, making it difficult to maintain market share against lower-priced imports. Rapid technological advancements necessitate significant investments in new processes, which can extend production timelines by several months, delaying deliveries for buyers. Additionally, supply chain disruptions linked to geopolitical tensions can result in shortages of critical components, causing assembly delays for manufacturers.
Trends in the China Structural Aerospace Components Market
Buyers and suppliers in the China Structural Aerospace Components Market are adjusting to the following trends.
- Shift towards Advanced Materials in Aerospace Manufacturing: Aerospace OEMs are increasingly adopting advanced materials like carbon fibre for structural components. In 2022, the market for carbon fibre in aerospace grew by 7.3%, reflecting a shift towards lightweight materials.
- Growing Demand for UAVs in Aerospace: Drone manufacturers are expanding their production capabilities, with the UAV market expected to grow rapidly. In 2022, this segment saw a growth rate of 7.7%, indicating a shift in aerospace focus.
- Increased Focus on Sustainability in Aerospace: Aerospace OEMs are prioritising sustainable practices, leading to the adoption of eco-friendly materials. The Civil Aviation Administration of China has set new standards promoting sustainability in aircraft manufacturing.
- Expansion of Military Aerospace Capabilities: The National Defense Technology Innovation Plan is driving advancements in military aerospace. Funding for military aerospace development has increased, supporting the growth of structural components.
Investment Opportunities in the China Structural Aerospace Components Market
Below are the investment opportunities with the strongest case in the China Structural Aerospace Components Market.
- Joint Ventures for Advanced Material Production: Investing in joint ventures for producing advanced materials in aerospace is timely. The Aerospace Industry Development Fund, with a budget of $1 billion, supports startups in this sector.
- Supply of Lightweight Structural Components: There is a growing opportunity to supply lightweight structural components, particularly aluminium alloys. Aerospace OEMs are seeking local partners to increase production capacity.
- Investment in UAV Manufacturing Facilities: Investing in UAV manufacturing facilities is timely, given the expected growth in this market. The Beijing-Tianjin-Hebei region is a major hub for aerospace manufacturing.
- Certification for Advanced Aerospace Standards: Obtaining certification for advanced aerospace standards is important. The CAAC sets standards that can improve market entry for new players.
Government Initiatives in the China Structural Aerospace Components Market
The 'Aerospace Industry Development Fund' was established in 2022 to support innovation in aerospace technologies, with a budget of $1 billion. This measure complements the '14th Five-Year Plan for the Development of the Aerospace Industry', launched in 2021, which aims to boost domestic production capabilities and improve the competitiveness of structural aerospace components.
The Civil Aviation Administration of China oversees the 'Civil Aviation Development Fund', which supports infrastructure projects in the aerospace sector. This fund has been active since 2021, facilitating various projects that improve manufacturing standards and safety compliance, benefiting producers and buyers in the structural aerospace components market.
Future Insight of the China Structural Aerospace Components Market
By 2032, buyers and suppliers in the China Structural Aerospace Components Market can expect substantial advancements, driven by government investments in aerospace technology and a 20% increase in domestic aircraft production capacity by 2025. Enhanced standards from the Civil Aviation Administration of China will elevate safety and manufacturing processes. The growing UAV market is anticipated to drive new applications for structural components, encouraging innovation and creating further growth opportunities. National programmes promoting advanced materials will also strengthen the sector's capabilities.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Component Type – Wing Structures Dominated, Bulkheads Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Wing Structures accounted for a 45% market share by component type in 2025. Wing structures are essential for maintaining aircraft integrity, making them a critical component in the aerospace industry. The production of over 300 commercial aircraft in 2022 illustrates the ongoing demand for these vital parts. Bulkheads are projected to grow fastest, at a CAGR of 7.6% during 2026–2032. Bulkheads are gaining prominence for their crucial role in providing structural support, especially as China's aircraft production capacity is set to increase by 20% by 2025. This growth trajectory will likely drive further demand for bulkheads in the market. Suppliers should enhance production capabilities to meet the increasing demand for wing structures and bulkheads.
By Material Type – Aluminum Alloys Dominated, Carbon Fiber Expected to Grow Fastest
Aluminum Alloys held a 42% share of the China Structural Aerospace Components Market by material type in 2025. Aluminum alloys hold the largest market share due to their lightweight properties, which are vital for optimising aircraft performance. Their widespread use in the manufacturing of over 300 commercial aircraft in 2022 highlights their importance in the aerospace sector. Carbon Fiber is set to record the highest CAGR in this split, 7.3% over 2026–2032. Carbon fiber is rapidly becoming popular as manufacturers seek weight reduction solutions, especially with government initiatives promoting advanced materials in aerospace. This shift indicates a growing preference for efficient materials in structural components, improving overall aircraft performance. Buyers should consider transitioning to carbon fiber to enhance aircraft efficiency, while suppliers must adapt their offerings to include advanced material options.
By Aircraft Type – Commercial Aircraft Dominated, UAVs Expected to Grow Fastest
In 2025, Commercial Aircraft led the aircraft type split with a 47% share. Commercial aircraft lead the market, driven by the high demand for air travel in a population of approximately 1.4 billion. This substantial market share is reinforced by ongoing domestic production and export requirements. The quickest growth will come from UAVs, forecast to expand at a CAGR of 7.7% between 2026 and 2032. UAVs are experiencing significant growth as their applications expand across various sectors, reflecting the increasing interest in unmanned systems. This trend indicates a notable shift in focus within the aerospace market, necessitating supplier adaptation. Suppliers must align their strategies to cater to the expanding UAV market while continuing to support the established commercial aircraft segment.
By End User – Aerospace OEMs Dominated, Drone Manufacturers Expected to Grow Fastest
Aerospace OEMs took a 51% share of end user in 2025, more than any other category. Aerospace OEMs are the primary manufacturers of aircraft, holding a substantial market share due to their central role in the production process. Their established presence in the industry ensures continued demand for structural components. Over 2026–2032, Drone Manufacturers are expected to post the fastest growth, at a CAGR of 7.7%. Drone manufacturers are emerging as a rapidly growing segment, driven by the increasing popularity of UAVs across multiple applications. This growth presents new opportunities for suppliers to engage with a dynamic market. Suppliers should diversify their offerings to meet the unique needs of both aerospace OEMs and the expanding drone manufacturing sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Aerospace Components Market Outlook
- Market Size of China Structural Aerospace Components Market, 2025
- Forecast of China Structural Aerospace Components Market, 2032
- Historical Data and Forecast of China Structural Aerospace Components Revenues & Volume for the Period 2022 - 2032F
- China Structural Aerospace Components Market Trend Evolution
- China Structural Aerospace Components Market Drivers and Challenges
- China Structural Aerospace Components Price Trends
- China Structural Aerospace Components Porter's Five Forces
- China Structural Aerospace Components Industry Life Cycle
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Wing Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Fuselage Sections for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Tail Assemblies for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Bulkheads for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Aluminum Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Titanium/Composite for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Carbon Fiber for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By High-Strength Alloys for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Aircraft Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Commercial Aircraft for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Military Jets for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By UAVs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Helicopters for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Aerospace OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Defense Contractors for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Drone Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Aerospace Components Market Revenues & Volume By Helicopter OEMs for the Period 2022 - 2032F
- China Structural Aerospace Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Aircraft Type
- Market Opportunity Assessment By End User
- China Structural Aerospace Components Top Companies Market Share
- China Structural Aerospace Components Competitive Benchmarking By Technical and Operational Parameters
- China Structural Aerospace Components Company Profiles
- China Structural Aerospace Components Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Component Type
- Wing Structures
- Fuselage Sections
- Tail Assemblies
- Bulkheads
By Material Type
- Aluminum Alloys
- Titanium/Composite
- Carbon Fiber
- High-Strength Alloys
By Aircraft Type
- Commercial Aircraft
- Military Jets
- UAVs
- Helicopters
By End User
- Aerospace OEMs
- Defense Contractors
- Drone Manufacturers
- Helicopter OEMs































