India Urologic Cancer Market Size & Growth Rate
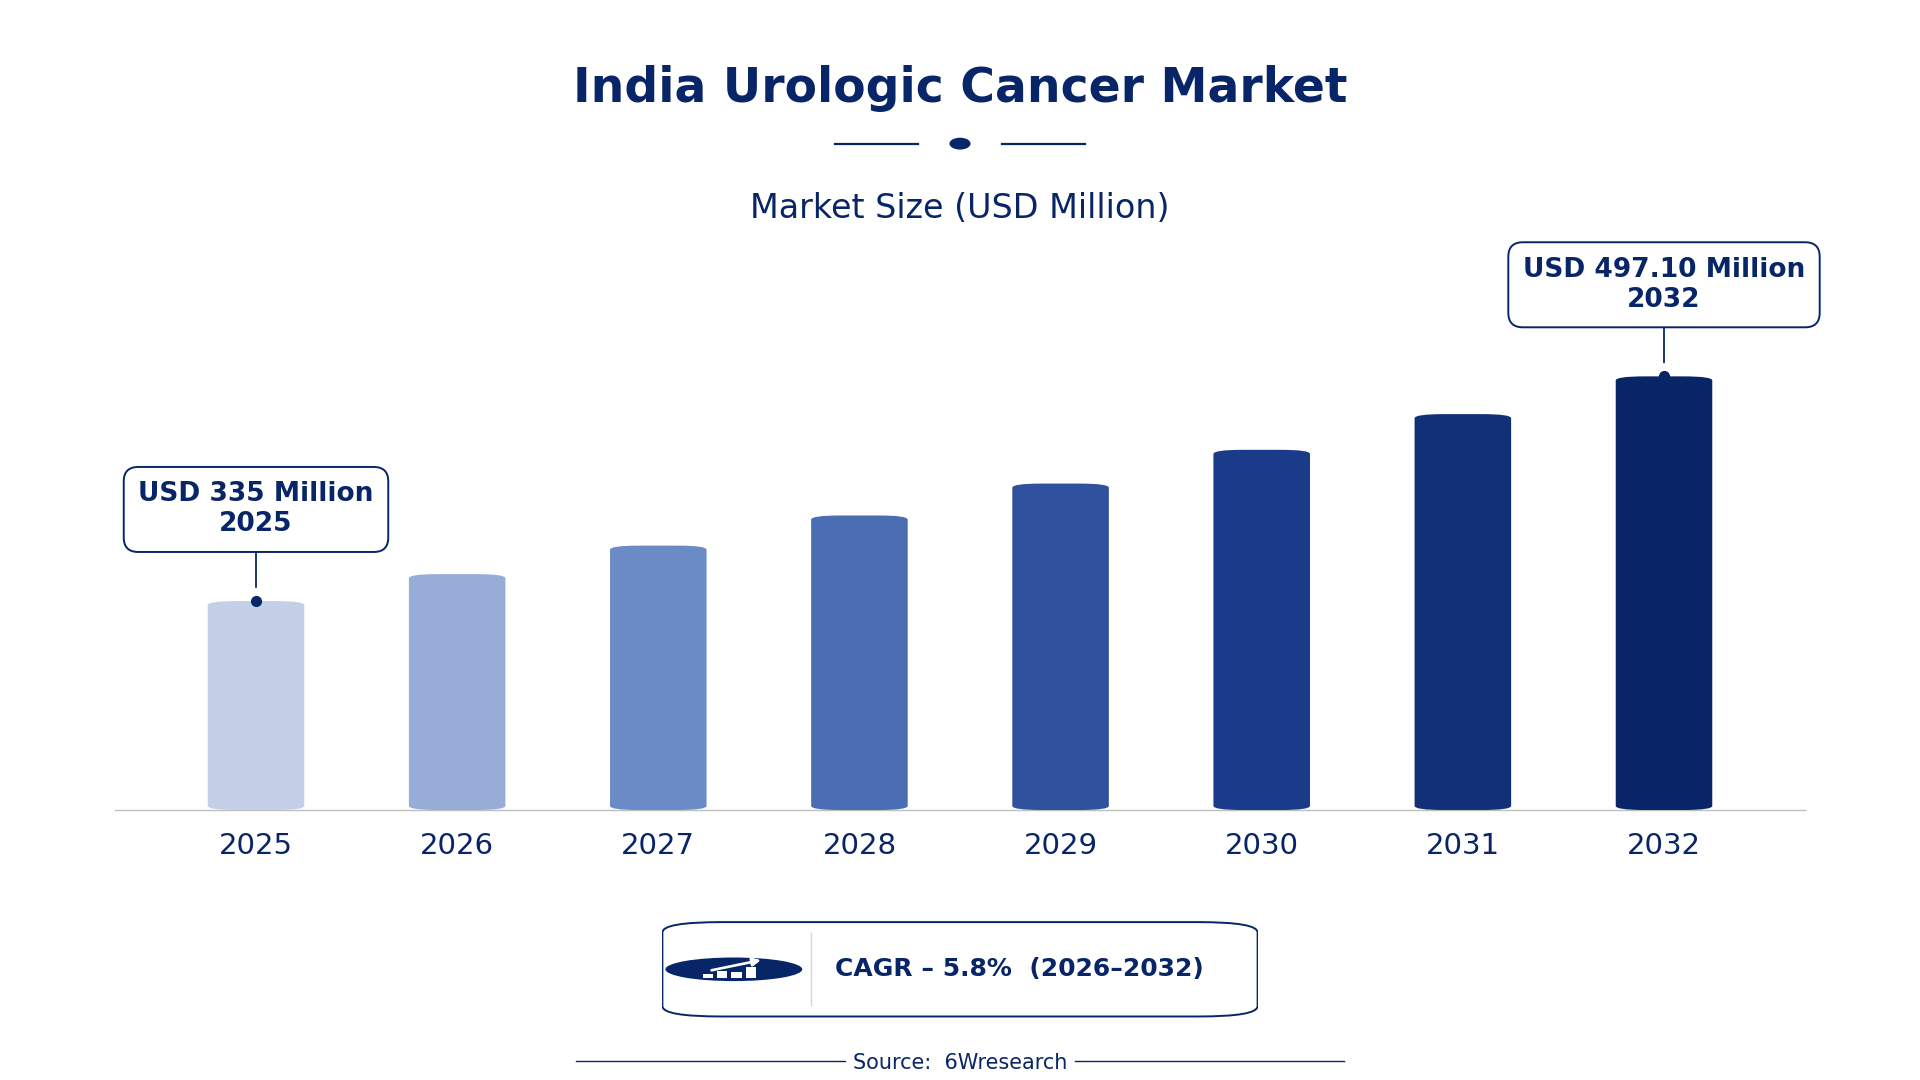
According to 6Wresearch internal database and industry insights, the India Urologic Cancer Market was valued at USD 335.0 million in 2025 and is projected to reach USD 497.10 million by 2032, growing at a CAGR of approximately 5.8% during 2026–2032.
India Urologic Cancer Market Highlights
| Report Metric | Details |
| Report Name | India Urologic Cancer Market |
| Market Size 2025 | USD 335.0 million |
| Market Size 2032 | USD 497.10 million |
| Absolute Growth 2025–2032 | USD 162.10 million |
| CAGR 2026–2032 | 5.8% |
| Peak Annual Growth | 8.0% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Cancer Type, 2025 | Prostate Cancer (41% share) |
| Leading Treatment Type, 2025 | Chemotherapy (40% share) |
| Leading Diagnosis Method, 2025 | PSA Testing (46% share) |
| Leading End User, 2025 | Hospitals (45% share) |
| Fastest-Growing Cancer Type | Bladder Cancer (7.1% CAGR) |
| Fastest-Growing Treatment Type | Immunotherapy (7.1% CAGR) |
| Fastest-Growing Diagnosis Method | Cytology + Imaging (8.5% CAGR) |
| Fastest-Growing End User | Oncology Clinics (7.6% CAGR) |
| Growing Sector | Oncology Clinics |
| Key End Users | Hospitals, Oncology Clinics, Cancer Centers, Urology Specialists |
India Urologic Cancer Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
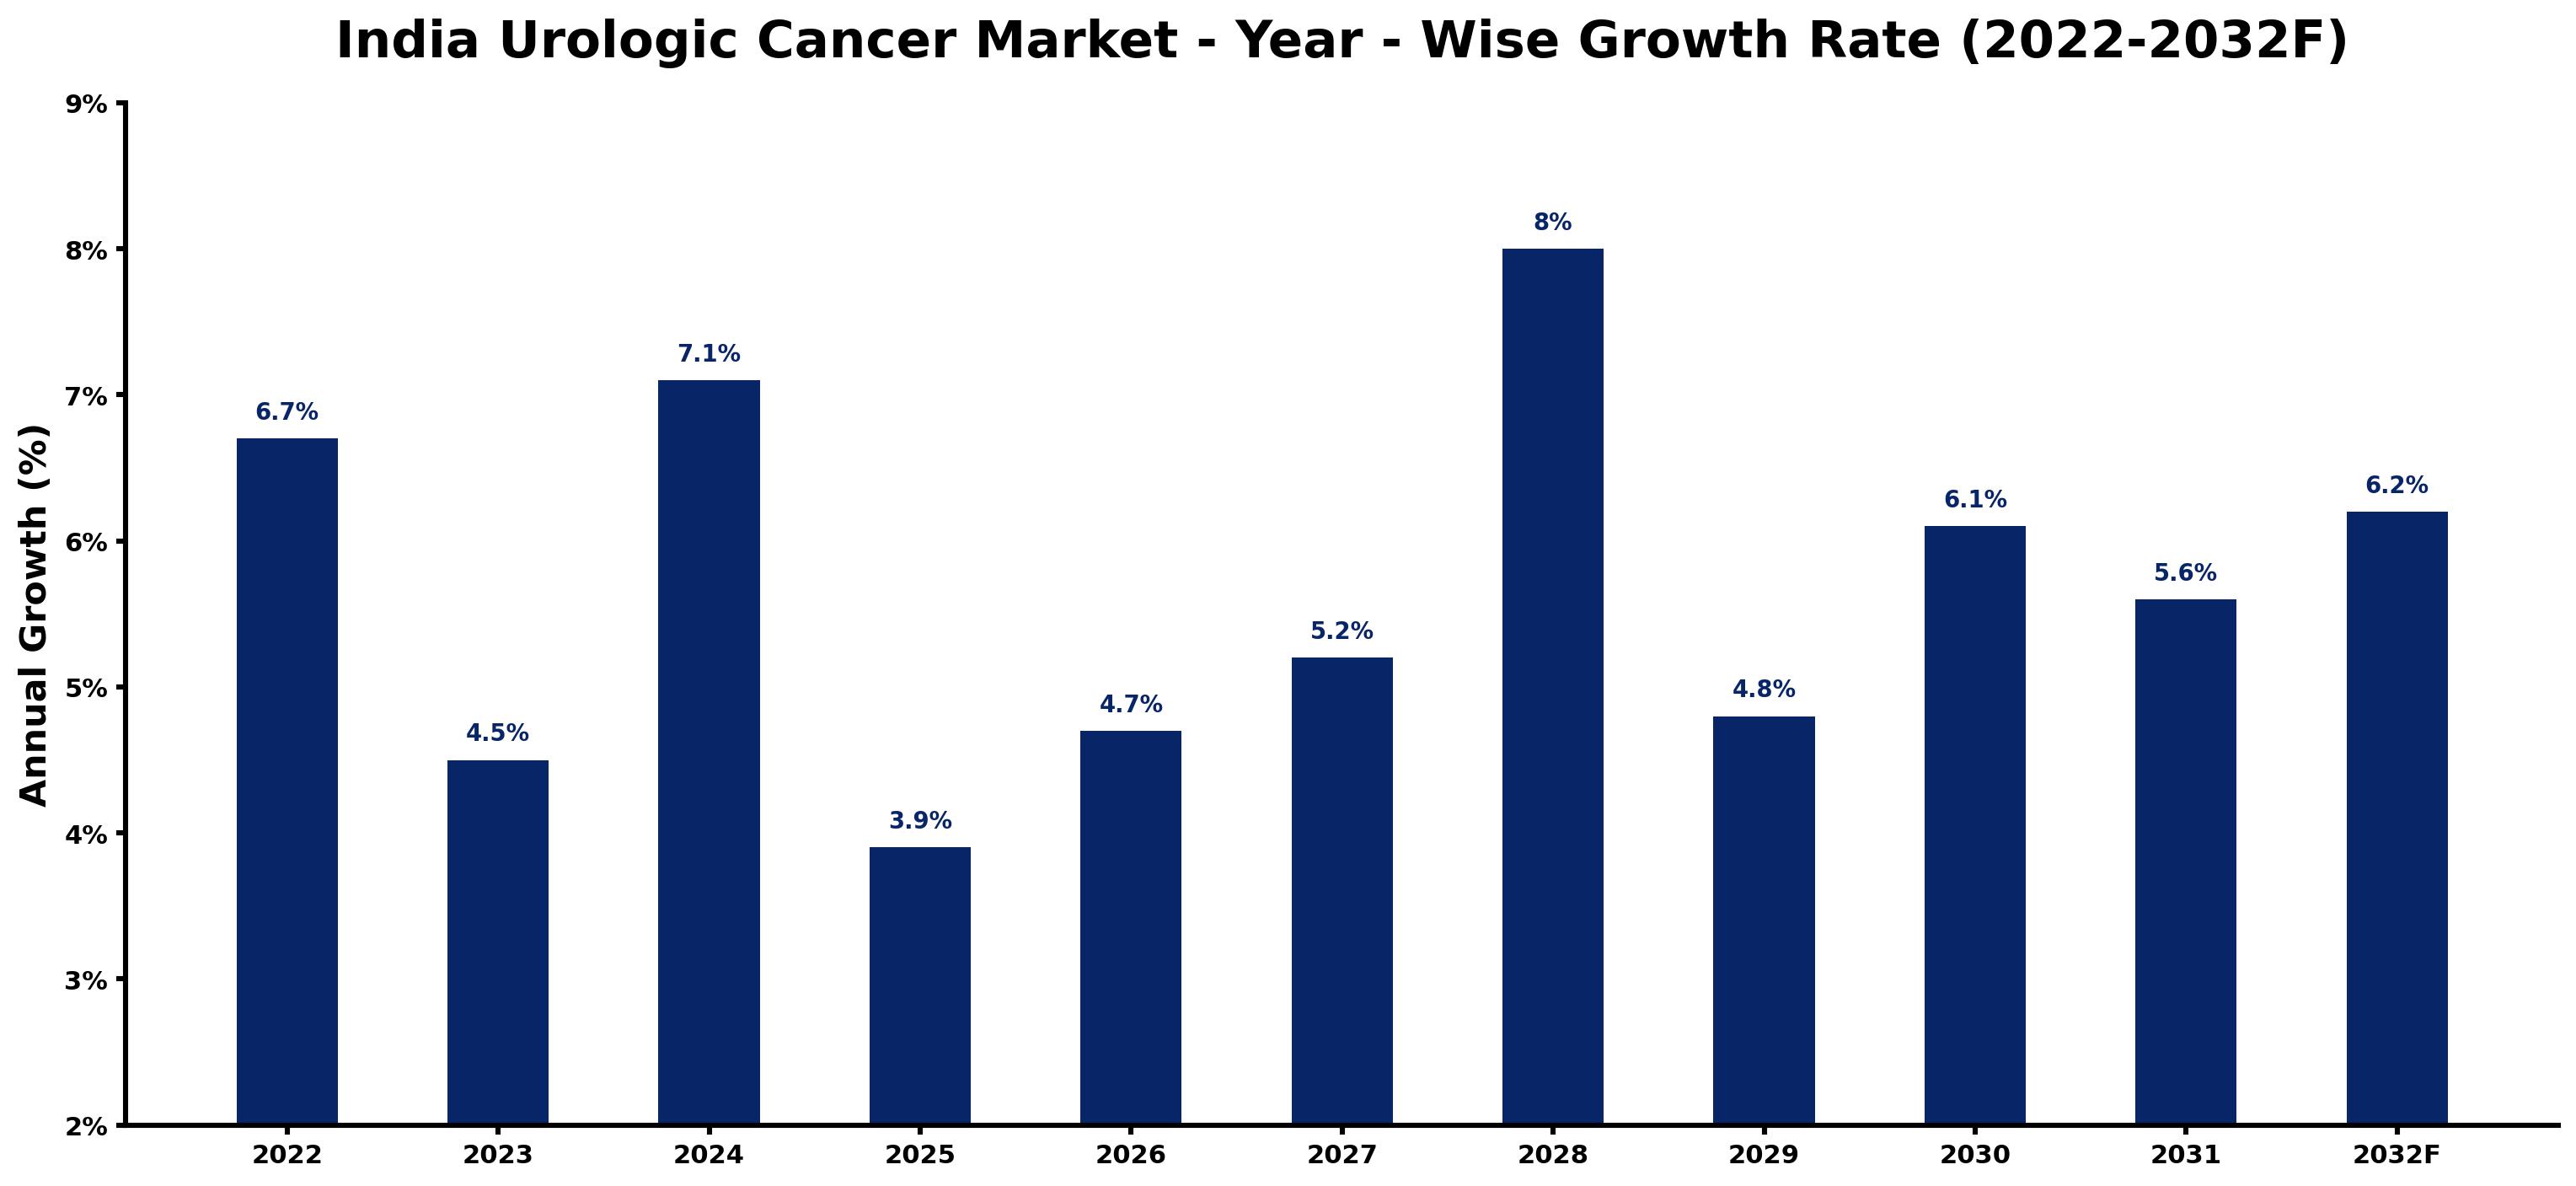
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.7 | The market experienced steady growth due to increasing awareness of urologic cancers. |
| 2023 | 4.5 | Demand growth slowed as hospitals faced resource allocation challenges amid rising patient numbers. |
| 2024 | 7.1 | A surge in bladder cancer cases contributed to faster growth as treatment facilities expanded. |
| 2025 | 3.9 | Growth decelerated as hospitals managed capacity constraints during peak treatment seasons. |
| 2026 | 4.7 | An increase in PSA testing recommendations boosted demand for prostate cancer treatments. |
| 2027 | 5.2 | Rising investments in oncology clinics supported a steady increase in treatment access. |
| 2028 | 8.0 | The market peaked as immunotherapy adoption surged across major cancer treatment centres. |
| 2029 | 4.8 | Growth slowed as competition intensified among healthcare facilities for patient acquisition. |
| 2030 | 6.1 | Increased funding for cancer research initiatives is expected to drive further demand. |
| 2031 | 5.6 | Growth moderated as hospitals adjusted to new treatment protocols and patient management. |
| 2032 | 6.2 | A rise in awareness campaigns is projected to enhance early detection and treatment access. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India Urologic Cancer Market Synopsis
Urologic Cancer in India includes malignancies that affect the urinary system and male reproductive organs, such as prostate and bladder cancers. Treatment options encompass chemotherapy and immunotherapy. The India Urologic Cancer Market is expanding due to the rising incidence of cancer and improved access to healthcare. Government initiatives are also improving treatment access and increasing patient awareness.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing prostate cancer cases | Driver | High | Prostate Cancer |
| Expansion of cancer treatment facilities | Driver | High | Oncology Clinics |
| Growing demand for immunotherapy | Opportunity | High | Immunotherapy |
| Rising awareness of early detection | Opportunity | High | PSA Testing |
| Limited access to advanced treatment options | Restraint | High | Chemotherapy |
| High treatment costs for patients | Restraint | Medium | Surgery + Radiation |
| Shortage of trained urology specialists | Challenge | High | Urology Specialists |
| Inconsistent patient follow-up care | Challenge | Medium | Cancer Centers |
Evaluation of Drivers in India Urologic Cancer Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising prostate cancer incidence | Prostate Cancer | Prostate cancer accounts for approximately 25% of all cancer cases in India, driving demand for screening and treatment across healthcare facilities. |
| Increased healthcare investments | Oncology Clinics | The expansion of oncology clinics in tier-2 cities is meeting rising patient demand for cancer treatment, improving access for underserved populations. |
| Growing adoption of immunotherapy | Immunotherapy | Immunotherapy is increasingly utilized in treatment protocols, improving patient outcomes and driving demand for related services and products. |
| Government awareness campaigns | PSA Testing | The National Health Mission's initiatives promote annual PSA testing for men over 50, increasing early diagnosis and encouraging timely treatment interventions. |
| Technological advancements in diagnostics | Cytology + Imaging | Cytology and imaging techniques are improving diagnostic accuracy, leading to more timely treatment interventions and better patient outcomes. |
Expansion of the Urologic Cancer market in India is backed by rising prostate cancer incidence, increased healthcare investments, and growing adoption of immunotherapy. Prostate cancer accounts for approximately 25% of all cancer cases in India, driving demand for screening and treatment. The expansion of oncology clinics in tier-2 cities is meeting rising patient demand for cancer treatment, with over 200,000 new bladder cancer cases reported in 2022. Advances in cytology and imaging are improving diagnostic accuracy, resulting in timely interventions for patients.
Evaluation of Restraints in India Urologic Cancer Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited access to advanced treatment options | Chemotherapy | Many rural hospitals lack the necessary infrastructure to provide advanced chemotherapy treatments, affecting patient outcomes and causing delays in care. |
| High treatment costs for patients | Surgery + Radiation | The average annual expenditure on cancer treatment in India is estimated at INR 20,000 crores, limiting affordability for many patients and restricting access to necessary therapies. |
| Shortage of trained urology specialists | Urology Specialists | The demand for urology specialists exceeds supply, resulting in longer wait times for patients seeking treatment and impacting timely care delivery. |
| Inconsistent patient follow-up care | Cancer Centers | Many patients do not receive adequate follow-up care after initial treatment, negatively impacting recovery rates and overall health outcomes. |
| Limited awareness of urologic cancers | Bladder Cancer | Despite high incidence rates, awareness campaigns remain insufficient in rural areas, affecting early diagnosis and treatment initiation. |
India Urologic Cancer Market Challenges
The India urologic cancer market still has to solve a few problems, starting with fierce competition among hospitals, which drives down treatment costs and reduces profit margins for providers. Buyers face high treatment expenses, with cancer care expenditures estimated at INR 20,000 crores annually, making essential therapies unaffordable for many patients. Technology adoption is slow, as only 150 cancer treatment centres provide radiation therapy, limiting access to advanced treatment options for those diagnosed. A shortage of trained urology specialists persists, as the training under Medical Council guidelines cannot keep pace with the rising demand for care across urban areas.
Trends in the India Urologic Cancer Market
Buyers and suppliers in the India Urologic Cancer Market are adjusting to the following trends.
- Hospitals Prioritising Advanced Diagnostics: Hospitals are increasingly adopting advanced diagnostic techniques for urologic cancers, with PSA testing accounting for 46% of diagnoses in 2025. This shift improves early detection and treatment outcomes for patients.
- Oncology Clinics Expanding in Tier-2 Cities: Since 2020, oncology clinics have been rapidly expanding in tier-2 cities to meet rising demand, with a projected CAGR of 7.6% for the segment. This expansion increases access to care for underserved populations.
- Shift Towards Immunotherapy: The adoption of immunotherapy in urologic cancer treatment has increased significantly, with a CAGR of 7.1% expected through 2032. This trend reflects advancements in treatment protocols and improved patient outcomes.
- Increased Focus on Patient Education: Since 2021, healthcare providers have been prioritising patient education initiatives, leading to a 20% increase in awareness of urologic cancers. This focus aims to improve early detection and treatment adherence among patients.
Investment Opportunities in the India Urologic Cancer Market
Below are the investment opportunities with the strongest case in the India Urologic Cancer Market.
- Urban Cancer Treatment Centres: Urban cancer treatment centres are in high demand, with over 200 facilities offering radiation therapy. Investment in these centres can improve treatment access for urban populations and enhance patient care.
- Expansion of Immunotherapy Services: With immunotherapy growing significantly, there is a substantial opportunity to supply related services and products. Oncology clinics are key buyers for these advancements, creating a market for innovative therapies.
- Development of Diagnostic Tools: The demand for improved diagnostic tools is evident, with PSA testing recommended for men over 50. Suppliers can partner with hospitals to develop and distribute these tools, improving diagnostic capabilities.
- Investment in Training Urology Specialists: There is a pressing need for trained urology specialists, with hospitals reporting shortages. Investment in training programmes can help meet this demand and improve patient care across healthcare facilities.
Government Initiatives in the India Urologic Cancer Market
The National Cancer Control Programme, revised in 2021, improves screening and treatment access for urologic cancers. This measure requires healthcare providers to implement standardised protocols for early detection and treatment, which improves patient outcomes. Additionally, the Ayushman Bharat scheme, launched in 2020, provides health insurance coverage for cancer treatment to economically weaker sections, ensuring that more patients can access necessary care without financial burden.
The Indian Council of Medical Research supports innovative treatment methods for urologic cancers through its 2023 funding initiative. This funding aims to facilitate research and development in cancer therapies, benefiting hospitals and treatment centres. Furthermore, the National Health Mission's 2022 initiative focuses on increasing awareness and early detection of urologic cancers across India, empowering healthcare providers to educate patients effectively.
Future Insight of the India Urologic Cancer Market
The India urologic cancer market is expected to undergo transformative changes by 2032, particularly with the expansion of oncology clinics in tier-2 cities, which will improve patient access to treatment. The Cancer Care Programme launched in 2022 aims to increase treatment accessibility, ensuring timely care for more patients. By 2032, over 200,000 new cases of bladder cancer will likely prompt advancements in treatment protocols. The National Programme for Prevention and Control of Cancer will continue to prioritise urologic cancer, strengthening the overall healthcare framework.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Cancer Type – Prostate Cancer Dominated, Bladder Cancer Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, with a 41% revenue share in 2025, Prostate Cancer was the largest cancer type category. Prostate cancer is the most prevalent urologic cancer in India, constituting around 25% of all cancer cases. The annual PSA testing recommendation for men over 50 years ensures a consistent flow of diagnosed patients, solidifying its market position. The quickest growth will come from Bladder Cancer, forecast to expand at a CAGR of 7.1% between 2026 and 2032. Bladder cancer is experiencing significant growth, with over 200,000 new cases reported in 2022. This rise highlights the urgent need for improved treatment options and increased public awareness to cater to the expanding patient demographic. Suppliers must focus on developing tailored solutions for bladder cancer to capture the growing market share.
By Treatment Type – Chemotherapy Dominated, Immunotherapy Expected to Grow Fastest
Chemotherapy accounted for a 40% market share by treatment type in 2025. Chemotherapy dominates the market as it is the standard treatment for more than 70% of urologic cancer cases in major hospitals. Its proven effectiveness in managing advanced urologic cancers reinforces its leading position in treatment protocols. Immunotherapy is set to record the highest CAGR in this split, 7.1% over 2026–2032. Immunotherapy is gaining traction as healthcare facilities increasingly incorporate it into their treatment regimens for various urologic cancers. This trend reflects a broader shift towards advanced treatment modalities that are likely to continue growing. Buyers should consider integrating immunotherapy into their offerings to stay competitive in the evolving treatment landscape.
By Diagnosis Method – PSA Testing Dominated, Cytology + Imaging Expected to Grow Fastest
PSA Testing took a 46% share of diagnosis method in 2025, more than any other category. PSA testing is the leading diagnostic method, serving as the primary screening tool for prostate cancer. Its widespread recommendation for men over 50 ensures a high rate of adoption among healthcare providers. Cytology + Imaging is projected to grow fastest, at a CAGR of 8.5% during 2026–2032. Cytology and imaging techniques are rapidly becoming essential for diagnosing bladder and kidney cancers, driven by the need for accurate and timely diagnosis. The increasing incidence of these cancers further propels this growth. Healthcare providers must invest in advanced diagnostic technologies to meet the rising demand for effective urologic cancer detection.
By End User – Hospitals Dominated, Oncology Clinics Expected to Grow Fastest
The largest end user category in 2025 was Hospitals, with a 45% share of total revenue. Hospitals hold the largest market share as they are the primary providers of comprehensive cancer care, handling a significant volume of urologic cancer cases. Their extensive resources and capabilities ensure high-quality treatment and patient management. Over 2026–2032, Oncology Clinics are expected to post the fastest growth, at a CAGR of 7.6%. Oncology clinics are rapidly expanding to address the rising demand for cancer treatment, especially in tier-2 cities. This growth indicates a shift towards more accessible cancer care solutions for patients nationwide. Suppliers should direct their efforts towards oncology clinics to tap into the expanding market and enhance service delivery in underserved areas.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India Urologic Cancer Market Outlook
- Market Size of India Urologic Cancer Market, 2025
- Forecast of India Urologic Cancer Market, 2032
- Historical Data and Forecast of India Urologic Cancer Revenues & Volume for the Period 2022 - 2032F
- India Urologic Cancer Market Trend Evolution
- India Urologic Cancer Market Drivers and Challenges
- India Urologic Cancer Price Trends
- India Urologic Cancer Porter's Five Forces
- India Urologic Cancer Industry Life Cycle
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Cancer Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Prostate Cancer for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Bladder Cancer for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Kidney Cancer for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Testicular Cancer for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Treatment Type for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Hormonal Therapy for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Immunotherapy for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Chemotherapy for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Surgery + Radiation for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Diagnosis Method for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By PSA Testing for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Cytology + Imaging for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Biopsy for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Ultrasound + Markers for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Oncology Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Urology Specialists for the Period 2022 - 2032F
- Historical Data and Forecast of India Urologic Cancer Market Revenues & Volume By Cancer Centers for the Period 2022 - 2032F
- India Urologic Cancer Import Export Trade Statistics
- Market Opportunity Assessment By Cancer Type
- Market Opportunity Assessment By Treatment Type
- Market Opportunity Assessment By Diagnosis Method
- Market Opportunity Assessment By End User
- India Urologic Cancer Top Companies Market Share
- India Urologic Cancer Competitive Benchmarking By Technical and Operational Parameters
- India Urologic Cancer Company Profiles
- India Urologic Cancer Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Cancer Type
- Prostate Cancer
- Bladder Cancer
- Kidney Cancer
- Testicular Cancer
By Treatment Type
- Hormonal Therapy
- Immunotherapy
- Chemotherapy
- Surgery + Radiation
By Diagnosis Method
- PSA Testing
- Cytology + Imaging
- Biopsy
- Ultrasound + Markers
By End User
- Oncology Clinics
- Hospitals
- Urology Specialists
- Cancer Centers































