Japan AI Chip Packaging Market Size & Growth Rate
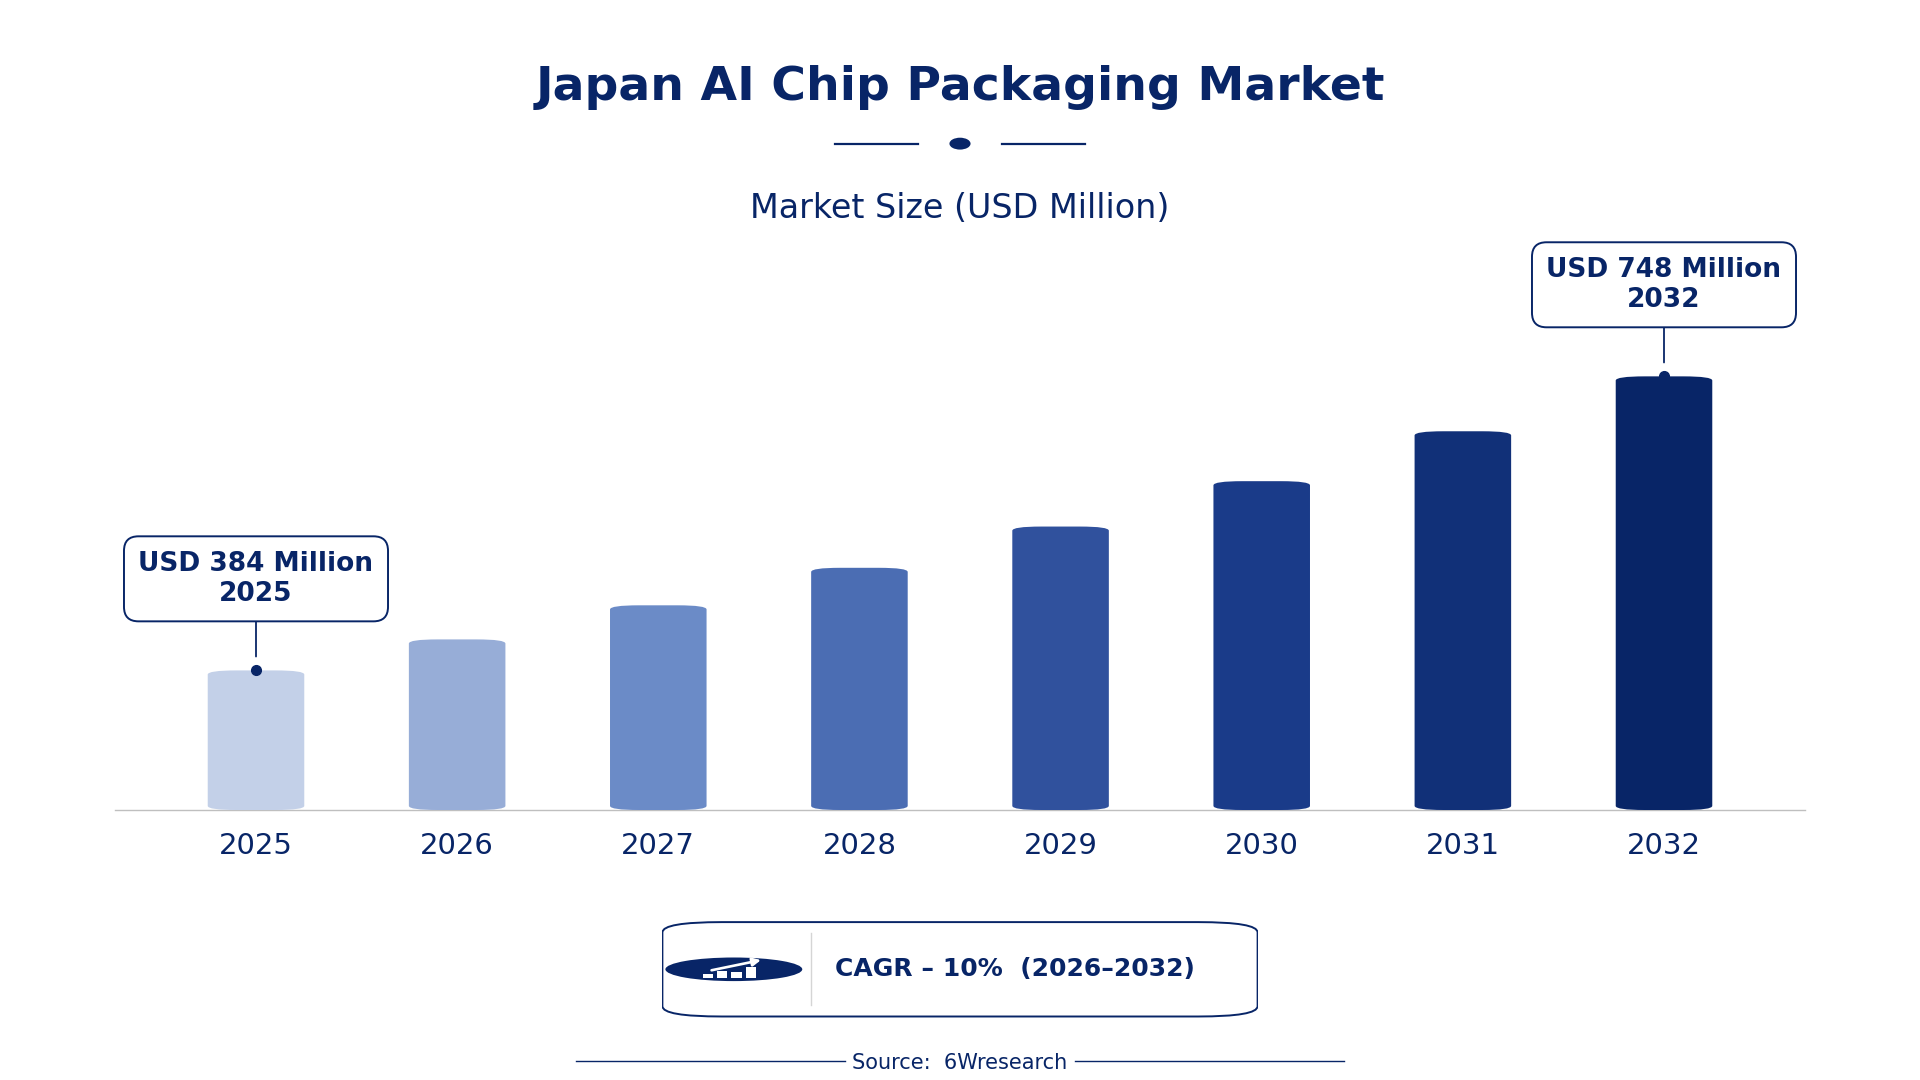
According to 6Wresearch internal database and industry insights, the Japan AI Chip Packaging Market was valued at USD 384 Million in 2025 and is projected to reach USD 748 Million by 2032, growing at a CAGR of approximately 10% during 2026–2032.
Japan AI Chip Packaging Market Highlights
| Report Metric | Details |
| Report Name | Japan AI Chip Packaging Market (2026-2032) |
| Market Size 2025 | USD 384 Million |
| Market Size 2032 | USD 748 Million |
| Absolute Growth 2025–2032 | USD 364 Million |
| CAGR 2026–2032 | 10% |
| Peak Annual Growth | 11.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Packaging Type, 2025 | Flip Chip Packaging (40% share) |
| Leading Material Used, 2025 | Organic Substrate (38% share) |
| Leading Distribution Channel, 2025 | Semiconductor Distributors (51% share) |
| Leading End User, 2025 | AI Chip Manufacturers (47% share) |
| Fastest-Growing Packaging Type | Fan-Out Packaging (14.7% CAGR) |
| Fastest-Growing Material Used | Silicon Interposer (14.1% CAGR) |
| Fastest-Growing Distribution Channel | OEM Direct Sales (13.2% CAGR) |
| Fastest-Growing End User | Data Center Operators (13.4% CAGR) |
| Growing Sector | semiconductor manufacturing |
| Key End Users | AI Chip Manufacturers, Data Center Operators, High-Performance Computing, Edge Device Producers |
Japan AI Chip Packaging Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
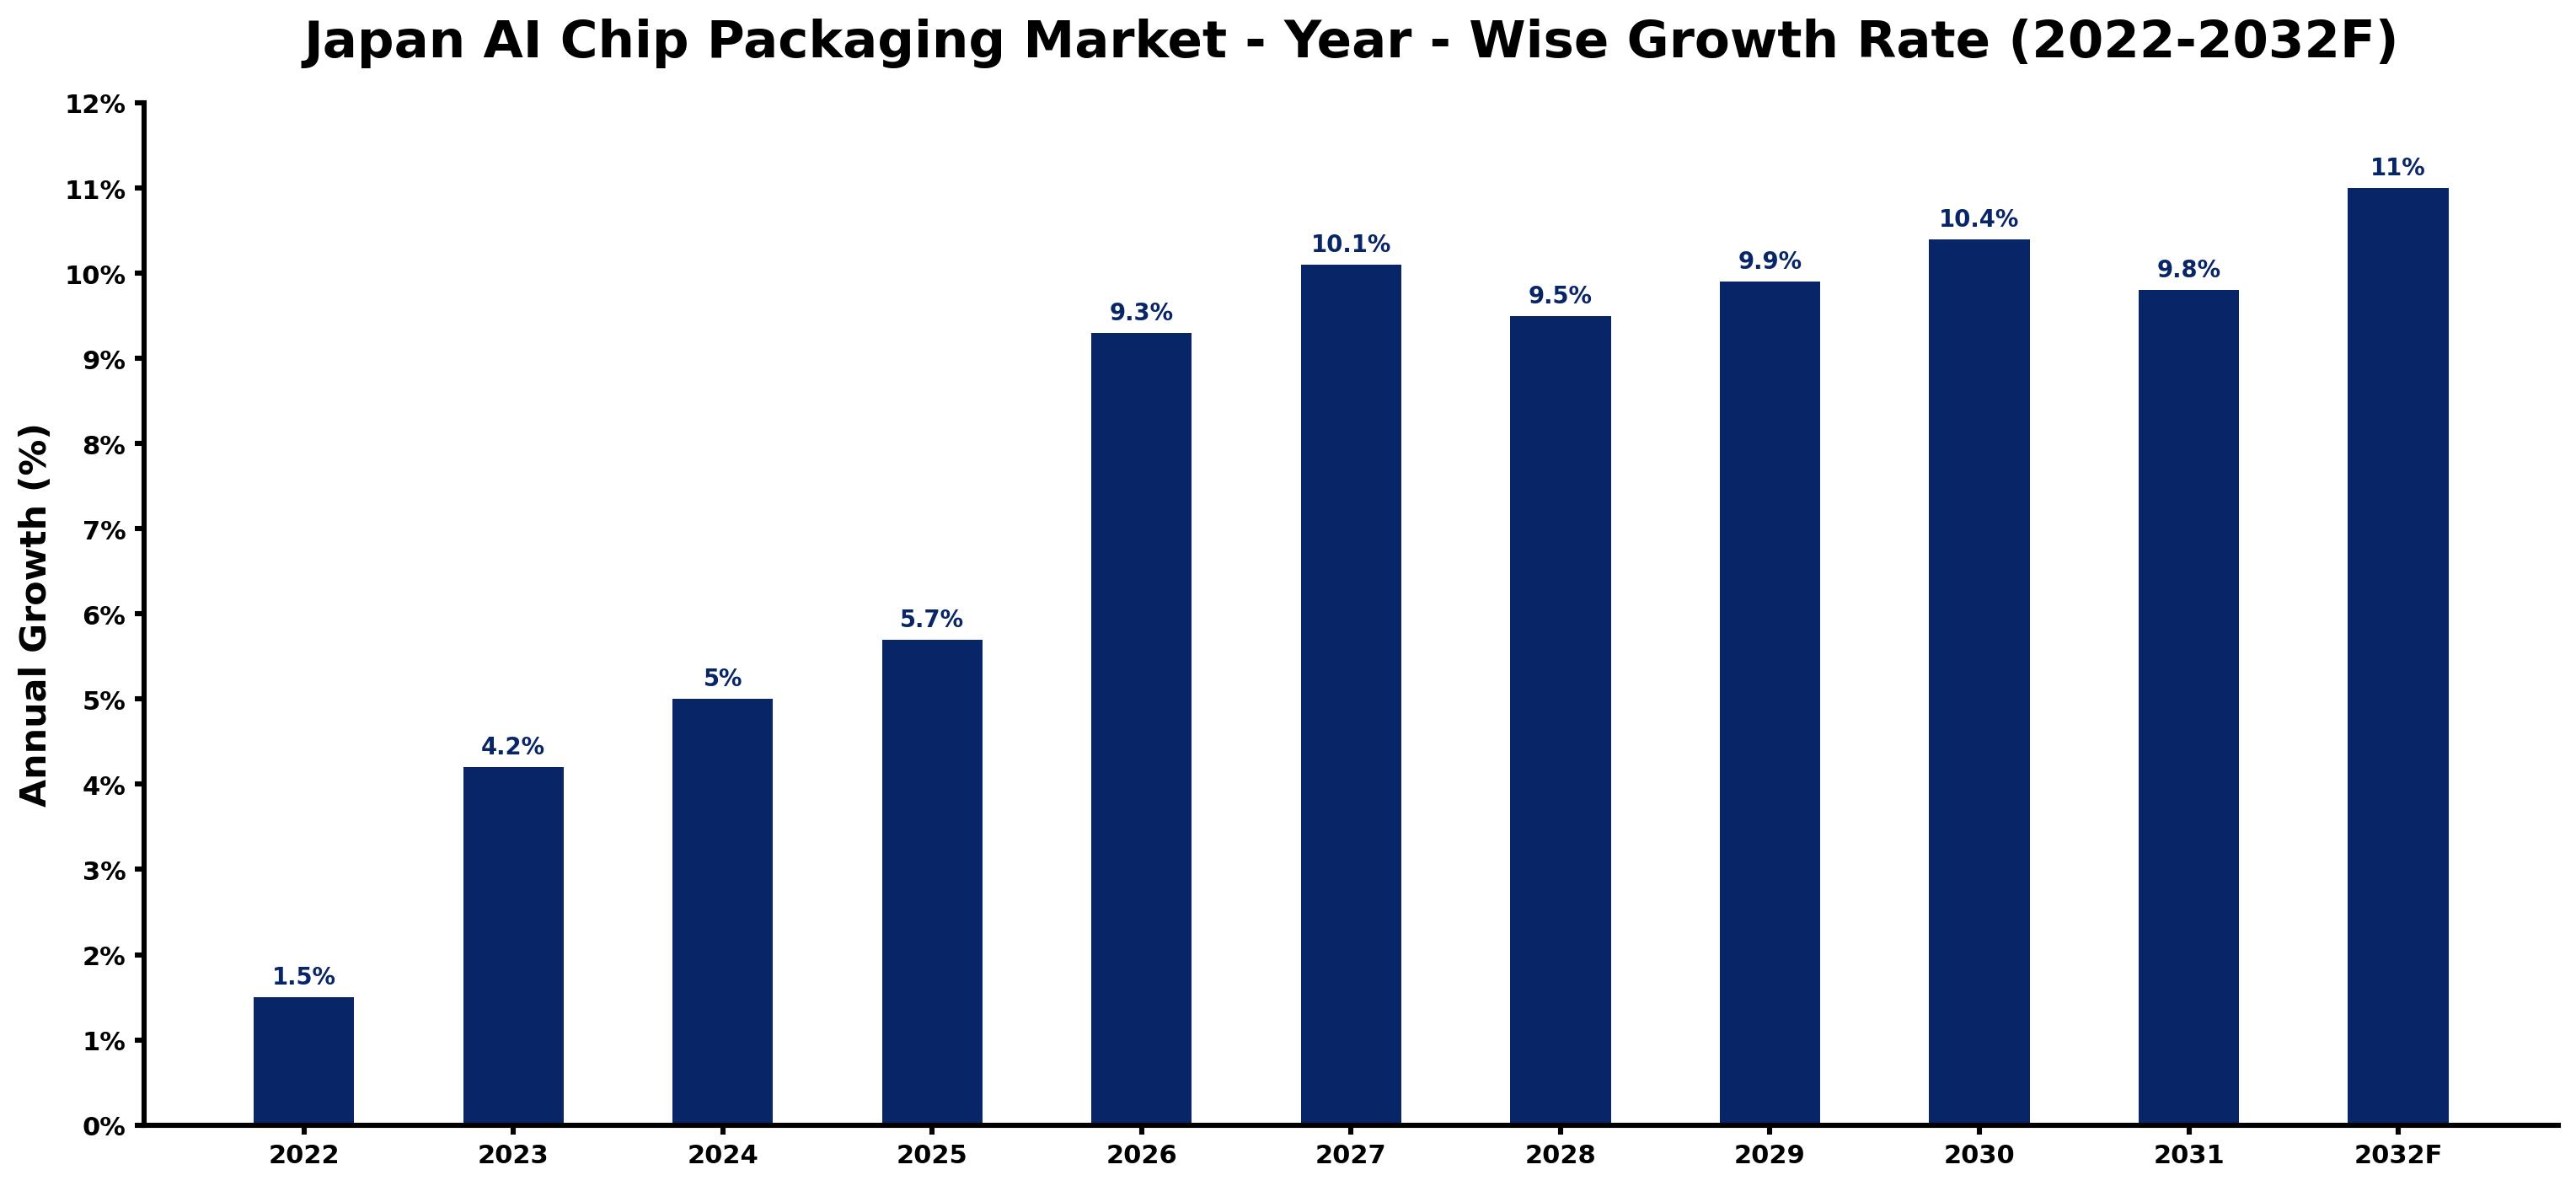
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 1.5 | The market showed steady activity with established semiconductor companies driving demand. |
| 2023 | 4.2 | Growth accelerated as domestic manufacturers increased investments in AI technologies. |
| 2024 | 5.0 | Continued investment in high-performance computing contributed to rising demand. |
| 2025 | 5.7 | The introduction of new AI applications spurred further growth in packaging needs. |
| 2026 | 9.3 | Demand surged as the semiconductor sector is expected to expand in response to innovation. |
| 2027 | 10.1 | Investment in advanced packaging technologies will continue to rise, boosting market growth. |
| 2028 | 9.5 | Growth is projected to slow slightly as the market adjusts to increased production capacities. |
| 2029 | 9.9 | Demand is expected to rebound as AI chip applications expand across various industries. |
| 2030 | 10.4 | Technological advancements in packaging will drive renewed interest and investments. |
| 2031 | 9.8 | Growth is projected to moderate as the market stabilises after rapid expansion in previous years. |
| 2032 | 11.0 | The market is expected to peak with heightened demand from AI applications and data centers. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan AI Chip Packaging Market Synopsis
AI Chip Packaging involves encapsulating and protecting AI chips to ensure their functionality and reliability, utilising processes like molding, layering, and soldering. The Japan AI Chip Packaging Market is growing due to rising demand from domestic semiconductor manufacturers, especially in the Tokyo region, a key hub. The projected annual growth rate of 15% for AI chips through 2025 is further supported by government initiatives like the 'Plastic Resource Circulation Act', which promotes sustainable practices in packaging materials.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising investments in semiconductor manufacturing facilities | Driver | High | Flip Chip Packaging |
| Increased demand for high-performance computing applications | Driver | High | Fan-Out Packaging |
| Growing requirement for advanced packaging solutions in data centers | Opportunity | High | 2.5D/3D Packaging |
| Expansion of AI chip applications in healthcare and automotive sectors | Opportunity | High | Wafer-Level Packaging |
| High costs associated with advanced packaging technologies | Restraint | Medium | Organic Substrate |
| Limited availability of skilled workforce in semiconductor packaging | Restraint | Medium | Epoxy Mold Compound |
| Compliance with stringent environmental regulations | Challenge | High | Silicon Interposer |
| Capacity constraints in production facilities | Challenge | Medium | Solder Bumps |
Evaluation of Drivers in Japan AI Chip Packaging Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in semiconductor manufacturing facilities | Flip Chip Packaging | Japan's semiconductor production reached 1 trillion yen in 2022, driving demand for advanced packaging. |
| Growing demand for AI applications in various sectors | Fan-Out Packaging | The rise of AI technologies is pushing manufacturers to seek improved packaging solutions. |
| Expansion of data centers requiring efficient chip packaging | 2.5D/3D Packaging | Data center operators are investing heavily in AI chips, increasing packaging needs. |
| Technological advancements in packaging processes | Wafer-Level Packaging | Innovations in packaging technology are leading to more compact designs for AI chips. |
| Increased focus on high-performance computing | Organic Substrate | The demand for high-performance computing solutions is driving the need for reliable packaging. |
The strongest pull on demand comes from increased investments in semiconductor manufacturing facilities, with Japan's production reaching 1 trillion yen in 2022. This investment unlocks greater demand for advanced packaging as manufacturers seek efficient solutions. The growing need for AI applications drives demand for improved performance, particularly in sectors like healthcare and automotive. The expansion of data centers necessitates efficient chip packaging, particularly for advanced configurations. Technological advancements are enabling more compact designs, stimulating demand for high-performance packaging solutions.
Evaluation of Restraints in Japan AI Chip Packaging Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced packaging technologies | Organic Substrate | The investment required for advanced packaging solutions can deter smaller manufacturers. |
| Limited availability of skilled workforce in semiconductor packaging | Epoxy Mold Compound | The shortage of trained professionals affects production efficiency and quality. |
| Compliance with stringent environmental regulations | Silicon Interposer | Manufacturers must invest in compliance measures, increasing operational costs. |
| Supply chain disruptions affecting material availability | Solder Bumps | Global supply chain issues can delay production timelines and increase costs. |
| Market saturation in certain packaging types | Fan-Out Packaging | As more players enter the market, competition increases, impacting profitability. |
Japan AI Chip Packaging Market Challenges
In 2022, Japan's semiconductor production reached 1 trillion yen, revealing a skills shortage in advanced packaging techniques that delays project timelines for manufacturers. Buyers encounter rising competition for AI chips, resulting in price increases of up to 20% and extended lead times, complicating their ability to satisfy market demand. Supply chain disruptions arise from reliance on specific materials, causing production delays for packaging firms, which can extend timelines by several weeks. Increasing raw material costs have raised expenses by 15%, compelling producers to pass these costs onto buyers, which may hinder the adoption of new technologies.
Trends in the Japan AI Chip Packaging Market
The trends below show where the Japan AI Chip Packaging Market is heading.
- AI Chip Manufacturers Prioritising High-Performance Computing: AI Chip Manufacturers are increasingly concentrating on high-performance computing solutions, with demand projected to rise. In 2022, Japan's semiconductor production reached 1 trillion yen, reflecting this trend.
- Shift to Advanced Packaging Techniques: The introduction of advanced packaging techniques began in 2023, with notable increases in Fan-Out Packaging adoption. This shift is driven by the need for miniaturisation and improved performance.
- Growing Interest in Sustainable Packaging Solutions: The Plastic Resource Circulation Act, enacted in 2021, has led to a growing interest in sustainable packaging materials. This shift is apparent as manufacturers seek alternatives to traditional plastics.
- Increased Investment in Semiconductor Innovation: The Japanese government's initiatives launched in 2023 aim to boost innovation in semiconductor technologies, with a funding target of 500 billion yen over five years.
Investment Opportunities in the Japan AI Chip Packaging Market
The following opportunities in the Japan AI Chip Packaging Market pair current demand with a clear way in.
- Gap in Advanced Packaging Solutions: With the demand for AI chips expected to grow by 15% annually through 2025, there is a gap in advanced packaging solutions. AI Chip Manufacturers are looking for new materials to enhance performance.
- Timing for Investment in Sustainable Packaging: As the Plastic Resource Circulation Act promotes sustainable practices, there is an opportunity to invest in biodegradable packaging solutions. Semiconductor Distributors are actively seeking eco-friendly alternatives.
- Expansion of Data Centers in Tokyo Region: The Tokyo region's growth in data centers presents an opportunity to supply advanced packaging technologies. With an expected investment of 200 billion yen, suppliers can enter through local partnerships.
- Development of AI Applications in Healthcare: The increasing demand for healthcare AI applications creates a need for specialised packaging solutions. Edge Device Producers are focusing on compact and efficient packaging for these applications.
Government Initiatives in the Japan AI Chip Packaging Market
The Food Sanitation Act amendment in 2018 introduced a positive list system for synthetic resins, improving safety standards for packaging materials. This law, effective from June 2020, has encouraged manufacturers to adopt safer materials in AI Chip Packaging.
The Ministry of Economy, Trade and Industry (METI) has launched initiatives to support semiconductor innovation, including funding for advanced packaging technologies. The 2023 initiative aims to boost production capabilities, benefiting AI Chip Manufacturers.
Future Insight of the Japan AI Chip Packaging Market
The establishment of new semiconductor fabrication facilities will enhance production capabilities by 2032, allowing suppliers to streamline processes and reduce costs. Investments in semiconductor technologies will improve the quality of AI chips available to buyers, facilitating better performance in applications. The implementation of ISO/IEC 60286 standards will ensure reliability and consistency across the industry. As demand for AI chips grows by 15% annually through 2025, suppliers will need to innovate to meet evolving buyer requirements.
Market Segmentation Analysis
Japan AI Chip Packaging Market report covers a detailed analysis of the following market segments:
By Packaging Type – Flip Chip Packaging Leads, Fan-Out Packaging Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Flip Chip Packaging accounted for 40% of the market by packaging type in 2025. Flip Chip Packaging commands the largest share due to its widespread application in high-density interconnections crucial for AI chips. Its extensive use in the Tokyo region's semiconductor manufacturing underlines its importance in meeting industry demands. Over 2026–2032, Fan-Out Packaging is expected to post the fastest growth, at a CAGR of 14.7%. Fan-Out Packaging is witnessing rapid growth as it offers enhanced performance and miniaturization, which are essential for modern semiconductor applications. The increasing need for compact designs in packaging technologies propels this segment's expansion. Suppliers should focus on advancing their Fan-Out Packaging capabilities to capture the growing market interest.
By Material Used – Organic Substrate Leads, Silicon Interposer Expected to Grow Fastest
In 2025, Organic Substrate led the material used split with a 38% share. Organic Substrate leads the market as it is essential for chip interconnection and support, making it a fundamental component in AI chip packaging. Its extensive use among over 1,000 semiconductor companies in Japan reinforces its dominance. The quickest growth will come from Silicon Interposer, forecast to expand at a CAGR of 14.1% between 2026 and 2032. Silicon Interposer is growing quickly due to its ability to facilitate high-speed connections between chips, which is vital for AI applications. The push for faster processing speeds in the semiconductor sector is a key factor in this growth. Buyers should consider sourcing Silicon Interposer materials to stay competitive in the fast-evolving AI chip market.
By Distribution Channel – Semiconductor Distributors Lead, OEM Direct Sales Expected to Grow Fastest
With 51% of distribution channel revenue in 2025, Semiconductor Distributors was the largest category. Semiconductor Distributors dominate the market as they play a vital role in the supply chain and distribution of packaging materials. Their established networks ensure timely access to essential components for manufacturers across Japan. OEM Direct Sales is set to record the highest CAGR in this split, 13.2% over 2026–2032. OEM Direct Sales is growing the fastest because it provides bespoke solutions directly to manufacturers, catering to their specific packaging needs. This trend reflects a broader shift towards customised offerings in the semiconductor industry. Suppliers need to enhance their direct sales approaches to effectively address the increasing demand for tailored packaging solutions.
By End User – AI Chip Manufacturers Lead, Data Center Operators Expected to Grow Fastest
AI Chip Manufacturers took 47% of end user revenue in 2025, more than any other category. AI Chip Manufacturers hold the largest share as they are the primary consumers of packaging technologies that ensure product performance and reliability. Their significant investments in advanced packaging methods are a key factor in maintaining this leading position. Data Center Operators are projected to grow fastest, at a CAGR of 13.4% during 2026–2032. Data Center Operators represent the fastest-growing segment as they increasingly depend on packaged AI chips for improved operational efficiency and reliability. The surging data processing requirements within data centres drive this rapid growth. Manufacturers should prioritise the development of packaging solutions specifically designed for the unique requirements of data centre operators.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan AI Chip Packaging Market Outlook
- Market Size of Japan AI Chip Packaging Market, 2025
- Forecast of Japan AI Chip Packaging Market, 2032
- Historical Data and Forecast of Japan AI Chip Packaging Revenues & Volume for the Period 2022-2032F
- Japan AI Chip Packaging Market Trend Evolution
- Japan AI Chip Packaging Market Drivers and Challenges
- Japan AI Chip Packaging Price Trends
- Japan AI Chip Packaging Porter's Five Forces
- Japan AI Chip Packaging Industry Life Cycle
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Packaging Type for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Flip Chip Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Fan-Out Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By 2.5D/3D Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Wafer-Level Packaging for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Material Used for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Organic Substrate for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Epoxy Mold Compound for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Silicon Interposer for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Solder Bumps for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Semiconductor Distributors for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By OEM Direct Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Online Tech Platforms for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Specialty Stores for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By AI Chip Manufacturers for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By High-Performance Computing for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Data Center Operators for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Chip Packaging Market Revenues & Volume By Edge Device Producers for the Period 2022-2032F
- Japan AI Chip Packaging Import Export Trade Statistics
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By Material Used
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan AI Chip Packaging Top Companies Market Share
- Japan AI Chip Packaging Competitive Benchmarking By Technical and Operational Parameters
- Japan AI Chip Packaging Company Profiles
- Japan AI Chip Packaging Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Packaging Type
- Flip Chip Packaging
- Fan-Out Packaging
- 2.5D/3D Packaging
- Wafer-Level Packaging
By Material Used
- Organic Substrate
- Epoxy Mold Compound
- Silicon Interposer
- Solder Bumps
By Distribution Channel
- Semiconductor Distributors
- OEM Direct Sales
- Online Tech Platforms
- Specialty Stores
By End User
- AI Chip Manufacturers
- High-Performance Computing
- Data Center Operators
- Edge Device Producers































