Japan AI Hardware Market Size & Growth Rate
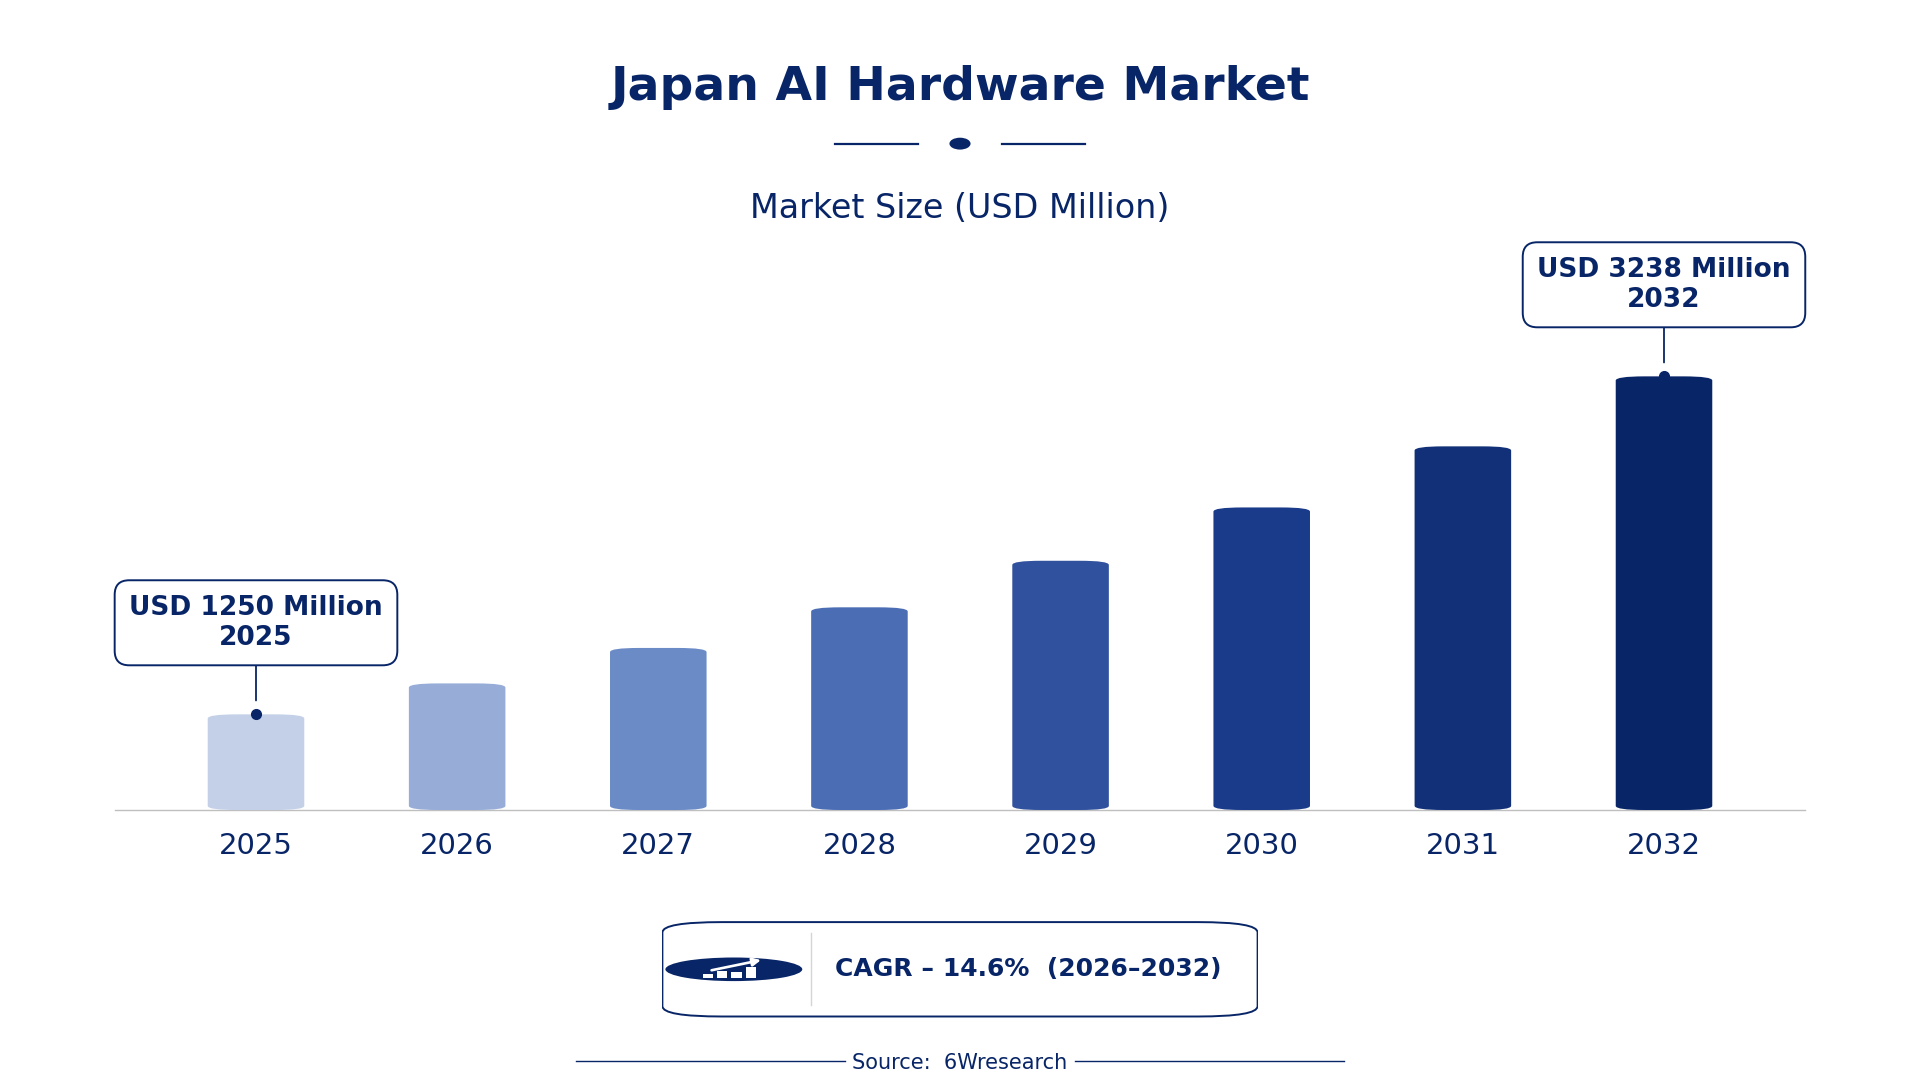
According to 6Wresearch internal database and industry insights, the Japan AI Hardware Market was valued at USD 1,250 Million in 2025 and is projected to reach USD 3,238 Million by 2032, growing at a CAGR of approximately 14.6% during 2026–2032.
Japan AI Hardware Market Highlights
| Report Metric | Details |
| Report Name | Japan AI Hardware Market (2026-2032) |
| Market Size 2025 | USD 1,250 Million |
| Market Size 2032 | USD 3,238 Million |
| Absolute Growth 2025–2032 | USD 1,988 Million |
| CAGR 2026–2032 | 14.6% |
| Peak Annual Growth | 16.2% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Hardware Type, 2025 | GPUs (49% share) |
| Leading Functionality, 2025 | High-speed Training (36% share) |
| Leading Distribution Channel, 2025 | OEM Sales (51% share) |
| Leading End User, 2025 | Cloud Providers (36% share) |
| Fastest-Growing Hardware Type | ASICs (20.5% CAGR) |
| Fastest-Growing Functionality | Edge Inference (20.1% CAGR) |
| Fastest-Growing End User | Smart Device Companies (19.9% CAGR) |
| Growing Sector | AI technology applications |
| Key End Users | Technology firms, research institutions, cloud providers, AI startups |
Japan AI Hardware Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
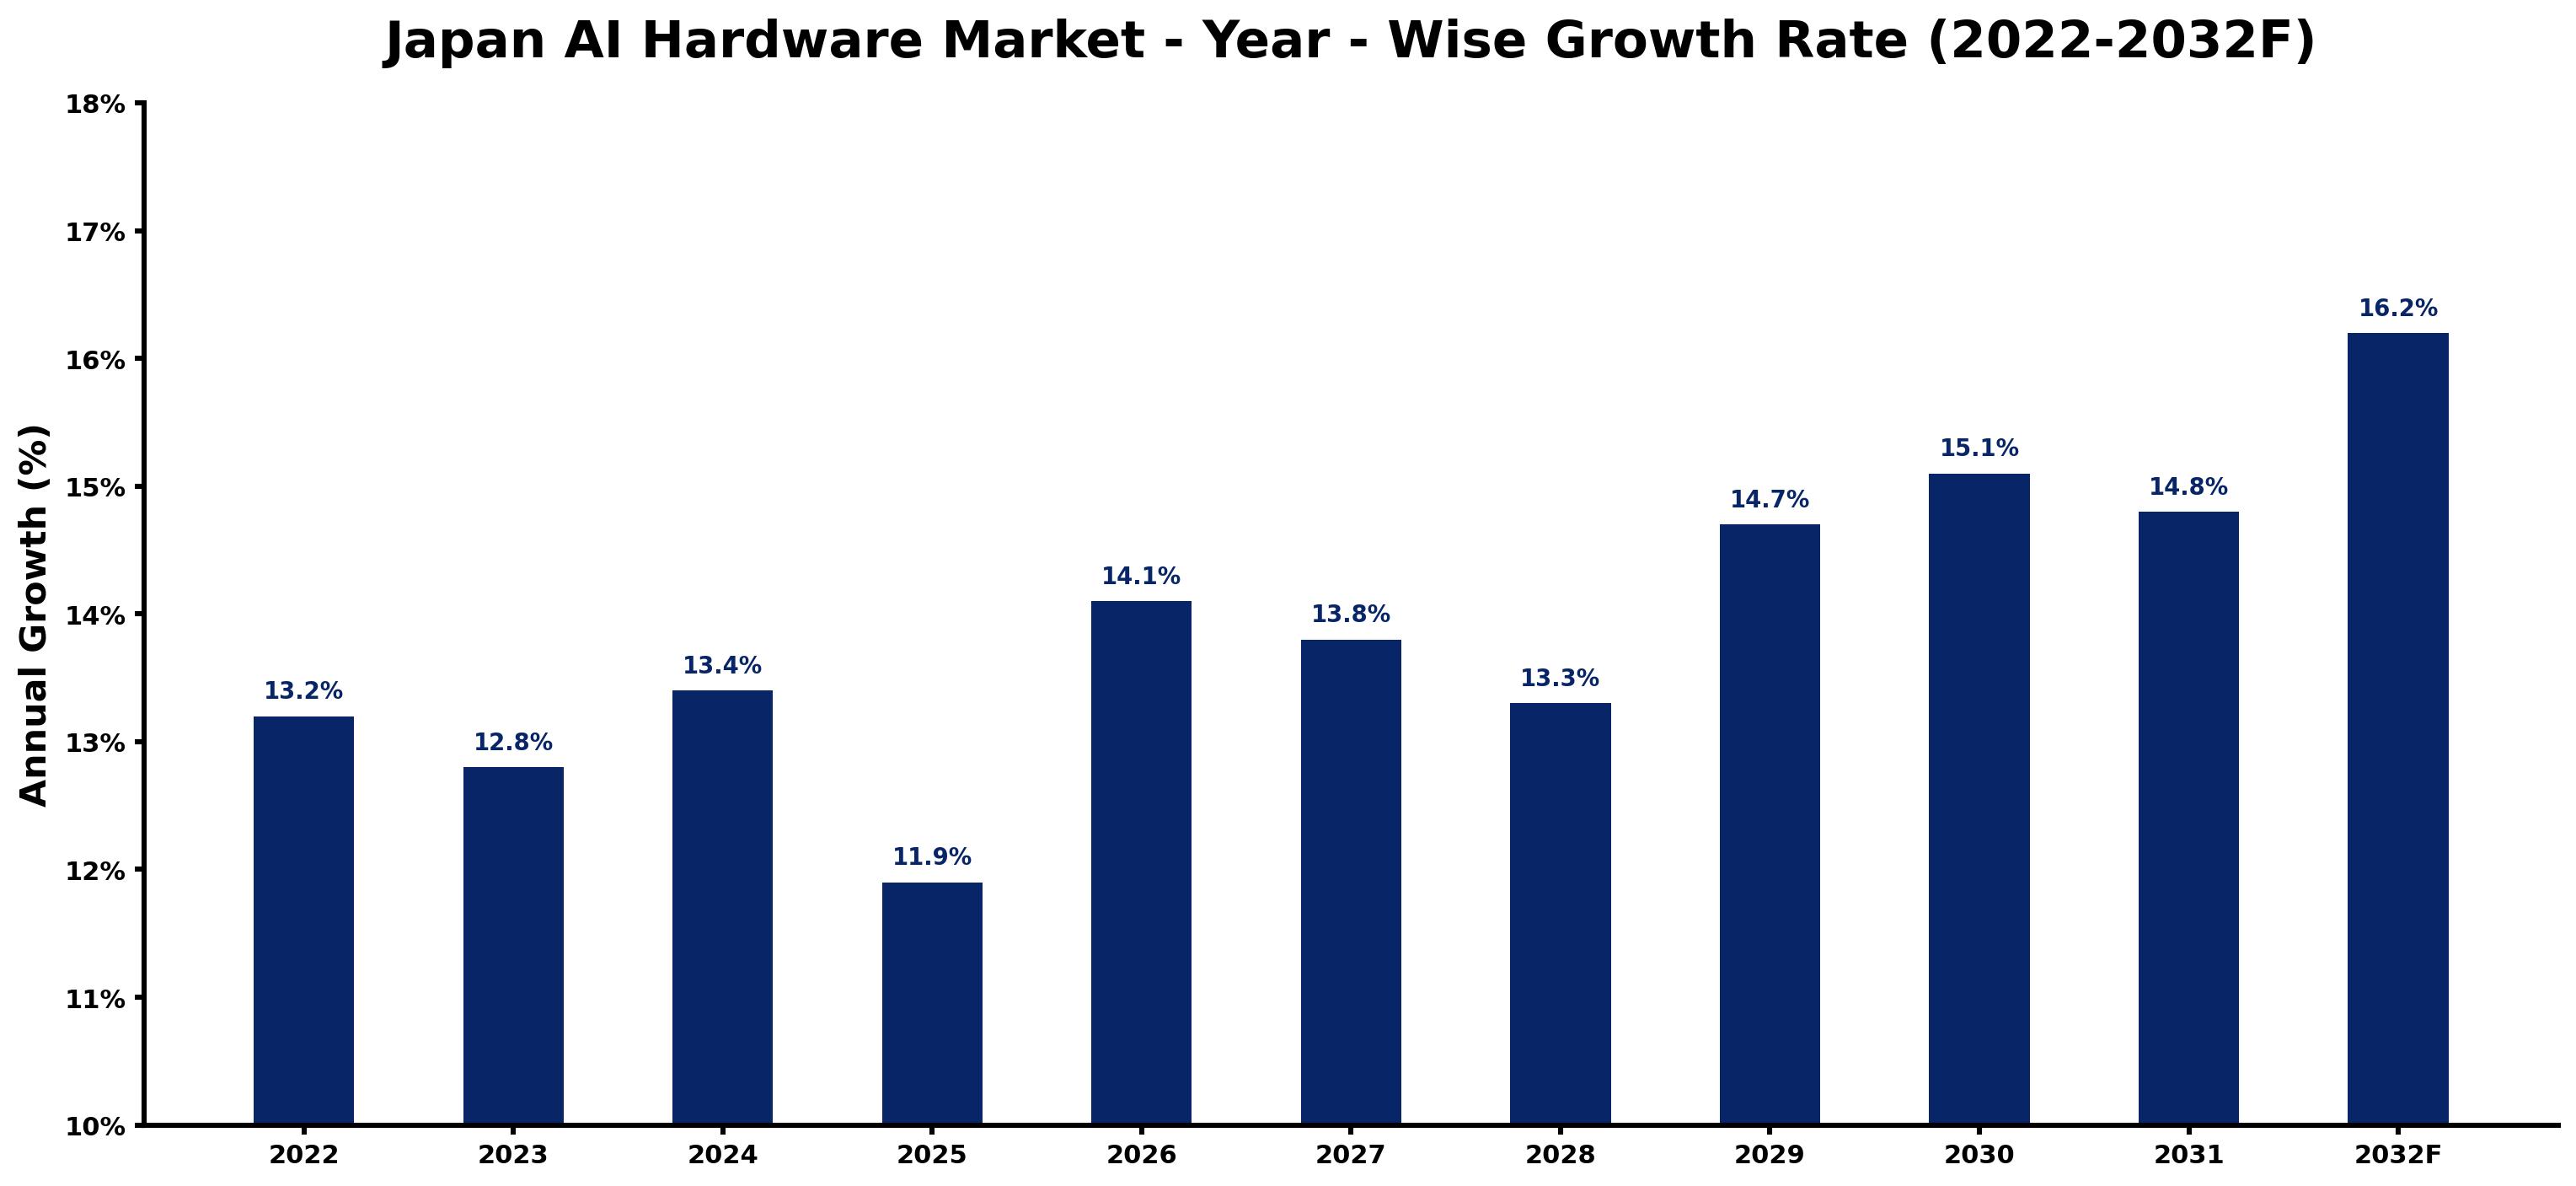
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 13.2 | The market experienced steady growth due to increasing technology adoption. |
| 2023 | 12.8 | Growth slowed slightly as firms adjusted to supply chain challenges. |
| 2024 | 13.4 | Demand surged as technology firms expanded their AI capabilities. |
| 2025 | 11.9 | Growth moderated as the market matured and competition intensified. |
| 2026 | 14.1 | Investment in AI infrastructure is expected to rise, boosting demand for hardware. |
| 2027 | 13.8 | Growth is projected to slow as market saturation begins to affect new orders. |
| 2028 | 13.3 | Demand will remain stable as firms focus on optimizing existing systems. |
| 2029 | 14.7 | Technological advancements are expected to drive renewed interest in AI applications. |
| 2030 | 15.1 | Investment in AI startups will increase, further driving hardware demand. |
| 2031 | 14.8 | Growth is projected to slow as the market stabilises after rapid expansion. |
| 2032 | 16.2 | The peak year will see increased investment in AI hardware capabilities. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan AI Hardware Market Synopsis
AI hardware includes specialized computing devices such as GPUs, NPUs, ASICs, and FPGAs, essential for artificial intelligence applications. The Japan AI Hardware Market is expanding due to strong domestic demand from technology firms and research institutions, supported by initiatives such as the 'AI Strategy 2022'. The government aims to increase AI startups by 30% by 2025, driving further investment and innovation in this sector. This growth is propelled by the rising need for efficient AI solutions across various industries, creating opportunities for suppliers.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing domestic demand for AI applications | Driver | High | GPUs |
| Investment in AI startups and technology infrastructure | Driver | High | ASICs |
| Increasing demand for real-time data processing solutions | Opportunity | High | Edge Inference |
| Need for tailored AI solutions in various industries | Opportunity | Medium | Task-Specific AI Ops |
| High costs associated with advanced semiconductor manufacturing | Restraint | High | FPGAs |
| Competition from international AI hardware suppliers | Restraint | Medium | GPUs |
| Supply chain disruptions affecting component availability | Challenge | High | ASICs |
| Rapid technological changes leading to obsolescence | Challenge | Medium | NPUs |
Evaluation of Drivers in Japan AI Hardware Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased adoption of AI technologies across sectors | GPUs | The installed base of GPUs in Japan is estimated at 2 million units, driving demand from technology firms. |
| Growing investment in AI startups and research | ASICs | The AI Accelerator program aims to establish 100 new AI startups by 2025, increasing demand for specialized hardware. |
| Rising need for real-time processing in edge applications | NPUs | FPGAs are increasingly used in telecommunications for AI applications, driving demand for efficient processing solutions. |
| Expansion of cloud-based AI services | Cloud Providers | Cloud Providers accounted for 36% of the end-user market in 2025, driving sales of AI hardware. |
| Government initiatives promoting AI technology adoption | High-speed Training | The Ministry of Internal Affairs and Communications promotes AI technology adoption, boosting demand for training hardware. |
Behind the steady rise in orders sits a surge in AI technology adoption, with the installed base of GPUs in Japan estimated at 2 million units. The growing need for real-time processing in edge applications drives demand for NPUs, particularly in telecommunications, where FPGAs are increasingly utilized. Cloud-based AI services are expanding, with Cloud Providers expected to account for 36% of the end-user market in 2025.
Evaluation of Restraints in Japan AI Hardware Market
The main factors holding the market back are set out below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs associated with advanced semiconductor manufacturing | FPGAs | Japan's semiconductor industry faces high production costs, limiting the affordability of advanced AI hardware. |
| Intense competition from international suppliers | GPUs | Local manufacturers struggle to compete with lower-priced imports, affecting market share. |
| Supply chain disruptions affecting component availability | ASICs | Global supply chain issues have led to delays in component availability, impacting production schedules. |
| Rapid technological changes leading to obsolescence | NPUs | The fast pace of AI technology evolution can render existing hardware obsolete, deterring investment. |
| Limited domestic production capacity for specific components | High-speed Training | Japan's reliance on imports for certain AI hardware components restricts local production capabilities. |
Japan AI Hardware Market Challenges
In 2023, Japan's AI hardware sector faced a skills shortage, with technology firms unable to fill 25% of engineering positions, delaying project timelines for buyers. Complex regulations surrounding standards like JIS X 0160 can extend product approval processes by up to six months, impacting suppliers' ability to launch new innovations. High production costs, driven by advanced semiconductor fabrication processes, force buyers to pay 15% more than global averages, reducing their competitiveness. Unpredictable demand fluctuations, influenced by global trends, can lead to sales volume variations of 20%, complicating inventory management for suppliers.
Trends in the Japan AI Hardware Market
The following changes are redrawing the Japan AI Hardware Market.
- Shift in AI Research Focus to Tokyo: Tokyo has emerged as a major hub for AI research and development activities, attracting substantial investment. In 2023, AI hardware sales through online platforms increased by 15%, reflecting this trend.
- Rise in Edge Computing Applications: The demand for real-time data processing has surged, particularly in telecommunications. FPGAs are increasingly utilised in this sector, demonstrating a 20% growth in their application since 2022.
- Growth of AI Startups in Japan: The AI Accelerator program aims to establish 100 new AI startups by 2025, driving innovation in the sector. This initiative is expected to increase the number of startups by 30% by 2025.
- Increased Focus on AI Standards: The Japan Electronics and Information Technology Industries Association advocates for AI hardware standards, such as JIS X 0160. This standardisation is important for ensuring compatibility and performance across devices.
Investment Opportunities in the Japan AI Hardware Market
Several openings in the Japan AI Hardware Market merit attention from investors.
- Joint Ventures for AI Hardware Production: Partnering with local manufacturers presents opportunities to supply AI hardware components. The Tokyo Metropolitan Government supports AI innovation through funding programs, making this an attractive entry point.
- Investment in High-Speed Training Solutions: The demand for efficient training solutions is rising, with a projected increase in AI applications. Cloud Providers are seeking advanced hardware to meet their service needs, creating a gap for suppliers.
- Expansion of Online Sales Channels: AI hardware sales through online platforms increased by 15% in 2023, indicating a growing opportunity. Suppliers can capitalise on this trend by enhancing their online presence and distribution capabilities.
- Development of Custom AI Hardware: With the rise of unique AI applications, there is a significant gap in the market for custom solutions. AI Accelerator Startups are particularly interested in tailored hardware to meet their specific needs.
Government Initiatives in the Japan AI Hardware Market
The Semiconductor and Digital Industry Strategy, established by METI in June 2021, aims to secure domestic semiconductor manufacturing. This measure is important for AI hardware producers, ensuring a stable supply of components and reducing reliance on imports. The government allocated ¥10 billion for AI technology initiatives in 2023, further supporting the development of AI hardware in Japan.
The Digital Agency, launched in 2021, oversees AI initiatives and facilitates funding for projects. This agency ensures that technology firms and research institutions can access the necessary resources to implement AI solutions effectively, supporting the growth of the AI hardware market.
Future Insight of the Japan AI Hardware Market
The AI Accelerator program will support new startups, driving innovation in the sector. By 2032, advancements in semiconductor fabrication will improve AI hardware efficiency, benefiting both buyers and suppliers. The 'Smart City' initiative will increase demand for AI solutions in urban planning, creating new growth opportunities. Government funding of ¥10 billion for AI technology initiatives will stimulate research and development, positioning Japan as a leader in AI hardware.
Market Segmentation Analysis
Japan AI Hardware Market report covers a detailed analysis of the following market segments:
By Hardware Type – GPUs Leads, ASICs Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, GPUs held 49% of the Japan AI Hardware Market by hardware type in 2025. GPUs hold the largest share due to their widespread use in training models, particularly among technology firms in urban centres like Tokyo. Their established presence, with an estimated installed base of 2 million units, underscores their critical role in the market. Over 2026–2032, ASICs are expected to post the fastest growth, at a CAGR of 20.5%. ASICs are experiencing rapid growth as they are specifically designed for certain tasks, greatly enhancing efficiency in sectors such as telecommunications. This trend is likely to persist as industries increasingly prioritise performance and optimisation. Suppliers should focus on developing ASICs to cater to the growing demand for specialised computing solutions.
By Functionality – High-speed Training Leads, Edge Inference Expected to Grow Fastest
High-speed Training took 36% of functionality revenue in 2025, more than any other category. High-speed Training leads the functionality segment as it is vital for efficiently processing large datasets, a primary focus for many research institutions in Japan. Government initiatives promoting AI technology further emphasise the significance of this capability. The quickest growth will come from Edge Inference, forecast to expand at a CAGR of 20.1% between 2026 and 2032. Edge Inference is the fastest-growing functionality because it enables immediate data processing on devices, which is essential for applications in smart city projects. The rising demand for real-time analytics is driving this segment's expansion. Buyers should invest in technologies that improve edge inference to maintain competitiveness in the market.
By Distribution Channel – OEM Sales Leads and Records the Fastest Growth
With 51% of distribution channel revenue in 2025, OEM Sales was the largest category. OEM Sales dominate the distribution channel by integrating hardware into final products, allowing technology firms to provide comprehensive solutions. This channel is crucial for ensuring efficiency within the AI hardware supply chain. OEM Sales is also forecast to expand faster than any other category, at a CAGR of 16.0% over 2026–2032. OEM Sales are also the fastest-growing channel, spurred by the increasing demand for integrated solutions among manufacturers. The combination of hardware and software in OEM products is propelling this segment's growth. Suppliers should strengthen partnerships with OEMs to enhance their market presence and operational effectiveness.
By End User – Cloud Providers Lead, Smart Device Companies Expected to Grow Fastest
The largest end user category in 2025 was Cloud Providers, at 36% of revenue. Cloud Providers represent the largest end-user segment as they utilise hardware for delivering cloud services to a wide customer base in Japan. Their reliance on advanced infrastructure drives the demand for high-performance components. Smart Device Companies are projected to grow fastest, at a CAGR of 19.9% during 2026–2032. Smart Device Companies are the fastest-growing end-user segment, increasingly incorporating hardware into consumer electronics to meet rising consumer expectations. This trend is anticipated to accelerate as technology continues to progress. Suppliers must align their offerings with the needs of smart device companies to capitalise on emerging market opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan AI Hardware Market Outlook
- Market Size of Japan AI Hardware Market, 2025
- Forecast of Japan AI Hardware Market, 2032
- Historical Data and Forecast of Japan AI Hardware Revenues & Volume for the Period 2022-2032F
- Japan AI Hardware Market Trend Evolution
- Japan AI Hardware Market Drivers and Challenges
- Japan AI Hardware Price Trends
- Japan AI Hardware Porter's Five Forces
- Japan AI Hardware Industry Life Cycle
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Hardware Type for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By GPUs for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By NPUs for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By ASICs for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By FPGAs for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Functionality for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By High-speed Training for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Edge Inference for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Task-Specific AI Ops for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Custom AI Hardware for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Semiconductor Dealers for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By OEM Sales for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Online Platforms for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Industrial Tech Suppliers for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Cloud Providers for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Smart Device Companies for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By AI Accelerator Startups for the Period 2022-2032F
- Historical Data and Forecast of Japan AI Hardware Market Revenues & Volume By Autonomous Vehicle Developers for the Period 2022-2032F
- Japan AI Hardware Import Export Trade Statistics
- Market Opportunity Assessment By Hardware Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Distribution Channel
- Market Opportunity Assessment By End User
- Japan AI Hardware Top Companies Market Share
- Japan AI Hardware Competitive Benchmarking By Technical and Operational Parameters
- Japan AI Hardware Company Profiles
- Japan AI Hardware Key Strategic Recommendations
Market Covered
The following segment groups are covered in the report.
By Hardware Type
- GPUs
- NPUs
- ASICs
- FPGAs
By Functionality
- High-speed Training
- Edge Inference
- Task-Specific AI Ops
- Custom AI Hardware
By Distribution Channel
- Semiconductor Dealers
- OEM Sales
- Online Platforms
- Industrial Tech Suppliers
By End User
- Cloud Providers
- Smart Device Companies
- AI Accelerator Startups
- Autonomous Vehicle Developers































