Japan Inflight Entertainment Market Size & Growth Rate
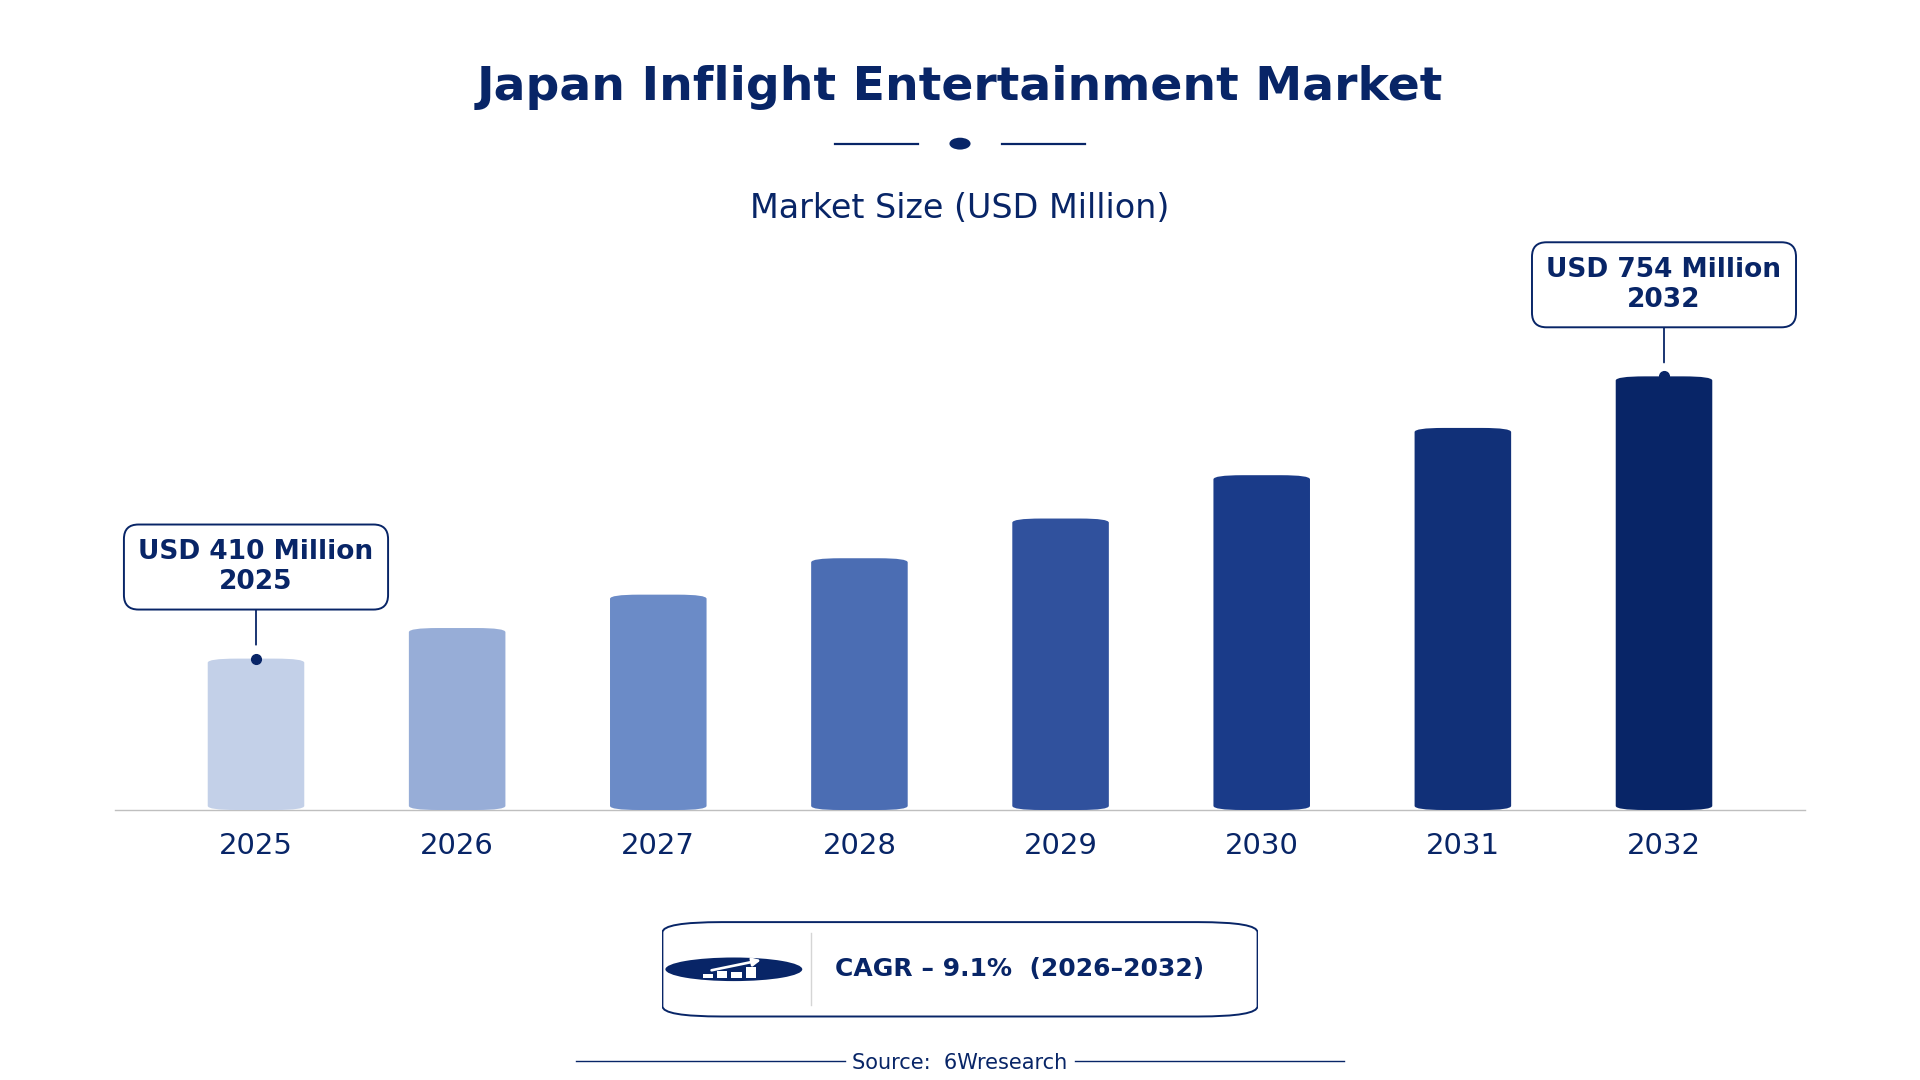
According to 6Wresearch internal database and industry insights, the Japan Inflight Entertainment Market was valued at USD 410 Million in 2025 and is projected to reach USD 754 Million by 2032, growing at a CAGR of approximately 9.1% during 2026–2032.
Japan Inflight Entertainment Market Highlights
| Report Metric | Details |
| Report Name | Japan Inflight Entertainment Market (2026-2032) |
| Market Size 2025 | USD 410 Million |
| Market Size 2032 | USD 754 Million |
| Absolute Growth 2025–2032 | USD 344 Million |
| CAGR 2026–2032 | 9.1% |
| Peak Annual Growth | 10.9% in 2028 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Content Type, 2025 | Video on Demand (39% share) |
| Leading Delivery Mode, 2025 | Personal Screens (40% share) |
| Leading Passenger Class, 2025 | Economy / Business (36% share) |
| Leading Distribution Channel, 2025 | Content Aggregators (40% share) |
| Fastest-Growing Content Type | Streaming Platforms (12.9% CAGR) |
| Fastest-Growing Delivery Mode | Wi-Fi Dependent (11.6% CAGR) |
| Fastest-Growing Passenger Class | All Aircraft (12.5% CAGR) |
| Fastest-Growing Distribution Channel | Entertainment Providers (11.9% CAGR) |
| Growing Sector | Airline Industry |
| Key End Users | Airlines, Passengers, Content Providers, Technology Vendors |
Japan Inflight Entertainment Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
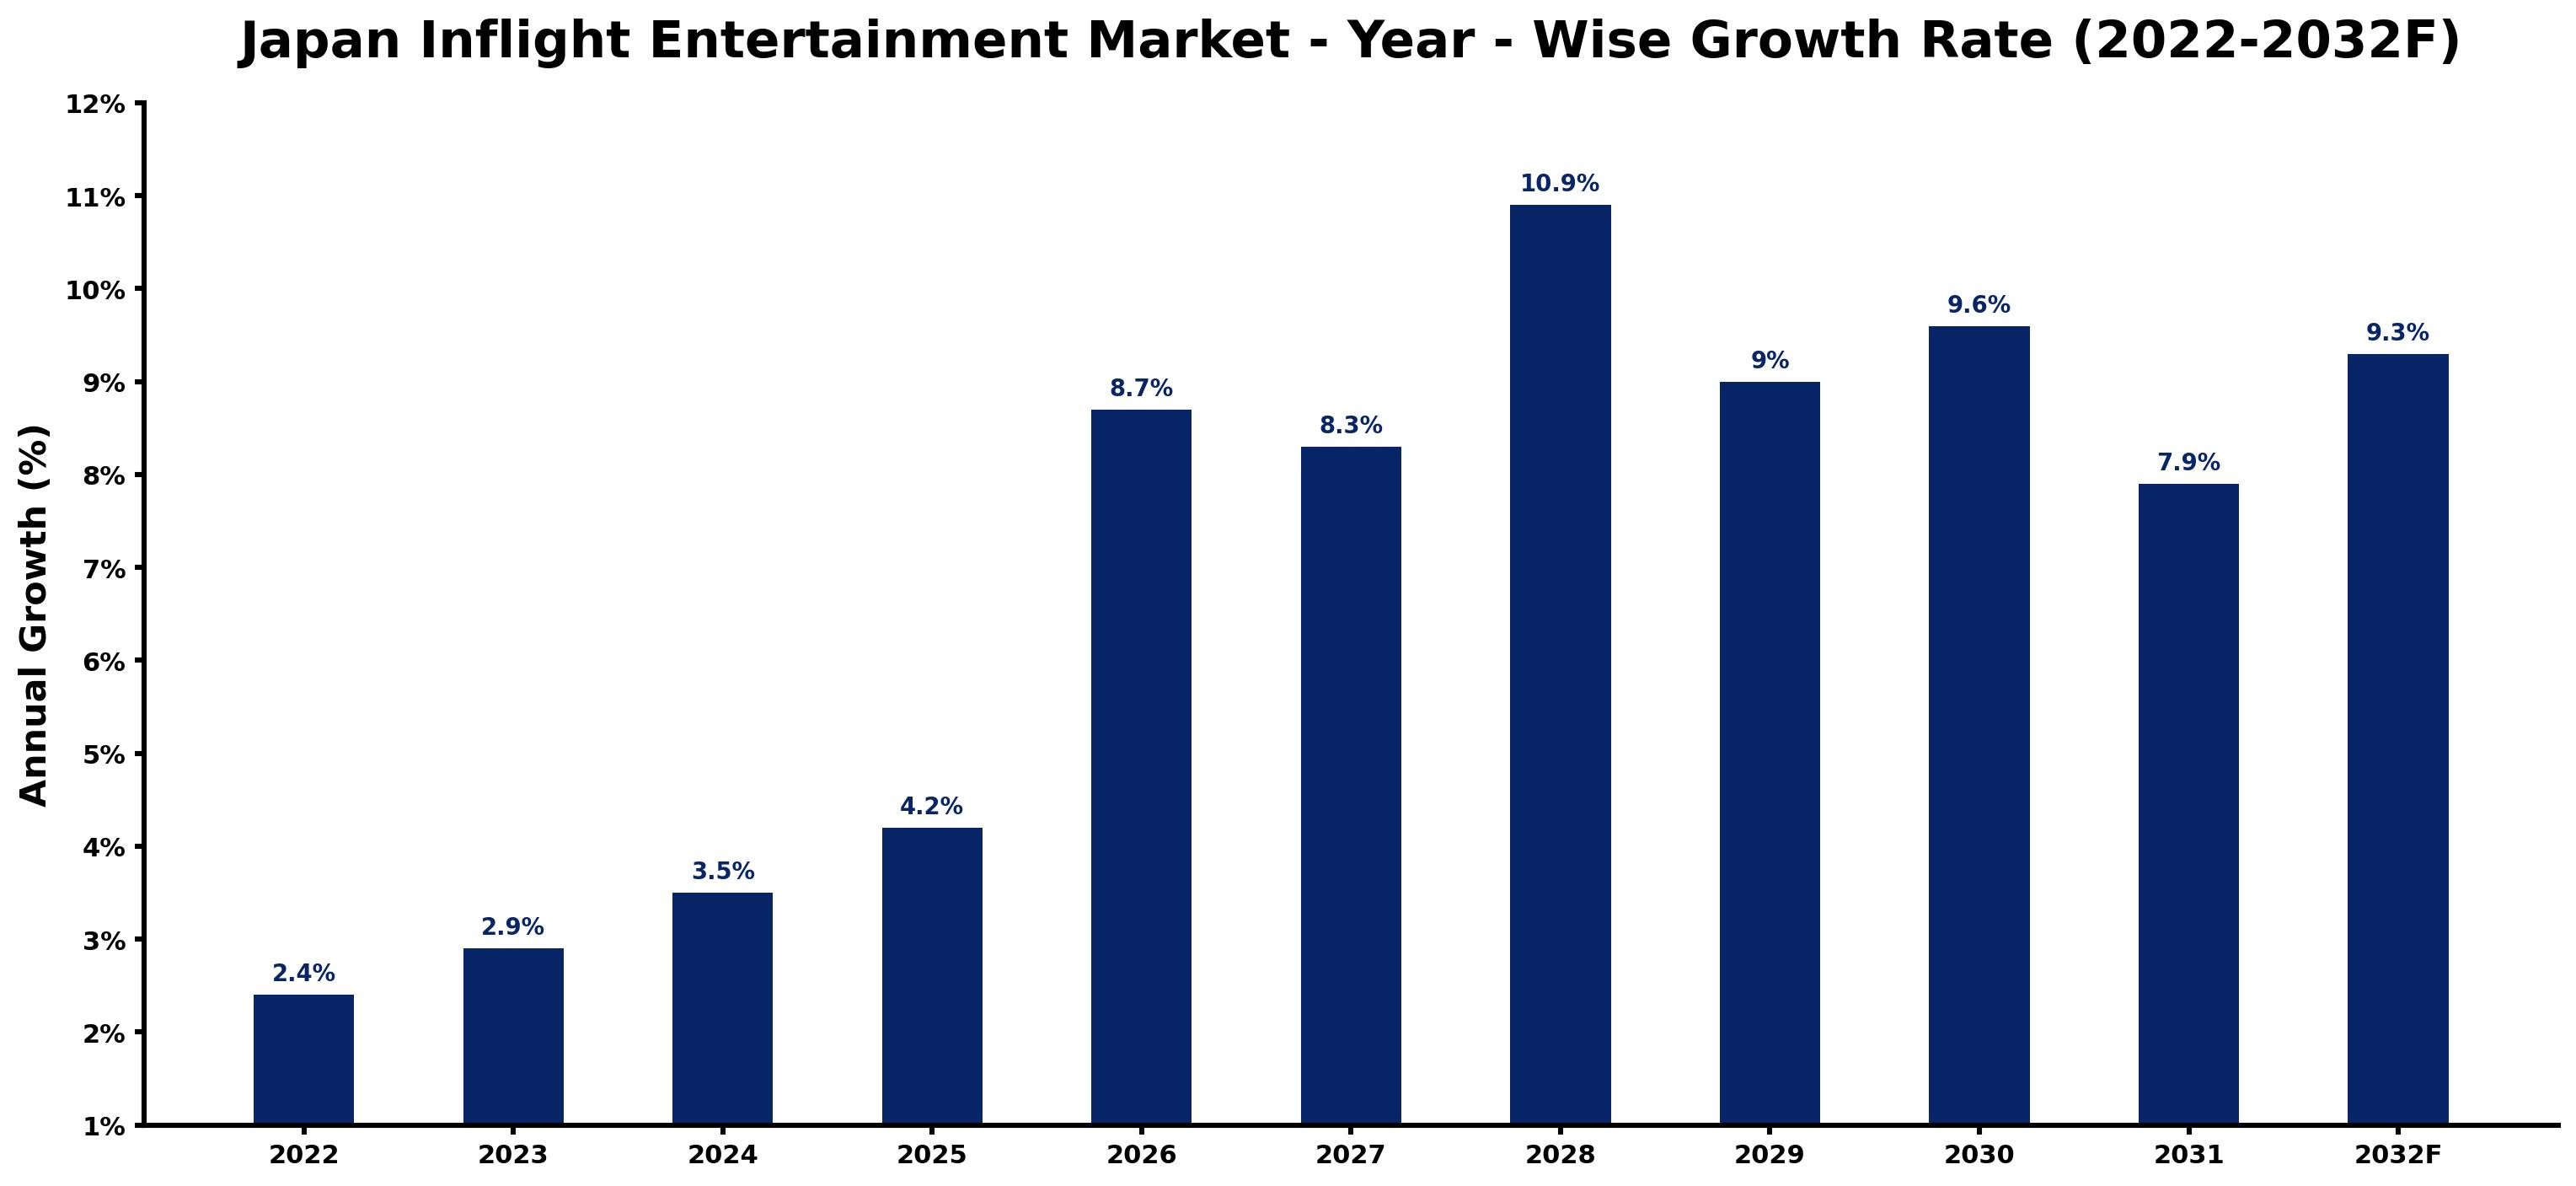
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.4 | The market experienced moderate growth as airlines began upgrading inflight systems. |
| 2023 | 2.9 | Growth accelerated as more airlines adopted advanced inflight entertainment technologies. |
| 2024 | 3.5 | Demand rose further with increased passenger expectations for entertainment options. |
| 2025 | 4.2 | The market peaked with substantial investments in personal screens and Wi-Fi solutions. |
| 2026 | 8.7 | Growth surged as airlines will expand Wi-Fi dependent services for passengers. |
| 2027 | 8.3 | The market growth slowed slightly as competition intensified among service providers. |
| 2028 | 10.9 | A peak in growth occurred as streaming platforms gained widespread acceptance. |
| 2029 | 9.0 | Growth moderated as market saturation began to impact new installations. |
| 2030 | 9.6 | Demand is expected to increase again as airlines focus on improving passenger experiences. |
| 2031 | 7.9 | The market growth slowed as airlines faced challenges in upgrading older fleets. |
| 2032 | 9.3 | Continued investment in digital content will support steady growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Inflight Entertainment Market Synopsis
Inflight entertainment systems provide video, audio, and interactive options to enhance passenger experiences during flights. The Japan Inflight Entertainment Market is projected to grow, driven by the adoption of Wi-Fi dependent solutions and rising demand for streaming platforms. With over 100 million passengers annually and a 15% increase in inflight entertainment adoption reported in 2023, airlines are investing in system upgrades to meet evolving passenger expectations and improve service quality.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased passenger demand for enhanced entertainment options | Driver | High | Personal Screens |
| Investment in Wi-Fi dependent entertainment solutions | Driver | High | Wi-Fi Dependent |
| Growing digital content consumption among consumers | Opportunity | High | Streaming Platforms |
| Expansion of long-haul routes requiring advanced entertainment systems | Opportunity | Medium | All Aircraft |
| Challenges in upgrading older aircraft to modern inflight systems | Restraint | High | Seat-Back Systems |
| Limited availability of high-quality content providers | Restraint | Medium | Content Aggregators |
| Pressure on airlines to balance costs with system upgrades | Challenge | High | Economy / Business |
| Competition among airlines leading to pricing pressures | Challenge | Medium | Entertainment Providers |
Evaluation of Drivers in Japan Inflight Entertainment Market (2026–2032)
Demand rests on the following drivers, each shown with the segment it touches most.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing passenger numbers | Personal Screens | Japan's airline industry serves over 100 million passengers annually, driving demand for individual entertainment options. |
| Investment in Wi-Fi infrastructure | Wi-Fi Dependent | Investment in Wi-Fi dependent entertainment solutions meets passenger expectations for connectivity. |
| Rise in digital content consumption | Streaming Platforms | Digital content consumption in Japan is projected to reach 80% by 2025, increasing demand for streaming services. |
| Long-haul flight durations | All Aircraft | The average flight duration for long-haul routes from Japan exceeds 10 hours, necessitating inflight entertainment. |
| Technological advancements in inflight systems | Seat-Back Systems | Airlines are investing in upgrading seat-back systems to improve passenger engagement. |
Much of the new demand traces back to the increasing number of passengers travelling on domestic and international flights, with over 100 million served annually. Substantial investment in Wi-Fi infrastructure led to a 15% increase in inflight entertainment adoption in 2023. Digital content consumption is anticipated to reach 80% by 2025, prompting airlines to upgrade their streaming platforms. The average flight duration for long-haul routes from Japan exceeds 10 hours, creating a need for engaging entertainment options. Technological advancements are driving upgrades to seat-back systems, improving the overall passenger experience.
Evaluation of Restraints in Japan Inflight Entertainment Market
Below are the constraints most often cited by buyers and suppliers, with the segment each affects.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in upgrading older aircraft | Seat-Back Systems | The average age of aircraft in Japan's commercial fleet is approximately 12 years, complicating upgrades. |
| Limited high-quality content availability | Content Aggregators | Content Aggregators face challenges in securing diverse and appealing content for inflight systems. |
| Cost pressures on airlines | Economy / Business | Airlines must balance costs with necessary upgrades to inflight entertainment systems. |
| Competition affecting budgets | Entertainment Providers | Intense competition among airlines can reduce budgets for inflight entertainment. |
| Regulatory compliance costs | Wi-Fi Dependent | Compliance with JIS standards for inflight entertainment systems incurs additional costs for airlines. |
Japan Inflight Entertainment Market Challenges
Buyers face high costs for advanced inflight entertainment systems, with installations exceeding $1 million per aircraft, straining airline budgets. Producers encounter supply chain disruptions for quality digital content, leading to delays in system upgrades and reduced passenger satisfaction. Distributors experience increased competition as airlines adopt Wi-Fi reliant solutions, forcing traditional providers to lower prices, which can erode profit margins. Buyers struggle with limited content availability since the average age of aircraft in Japan's commercial fleet is approximately 12 years, hindering access to modern inflight entertainment features.
Trends in the Japan Inflight Entertainment Market
The trends below show where the Japan Inflight Entertainment Market is heading.
- Shift Towards Wi-Fi Dependent Entertainment: Airlines are increasingly adopting Wi-Fi dependent entertainment solutions, with a reported 15% increase in adoption in 2023. This shift improves passenger connectivity and access to streaming services.
- Expansion of Streaming Platforms: Streaming platforms are gaining popularity, with a projected CAGR of 12.9% from 2026 to 2032. This trend reflects changing consumer preferences for on-demand content during flights.
- Increased Focus on Personal Screens: Personal screens are becoming the primary mode of content delivery, accounting for 40% of the market share in 2025. This trend improves individual passenger experiences on flights.
- Growth in Long-Haul Routes: Long-haul routes are driving demand for advanced inflight entertainment systems, as the average flight duration exceeds 10 hours. Airlines are investing in these systems to improve passenger satisfaction.
Investment Opportunities in the Japan Inflight Entertainment Market
Several openings in the Japan Inflight Entertainment Market merit attention from investors.
- Investment in Wi-Fi Dependent Solutions: With a 15% increase in inflight entertainment adoption, airlines should invest in Wi-Fi dependent solutions to meet rising passenger expectations for connectivity.
- Enhancing Streaming Content Libraries: Digital content consumption is projected to reach 80% by 2025, creating opportunities for airlines to enhance their streaming content libraries to attract more passengers.
- Upgrading Seat-Back Systems: Airlines are investing in upgrading seat-back systems, with over 1,500 inflight entertainment systems installed, to improve passenger engagement and satisfaction.
- Expanding Personal Screen Offerings: Personal Screens accounted for 40% of the market share in 2025, indicating a need for airlines to expand their offerings in this area to improve passenger experiences.
Government Initiatives in the Japan Inflight Entertainment Market
The Semiconductor and Digital Industry Strategy, established by the Ministry of Economy, Trade and Industry in June 2021, aims to strengthen domestic semiconductor manufacturing. This initiative ensures that inflight entertainment systems meet JIS standards, enhancing the quality and reliability of the content provided to passengers. The Digital Agency, formed in September 2021, leads the digital transformation in Japan, establishing common system standards that support the integration of advanced technology in inflight entertainment systems, benefiting both producers and airlines.
Airlines utilise the AI Promotion Act, implemented in 2025, to improve their inflight entertainment offerings through AI-driven content recommendations. This framework allows airlines to analyse passenger preferences, ensuring a more tailored entertainment experience. The Entertainment Providers Association of Japan also plays an important role by promoting industry standards and facilitating collaboration among content providers, ensuring that airlines can access a diverse range of digital content to meet passenger expectations.
Future Insight of the Japan Inflight Entertainment Market
New inflight entertainment systems will be installed in over 1,500 aircraft by 2032, enhancing passenger experience. The shift towards Wi-Fi reliant solutions will enable more interactive content and timely updates. Regulatory standards from the Ministry of Land, Infrastructure, Transport and Tourism will ensure that all systems meet safety and quality requirements. The ongoing digital transformation will drive demand for diverse entertainment options, aligning with the growing trend of digital content consumption.
Market Segmentation Analysis
Japan Inflight Entertainment Market report covers a detailed analysis of the following market segments:
By Content Type – Video on Demand Leads, Streaming Platforms Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, with 39% of content type revenue in 2025, Video on Demand was the largest category. Video on Demand holds the largest share due to its widespread adoption among airlines, allowing passengers to choose their viewing preferences during flights. This format caters to millions of passengers, supported by the extensive installed base of over 1,500 inflight entertainment systems. Streaming Platforms are set to record the highest CAGR in this split, 12.9% over 2026–2032. Streaming Platforms are rapidly gaining popularity as airlines implement Wi-Fi dependent solutions, enabling passengers to access a wide variety of content. The 15% increase in inflight entertainment adoption in 2023 indicates a strong shift towards this delivery method. Suppliers should enhance content offerings to meet the growing demand for diverse viewing options.
By Delivery Mode – Personal Screens Lead, Wi-Fi Dependent Expected to Grow Fastest
Personal Screens accounted for 40% of the market by delivery mode in 2025. Personal Screens dominate the market as they serve as the primary mode of content delivery for individual passengers, ensuring a personalised experience during flights. The average age of Japan's commercial aircraft fleet, approximately 12 years, supports the continued reliance on this delivery mode. Over 2026–2032, Wi-Fi Dependent is expected to post the fastest growth, at a CAGR of 11.6%. Wi-Fi Dependent solutions are experiencing rapid growth, facilitating streaming services that enhance passenger connectivity and entertainment choices. This trend aligns with the projected increase in digital content consumption in Japan, expected to reach 80% by 2025. Buyers will benefit from improved connectivity options, enhancing overall passenger satisfaction during flights.
By Passenger Class – Economy / Business Leads, All Aircraft Expected to Grow Fastest
In 2025, Economy / Business led the passenger class split with a 36% share. Economy / Business classes account for the largest share as both segments utilise inflight entertainment systems, appealing to a wide passenger demographic. With Japan's airline industry serving over 100 million passengers annually, this segment is essential for enhancing the travel experience. The quickest growth will come from All Aircraft, forecast to expand at a CAGR of 12.5% between 2026 and 2032. All Aircraft is the fastest growing segment as inflight entertainment systems are increasingly installed across various aircraft types, broadening access to entertainment options. This trend reflects airlines' commitment to improving passenger experiences across all classes. Suppliers must ensure their products are adaptable to various aircraft types to capture this expanding market.
By Distribution Channel – Content Aggregators Lead, Entertainment Providers Expected to Grow Fastest
The largest distribution channel category in 2025 was Content Aggregators, at 40% of revenue. Content Aggregators lead the market by providing a diverse range of content options that cater to a broad spectrum of passengers. Their pivotal role in the inflight entertainment ecosystem is underscored by the growing demand for varied programming. Entertainment Providers are projected to grow fastest, at a CAGR of 11.9% during 2026–2032. Entertainment Providers are witnessing the fastest growth as they supply both content and technology for inflight systems, addressing the increasing need for high-quality entertainment solutions. This trend is driven by airlines' investments in upgrading their inflight offerings. Suppliers should collaborate closely with entertainment providers to ensure their offerings align with market demands.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Inflight Entertainment Market Outlook
- Market Size of Japan Inflight Entertainment Market, 2025
- Forecast of Japan Inflight Entertainment Market, 2032
- Historical Data and Forecast of Japan Inflight Entertainment Revenues & Volume for the Period 2022-2032F
- Japan Inflight Entertainment Market Trend Evolution
- Japan Inflight Entertainment Market Drivers and Challenges
- Japan Inflight Entertainment Price Trends
- Japan Inflight Entertainment Porter's Five Forces
- Japan Inflight Entertainment Industry Life Cycle
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Content Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Video on Demand for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Streaming Platforms for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Audio / Podcasts for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Gaming and Interactivity for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Delivery Mode for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Personal Screens for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Wi-Fi Dependent for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Seat-Back Systems for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By App-Based Access for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Passenger Class for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Economy / Business for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By All Aircraft for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Long Haul Routes for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Premium Cabins for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Distribution Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Content Aggregators for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Entertainment Providers for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Airline OEMs for the Period 2022-2032F
- Historical Data and Forecast of Japan Inflight Entertainment Market Revenues & Volume By Digital Solution Vendors for the Period 2022-2032F
- Japan Inflight Entertainment Import Export Trade Statistics
- Market Opportunity Assessment By Content Type
- Market Opportunity Assessment By Delivery Mode
- Market Opportunity Assessment By Passenger Class
- Market Opportunity Assessment By Distribution Channel
- Japan Inflight Entertainment Top Companies Market Share
- Japan Inflight Entertainment Competitive Benchmarking By Technical and Operational Parameters
- Japan Inflight Entertainment Company Profiles
- Japan Inflight Entertainment Key Strategic Recommendations
Market Covered
Coverage by segment is as follows.
By Content Type
- Video on Demand
- Streaming Platforms
- Audio / Podcasts
- Gaming and Interactivity
By Delivery Mode
- Personal Screens
- Wi-Fi Dependent
- Seat-Back Systems
- App-Based Access
By Passenger Class
- Economy / Business
- All Aircraft
- Long Haul Routes
- Premium Cabins
By Distribution Channel
- Content Aggregators
- Entertainment Providers
- Airline OEMs
- Digital Solution Vendors































