Japan Insurance Distribution Market Size & Growth Rate
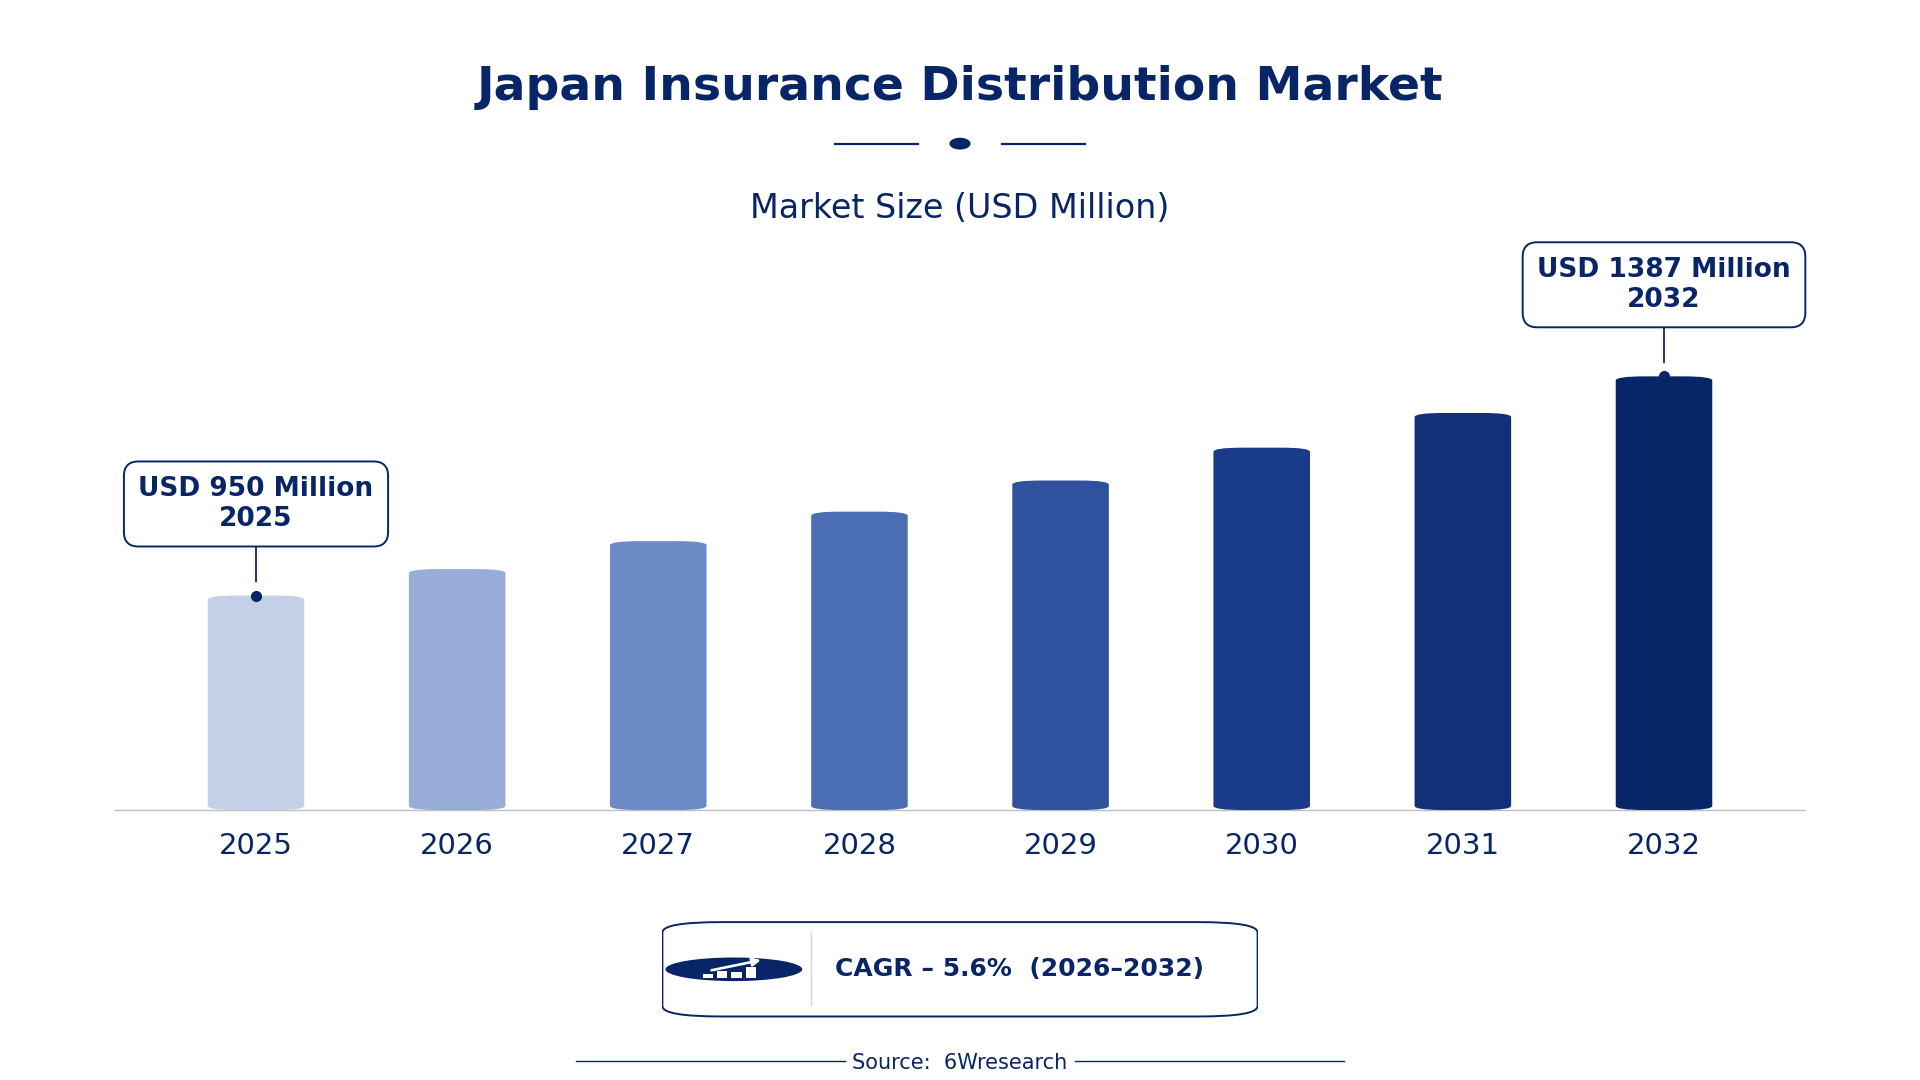
According to 6Wresearch internal database and industry insights, the Japan Insurance Distribution Market was valued at USD 950 Million in 2025 and is projected to reach USD 1,387 Million by 2032, growing at a CAGR of approximately 5.6% during 2026–2032.
Japan Insurance Distribution Market Highlights
| Report Metric | Details |
| Report Name | Japan Insurance Distribution Market (2026-2032) |
| Market Size 2025 | USD 950 Million |
| Market Size 2032 | USD 1,387 Million |
| Absolute Growth 2025–2032 | USD 437 Million |
| CAGR 2026–2032 | 5.6% |
| Peak Annual Growth | 6.2% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Channel Type, 2025 | Agency-Based (37% share) |
| Leading Product Type, 2025 | Life Insurance (53% share) |
| Leading Customer Segment, 2025 | Individual (39% share) |
| Leading Technology Mode, 2025 | Digital (54% share) |
| Leading End User, 2025 | General Public (39% share) |
| Fastest-Growing Channel Type | Direct Online (7.2% CAGR) |
| Fastest-Growing Product Type | Health Insurance (8.0% CAGR) |
| Fastest-Growing Customer Segment | SMEs (7.1% CAGR) |
| Fastest-Growing End User | Enterprises (7.4% CAGR) |
| Growing Sector | Insurance Distribution |
| Key End Users | General Public, SMEs, Individual, Corporate |
Japan Insurance Distribution Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
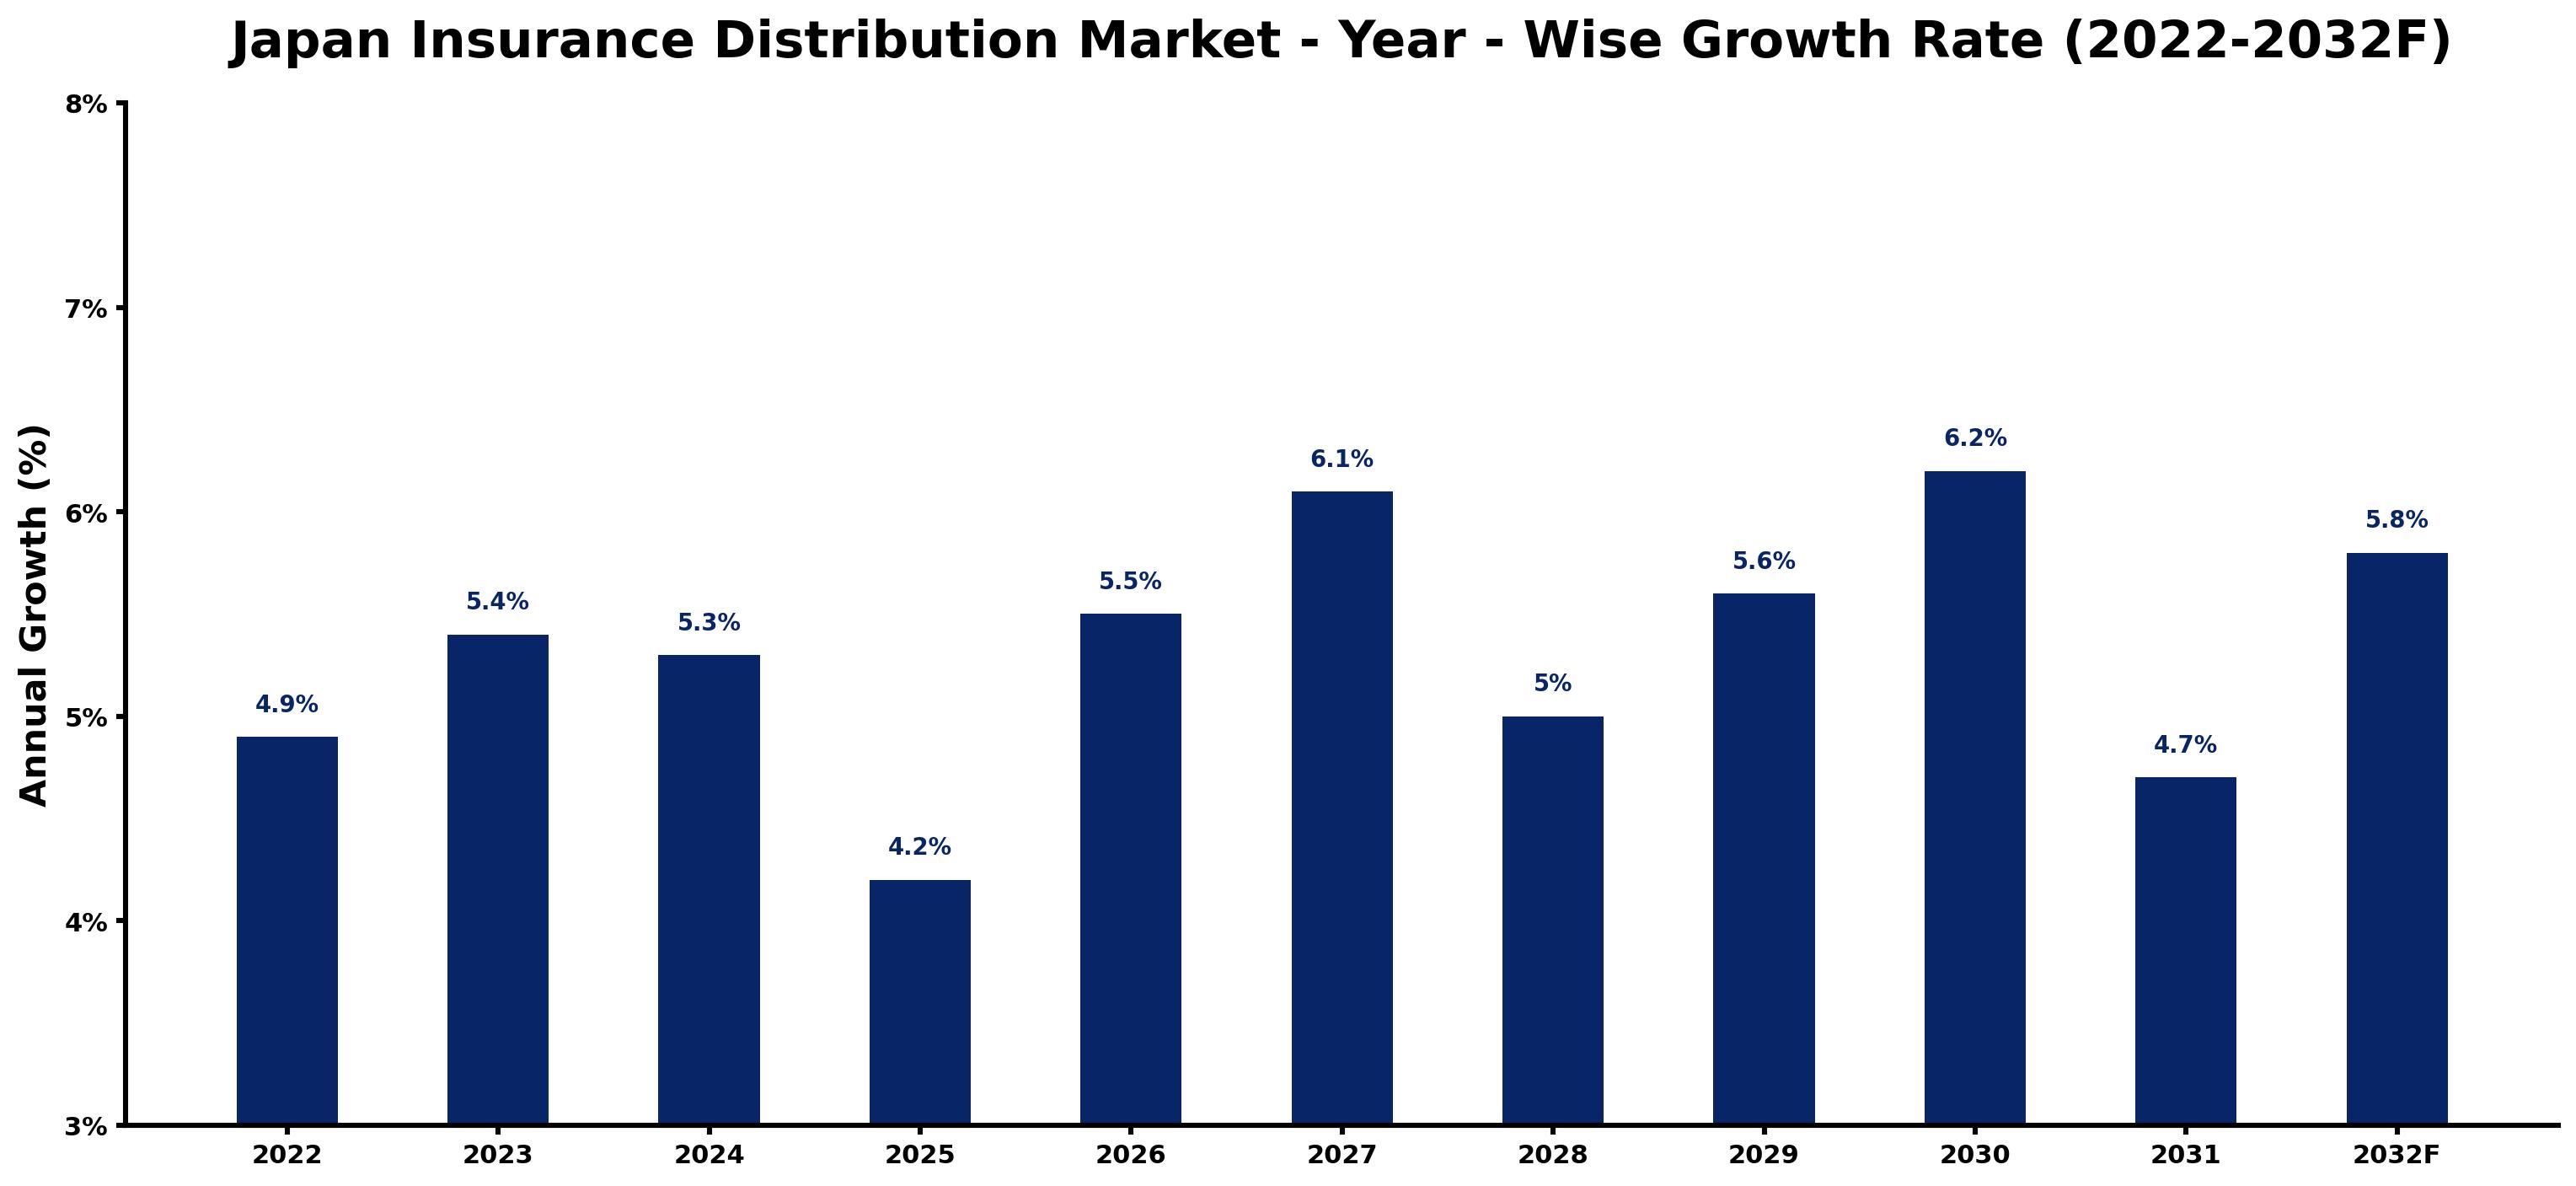
For each year, the table pairs the estimated growth rate with the leading influence on demand, showing how the drivers changed across the period.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 4.9 | The market experienced solid demand, driven by a high insurance penetration rate. |
| 2023 | 5.4 | Growth accelerated due to increased consumer awareness of insurance products. |
| 2024 | 5.3 | The growth rate slowed slightly as market maturity set in. |
| 2025 | 4.2 | A further slowdown occurred as competition intensified among providers. |
| 2026 | 5.5 | Demand increased again, supported by the rise of digital insurance platforms. |
| 2027 | 6.1 | Growth continued as consumers sought more tailored insurance solutions. |
| 2028 | 5.0 | The market saw a slowdown as economic conditions stabilised. |
| 2029 | 5.6 | Demand rose again, driven by the expansion of online sales channels. |
| 2030 | 6.2 | The peak growth rate was achieved due to technological advancements in distribution. |
| 2031 | 4.7 | Growth slowed as the market began to stabilise after rapid expansion. |
| 2032 | 5.8 | Demand is expected to rise again, supported by ongoing digital transformation. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
Japan Insurance Distribution Market Synopsis
Insurance distribution in Japan involves selling various insurance products through licensed agents, brokers, banks, and online platforms. The market is expanding as consumer awareness rises, with around 90% of households holding insurance. The adoption of digital platforms has increased by 25% from 2021 to 2023, improving accessibility and convenience for buyers. Additionally, bancassurance represented approximately 30% of new insurance sales in 2022, indicating a shift towards integrated financial services.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising consumer awareness of insurance products | Driver | High | General Public |
| Increased adoption of digital platforms | Driver | High | Digital |
| Expansion of bancassurance offerings | Opportunity | High | Bancassurance |
| Growing demand for tailored insurance solutions | Opportunity | Medium | Broker Channel |
| Intense competition among providers | Restraint | High | Agency-Based |
| Market maturity leading to slower growth rates | Restraint | Medium | Life Insurance |
| Rising operational costs for agencies | Challenge | High | Agency-Based |
| Technological integration challenges | Challenge | Medium | Digital |
Evaluation of Drivers in Japan Insurance Distribution Market (2026–2032)
The table below links each growth driver to the segment it affects and the evidence for it.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased consumer awareness of insurance products | General Public | Approximately 90% of Japanese households had some form of insurance in 2022. |
| Adoption of digital platforms | Digital | The adoption of digital insurance platforms has increased by 25% from 2021 to 2023. |
| Demand for tailored solutions | Broker Channel | Brokers provide tailored insurance solutions, meeting diverse client needs effectively. |
| Technological advancements in distribution | Direct Online | Digital channels are increasingly preferred for their convenience and accessibility. |
| Bancassurance offerings | Bancassurance | Bancassurance accounted for about 30% of new insurance sales in 2022. |
Buyers are adding capacity as consumer awareness of insurance products rises, with approximately 90% of households insured in 2022. The adoption of digital platforms surged by 25% from 2021 to 2023, leading to increased convenience for buyers. Brokers are responding to the demand for tailored solutions, expanding their offerings to meet diverse needs. Digital channels are preferred for their accessibility, driving further investment in technology by providers. Bancassurance offerings accounted for about 30% of new sales in 2022, integrating financial services with insurance.
Evaluation of Restraints in Japan Insurance Distribution Market
Several factors work against faster growth; the main ones are summarised below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Intense competition among providers | Agency-Based | This competition leads to price wars that diminish profit margins for agencies. |
| Market maturity leading to slower growth rates | Life Insurance | As the market matures, growth rates are projected to stabilise over time. |
| Rising operational costs for agencies | Agency-Based | Agencies face increasing costs due to regulatory compliance and technology investments. |
| Technological integration challenges | Digital | Many providers struggle to incorporate new technologies into existing systems, which limits efficiency. |
| Consumer preferences shifting towards digital solutions | Direct Online | This shift may reduce demand for traditional sales channels, impacting agency sales. |
Japan Insurance Distribution Market Challenges
High operational costs burden producers, as maintaining over 1,000 licensed agencies requires substantial investment in training and infrastructure. This leads to increased premiums for households, making insurance less affordable and limiting access to necessary coverage. A shortage of skilled agents complicates recruitment, delaying policy issuance and customer service for clients. Slow technology adoption, with only a 25% rise in digital platforms since 2021, restricts efficiency and innovation in service delivery for producers. Regulatory requirements add complexity and costs, diverting resources from product development for producers, ultimately affecting their competitiveness.
Trends in the Japan Insurance Distribution Market
Several trends are reshaping the Japan Insurance Distribution Market; the most important are set out below.
- Shift towards Digital Insurance: The general public is increasingly opting for digital insurance solutions, with digital platforms projected to account for 54% of the market by 2025. This shift reflects a growing preference for convenience and accessibility.
- Rise of Bancassurance: Bancassurance accounted for about 30% of new insurance sales in 2022, illustrating a trend where banks offer integrated financial services, improving customer convenience.
- Increased Demand for Tailored Solutions: The broker channel is seeing a rise in demand for tailored insurance solutions, driven by diverse consumer needs and preferences, particularly among SMEs.
- Growth in Insurance Literacy Initiatives: The government has implemented programs to improve insurance literacy among citizens, aiming to increase understanding and uptake of insurance products.
Investment Opportunities in the Japan Insurance Distribution Market
Several openings in the Japan Insurance Distribution Market merit attention from investors.
- SMEs Seeking Tailored Insurance Solutions: SMEs are increasingly looking for tailored insurance solutions, with a growing demand for specific coverage. Collaborating with local brokers can facilitate entry into this market.
- Digital Platforms for Improved Accessibility: The rise in digital insurance platforms opens opportunities for investment in technology solutions that improve accessibility for consumers, particularly in urban areas.
- Bancassurance Expansion: Bancassurance is expanding, providing opportunities for partnerships with banks to offer integrated insurance products alongside financial services.
- Investment in Insurance Literacy Programs: Investing in insurance literacy initiatives can capture the attention of the general public, increasing awareness and demand for various insurance products.
Government Initiatives in the Japan Insurance Distribution Market
In 2023, the government launched a digital insurance initiative to improve accessibility for consumers. This initiative builds upon existing laws, ensuring that digital platforms comply with regulatory standards while promoting best practices within the industry. The program aims to improve the distribution of insurance products across various channels, benefiting both producers and consumers.
The Financial Services Agency oversees the implementation of the digital insurance initiative, ensuring compliance and promoting consumer protection. This agency also supports insurance literacy programs, aiming to educate the general public about insurance products and their benefits, with funding allocated for outreach and educational materials.
Future Insight of the Japan Insurance Distribution Market
The digital insurance initiative launched in 2023 will transform demand by making policies more accessible, particularly for younger consumers. By 2032, the integration of advanced analytics and artificial intelligence will streamline underwriting processes, improving efficiency for suppliers. The government’s insurance literacy program will empower buyers, creating a more informed customer base. With approximately 90% of Japanese households insured, suppliers will focus on tailored products to meet the needs of an ageing population, ensuring they remain competitive in a changing market.
Market Segmentation Analysis
Japan Insurance Distribution Market report covers a detailed analysis of the following market segments:
By Channel Type – Agency-Based Leads, Direct Online Expected to Grow Fastest
According to Saurav Kr Singh, Senior Research Analyst at 6Wresearch, Agency-Based took 37% of channel type revenue in 2025, more than any other category. Agency-based distribution dominates the market due to its extensive network of over 1,000 licensed agencies across Japan, effectively reaching individual customers. This method is particularly favoured by those who appreciate personal interactions when purchasing insurance products. Direct Online is set to record the highest CAGR in this split, 7.2% over 2026–2032. The direct online channel is experiencing rapid growth, with a 25% increase in adoption from 2021 to 2023, as consumers prioritise convenience and accessibility. This trend indicates that the preference for digital solutions will continue to rise, further widening the gap with traditional methods. Suppliers must enhance their digital offerings to align with consumer preferences for online insurance solutions.
By Product Type – Life Insurance Leads, Health Insurance Expected to Grow Fastest
With 53% of product type revenue in 2025, Life Insurance was the largest category. Life insurance holds the largest market share, accounting for approximately 40% of total insurance sales, as it is essential for financial security and estate planning among Japanese households. The average coverage of about ¥20 million highlights its critical role in personal financial planning. The quickest growth will come from Health Insurance, forecast to expand at a CAGR of 8.0% between 2026 and 2032. Health insurance is witnessing rapid growth, propelled by mandatory coverage for all residents, ensuring that medical expenses are adequately addressed. This regulatory requirement leads to a steady increase in health insurance adoption across the population. Providers should focus on expanding health insurance options to meet regulatory demands and consumer expectations.
By Customer Segment – Individual Leads, SMEs Expected to Grow Fastest
In 2025, Individual led the customer segment split with a 39% share. The individual customer segment leads the market, representing a major portion of personal insurance needs, particularly with approximately 90% of households having some form of insurance. This high penetration rate reflects the importance of insurance in personal financial planning. Over 2026–2032, SMEs are expected to post the fastest growth, at a CAGR of 7.1%. SMEs are the fastest-growing segment as they seek tailored insurance solutions to protect their businesses, which are increasingly recognised as vital for economic stability. This trend highlights the need for specialised products catering to small business owners. Insurers should develop targeted products and services to better serve the unique requirements of SMEs.
By Technology Mode – Digital Leads and Records the Fastest Growth
The largest technology mode category in 2025 was Digital, at 54% of revenue. Digital technology is the leading mode for insurance transactions, aligning with modern consumer behaviour that favours online services. The widespread use of digital platforms has significantly transformed how insurance products are marketed and sold in Japan. The same category is also set to grow fastest, at a CAGR of 7.1% during 2026–2032. Digital remains the fastest-growing mode, reflecting a consistent trend towards online transactions in the insurance sector. This growth is fuelled by increasing demand for efficient and accessible insurance solutions among consumers. Insurance providers must invest in improving their digital platforms to leverage this growth and enhance customer engagement.
By End User – General Public Leads, Enterprises Expected to Grow Fastest
General Public held 39% of the Japan Insurance Distribution Market by end user in 2025. The general public represents the primary end user of insurance products, with a wide range of offerings catering to those seeking financial protection. This broad demand is underscored by the high insurance penetration rate among Japanese households, with approximately 90% covered. Enterprises are set to record the highest CAGR in this split, 7.4% over 2026–2032. Enterprises are emerging as the fastest-growing end user group, driven by the need for comprehensive insurance solutions to manage business risks. This trend indicates a growing recognition of the importance of insurance in supporting business operations. Insurers should tailor their products to meet the specific requirements of enterprise clients.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- Japan Insurance Distribution Market Outlook
- Market Size of Japan Insurance Distribution Market, 2025
- Forecast of Japan Insurance Distribution Market, 2032
- Historical Data and Forecast of Japan Insurance Distribution Revenues & Volume for the Period 2022-2032F
- Japan Insurance Distribution Market Trend Evolution
- Japan Insurance Distribution Market Drivers and Challenges
- Japan Insurance Distribution Price Trends
- Japan Insurance Distribution Porter's Five Forces
- Japan Insurance Distribution Industry Life Cycle
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Channel Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Agency-Based for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Bancassurance for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Direct Online for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Broker Channel for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Product Type for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Life Insurance for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Health Insurance for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Auto/Home Insurance for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Travel/Property Insurance for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Customer Segment for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Individual for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Corporate for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Retail Customers for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By SMEs for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Technology Mode for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Manual for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Assisted Digital for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Digital for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Hybrid for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By End User for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By General Public for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By Enterprises for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By E-Commerce Users for the Period 2022-2032F
- Historical Data and Forecast of Japan Insurance Distribution Market Revenues & Volume By SMEs for the Period 2022-2032F
- Japan Insurance Distribution Import Export Trade Statistics
- Market Opportunity Assessment By Channel Type
- Market Opportunity Assessment By Product Type
- Market Opportunity Assessment By Customer Segment
- Market Opportunity Assessment By Technology Mode
- Market Opportunity Assessment By End User
- Japan Insurance Distribution Top Companies Market Share
- Japan Insurance Distribution Competitive Benchmarking By Technical and Operational Parameters
- Japan Insurance Distribution Company Profiles
- Japan Insurance Distribution Key Strategic Recommendations
Market Covered
The study includes the following segmentation.
By Channel Type
- Agency-Based
- Bancassurance
- Direct Online
- Broker Channel
By Product Type
- Life Insurance
- Health Insurance
- Auto/Home Insurance
- Travel/Property Insurance
By Customer Segment
- Individual
- Corporate
- Retail Customers
- SMEs
By Technology Mode
- Manual
- Assisted Digital
- Digital
- Hybrid
By End User
- General Public
- Enterprises
- E-Commerce Users
- SMEs































