China Hydrogen Production Market Size & Growth Rate
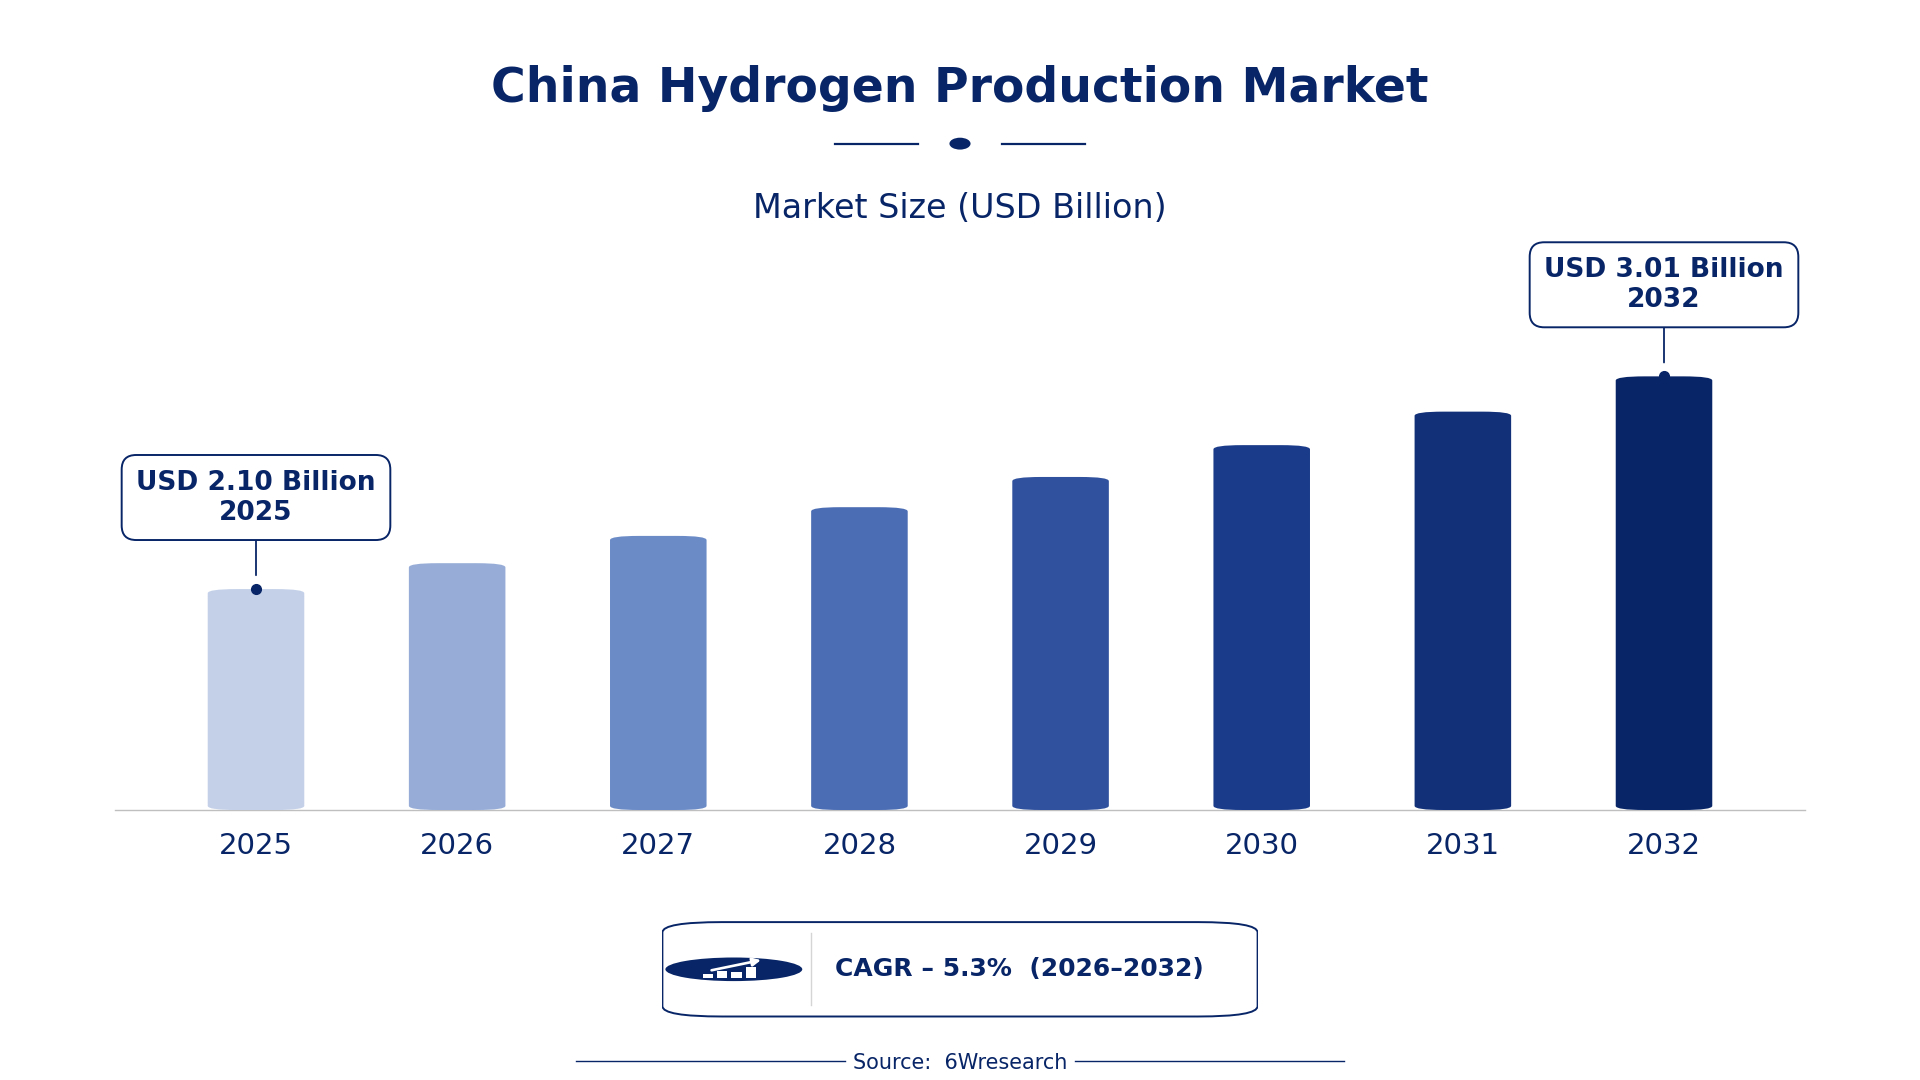
According to 6Wresearch internal database and industry insights, the China Hydrogen Production Market was valued at USD 2.10 billion in 2025 and is projected to reach USD 3.01 billion by 2032, growing at a CAGR of approximately 5.3% during 2026–2032.
China Hydrogen Production Market Highlights
| Report Metric | Details |
| Report Name | China Hydrogen Production Market |
| Market Size 2025 | USD 2.10 billion |
| Market Size 2032 | USD 3.01 billion |
| Absolute Growth 2025–2032 | USD 0.91 billion |
| CAGR 2026–2032 | 5.3% |
| Peak Annual Growth | 7.5% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Production Method, 2025 | Electrolysis (45% share) |
| Leading Energy Source, 2025 | Renewable Energy (51% share) |
| Leading Output Purity, 2025 | High Purity (46% share) |
| Leading End User, 2025 | Fuel Cell Suppliers (42% share) |
| Fastest-Growing Production Method | Steam Methane Reforming (6.7% CAGR) |
| Fastest-Growing Energy Source | Natural Gas (7.8% CAGR) |
| Fastest-Growing Output Purity | Medium Purity (7.0% CAGR) |
| Fastest-Growing End User | Industrial Users (6.5% CAGR) |
| Growing Sector | Fuel Cell Suppliers |
| Key End Users | Industrial Users, Fuel Cell Suppliers, Decentralized Producers |
China Hydrogen Production Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
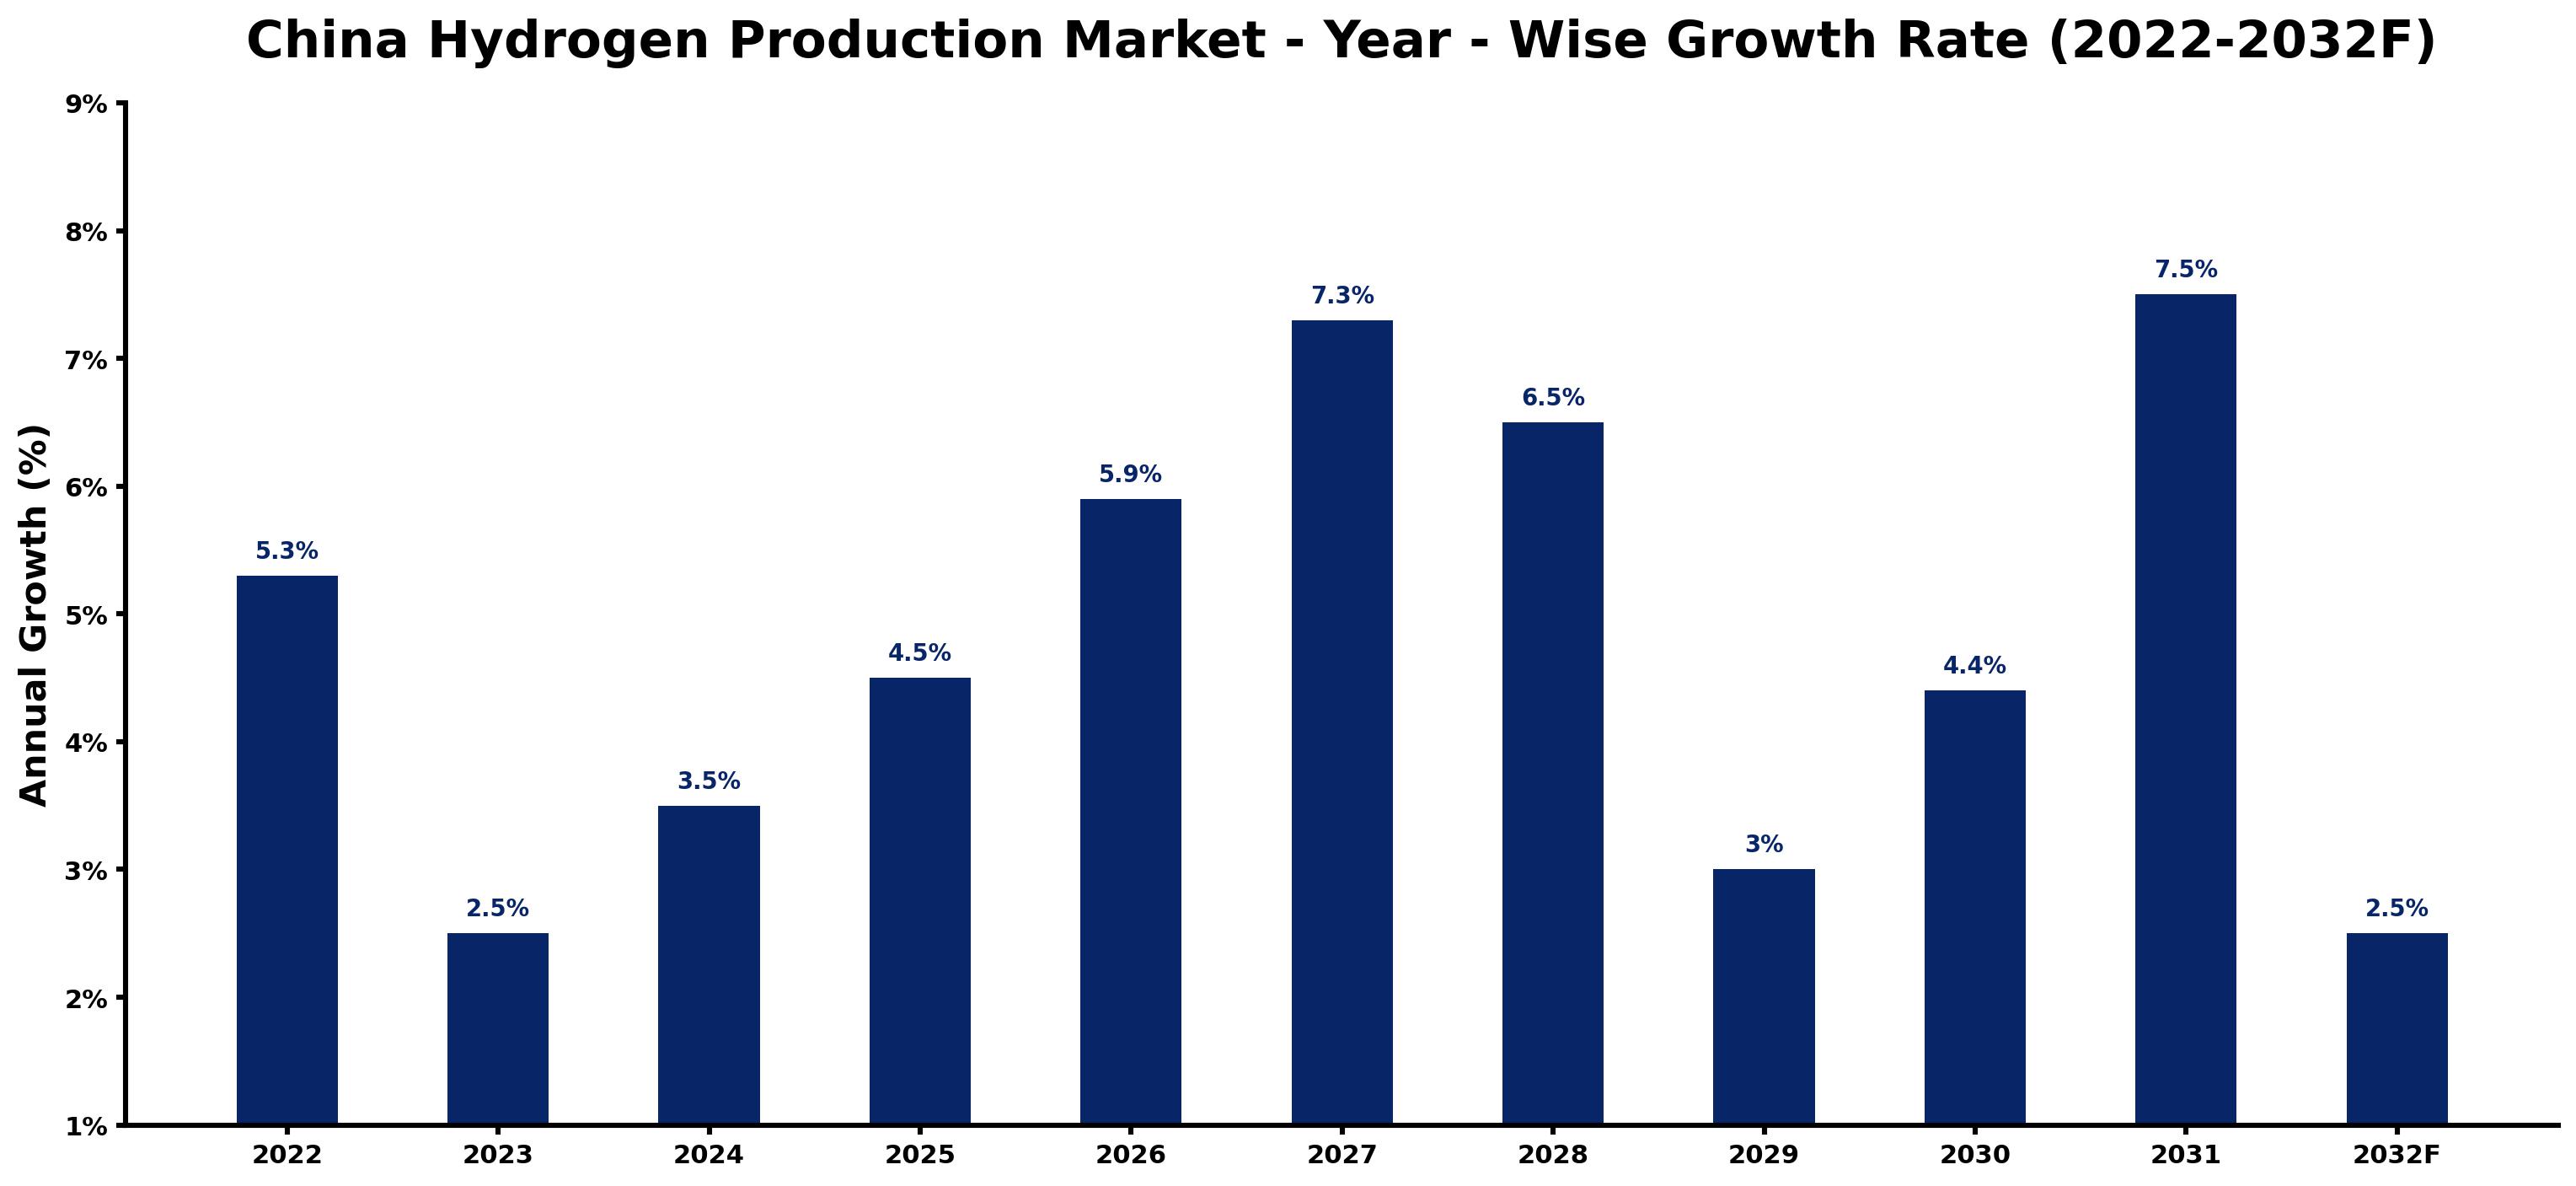
Annual growth estimates for each year appear below with the principal reason behind them, explaining the shifts that set the pace of the market.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.3 | The market experienced strong demand from industrial users and fuel cell suppliers. |
| 2023 | 2.5 | Growth slowed as the hydrogen production capacity expanded but faced regulatory challenges. |
| 2024 | 3.5 | Demand increased with rising investments in hydrogen infrastructure and technology. |
| 2025 | 4.5 | Fuel cell suppliers drove growth as the country aimed for 1 million tons of green hydrogen. |
| 2026 | 5.9 | The '14th Five-Year Plan for Energy Development' will spur investments in green hydrogen production. |
| 2027 | 7.3 | The market will benefit from increased collaboration within the Hydrogen Energy Industry Alliance. |
| 2028 | 6.5 | Growth is expected to slow as the market adjusts to new production capabilities and standards. |
| 2029 | 3.0 | Demand will remain steady as industrial users seek cleaner energy solutions. |
| 2030 | 4.4 | Increased focus on sustainability will push hydrogen utilization in industrial processes. |
| 2031 | 7.5 | The market is projected to peak with investments in hydrogen infrastructure and technology. |
| 2032 | 2.5 | Growth will slow as the market stabilizes after reaching production targets. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Hydrogen Production Market Synopsis
Hydrogen Production in China encompasses the methods of producing hydrogen gas, primarily through electrolysis and steam methane reforming. These processes convert water and natural gas into hydrogen, which is essential for fuel cells and various industrial applications. The China Hydrogen Production Market is expanding due to strong demand from fuel cell suppliers and industrial users. With a target of 1 million tons of green hydrogen by 2025, investments in hydrogen technology are accelerating. The National Energy Administration's support underlines the government's commitment to hydrogen as a key energy source.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing investments in hydrogen infrastructure and technology. | Driver | High | Electrolysis |
| Increased demand for green hydrogen from industrial users. | Driver | High | Renewable Energy |
| Rising need for cleaner energy solutions in industrial processes. | Opportunity | High | Fuel Cell Suppliers |
| Expansion of hydrogen production capacity in key provinces. | Opportunity | High | Industrial Users |
| Regulatory hurdles affecting production timelines and costs. | Restraint | High | Steam Methane Reforming |
| Limited awareness of hydrogen applications among smaller producers. | Restraint | Medium | Decentralized Producers |
| Competition from alternative energy sources impacting market share. | Challenge | High | Natural Gas |
| Technological barriers in scaling up production methods. | Challenge | Medium | Biomass Gasification |
Evaluation of Drivers in China Hydrogen Production Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased investments in hydrogen infrastructure. | Electrolysis | China has invested over 100 billion yuan in hydrogen infrastructure development since 2020, leading to more production capabilities. |
| Growing demand for green hydrogen. | Renewable Energy | The country aims to produce 1 million tons of green hydrogen annually by 2025, driving demand from fuel cell suppliers. |
| Regulatory support for hydrogen initiatives. | Fuel Cell Suppliers | The National Energy Administration promotes hydrogen as a key part of the 14th Five-Year Plan, encouraging industrial adoption. |
| Expansion of production capacity in key regions. | Industrial Users | The hydrogen production capacity in Guangdong province is rapidly expanding, attracting more industrial users. |
| Technological advancements in hydrogen production methods. | Steam Methane Reforming | The fastest-growing method is projected to have a CAGR of 6.7% due to technological improvements. |
The Hydrogen Production market in China is growing on the back of rising end-use demand from industrial users and fuel cell suppliers. The country aims to produce 1 million tons of green hydrogen annually by 2025, driving investments in infrastructure. Over 100 billion yuan has been invested in hydrogen infrastructure development since 2020, increasing production capacity. Support from the National Energy Administration encourages industrial adoption of hydrogen technologies. The hydrogen production capacity in Guangdong province is rapidly expanding, attracting more industrial users and boosting demand.
Evaluation of Restraints in China Hydrogen Production Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory hurdles affecting production timelines. | Steam Methane Reforming | Compliance with the ISO 14687 standard can delay production, impacting supply timelines. |
| Limited awareness of hydrogen applications among smaller producers. | Decentralized Producers | Many smaller producers lack knowledge about hydrogen's potential, limiting their market participation. |
| Competition from alternative energy sources impacting market share. | Natural Gas | The increasing adoption of renewable energy sources poses a challenge to traditional hydrogen production methods. |
| Technological barriers in scaling up production methods. | Biomass Gasification | Biomass gasification remains less common due to technological challenges and limited application. |
| High initial investment costs for infrastructure development. | Electrolysis | The need for substantial capital investment can deter new entrants into the hydrogen market. |
China Hydrogen Production Market Challenges
Buyers in the China hydrogen production market are facing rising costs, with natural gas prices increasing by 30% over the past year, which strains budgets for those depending on steam methane reforming. Supply chain disruptions are delaying access to essential components, impacting production schedules for suppliers. A shortage of skilled workers in advanced hydrogen technologies complicates recruitment, leading to a 15% rise in training costs for existing staff. Local producers are pressured to lower prices due to competition from international markets, which compresses profit margins and threatens sustainability for many in the sector.
Trends in the China Hydrogen Production Market
Several trends are reshaping the China Hydrogen Production Market; the most important are set out below.
- Shift from Traditional to Green Hydrogen Production: China is increasingly focusing on green hydrogen production methods to meet environmental targets. The National Development and Reform Commission's 'Green Hydrogen Development Initiative' aims to promote sustainable practices, with a target of 20% hydrogen utilization in industrial processes by 2030.
- Transition from Centralized to Decentralized Hydrogen Production: In regions like Jiangsu, there is a growing trend towards decentralized hydrogen production. This shift allows smaller producers to contribute to local supply chains, improving flexibility and responsiveness in meeting demand.
- Emergence of High Purity Hydrogen Demand: High purity hydrogen is becoming essential for semiconductor manufacturing in China. As industries expand, the demand for high purity hydrogen is expected to grow, driven by technological advancements and increased production.
- Increase in Hydrogen Refueling Stations: The installed base of hydrogen refueling stations in China reached 200 in 2023. This expansion supports the growing fuel cell vehicle market, facilitating the adoption of hydrogen as a clean energy source.
Investment Opportunities in the China Hydrogen Production Market
Several openings in the China Hydrogen Production Market merit attention from investors.
- Timing for Investment in Green Hydrogen: With a target of producing 1 million tons of green hydrogen by 2025, there is a prime opportunity for investment in renewable energy sources. Fuel cell suppliers are looking for partners to meet this demand.
- Gap in High Purity Hydrogen Supply: As high purity hydrogen is essential for semiconductor manufacturing, there is a gap in supply. Industrial users in Jiangsu province are seeking reliable sources, presenting an investment opportunity for producers.
- Growing Demand from Industrial Users: Industrial users are increasingly adopting hydrogen for cleaner energy solutions. This trend creates opportunities for suppliers to enter the market with innovative production methods.
- Expansion of Hydrogen Production Facilities: The rapid expansion of hydrogen production facilities in Guangdong province presents opportunities for investment. Collaborating with local producers can improve market entry and supply chain efficiency.
Government Initiatives in the China Hydrogen Production Market
In 2022, the National Development and Reform Commission launched the 'Green Hydrogen Development Initiative' to promote sustainable hydrogen production methods. This initiative builds on previous efforts to establish a hydrogen economy by 2035, refining the regulatory framework for the hydrogen sector. It sets specific targets for hydrogen utilisation in industrial processes and encourages investment in green hydrogen technologies, aiming to stimulate innovation and collaboration among stakeholders in the hydrogen industry.
The 'Hydrogen Fuel Cell Vehicle Technology Innovation Program' has a budget of 2 billion yuan to support research and development. This programme funds initiatives aimed at advancing hydrogen fuel cell vehicle technology, ensuring the industry meets national energy goals. The National Energy Administration oversees the implementation of these initiatives, ensuring alignment with broader energy development strategies.
Future Insight of the China Hydrogen Production Market
The China hydrogen production market is set for substantial changes by 2032, driven by government initiatives and technological advancements. The country aims to produce 1 million tons of green hydrogen annually by 2025, which will strengthen its energy transition strategy. Investment in hydrogen infrastructure has exceeded 100 billion yuan, facilitating the growth of production capacities. The National Energy Administration's promotion of hydrogen in the 14th Five-Year Plan will further encourage collaboration and innovation among stakeholders.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Production Method – Electrolysis Dominated, Steam Methane Reforming Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, in 2025, Electrolysis led the production method split with a 45% share. Electrolysis holds the largest market share as it is the primary method for producing green hydrogen, essential for China's environmental goals. The National Energy Administration's support for hydrogen in the 14th Five-Year Plan underscores the importance of this production technique. Steam Methane Reforming is set to record the highest CAGR in this split, 6.7% over 2026–2032. Steam Methane Reforming is experiencing rapid growth due to its effectiveness in converting natural gas into hydrogen, a crucial feedstock. As China expands its hydrogen production capacity, this method's usage is likely to increase, reinforcing its market position. Suppliers should focus on advancing electrolysis technology to meet China's ambitious green hydrogen production objectives.
By Energy Source – Renewable Energy Dominated, Natural Gas Expected to Grow Fastest
Renewable Energy accounted for a 51% market share by energy source in 2025. Renewable Energy captures the largest market share as it is critical for producing green hydrogen, which is increasingly emphasised in China's energy strategies. The goal of achieving 1 million tons of green hydrogen annually by 2025 highlights the essential role of renewable sources in this market. The quickest growth will come from Natural Gas, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Natural Gas is the fastest-growing energy source, mainly due to its role as the primary feedstock for hydrogen production. The growth of hydrogen refueling stations indicates that reliance on natural gas will likely increase significantly in the near future. Buyers should consider integrating renewable energy sources to improve the sustainability of hydrogen production.
By Output Purity – High Purity Dominated, Medium Purity Expected to Grow Fastest
High Purity held a 46% share of the China Hydrogen Production Market by output purity in 2025. High Purity hydrogen commands the largest market share because it is essential for critical industrial applications and fuel cells, which are vital in various sectors. The semiconductor manufacturing industry in China particularly relies on high purity standards to ensure product quality. Over 2026–2032, Medium Purity is expected to post the fastest growth, at a CAGR of 7.0%. Medium Purity hydrogen is growing quickly as it finds applications in less critical processes, allowing for broader adoption across various industries. This growth indicates a shift towards utilising hydrogen in diverse applications beyond high-end uses. Suppliers should invest in technologies that can produce both high and medium purity hydrogen to cater to varying market demands.
By End User – Fuel Cell Suppliers Dominated, Industrial Users Expected to Grow Fastest
The largest end user category in 2025 was Fuel Cell Suppliers, with a 42% share of total revenue. Fuel Cell Suppliers dominate the market share as they are major consumers of hydrogen for energy applications, particularly in transportation and power generation. The Ministry of Industry and Information Technology's support for fuel cell vehicle development further cements this segment's leadership. Industrial Users are projected to grow fastest, at a CAGR of 6.5% during 2026–2032. Industrial Users are the fastest-growing segment, driven by increasing hydrogen consumption in various industrial processes. As industries seek greater efficiency and sustainability, the demand for hydrogen is expected to rise significantly. Suppliers need to diversify their offerings to meet the growing demands of both fuel cell suppliers and industrial users.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Hydrogen Production Market Outlook
- Market Size of China Hydrogen Production Market, 2025
- Forecast of China Hydrogen Production Market, 2032
- Historical Data and Forecast of China Hydrogen Production Revenues & Volume for the Period 2022 - 2032F
- China Hydrogen Production Market Trend Evolution
- China Hydrogen Production Market Drivers and Challenges
- China Hydrogen Production Price Trends
- China Hydrogen Production Porter's Five Forces
- China Hydrogen Production Industry Life Cycle
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Production Method for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Electrolysis for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Steam Methane Reforming for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Biomass Gasification for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Solar Thermochemical for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Energy Source for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Renewable Energy for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Natural Gas for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Agricultural Waste for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Solar Heat for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Output Purity for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By High Purity for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Medium Purity for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Syngas-Derived Hydrogen for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Green Hydrogen for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Fuel Cell Suppliers for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Industrial Users for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Decentralized Producers for the Period 2022 - 2032F
- Historical Data and Forecast of China Hydrogen Production Market Revenues & Volume By Green Energy Providers for the Period 2022 - 2032F
- China Hydrogen Production Import Export Trade Statistics
- Market Opportunity Assessment By Production Method
- Market Opportunity Assessment By Energy Source
- Market Opportunity Assessment By Output Purity
- Market Opportunity Assessment By End User
- China Hydrogen Production Top Companies Market Share
- China Hydrogen Production Competitive Benchmarking By Technical and Operational Parameters
- China Hydrogen Production Company Profiles
- China Hydrogen Production Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Production Method
- Electrolysis
- Steam Methane Reforming
- Biomass Gasification
- Solar Thermochemical
By Energy Source
- Renewable Energy
- Natural Gas
- Agricultural Waste
- Solar Heat
By Output Purity
- High Purity
- Medium Purity
- Syngas-Derived Hydrogen
- Green Hydrogen
By End User
- Fuel Cell Suppliers
- Industrial Users
- Decentralized Producers
- Green Energy Providers































