China iGaming Market Size & Growth Rate
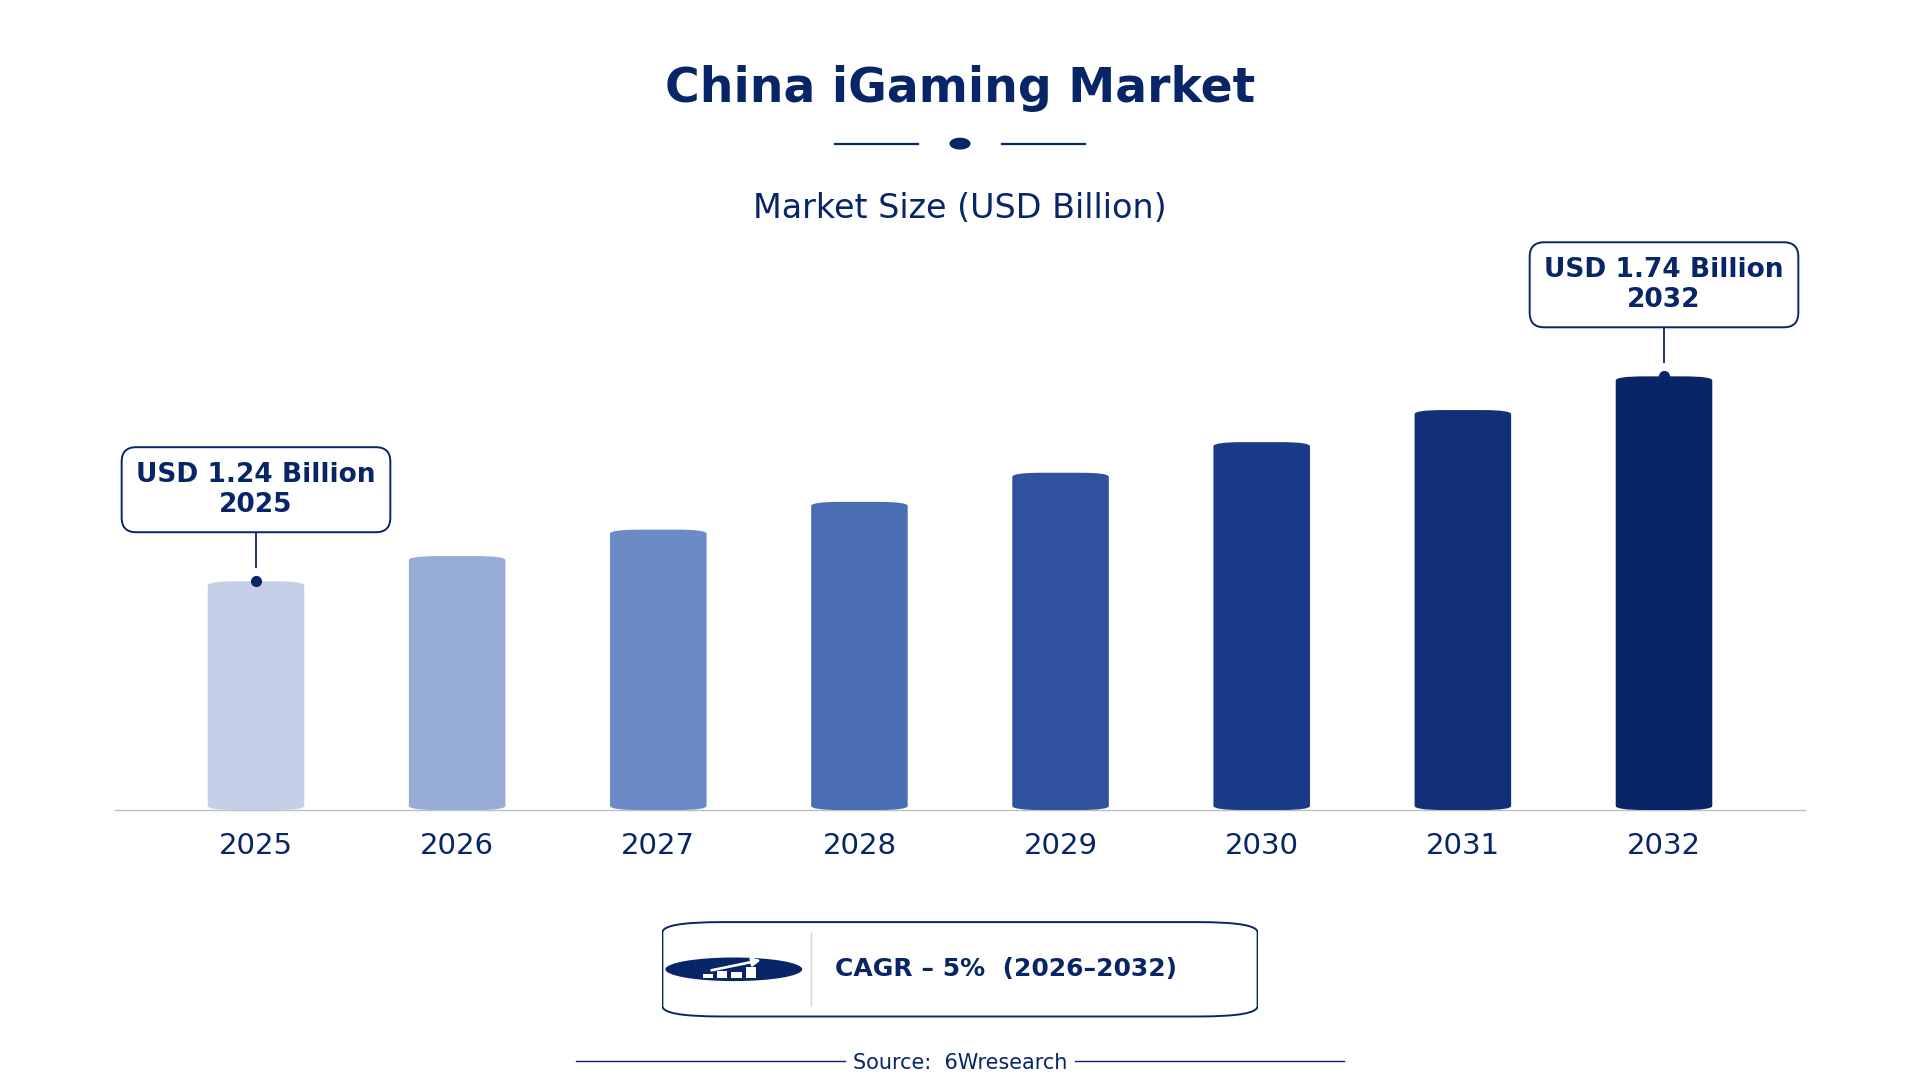
According to 6Wresearch internal database and industry insights, the China iGaming Market was valued at USD 1.24 billion in 2025 and is projected to reach USD 1.74 billion by 2032, growing at a CAGR of approximately 5% during 2026–2032.
China iGaming Market Highlights
| Report Metric | Details |
| Report Name | China iGaming Market |
| Market Size 2025 | USD 1.24 billion |
| Market Size 2032 | USD 1.74 billion |
| Absolute Growth 2025–2032 | USD 0.50 billion |
| CAGR 2026–2032 | 5% |
| Peak Annual Growth | 7.0% in 2031 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Game Type, 2025 | Casino Games (45% share) |
| Leading Platform Type, 2025 | Web/Mobile App (47% share) |
| Leading Monetization Model, 2025 | Real Money Betting (47% share) |
| Leading End User, 2025 | Online Players (52% share) |
| Fastest-Growing Game Type | Poker & Card Games (6.6% CAGR) |
| Fastest-Growing Platform Type | Mobile/Desktop (6.4% CAGR) |
| Fastest-Growing Monetization Model | In-App Purchases (6.7% CAGR) |
| Fastest-Growing End User | High-Engagement Users (6.7% CAGR) |
| Growing Sector | Online Players |
| Key End Users | Online Players, Sports Fans, High-Engagement Users |
China iGaming Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
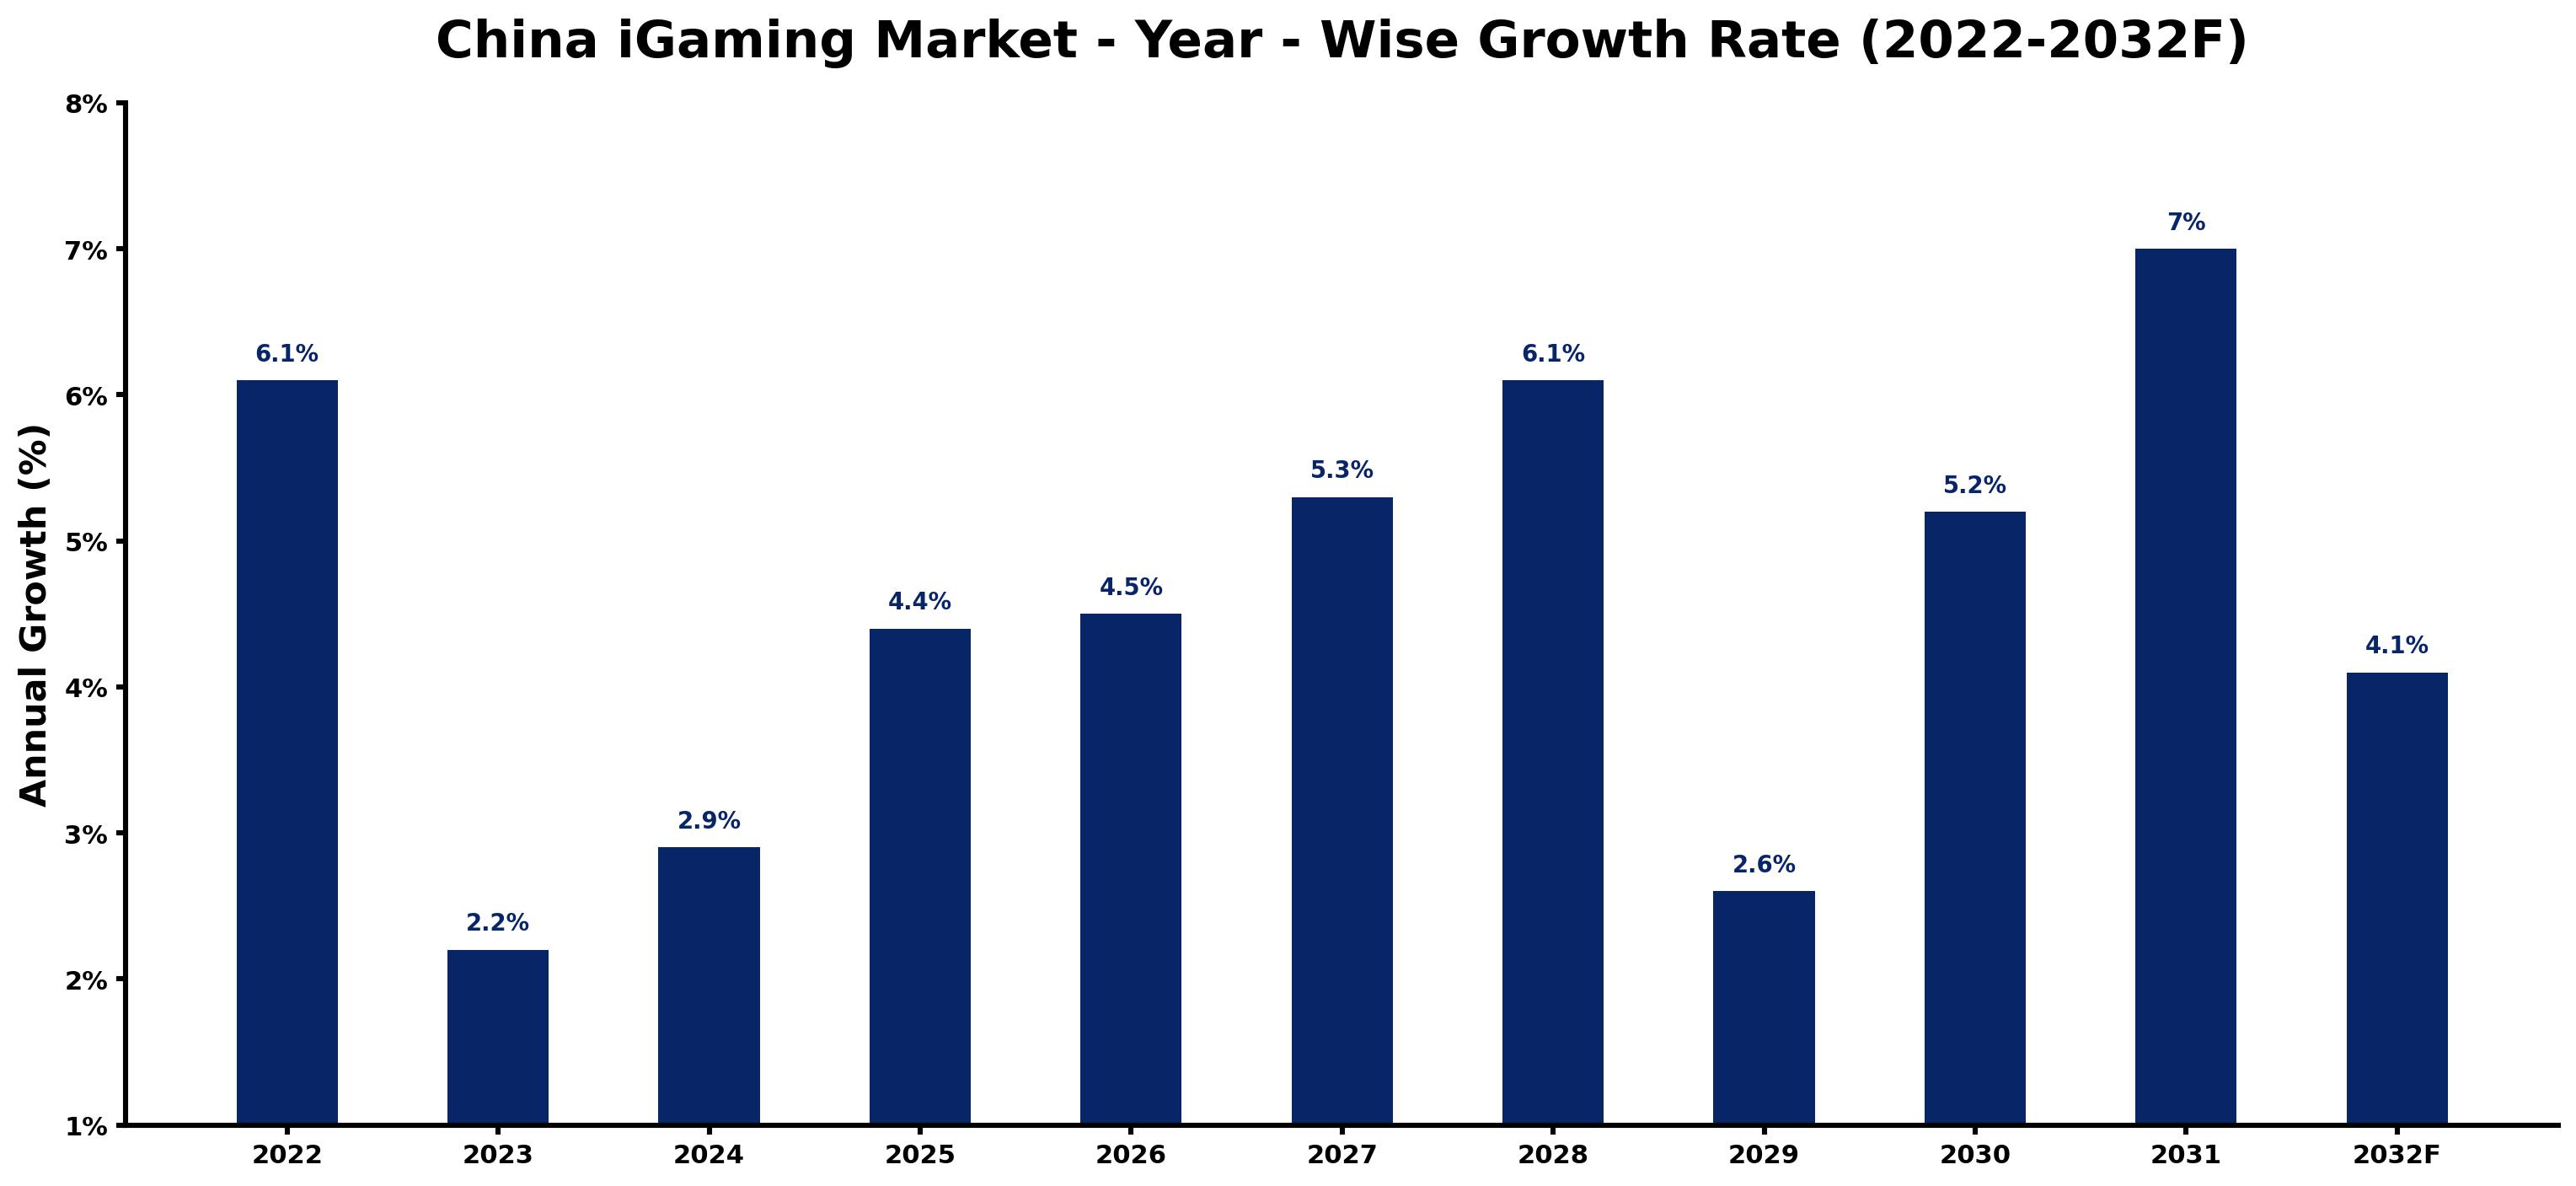
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.1 | The online gaming population was approximately 500 million users, driving demand. |
| 2023 | 2.2 | Growth slowed as regulatory scrutiny increased, affecting new game approvals. |
| 2024 | 2.9 | Increased interest in mobile platforms led to faster growth in user engagement. |
| 2025 | 4.4 | The revenue from iGaming rose as more players engaged in real money betting. |
| 2026 | 4.5 | New guidelines for online game approvals will streamline the market. |
| 2027 | 5.3 | The growing popularity of poker and card games will attract more online players. |
| 2028 | 6.1 | User engagement will increase as immersive gaming technologies gain traction. |
| 2029 | 2.6 | A slowdown is expected as regulatory measures continue to impact the market. |
| 2030 | 5.2 | Increased revenue from online betting is anticipated to boost overall market growth. |
| 2031 | 7.0 | The peak growth rate will be driven by rising participation in sports betting. |
| 2032 | 4.1 | Market growth is projected to slow as regulatory measures continue to shape user engagement. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China iGaming Market Synopsis
The China iGaming Market encompasses online gaming platforms offering gambling options such as casino games and sports betting. Users engage primarily through mobile and web applications, with entertainment and wagering as key uses. The market is expanding due to a substantial online gaming population, estimated at 500 million users, and increasing revenues from real money betting. The Guangdong province serves as a major hub for these activities, while new regulations aim to improve user protection and market integrity.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing online gaming population drives demand for diverse gaming options. | Driver | High | Online Players |
| Increased revenue from real money betting fuels market expansion. | Driver | High | Real Money Betting |
| The rise of mobile gaming platforms presents significant investment opportunities. | Opportunity | High | Mobile/Desktop |
| Emerging interest in immersive gaming technologies opens new market avenues. | Opportunity | Medium | Immersive Devices |
| Regulatory scrutiny limits the approval of new online games. | Restraint | High | Web/Mobile App |
| Age restrictions imposed by the government hinder market access for minors. | Restraint | Medium | Online Players |
| Regulatory compliance costs pose challenges for new entrants in the market. | Challenge | High | Real Money Betting |
| Technological barriers in immersive gaming limit broader market adoption. | Challenge | Medium | Immersive Devices |
Evaluation of Drivers in China iGaming Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing online gaming population supports diverse gaming options. | Online Players | In 2022, the online gaming population reached approximately 500 million users, increasing demand for various gaming experiences. |
| Increased revenue from real money betting fuels market expansion. | Real Money Betting | The total revenue from iGaming was estimated at 30 billion USD in 2022, encouraging further investments. |
| Mobile platforms attract more users, driving engagement. | Mobile/Desktop | Around 70% of online gamers prefer mobile platforms, leading to higher participation rates. |
| Emerging interest in poker and card games boosts market growth. | Poker & Card Games | The fastest-growing segment is projected to grow at a CAGR of 6.6% from 2026 to 2032. |
| Regulatory updates improve user protection and market integrity. | Web/Mobile App | The National Standard for Online Gaming was updated in 2021 to improve user safety. |
Market growth for iGaming in China is supported by an expanding online gaming population and increased revenue from a variety of gaming options. In 2022, around 500 million users engaged with different gaming choices, fuelling demand. The total revenue from iGaming reached 30 billion USD, prompting further investments in the sector. Mobile platforms are especially favoured, with approximately 70% of online gamers opting for mobile access, which boosts user engagement. The poker and card games segment is expected to grow at a CAGR of 6.6%, attracting more players to the market.
Evaluation of Restraints in China iGaming Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory scrutiny limits the approval of new online games. | Web/Mobile App | Stricter approval processes implemented in 2023 hinder the introduction of new gaming options. |
| Age restrictions imposed by the government hinder market access for minors. | Online Players | The 2022 Online Game Anti-Addiction Program limits gaming time for minors, affecting user demographics. |
| Compliance costs for regulatory measures can deter new entrants. | Real Money Betting | New regulations require investments in compliance, limiting market entry for smaller firms. |
| Technological barriers in immersive gaming limit broader market adoption. | Immersive Devices | Limited current user base for immersive devices restricts growth potential in this segment. |
| Market fluctuations due to regulatory changes can create uncertainty. | Poker & Card Games | Changes in regulations can impact player engagement and investment in this segment. |
China iGaming Market Challenges
The iGaming market in China struggles with a critical skills shortage, as only 30% of developers meet the high standards required by the industry. This gap exists due to a lack of targeted educational programs, resulting in delays in game launches that can extend timelines by up to six months for producers. Buyers face inflated operational costs, with compliance expenses rising by approximately 15% due to stringent regulations enforced by the Ministry of Culture and Tourism. Moreover, illegal competition undermines legitimate platforms, forcing them to cut prices, which can reduce revenue by as much as 20% for compliant businesses.
Trends in the China iGaming Market
The trends below show where the China iGaming Market is heading.
- Shift towards Mobile Platforms in 2022: In 2022, mobile platforms became the preferred choice for online gamers, with 70% of users opting for mobile access. This shift is reshaping the iGaming market, resulting in increased investments in mobile app development.
- Emergence of Immersive Gaming Technologies in 2020: In 2020, the Ministry of Industry and Information Technology initiated a program to support immersive gaming technologies. This initiative is attracting a niche market, improving user experiences and engagement.
- Increase in Real Money Betting Revenue in 2023: The 2023 National Sports Lottery report indicated a revenue increase of 10% from online betting. This growth highlights the rising interest in real money betting among online players.
- Regulatory Updates Improving User Protection in 2021: The National Standard for Online Gaming was updated in 2021 to improve user protection. These changes are important for maintaining trust and safety in the iGaming sector.
Investment Opportunities in the China iGaming Market
Some of the investment opportunities in the China iGaming Market are mentioned below.
- Invest in Mobile Gaming Platforms: With 70% of online gamers favouring mobile platforms, there is an opportunity to invest in mobile gaming applications. The Guangdong province is a key region for this growth, presenting a vibrant market.
- Supply Immersive Gaming Technologies: The market gap for immersive gaming technologies offers investment opportunities, especially as interest increases. The National Strategy for Digital Economy Development in 2022 aims to promote this sector.
- Develop Poker and Card Game Offerings: The poker and card games segment is projected to grow, indicating a demand for new offerings. Engaging with online players in major urban centres can facilitate market entry.
- Expand Real Money Betting Options: The increasing revenue from real money betting highlights the need for diverse offerings. Collaborating with local gaming authorities can streamline the approval process for new products.
Government Initiatives in the China iGaming Market
The 'Regulations on the Administration of Online Games' updated in 2021 by the Ministry of Culture and Tourism improved player protections. This law requires gaming operators to implement measures ensuring user safety and compliance with national standards. The '2022 Online Game Anti-Addiction Program' was launched to limit gaming time for minors, aiming to protect younger audiences. Additionally, the 'National Strategy for Digital Economy Development' introduced in 2022 promotes the growth of the digital gaming industry, providing a framework for future developments.
Buyers in the online gaming sector benefit from the stricter approval processes implemented by the State Administration of Press and Publication in 2023. This agency ensures that new online games meet national standards, improving user protection and market integrity. The funding for compliance initiatives has increased, allowing for better oversight of gaming activities. The focus on user safety and responsible gaming practices is expected to create a more sustainable market environment.
Future Insight of the China iGaming Market
The iGaming market in China will undergo substantial changes by 2032, driven by evolving regulations and technological advancements. The updated National Standard for Online Gaming will improve user protection, building greater trust among players. Initiatives such as the '2022 Online Game Anti-Addiction Program' will promote responsible gaming, likely increasing participation rates. By 2025, the online gaming population is projected to reach 525 million users, reflecting a shift towards regulated platforms and enhanced user experiences.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Game Type – Casino Games Dominated, Poker & Card Games Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, Casino Games held a 45% share of the China iGaming Market by game type in 2025. Casino games dominate the iGaming market in China, appealing to users who seek both entertainment and gambling opportunities. Their popularity is particularly pronounced in the Guangdong province, which serves as a central hub for online gaming activities. Poker & Card Games are set to record the highest CAGR in this split, 6.6% over 2026–2032. Poker and card games are experiencing rapid growth as they attract players interested in competitive and skill-based gaming experiences. This trend is evidenced by the increasing number of dedicated online platforms focusing on these games. Suppliers must focus on developing a diverse range of high-quality casino and poker games to satisfy the growing demand in these segments.
By Platform Type – Web/Mobile App Dominated, Mobile/Desktop Expected to Grow Fastest
Web/Mobile App accounted for a 47% market share by platform type in 2025. Web and mobile applications lead the platform segment, as they provide the most accessible means for users to engage with iGaming services. Approximately 70% of online gamers prefer mobile platforms, highlighting their dominance in the market share. Over 2026–2032, Mobile/Desktop is expected to post the fastest growth, at a CAGR of 6.4%. Mobile and desktop platforms are rapidly gaining traction, driven by the increasing number of users accessing iGaming services through mobile devices. The shift towards mobile gaming is underscored by the growing smartphone penetration in China. Suppliers must prioritise mobile optimisation to meet the increasing demand for gaming accessibility on various devices.
By Monetization Model – Real Money Betting Dominated, In-App Purchases Expected to Grow Fastest
Real Money Betting took a 47% share of monetization model in 2025, more than any other category. Real money betting leads the monetization models in the iGaming sector, drawing serious gamblers who engage in wagering for potential financial rewards. This model is crucial to the industry's revenue share, underscoring its importance. The quickest growth will come from In-App Purchases, forecast to expand at a CAGR of 6.7% between 2026 and 2032. In-app purchases are rapidly gaining traction, especially in mobile gaming, as users show a willingness to spend on enhancements and additional features. This shift towards microtransactions is becoming a significant revenue source for the market. Suppliers should consider integrating in-app purchase options to capitalise on the rising trend of microtransactions among users.
By End User – Online Players Dominated, High-Engagement Users Expected to Grow Fastest
The largest end user category in 2025 was Online Players, with a 52% share of total revenue. Online players represent the largest user base in the iGaming market, motivated by their pursuit of entertainment and the thrill of gambling. Their considerable numbers play a vital role in shaping the overall market share, making them a key focus for suppliers. High-Engagement Users are projected to grow fastest, at a CAGR of 6.7% during 2026–2032. High-engagement users are increasingly prevalent as dedicated players devote more time and resources to their gaming activities. This growth is crucial for suppliers aiming to optimise revenue through tailored offerings. Suppliers should customise their products to align with the preferences of high-engagement users to improve retention and drive overall revenue.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China iGaming Market Outlook
- Market Size of China iGaming Market, 2025
- Forecast of China iGaming Market, 2032
- Historical Data and Forecast of China iGaming Revenues & Volume for the Period 2022 - 2032F
- China iGaming Market Trend Evolution
- China iGaming Market Drivers and Challenges
- China iGaming Price Trends
- China iGaming Porter's Five Forces
- China iGaming Industry Life Cycle
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Game Type for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Casino Games for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Sports Betting for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Poker & Card Games for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Virtual Reality Games for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Mobile/Desktop for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Web/Mobile App for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Browser-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Immersive Devices for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Monetization Model for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By In-App Purchases for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Real Money Betting for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Subscription/Chips for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Freemium for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Online Players for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Sports Fans for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By Casual Gamers for the Period 2022 - 2032F
- Historical Data and Forecast of China iGaming Market Revenues & Volume By High-Engagement Users for the Period 2022 - 2032F
- China iGaming Import Export Trade Statistics
- Market Opportunity Assessment By Game Type
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By Monetization Model
- Market Opportunity Assessment By End User
- China iGaming Top Companies Market Share
- China iGaming Competitive Benchmarking By Technical and Operational Parameters
- China iGaming Company Profiles
- China iGaming Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Game Type
- Casino Games
- Sports Betting
- Poker & Card Games
- Virtual Reality Games
By Platform Type
- Mobile/Desktop
- Web/Mobile App
- Browser-Based
- Immersive Devices
By Monetization Model
- In-App Purchases
- Real Money Betting
- Subscription/Chips
- Freemium
By End User
- Online Players
- Sports Fans
- Casual Gamers
- High-Engagement Users































