India iGaming Market Size & Growth Rate
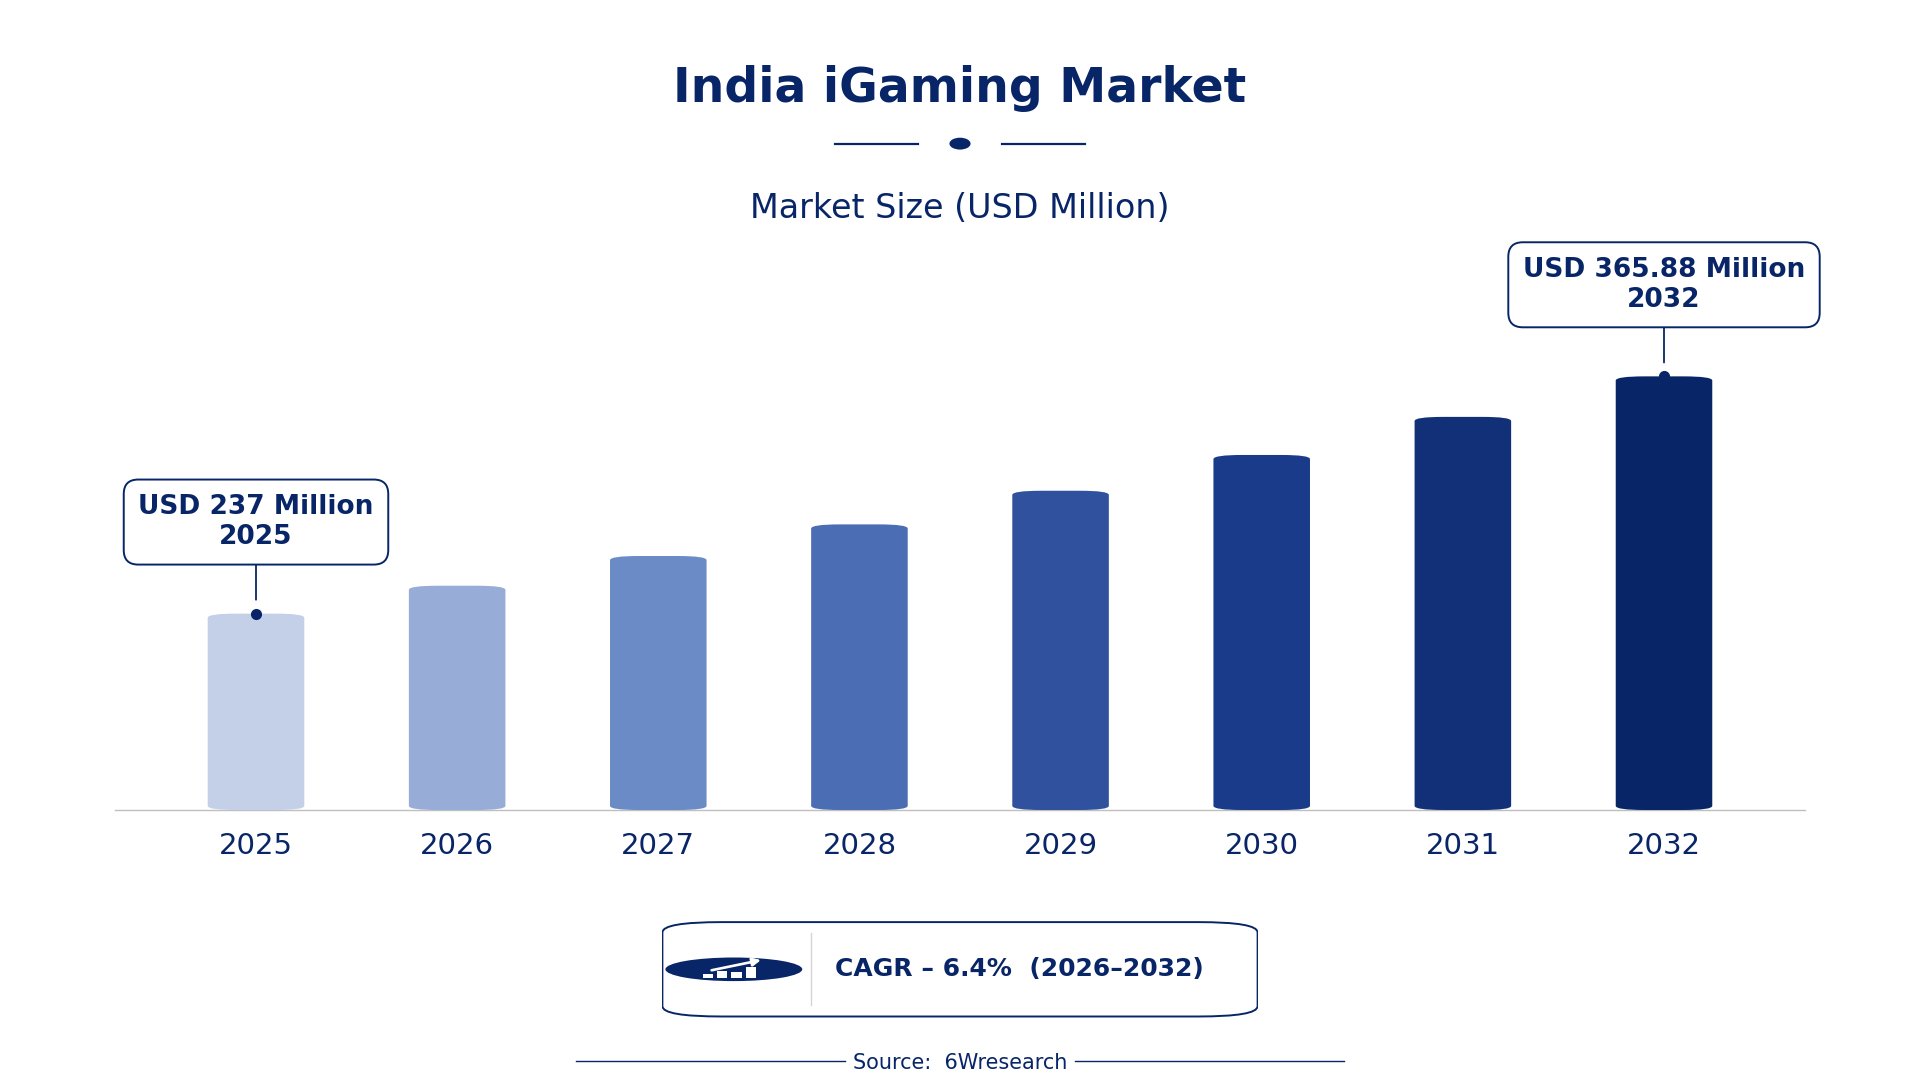
According to 6Wresearch internal database and industry insights, the India iGaming Market was valued at USD 237.0 million in 2025 and is projected to reach USD 365.88 million by 2032, growing at a CAGR of approximately 6.4% during 2026–2032.
India iGaming Market Highlights
| Report Metric | Details |
| Report Name | India iGaming Market |
| Market Size 2025 | USD 237.0 million |
| Market Size 2032 | USD 365.88 million |
| Absolute Growth 2025–2032 | USD 128.88 million |
| CAGR 2026–2032 | 6.4% |
| Peak Annual Growth | 9.1% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Game Type, 2025 | Casino Games (42% share) |
| Leading Platform Type, 2025 | Mobile/Desktop (36% share) |
| Leading Monetization Model, 2025 | Real Money Betting (37% share) |
| Leading End User, 2025 | Online Players (49% share) |
| Fastest-Growing Game Type | Poker & Card Games (8.6% CAGR) |
| Fastest-Growing Platform Type | Web/Mobile App (7.9% CAGR) |
| Fastest-Growing Monetization Model | In-App Purchases (8.2% CAGR) |
| Fastest-Growing End User | High-Engagement Users (8.5% CAGR) |
| Growing Sector | High-Engagement Users |
| Key End Users | Online Players, Sports Fans, High-Engagement Users, Casual Gamers |
India iGaming Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
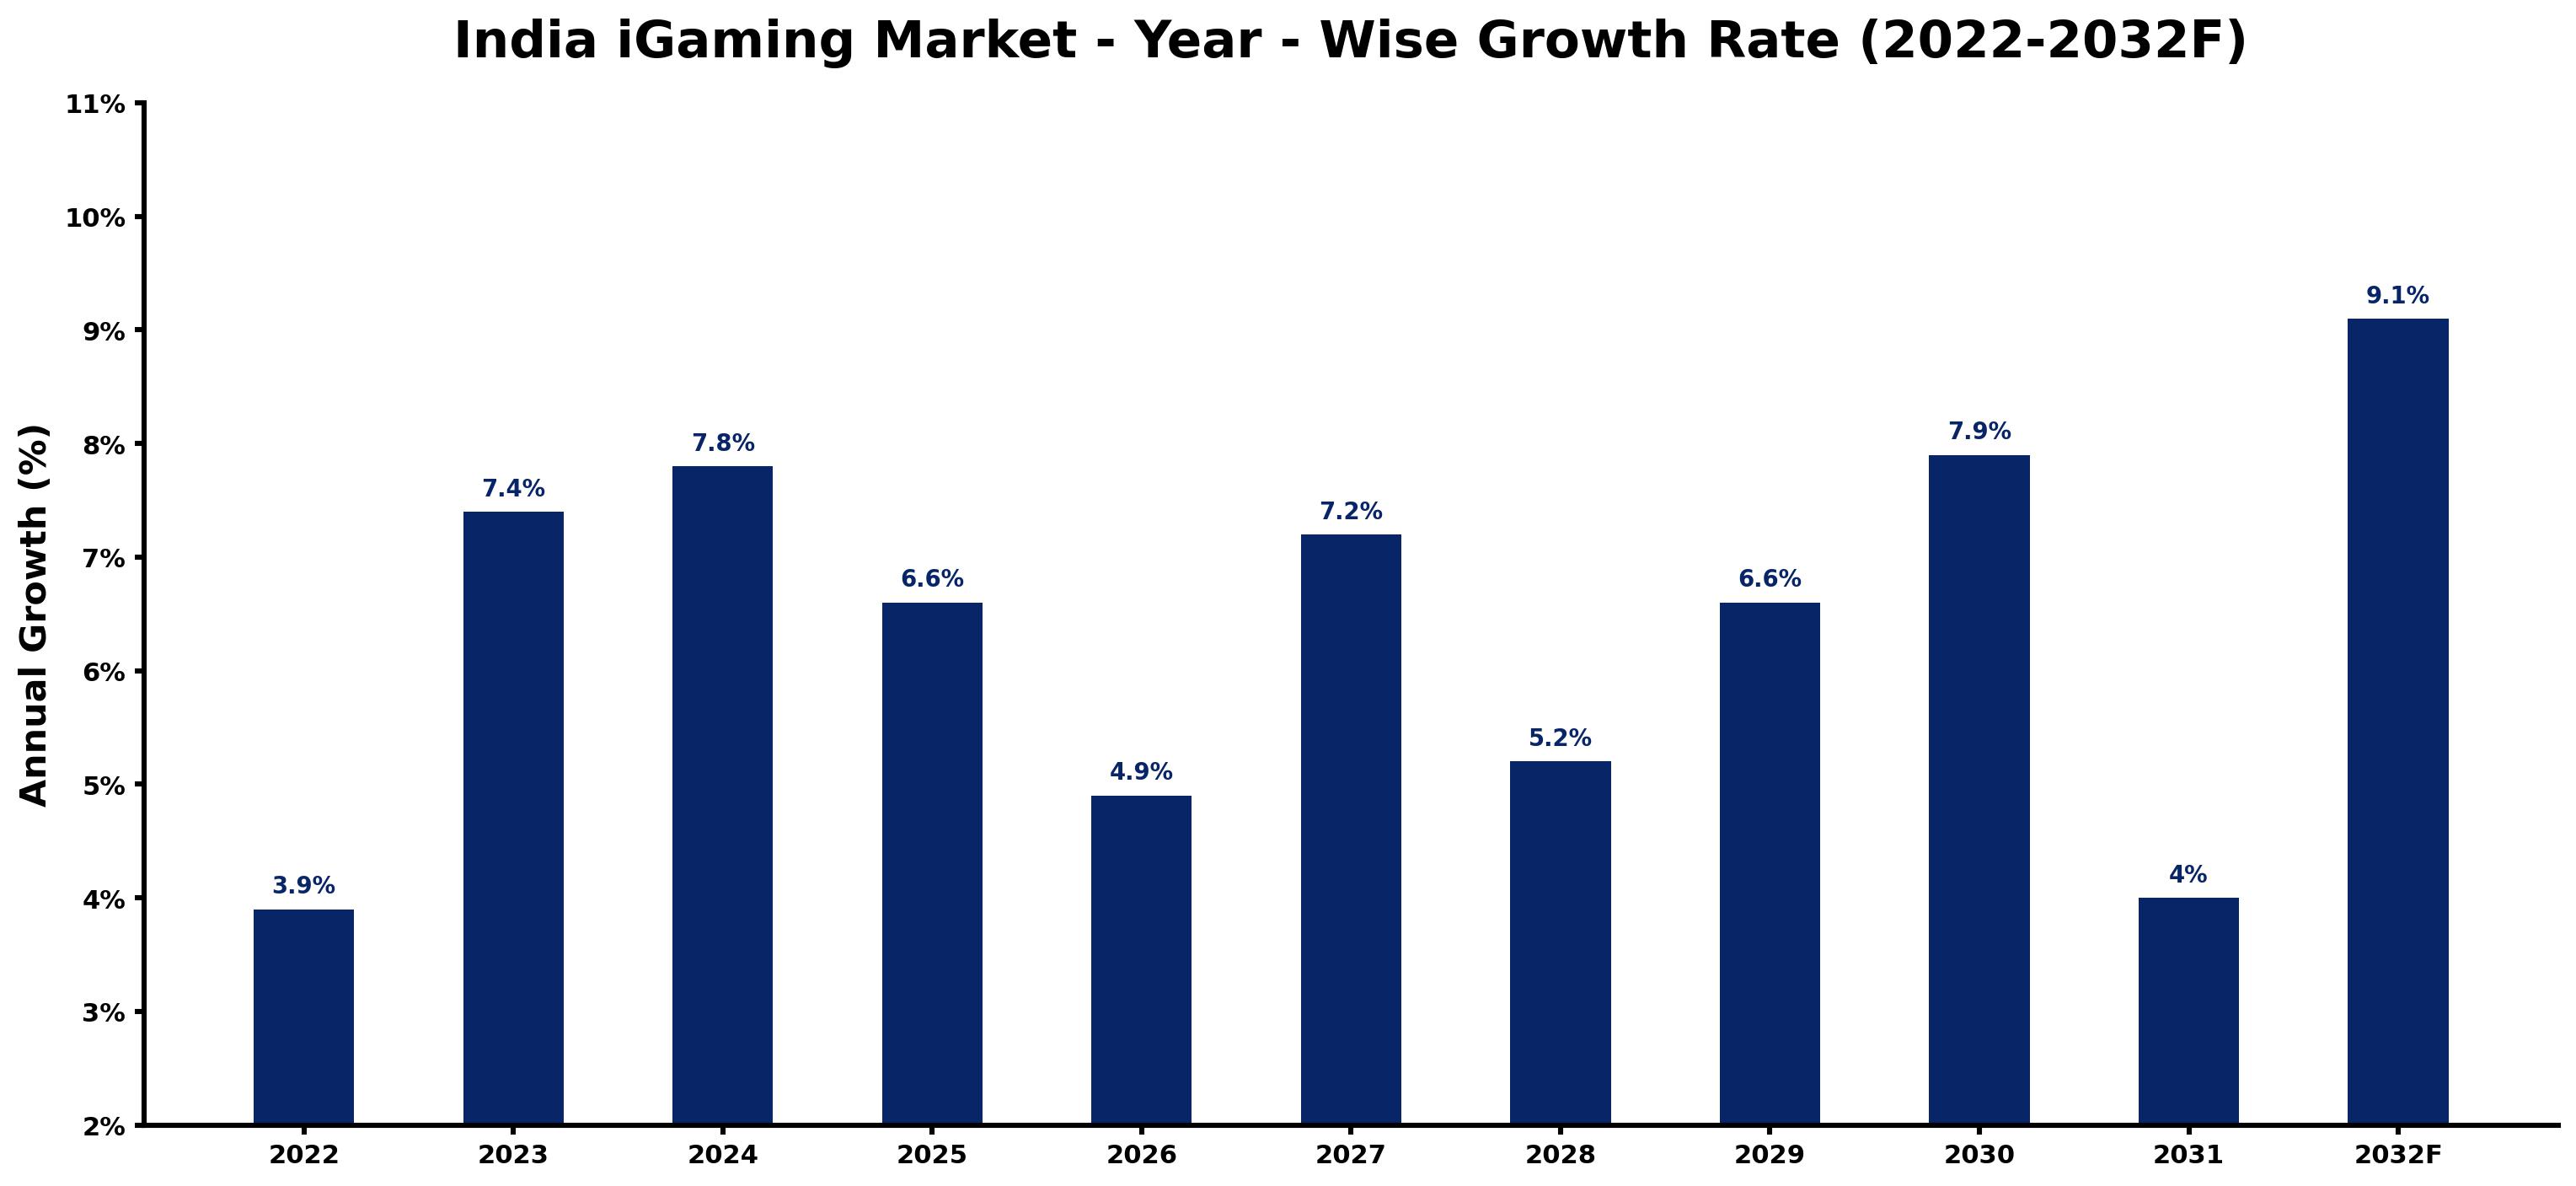
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 3.9 | The market experienced steady growth, driven by a rising number of online players engaging in real money gaming. |
| 2023 | 7.4 | Increased engagement from sports fans contributed to a faster growth rate than the previous year. |
| 2024 | 7.8 | The popularity of casino games further accelerated growth, reaching a new peak. |
| 2025 | 6.6 | Growth slowed slightly as market adjustments occurred following rapid expansion. |
| 2026 | 4.9 | A continued slowdown is expected as the market stabilises after previous highs. |
| 2027 | 7.2 | Renewed interest in poker and card games will lead to a resurgence in growth rates. |
| 2028 | 5.2 | Growth is projected to slow again as the market begins to normalise after the previous peak. |
| 2029 | 6.6 | Increased user engagement from high-engagement users is expected to boost growth once more. |
| 2030 | 7.9 | The market will see a further rise as online gaming continues to attract new players. |
| 2031 | 4.0 | Growth is projected to decelerate again as the market reaches a more mature phase. |
| 2032 | 9.1 | A surge in real money betting and sports betting will contribute to peak growth. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
India iGaming Market Synopsis
The India iGaming Market encompasses online gaming platforms that offer various forms of gambling, including casino games and sports betting. With a user base of 500 million in 2023, the sector is thriving, particularly in states like Sikkim that regulate online gambling. The market is projected to exceed $1 billion by 2025, driven by a growing population of online players and sports enthusiasts. Investment in mobile gaming platforms, which account for over 80% of the market, is also a key factor behind this growth. The ongoing discussions around the Gaming and Sports Betting Bill further indicate the sector's potential for expansion.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Growing user base of online players engaging in real money gaming. | Driver | High | Online Players |
| Increased investment in mobile gaming platforms enhancing accessibility. | Driver | High | Mobile/Desktop |
| Emerging interest in poker and card games attracting new players. | Opportunity | Medium | Poker & Card Games |
| Expansion of licensed operators in regulated states creating competitive offerings. | Opportunity | Medium | Casino Games |
| Inconsistent regulations across states creating confusion for operators. | Restraint | High | Online Players |
| Limited supply of licensed operators in key states like Maharashtra. | Restraint | High | Casino Games |
| Regulatory hurdles from ongoing discussions around the Gaming and Sports Betting Bill. | Challenge | High | Online Players |
| Absence of robust cybersecurity standards deterring user engagement. | Challenge | Medium | Real Money Betting |
Evaluation of Drivers in India iGaming Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Growing user base of online players engaging in real money gaming. | Online Players | This increase in users drives demand for more gaming platforms and services. |
| Increased investment in mobile gaming platforms improving accessibility. | Mobile/Desktop | Investment in mobile platforms leads to higher user engagement and spending. |
| Emerging interest in poker and card games attracting new players. | Poker & Card Games | As more players seek competitive play, demand for these games rises. |
| Expansion of licensed operators in regulated states creating competitive offerings. | Casino Games | More operators entering the market increases choices for consumers. |
| Growing sports fandom driving engagement in betting activities. | Sports Betting | An increase in sports fans leads to higher betting volumes on events. |
Growth across the iGaming market in India is anchored in the expanding user base of online players and increased investment in mobile gaming platforms. The online gaming user base reached 500 million in 2023, driving demand for diverse gaming options. Mobile gaming accounts for over 80% of the market, improving accessibility for users. The popularity of poker and card games is rising, attracting new players seeking competitive experiences. The expansion of licensed operators in states like Sikkim is creating a more competitive environment, further stimulating growth.
Evaluation of Restraints in India iGaming Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Inconsistent regulations across states creating confusion for operators. | Online Players | This inconsistency complicates compliance and can delay market entry for new operators. |
| Limited supply of licensed operators in key states like Maharashtra. | Casino Games | The scarcity of operators can lead to increased costs and limited choices for consumers. |
| Regulatory hurdles from ongoing discussions around the Gaming and Sports Betting Bill. | Online Players | Uncertainty in regulations may deter investment and slow market growth. |
| Absence of cybersecurity standards deterring user engagement. | Real Money Betting | Concerns over safety can prevent users from participating in real money gaming. |
| High taxation rates on gaming revenues affecting profitability. | Casino Games | Increased costs can limit the ability of operators to invest in growth and innovation. |
India iGaming Market Challenges
The India iGaming market encounters several practical issues, starting with the lack of uniform regulation across states. This inconsistency creates confusion for consumers as they navigate different legal frameworks, potentially delaying access to gaming platforms. Another challenge is the limited number of licensed operators, particularly in Maharashtra, which has 200 million online gaming users; this scarcity can lead to higher costs for consumers. Regulatory hurdles persist, as ongoing discussions about the Gaming and Sports Betting Bill may introduce new compliance requirements, complicating operations for producers. Technology adoption is also impeded by the absence of cybersecurity standards, raising safety concerns and discouraging consumers from participating in real money gaming.
Trends in the India iGaming Market
Several trends are reshaping the India iGaming Market; the most important are set out below.
- Shift Towards Mobile Gaming Platforms: India is witnessing a transition towards mobile gaming platforms, with over 80% of the iGaming market attributed to mobile access. This trend is supported by growing smartphone penetration and user preference for on-the-go gaming experiences.
- Emerging Popularity of Poker and Card Games: Poker and card games are gaining traction among users, particularly in states where regulations support these activities. The segment is projected to grow at a CAGR of 8.6% from 2026 to 2032, attracting competitive players.
- Increased Focus on Responsible Gaming Practices: The All India Gaming Federation is promoting responsible gaming practices, which are becoming essential for operators. This focus is anticipated to improve consumer trust and engagement in the gaming sector.
- Growth in Real Money Betting: Real money betting is becoming increasingly popular, driven by a surge in sports betting activities. This segment is expected to expand as more users engage in betting on various sporting events.
Investment Opportunities in the India iGaming Market
Below are the investment opportunities with the strongest case in the India iGaming Market.
- Investment in Mobile Gaming Platforms: Investment in mobile gaming platforms is essential now, as mobile gaming accounts for over 80% of the market. Engaging with online players in states like Maharashtra can yield substantial returns.
- Supply of Licensed Operators: The demand for more licensed operators is urgent, particularly in Maharashtra, which has the largest user base. Collaborating with local entities could facilitate entry into this growing market.
- Expansion of Poker and Card Games: The increasing interest in poker and card games presents opportunities for developers to create competitive platforms. Targeting high-engagement users can stimulate growth in this segment.
- Focus on Responsible Gaming Initiatives: Investing in responsible gaming initiatives is timely, as consumer trust is crucial. Partnering with organisations like the All India Gaming Federation can bolster credibility.
Government Initiatives in the India iGaming Market
The Gaming and Sports Betting Bill, proposed by the Ministry of Electronics and Information Technology in 2023, seeks to regulate online gaming and ensure fair play. This initiative builds on the National Policy on Electronics 2020, which includes measures to support the growth of the gaming industry and aims to create 1 million jobs by 2025. The bill is expected to establish a clearer regulatory framework, encouraging more licensed operators to enter the market.
The Ministry of Electronics and Information Technology oversees the implementation of the National Gaming Authority, which regulates the gaming industry. This agency approves licenses for online gaming operators and ensures compliance with consumer protection standards. Additionally, the Digital India initiative, launched in 2021, promotes digital gaming and skill development, further supporting the sector's growth.
Future Insight of the India iGaming Market
The iGaming market in India will undergo significant transformation by 2032, primarily driven by the anticipated approval of the Gaming and Sports Betting Bill, which will establish a clearer regulatory framework. This change will encourage more licensed operators to enter the market, enhancing competition and improving options for buyers. The National Policy on Electronics aims to boost the sector, potentially creating 1 million jobs by 2025. As mobile gaming continues to dominate, with 80% of users engaging through mobile platforms, advancements in technology will further enrich user experiences and expand the player base.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Game Type – Casino Games Dominated, Poker & Card Games Expected to Grow Fastest
According to Bhawna Singh, Assistant Manager at 6Wresearch, with a 42% revenue share in 2025, Casino Games was the largest game type category. Casino games hold the largest share in the India iGaming market due to their widespread popularity among users who seek both entertainment and the chance to win money. The significant user base in Maharashtra showcases the strong demand for these games, reinforcing their leading position. Poker & Card Games are projected to grow fastest, at a CAGR of 8.6% during 2026–2032. Poker and card games are experiencing rapid growth as they attract a dedicated audience interested in competitive play, reflecting a shift towards skill-based gaming. The increasing availability of online platforms offering these games further enhances their appeal. Suppliers should focus on expanding their casino game offerings to capture a larger share of the growing market.
By Platform Type – Mobile/Desktop Dominated, Web/Mobile App Expected to Grow Fastest
The largest platform type category in 2025 was Mobile/Desktop, with a 36% share of total revenue. Mobile and desktop platforms dominate the iGaming market as they serve as the primary access points for users engaging with various gaming services. Their convenience plays a crucial role in attracting a large number of online players throughout the country. Over 2026–2032, Web/Mobile App is expected to post the fastest growth, at a CAGR of 7.9%. Web and mobile app platforms are growing quickly, driven by the need for seamless user engagement and accessibility, particularly among younger demographics. This trend underscores the importance of mobile optimisation in the iGaming sector. Suppliers must prioritise the development of mobile and web applications to stay competitive and effectively cater to the expanding user base.
By Monetization Model – Real Money Betting Dominated, In-App Purchases Expected to Grow Fastest
Real Money Betting accounted for a 37% market share by monetization model in 2025. Real money betting represents the largest share of monetization models within the iGaming market, as it is essential for generating substantial revenue. This model appeals to users who are eager for the excitement of gambling with real stakes involved. The quickest growth will come from In-App Purchases, forecast to expand at a CAGR of 8.2% between 2026 and 2032. In-app purchases are rapidly gaining popularity, as they significantly enhance user experience and engagement, especially among dedicated players. This trend indicates a growing acceptance of microtransactions within gaming platforms, appealing to a wider audience. Suppliers should explore diversifying their monetization strategies to include in-app purchases alongside real money betting to optimise revenue potential.
By End User – Online Players Dominated, High-Engagement Users Expected to Grow Fastest
In 2025, Online Players led the end user split with a 49% share. Online players make up the largest user segment in the India iGaming market, driving overall market growth through their engagement and spending. The impressive figure of 500 million users in 2023 highlights the vital role of this demographic. High-Engagement Users are set to record the highest CAGR in this split, 8.5% over 2026–2032. High-engagement users are emerging as the fastest-growing segment, as they tend to invest more in premium offerings and actively participate in competitive gaming. Their increasing presence indicates a shift towards more committed gaming experiences. Suppliers should tailor their products to attract high-engagement users, ensuring they meet the demands of this lucrative segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- India iGaming Market Outlook
- Market Size of India iGaming Market, 2025
- Forecast of India iGaming Market, 2032
- Historical Data and Forecast of India iGaming Revenues & Volume for the Period 2022 - 2032F
- India iGaming Market Trend Evolution
- India iGaming Market Drivers and Challenges
- India iGaming Price Trends
- India iGaming Porter's Five Forces
- India iGaming Industry Life Cycle
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Game Type for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Casino Games for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Sports Betting for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Poker & Card Games for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Virtual Reality Games for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Platform Type for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Mobile/Desktop for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Web/Mobile App for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Browser-Based for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Immersive Devices for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Monetization Model for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By In-App Purchases for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Real Money Betting for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Subscription/Chips for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Freemium for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Online Players for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Sports Fans for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By Casual Gamers for the Period 2022 - 2032F
- Historical Data and Forecast of India iGaming Market Revenues & Volume By High-Engagement Users for the Period 2022 - 2032F
- India iGaming Import Export Trade Statistics
- Market Opportunity Assessment By Game Type
- Market Opportunity Assessment By Platform Type
- Market Opportunity Assessment By Monetization Model
- Market Opportunity Assessment By End User
- India iGaming Top Companies Market Share
- India iGaming Competitive Benchmarking By Technical and Operational Parameters
- India iGaming Company Profiles
- India iGaming Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Game Type
- Casino Games
- Sports Betting
- Poker & Card Games
- Virtual Reality Games
By Platform Type
- Mobile/Desktop
- Web/Mobile App
- Browser-Based
- Immersive Devices
By Monetization Model
- In-App Purchases
- Real Money Betting
- Subscription/Chips
- Freemium
By End User
- Online Players
- Sports Fans
- Casual Gamers
- High-Engagement Users































