China Industrial Automation Components Market Size & Growth Rate
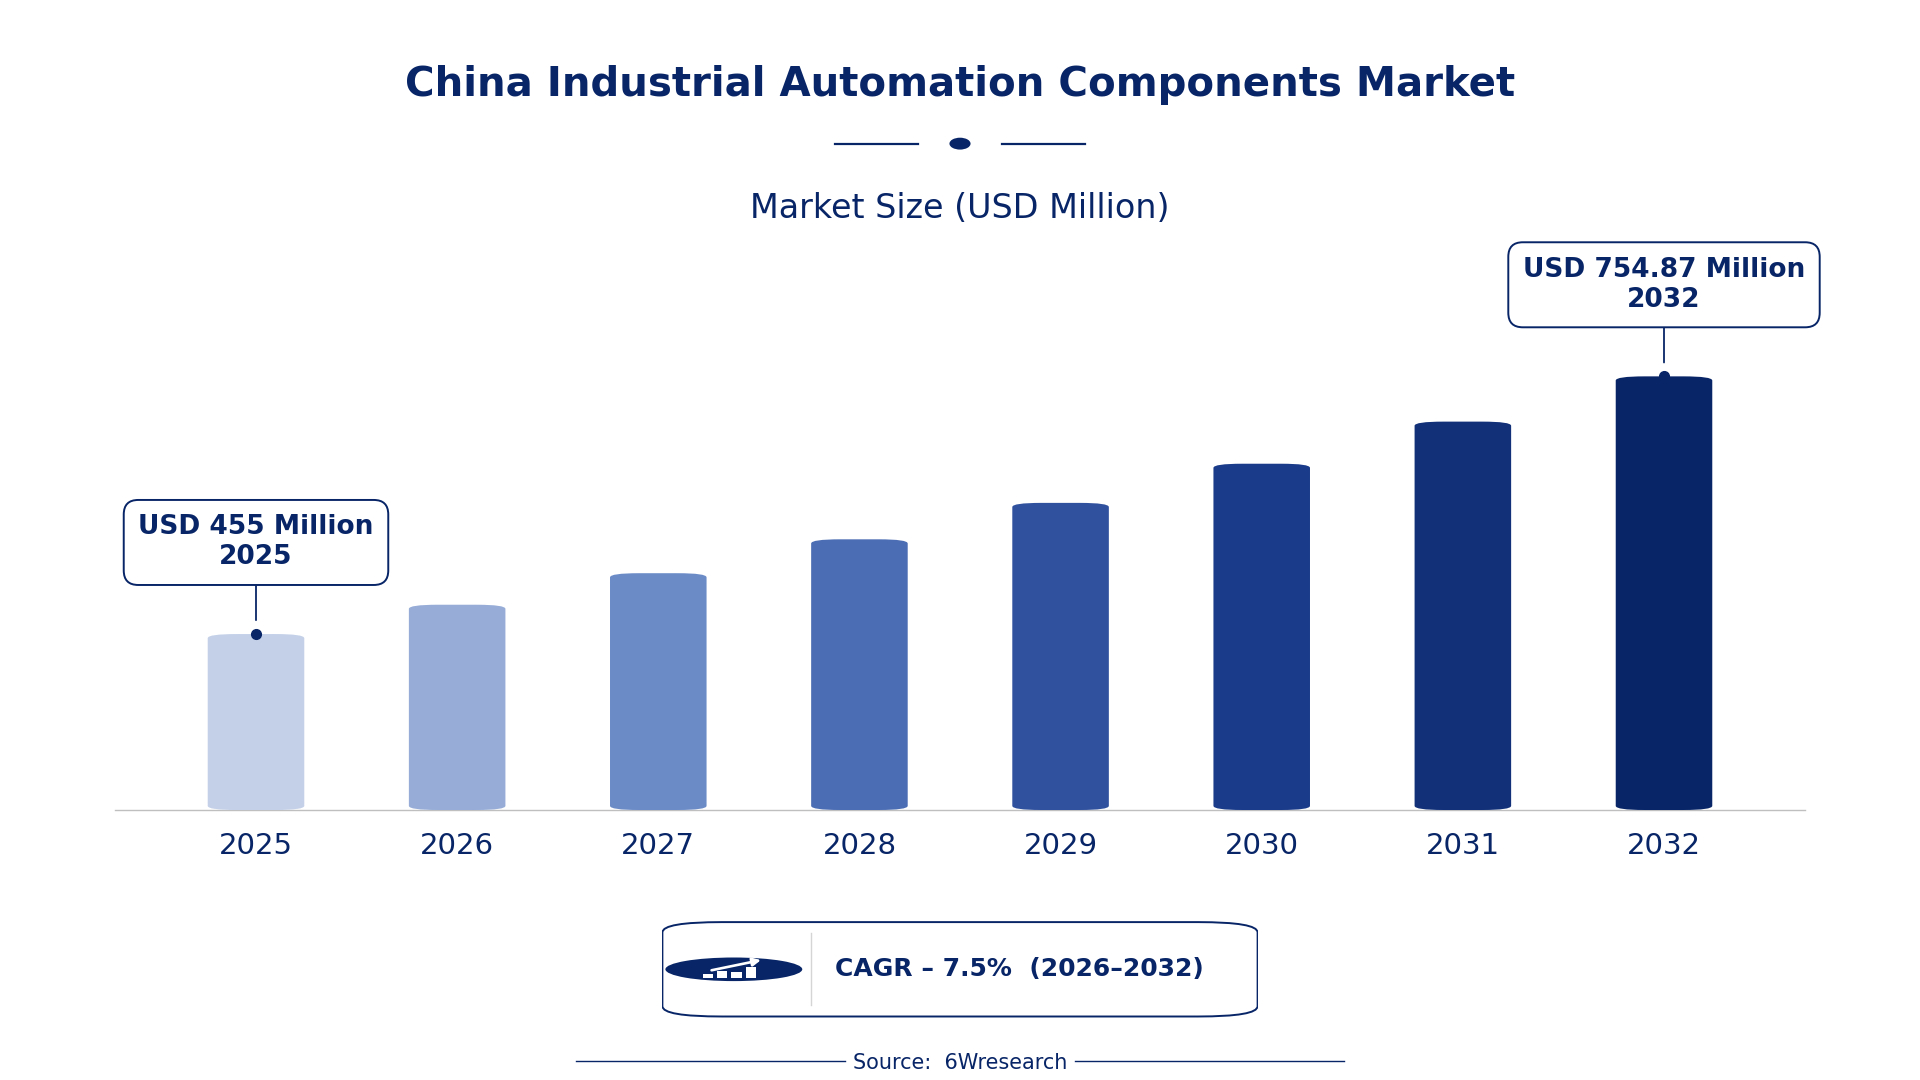
According to 6Wresearch internal database and industry insights, the China Industrial Automation Components Market was valued at USD 455.0 million in 2025 and is projected to reach USD 754.87 million by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Industrial Automation Components Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Automation Components Market |
| Market Size 2025 | USD 455.0 million |
| Market Size 2032 | USD 754.87 million |
| Absolute Growth 2025–2032 | USD 299.87 million |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 9.9% in 2030 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Component Type, 2025 | Sensors (33% share) |
| Leading Functionality, 2025 | Measurement (36% share) |
| Leading Integration Level, 2025 | PLC-Connected (41% share) |
| Leading End User, 2025 | Machine Builders (41% share) |
| Fastest-Growing Component Type | PLCs (9.9% CAGR) |
| Fastest-Growing Functionality | Motion Control (9.8% CAGR) |
| Fastest-Growing End User | Robotics OEMs (8.6% CAGR) |
| Growing Sector | Robotics |
| Key End Users | Machine Builders, Robotics OEMs, Assembly Lines, Control Panel Makers |
China Industrial Automation Components Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
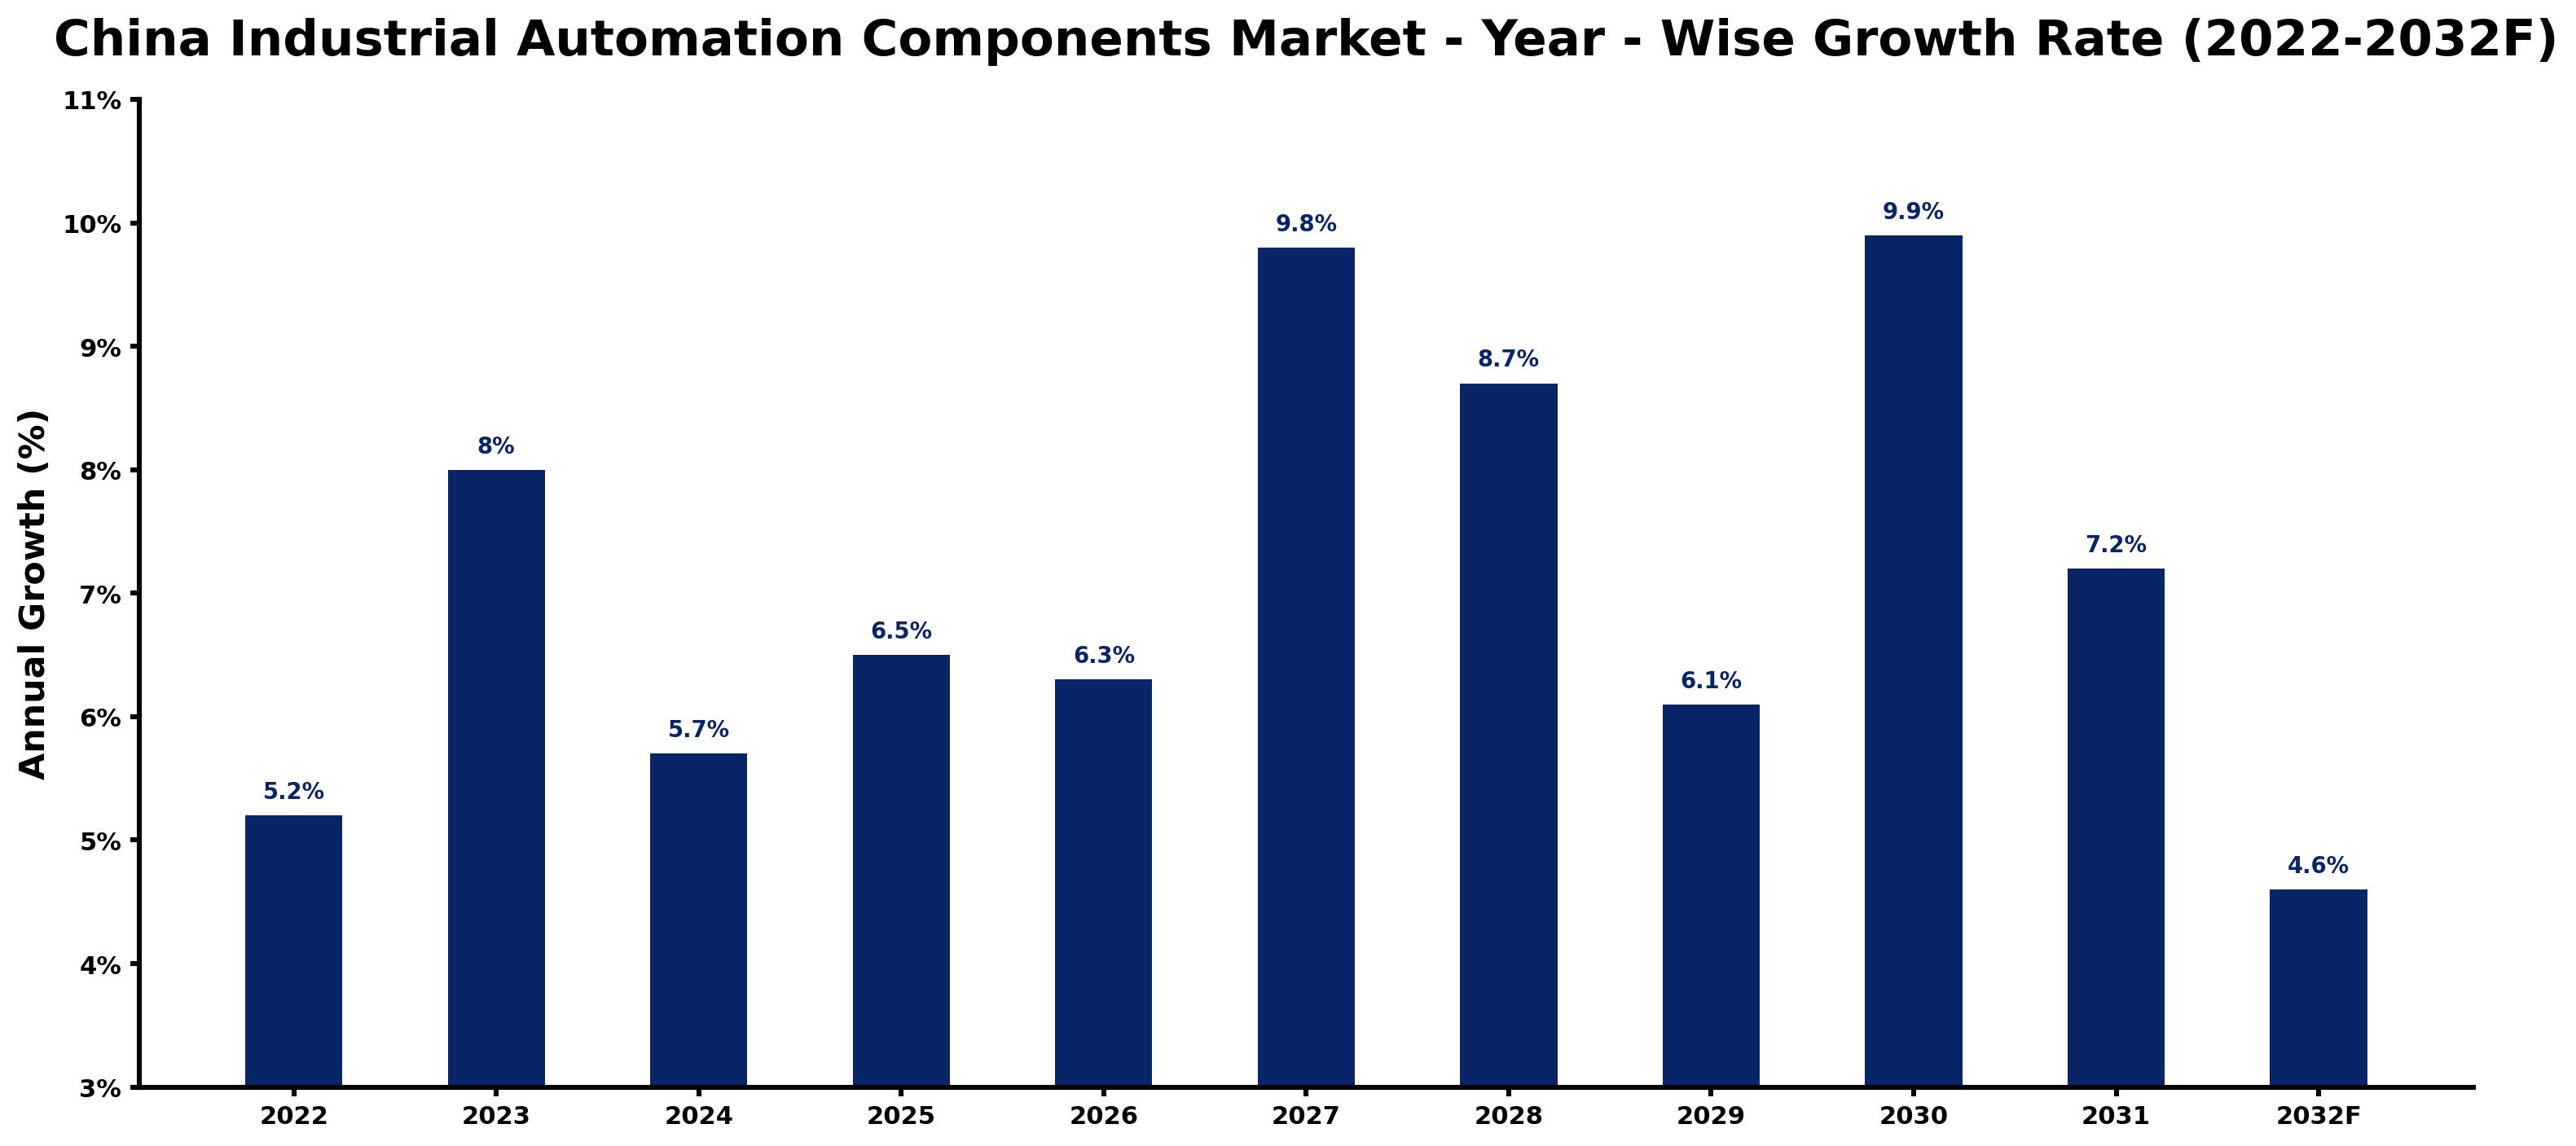
Below, each year's estimated growth is shown next to the factor that most influenced it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.2 | The manufacturing sector employed over 100 million workers, driving initial demand for automation components. |
| 2023 | 8.0 | Growth accelerated due to the launch of the 'Made in China 2025' initiative, promoting automation. |
| 2024 | 5.7 | Demand slowed as companies adjusted to the previous year's rapid growth and market conditions. |
| 2025 | 6.5 | Increased investments in the Yangtze River Delta region spurred demand for automation components. |
| 2026 | 6.3 | A slowdown is anticipated as manufacturers face challenges in scaling production efficiently. |
| 2027 | 9.8 | Growth is expected to surge as Robotics OEMs expand, increasing the need for automation components. |
| 2028 | 8.7 | A slight slowdown is anticipated as the market adjusts to the previous high growth rates. |
| 2029 | 6.1 | Demand will continue to slow as manufacturers focus on optimising existing automation systems. |
| 2030 | 9.9 | The market will peak due to heightened investments in automation driven by the 'Intelligent Manufacturing Development Plan'. |
| 2031 | 7.2 | Growth will decelerate as the 'Smart Manufacturing Pilot Program' begins to influence investment patterns. |
| 2032 | 4.6 | The market is projected to slow further as companies consolidate their automation capabilities. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Automation Components Market Synopsis
The China Industrial Automation Components Market includes essential elements used in manufacturing processes to improve efficiency and precision. These components, made from metals, plastics, and electronic materials, control machinery and monitor processes. The market is expanding due to strong demand from domestic manufacturing, robotics, and assembly industries. The 'Made in China 2025' initiative drives this growth, aiming to boost automation across sectors.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Rising demand for automation in the automotive sector | Driver | High | PLCs |
| Increased production of industrial robots | Driver | High | Sensors |
| Expansion of Robotics OEMs in China | Opportunity | High | Robotics OEMs |
| Growing investments in the Yangtze River Delta region | Opportunity | High | Machine Builders |
| Challenges in scaling production capacity | Restraint | Medium | Actuators |
| Market saturation affecting new investments | Restraint | Medium | PLCs |
| High competition among local manufacturers | Challenge | High | Sensors |
| Technological advancements requiring constant updates | Challenge | High | Measurement |
Evaluation of Drivers in China Industrial Automation Components Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased demand for automation in the automotive sector | PLCs | This sector's growth drives the need for more PLCs to automate processes, with demand rising as production ramps up. |
| Surge in industrial robot production | Sensors | With China producing over 50% of the world's industrial robots, the need for sensors for feedback and measurement is increasing. |
| Expansion of Robotics OEMs | Robotics OEMs | This sector is projected to grow by 15% annually, leading to higher demand for automation components. |
| Growing investments in the Yangtze River Delta region | Machine Builders | This region's focus on automation technology is driving demand for components, with significant investments being made. |
| Adoption of ISO 9001 quality management standards | Measurement | The widespread adoption of this standard increases the need for measurement components to ensure compliance and efficiency. |
Growth in the Industrial Automation Components market in China comes from rising demand for automation in the automotive sector, which drives the need for more PLCs. The production of industrial robots is surging, with China producing over 50% of the world's supply, increasing the demand for sensors. Expansion in Robotics OEMs is anticipated to grow by 15% annually, resulting in higher demand for automation components. Investments in the Yangtze River Delta region are driving demand for machine building components. The adoption of ISO 9001 quality management standards increases the need for measurement components to ensure compliance and efficiency.
Evaluation of Restraints in China Industrial Automation Components Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Challenges in scaling production capacity | Actuators | Manufacturers face difficulties in expanding production to meet growing demand, affecting supply timelines. |
| Market saturation affecting new investments | PLCs | As the market becomes saturated, attracting new investments in PLCs becomes increasingly challenging. |
| High competition among local manufacturers | Sensors | Intense competition leads to price wars, impacting profit margins for manufacturers. |
| Technological advancements requiring constant updates | Measurement | Manufacturers must continuously invest in R&D to keep up with rapid technological changes. |
| Regulatory compliance costs | PLCs | Meeting stringent regulations increases operational costs for manufacturers, affecting pricing. |
China Industrial Automation Components Market Challenges
The China Industrial Automation Components Market encounters several practical issues, beginning with supply chain disruptions that can postpone production timelines for manufacturers. These disruptions arise from dependence on global suppliers, resulting in lead times for critical components extending by up to 30%. Regulatory challenges also present obstacles; compliance with ISO 9001 standards necessitates substantial investment in quality management systems, costing suppliers over 200,000 yuan. Skills shortages in the workforce complicate operations, as over 40% of companies struggle to find qualified technicians, which can impede project implementations. Technology adoption is lagging, with only 30% of firms fully integrating advanced automation solutions, limiting operational efficiency for buyers.
Trends in the China Industrial Automation Components Market
Four trends stand out in the China Industrial Automation Components Market.
- Shift towards Smart Manufacturing: China is increasingly adopting smart manufacturing practices, driven by the 'Intelligent Manufacturing Development Plan' launched in 2021. This initiative aims to improve automation capabilities across industries, with a target of increasing efficiency by 20%.
- Growing Focus on Robotics Integration: The '13th Five-Year Plan for Robotics Industry' aims to increase domestic robot production by 30% by 2025. This plan is reshaping the market, with manufacturers investing heavily in robotics integration.
- Increase in PLC-Connected Components: The demand for PLC-connected components is rising, with their market share expected to reach 41% by 2025. This trend reflects the growing need for real-time data processing in automation.
- Expansion of Automation in Small Enterprises: The 'Smart Manufacturing Pilot Program' initiated in 2020 promotes automation in small and medium enterprises. This programme is expected to boost automation adoption, with an estimated 10,000 SMEs participating.
Investment Opportunities in the China Industrial Automation Components Market
Investors looking at the China Industrial Automation Components Market should consider the following areas.
- Forming Alliances with Local Manufacturers: Now is an ideal time to form partnerships with local manufacturers in the Yangtze River Delta region, where demand for automation components is surging, with investments exceeding USD 100 million.
- Investing in Robotics OEMs: With Robotics OEMs projected to grow by 15% annually, investing in this sector presents a valuable opportunity for suppliers aiming to meet increasing demand for automation components.
- Certification for ISO 9001 Compliance: There is a growing need for suppliers to obtain ISO 9001 certification, as manufacturers seek compliant partners to ensure quality standards are met, enhancing market entry prospects.
- Focus on Automation for Small Enterprises: The ongoing push for automation in small and medium enterprises presents a significant opportunity for suppliers to provide tailored solutions, with an estimated 10,000 SMEs targeted for automation upgrades.
Government Initiatives in the China Industrial Automation Components Market
In 2022, the National Standardization Administration introduced the 'National Standard for Industrial Automation Systems' to enhance safety and efficiency in automation. This measure builds on previous regulations by establishing clearer standards for component performance and safety, ensuring manufacturers meet industry requirements. The introduction of this standard is expected to improve compliance across the sector, benefiting both producers and buyers.
The 'Intelligent Manufacturing Development Plan', overseen by the Ministry of Industry and Information Technology, allocated USD 500 million in funding to enhance automation capabilities across industries. This agency supports projects that align with national automation goals, facilitating industry growth and development, enabling producers to access new technologies and improve operational efficiency.
Future Insight of the China Industrial Automation Components Market
The outlook for Industrial Automation Components in China will evolve by 2032, driven by the 'Made in China 2025' initiative focused on boosting automation. Robotics OEMs will experience strong growth, with an annual increase of 15%, improving the availability of automation solutions for buyers. The installed base of industrial sensors, exceeding 1 billion units in 2022, will continue to grow, enhancing monitoring and control capabilities. Investment in the Beijing-Tianjin-Hebei region will increase, promoting innovation and competitiveness among suppliers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Component Type – Sensors Dominated, PLCs Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Sensors led the component type split with a 33% share. Sensors command the largest market share because they are essential for measurement and feedback in automation systems. With over 1 billion units installed in China by 2022, their widespread use across various industries underscores their importance. PLCs are projected to grow fastest, at a CAGR of 9.9% during 2026–2032. The surge in PLCs is primarily propelled by increased automation in the automotive and electronics sectors, which are keen on improving operational efficiency. This trend is expected to continue as these industries adopt more automated processes. Suppliers should enhance their PLC offerings to capitalise on the growing automation demand in China.
By Functionality – Measurement Dominated, Motion Control Expected to Grow Fastest
Measurement held a 36% share of the China Industrial Automation Components Market by functionality in 2025. Measurement functionalities lead the market share as they are crucial for effective monitoring and control in automation systems, ensuring smooth operations. The strong demand from diverse manufacturing sectors in China highlights their vital role in industrial processes. Motion Control is set to record the highest CAGR in this split, 9.8% over 2026–2032. Motion control is experiencing the fastest growth due to its essential function in ensuring precise movement in machinery, particularly in advanced manufacturing settings. As industries adopt more sophisticated technologies, the demand for motion control solutions will escalate. Buyers should focus on investing in advanced motion control technologies to improve operational efficiency and precision in their manufacturing activities.
By Integration Level – PLC-Connected Dominated and Is Expected to Record the Fastest Growth
PLC-Connected took a 41% share of integration level in 2025, more than any other category. PLC-connected components hold the largest market share as they are critical for real-time data processing and control in automation systems. This integration is vital for manufacturers looking to optimise operations and boost productivity. PLC-Connected is also forecast to expand faster than any other category, at a CAGR of 9.1% over 2026–2032. The synergy between PLCs and other automation components will further reinforce their market position. Suppliers must prioritise the development of PLC-connected solutions to meet the rising demand for integrated automation systems.
By End User – Machine Builders Dominated, Robotics OEMs Expected to Grow Fastest
The largest end user category in 2025 was Machine Builders, with a 41% share of total revenue. Machine builders account for the largest market share as they rely on automation components to construct automated systems for various industries. Their pivotal role in the manufacturing landscape generates substantial demand for these components. The quickest growth will come from Robotics OEMs, forecast to expand at a CAGR of 8.6% between 2026 and 2032. Robotics OEMs are the fastest growing end user segment, heavily depending on automation components to create robotic systems that are becoming essential in modern manufacturing. This growth reflects the broader shift towards automation across multiple sectors. Suppliers should tailor their products to meet the specific needs of robotics OEMs to capture growth opportunities in this segment.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Automation Components Market Outlook
- Market Size of China Industrial Automation Components Market, 2025
- Forecast of China Industrial Automation Components Market, 2032
- Historical Data and Forecast of China Industrial Automation Components Revenues & Volume for the Period 2022 - 2032F
- China Industrial Automation Components Market Trend Evolution
- China Industrial Automation Components Market Drivers and Challenges
- China Industrial Automation Components Price Trends
- China Industrial Automation Components Porter's Five Forces
- China Industrial Automation Components Industry Life Cycle
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Component Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Sensors for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Actuators for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By PLCs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Relays & Timers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Functionality for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Measurement for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Motion Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Process Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Switching Functions for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Integration Level for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Embedded/External for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By PLC-Connected for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Modular/Compact for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Panel-Mounted for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Machine Builders for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Robotics OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Assembly Lines for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation Components Market Revenues & Volume By Control Panel Makers for the Period 2022 - 2032F
- China Industrial Automation Components Import Export Trade Statistics
- Market Opportunity Assessment By Component Type
- Market Opportunity Assessment By Functionality
- Market Opportunity Assessment By Integration Level
- Market Opportunity Assessment By End User
- China Industrial Automation Components Top Companies Market Share
- China Industrial Automation Components Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Automation Components Company Profiles
- China Industrial Automation Components Key Strategic Recommendations
Market Covered
The report offers an extensive study of the following market segments.
By Component Type
- Sensors
- Actuators
- PLCs
- Relays & Timers
By Functionality
- Measurement
- Motion Control
- Process Control
- Switching Functions
By Integration Level
- Embedded/External
- PLC-Connected
- Modular/Compact
- Panel-Mounted
By End User
- Machine Builders
- Robotics OEMs
- Assembly Lines
- Control Panel Makers































