China Industrial Automation IC Market Size & Growth Rate
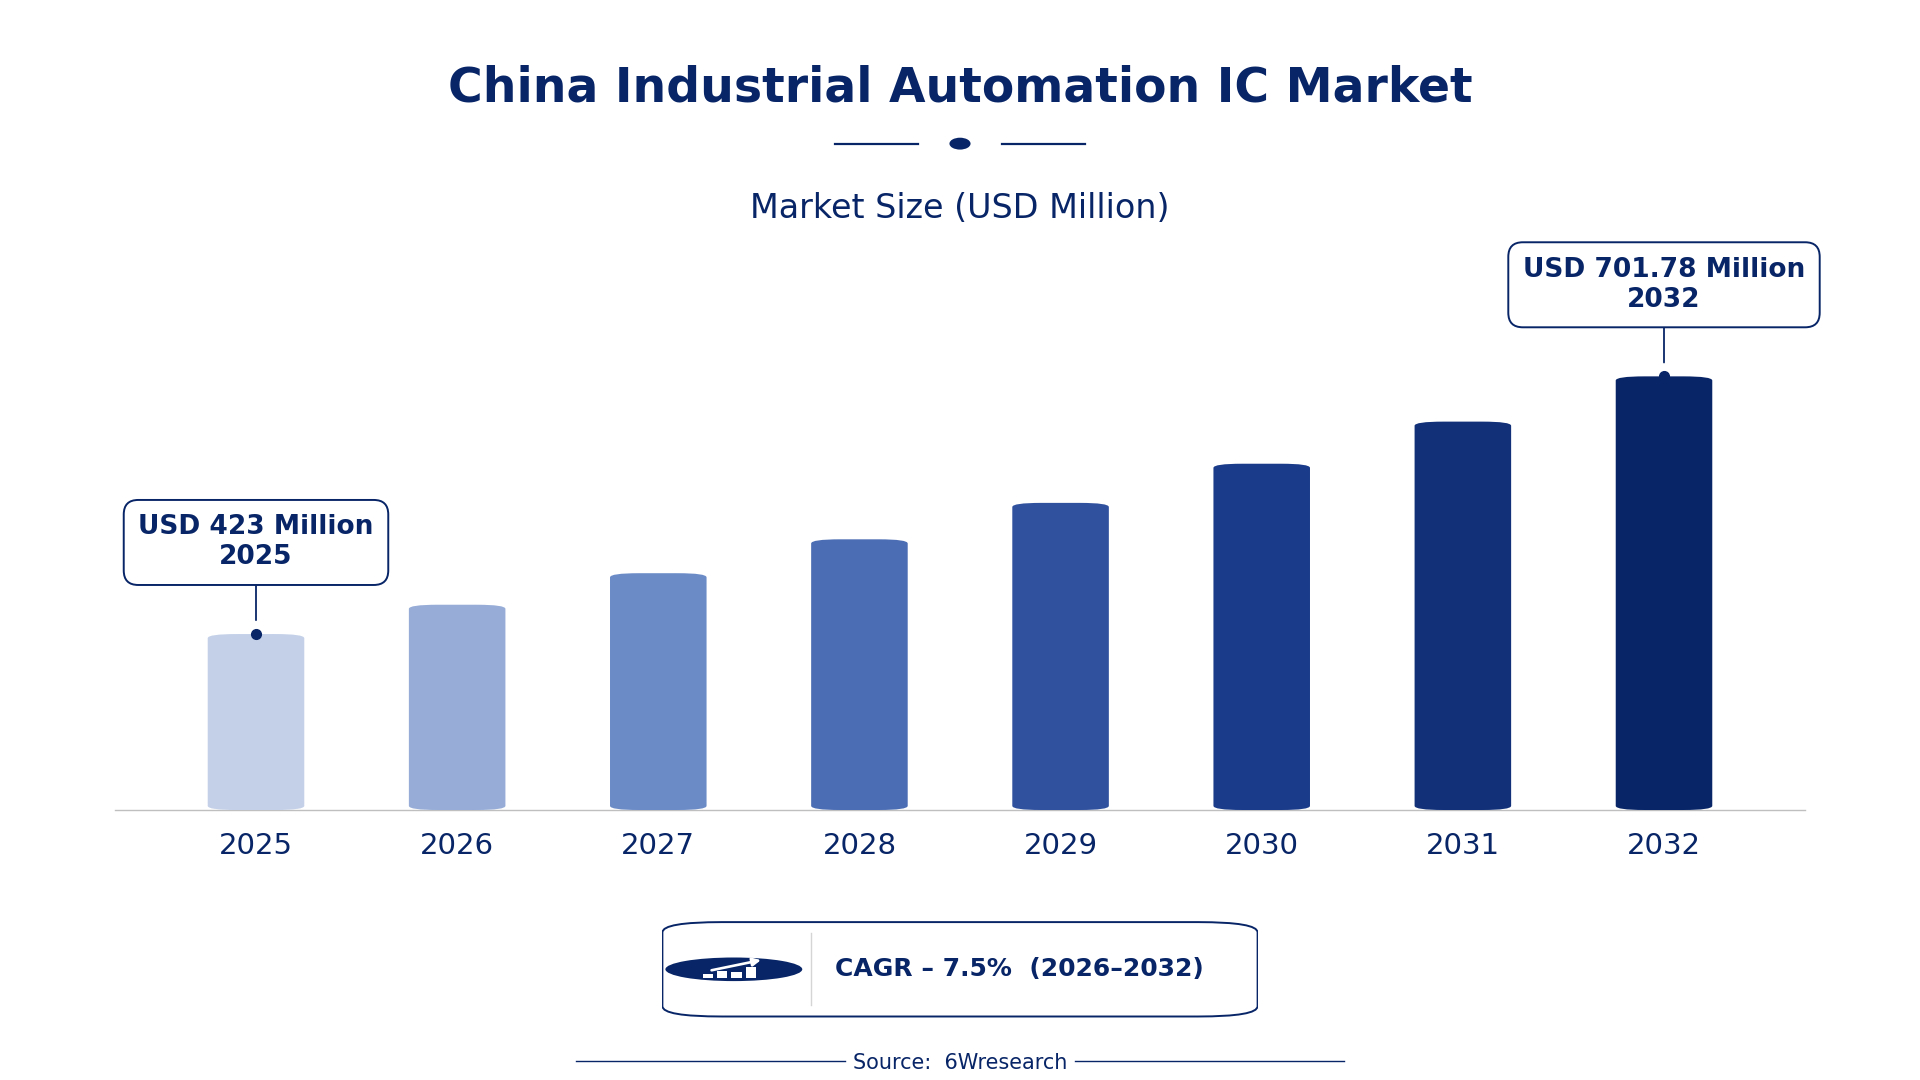
According to 6Wresearch internal database and industry insights, the China Industrial Automation IC Market was valued at USD 423.0 million in 2025 and is projected to reach USD 701.78 million by 2032, growing at a CAGR of approximately 7.5% during 2026–2032.
China Industrial Automation IC Market Highlights
| Report Metric | Details |
| Report Name | China Industrial Automation IC Market |
| Market Size 2025 | USD 423.0 million |
| Market Size 2032 | USD 701.78 million |
| Absolute Growth 2025–2032 | USD 278.78 million |
| CAGR 2026–2032 | 7.5% |
| Peak Annual Growth | 9.5% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading IC Type, 2025 | Microcontrollers (MCUs) (48% share) |
| Leading Application Segment, 2025 | Motor Drives (38% share) |
| Leading Packaging Type, 2025 | SMD/Through-Hole (47% share) |
| Leading End User, 2025 | Automation Hardware OEMs (47% share) |
| Fastest-Growing IC Type | ASICs for Automation (8.6% CAGR) |
| Fastest-Growing Application Segment | Process Control (8.7% CAGR) |
| Fastest-Growing Packaging Type | QFP/BGA (10.0% CAGR) |
| Fastest-Growing End User | Robotics Integrators (8.8% CAGR) |
| Growing Sector | Process Control |
| Key End Users | Motor Drives, Process Control, Signal Processing, Custom Tasks |
China Industrial Automation IC Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
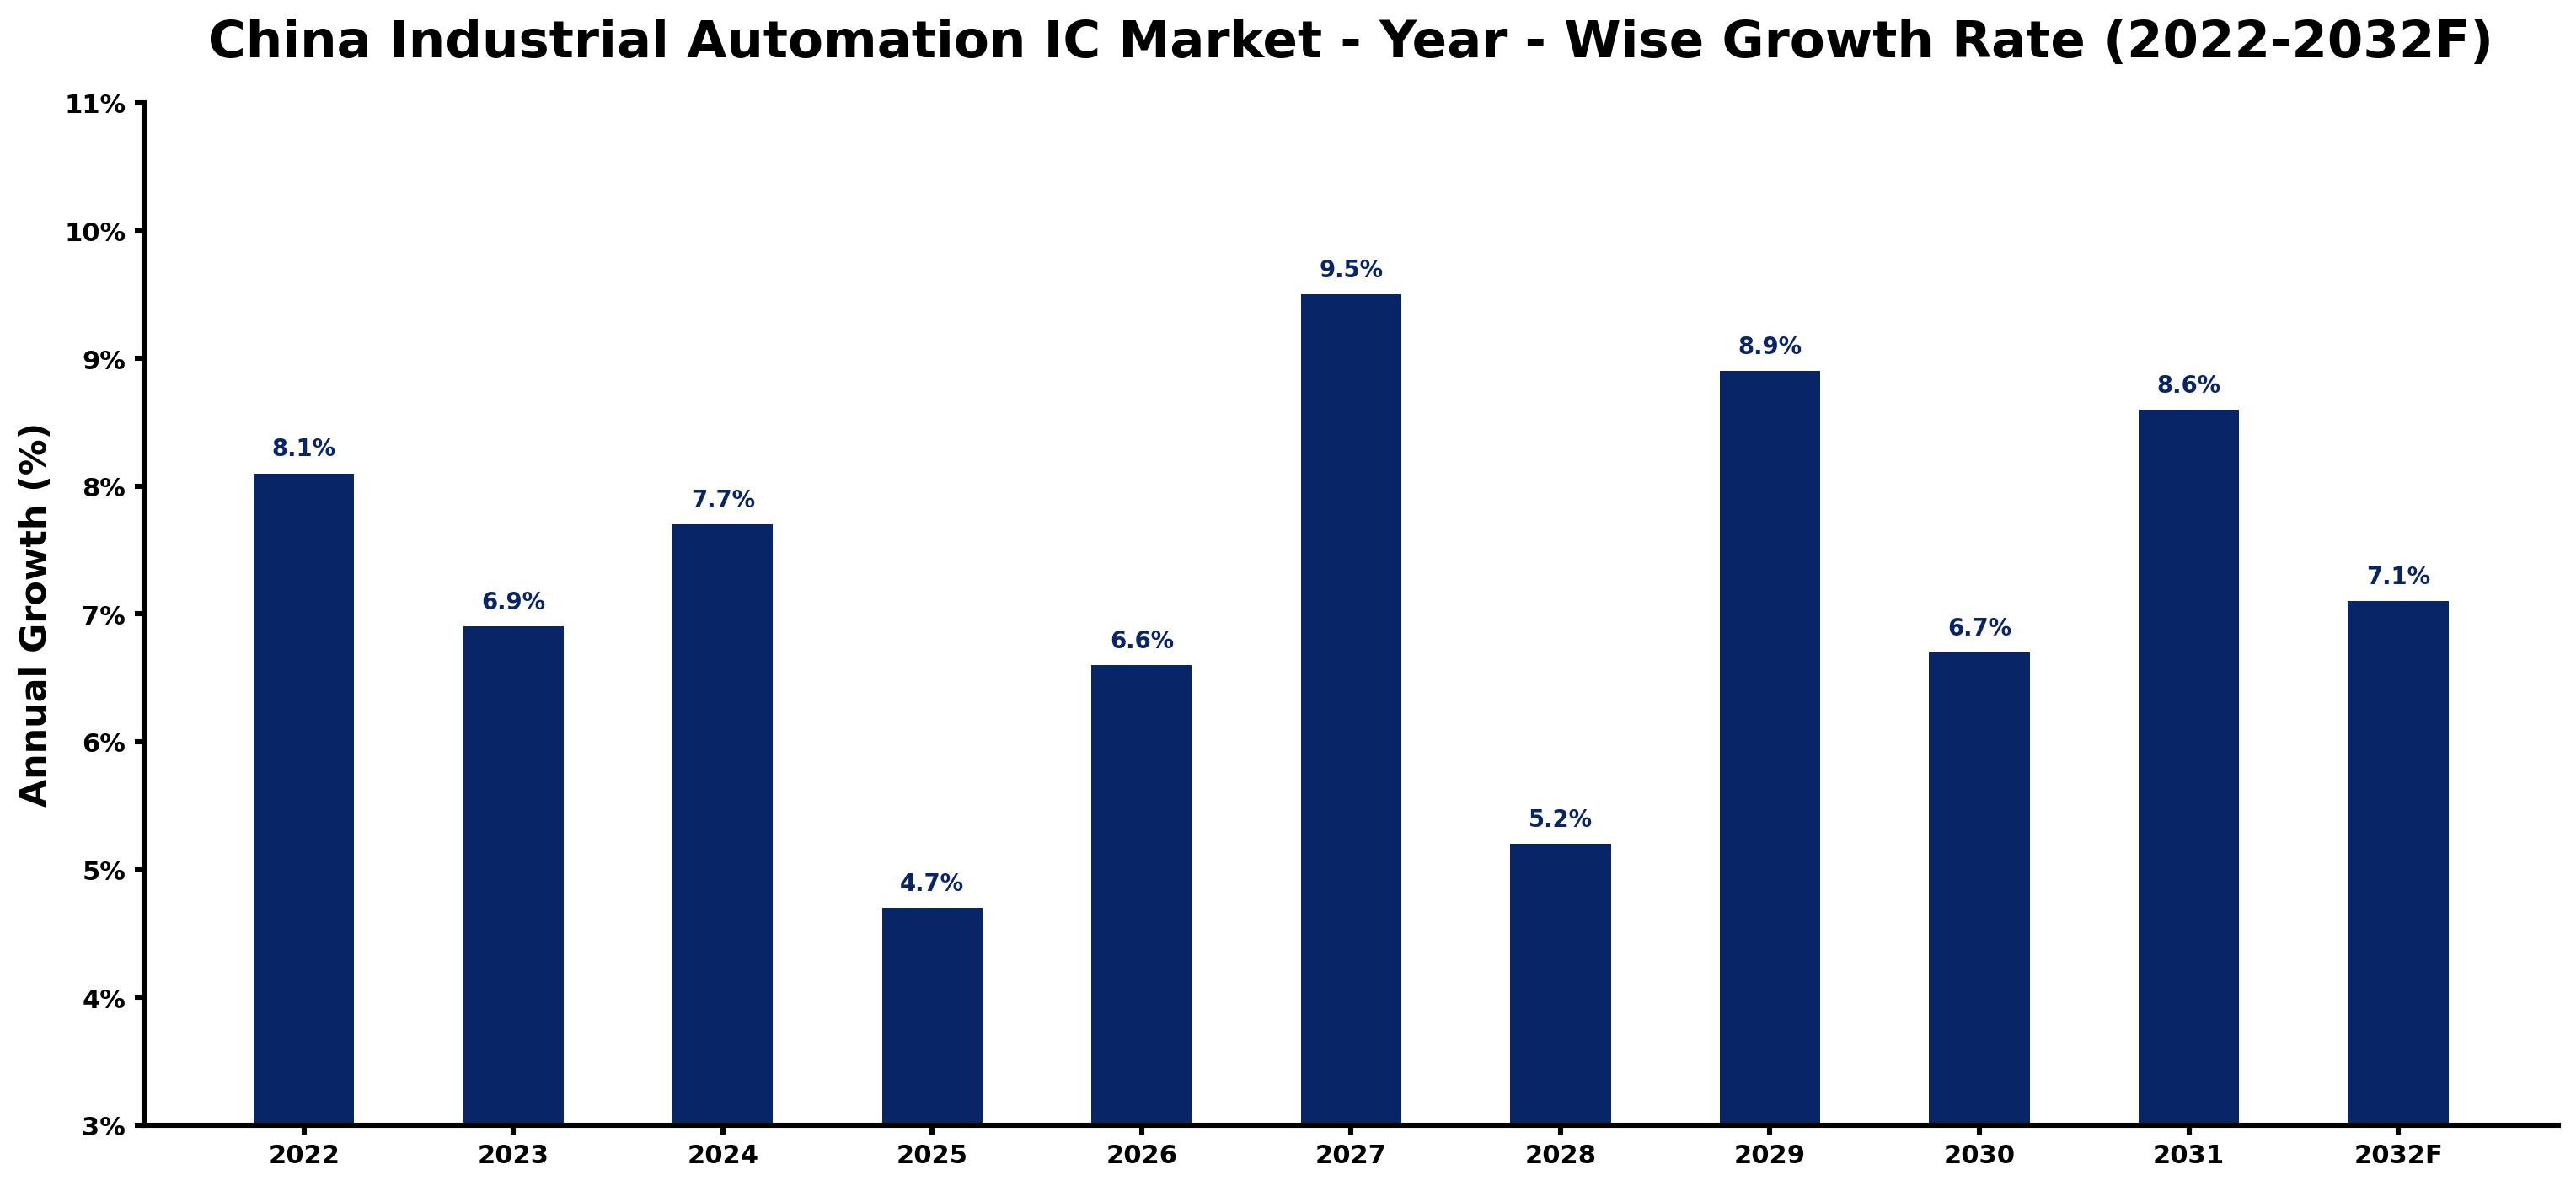
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 8.1 | The market showed strong growth due to increased automation investments across various sectors. |
| 2023 | 6.9 | Growth slowed as manufacturers adjusted to supply chain challenges and fluctuating demand. |
| 2024 | 7.7 | An uptick in demand for automation solutions led to faster growth in the market. |
| 2025 | 4.7 | Growth decelerated as some sectors faced saturation and reduced investment levels. |
| 2026 | 6.6 | An increase in energy efficiency regulations is expected to spur demand for Power Management ICs. |
| 2027 | 9.5 | The market is projected to peak as automation technology adoption surges across industries. |
| 2028 | 5.2 | Growth is expected to slow as the market begins to stabilise after the peak in investments. |
| 2029 | 8.9 | A resurgence in demand from Robotics Integrators will lead to faster growth rates. |
| 2030 | 6.7 | Growth is projected to decelerate as the market adjusts to new regulatory standards and competition. |
| 2031 | 8.6 | Increased investments in automation technology will drive a rebound in growth rates. |
| 2032 | 7.1 | The market is expected to stabilise as demand levels off after rapid expansion. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Industrial Automation IC Market Synopsis
Industrial Automation IC in China encompasses semiconductor devices used to control and manage industrial processes. These ICs are essential for applications such as motor control and process automation, manufactured through advanced techniques. The China Industrial Automation IC Market is expanding due to rising domestic demand and ongoing technological advancements. The installed base of industrial robots reached approximately 1 million units in 2022, highlighting the sector's growth. Initiatives like 'Made in China 2025' further stimulate demand for automation solutions.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased investment in automation technologies is driving demand for Power Management ICs. | Driver | High | Power Management ICs |
| The widespread use of Microcontrollers in over 70% of applications fuels demand for MCUs. | Driver | High | Microcontrollers (MCUs) |
| The growing need for energy-efficient solutions presents opportunities for Power Management ICs. | Opportunity | High | Power Management ICs |
| The rise of smart manufacturing creates demand for advanced automation solutions. | Opportunity | High | Automation Hardware OEMs |
| Supply chain disruptions can affect the availability of critical components. | Restraint | Medium | Microcontrollers (MCUs) |
| High competition among manufacturers can lead to price pressures in the market. | Restraint | Medium | Motor Drives |
| This market still has to solve a few problems, including supply chain issues. | Challenge | High | Microcontrollers (MCUs) |
| Technological advancements require continuous investment, which can strain smaller firms. | Challenge | High | Automation Hardware OEMs |
Evaluation of Drivers in China Industrial Automation IC Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising investments in automation technologies are increasing demand for Power Management ICs. | Power Management ICs | The demand for energy-efficient solutions is driven by regulations aimed at reducing energy consumption. |
| The widespread adoption of Microcontrollers in automation applications is boosting demand. | Microcontrollers (MCUs) | With over 70% usage in automation, MCUs are essential for controlling various tasks. |
| The need for efficient process control is driving demand for ASICs tailored for automation. | ASICs for Automation | These ICs are specifically designed for automation tasks, improving operational efficiency. |
| The growth of Robotics Integrators is increasing demand for Motor Drives. | Motor Drives | Motor Drives are integral for controlling motor functions in robotic systems. |
| The push for smart manufacturing is driving demand for Process Control ICs. | Process Control | These ICs are vital for maintaining operational efficiency in automated processes. |
The Industrial Automation IC market in China is growing as investments in automation technologies rise alongside increasing end-use demand. In 2022, the installed base of industrial robots reached about 1 million units, elevating the need for automation solutions. The growing emphasis on Robotics Integrators also fuels the demand for Motor Drives, which are essential for robotic systems. The need for Process Control ICs is increasing as manufacturers aim to improve operational efficiency in automated processes.
Evaluation of Restraints in China Industrial Automation IC Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Supply chain disruptions affect production timelines. | Microcontrollers (MCUs) | Manufacturers face delays of up to six months due to reliance on limited suppliers. |
| Rising costs impact budgets for automation manufacturers. | Power Management ICs | In 2023, the average price of industrial automation ICs increased by 15%. |
| Regulatory compliance adds operational costs for producers. | ASICs for Automation | Adhering to ISO 9001 standards can increase costs by up to 20%. |
| Competition from international markets pressures local suppliers. | Motor Drives | Local manufacturers must lower prices, risking quality to remain competitive. |
| Limited innovation in certain segments hampers growth. | Process Control | Some manufacturers struggle to keep pace with technological advancements. |
China Industrial Automation IC Market Challenges
The China Industrial Automation IC market still has to solve a few problems, starting with supply chain disruptions. Many manufacturers rely on a small number of suppliers for critical components, leading to production delays of up to six months for producers. Rising costs present another challenge; in 2023, the average price of industrial automation ICs increased by 15%, impacting budgets for over 1,000 automation equipment manufacturers. Regulatory compliance with ISO 9001 standards adds complexity, raising operational costs by as much as 20% for clinics and plants. Competition from international markets pressures local suppliers to lower prices, which can compromise quality for buyers.
Trends in the China Industrial Automation IC Market
Buyers and suppliers in the China Industrial Automation IC Market are adjusting to the following trends.
- Shift from Traditional to Smart Manufacturing: Automation Hardware OEMs are increasingly embracing smart manufacturing practices, with the 'Smart Manufacturing' program introduced in 2023. This transition is expected to boost productivity and efficiency across the manufacturing sector.
- Transition from Standard to Custom Automation Solutions: In 2022, the demand for customised automation solutions surged, particularly in the Guangdong province, where local manufacturers are concentrating on bespoke applications. This trend is reshaping market dynamics.
- Emergence of Energy-Efficient ICs: The drive for energy efficiency has led to the rise of Power Management ICs, with regulations propelling their adoption. The market for these ICs is anticipated to expand as energy efficiency becomes a priority.
- Prioritisation of Robotics Integration: Robotics Integrators are increasingly focusing on advanced automation solutions, with a projected growth rate of 8.8% for this segment. This trend highlights the growing significance of automation across various industries.
Investment Opportunities in the China Industrial Automation IC Market
Investors looking at the China Industrial Automation IC Market should consider the following areas.
- Supply of Energy-Efficient ICs: The demand for energy-efficient ICs is on the rise, with the market expected to grow. Automation Hardware OEMs are seeking solutions to meet regulatory standards, creating opportunities for suppliers to enter through partnerships.
- Custom Automation Solutions: With an increasing need for tailored solutions, suppliers can invest in custom automation ICs. The Guangdong province is a key area for this, where local manufacturers are focusing on bespoke applications.
- Investment in Robotics Integration: The Robotics Integrators segment is expanding, with a projected growth rate of 8.8%. Suppliers can tap into this market by collaborating with local integrators to provide advanced automation solutions.
- Expansion of Process Control Technologies: The demand for efficient process control is rising, creating opportunities for suppliers of Process Control ICs. Engaging with Automation Hardware OEMs can facilitate entry into this growing market.
Government Initiatives in the China Industrial Automation IC Market
The 'Made in China 2025' initiative, updated in 2021, highlights the importance of automation in manufacturing sectors. This policy aims to enhance the production capabilities of local manufacturers by promoting advanced automation technologies. The initiative encourages investment in research and development, ensuring that domestic producers can compete globally. Additionally, the '14th Five-Year Plan for Economic and Social Development' launched in 2021 focuses on improving automation technologies across industries, providing a framework for sustainable growth in the sector.
In 2023, the 'Smart Manufacturing' program was launched by the Ministry of Industry and Information Technology to assist manufacturers in adopting smart technologies. This initiative aims to enhance operational efficiency and provides funding for projects that integrate advanced automation solutions, promoting innovation in the industry. The 'Digital Economy Development Plan' initiated in 2022 further supports the growth of smart manufacturing and automation.
Future Insight of the China Industrial Automation IC Market
By 2032, buyers and suppliers in the China Industrial Automation IC market can expect transformative changes driven by key initiatives. The 'Smart Manufacturing' program launched in 2023 will accelerate the adoption of advanced automation technologies, streamlining processes across sectors. The installed base of industrial robots is expected to reach around 2 million units, significantly improving operational efficiency for manufacturers. Continued support from the Ministry of Industry and Information Technology will encourage innovation in automation, enabling local producers to compete effectively. The increasing focus on energy efficiency will also create new opportunities for innovative solutions.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By IC Type – Microcontrollers (MCUs) Dominated, ASICs for Automation Expected to Grow Fastest
According to Sachin Kumar Rai, Senior Research Analyst at 6Wresearch, in 2025, Microcontrollers (MCUs) led the ic type split with a 48% share. Microcontrollers dominate the market share as they are essential for controlling various automation tasks across numerous applications. Their importance is highlighted by the fact that they are used in over 70% of automation applications in China. ASICs for Automation is set to record the highest CAGR in this split, 8.6% over 2026–2032. ASICs for Automation are experiencing rapid growth due to their design for specific automation needs, aligning with the increasing complexity of industrial processes. This tailored approach is attracting industries seeking efficient solutions, thus driving demand. Suppliers should focus on enhancing their microcontroller offerings while also tapping into the growing market for ASICs to cater to specific automation requirements.
By Application Segment – Motor Drives Dominated, Process Control Expected to Grow Fastest
With a 38% revenue share in 2025, Motor Drives was the largest application segment category. Motor Drives dominate the market due to their integral role in controlling motor functions across various industrial applications. Their importance in ensuring operational efficiency and reliability makes them a preferred choice among manufacturers. The quickest growth will come from Process Control, forecast to expand at a CAGR of 8.7% between 2026 and 2032. Process Control is the fastest-growing segment, driven by the pressing need for operational efficiency in automated environments. As industries increasingly focus on optimising their processes, the demand for advanced control solutions is surging. Buyers should prioritise investments in motor drives while also considering emerging technologies in process control for improved operational performance.
By Packaging Type – SMD/Through-Hole Dominated, QFP/BGA Expected to Grow Fastest
SMD/Through-Hole held a 47% share of the China Industrial Automation IC Market by packaging type in 2025. SMD/Through-Hole packaging leads the market share because of its widespread use in various industrial applications, ensuring compatibility with a broad range of automation equipment. This established packaging type is preferred for its reliability and ease of integration into existing systems. QFP/BGA is projected to grow fastest, at a CAGR of 10.0% during 2026–2032. QFP/BGA packaging is rapidly gaining traction as it is favoured for high-density applications, which are increasingly common in modern automation systems. The shift towards compact and efficient designs in automation technology is driving this segment's growth. Suppliers must adapt to the rising demand for QFP/BGA packaging while maintaining robust offerings in SMD/Through-Hole solutions.
By End User – Automation Hardware OEMs Dominated, Robotics Integrators Expected to Grow Fastest
The largest end user category in 2025 was Automation Hardware OEMs, with a 47% share of total revenue. Automation Hardware OEMs hold the largest market share as they are the primary users of industrial automation ICs, integrating these components into their products. Their significant role in the automation ecosystem underscores their influence on driving demand for ICs. Over 2026–2032, Robotics Integrators are expected to post the fastest growth, at a CAGR of 8.8%. Robotics Integrators are the fastest-growing end-user segment, playing a crucial role in robotic control systems that are becoming increasingly prevalent across various industries. The rapid expansion of robotics applications is propelling their growth in the market. Suppliers should strengthen partnerships with Automation Hardware OEMs while also targeting Robotics Integrators to leverage emerging opportunities.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Industrial Automation IC Market Outlook
- Market Size of China Industrial Automation IC Market, 2025
- Forecast of China Industrial Automation IC Market, 2032
- Historical Data and Forecast of China Industrial Automation IC Revenues & Volume for the Period 2022 - 2032F
- China Industrial Automation IC Market Trend Evolution
- China Industrial Automation IC Market Drivers and Challenges
- China Industrial Automation IC Price Trends
- China Industrial Automation IC Porter's Five Forces
- China Industrial Automation IC Industry Life Cycle
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By IC Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Power Management ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Microcontrollers (MCUs) for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Logic ICs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By ASICs for Automation for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Application Segment for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Motor Drives for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Process Control for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Signal Processing for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Custom Tasks for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Packaging Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By SMD/Through-Hole for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By QFP/BGA for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By SOIC/DIP for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Die-Level/SIP for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Automation Hardware OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Industrial PC Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By PLC Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Industrial Automation IC Market Revenues & Volume By Robotics Integrators for the Period 2022 - 2032F
- China Industrial Automation IC Import Export Trade Statistics
- Market Opportunity Assessment By IC Type
- Market Opportunity Assessment By Application Segment
- Market Opportunity Assessment By Packaging Type
- Market Opportunity Assessment By End User
- China Industrial Automation IC Top Companies Market Share
- China Industrial Automation IC Competitive Benchmarking By Technical and Operational Parameters
- China Industrial Automation IC Company Profiles
- China Industrial Automation IC Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By IC Type
- Power Management ICs
- Microcontrollers (MCUs)
- Logic ICs
- ASICs for Automation
By Application Segment
- Motor Drives
- Process Control
- Signal Processing
- Custom Tasks
By Packaging Type
- SMD/Through-Hole
- QFP/BGA
- SOIC/DIP
- Die-Level/SIP
By End User
- Automation Hardware OEMs
- Industrial PC Makers
- PLC Manufacturers
- Robotics Integrators































