China Structural Adhesives for Vehicles Market Size & Growth Rate
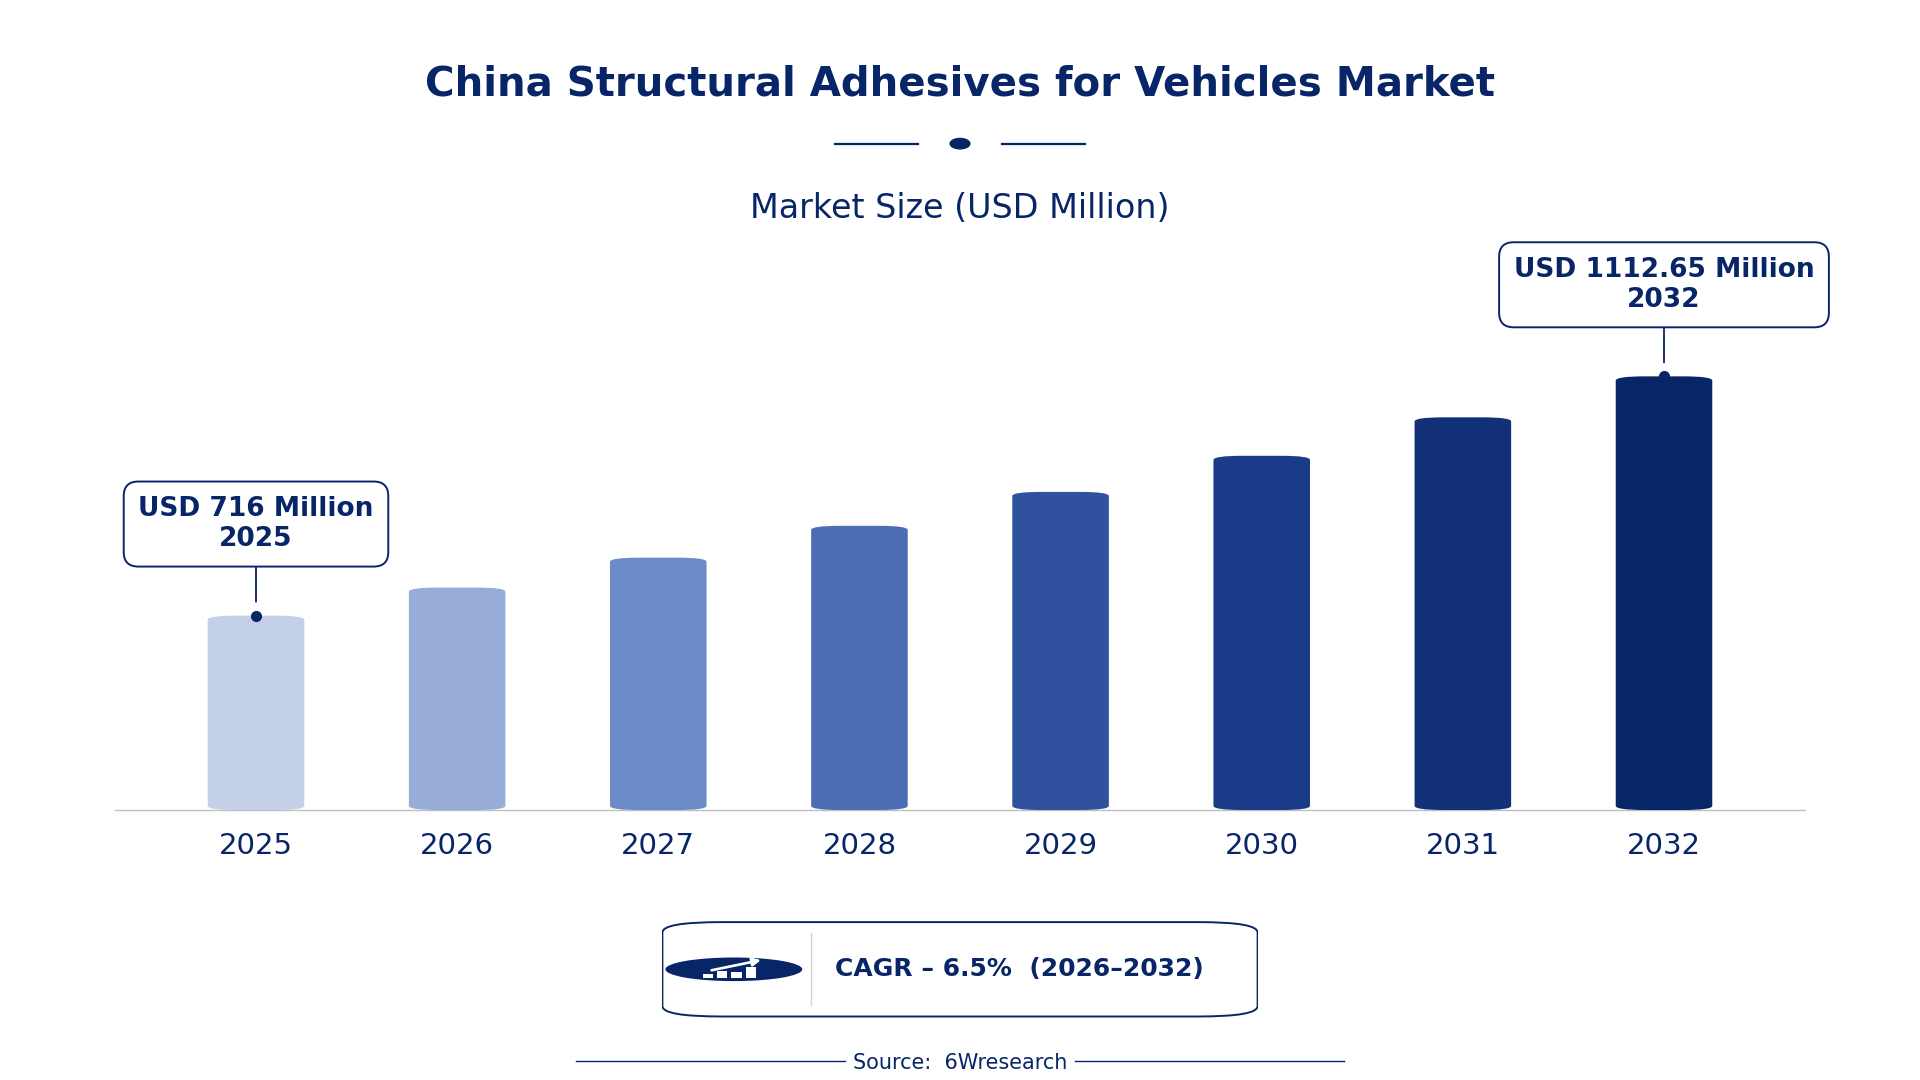
According to 6Wresearch internal database and industry insights, the China Structural Adhesives for Vehicles Market was valued at USD 716.0 million in 2025 and is projected to reach USD 1,112.65 million by 2032, growing at a CAGR of approximately 6.5% during 2026–2032.
China Structural Adhesives for Vehicles Market Highlights
| Report Metric | Details |
| Report Name | China Structural Adhesives for Vehicles Market |
| Market Size 2025 | USD 716.0 million |
| Market Size 2032 | USD 1,112.65 million |
| Absolute Growth 2025–2032 | USD 396.65 million |
| CAGR 2026–2032 | 6.5% |
| Peak Annual Growth | 9.3% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Adhesive Type, 2025 | Epoxy Adhesives (42% share) |
| Leading Chemistry Base, 2025 | Two-Part Epoxy (44% share) |
| Leading Application Area, 2025 | Chassis Bonding (44% share) |
| Leading End User, 2025 | Vehicle OEMs (36% share) |
| Fastest-Growing Adhesive Type | Polyurethane Adhesives (7.6% CAGR) |
| Fastest-Growing Chemistry Base | One-Part Polyurethane (7.9% CAGR) |
| Fastest-Growing Application Area | Crash Structures (8.1% CAGR) |
| Fastest-Growing End User | Electric Vehicle Makers (8.0% CAGR) |
| Growing Sector | Crash Structures |
| Key End Users | Chassis Bonding, Crash Structures, Roof Panels, Doors & Interiors |
China Structural Adhesives for Vehicles Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
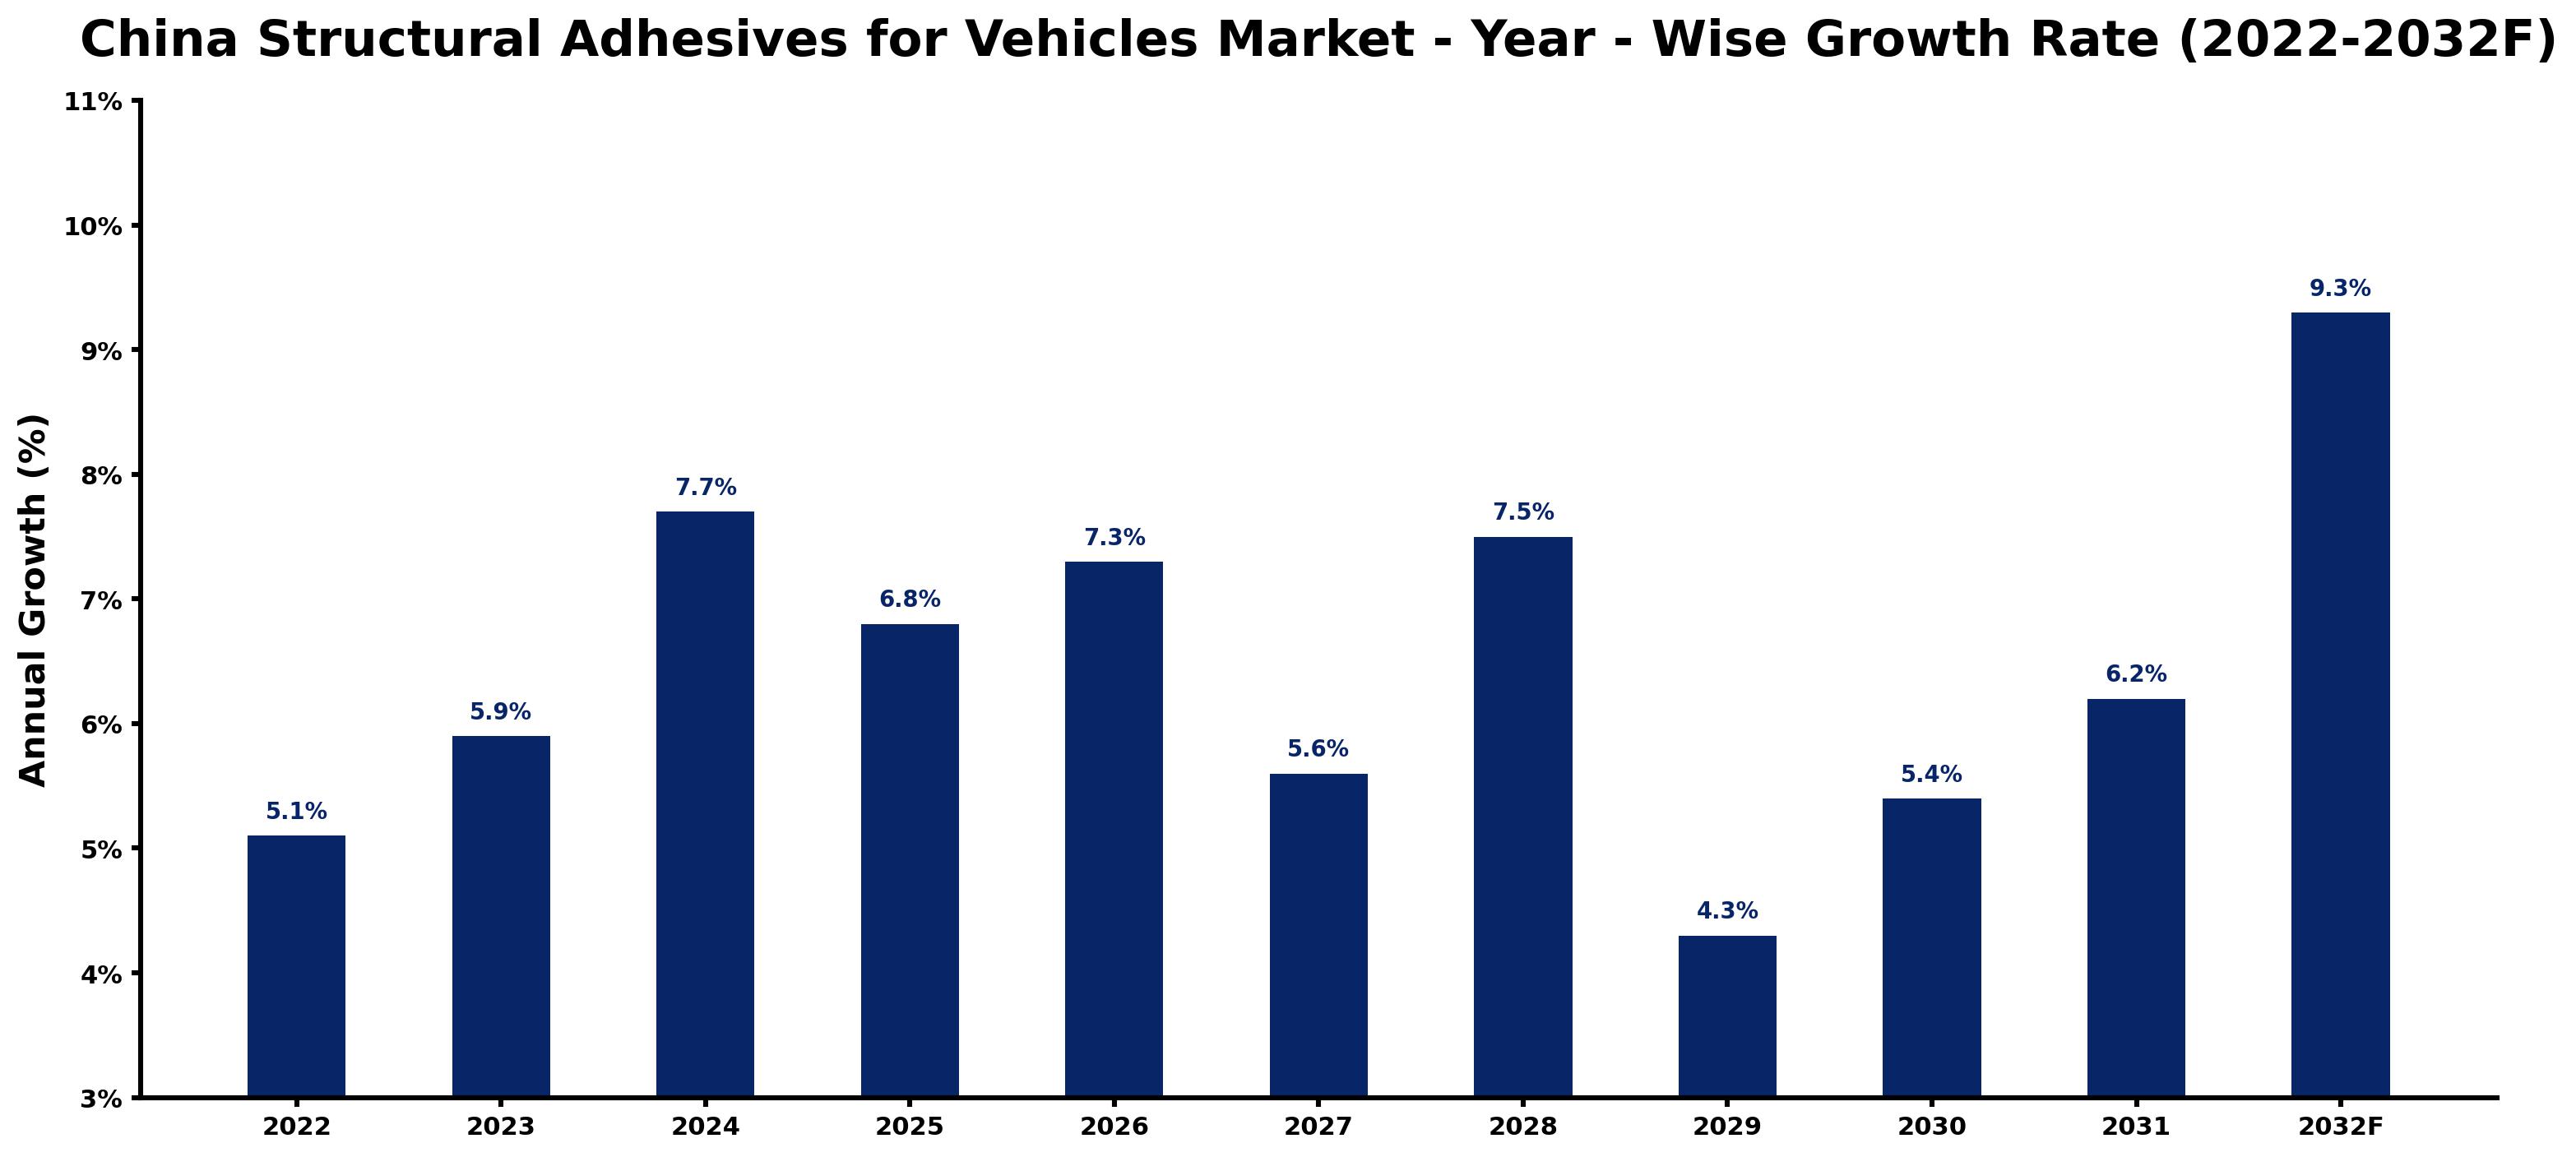
The table below sets out the estimated growth rate for each year and the main factor behind it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.1 | The automotive sector showed steady demand for structural adhesives, reflecting ongoing production levels in vehicle manufacturing. |
| 2023 | 5.9 | Demand increased due to higher vehicle production and the growing adoption of electric vehicles in the market. |
| 2024 | 7.7 | The market expanded as manufacturers adopted advanced bonding technologies that improved safety and performance standards. |
| 2025 | 6.8 | Growth slowed slightly as manufacturers adjusted to evolving material requirements and industry standards. |
| 2026 | 7.3 | Demand is expected to rise with the ongoing emphasis on lightweight vehicle designs for enhanced fuel efficiency. |
| 2027 | 5.6 | A slowdown is projected as manufacturers face challenges in sourcing sustainable materials for production. |
| 2028 | 7.5 | Growth is anticipated as the focus on electric vehicles drives demand for effective bonding solutions. |
| 2029 | 4.3 | The market is expected to experience a slowdown as manufacturers adapt to changing consumer preferences and needs. |
| 2030 | 5.4 | Demand will increase as vehicle OEMs seek to enhance structural integrity through advanced adhesive applications. |
| 2031 | 6.2 | Growth is projected as the automotive sector embraces sustainable practices and advanced bonding materials. |
| 2032 | 9.3 | The market is expected to peak as electric vehicle production surges, driving unprecedented demand for structural adhesives. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Adhesives for Vehicles Market Synopsis
The China Structural Adhesives for Vehicles Market encompasses specialized bonding agents used in automotive manufacturing. These adhesives improve structural integrity while reducing vehicle weight, primarily applied in chassis and body panel bonding. The market is growing due to increased vehicle production, with 26 million units produced in 2022, and the rise of electric vehicles, which require advanced materials for lightweight construction. The Guangdong province serves as a key hub for automotive manufacturing, further fueling demand for these bonding agents.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increased vehicle production drives demand for adhesives to bond critical components. | Driver | High | Chassis Bonding |
| The shift towards electric vehicles necessitates lightweight materials, boosting adhesive use. | Driver | High | Electric Vehicle Makers |
| The growing number of electric vehicle manufacturers creates opportunities for adhesive suppliers. | Opportunity | High | Electric Vehicle Makers |
| The push for eco-friendly adhesives opens new markets for sustainable products. | Opportunity | Medium | Polyurethane Adhesives |
| Regulatory standards for adhesive performance can limit product options for manufacturers. | Restraint | High | Epoxy Adhesives |
| Competition from alternative bonding technologies may hinder market growth. | Restraint | Medium | Acrylic Adhesives |
| The Structural Adhesives for Vehicles market in China faces challenges in sourcing eco-friendly materials. | Challenge | High | Polyurethane Adhesives |
| Technological advancements in bonding methods may outpace current adhesive offerings. | Challenge | Medium | Two-Part Epoxy |
Evaluation of Drivers in China Structural Adhesives for Vehicles Market (2026–2032)
Key forces behind demand, with the segment each one moves most, are listed below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased vehicle production necessitates high-strength bonding solutions for safety and performance. | Epoxy Adhesives | China produced 26 million vehicles in 2022, leading to higher adhesive demand. |
| The rise of electric vehicles requires lightweight materials, increasing the need for structural adhesives. | Polyurethane Adhesives | Electric vehicle sales reached 6.9 million units in 2022, driving adhesive usage. |
| The Guangdong province is a major hub for automotive manufacturing, boosting local adhesive demand. | Chassis Bonding | The region's automotive production facilities support adhesive consumption, with significant output. |
| The 'New Energy Vehicle Industry Development Plan' promotes advanced materials, including adhesives. | Electric Vehicle Makers | This initiative drives innovation in bonding technologies, enhancing production capabilities. |
| The 'Made in China 2025' initiative encourages the use of advanced materials in automotive production. | Two-Part Epoxy | This policy supports the adoption of high-performance adhesives in the industry. |
Growth in the Structural Adhesives for Vehicles market in China comes from increased investment in production capabilities, the rise in electric vehicle manufacturing, and regional manufacturing hubs. The production of 26 million vehicles in 2022 boosted demand for adhesives, particularly in chassis bonding applications. Electric vehicle sales reached 6.9 million units, driving the need for lightweight materials in vehicle assembly. The Guangdong province, as a major manufacturing hub, supports local adhesive consumption, while the 'New Energy Vehicle Industry Development Plan' promotes advanced bonding technologies, creating new opportunities for suppliers.
Evaluation of Restraints in China Structural Adhesives for Vehicles Market
The table below lists the restraints and the evidence behind each.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory standards for adhesive performance can limit product options for manufacturers. | Epoxy Adhesives | The National Standard GB/T 2793-2017 regulates adhesive testing, impacting product availability. |
| Competition from alternative bonding technologies may hinder market growth. | Acrylic Adhesives | Innovations in welding and mechanical fastening can reduce reliance on adhesives. |
| The high cost of eco-friendly materials may deter manufacturers from adopting them. | Polyurethane Adhesives | Sourcing sustainable materials can increase production costs for vehicle OEMs. |
| Supply chain disruptions can delay adhesive availability for manufacturers. | Two-Part Epoxy | Recent global supply chain issues have affected material sourcing and production timelines. |
| Limited awareness of advanced adhesive technologies among smaller manufacturers may restrict market growth. | Crash Structures | Smaller vehicle OEMs may not invest in new bonding technologies due to cost concerns. |
China Structural Adhesives for Vehicles Market Challenges
The China Structural Adhesives for Vehicles Market encounters regulatory challenges that elevate compliance costs for producers, with the National Standard GB/T 2793-2017 imposing stringent testing requirements that can increase expenses by up to 15%. This regulation delays product launches for manufacturers, hindering their ability to meet the demand generated by the production of 26 million vehicles in 2022. Supply chain disruptions are frequent, as dependence on specific raw materials can lead to shortages, affecting production timelines for automotive manufacturers. Skills shortages in advanced adhesive technologies restrict innovation, causing delays in developing new formulations that meet market needs, which can impede the overall growth of the sector.
Trends in the China Structural Adhesives for Vehicles Market
Buyers and suppliers in the China Structural Adhesives for Vehicles Market are adjusting to the following trends.
- Shift towards Eco-Friendly Adhesives: In 2022, the Ministry of Ecology and Environment introduced the 'Green Manufacturing System', encouraging the use of eco-friendly adhesives. This shift is important as manufacturers seek to comply with sustainability standards, impacting purchasing decisions.
- Growth in Electric Vehicle Adhesive Applications: The rise of electric vehicles has led to increased demand for lightweight structural adhesives. In 2023, over 1,000 electric vehicle manufacturers in China are driving this trend, pushing for effective bonding solutions.
- Focus on Advanced Bonding Technologies: The '14th Five-Year Plan for the Automotive Industry' emphasizes innovation in automotive materials. This focus on advanced bonding technologies is reshaping adhesive applications in vehicle manufacturing, impacting supplier strategies.
- Increased Adoption of Two-Part Epoxy: Two-Part Epoxy is gaining traction due to its high-strength bonding capabilities. With a projected market share of 44% by 2025, it is becoming the preferred choice for critical load-bearing joints.
Investment Opportunities in the China Structural Adhesives for Vehicles Market
Investors looking at the China Structural Adhesives for Vehicles Market should consider the following areas.
- Timing for Sustainable Adhesives: The push for eco-friendly materials creates a timely opportunity for adhesive suppliers. With the automotive adhesives market projected to reach 2.5 billion USD by 2025, manufacturers are seeking sustainable options.
- Supply of Lightweight Adhesives: The demand for lightweight adhesives is rising as vehicle OEMs focus on reducing weight. Suppliers can target electric vehicle manufacturers, who are increasingly prioritising these materials.
- Investing in Advanced Bonding Technologies: There is a growing opportunity to invest in advanced bonding technologies. Vehicle OEMs are seeking effective solutions that improve structural integrity and performance in vehicles.
- Partnerships for Adhesive Development: Collaborating with local manufacturers can facilitate entry into the Chinese market. Joint ventures with automotive producers in Guangdong can support adhesive development and distribution.
Government Initiatives in the China Structural Adhesives for Vehicles Market
The '14th Five-Year Plan for the Automotive Industry' initiated by the Ministry of Industry and Information Technology in 2021 emphasises innovation and sustainability in automotive materials. This plan encourages manufacturers to adopt advanced adhesives that meet new performance standards. Additionally, the 'New Energy Vehicle Industry Development Plan' approved by the National Development and Reform Commission in 2020 promotes the use of eco-friendly materials, including adhesives, in vehicle production. These initiatives aim to enhance the competitiveness of the automotive sector while ensuring compliance with environmental regulations.
The Ministry of Industry and Information Technology oversees the implementation of the 'New Energy Vehicle Industry Development Plan', which funds research into advanced materials. The State Administration for Market Regulation enforces the updated 'Product Quality Law', ensuring that manufacturers adhere to adhesive performance standards. These agencies play a key role in approving new adhesive products and ensuring they meet the necessary regulatory requirements, thus supporting the market's growth.
Future Insight of the China Structural Adhesives for Vehicles Market
The China Structural Adhesives for Vehicles Market is expected to evolve significantly by 2032, driven by the rising adoption of electric vehicles and advancements in adhesive technologies. The 'New Energy Vehicle Industry Development Plan' will likely boost demand for lightweight materials, increasing the application of structural adhesives in vehicle manufacturing. By 2025, the automotive adhesives market is projected to reach 2.5 billion USD, reflecting strong growth potential. The pursuit of ISO 9001 certification among manufacturers will improve product quality and reliability, benefiting both suppliers and buyers.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Adhesive Type – Epoxy Adhesives Dominated, Polyurethane Adhesives Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Epoxy Adhesives took a 42% share of adhesive type in 2025, more than any other category. Epoxy adhesives dominate the market due to their high strength, making them ideal for bonding critical vehicle components. Their widespread use in automotive manufacturing, particularly in regions like Guangdong, solidifies their leading market share. Over 2026–2032, Polyurethane Adhesives are expected to post the fastest growth, at a CAGR of 7.6%. Polyurethane adhesives are experiencing rapid growth thanks to their flexibility and suitability for various automotive applications. This surge is largely driven by the increasing demand for lightweight vehicles, especially within the electric segment. Suppliers should focus on advancing polyurethane adhesive technologies to meet the growing requirements of the automotive sector.
By Chemistry Base – Two-Part Epoxy Dominated, One-Part Polyurethane Expected to Grow Fastest
With a 44% revenue share in 2025, Two-Part Epoxy was the largest chemistry base category. Two-part epoxy adhesives hold the largest market share due to their strong bonding capabilities, which are vital for load-bearing joints in vehicles. Their proven reliability in high-stress applications makes them a preferred choice among automotive manufacturers. One-Part Polyurethane is set to record the highest CAGR in this split, 7.9% over 2026–2032. One-part polyurethane adhesives are rapidly gaining traction, primarily due to their ease of application and durability, which appeals to manufacturers seeking efficiency. The industry's shift towards lightweight materials further accelerates their adoption. Manufacturers should invest in one-part polyurethane technologies to align with the market's focus on efficiency and lightweight solutions.
By Application Area – Chassis Bonding Dominated, Crash Structures Expected to Grow Fastest
In 2025, Chassis Bonding led the application area split with a 44% share. Chassis bonding is the leading application area, essential for maintaining vehicle structural integrity. The critical role of chassis in overall vehicle safety ensures a consistent demand for adhesives in this segment. Crash Structures are projected to grow fastest, at a CAGR of 8.1% during 2026–2032. Crash structures are witnessing the fastest growth, driven by stricter safety regulations and the need for enhanced impact resistance in vehicles. The rise in electric vehicle production, which prioritises safety, further propels this segment's expansion. Suppliers should develop adhesives specifically designed for crash structures to capitalise on the increasing focus on vehicle safety.
By End User – Vehicle OEMs Dominated, Electric Vehicle Makers Expected to Grow Fastest
Vehicle OEMs accounted for a 36% market share by end user in 2025. Vehicle OEMs represent the largest end-user group, being the primary consumers of structural adhesives during the manufacturing process. Their crucial role in vehicle production guarantees a substantial market share for this segment. The quickest growth will come from Electric Vehicle Makers, forecast to expand at a CAGR of 8.0% between 2026 and 2032. Electric vehicle makers are the fastest-growing end-user segment, propelled by the demand for lightweight construction that enhances efficiency and range. The significant increase in electric vehicle production in China is a key factor in this rapid growth. Suppliers should tailor their products to meet the specific needs of electric vehicle manufacturers to seize this expanding market opportunity.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Adhesives for Vehicles Market Outlook
- Market Size of China Structural Adhesives for Vehicles Market, 2025
- Forecast of China Structural Adhesives for Vehicles Market, 2032
- Historical Data and Forecast of China Structural Adhesives for Vehicles Revenues & Volume for the Period 2022 - 2032F
- China Structural Adhesives for Vehicles Market Trend Evolution
- China Structural Adhesives for Vehicles Market Drivers and Challenges
- China Structural Adhesives for Vehicles Price Trends
- China Structural Adhesives for Vehicles Porter's Five Forces
- China Structural Adhesives for Vehicles Industry Life Cycle
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Adhesive Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Epoxy Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Polyurethane Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Acrylic Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Rubber-Based Adhesives for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Chemistry Base for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Two-Part Epoxy for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By One-Part Polyurethane for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Methacrylate Base for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Synthetic Rubber for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Chassis Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Crash Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Roof Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Doors & Interiors for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Body Shops for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Electric Vehicle Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Adhesives for Vehicles Market Revenues & Volume By Auto Parts Manufacturers for the Period 2022 - 2032F
- China Structural Adhesives for Vehicles Import Export Trade Statistics
- Market Opportunity Assessment By Adhesive Type
- Market Opportunity Assessment By Chemistry Base
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China Structural Adhesives for Vehicles Top Companies Market Share
- China Structural Adhesives for Vehicles Competitive Benchmarking By Technical and Operational Parameters
- China Structural Adhesives for Vehicles Company Profiles
- China Structural Adhesives for Vehicles Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Adhesive Type
- Epoxy Adhesives
- Polyurethane Adhesives
- Acrylic Adhesives
- Rubber-Based Adhesives
By Chemistry Base
- Two-Part Epoxy
- One-Part Polyurethane
- Methacrylate Base
- Synthetic Rubber
By Application Area
- Chassis Bonding
- Crash Structures
- Roof Panels
- Doors & Interiors
By End User
- Vehicle OEMs
- Body Shops
- Electric Vehicle Makers
- Auto Parts Manufacturers































