China Structural Bonding Materials Market Size & Growth Rate
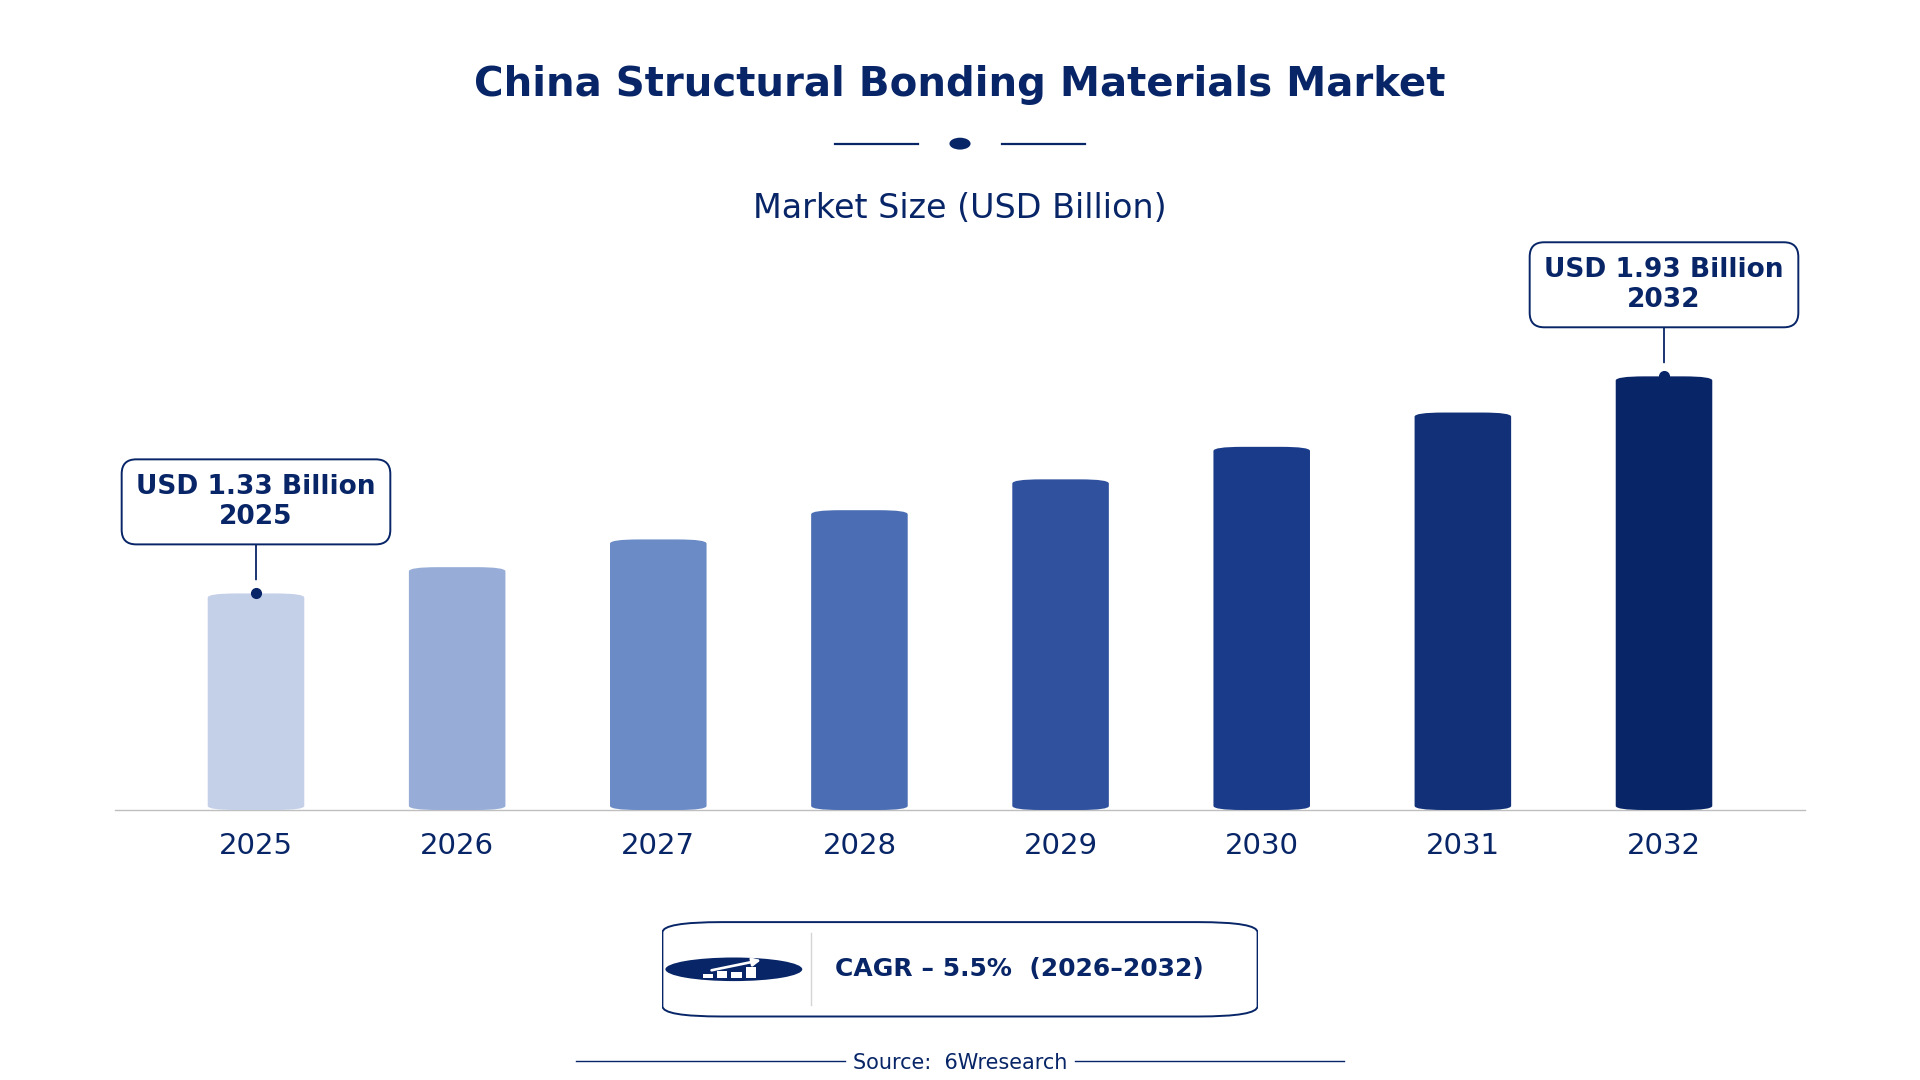
According to 6Wresearch internal database and industry insights, the China Structural Bonding Materials Market was valued at USD 1.33 billion in 2025 and is projected to reach USD 1.93 billion by 2032, growing at a CAGR of approximately 5.5% during 2026–2032.
China Structural Bonding Materials Market Highlights
| Report Metric | Details |
| Report Name | China Structural Bonding Materials Market |
| Market Size 2025 | USD 1.33 billion |
| Market Size 2032 | USD 1.93 billion |
| Absolute Growth 2025–2032 | USD 0.60 billion |
| CAGR 2026–2032 | 5.5% |
| Peak Annual Growth | 7.5% in 2027 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Epoxy Resins (52% share) |
| Leading Chemical Base, 2025 | Thermosetting Polymer (33% share) |
| Leading Bonding Application, 2025 | Automotive Panels (43% share) |
| Leading End User, 2025 | Body Assembly Units (39% share) |
| Fastest-Growing Material Type | Polyurethanes (7.8% CAGR) |
| Fastest-Growing Chemical Base | Solvent-Free (7.4% CAGR) |
| Fastest-Growing Bonding Application | Prefab Construction (6.7% CAGR) |
| Fastest-Growing End User | Building Component Firms (8.0% CAGR) |
| Growing Sector | Automotive |
| Key End Users | Automotive manufacturers, aerospace companies, construction firms, body assembly units |
China Structural Bonding Materials Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
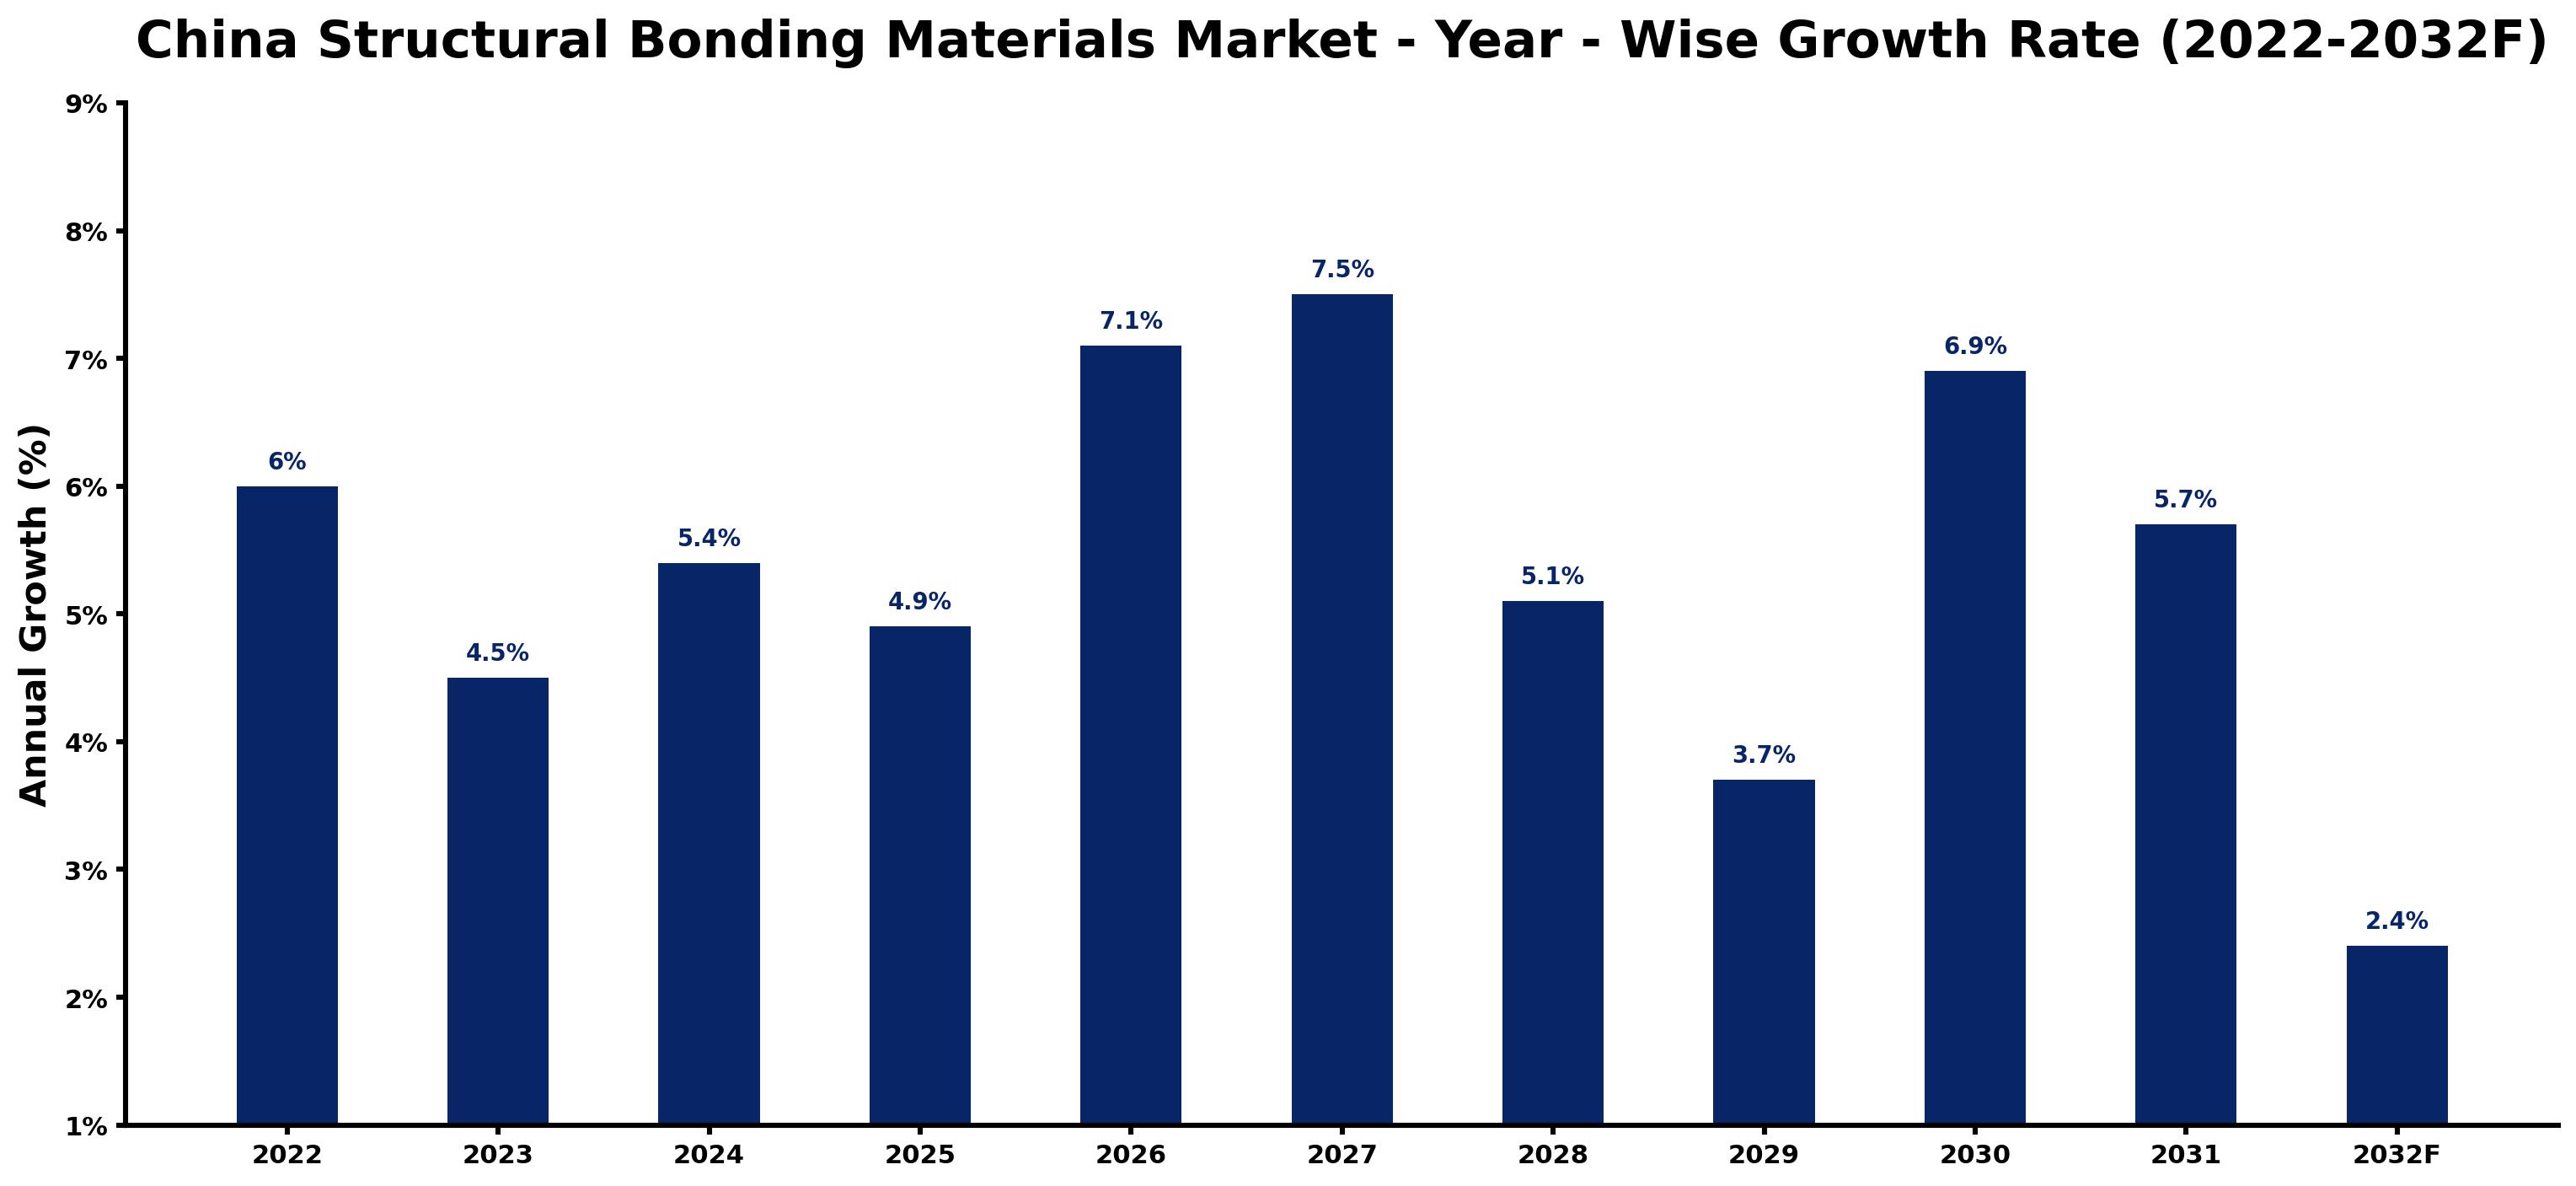
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 6.0 | The automotive sector's strong performance drove demand for bonding materials. |
| 2023 | 4.5 | Growth slowed due to a temporary dip in automotive production rates. |
| 2024 | 5.4 | Increased construction activities boosted demand for structural bonding materials. |
| 2025 | 4.9 | Automotive production continued to grow, sustaining demand for bonding solutions. |
| 2026 | 7.1 | The aerospace sector's expansion is expected to increase bonding material requirements. |
| 2027 | 7.5 | Peak growth will occur as the construction industry ramps up projects. |
| 2028 | 5.1 | Growth is projected to slow as the market stabilises after rapid expansion. |
| 2029 | 3.7 | Demand will soften due to adjustments in the automotive sector. |
| 2030 | 6.9 | A resurgence in construction projects is expected to revitalise the market's growth. |
| 2031 | 5.7 | Growth will slow as the market approaches saturation in certain segments. |
| 2032 | 2.4 | The market is expected to stabilise as demand reaches a mature phase. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Bonding Materials Market Synopsis
Structural Bonding Materials in China encompass advanced adhesives primarily made from polymers, providing durable bonds for automotive, aerospace, and construction applications. These materials are produced through chemical processes involving resin and hardener components. The China Structural Bonding Materials Market is growing due to strong demand from the automotive sector, which is the largest consumer, alongside contributions from construction and aerospace industries. The construction industry is projected to reach over $1 trillion by 2025, further driving material usage.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Strong demand from the automotive sector drives the need for high-performance bonding solutions. | Driver | High | Automotive Panels |
| The growth of the aerospace industry increases the requirement for lightweight bonding materials. | Driver | High | Aerospace Structures |
| The ongoing shift towards eco-friendly materials presents opportunities for innovative bonding solutions. | Opportunity | High | Solvent-Free |
| The rise in modular construction techniques creates a demand for efficient bonding materials. | Opportunity | Medium | Prefab Construction |
| Regulatory compliance for safety standards can restrict market entry for new manufacturers. | Restraint | High | Epoxy Resins |
| High production costs for advanced bonding materials may limit affordability for some buyers. | Restraint | Medium | Epoxy Resins |
| The Structural Bonding Materials Market in China faces challenges related to fluctuating raw material prices. | Challenge | High | Epoxy Resins |
| Technological advancements require constant investment, posing a challenge for smaller manufacturers. | Challenge | Medium | Epoxy Resins |
Evaluation of Drivers in China Structural Bonding Materials Market (2026–2032)
The main growth drivers and the segments they affect most are set out below.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increasing vehicle production rates drive demand for automotive bonding materials. | Automotive Panels | In 2022, millions of vehicles were produced in China, necessitating strong adhesives for assembly. |
| The aerospace sector's growth boosts the need for high-performance bonding solutions. | Aerospace Structures | Over 100 aircraft were produced in 2022, increasing the demand for structural adhesives. |
| The construction industry's expansion fuels the need for durable bonding materials. | Prefab Construction | The construction industry is projected to exceed $1 trillion by 2025, driving material usage. |
| The push for environmentally friendly products encourages innovation in bonding technologies. | Solvent-Free | The Green Manufacturing Program, with a budget of 500 million yuan, promotes eco-friendly adhesive technologies, impacting market growth. |
| Technological advancements in bonding applications improve product performance. | Thermosetting Polymer | New formulations improve heat resistance, attracting more buyers in demanding sectors. |
Market growth in China for Structural Bonding Materials hinges on rising vehicle production rates, expanding construction activities, and advancements in bonding applications. In 2022, millions of vehicles were produced, creating a need for reliable adhesives in assembly. The construction industry is anticipated to exceed $1 trillion by 2025, further boosting material usage. The aerospace sector also plays a role, with over 100 aircraft produced in 2022, heightening the demand for high-performance bonding solutions. Developments in bonding technologies are improving product performance, attracting buyers in demanding sectors.
Evaluation of Restraints in China Structural Bonding Materials Market
The following restraints limit how fast demand can grow.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Regulatory compliance for safety standards can restrict market entry for new manufacturers. | Epoxy Resins | The implementation of the 'Regulations on the Supervision and Administration of Adhesives' in 2022 imposes strict requirements. |
| High production costs for advanced bonding materials may limit affordability for some buyers. | Epoxy Resins | The need for high-quality materials often leads to increased pricing, affecting market accessibility. |
| Fluctuating raw material prices can impact production costs and pricing strategies. | Epoxy Resins | Volatility in the prices of key ingredients affects manufacturers' margins and pricing. |
| Limited awareness of advanced bonding technologies may hinder market growth. | Epoxy Resins | Some buyers may not fully understand the benefits of modern bonding solutions. |
| Competition from alternative adhesive technologies can restrict market share. | Epoxy Resins | Emerging technologies may offer cheaper or more accessible solutions for end-users. |
China Structural Bonding Materials Market Challenges
The China Structural Bonding Materials Market encounters several practical issues, with cost being a primary concern. Rising raw material prices have increased production costs by around 15% over the past year, affecting automotive sector buyers who depend on these materials for vehicle assembly. Supply chain disruptions have caused delivery delays, prompting construction firms to postpone projects, potentially leading to financial losses of up to 20% for contractors. Intense competition among local manufacturers has resulted in price reductions, compelling suppliers to compromise on quality, ultimately impacting the durability of bonding materials used in various applications.
Trends in the China Structural Bonding Materials Market
The trends below show where the China Structural Bonding Materials Market is heading.
- Shift towards Eco-Friendly Bonding Solutions: China is increasingly adopting eco-friendly bonding materials, spurred by the Green Manufacturing Program. In 2023, a subsidy program of 500 million yuan was announced to promote the development of sustainable adhesives, influencing buyer preferences.
- Growth in Modular Construction Techniques: The rise of modular construction is transforming the bonding materials market, particularly in Guangdong. As the construction industry evolves, the demand for efficient bonding materials is expected to rise significantly.
- Increased Demand for Lightweight Materials in Aerospace: The aerospace sector is moving towards lightweight bonding materials to enhance fuel efficiency. With over 100 aircraft produced in 2022, this trend is likely to drive further advancements in bonding technologies.
- Expansion of Automotive Manufacturing Hubs: Guangdong province is emerging as a major hub for automotive manufacturing, impacting bonding material demand. As millions of vehicles are produced each year, the need for high-performance adhesives continues to grow.
Investment Opportunities in the China Structural Bonding Materials Market
Below are the investment opportunities with the strongest case in the China Structural Bonding Materials Market.
- Growing Demand for Eco-Friendly Products: With the Green Manufacturing Program in place, there is a chance for investment in eco-friendly bonding materials. Companies developing sustainable solutions stand to gain from the subsidy announced in 2023.
- Increased Investment in Modular Construction: The ongoing shift towards modular construction presents a timely opportunity for suppliers of bonding materials. As the construction industry evolves, building component firms will require innovative bonding solutions.
- Expansion of the Aerospace Sector: The growth of the aerospace industry offers a prime opportunity for manufacturers of high-performance bonding materials. With over 100 aircraft produced in 2022, suppliers can target aviation OEMs for advanced solutions.
- Collaboration with Automotive Manufacturers: Now is an ideal time for joint ventures with automotive manufacturers in Guangdong. As vehicle production increases, suppliers can establish partnerships to meet rising demand for bonding materials.
Government Initiatives in the China Structural Bonding Materials Market
The Ministry of Industry and Information Technology launched the '14th Five-Year Plan for the Development of Advanced Materials' in 2021, aiming to improve domestic production capabilities for structural bonding materials. This plan supports manufacturers in improving their production processes and product quality. The 'Regulations on the Supervision and Administration of Adhesives' implemented in 2022 ensures that bonding materials meet safety and quality standards, impacting how producers operate in the market. These measures collectively aim to strengthen the domestic sector and ensure compliance with international standards.
The State Administration for Market Regulation oversees funding for companies developing eco-friendly bonding materials, with a budget of 500 million yuan announced in 2023. This funding encourages innovation and the adoption of sustainable practices in the industry. Additionally, the Ministry of Ecology and Environment introduced the 'Green Product Certification' program in 2020, promoting sustainable bonding materials across various sectors. The National Development and Reform Commission ensures that products meet regulatory requirements, impacting producers and buyers alike.
Future Insight of the China Structural Bonding Materials Market
The China Structural Bonding Materials Market will undergo significant changes by 2032, driven by several key factors. The automotive sector will continue to be the largest consumer, with millions of vehicles produced annually, while the construction industry is projected to exceed a value of $1 trillion by 2025, leading to increased bonding material usage. The Green Manufacturing Program will motivate manufacturers to adopt environmentally friendly adhesive technologies, while advancements in bonding technologies, supported by the National Development and Reform Commission, will improve product offerings and benefit both buyers and suppliers.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Material Type – Epoxy Resins Dominated, Polyurethanes Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, Epoxy Resins held a 52% share of the China Structural Bonding Materials Market by material type in 2025. Epoxy resins hold the largest share in the China structural bonding materials market due to their critical role in high-strength applications, particularly in the automotive and construction sectors. The automotive industry, producing millions of vehicles annually, significantly relies on epoxy resins for their durability and performance. The quickest growth will come from Polyurethanes, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Polyurethanes are experiencing rapid growth as they are increasingly favoured for flexible bonding applications in both automotive and construction industries. This surge is largely driven by rising environmental regulations that promote the use of sustainable materials, positioning polyurethanes for continued expansion. Suppliers should enhance their polyurethane product offerings to meet the increasing demand driven by environmental considerations.
By Chemical Base – Thermosetting Polymer Dominated, Solvent-Free Expected to Grow Fastest
The largest chemical base category in 2025 was Thermosetting Polymer, with a 33% share of total revenue. Thermosetting polymers dominate the market due to their essential role in applications that require heat resistance, particularly in automotive and construction sectors. Their robust performance characteristics make them the preferred choice for manufacturers operating in demanding environments. Over 2026–2032, Solvent-Free is expected to post the fastest growth, at a CAGR of 7.4%. Solvent-free adhesives are gaining popularity, primarily due to stringent environmental regulations that encourage manufacturers to seek greener alternatives. This shift indicates a growing consumer preference for sustainable bonding solutions, which is likely to persist. Manufacturers must adapt to the increasing demand for solvent-free options to maintain competitiveness in the market.
By Bonding Application – Automotive Panels Dominated, Prefab Construction Expected to Grow Fastest
In 2025, Automotive Panels led the bonding application split with a 43% share. Automotive panels represent the largest share in bonding applications, extensively used in vehicle manufacturing processes. The high volume of vehicles produced in China necessitates reliable bonding materials to ensure structural integrity. Prefab Construction is projected to grow fastest, at a CAGR of 6.7% during 2026–2032. Prefab construction is the fastest-growing application segment, driven by the rising adoption of modular building systems that enhance construction efficiency. This trend reflects a broader shift towards innovative construction methods that require advanced bonding technologies. Suppliers should consider expanding their product lines to address the growing demand in the prefab construction market.
By End User – Body Assembly Units Dominated, Building Component Firms Expected to Grow Fastest
Body Assembly Units accounted for a 39% market share by end user in 2025. Body assembly units are the leading end users of structural bonding materials, playing a critical role in vehicle assembly processes that demand high-strength adhesives. The scale of the automotive industry in China ensures a consistent demand for these materials. Building Component Firms are set to record the highest CAGR in this split, 8.0% over 2026–2032. Building component firms are the fastest-growing end users, as they increasingly rely on bonding materials to ensure structural integrity in modern construction practices. This growth indicates a shift towards more efficient building methods that leverage advanced bonding technologies. Suppliers should target building component firms to capitalise on expanding market opportunities in the construction sector.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Bonding Materials Market Outlook
- Market Size of China Structural Bonding Materials Market, 2025
- Forecast of China Structural Bonding Materials Market, 2032
- Historical Data and Forecast of China Structural Bonding Materials Revenues & Volume for the Period 2022 - 2032F
- China Structural Bonding Materials Market Trend Evolution
- China Structural Bonding Materials Market Drivers and Challenges
- China Structural Bonding Materials Price Trends
- China Structural Bonding Materials Porter's Five Forces
- China Structural Bonding Materials Industry Life Cycle
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Epoxy Resins for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Acrylics for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Polyurethanes for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Silicone-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Chemical Base for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Thermosetting Polymer for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Solvent-Free for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Flexible Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Weatherproofing for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Bonding Application for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Aerospace Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Automotive Panels for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Rail Vehicle Bonding for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Prefab Construction for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Aviation OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Body Assembly Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Rolling Stock Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Bonding Materials Market Revenues & Volume By Building Component Firms for the Period 2022 - 2032F
- China Structural Bonding Materials Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Chemical Base
- Market Opportunity Assessment By Bonding Application
- Market Opportunity Assessment By End User
- China Structural Bonding Materials Top Companies Market Share
- China Structural Bonding Materials Competitive Benchmarking By Technical and Operational Parameters
- China Structural Bonding Materials Company Profiles
- China Structural Bonding Materials Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Material Type
- Epoxy Resins
- Acrylics
- Polyurethanes
- Silicone-Based
By Chemical Base
- Thermosetting Polymer
- Solvent-Free
- Flexible Bonding
- Weatherproofing
By Bonding Application
- Aerospace Structures
- Automotive Panels
- Rail Vehicle Bonding
- Prefab Construction
By End User
- Aviation OEMs
- Body Assembly Units
- Rolling Stock Manufacturers
- Building Component Firms































