China Structural Light-Weight Design Market Size & Growth Rate
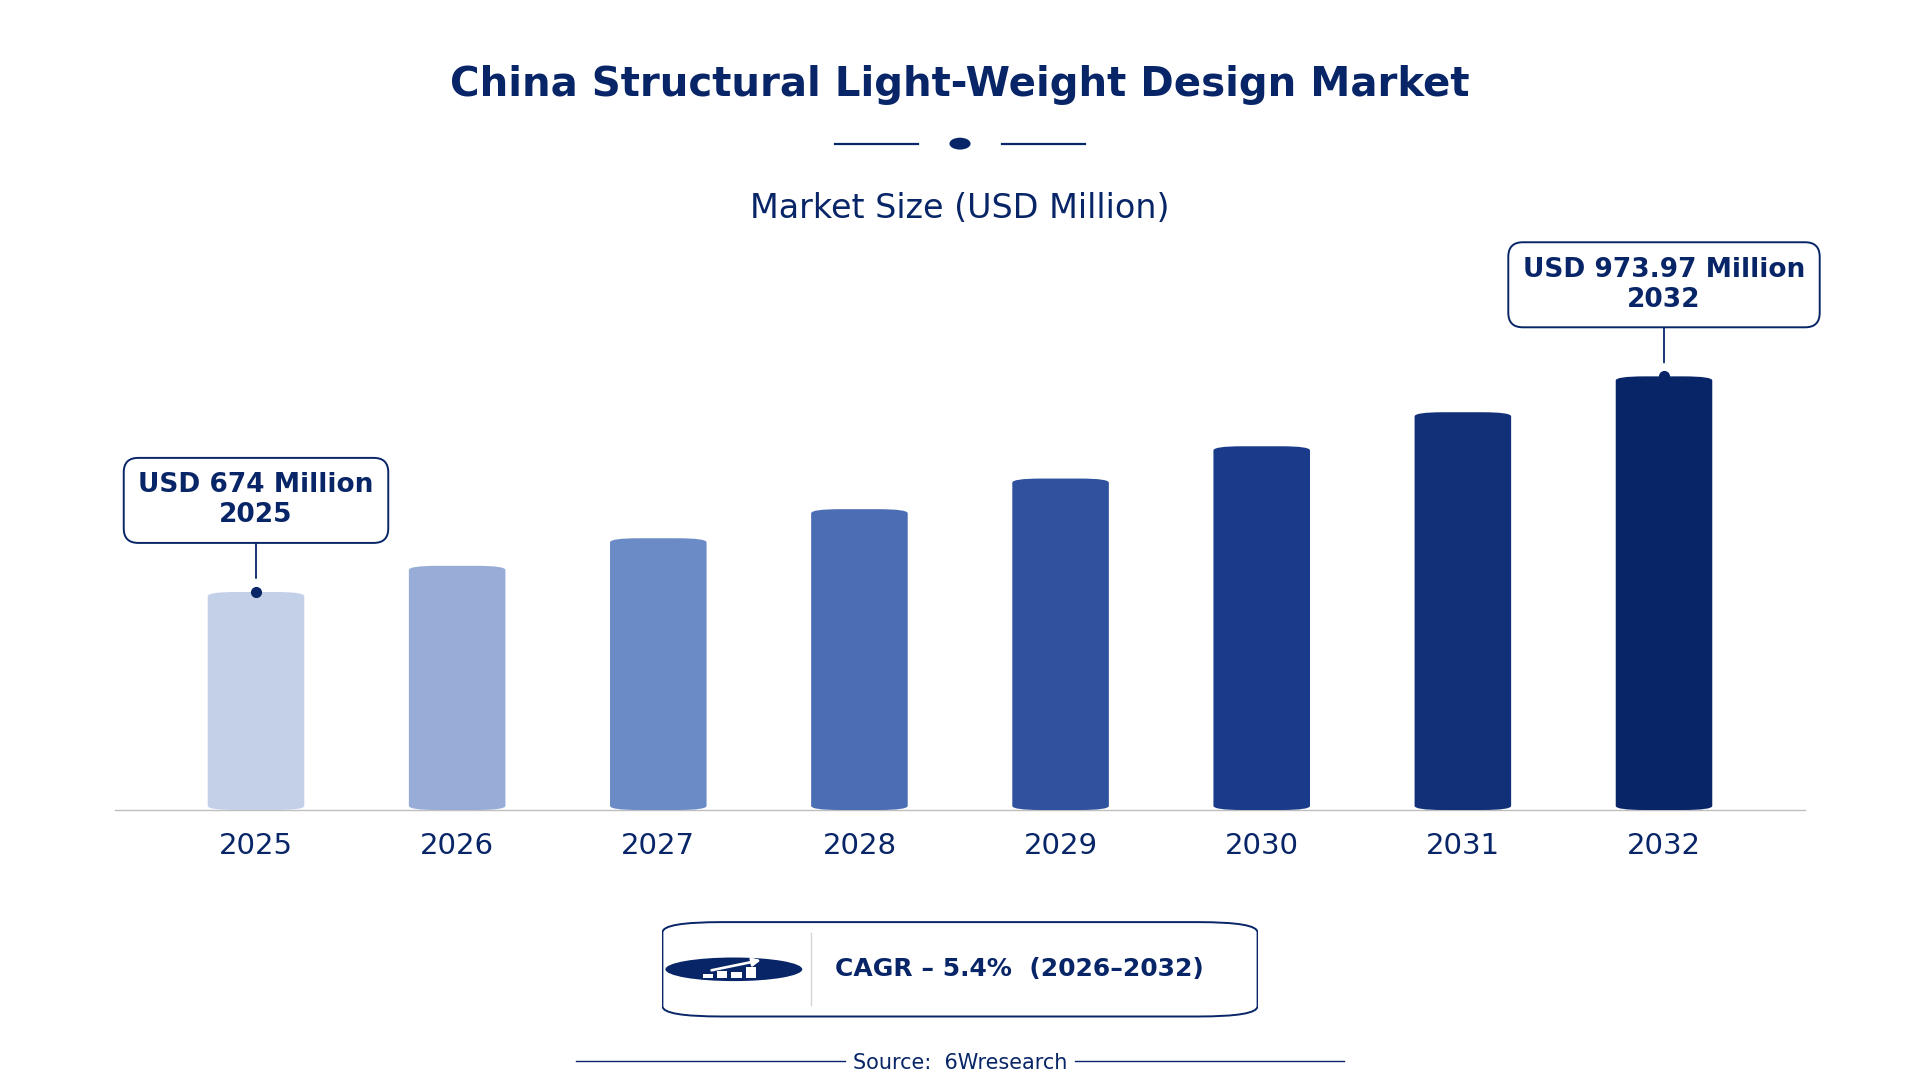
According to 6Wresearch internal database and industry insights, the China Structural Light-Weight Design Market was valued at USD 674.0 million in 2025 and is projected to reach USD 973.97 million by 2032, growing at a CAGR of approximately 5.4% during 2026–2032.
China Structural Light-Weight Design Market Highlights
| Report Metric | Details |
| Report Name | China Structural Light-Weight Design Market |
| Market Size 2025 | USD 674.0 million |
| Market Size 2032 | USD 973.97 million |
| Absolute Growth 2025–2032 | USD 299.97 million |
| CAGR 2026–2032 | 5.4% |
| Peak Annual Growth | 7.7% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Material Type, 2025 | Aluminum Alloy (48% share) |
| Leading Design Approach, 2025 | Topology Optimization (34% share) |
| Leading Application Area, 2025 | Chassis (45% share) |
| Leading End User, 2025 | Vehicle OEMs (40% share) |
| Fastest-Growing Material Type | Carbon Fiber Composite (6.4% CAGR) |
| Fastest-Growing Design Approach | CAD-Integrated Design (7.8% CAGR) |
| Fastest-Growing Application Area | EV Body Frames (6.4% CAGR) |
| Fastest-Growing End User | Electric Vehicle Makers (7.8% CAGR) |
| Growing Sector | automotive |
| Key End Users | Vehicle OEMs, Electric Vehicle Makers, Performance Car Manufacturers, Safety Engineering Firms |
China Structural Light-Weight Design Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
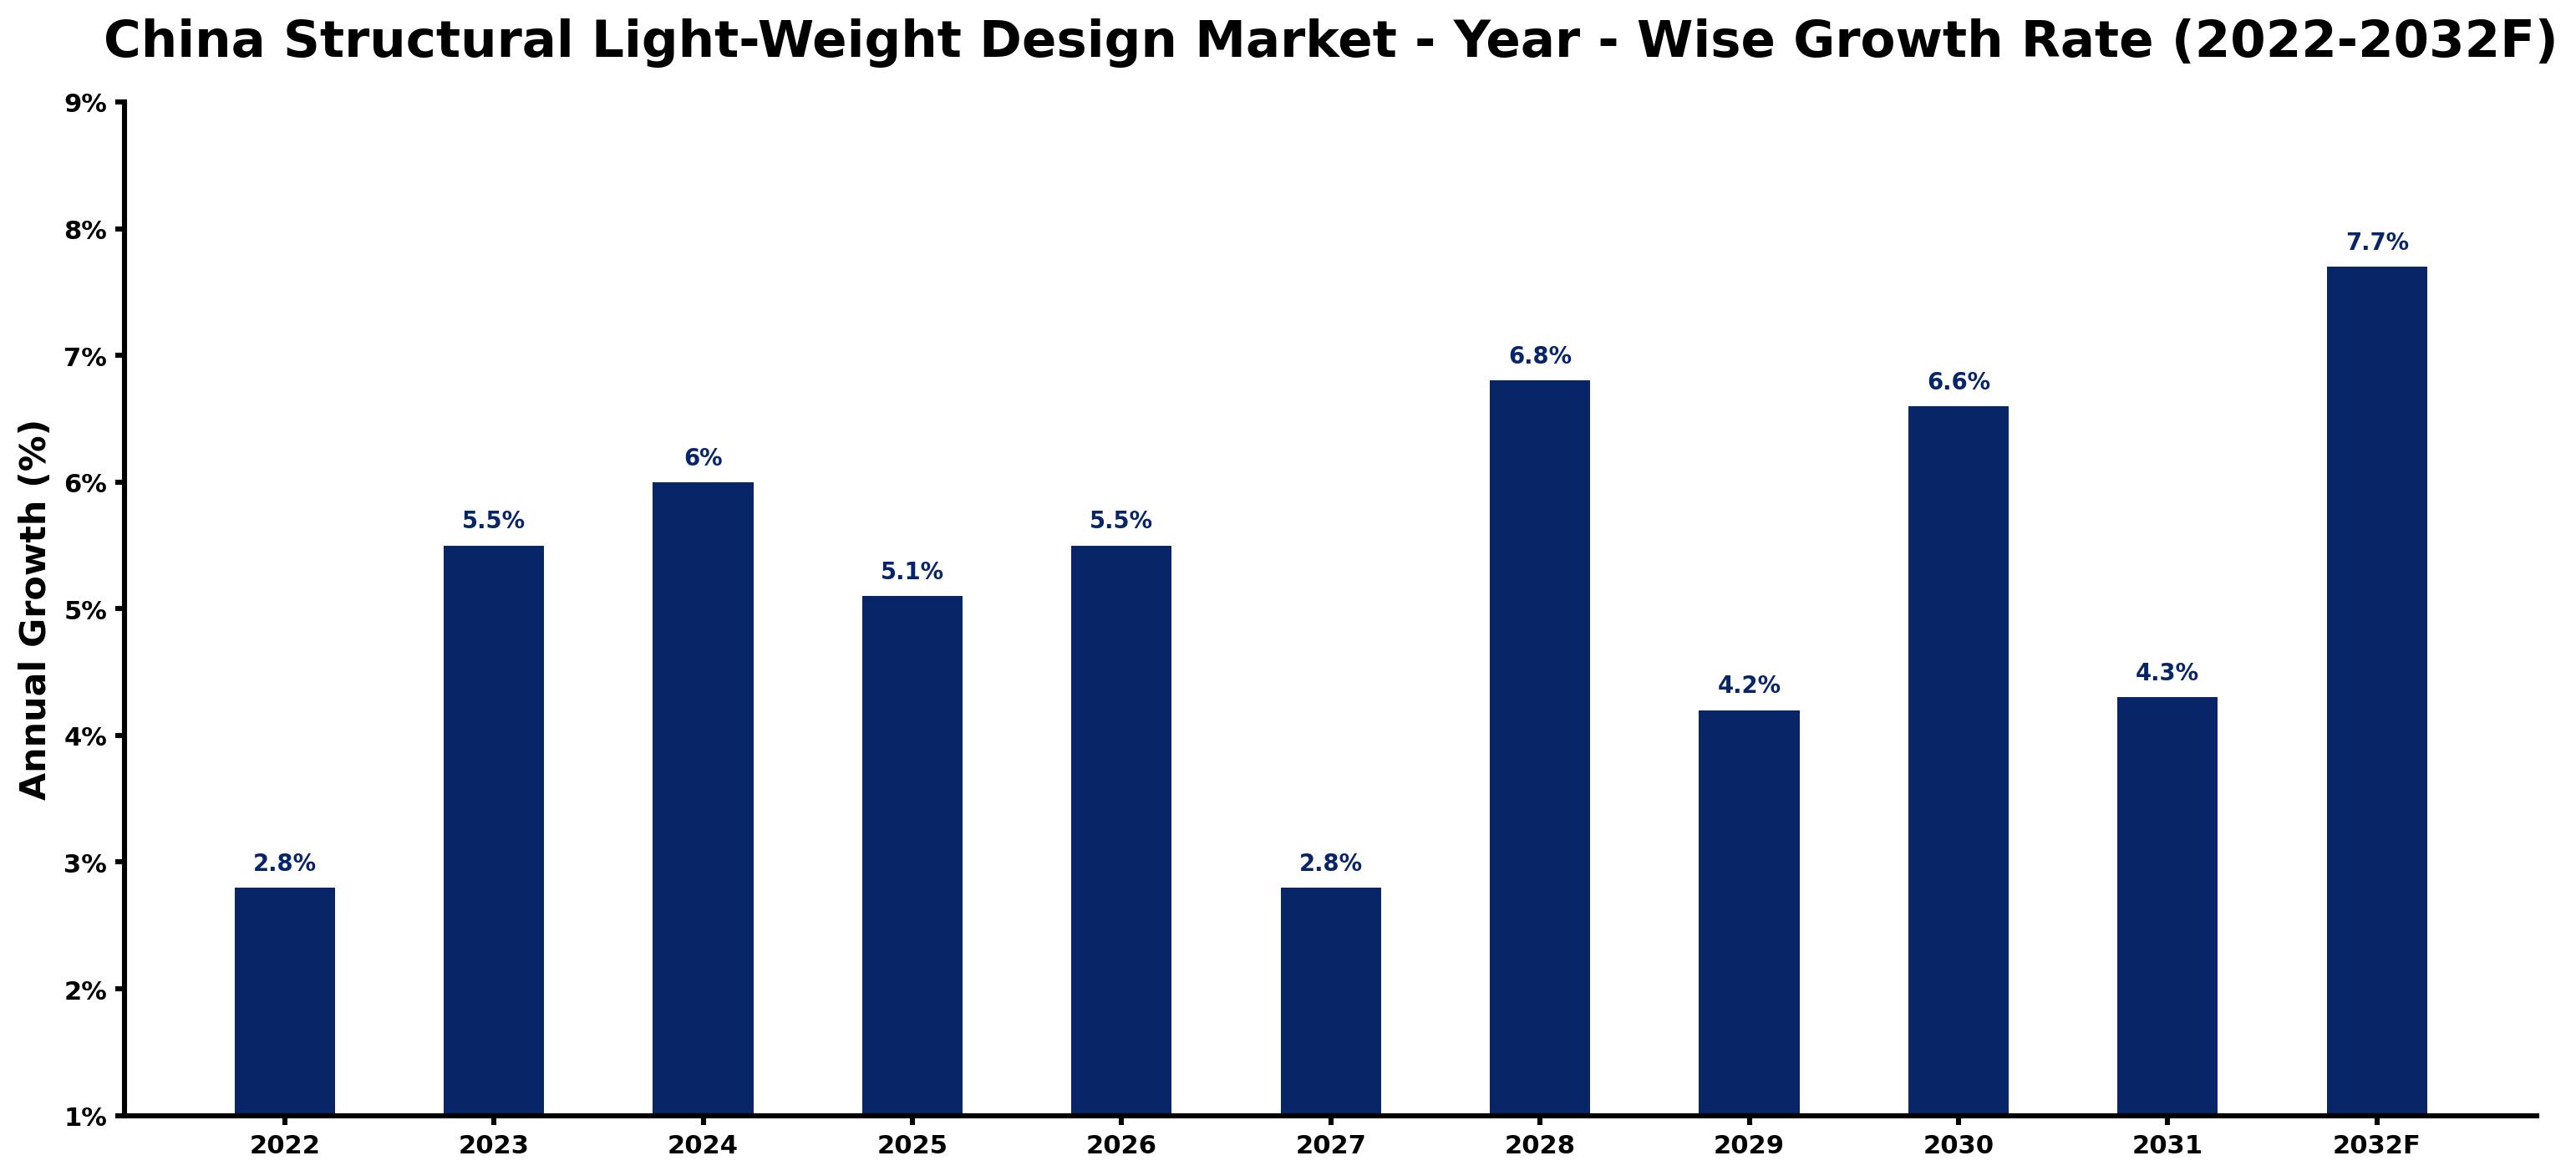
Each row of the following table gives one year's estimated growth and the event or demand shift that explains it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 2.8 | The market showed steady growth with increasing interest in lightweight automotive designs driven by the automotive sector's expansion and the 'Made in China 2025' initiative. |
| 2023 | 5.5 | Demand surged due to the rise in electric vehicle production and innovation in lightweight materials, particularly in the Beijing-Tianjin-Hebei region. |
| 2024 | 6.0 | The automotive sector experienced growth, driven by advancements in lightweight materials and the 'Automotive Industry Development Policy'. |
| 2025 | 5.1 | Growth slowed as manufacturers adjusted to new standards and production capacities outlined in the 'New Energy Vehicle Development Plan'. |
| 2026 | 5.5 | The market is expected to rebound with renewed interest in energy-efficient vehicle designs and CAD-integrated approaches. |
| 2027 | 2.8 | Growth is projected to decelerate as manufacturers face challenges in sourcing advanced materials and complying with GB/T 20000 standards. |
| 2028 | 6.8 | A surge in electric vehicle adoption is anticipated to spur demand for lightweight designs, particularly in the Guangdong province. |
| 2029 | 4.2 | The market is expected to experience a slowdown as competition intensifies among manufacturers in the automotive sector. |
| 2030 | 6.6 | Growth is projected to accelerate again, driven by technological advancements in lightweight design methodologies and the push for safety in vehicle production. |
| 2031 | 4.3 | The market is expected to see a slowdown as manufacturers adjust to evolving consumer preferences and regulatory standards. |
| 2032 | 7.7 | The market is expected to peak, driven by increasing demand for lightweight electric vehicles and innovations in material science. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Structural Light-Weight Design Market Synopsis
Structural Light-Weight Design in China involves advanced techniques and materials aimed at reducing weight while maintaining integrity. This approach is crucial for improving vehicle performance and energy efficiency, especially in electric vehicles. The China Structural Light-Weight Design Market is expanding due to strong demand from the automotive sector, driven by the production of over 3 million electric vehicles in 2022 and initiatives like the 'New Energy Vehicle Development Plan'. These elements are propelling the adoption of lightweight designs across various vehicle types.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing demand for electric vehicles drives the need for lightweight designs. | Driver | High | EV Body Frames |
| The rise in performance car manufacturing boosts the adoption of advanced materials. | Driver | High | Performance Car Manufacturers |
| Growing investment in lightweight material research presents opportunities for suppliers. | Opportunity | High | Aluminum Alloy |
| The demand for innovative design approaches opens new markets for CAD-integrated solutions. | Opportunity | Medium | CAD-Integrated Design |
| High costs associated with advanced materials can limit adoption rates. | Restraint | High | Carbon Fiber Composite |
| Regulatory compliance for lightweight materials can delay production timelines. | Restraint | Medium | Aluminum Alloy |
| Supply chain disruptions affect material availability for manufacturers. | Challenge | High | Vehicle OEMs |
| Technological challenges in integrating new materials can hinder design processes. | Challenge | Medium | Safety Engineering Firms |
Evaluation of Drivers in China Structural Light-Weight Design Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Rising electric vehicle production increases demand for lightweight designs. | EV Body Frames | China produced over 3 million electric vehicles in 2022, necessitating lighter structures for improved energy efficiency. |
| Performance car manufacturers seek advanced materials for speed and handling. | Performance Car Manufacturers | The automotive sector employs over 4 million people, driving innovation in lightweight designs to improve vehicle performance. |
| Investment in lightweight material research boosts design capabilities. | Hybrid Structures | The Jiangsu province has allocated substantial funding for lightweight material research, enhancing local production capabilities and innovation. |
| The adoption of CAD-integrated design improves efficiency in engineering. | CAD-Integrated Design | National standards like GB/T 20000 series promote advanced design techniques, leading to more efficient manufacturing processes. |
| The push for safety in vehicle design drives demand for crash zones. | Crash Zones | The 'Automotive Industry Development Policy' outlines goals for lightweight vehicle production, emphasizing safety and efficiency. |
Growth across the Structural Light-Weight Design market in China is anchored in rising electric vehicle production, increasing investment in lightweight materials, and the adoption of advanced design techniques. In 2022, over 3 million electric vehicles were produced, creating a strong demand for lightweight designs to improve energy efficiency. Investment in lightweight material research has grown, particularly in regions like Jiangsu, enhancing local production capabilities.
Evaluation of Restraints in China Structural Light-Weight Design Market
The key brakes on demand, and where they bite hardest, are shown below.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| High costs of advanced materials limit widespread adoption. | Carbon Fiber Composite | The price of carbon fiber remains high, affecting budget constraints for manufacturers and limiting their ability to innovate. |
| Regulatory compliance can delay production timelines for lightweight designs. | Aluminum Alloy | Manufacturers must adhere to stringent national standards like GB/T 20000, impacting time-to-market for new products. |
| Supply chain disruptions affect material availability for manufacturers. | Hybrid Structures | Recent global supply chain issues have led to shortages in essential lightweight materials, hindering production capabilities. |
| Technological challenges in integrating new materials hinder design processes. | Safety Engineering Firms | Complexity in new material applications can slow down development cycles and increase costs for safety assessments. |
| Limited awareness of lightweight benefits among traditional manufacturers. | Vehicle OEMs | Some manufacturers remain hesitant to invest in lightweight technologies due to perceived risks and lack of information. |
China Structural Light-Weight Design Market Challenges
Buyers and suppliers in the China Structural Light-Weight Design market face intense competition, with over 3 million electric vehicles produced in 2022, raising the stakes for lightweight solutions. This competition compels manufacturers to reduce costs, often at the expense of material quality, which ultimately affects vehicle safety. Regulatory compliance with national standards, specifically the GB/T 20000 series, can delay product launches and increase costs for producers, impacting their market position. Buyers must invest heavily in advanced technologies to achieve a 15% weight reduction target for electric vehicles by 2025, straining their budgets and resources.
Trends in the China Structural Light-Weight Design Market
Several trends are reshaping the China Structural Light-Weight Design Market; the most important are set out below.
- Shift towards Advanced CAD-Integrated Design: The automotive sector is increasingly adopting CAD-integrated design approaches to improve efficiency and accuracy. The 'Made in China 2025' initiative promotes this shift, with a projected growth rate of 7.8% for CAD-integrated design by 2032.
- Electric Vehicle Makers Prioritising Lightweight Solutions: Electric vehicle makers are focusing on lightweight designs to improve energy efficiency. The average weight reduction target for EVs is around 15% by 2025, reflecting a trend in the industry.
- Guangdong Province Leading in Lightweight Material Innovation: Guangdong province is emerging as a hub for lightweight material innovation, supported by local government initiatives. This region produced over 1 million electric vehicles in 2022, driving demand for advanced lightweight designs.
- Performance Car Manufacturers Emphasising Weight Reduction: Performance car manufacturers are increasingly prioritising weight reduction to enhance speed and handling. The Shanghai International Automobile Industry Exhibition highlights advancements in lightweight materials, showcasing innovations in this area.
Investment Opportunities in the China Structural Light-Weight Design Market
Some of the investment opportunities in the China Structural Light-Weight Design Market are mentioned below.
- Investment in Lightweight Material Research: Investment in lightweight material research presents opportunities for suppliers in the automotive sector. The Jiangsu province has allocated substantial funding for this purpose, indicating a growing market demand for advanced materials.
- Supply of Advanced CAD-Integrated Design Solutions: There is a rising demand for advanced CAD-integrated design solutions among vehicle OEMs. The average weight reduction target for EVs is around 15% by 2025, creating a gap for innovative design services.
- Development of Hybrid Structures: The development of hybrid structures is gaining traction as manufacturers seek optimal performance. The Guangdong province is a key area for automotive manufacturing, offering opportunities for local partnerships in material innovation.
- Focus on Crash Zone Innovations: The focus on crash zone innovations opens avenues for safety engineering firms. The 'Green Manufacturing' program encourages the adoption of lightweight materials, enhancing safety features in vehicles.
Government Initiatives in the China Structural Light-Weight Design Market
The 'New Energy Vehicle Development Plan' launched by the Ministry of Industry and Information Technology in 2023 supports the growth of the lightweight design market. This initiative aims to promote the production of electric vehicles and the use of lightweight materials, with a target of increasing the number of electric vehicles to 10 million units by 2025. Additionally, the 'Automotive Industry Development Policy' outlines specific goals for lightweight vehicle production, ensuring compliance with national standards. These measures encourage manufacturers to invest in new designs and materials, driving market growth.
The National Development and Reform Commission oversees various schemes that fund research and development in lightweight automotive technologies. Programs like the 'Green Manufacturing' initiative provide financial support to manufacturers adopting lightweight materials, with an investment of over USD 100 million aimed at improving production efficiency. The China Association of Automobile Manufacturers also plays a key role in promoting lightweight technologies, facilitating collaboration among industry stakeholders to enhance innovation and competitiveness.
Future Insight of the China Structural Light-Weight Design Market
The China Structural Light-Weight Design market will evolve significantly by 2032, influenced by the 'New Energy Vehicle Development Plan' and the 'Made in China 2025' initiative. These initiatives will encourage the adoption of lightweight materials, enhancing vehicle performance and energy efficiency. The Guangdong province is set to be a hub for innovation, driving advancements in materials and manufacturing processes. As the automotive sector continues to grow, suppliers will need to adapt to new technologies and standards to meet the rising demand.
Market Segmentation Analysis
Each segment group is reviewed below, with the leader by share and the fastest grower by CAGR.
By Material Type – Aluminum Alloy Dominated, Carbon Fiber Composite Expected to Grow Fastest
According to Summon Dutta, Assistant Manager at 6Wresearch, in 2025, Aluminum Alloy led the material type split with a 48% share. Aluminum alloy holds the largest market share in the China structural light-weight design market due to its widespread application in the automotive industry, particularly in electric vehicles. The installed base of electric vehicles in China reached 10 million units in 2023, driving demand for lightweight solutions like aluminum. Over 2026–2032, Carbon Fiber Composite is expected to post the fastest growth, at a CAGR of 6.4%. Carbon fiber composite is experiencing rapid growth as it becomes more prevalent in high-performance applications, especially within luxury electric vehicles. The 'New Energy Vehicle Development Plan' launched in 2023 encourages the adoption of advanced materials that improve vehicle efficiency, further propelling this segment. Suppliers should focus on enhancing their aluminum alloy offerings while also exploring carbon fiber composites to align with market trends.
By Design Approach – Topology Optimization Dominated, CAD-Integrated Design Expected to Grow Fastest
Topology Optimization held a 34% share of the China Structural Light-Weight Design Market by design approach in 2025. Topology optimization leads the market share in design approaches as it is crucial for developing efficient designs that reduce weight, essential for automotive safety and performance. This method is increasingly adopted by major automotive manufacturers in China, ensuring optimal structural integrity in their vehicles. CAD-Integrated Design is set to record the highest CAGR in this split, 7.8% over 2026–2032. CAD-integrated design is the fastest-growing approach, driven by its importance in modern engineering that streamlines design processes. The ongoing digital transformation in the automotive sector makes CAD integration vital for maintaining a competitive edge. Manufacturers should invest in advanced design software and training to fully leverage CAD-integrated design for improved product development.
By Application Area – Chassis Dominated, EV Body Frames Expected to Grow Fastest
Chassis accounted for a 45% market share by application area in 2025. Chassis holds the largest share in application areas due to its critical role in vehicle structure and safety, making it a primary focus for automotive manufacturers. The emphasis on lightweight designs in chassis is reflected in national standards outlined in the GB/T 20000 series, guiding industry practices. EV Body Frames are projected to grow fastest, at a CAGR of 6.4% during 2026–2032. EV body frames are the fastest-growing application area, driven by the surge in electric vehicle production, which necessitates lightweight solutions for improved efficiency. The average weight reduction target for EVs is around 15% by 2025, underscoring the urgency for innovation in this segment. Suppliers targeting the EV segment should prioritise lightweight solutions for body frames to align with industry standards and consumer expectations.
By End User – Vehicle OEMs Dominated, Electric Vehicle Makers Expected to Grow Fastest
Vehicle OEMs took a 40% share of end user in 2025, more than any other category. Vehicle OEMs dominate the market share as the primary users of structural light-weight designs in the automotive sector, significantly impacting material and design decisions. Their extensive production capabilities and commitment to innovation drive the demand for lightweight solutions across various vehicle types. The quickest growth will come from Electric Vehicle Makers, forecast to expand at a CAGR of 7.8% between 2026 and 2032. Electric vehicle makers represent the fastest-growing end user group, reflecting the increasing shift towards electric mobility and the necessity for lightweight designs to boost performance. With over 3 million electric vehicles produced in 2022, this segment's growth trajectory is poised to accelerate further. Suppliers should tailor their offerings to meet the specific requirements of electric vehicle makers, ensuring alignment with lightweight design objectives.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Structural Light-Weight Design Market Outlook
- Market Size of China Structural Light-Weight Design Market, 2025
- Forecast of China Structural Light-Weight Design Market, 2032
- Historical Data and Forecast of China Structural Light-Weight Design Revenues & Volume for the Period 2022 - 2032F
- China Structural Light-Weight Design Market Trend Evolution
- China Structural Light-Weight Design Market Drivers and Challenges
- China Structural Light-Weight Design Price Trends
- China Structural Light-Weight Design Porter's Five Forces
- China Structural Light-Weight Design Industry Life Cycle
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Material Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Aluminum Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Carbon Fiber Composite for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Magnesium Alloy for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Hybrid Structures for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Design Approach for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Topology Optimization for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By CAD-Integrated Design for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Load Bearing Elements for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Simulation-Based for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Application Area for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Chassis for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By EV Body Frames for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Engine Bays for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Crash Zones for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Vehicle OEMs for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Electric Vehicle Makers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Performance Car Manufacturers for the Period 2022 - 2032F
- Historical Data and Forecast of China Structural Light-Weight Design Market Revenues & Volume By Safety Engineering Firms for the Period 2022 - 2032F
- China Structural Light-Weight Design Import Export Trade Statistics
- Market Opportunity Assessment By Material Type
- Market Opportunity Assessment By Design Approach
- Market Opportunity Assessment By Application Area
- Market Opportunity Assessment By End User
- China Structural Light-Weight Design Top Companies Market Share
- China Structural Light-Weight Design Competitive Benchmarking By Technical and Operational Parameters
- China Structural Light-Weight Design Company Profiles
- China Structural Light-Weight Design Key Strategic Recommendations
Market Covered
Segments analysed in this report are listed below.
By Material Type
- Aluminum Alloy
- Carbon Fiber Composite
- Magnesium Alloy
- Hybrid Structures
By Design Approach
- Topology Optimization
- CAD-Integrated Design
- Load Bearing Elements
- Simulation-Based
By Application Area
- Chassis
- EV Body Frames
- Engine Bays
- Crash Zones
By End User
- Vehicle OEMs
- Electric Vehicle Makers
- Performance Car Manufacturers
- Safety Engineering Firms































