China Trauma Management Market Size & Growth Rate
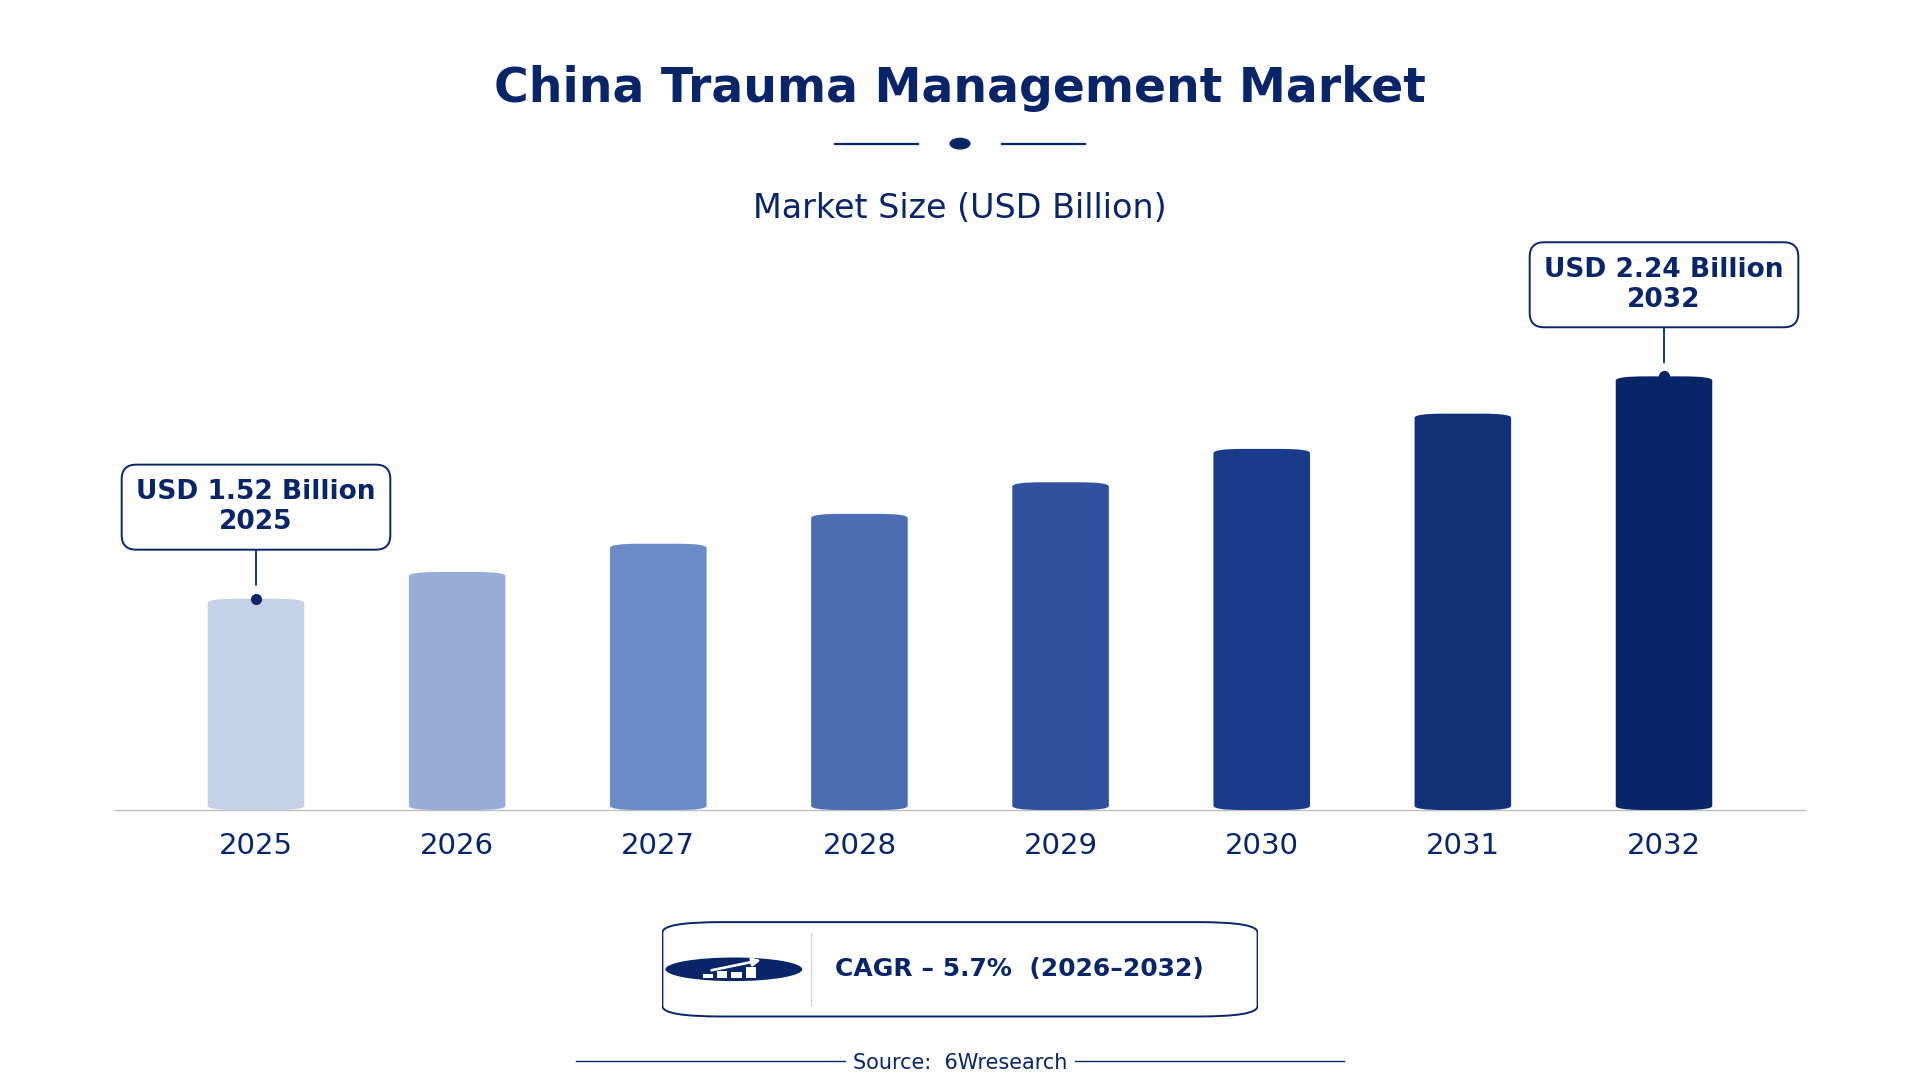
According to 6Wresearch internal database and industry insights, the China Trauma Management Market was valued at USD 1.52 billion in 2025 and is projected to reach USD 2.24 billion by 2032, growing at a CAGR of approximately 5.7% during 2026–2032.
China Trauma Management Market Highlights
| Report Metric | Details |
| Report Name | China Trauma Management Market |
| Market Size 2025 | USD 1.52 billion |
| Market Size 2032 | USD 2.24 billion |
| Absolute Growth 2025–2032 | USD 0.72 billion |
| CAGR 2026–2032 | 5.7% |
| Peak Annual Growth | 8.0% in 2032 |
| Forecast Period | 2026–2032 |
| Historical Data | 2022–2025 |
| Base Year | 2025 |
| Leading Management Approach, 2025 | Surgical Trauma Care (40% share) |
| Leading Specialty Focus, 2025 | Orthopedic/Neuro (42% share) |
| Leading Delivery Type, 2025 | Inpatient (41% share) |
| Leading End User, 2025 | Hospitals (49% share) |
| Fastest-Growing Management Approach | Non-Surgical Care (6.7% CAGR) |
| Fastest-Growing Specialty Focus | Physiotherapy (7.0% CAGR) |
| Fastest-Growing Delivery Type | Outpatient (8.2% CAGR) |
| Fastest-Growing End User | Clinics (7.0% CAGR) |
| Growing Sector | Pediatric Trauma Care |
| Key End Users | Hospitals, Clinics, Trauma Survivors, Children's Hospitals |
China Trauma Management Market Year-wise Growth Rate and Key Drivers (2022–2032)
This graph illustrates the annual growth rates of the market from 2022 to 2032, highlighting a steady upward trajectory and projected market expansion over the forecast period.
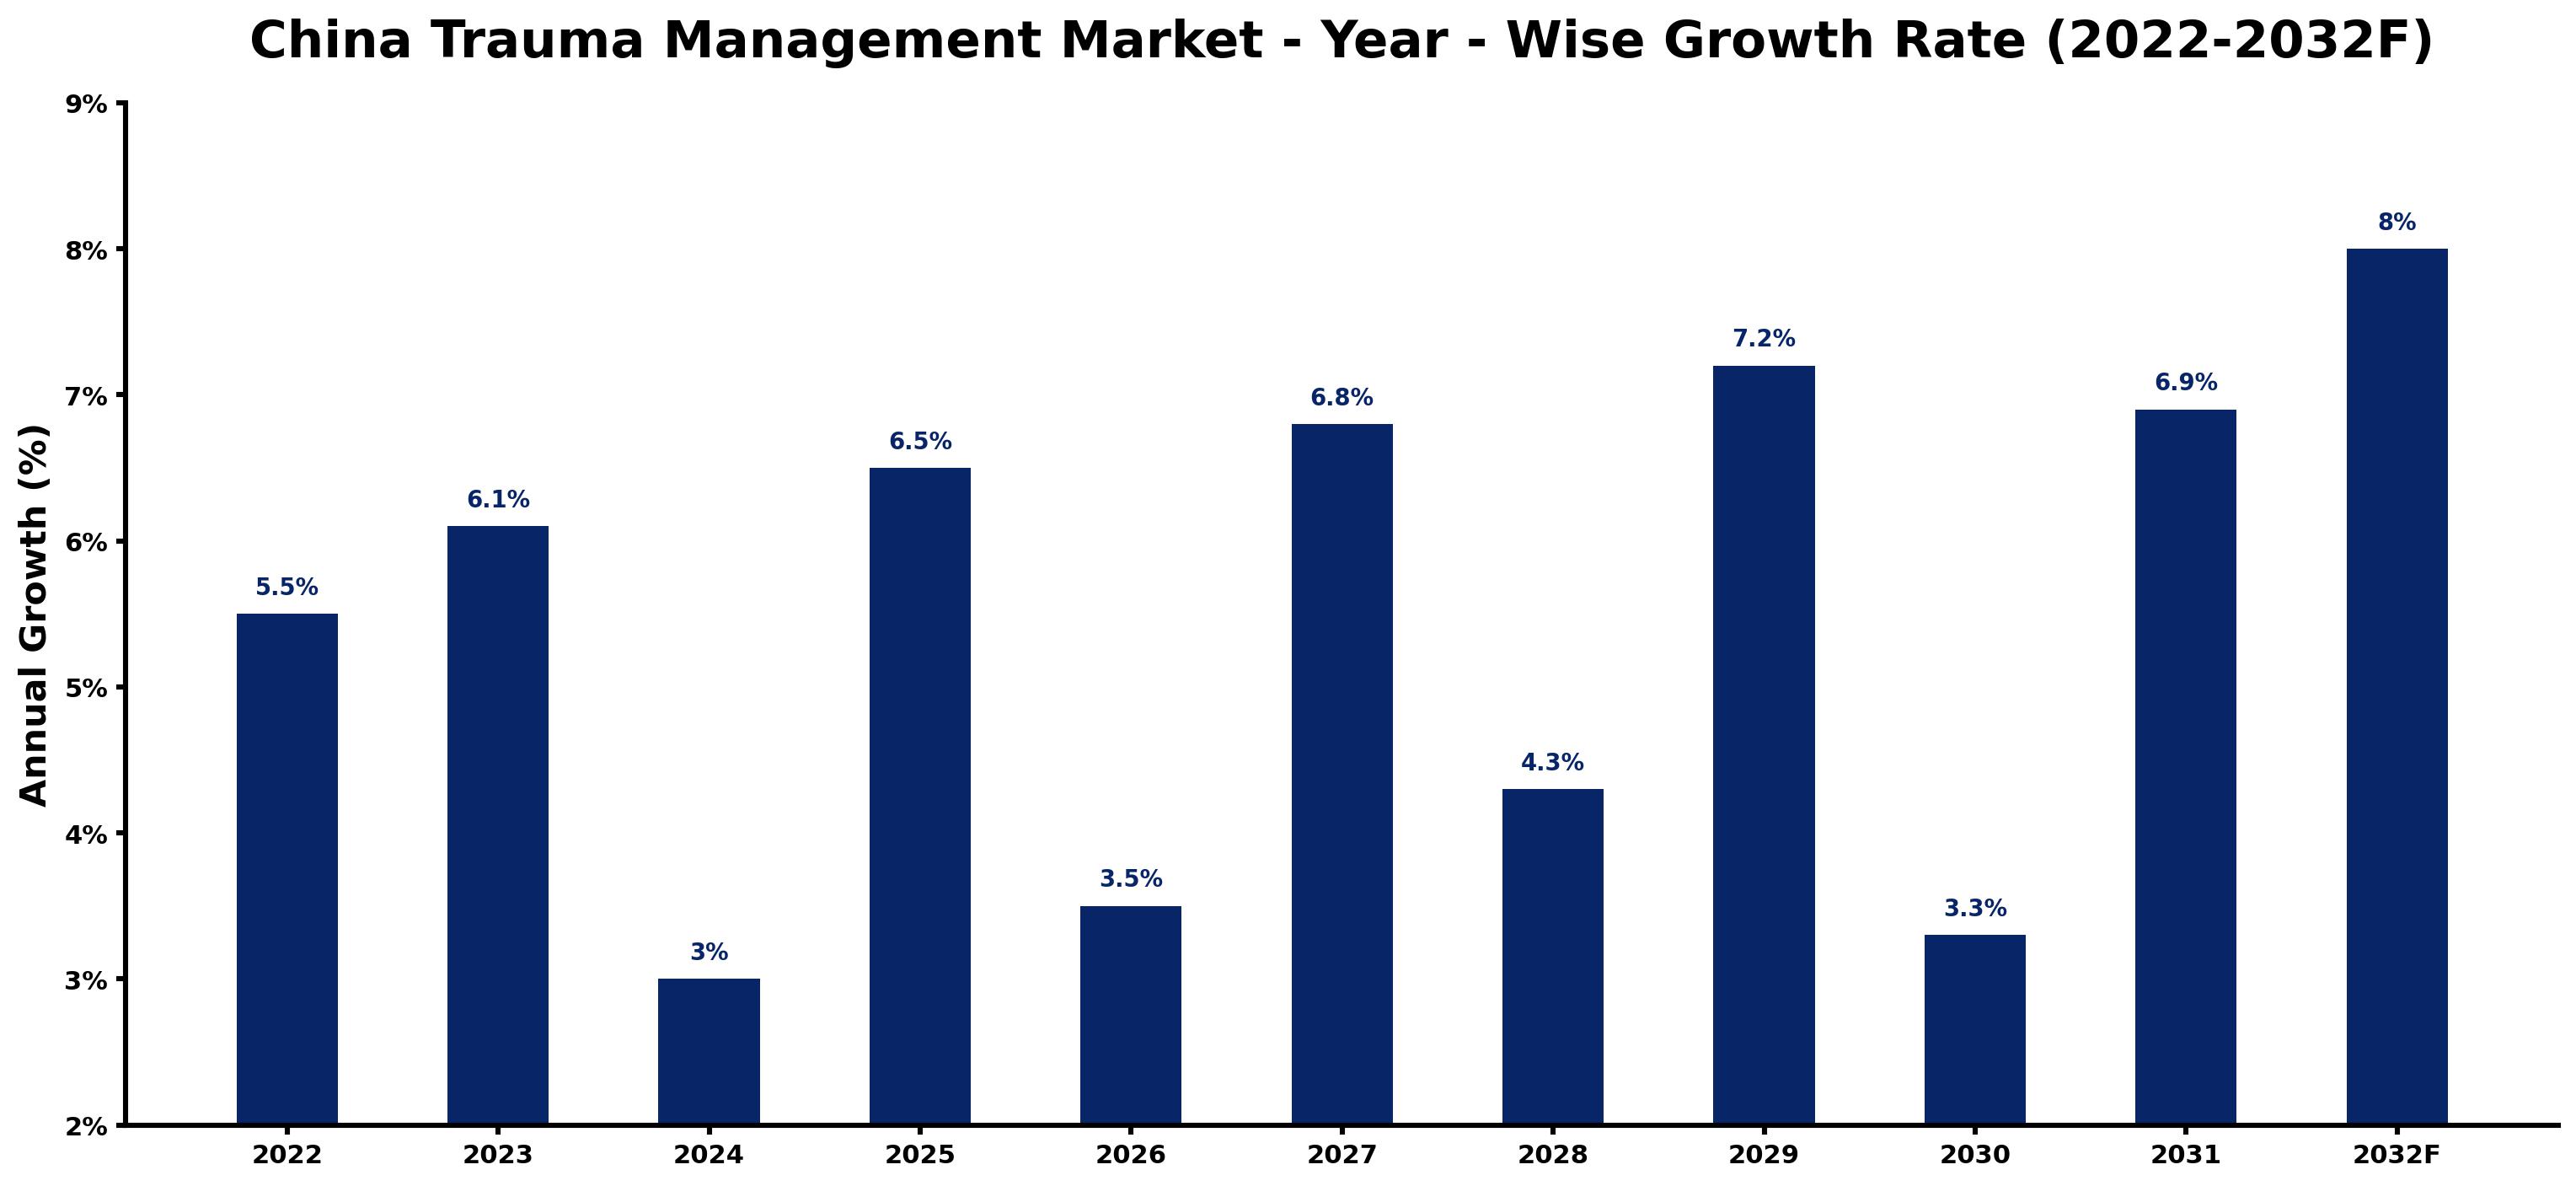
Year by year, the estimates below pair each growth rate with the development that shaped it.
| Year | Estimated Annual Growth (%) | Market Rationale |
| 2022 | 5.5 | Trauma cases were prevalent, with over 30,000 treated in hospitals across China. |
| 2023 | 6.1 | Increased mental health service utilization by 15% highlighted the growing need for trauma management. |
| 2024 | 3.0 | The market experienced a slowdown as healthcare facilities adjusted to new standards and practices. |
| 2025 | 6.5 | Demand surged as hospitals reported a rise in trauma cases and improved surgical capabilities. |
| 2026 | 3.5 | A slowdown occurred due to adjustments in trauma care protocols and resource allocation. |
| 2027 | 6.8 | The market rebounded with a 6.8% growth as trauma training programs gained traction. |
| 2028 | 4.3 | Growth slowed as hospitals faced challenges in maintaining service levels amid rising patient numbers. |
| 2029 | 7.2 | A resurgence in demand was noted as outpatient visits for trauma care increased significantly. |
| 2030 | 3.3 | The market slowed again as healthcare systems faced operational pressures from high patient volumes. |
| 2031 | 6.9 | Demand accelerated as hospitals enhanced their trauma care capabilities and expanded services. |
| 2032 | 8.0 | The market is expected to peak with a focus on mental health and rehabilitation services. |
Note: Market size estimations and growth projections presented in this report are based on 6Wresearch's proprietary forecasting methodology, utilizing the latest available industry data, government publications, and primary research inputs.
China Trauma Management Market Synopsis
Trauma Management in China encompasses a range of medical practices aimed at treating injuries and psychological trauma. It includes surgical and non-surgical interventions, rehabilitation, and mental health support. The China Trauma Management Market is expanding due to increased demand from hospitals and a focus on mental health services. In 2022, over 30,000 trauma cases were treated in hospitals, and the government is investing in trauma care infrastructure. Initiatives like the enhanced trauma care training program are further driving demand.
Market Dynamics Impact Analysis (2026–2032)
| Factor | Type | Impact | Primary Segment Affected |
| Increasing focus on mental health services is driving demand for psychological trauma care. | Driver | High | Mental Trauma Care |
| Rising number of trauma cases treated in hospitals boosts demand for surgical interventions. | Driver | High | Surgical Trauma Care |
| Growing outpatient care needs present opportunities for clinics to expand trauma services. | Opportunity | High | Outpatient |
| Investment in trauma care infrastructure creates opportunities for healthcare facilities. | Opportunity | High | Hospitals |
| Limited funding for trauma care improvements can hinder service expansion. | Restraint | High | Hospitals |
| Challenges in recruiting specialized trauma surgeons may affect service delivery. | Restraint | Medium | Surgical Trauma Care |
| High operational costs for trauma care facilities can limit access to services. | Challenge | High | Hospitals |
| Delays in implementing updated trauma care standards can slow market growth. | Challenge | Medium | Surgical Trauma Care |
Evaluation of Drivers in China Trauma Management Market (2026–2032)
Below mentioned are some major drivers and their influence on market dynamics.
| Drivers | Primary Segment Affected | Why It Matters (Evidence) |
| Increased mental health service utilization drives demand for psychological support. | Mental Trauma Care | In 2023, mental health service utilization rose by 15%, leading to more trauma care purchases. |
| Rising trauma cases necessitate more surgical interventions in hospitals. | Surgical Trauma Care | Over 30,000 trauma cases were treated in hospitals in 2022, increasing demand for surgical services. |
| Expansion of outpatient services improves accessibility for trauma patients. | Outpatient | Outpatient visits for trauma-related care reached 1.5 million in 2022, boosting demand for services. |
| Government funding for trauma care infrastructure improvements supports facility upgrades. | Hospitals | In 2023, the government allocated 500 million CNY for trauma care infrastructure improvements. |
| Training programs for healthcare professionals improve service delivery in trauma management. | Surgical Trauma Care | The Ministry of Health's 2023 program improves trauma care training, increasing service quality. |
The Trauma Management market in China is expanding as hospitals and clinics increase their focus on mental health services, surgical interventions, and outpatient care. In 2023, mental health service utilisation rose by 15%, leading to more trauma care purchases. Over 30,000 trauma cases were treated in hospitals in 2022, increasing demand for surgical services. Outpatient visits for trauma-related care reached 1.5 million in 2022, boosting demand for services.
Evaluation of Restraints in China Trauma Management Market
Below mentioned are some major restraints and their influence on market dynamics.
| Market Restraint | Primary Segment Affected | Why It Matters (Evidence) |
| Limited funding for trauma care improvements can hinder service expansion. | Hospitals | Budget constraints restrict hospitals from investing in necessary trauma care upgrades. |
| Challenges in recruiting specialized trauma surgeons may affect service delivery. | Surgical Trauma Care | A 20% increase in trauma surgeons since 2020 is still insufficient to meet demand. |
| High operational costs for trauma care facilities can limit access to services. | Hospitals | Rising costs make it difficult for hospitals to maintain quality trauma care. |
| Delays in implementing updated trauma care standards can slow market growth. | Surgical Trauma Care | Compliance with new standards can take time, affecting service availability. |
| Inadequate mental health support resources may limit trauma recovery options. | Mental Trauma Care | The growing demand for mental health services is not matched by available resources. |
China Trauma Management Market Challenges
The China Trauma Management Market faces technological barriers that hinder the adoption of advanced trauma care systems, costing hospitals valuable time in providing timely treatment. Regulatory complexities delay the implementation of updated care standards, resulting in inconsistent quality across over 2,000 specialized trauma centers, which ultimately impacts patient recovery rates. A shortage of skilled professionals, particularly trauma surgeons, limits healthcare providers' capacity to manage the increasing number of trauma cases, leading to longer wait times for patients. The substantial cost of trauma care infrastructure improvements, with 500 million CNY allocated in 2023, strains hospital budgets, restricting their ability to expand necessary services.
Trends in the China Trauma Management Market
Below mentioned are some of the trends shaping the China Trauma Management Market growth.
- Launch of Trauma Care Training Program: In 2023, the Ministry of Health initiated a program to improve trauma care training for healthcare professionals. This initiative aims to elevate the quality of trauma management across the country, addressing the rising number of trauma cases treated in hospitals.
- Shift Towards Outpatient Trauma Services: The market is seeing a shift towards outpatient trauma services, with an 8.2% growth projected for this segment. This change reflects the increasing preference for less invasive treatments and quicker recovery times, particularly in urban areas.
- Expansion of Teletherapy for Trauma Survivors: Teletherapy services for trauma survivors expanded by 30% in urban areas since 2021. This trend indicates a growing acceptance of remote mental health support, making it more accessible for trauma patients.
- Focus on Pediatric Trauma Care: The Beijing region has implemented a trauma care improvement plan focusing on pediatric patients. This initiative aims to address the increasing number of children affected by trauma, ensuring specialised care is available.
Investment Opportunities in the China Trauma Management Market
Several openings in the China Trauma Management Market merit attention from investors.
- Investment in Pediatric Trauma Units: Hospitals are seeking to improve pediatric trauma care, with over 2,000 specialised trauma centres nationwide. Investing in these units can meet the demand for specialised care for children.
- Expansion of Outpatient Trauma Services: With outpatient visits for trauma-related care reaching 1.5 million in 2022, clinics can expand their services. Partnering with local healthcare providers can facilitate this growth and improve patient access.
- New Mental Health Support Programs: The increasing focus on mental health services presents opportunities for new programs. Collaborating with mental health organisations can improve service offerings for trauma survivors.
- Trauma Care Infrastructure Development: The government allocated substantial funding for trauma care infrastructure improvements in 2023. Investing in facility upgrades can improve service delivery and patient outcomes.
Government Initiatives in the China Trauma Management Market
The legal framework for trauma management in China is shaped by several key laws and initiatives. The Pediatric Surgery standard, updated in 2021, aimed to improve care quality for children. The National Health Commission's establishment of the National Trauma Registry in 2020 has facilitated data collection on trauma incidents, enhancing understanding of the issue. Furthermore, the Ministry of Health's 2023 program to improve trauma care training for healthcare professionals is critical for enhancing service delivery and ensuring better patient outcomes.
The Ministry of Health oversees the implementation of trauma care initiatives and funds various programs. In 2023, it allocated 500 million CNY to improve trauma care infrastructure across the country. The National Health Commission also plays a role in approving trauma care standards and guidelines, ensuring that facilities meet necessary requirements. These efforts are aimed at improving the quality of trauma management services available to patients.
Future Insight of the China Trauma Management Market
The China Trauma Management Market is set to develop by 2032, driven by several pivotal changes. The government's trauma care training program will enhance the skills of healthcare professionals, improving service delivery across the nation. Integrating trauma care education into medical curricula will ensure a steady supply of qualified practitioners. The growing focus on mental health services will facilitate better access to psychological support for trauma patients. These initiatives will collectively elevate the quality of trauma management and patient outcomes in the years ahead.
Market Segmentation Analysis
The analysis below covers each segmentation, its leading category in 2025 and its fastest-growing category through 2032.
By Management Approach – Surgical Trauma Care Dominated, Non-Surgical Care Expected to Grow Fastest
According to Vasudha, AM at 6Wresearch, Surgical Trauma Care accounted for a 40% market share by management approach in 2025. Surgical trauma care holds the largest market share due to its vital role in addressing severe injuries, with over 30,000 trauma cases treated in hospitals across China in 2022. The extensive infrastructure and increasing number of trauma surgeons ensure effective management of critical cases. Non-Surgical Care is set to record the highest CAGR in this split, 6.7% over 2026–2032. Non-surgical care is experiencing rapid growth, driven by a greater emphasis on rehabilitation and recovery, exemplified by a 30% increase in teletherapy services in urban areas since 2021. This segment's expansion is further bolstered by government initiatives focused on enhancing mental health services, ensuring its growing acceptance in trauma management. Suppliers should focus on developing non-surgical solutions to meet the rising demand for holistic trauma management.
By Specialty Focus – Orthopedic/Neuro Dominated, Physiotherapy Expected to Grow Fastest
Orthopedic/Neuro took a 42% share of specialty focus in 2025, more than any other category. Orthopedic/neuro specialties dominate the market share as they are critical for addressing injuries related to bones and the nervous system, which are prevalent in trauma cases. This focus aligns with the increasing number of trauma cases treated, ensuring a steady demand for these specialized services. Over 2026–2032, Physiotherapy is expected to post the fastest growth, at a CAGR of 7.0%. Physiotherapy is the fastest-growing segment, driven by its key role in rehabilitation post-injury, which is becoming increasingly recognised in trauma care. The growing awareness of the importance of recovery processes is propelling demand for physiotherapy services. Providers should invest in physiotherapy capabilities to capitalise on the increasing focus on rehabilitation in trauma management.
By Delivery Type – Inpatient Dominated, Outpatient Expected to Grow Fastest
Inpatient held a 41% share of the China Trauma Management Market by delivery type in 2025. Inpatient care dominates the market share as it is crucial for severe cases that necessitate hospitalisation, providing comprehensive treatment for critical trauma patients. The average hospital stay of approximately 7 days highlights the importance of well-equipped inpatient facilities in delivering effective care. The quickest growth will come from Outpatient, forecast to expand at a CAGR of 8.2% between 2026 and 2032. Outpatient care is rapidly gaining traction, primarily due to its effectiveness in managing less severe trauma cases, which allows for more efficient patient handling. The increase in outpatient visits indicates a shift towards more accessible trauma care options in clinics, reflecting evolving patient preferences. Healthcare facilities should enhance their outpatient services to cater to the growing demand for less intensive trauma care.
By End User – Hospitals Dominated, Clinics Expected to Grow Fastest
With a 49% revenue share in 2025, Hospitals was the largest end user category. Hospitals represent the largest share of the market as they are the primary providers of trauma care, equipped with the necessary resources and specialists to handle severe cases. The establishment of over 2,000 specialized trauma centers nationwide further solidifies their leading position. Clinics are projected to grow fastest, at a CAGR of 7.0% during 2026–2032. Clinics are the fastest-growing segment, as they play a supportive role in managing minor trauma cases, which are on the rise. The increase in outpatient visits for trauma-related care indicates a shift towards more accessible treatment options. Suppliers should consider partnerships with clinics to expand their reach in the growing outpatient trauma care market.
Key Attractiveness of the Report
- 10 Years of Market Numbers
- Historical Data Starting from 2022 to 2025
- Base Year 2025
- Forecast Data until 2032
- Key Performance Indicators Impacting the Market
- Major Upcoming Developments and Projects
Key Highlights of the Report:
- China Trauma Management Market Outlook
- Market Size of China Trauma Management Market, 2025
- Forecast of China Trauma Management Market, 2032
- Historical Data and Forecast of China Trauma Management Revenues & Volume for the Period 2022 - 2032F
- China Trauma Management Market Trend Evolution
- China Trauma Management Market Drivers and Challenges
- China Trauma Management Price Trends
- China Trauma Management Porter's Five Forces
- China Trauma Management Industry Life Cycle
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Management Approach for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Surgical Trauma Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Non-Surgical Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Mental Trauma Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Pediatric Trauma Units for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Specialty Focus for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Orthopedic/Neuro for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Physiotherapy for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Psychiatry/Psychology for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Pediatric Surgery for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Delivery Type for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Inpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Outpatient for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Teletherapy for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Critical Care for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By End User for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Hospitals for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Clinics for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Trauma Survivors for the Period 2022 - 2032F
- Historical Data and Forecast of China Trauma Management Market Revenues & Volume By Children's Hospitals for the Period 2022 - 2032F
- China Trauma Management Import Export Trade Statistics
- Market Opportunity Assessment By Management Approach
- Market Opportunity Assessment By Specialty Focus
- Market Opportunity Assessment By Delivery Type
- Market Opportunity Assessment By End User
- China Trauma Management Top Companies Market Share
- China Trauma Management Competitive Benchmarking By Technical and Operational Parameters
- China Trauma Management Company Profiles
- China Trauma Management Key Strategic Recommendations
Market Covered
This report examines the market across the segments below.
By Management Approach
- Surgical Trauma Care
- Non-Surgical Care
- Mental Trauma Care
- Pediatric Trauma Units
By Specialty Focus
- Orthopedic/Neuro
- Physiotherapy
- Psychiatry/Psychology
- Pediatric Surgery
By Delivery Type
- Inpatient
- Outpatient
- Teletherapy
- Critical Care
By End User
- Hospitals
- Clinics
- Trauma Survivors
- Children's Hospitals































